
 Disinfection Cupboard Market | 2026-2036
Disinfection Cupboard Market Size, Share, and Industry Trends Forecast 2026-2036
Disinfection Cupboard Market Insights
GB standards compliance for disinfection efficacy and electrical safety is bifurcating the competitive landscape between certified incumbents and uncertified challengers. Midea Group leverages its appliance manufacturing scale to dominate domestic distribution channels. Haier sustains R&D intensity across integrated kitchen ecosystems that embed disinfection modules. SIEMENS competes on European regulatory alignment and premium channel positioning in developed markets.
A disinfection cupboard is an enclosed cabinet system employing UV-C light, ozone, thermal, or chemical agents to eliminate pathogens on surfaces, instruments, or containers, typically operating at temperatures between 60°C and 125°C depending on sterilization grade. The device serves commercial and institutional buyers requiring validated hygiene protocols for reusable equipment. Wall-mounted and integrated configurations anchor current revenue pools across residential and healthcare settings, while mobile units represent the fastest-growing structural segment as laboratories and field clinics prioritize flexibility. Heat-based technology retains the largest installed base, though UV-C systems are capturing margin-rich replacement cycles in facilities upgrading from legacy ozone units.
China's SAMR enforces GB standards that gate market access for domestic manufacturers, while the EU's CE marking and MDR frameworks compel technical file documentation for medical-grade cupboard exports. The US FDA regulates instrument sterilization claims for healthcare-bound units, creating a multi-jurisdictional compliance burden for cross-border suppliers. Stakeholders must monitor diverging national efficacy testing protocols and decide whether to pursue modular platform designs that can be reconfigured for regional certification requirements.
Market Dynamics
Healthcare procurement teams are consolidating sterilization equipment vendors to reduce compliance overhead, compressing supplier margins while elevating certified incumbents who can document multi-jurisdictional efficacy testing.
Growth Catalysts
- EU MDR framework expansion:Medical-grade cupboard exports to European hospitals now require technical file documentation, filtering out uncertified competitors and expanding addressable market share for compliant manufacturers.
- UV-C wavelength optimization:254-nanometer lamp systems achieve log-4 reduction on heat-sensitive endoscopes, opening replacement cycles in surgical centers previously locked into steam autoclaves.
- Jiangsu manufacturing cluster scale:Domestic Chinese brands leverage component supplier density to compress production lead times and undercut import pricing in Southeast Asian hospital tenders.
Market Restraints
- Quartz sleeve supply concentration:High-purity fused quartz for UV-C lamp housings sources primarily from three Hubei province suppliers, exposing manufacturers to input price volatility and allocation risk.
- Ozone residual toxicity thresholds:China's GB 28232 standard mandates maximum 0.16 ppm post-cycle ozone levels, forcing legacy ozone-dominant cupboard designs into costly catalyst decomposition retrofits.
- Steam sterilizer substitution:Central sterile supply departments in tertiary hospitals retain preference for validated steam autoclaves for surgical instrument loads, capping UV-C cupboard penetration in high-volume settings.
Strategic Opportunities
- India PLI scheme for medical devices:Production-linked incentives for domestic manufacturing create tariff-advantaged positioning for cupboard assembly targeting government hospital procurement.
- Mobile unit field deployment:Battery-powered UV-C cupboards with integrated ozone destruction enable sterilization workflows in temporary clinics and disaster response settings lacking fixed infrastructure.
- IoT sensor integration:Real-time cycle logging and cloud-based compliance documentation align with Joint Commission audit requirements, creating subscription revenue attachment to hardware sales.
Industry Challenges
- Photometric calibration technician scarcity:UV-C irradiance verification requires specialized radiometry expertise that biomedical engineering programs have not scaled to match equipment deployment rates.
- Multi-jurisdictional certification timelines:Simultaneous FDA 510(k) clearance and CE MDR technical file preparation extends product launch windows and consumes regulatory affairs bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disinfection Cupboard Market |
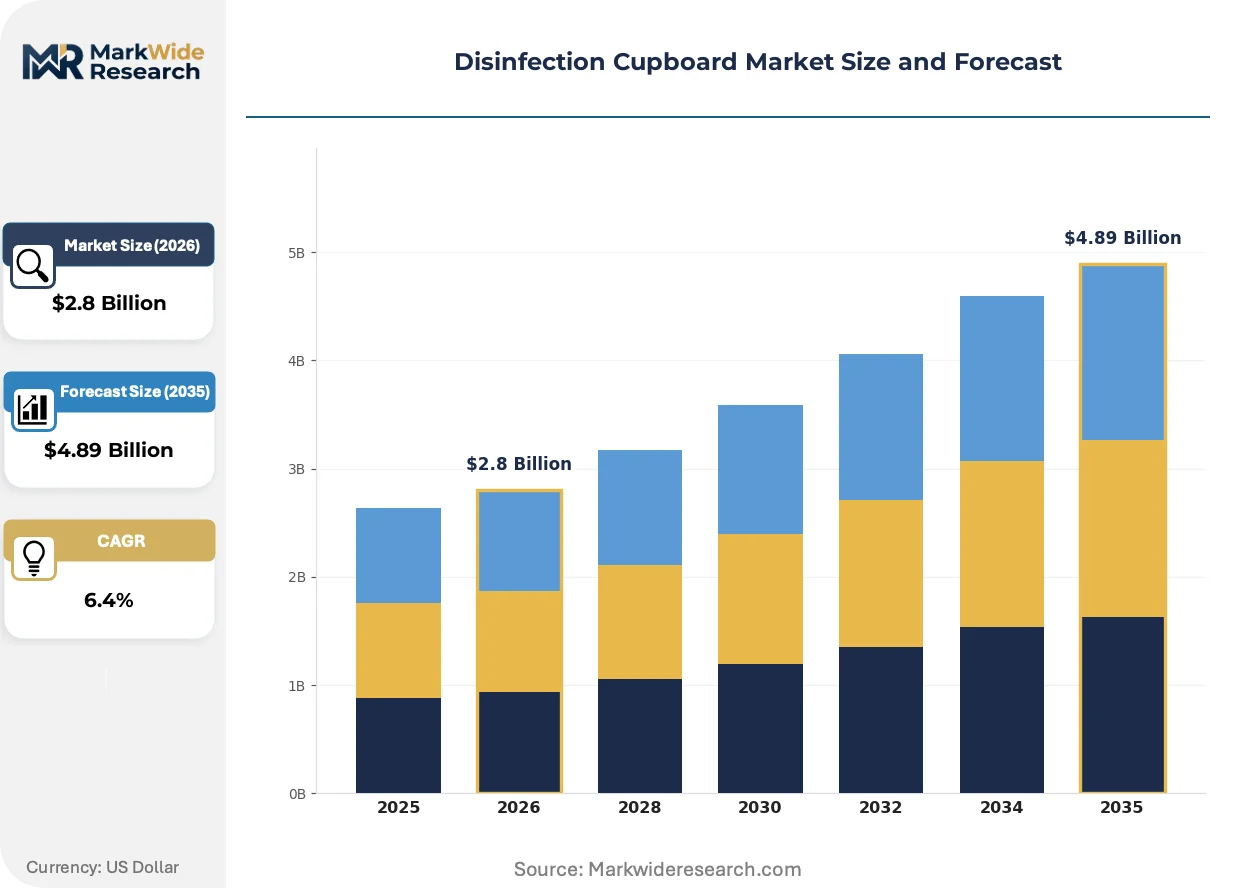
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wall-Mounted, Freestanding, Mobile, Integrated Technology: UV-C Light, Ozone, Chemical, Heat End User: Healthcare Facilities, Educational Institutions, Laboratories, Hospitality Application: Surface Disinfection, Instrument Sterilization, Air Purification, Container Sanitization |
| Companies Covered | Midea Group, Haier, SIEMENS, Canbo, ROBAM, Vatti, Vanward, Fotile, Macro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disinfection Cupboard Market Trends and Innovations
Equipment architectures are fragmenting between validated medical-grade systems and cost-optimized commercial units, with technology choices increasingly determined by end-use sterilization assurance requirements rather than capital budget alone.
UV-C LED arrays operating at 265-280 nanometers are bifurcating the upper equipment tier from mercury vapor lamp systems. Tertiary care networks in Germany and Japan are piloting solid-state units for their instant-on capability and mercury-free disposal profiles. This wavelength precision is compressing thermal sterilization's residual dominance in temperature-sensitive instrument processing.
China's SAMR is tightening GB standard efficacy testing protocols to require third-party laboratory validation for all new cupboard registrations. Domestic manufacturers in Zhejiang province are absorbing six-month certification delays while reconfiguring test documentation for parallel EU MDR submissions. The policy friction most impacts mid-size exporters lacking captive regulatory affairs capacity.
Hospital procurement departments are unbundling after-sales service contracts from initial equipment purchase, compressing vendor service margins and elevating third-party sterilization equipment service specialists. This disintermediation is most advanced in US integrated delivery networks and is spreading to Australian private hospital groups seeking operational expenditure flexibility.
Disinfection Cupboard Market Segmentation
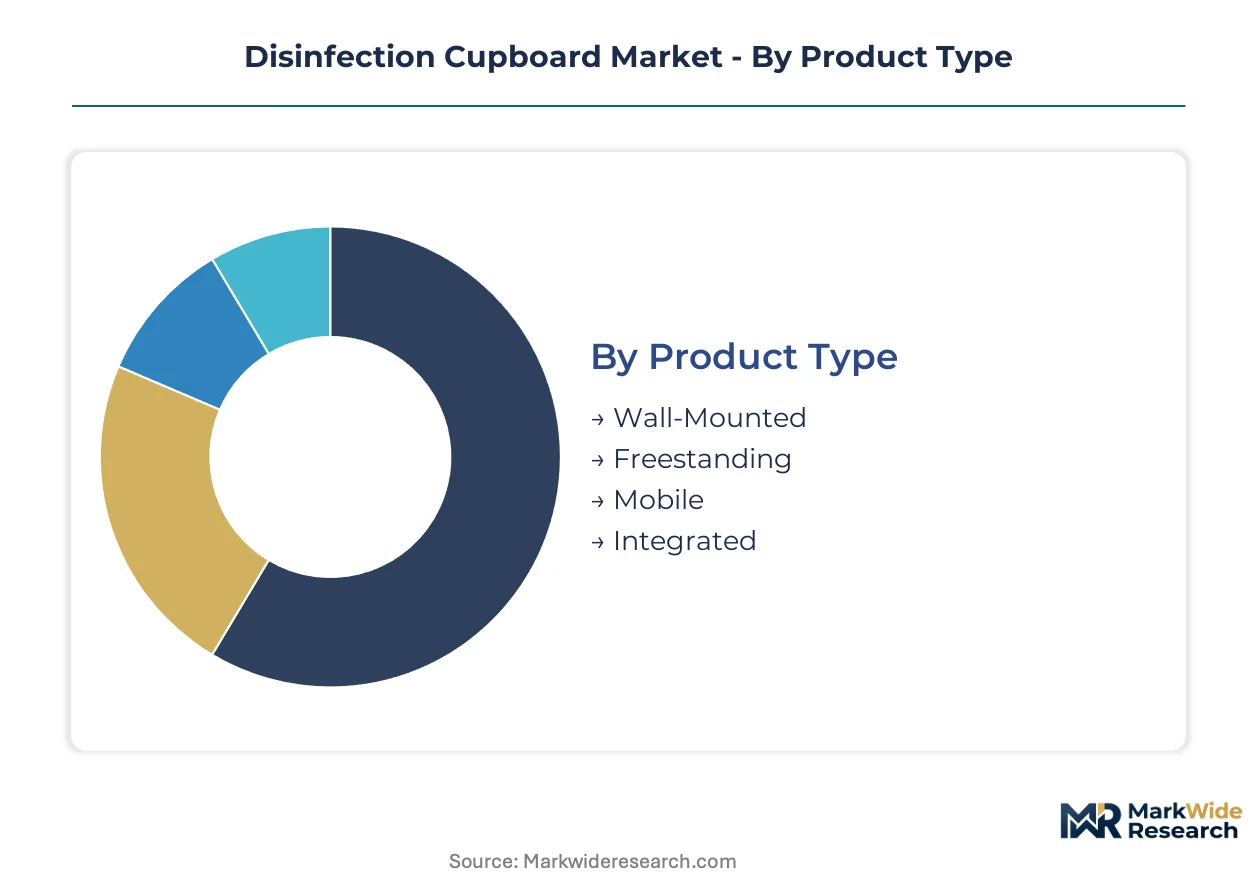
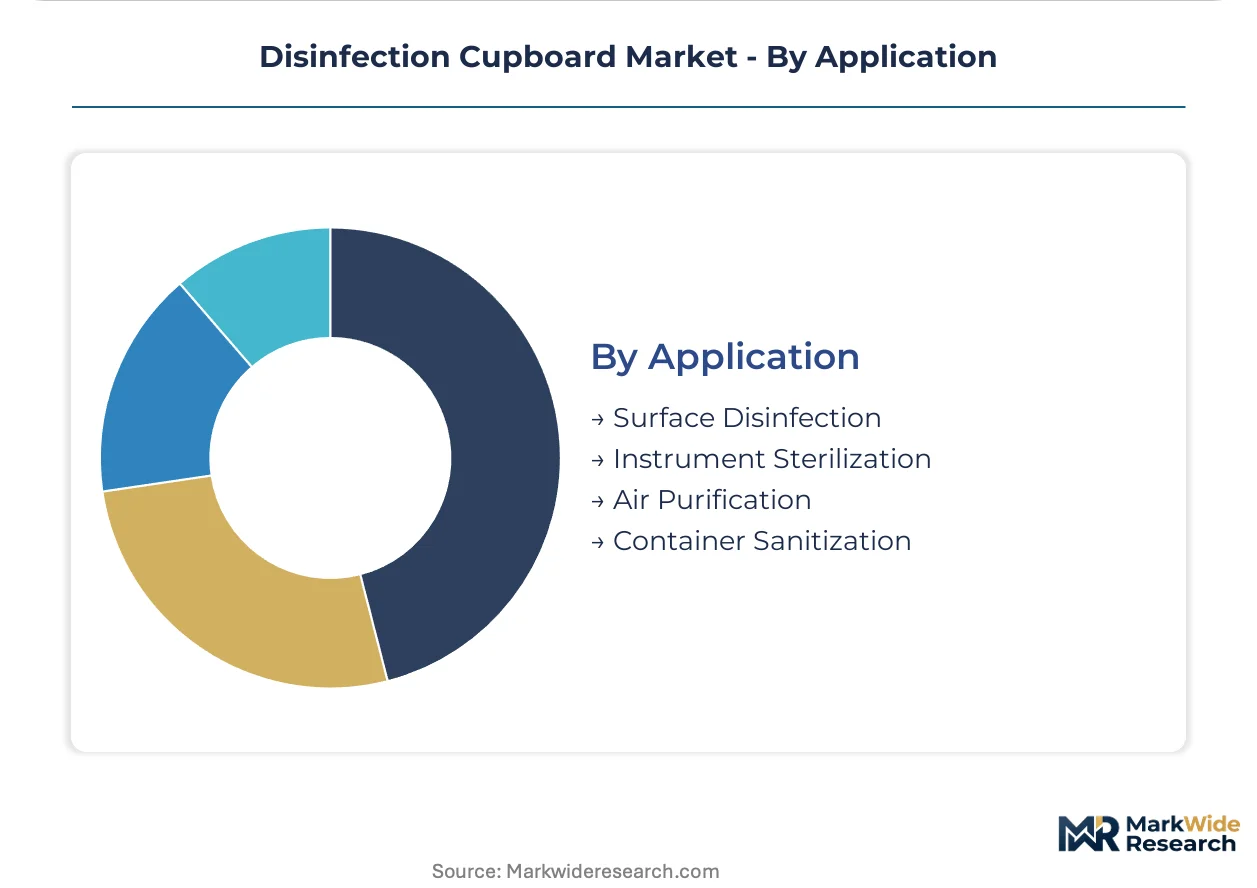
Segmentation in the disinfection cupboard market reflects divergent sterilization assurance requirements across institutional settings. Regulatory frameworks from China's SAMR, the EU's MDR, and the US FDA create distinct compliance tiers that reshape product positioning and channel access.
Product Type:
GB standards and CE marking requirements enforce different structural specifications for wall-mounted versus mobile configurations, bifurcating manufacturing footprints.
- Wall-Mounted:Fixed installations dominate residential kitchens and compact clinical spaces where floor area commands premium value. China's Jiangsu manufacturers anchor production scale for this configuration, leveraging component supplier density to compress lead times for domestic distribution.
- Freestanding:Modular cabinet systems accommodate variable load volumes in hospital central sterile supply departments. Demand concentrates in tertiary care networks across Germany and Japan where infrastructure flexibility supports multi-department deployment.
- Mobile:Battery-powered units with integrated ozone destruction enable field sterilization workflows. Laboratories and disaster response clinics in Southeast Asia prioritize this configuration where fixed infrastructure is absent.
- Integrated:Embedded modules within kitchen ecosystems serve high-end residential and commercial food service applications. Haier's R&D intensity targets this segment through smart home connectivity and space optimization.
Established volume favors wall-mounted systems; emerging adoption favors mobile units.
Technology:
Cost tier differentiation separates validated medical-grade systems from commercial units, with wavelength precision and thermal profiles determining end-use access.
- UV-C Light:254-nanometer mercury vapor lamps and emerging 265-280 nanometer LED arrays achieve log-4 pathogen reduction without thermal damage. Surgical centers in Germany and Japan are piloting solid-state systems for mercury-free disposal compliance.
- Ozone:Gas-phase oxidation systems face regulatory pressure from China's GB 28232 residual toxicity thresholds. Legacy designs require costly catalyst decomposition retrofits to meet the 0.16 ppm post-cycle mandate.
- Chemical:Agent-based systems deploy hydrogen peroxide vapor or chlorine dioxide for heat-sensitive instrument loads. Pharmaceutical laboratories in Switzerland and Singapore specify these for validated sterilization protocols.
- Heat:Thermal sterilization between 60°C and 125°C retains the largest installed base in food service and basic medical settings. Steam autoclave substitution limits penetration in high-volume surgical instrument processing.
Margin concentration favors UV-C systems; replacement cycle timing favors heat-based units.
End User:
Customer type determines certification burden intensity, with healthcare procurement teams consolidating vendors to reduce compliance overhead.
- Healthcare Facilities:Hospitals and surgical centers drive demand for medical-grade cupboards with FDA 510(k) clearance or CE MDR technical files. US integrated delivery networks are unbundling service contracts from equipment purchase, compressing vendor margins.
- Educational Institutions:Universities and K-12 systems specify cost-optimized commercial units for laboratory and food service hygiene. India's PLI scheme for medical devices creates tariff-advantaged positioning for domestic assembly targeting government tenders.
- Laboratories:Research facilities require validated cycle documentation and IoT sensor integration for audit compliance. Cloud-based logging aligns with Joint Commission requirements in US academic medical centers.
- Hospitality:Hotels and restaurants prioritize rapid-cycle surface disinfection for guest-facing equipment. Australia's private hospital groups are extending operational expenditure flexibility models into food service procurement.
Certification complexity favors healthcare facilities; volume scaling favors educational procurement.
Application:
Functional specification determines technology pairing, with instrument sterilization commanding the most stringent validation protocols.
- Surface Disinfection:UV-C exposure protocols for countertops and equipment exteriors serve rapid-turnover settings. Hospitality operators in Dubai and Singapore specify these for guest room turnover efficiency.
- Instrument Sterilization:Validated lethality assurance for reusable medical devices requires FDA or CE medical-grade certification. Tertiary hospitals retain steam autoclave preference for surgical loads, capping UV-C cupboard penetration.
- Air Purification:Combined UV-C and filtration systems address airborne pathogen loads in high-occupancy spaces. Post-pandemic building retrofits in South Korea and Taiwan are driving specification.
- Container Sanitization:Reusable vessel processing for food service and laboratory glassware employs heat or chemical protocols. China's Zhejiang manufacturers target this segment with cost-optimized commercial designs.
Regulatory stringency favors instrument sterilization; deployment velocity favors surface disinfection.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Healthcare procurement teams and commercial kitchen operators concentrate demand across distinct regulatory environments. Certification requirements from FDA, CE MDR, and China's GB standards fragment competitive access by geography.
China
Hospital central sterile supply departments and residential kitchen renovation cycles drive procurement volumes. SAMR enforces GB 28232 ozone residual limits and efficacy testing protocols that extend certification timelines. Jiangsu and Zhejiang manufacturing clusters anchor domestic production scale, with component supplier density compressing lead times for Southeast Asian export tenders.
Germany
Tertiary care networks pilot UV-C LED systems for mercury-free instrument processing compliance. The EU MDR framework mandates technical file documentation for medical-grade cupboard exports, filtering uncertified competitors. Bavaria and Baden-Württemberg host surgical center concentration where sterilization assurance requirements exceed commercial-grade specifications.
United States
Integrated delivery networks consolidate sterilization equipment vendors to reduce compliance overhead. FDA 510(k) clearance requirements govern instrument sterilization claims for healthcare-bound units. The Southeast and Midwest regions concentrate hospital procurement activity where unbundled service contracts compress vendor margins.
Japan
Surgical centers and pharmaceutical laboratories specify validated cycle documentation for heat-sensitive endoscope processing. METI oversees industrial standards alignment with international sterilization protocols. The Kanto and Kansai regions concentrate demand where solid-state UV-C pilot programs displace legacy mercury vapor installations.
India
Government hospital procurement and educational institution laboratory expansion drive commercial-grade demand. The PLI scheme for medical devices creates tariff-advantaged positioning for domestic cupboard assembly. Maharashtra and Gujarat manufacturing zones attract component sourcing for regional tender participation.
Disinfection Cupboard Market Competitive Landscape
Player mix skews toward diversified appliance conglomerates with captive distribution networks. Market structure concentrates around manufacturers leveraging scale economies in component procurement and multi-jurisdictional certification capacity. Strategic archetypes separate certified medical-grade specialists from cost-optimized commercial fabricators and integrated kitchen ecosystem providers. Competitive moves center on regulatory affairs capacity expansion and backward integration into UV-C lamp and quartz sleeve supply.
Among Chinese appliance conglomerates, Midea Group and Haier occupy positions reflecting scale-driven manufacturing and integrated ecosystem R&D intensity respectively. SIEMENS represents European regulatory alignment archetypes competing on premium channel positioning in developed markets. These three exemplify how geographic certification concentration and end-use specialization stratify competitive access.
| Leading Market Players |
|---|
| Midea Group |
| Haier |
| SIEMENS |
| Canbo |
| ROBAM |
| Vatti |
| Vanward |
| Fotile |
| Macro |
| Others |
Pricing and Supply Chain Analysis
Long-term capacity reservation contracts with Hubei province quartz suppliers lock in UV-C lamp housing access and stabilize input cost visibility for manufacturers targeting EU MDR compliance timelines. These arrangements bind Jiangsu and Zhejiang production clusters to fixed-volume commitments that compress margin flexibility but secure certification-grade output for hospital procurement tenders.
Pricing Analysis
Cost-plus contracts indexed to fused quartz spot prices dominate UV-C cupboard procurement, with medical-grade certification tiers commanding 40-60% premiums over commercial units. Price differentiation separates FDA-cleared systems from basic GB-standard models, while after-sales service unbundling intensifies cost compression in US integrated delivery networks. Procurement consolidation by tertiary hospital systems renders mid-tier manufacturers most vulnerable to price erosion.
Supply Chain Analysis
High-purity fused quartz sourcing from Hubei province chokepoints exposes manufacturers to allocation risk when lamp demand surges. Component dependencies center on mercury vapor tubes, 265-nanometer LED chips from Taiwan and South Korea, and ozone catalyst substrates from Japan. Tariff exposure on semiconductor-grade electronics feeds downstream distribution through regional medical device distributors and direct hospital GPO contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Disinfection cupboard penetration sits at early-cycle expansion as UV-C LED displacement of mercury vapor systems accelerates replacement demand across German and Japanese surgical networks.
For Market Incumbents: Shield certification-grade margins by deepening backward integration into quartz sleeve production and expanding captive regulatory affairs capacity for parallel FDA-CE submissions. Consolidate distributor relationships before procurement unbundling spreads from US IDNs to Australian private hospital groups. For New Entrants and Emerging Players: Anchor in India's PLI-advantaged manufacturing zones for tariff-competitive positioning in government hospital tenders. Target mobile battery-powered configurations for Southeast Asian field clinic deployment where fixed infrastructure gaps create white-space demand. For Investors and Strategic Acquirers: Component-captive specialists with in-house UV-C lamp fabrication represent the most defensible acquisition profile for sterilization equipment rollups. Watch quartz supply allocation announcements from Hubei province as inflection signals for input cost volatility and margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical File Preparation | CE marking documentation filters uncertified competitors from European hospital procurement pools. |
| UV-C LED Array Platform Launch | 265-nanometer solid-state systems displace mercury vapor in German surgical center pilots. |
| Backward Integration into Quartz Supply | Hubei province sleeve production secures lamp housing allocation against supply shocks. |
| IoT Sensor Subscription Attachment | Cloud-based cycle logging aligns with Joint Commission audit requirements in US academic medical centers. |
| Mobile Unit Field Deployment Partnership | Battery-powered configurations serve disaster response clinics lacking fixed sterilization infrastructure. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with hospital procurement managers, biomedical engineering directors, GPO contracts specialists, and regulatory affairs leads at sterilization equipment manufacturers; and secondary validation against FDA 510(k) filings, CE MDR technical file databases, SAMR registration records, and hospital capital expenditure tracking systems. Bottom-up installation base modeling triangulated against top-down healthcare infrastructure spending forecasts.
Forecasts across the projection horizon segment by product configuration, sterilization technology, end-user certification tier, and regional regulatory cluster. CAGRs derive from equipment replacement cycle timing, hospital construction pipeline data, and UV-C LED adoption curve assumptions. Modeled inputs include quartz supply allocation patterns, MDR transition compliance deadlines, and PLI scheme participation rates.
Material uncertainties — quartz supply disruption, MDR audit backlog extensions, steam autoclave substitution resilience — sit outside the modeled envelope. Forecasts reflect documented assumptions about certification timeline standardization and LED cost reduction curves. Practitioners should keep alternative scenarios live as GB standard efficacy testing protocol revisions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infection Control
Antimicrobial Suture Market
Infection Control
New Zealand Healthcare Surface Disinfectant Wipes Market
Infection Control
UV Sterilizer Pouch Market
Infection Control
Dental Infection Treatment Market
Infection Control
Hand Hygiene Products Market
Infection Control
Hospital Acquired Infections Market
Infection Control
Salivary Gland Infection Market
Infection Control
Global Hospital Disinfectant Products and Services Market
Infection Control
Australia Healthcare Surface Disinfectant Wipes Market
Infection Control
Catheter-Related Bloodstream Infections (Crbsis) Market
Infection Control
Global Sepsis Therapeutics Market
Infection Control
Peptide-Based Infection Therapeutics Market
Infection Control
Surgical Site Infection Control Market
Infection Control
Sterilization Monitoring Market
Infection Control
Surgical Site Infections Market
Infection Control
Denture Disinfectants Market