
 Global Medical Device Reprocessing Market | 2026-2036
Global Medical Device Reprocessing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Medical Device Reprocessing Market Foresight
Buyer concentration among hospital systems is expanding as integrated delivery networks consolidate supplier contracts for reprocessed devices. Stryker Corporation leverages its endoscopy reprocessing portfolio to sustain service relationships with major health systems. Johnson & Johnson Services, Inc. anchors its position through sterilization technology leadership in critical device categories. Medline Industries, LP competes on distribution density, ensuring same-day replenishment of reprocessed inventory to ambulatory surgical centers.
Medical device reprocessing encompasses the validated cleaning, disinfection, and sterilization of previously used medical devices to restore them for safe clinical reuse, governed by ISO 17664 standards for manufacturer instructions and FDA 510(k) clearance pathways for third-party reprocessors. The process reduces per-procedure costs by 50 percent versus original device procurement while maintaining biocompatibility and functional performance parameters. Single-use device reprocessing occupies the largest revenue pool within product type segments, though critical device reprocessing commands premium pricing due to stringent validation requirements. Automated sterilization technology leads technology adoption in hospital settings, while ultrasonic cleaning dominates ambulatory surgical center workflows where technician staffing constraints favor less labor-intensive protocols.
FDA enforcement of reprocessing quality system regulations shapes market access requirements for all commercial reprocessors, while EMA's Medical Device Regulation imposes equivalent conformity assessment burdens across European markets. ISO 13485 certification serves as the baseline quality management credential that purchasers demand before contract eligibility. Stakeholders must monitor evolving FDA guidance on novel device categories eligible for reprocessing, as each expansion of the approved device list reshapes addressable market boundaries and competitive positioning.
Market Dynamics
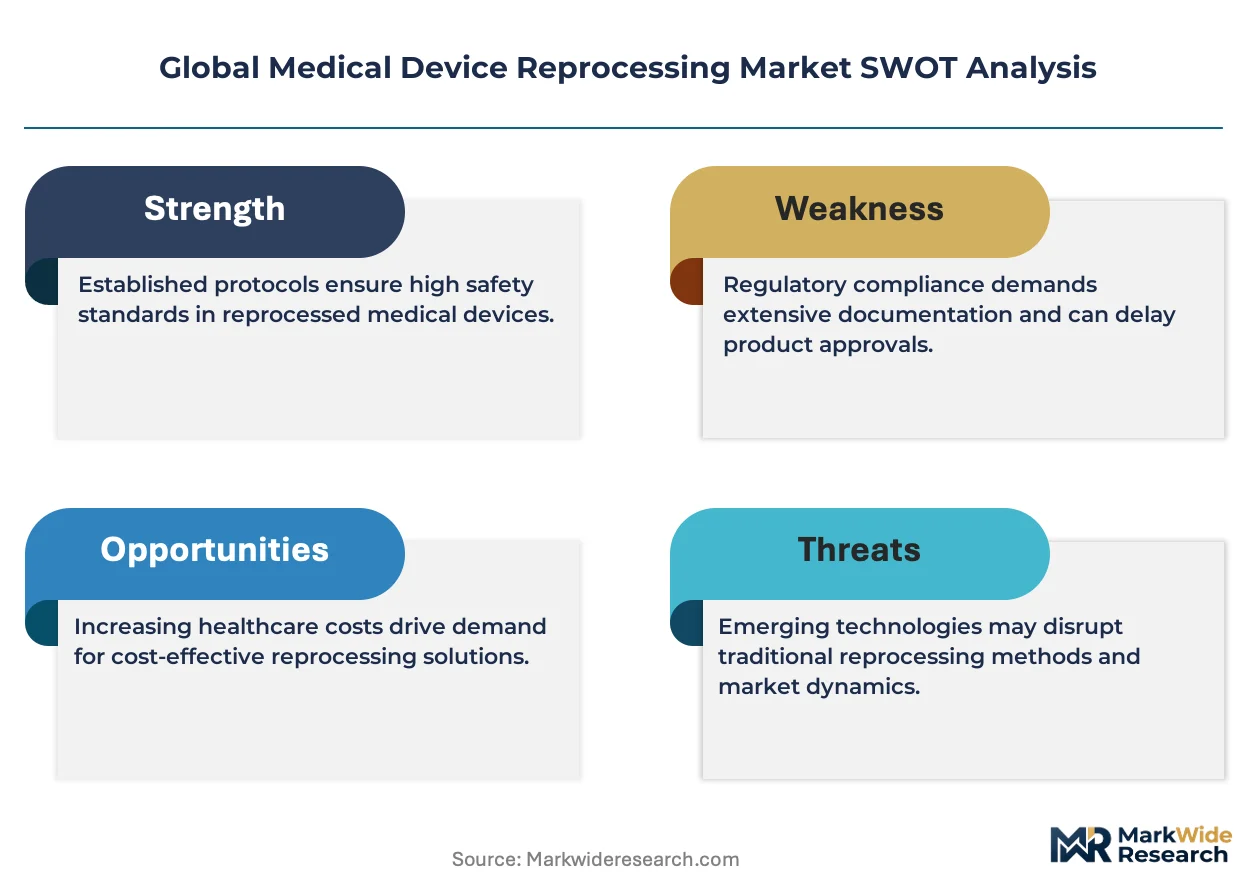
Hospital procurement consolidation is compressing vendor margins while simultaneously expanding contract volumes for third-party reprocessors, creating a bifurcated market where scale operators capture integrated delivery network tenders and smaller players retreat to ambulatory surgical center niches.
Growth Catalysts
- FDA 510(k) pathway expansion:The FDA's updated guidance on novel device categories eligible for reprocessing is widening addressable market boundaries for validated single-use devices, particularly in electrophysiology and orthopedics.
- Ultrasonic cleaning automation:Ambulatory surgical centers facing technician staffing constraints are adopting automated ultrasonic protocols that reduce labor intensity while maintaining ISO 17664 compliance standards.
- Cost-containment mandates:United States integrated delivery networks are embedding reprocessed device targets into physician preference item committees, institutionalizing volume commitments across cardiac catheterization and endoscopy service lines.
Market Restraints
- Polymer degradation uncertainty:Reprocessed single-use devices face functional performance degradation risks in multi-layer catheter materials, limiting reprocessing cycles and compressing per-unit economics.
- EMA MDR conformity burdens:The European Medical Device Regulation's enhanced clinical evidence requirements for reprocessed critical devices are extending market access timelines and elevating compliance costs for EU-bound operators.
- Original equipment manufacturer lockouts:Device manufacturers are implementing electronic handshake protocols and material tracing technologies that restrict third-party reprocessor access to proprietary device architectures.
Strategic Opportunities
- Brazil ANVISA harmonization:Emerging regulatory alignment between ANVISA and FDA quality system requirements is opening import pathways for validated reprocessors seeking South American market entry.
- Robotic surgery instrument reprocessing:Da Vinci surgical system accessory reprocessing represents an underpenetrated category where validated cleaning protocols for robotic end-effectors command premium pricing due to capital equipment concentration.
- Same-day surgical center distribution:Direct-to-site replenishment partnerships with ambulatory surgical centers bypass traditional hospital supply chain intermediaries, capturing margin through inventory velocity.
Industry Challenges
- ISO 13485 auditor scarcity:Certification body capacity constraints are extending quality management system audit timelines, delaying contract eligibility for reprocessors seeking integrated delivery network vendor status.
- Bioburden validation complexity:Establishing repeatable cleaning efficacy for protein-sensitive devices requires substantial capital investment in residual soil detection instrumentation and microbiological testing infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Medical Device Reprocessing Market |
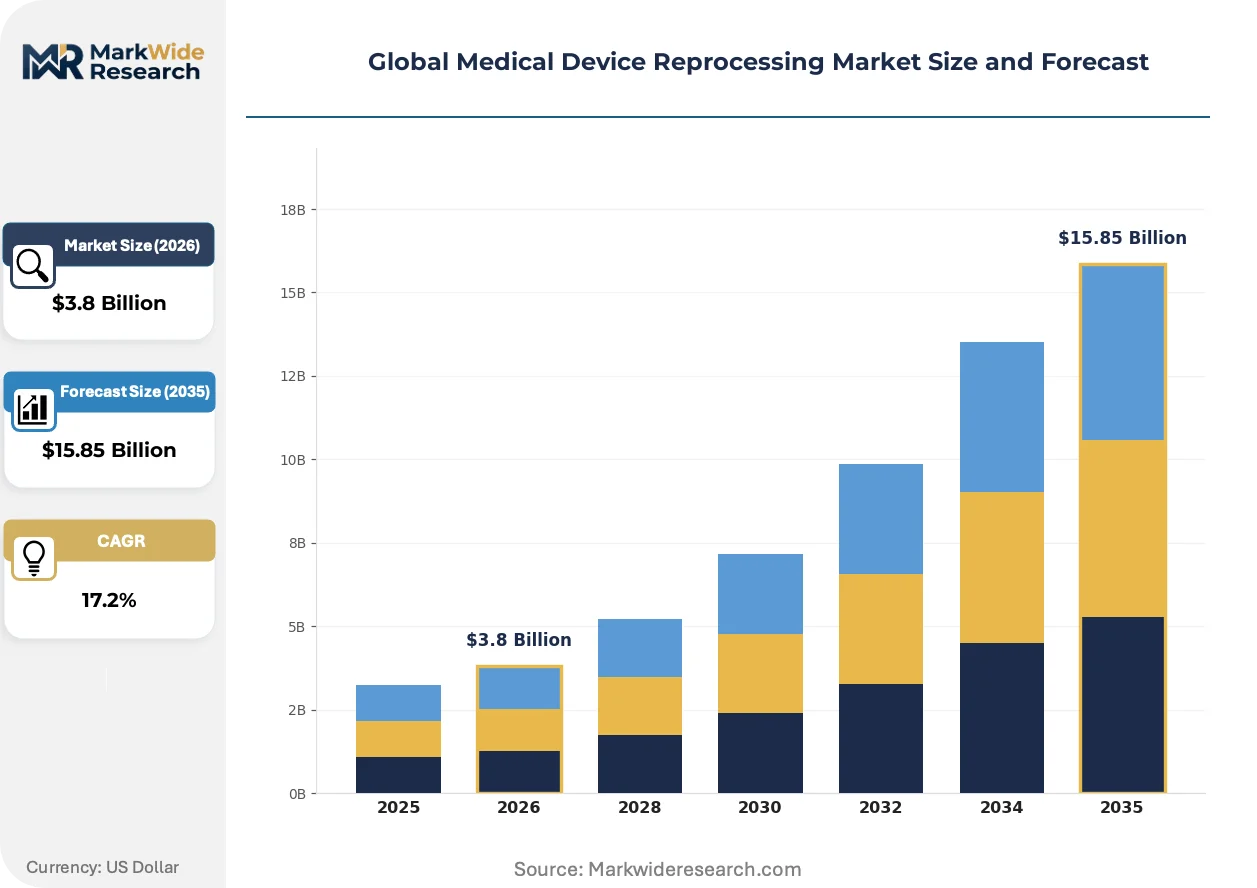
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $15.85 Billion |
| CAGR (2026 – 2036) | 17.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Use Devices, Semi-Critical Devices, Critical Devices, Diagnostic Instruments, Surgical Instruments Technology: Automated Sterilization, Manual Cleaning, Ultrasonic Cleaning, Chemical Disinfection, Thermal Disinfection Application: Hospitals, Ambulatory Surgical Centers, Dental Clinics, Diagnostic Laboratories, Long-Term Care Facilities End User Type: Healthcare Providers, Sterilization Service Providers, Medical Equipment Manufacturers, Infection Control Departments |
| Companies Covered | Stryker Corporation, Johnson & Johnson Services, Inc., Medline Industries, LP, Vanguard AG, Cardinal Health, STERIS, Arjo, NEScientific, Inc., SureTek Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Medical Device Reprocessing Market Shifts & Advancements
Automation is penetrating reprocessing workflows at divergent speeds across facility types, with capital deployment patterns revealing strategic bets on labor substitution versus quality assurance enhancement.
Radio-frequency identification tracking systems are integrating with hospital enterprise resource planning platforms to enable real-time location monitoring of reprocessed device inventory. United States health systems with centralized sterile processing departments are deploying these systems fastest, typically within 18-month implementation windows. The technology is integrating previously siloed supply chain data streams, compressing reconciliation cycles and reducing phantom inventory write-offs.
The European Union's Medical Device Regulation is mandating unique device identification compliance for all reprocessed devices entering EU member states, with full enforcement phasing through 2026. Reprocessors serving European markets are restructuring quality management systems to accommodate EUDAMED database registration and post-market surveillance obligations. Critical device categories including cardiovascular implants face the steepest documentation burdens, driving consolidation among reprocessors with limited regulatory affairs capacity.
Physician preference item committees are consolidating supplier rosters from an average of twelve reprocessing vendors to three or fewer per device category, centralizing purchasing authority within supply chain executives. This concentration is displacing incumbent reprocessors lacking integrated delivery network-scale validation infrastructure. The United States exhibits the most pronounced committee consolidation, with multi-hospital systems in Texas and California completing vendor rationalization programs during 2024-2025 contract cycles.
Global Medical Device Reprocessing Market Segmentation
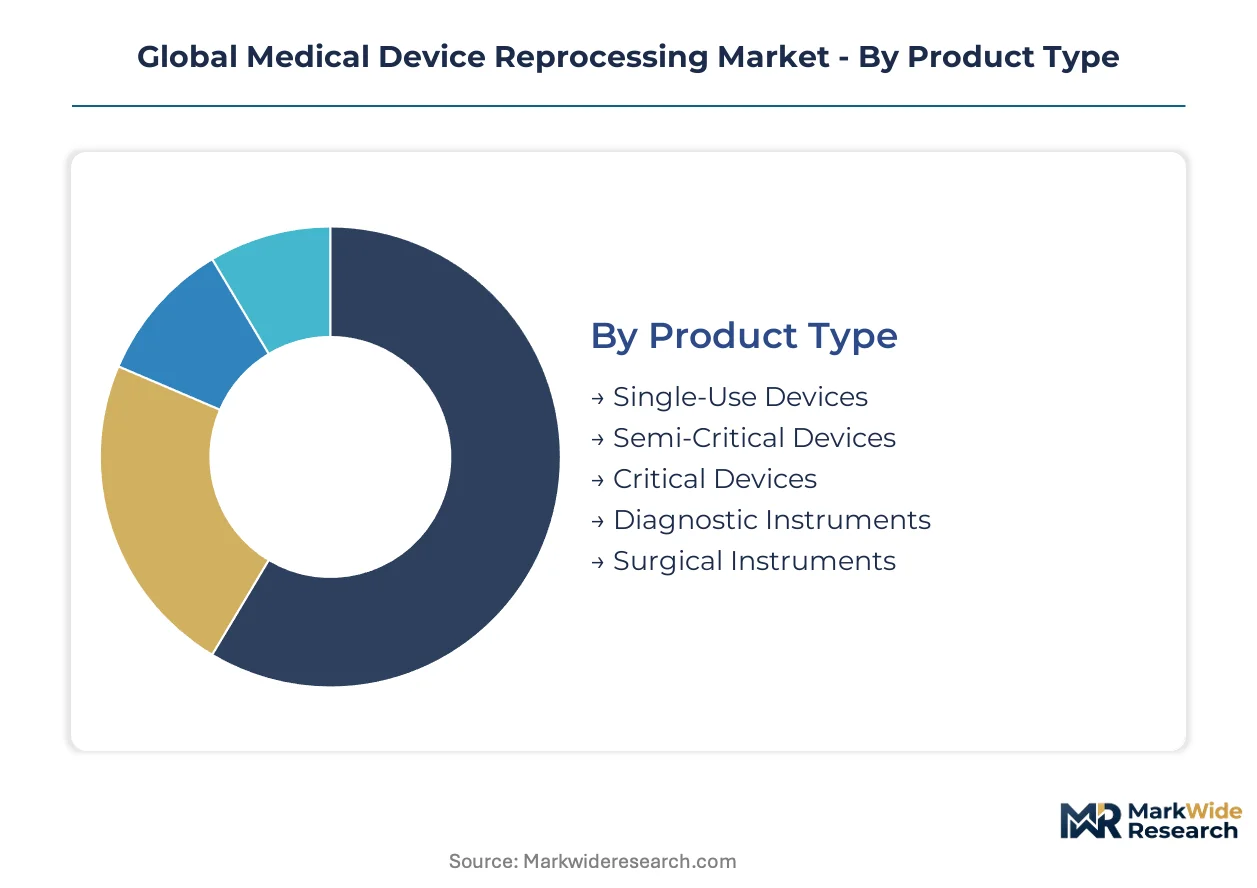
Segmentation in medical device reprocessing reveals where capital deployment, regulatory burden, and margin structure diverge across the value chain. Procurement patterns vary sharply by product risk classification and facility type, reshaping vendor targeting strategies.
Product Type:
Capital intensity escalates with device complexity and bioburden tolerance, creating tiered investment thresholds across reprocessing categories.
- Single-Use Devices:Polymer-based catheters, compression sleeves, and pulse oximeter probes undergo validated cleaning for limited reuse cycles. Demand concentrates in United States cardiac catheterization labs where SUD reprocessing reduces per-procedure supply costs by half under integrated delivery network procurement mandates.
- Critical Devices:Implantable cardiovascular stents and orthopedic fixation hardware require ISO 13485-validated sterilization with residual protein detection below 6.4 micrograms per square centimeter. German university hospitals and Swiss tertiary centers drive specification intensity due to EMA MDR post-market surveillance obligations.
- Semi-Critical Devices:Endoscopes and respiratory therapy equipment occupy intermediate regulatory classification with moderate bioburden validation requirements.
- Diagnostic Instruments:Ultrasound transducers and electrophysiology mapping catheters face material compatibility constraints with repeated sterilization cycles.
- Surgical Instruments:Stainless steel forceps, retractors, and clamps represent mature reprocessing with established steam sterilization protocols across all facility tiers.
Most installed capacity flows through Single-Use Devices. Expansion is steepest in Critical Devices.
Technology:
Technology selection tracks labor availability and throughput requirements, with automation premiums justified differently across facility scale.
- Automated Sterilization:Ethylene oxide and vaporized hydrogen peroxide chamber systems eliminate human variability in cycle parameter control. United States health systems with centralized sterile processing departments deploy these systems fastest, typically achieving payback within eighteen months through reduced technician headcount.
- Ultrasonic Cleaning:Cavitation-based soil removal for lumened devices and delicate instrument geometries requires lower capital outlay than automated sterilization lines. Ambulatory surgical centers in Texas and Florida adopt ultrasonic protocols to offset certified sterile processing technician shortages.
- Manual Cleaning:Brush and flush protocols for simple instrument geometries persist in low-volume settings with constrained capital budgets.
- Chemical Disinfection:High-level disinfection with ortho-phthalaldehyde or hydrogen peroxide solutions serves heat-sensitive endoscopes and flexible bronchoscopes.
- Thermal Disinfection:Steam and dry heat sterilization dominates surgical instrument reprocessing where material compatibility permits.
Automated Sterilization commands the highest capital commitment per installation. Ultrasonic Cleaning is climbing the fastest among mid-scale facilities.
Application:
Application segmentation reflects divergent supply chain velocity requirements and regulatory inspection frequency across care settings.
- Hospitals:Tertiary and community hospitals with on-site sterile processing departments manage the highest device throughput volumes. FDA quality system regulation enforcement and Joint Commission accreditation surveys drive compliance investment intensity in United States hospital systems exceeding three hundred beds.
- Ambulatory Surgical Centers:Freestanding surgical facilities perform lower-complexity procedures with same-day discharge protocols. Same-day replenishment partnerships with third-party reprocessors bypass traditional distribution intermediaries in California and Arizona markets.
- Dental Clinics:Handpiece and ultrasonic scaler reprocessing operates under state dental board regulations with variable sterilization monitoring requirements.
- Diagnostic Laboratories:Specimen collection device and centrifuge rotor reprocessing serves high-throughput testing operations with distinct workflow timing constraints.
- Long-Term Care Facilities:Urinary catheter and enteral feeding tube reprocessing faces staffing limitations and lower regulatory inspection frequency than acute care settings.
Hospitals absorb the majority of installed reprocessing infrastructure. Ambulatory Surgical Centers are gaining share fastest as procedure migration accelerates.
End User Type:
End user type determines whether reprocessing occurs within facility walls or through outsourced service relationships with distinct contracting structures.
- Healthcare Providers:Hospital and health system sterile processing departments manage reprocessing in-house or through hybrid models with third-party partners. Physician preference item committees in United States integrated delivery networks consolidate vendor rosters to three or fewer reprocessors per device category.
- Sterilization Service Providers:Third-party reprocessors like Stryker's Sustainability Solutions and Arjo's ReNu Medical operate FDA-registered facilities with dedicated validation laboratories. These providers capture multi-hospital system contracts through ISO 13485 certification and same-day logistics networks.
- Medical Equipment Manufacturers:Original equipment manufacturers maintain captive reprocessing capabilities for warranty service and customer retention in robotic surgery and advanced imaging modalities.
- Infection Control Departments:Hospital-based quality units oversee reprocessing audit protocols and bioburden surveillance without direct operational responsibility for device turnaround.
Healthcare Providers retain the largest share of direct reprocessing activity. Sterilization Service Providers are expanding most quickly as outsourcing accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sterile processing technicians concentrate in the United States, Germany, and Japan, anchoring the highest reprocessing volumes globally. These workforce clusters align with integrated delivery network procurement centralization and stringent regulatory enforcement corridors.
United States
Integrated delivery networks in Texas and California consolidate vendor contracts to three or fewer reprocessors per device category. FDA quality system regulation enforcement drives ISO 13485 certification mandates before contract eligibility. The Dallas-Fort Worth metroplex hosts centralized sterile processing departments deploying automated sterilization systems with eighteen-month payback cycles.
Germany
University hospitals in Bavaria and North Rhine-Westphalia specify residual protein detection below 6.4 micrograms per square centimeter for critical device reprocessing. EMA Medical Device Regulation conformity assessment extends market access timelines for reprocessed cardiovascular implants. The Stuttgart industrial corridor concentrates validation laboratory capacity serving EU-bound operators.
Switzerland
Tertiary centers in Zurich and Geneva drive specification intensity for orthopedic fixation hardware reprocessing under Swissmedic oversight. EUDAMED database registration requirements restructure quality management systems for post-market surveillance compliance. The Basel cluster anchors sterile processing innovation for implantable device categories.
Japan
Metropolitan Tokyo hospitals manage high-throughput endoscope reprocessing under PMDA sterilization monitoring protocols. METI industrial standards harmonize with ISO 17664 manufacturer instruction requirements for third-party reprocessors. The Osaka-Kobe manufacturing belt supplies automated cleaning equipment to domestic health systems.
Brazil
Cardiac catheterization labs in São Paulo and Rio de Janeiro adopt reprocessed single-use devices as ANVISA harmonizes quality system requirements with FDA benchmarks. Emerging regulatory alignment opens import pathways for validated reprocessors seeking South American market entry. The São Paulo state health system consolidates procurement across its hospital network.
Global Medical Device Reprocessing Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Hospital procurement consolidation compresses vendor margins while expanding contract volumes for scale operators, displacing smaller players to ambulatory surgical center niches. Three archetypes dominate: diversified medical technology conglomerates with reprocessing divisions, third-party sterilization service providers, and distribution-intensive supply chain operators. Competitive moves center on same-day logistics network expansion and ISO 13485 certification acceleration to capture integrated delivery network tenders.
Within the diversified conglomerate tier, Stryker Corporation and Johnson & Johnson Services, Inc. exemplify scale-driven positioning through endoscopy and sterilization technology leadership. Third-party specialists including Vanguard AG and STERIS occupy the service-provider archetype with FDA-registered validation laboratories. Medline Industries, LP anchors the distribution-intensive segment through replenishment velocity to ambulatory surgical centers.
| Leading Market Players |
|---|
| Stryker Corporation |
| Johnson & Johnson Services, Inc. |
| Medline Industries, LP |
| Vanguard AG |
| Cardinal Health |
| STERIS |
| Arjo |
| NEScientific, Inc. |
| SureTek Medical |
| Others |
Supply & Pricing Matrix
Captive sterile processing infrastructure within United States integrated delivery networks anchors both supply security and pricing leverage for reprocessed single-use devices. Hospital systems with centralized departments command volume discounts that compress third-party reprocessor margins while securing ISO 13485-validated supply continuity.
Pricing Analysis
Capacity additions in Texas and California are reshaping price floors for automated sterilization services as regional health systems consolidate vendor rosters. Contract-based long-term offtake dominates, with pricing stratifying across ISO 13485 certification tiers and same-day replenishment capability. Cost compression in ambulatory surgical center tiers is intensifying because technician staffing shortages elevate labor-adjusted costs. Ambulatory surgical centers exhibit highest price sensitivity; tertiary hospitals with captive processing departments least.
Supply Chain Analysis
Dual-sourcing requirements embedded in United States GPO contracts mandate multi-supplier qualification for critical device categories. Supply concentrates in the United States, Germany, and Japan for validation laboratory capacity and automated sterilization equipment. Raw material flows draw from medical-grade polymer suppliers, ethylene oxide sterilization agents, and RFID tracking components. Single-source vulnerability persists in proprietary robotic surgery instrument architectures. Distribution runs through same-day logistics networks serving integrated delivery networks and ambulatory surgical center partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in medical device reprocessing rests on automation-driven cost-down trajectories in labor-intensive cleaning workflows and premium-tier capture in critical device validation services.
For Market Incumbents: Hedge against original equipment manufacturer lockout protocols by deepening backward integration into polymer characterization laboratories and RFID-enabled inventory tracking systems. Consolidate vendor status within shrinking physician preference item committee rosters through accelerated ISO 13485 certification investments before audit timeline extensions delay contract eligibility. For New Entrants and Emerging Players: Freestanding ambulatory surgical centers in Arizona and Florida represent the most penetrable buyer archetype, underserved by same-day replenishment networks and facing acute sterile processing technician shortages. Capture initial volume through ultrasonic cleaning automation partnerships before expanding into automated sterilization service tiers. For Investors and Strategic Acquirers: Roll-up economics work for regional third-party reprocessors with FDA-registered validation laboratories because hospital procurement consolidation is displacing sub-scale operators lacking integrated delivery network logistics infrastructure. Monitor ANVISA-FDA regulatory harmonization progress as inflection indicator for South American market entry viability.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Acceleration | Contract eligibility with integrated delivery networks requires certification before vendor rationalization cycles conclude. |
| Same-Day Logistics Network Expansion | Ambulatory surgical center partnerships bypass traditional distribution intermediaries and capture inventory velocity premiums. |
| Robotic Surgery Instrument Validation | Da Vinci accessory reprocessing commands premium pricing due to capital equipment concentration and limited competition. |
| RFID-ERP Platform Integration | Real-time location monitoring compresses reconciliation cycles and reduces phantom inventory write-offs for hospital systems. |
| EUDAMED Database Registration | EU Medical Device Regulation compliance restructures quality management systems for European market access continuity. |
Research Methodology
Bottom-up hospital and ambulatory surgical center modeling reconciled against top-down sterilization service provider capacity tracking forms the analytical core of this study. Primary interviews with sterile processing department directors, hospital purchasing committee members, biomedical engineers, and GPO contracts managers combined with secondary validation from FDA 510(k) filings, hospital procurement databases, CMS Medicare cost reports, and ISO certification registries. Triangulation between demand-side utilization patterns and supply-side validation infrastructure investments ensures segment-level precision.
Input-output matrices map reprocessed device throughput against sterilization capacity deployment across product type, technology, application, and end user type dimensions over the projection horizon. CAGRs derive from segment-specific adoption curves weighted by regulatory approval timelines and procurement consolidation velocity. Forecast inputs incorporate FDA guidance expansion schedules for novel device categories and EMA MDR conformity assessment completion rates.
Underlying measurement precision varies by segment; single-use device reprocessing carries tighter precision than critical device categories where validation protocol heterogeneity expands uncertainty bands. Forecasts reflect assumptions regarding regulatory harmonization progress and integrated delivery network vendor consolidation speed. Deviation in FDA enforcement intensity or original equipment manufacturer lockout technology deployment would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Bench-Top Dental Autoclaves Market
Medical Equipment
India Massage Equipment Market
Medical Equipment
Medical Equipment Maintenance Market
Medical Equipment
Equine Operating Tables Market
Medical Equipment
Ultrasound Equipment Market
Medical Equipment
Urodynamic Equipment and Consumables Market
Medical Equipment
Bone Marrow Processing Systems Market
Medical Equipment
Histology Embedding System Market
Medical Equipment
Water Bath Market
Medical Equipment
Medication Pouch Inspection Systems Market
Medical Equipment
Global Capnography Equipment Market
Medical Equipment
North America Nuclear Medicine Equipment Market
Medical Equipment
Autopsy Saw Market
Medical Equipment
Hospital-at-Home Equipment Rental Market
Medical Equipment
North America Medical Device Reprocessing Market
Medical Equipment
Global Medical Lifting Slings Market