
 Germany Anesthesia Devices Market | 2026-2036
Germany Anesthesia Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Anesthesia Devices Market Foresight
Anesthesiologist workforce shortages across German hospital networks is unwinding surgical throughput and forcing capital investment into automation-capable anesthesia platforms. Drägerwerk AG leverages its Telford manufacturing base to sustain domestic supply security for critical care gas delivery systems. B. Braun Melsungen AG anchors its position through deep specialization in regional anesthesia disposables and closed-circuit breathing systems. GE Healthcare competes on digital integration, embedding its patient monitoring architectures into hospital IT backbone upgrades.
Germany anesthesia devices encompass electromechanical systems engineered to deliver precise gas mixtures—typically oxygen, nitrous oxide, and volatile anesthetics such as sevoflurane or desflurane—while maintaining automated ventilation parameters between 5-40 mL/kg tidal volumes and continuous capnography feedback loops for patient safety during induced unconsciousness. Anesthesia machines with integrated automatic ventilation modules command the dominant share of product-type revenue as German hospitals consolidate toward single-vendor workstation ecosystems. Digital integration technology represents the fastest-expanding technology dimension, driven by mandated connectivity to hospital electronic medical record systems and real-time alarm telemetry.
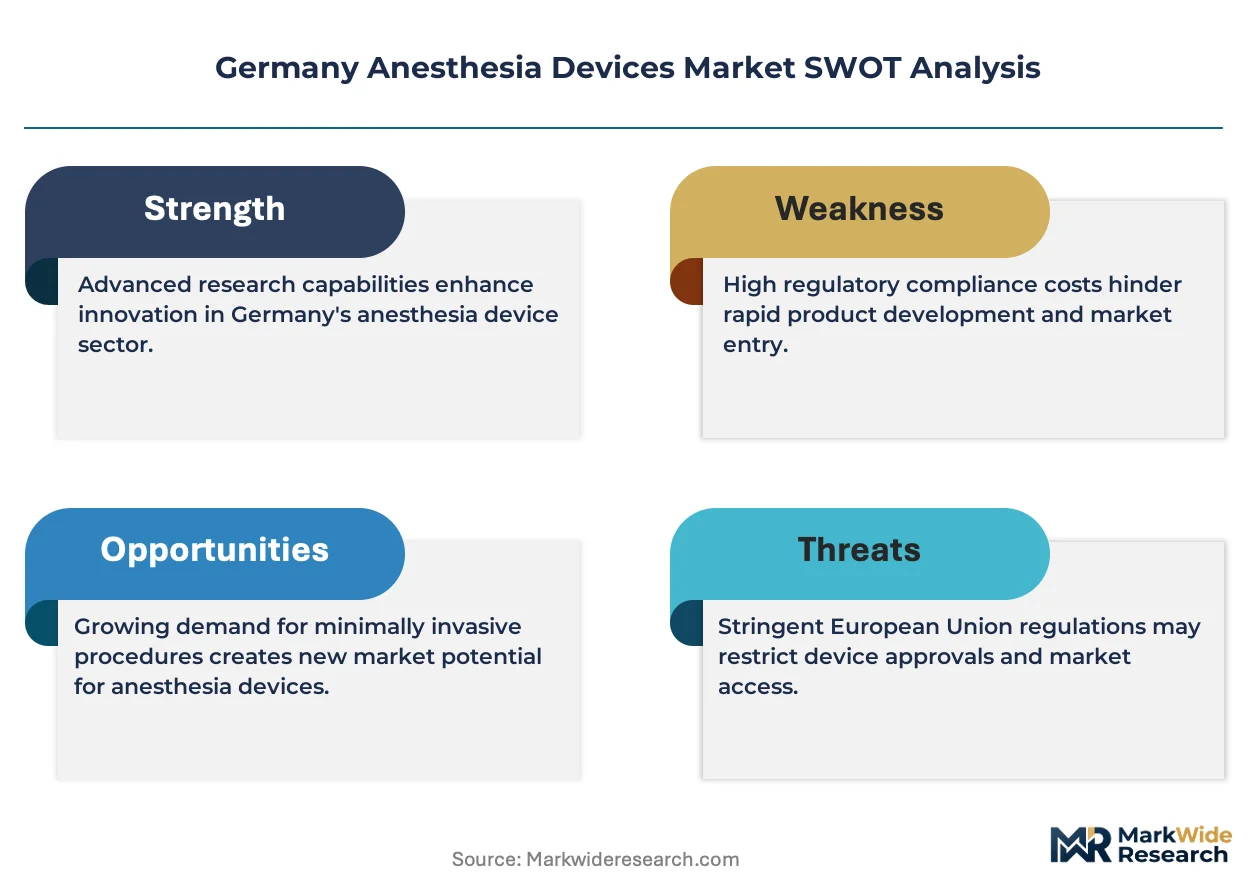
Germany's Federal Institute for Drugs and Medical Devices enforces EU MDR conformity assessment alongside BfArM vigilance reporting, elevating documentation burdens for manufacturers seeking market access. The EU AI Act introduces additional algorithmic transparency requirements for anesthesia monitoring software incorporating predictive analytics. Stakeholders must track how reimbursement shifts under Germany's DRG hospital payment reform affect capital equipment replacement cycles in outpatient surgical centers.
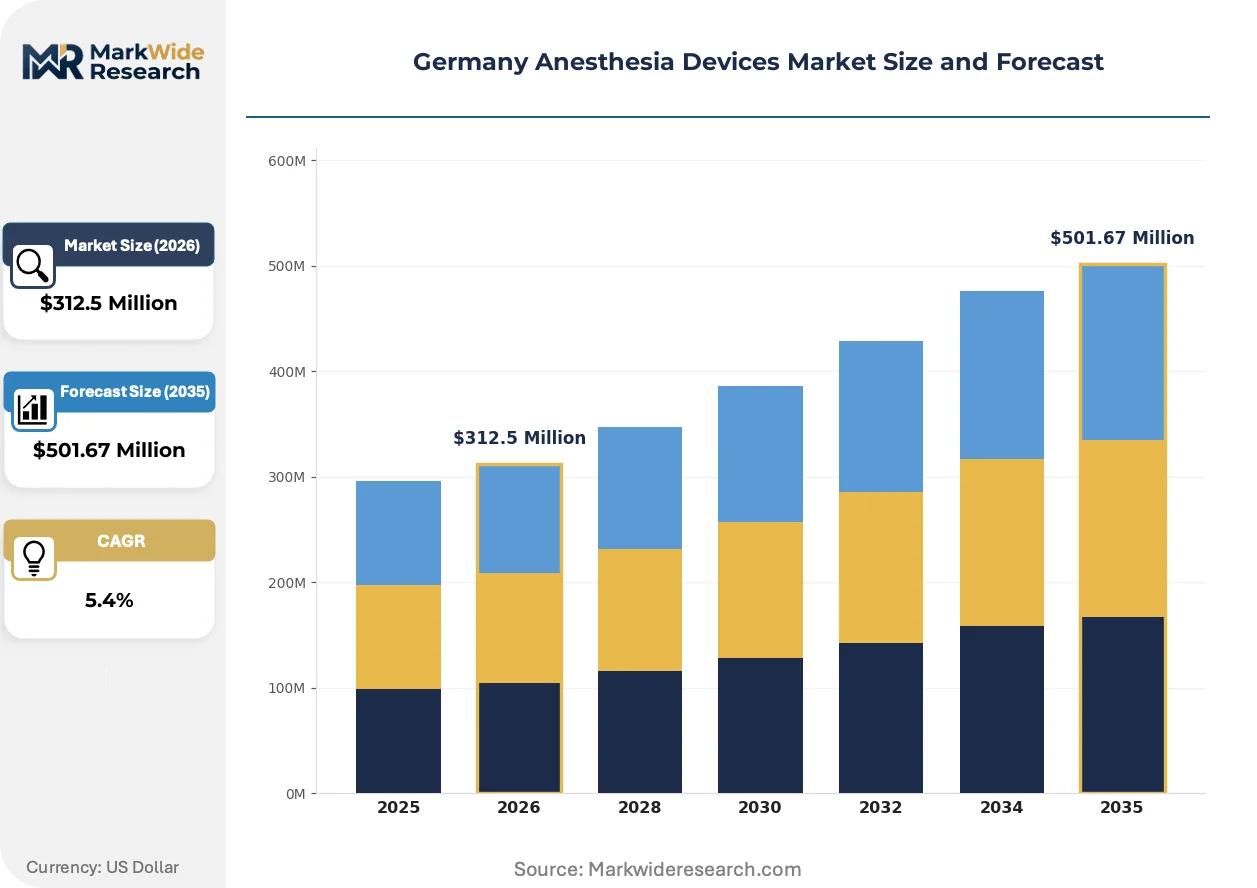
Market Dynamics
EU MDR conformity assessment is compressing vendor timelines while Baden-Württemberg's surgical hub concentrates procurement power among three university hospital networks. The structural force reshaping competitive positioning is regulatory documentation burden intersecting with buyer consolidation.
Growth Catalysts
- Workstation consolidation:German university hospitals are standardizing on single-vendor anesthesia ecosystems to reduce training overhead and spare part complexity. Heidelberg and Mannheim clusters anchor this procurement pattern.
- EU AI Act algorithmic transparency:Mandated documentation for predictive monitoring software is creating compliance-driven replacement cycles for anesthesia platforms lacking audit trails.
- Anesthesiologist workforce gaps:Labor shortages across hospital networks are forcing capital investment into automation-capable ventilation modules with closed-loop control.
Market Restraints
- MDR technical documentation:Elevated clinical evidence requirements for Class IIb devices are extending time-to-market by 18-24 months for workstation manufacturers.
- Supply concentration in Telford:Critical care gas delivery systems depend heavily on a single UK manufacturing base, exposing German buyers to post-Brexit customs friction and sterling volatility.
- Volatile sevoflurane input costs:Fluorinated anesthetic compound pricing fluctuates with EU F-Gas Regulation phase-down schedules and Chinese API export controls.
Strategic Opportunities
- Outpatient surgical center penetration:DRG payment reform is shifting volume toward ambulatory settings in Bavaria and North Rhine-Westphalia, creating demand for compact, portable anesthesia systems.
- Digital twin integration:Convergence of patient monitoring architectures with hospital IT backbone upgrades enables predictive maintenance and remote service revenue streams.
- Regional anesthesia disposable specialization:Closed-circuit breathing systems and catheter technologies represent underexploited white space as hospitals seek to reduce anesthetic gas waste and environmental compliance costs.
Industry Challenges
- BfArM vigilance reporting complexity:Post-market surveillance obligations for anesthesia incidents require dedicated regulatory affairs capacity that mid-tier manufacturers struggle to maintain.
- Legacy EMR integration:Real-time alarm telemetry connectivity demands API development against heterogeneous hospital information systems, stretching R&D budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Anesthesia Devices Market |
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $501.67 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anesthesia Machines, Vaporizers, Breathing Circuits, Ventilators, Monitoring Devices Technology: Gas Delivery, Electrical Monitoring, Automatic Ventilation, Safety Alarms, Digital Integration Application: Surgical Procedures, Pain Management, Intensive Care, Emergency Care End User: Hospitals, Outpatient Clinics, Surgical Centers, Specialty Care Facilities |
| Companies Covered | Drägerwerk AG, B. Braun Melsungen AG, GE Healthcare, Medtronic PLC, Koninklijke Philips NV, Mindray Medical International Limited, Fisher & Paykel Healthcare Limited, Smiths Group PLC, Ambu A/S, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Anesthesia Devices Market Shifts & Advancements
Automation architectures are reshaping how German hospitals configure anesthesia delivery, with three distinct vectors altering competitive dynamics across the forecast window.
Closed-loop anesthesia control systems are displacing manual vaporizer adjustment in university hospital settings. Heidelberg and Mannheim surgical hubs are piloting systems that automatically titrate propofol and remifentanil based on processed EEG signals. This displacement is compressing the role of traditional anesthesiologist oversight while elevating capital equipment specifications.
EU MDR Article 10 clinical evaluation requirements are forcing manufacturers to generate post-market clinical follow-up data for legacy workstation platforms. The industrial consequence is accelerated end-of-life declarations for devices lacking sufficient PMCF documentation. Anesthesia machines with integrated automatic ventilation modules face the steepest compliance burden due to their Class IIb designation.
Service contract unbundling is fragmenting how German hospitals acquire anesthesia platforms. Procurement teams in Baden-Württemberg are separating hardware acquisition from preventive maintenance and software updates, pressuring vendor margin structures. This behavioral shift is most visible among university hospital networks with dedicated clinical engineering departments capable of first-line service.
Germany Anesthesia Devices Market Segmentation
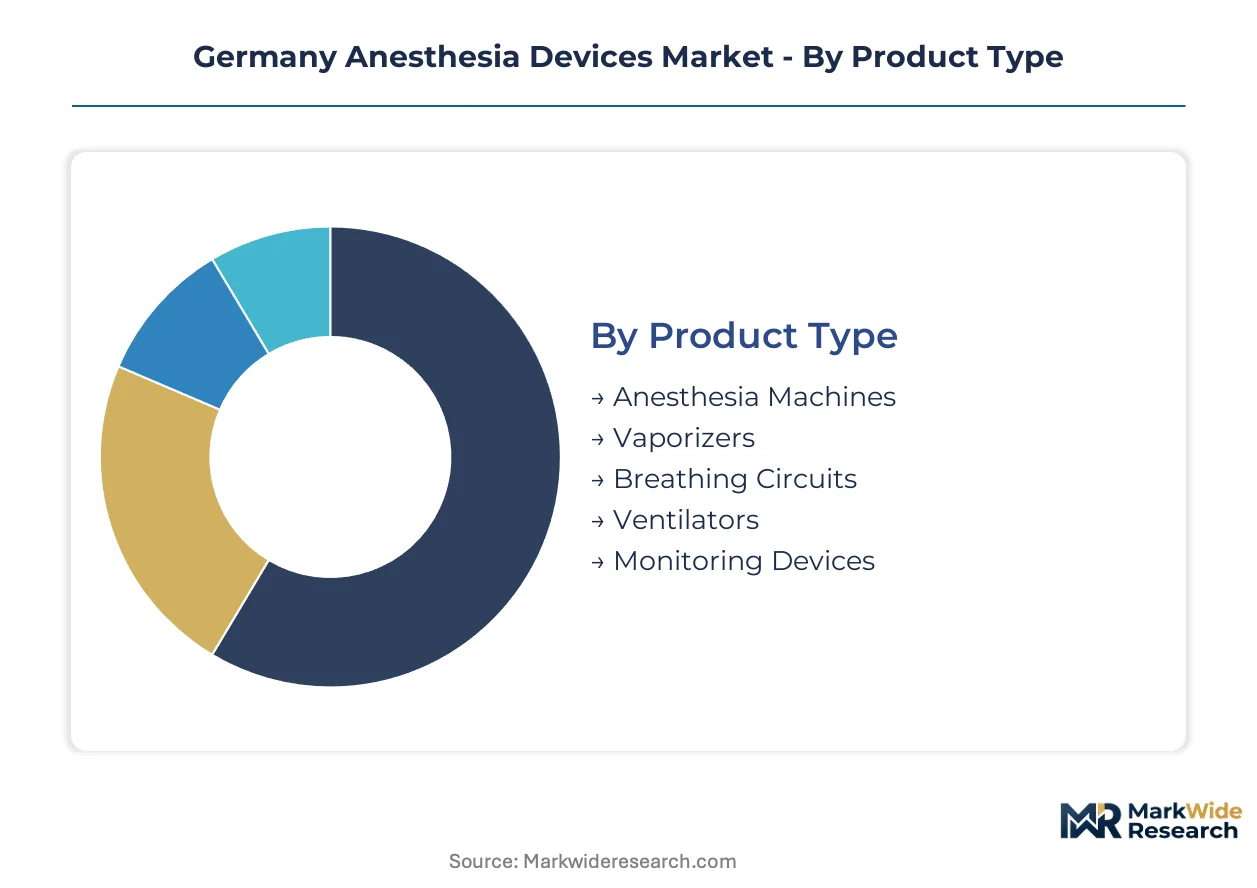
Segmentation reveals how procurement patterns diverge between Baden-Württemberg's university hospital networks and ambulatory settings across Bavaria. Understanding these splits exposes where automation investment concentrates versus where cost compression dominates purchasing criteria.
Product Type:
Domestic manufacturing in Telford anchors gas delivery systems for German hospital networks, while export-dependent vaporizer components face sterling volatility and customs friction post-Brexit.
- Anesthesia Machines:Integrated workstations with automatic ventilation modules dominate capital budgets in Heidelberg and Mannheim surgical clusters. Procurement teams standardize on single-vendor ecosystems to reduce training overhead and spare part complexity across university hospital networks.
- Vaporizers:Precision vaporizer units for sevoflurane and desflurane delivery face input cost pressure from EU F-Gas Regulation phase-down schedules and Chinese API export controls. Demand concentrates in tertiary care settings requiring volatile anesthetic flexibility.
- Breathing Circuits:Closed-circuit configurations reduce anesthetic gas waste and environmental compliance costs in high-volume surgical centers.
- Ventilators:Standalone ventilation modules see ambulatory demand in Bavaria's expanding outpatient surgical network.
- Monitoring Devices:Capnography and processed EEG systems integrate into hospital IT backbone upgrades for real-time alarm telemetry.
Anesthesia machines hold the largest share; momentum sits with monitoring devices as EU AI Act algorithmic transparency mandates drive replacement cycles.
Technology:
Cost tier stratification separates premium digital integration platforms from standard gas delivery systems, with mid-tier electrical monitoring occupying the contested middle ground.
- Gas Delivery:Oxygen-nitrous oxide mixing systems with precise flow control constitute the foundational layer of workstation architecture. Heidelberg procurement patterns favor integrated gas delivery over standalone configurations to minimize interface complexity.
- Digital Integration:EMR connectivity and predictive analytics software face steepening compliance burdens under EU AI Act documentation requirements. Baden-Württemberg university hospitals pilot digital twin architectures for remote service revenue capture.
- Electrical Monitoring:Continuous parameter tracking with automated alarm thresholds spans mid-tier hospital budgets.
- Automatic Ventilation:Closed-loop control modules address anesthesiologist workforce gaps through propofol and remifentanil titration.
- Safety Alarms:Capnography feedback loops with standardized alert protocols meet BfArM vigilance reporting obligations.
Gas delivery holds the largest share; digital integration gains share fastest as connectivity mandates harden.
Application:
Volume concentration in surgical procedures contrasts with margin opportunities in intensive care, where equipment utilization rates stretch replacement cycles.
- Surgical Procedures:Elective and emergency operative settings consume the majority of anesthesia workstation deployment in Mannheim and Heidelberg clusters. DRG payment reform is shifting volume toward ambulatory settings while maintaining capital intensity in university hospitals.
- Pain Management:Regional anesthesia techniques with catheter-based delivery systems represent underexploited white space as hospitals seek to reduce systemic anesthetic exposure. B. Braun Melsungen AG anchors this segment through disposable specialization.
- Intensive Care:Critical care gas delivery systems from Telford manufacturing serve prolonged ventilation scenarios with distinct maintenance protocols.
- Emergency Care:Portable configurations for rapid deployment face procurement constraints from compact footprint requirements.
Surgical procedures hold the largest share; pain management climbs fastest as regional anesthesia adoption accelerates.
End User:
Customer type stratification reflects the structural divide between consolidated university hospital networks and fragmented outpatient clinic procurement.
- Hospitals:University hospital networks in Baden-Württemberg concentrate procurement power through standardized workstation ecosystems. Service contract unbundling is fragmenting acquisition patterns as clinical engineering departments assume first-line maintenance.
- Outpatient Clinics:Bavaria and North Rhine-Westphalia ambulatory settings demand compact, portable anesthesia systems as DRG reform shifts surgical volume. Capital constraints favor leasing over ownership in this expanding channel.
- Surgical Centers:Dedicated operative facilities balance throughput requirements against space limitations in urban configurations.
- Specialty Care Facilities:Cardiac and neurological centers require specialized monitoring architectures with distinct integration protocols.
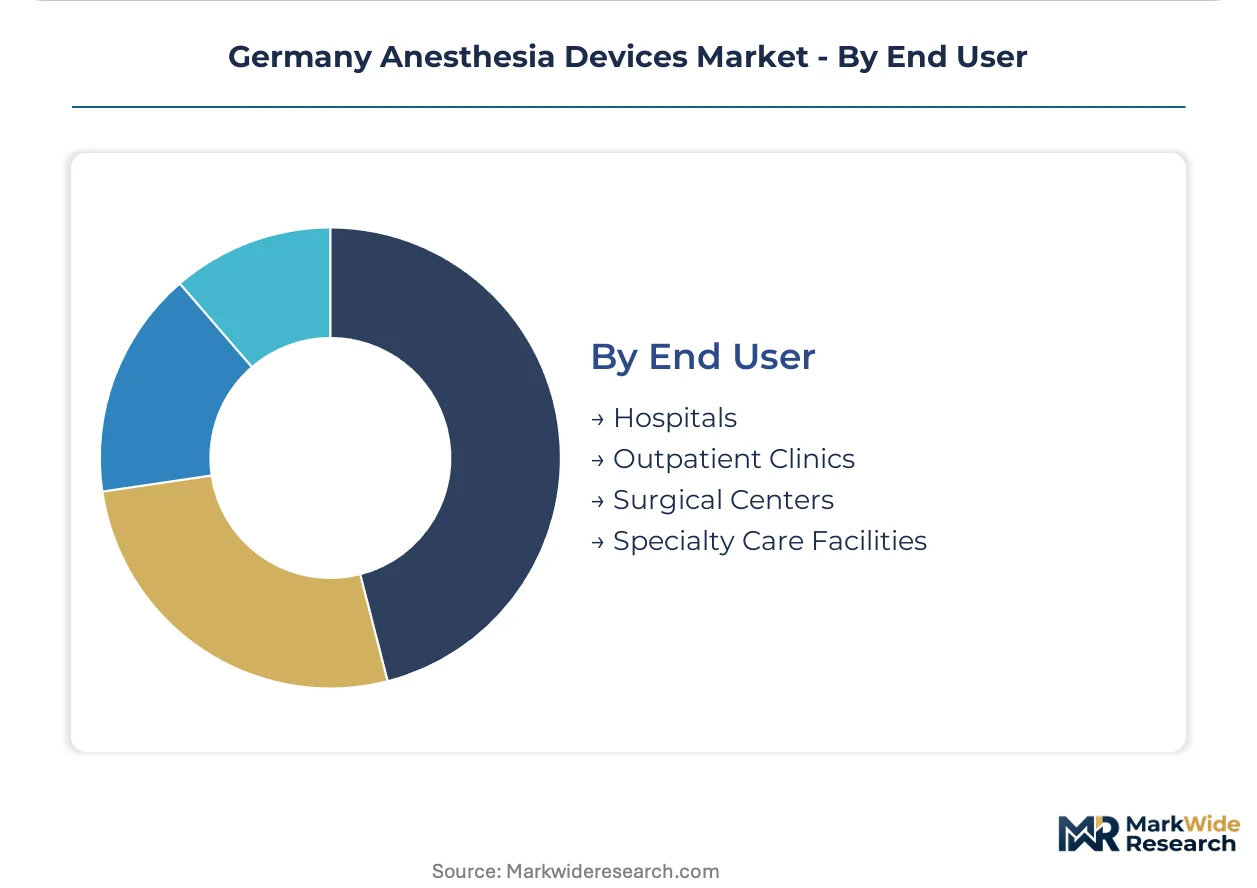
Hospitals hold the largest share; outpatient clinics expand most quickly as payment reform redirects surgical volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Baden-Württemberg commands procurement premiums for integrated anesthesia workstations while Bavaria's outpatient networks compress pricing on portable configurations. This pricing-power asymmetry between consolidated university hospital clusters and fragmented ambulatory settings defines regional competitive dynamics.
Baden-Württemberg
Heidelberg and Mannheim surgical hubs concentrate demand for single-vendor anesthesia ecosystems with automatic ventilation modules. KBA oversight of medical device transport logistics intersects with EU MDR conformity timelines. University hospital networks here standardize procurement to reduce training overhead and spare part complexity.
Bavaria
Ambulatory surgical centers drive demand for compact, portable anesthesia systems as DRG payment reform shifts volume away from inpatient settings. BfArM vigilance reporting obligations elevate documentation burdens for outpatient clinic operators. Munich and Nuremberg clusters anchor this channel expansion with capital-constrained procurement favoring leasing structures.
North Rhine-Westphalia
Outpatient clinic penetration accelerates fastest here, with Dortmund and Düsseldorf surgical networks seeking cost-optimized anesthesia platforms. EU F-Gas Regulation phase-down schedules pressure fluorinated anesthetic input costs. Regional hospital procurement coalitions leverage scale to negotiate service contract unbundling.
Lower Saxony
Hannover Medical School anchors tertiary care demand for closed-loop anesthesia control systems with processed EEG integration. BfArM post-market surveillance requirements concentrate regulatory affairs capacity among larger hospital operators. Wolfsburg industrial spillover creates adjacent demand for emergency care portable configurations.
Hesse
Frankfurt Rhine-Main metropolitan surgical networks balance university hospital standards against outpatient throughput pressures. EU AI Act algorithmic transparency mandates drive replacement cycles for anesthesia monitoring software lacking audit trails. Darmstadt technical university linkages support digital twin pilot programs for predictive maintenance revenue capture.
Germany Anesthesia Devices Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with consolidated university hospital procurement favoring integrated workstation ecosystems while ambulatory settings fragment toward specialized component suppliers. The vendor base organizes into three strategic tiers: diversified medical technology conglomerates with full-stack anesthesia platforms, mid-cap specialists in regional anesthesia disposables, and Asian-origin manufacturers competing on portable system cost structures. Dominant competitive moves include service contract unbundling to capture recurring revenue streams and M&A activity targeting digital integration capabilities for EMR connectivity.
Among Germany-based operators, Drägerwerk AG and B. Braun Melsungen AG occupy anchor positions representing contrasting strategic archetypes. Drägerwerk AG exemplifies the integrated workstation specialist with domestic manufacturing presence, while B. Braun Melsungen AG anchors the regional anesthesia disposable segment through closed-circuit breathing system specialization. GE Healthcare represents the diversified conglomerate tier competing on digital patient monitoring architectures embedded into hospital IT backbone upgrades.
| Leading Market Players |
|---|
| Drägerwerk AG |
| B. Braun Melsungen AG |
| GE Healthcare |
| Medtronic PLC |
| Koninklijke Philips NV |
| Mindray Medical International Limited |
| Fisher & Paykel Healthcare Limited |
| Smiths Group PLC |
| Ambu A/S |
| Others |
Supply & Pricing Matrix
Sevoflurane-to-desflurane substitution in German university hospitals is redrawing raw material sourcing geography while compressing margin structures across vaporizer component tiers. This input shift simultaneously exposes procurement teams to Chinese API export control volatility and EU F-Gas Regulation phase-down cost escalations, forcing price recalibration across workstation configurations.
Pricing Analysis
Baden-Württemberg university hospital networks command 15-20% procurement premiums over Bavarian outpatient clinics for identical anesthesia workstation specifications. Three-tier pricing structure across premium, standard, and economy levels separates integrated automatic ventilation modules from basic gas delivery configurations, with certification grade under EU MDR Article 10 serving as the primary price discriminator. Cost compression in economy-tier portable systems is intensifying because DRG payment reform redirects surgical volume toward ambulatory settings with capital-constrained budgets. Outpatient clinics in North Rhine-Westphalia exhibit highest price sensitivity, while Heidelberg and Mannheim tertiary centers prioritize single-vendor ecosystem standardization over unit cost minimization.
Supply Chain Analysis
Telford manufacturing concentration for critical care gas delivery systems creates a post-Brexit chokepoint exposing German buyers to sterling volatility and customs documentation friction. Component sourcing draws from UK precision engineering for gas mixing manifolds, Chinese API production for fluorinated anesthetic compounds, and German domestic fabrication for electronic control modules. Single-source vulnerability in Telford-based final assembly amplifies disruption risk from trade policy shifts. Distribution runs through hospital procurement coalitions in Baden-Württemberg and Bavaria, with regional GPOs consolidating bargaining power for university hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The scarcity of EU MDR-compliant PMCF documentation capacity is concentrating competitive advantage among manufacturers with dedicated clinical affairs infrastructure, while mid-tier players face accelerated obsolescence. This capability gap rewards early investment in post-market surveillance systems and regulatory intelligence functions.
For Market Incumbents: Shield installed base revenue through service contract unbundling that captures preventive maintenance and software update streams separately from hardware replacement cycles. Accelerate backward integration into vaporizer component production to offset Chinese API export control exposure. Prioritize BfArM vigilance reporting infrastructure investment as post-market surveillance obligations tighten compliance burdens for Class IIb devices. For New Entrants and Emerging Players: CE marking fast-track through notified body partnerships in Germany offers the most viable market entry pathway for anesthesia monitoring software with embedded AI diagnostics. Target Bavaria's outpatient surgical center expansion as the most penetrable geography, where DRG reform creates demand for compact portable configurations absent entrenched vendor relationships. Lead with leasing-based commercial models that circumvent capital ownership constraints among ambulatory clinic operators. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap regional anesthesia disposable specialists with closed-circuit breathing system IP and established B. Braun Melsungen AG supplier relationships. Long-term viability in this market hinges on algorithmic transparency compliance under EU AI Act mandates for predictive monitoring platforms. Monitor BfArM incident reporting database trends as the critical inflection signal for replacement cycle acceleration among legacy workstation platforms lacking sufficient audit trail documentation.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Conformity Pathway | Accelerated PMCF documentation investment compresses time-to-market for Class IIb workstation platforms. |
| Hospital System Partnership | Heidelberg and Mannheim university network standardization creates captive demand for single-vendor ecosystems. |
| Software Companion Development | Digital twin integration for predictive maintenance captures recurring revenue from Baden-Württemberg clinical engineering departments. |
| Reimbursement Strategy | DRG payment reform navigation determines outpatient clinic penetration success in Bavaria and North Rhine-Westphalia. |
| CE Marking Pathway | Notified body relationship depth differentiates market access speed for AI-enabled anesthesia monitoring entrants. |
Research Methodology
Initial hypotheses were tested against primary input from anesthesiologists, hospital procurement committee members, biomedical engineering directors, and GPO contracts managers, then refined through secondary validation against BfArM vigilance reports, EU MDR notified body guidance documents, hospital procurement databases, and DRG payment reform regulatory filings. Bottom-up demand modeling across product type, technology, application, and end user segments was cross-checked against top-down macroeconomic indicators for medical device capital expenditure.
Variance decomposition across the projection horizon isolates regulatory compliance timeline uncertainty, anesthesiologist workforce gap persistence, and DRG payment reform implementation pace as the three dominant forecast sensitivity drivers. Segmentation modeling incorporated gas delivery architecture, digital integration maturity, ventilation automation level, and regional hospital network consolidation status. CAGRs were derived from installed base replacement cycle analysis and ambulatory surgical center penetration elasticity estimates.
Decision-makers should treat outputs as directional under assumptions of steady EU MDR enforcement intensity and continued Baden-Württemberg university hospital procurement consolidation; material deviation in either would warrant model refresh. Practitioners should keep alternative scenarios live as Brexit trade friction evolution and Chinese API export policy shifts unfold.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Latin America Insulin Delivery Devices Market
Medical Devices
France Ophthalmic Devices Market
Medical Devices
Bone Conduction Hearing Devices Market
Medical Devices
Medication Dispensing and Packaging Systems Market
Medical Devices
Global Wearable Injectors Market
Medical Devices
Urolithiasis Management Devices Market
Medical Devices
Implantable Cardiac Rhythm Management Device Market
Medical Devices
Global Surgical Visualization Systems Market
Medical Devices
Surgical Robotics Performance and Safety Validation Test Platforms Market
Medical Devices
Next Generation Nebulizers Market
Medical Devices
Support Surfaces Market
Medical Devices
US Intrauterine Devices Market
Medical Devices
Germanium-68/Gallium-68 Generators Market
Medical Devices
Anesthesia Face Masks Market
Medical Devices
Bowel Stimulators Market
Medical Devices
Global Positive Airway Pressure Devices Market