
 Global Medical Equipment Cooling Market | 2026-2036
Global Medical Equipment Cooling Market Size, Share, and Industry Trends Forecast 2026-2036
Global Medical Equipment Cooling Market Foresight
Specialized thermal engineering talent is reorganizing competitive dynamics as OEMs struggle to source engineers fluent in both medical device validation and refrigerant transition protocols. Laird Thermal Systems leverages its European engineering base to dominate thermoelectric sub-assemblies for patient monitoring. Filtrine Manufacturing Company anchors North American hospital infrastructure through stainless-steel chiller systems designed for diagnostic imaging suites. Glen Dimplex Group competes on geographic breadth, sustaining manufacturing presence across multiple continents to reduce lead times for liquid cooling hardware.
Medical equipment cooling encompasses engineered thermal management systems that maintain precise temperature thresholds—typically between 15°C and 25°C for sensitive electronics—using vapor-compression, thermoelectric, or liquid-cooled architectures to prevent imaging artifact, laser drift, or reagent degradation. Chillers retain the largest installed base across diagnostic imaging suites, yet liquid cooling systems are expanding fastest as MRI magnet bore densities and proton therapy beam currents escalate thermal loads beyond air-cooled thresholds. Compressor coolers occupy the mature margin pool in dental equipment and smaller laboratory devices where specification tolerance bands remain wider.
FDA 21 CFR Part 820 quality system regulations and EU MDR technical documentation requirements are forcing thermal subsystem suppliers to elevate validation traceability, while REACH and F-Gas Regulation phase-downs are accelerating refrigerant chemistry transitions across European supply chains. ISO 13485 medical device quality management standards govern contract manufacturer qualifications, creating barriers for cooling specialists lacking established quality infrastructure. Stakeholders must weigh refrigerant portfolio transitions against validation cycle investments as regulatory timelines compress and thermal performance benchmarks tighten simultaneously.
Market Dynamics
Refrigerant chemistry transitions under EU F-Gas Regulation and EPA AIM Act are compressing validation cycles as thermal subsystem suppliers must requalify hardware while maintaining ISO 13485 compliance. This dual regulatory pressure is restructuring competitive positions around engineering talent capable of managing simultaneous refrigerant swaps and medical device documentation.
Growth Catalysts
- EU MDR technical documentation mandates:Thermal validation protocols for diagnostic imaging equipment are tightening across European hospital procurement, forcing cooling subsystem upgrades that expand addressable hardware demand.
- Proton therapy beam current escalation:Oncology centers in the United States and Japan are installing higher-power particle accelerators that exceed air-cooled thermal thresholds, pulling liquid cooling infrastructure into radiation therapy suites.
- MRI magnet bore density increases:Superconducting magnet manufacturers are packing more coil layers per unit volume, generating heat flux densities that demand specialized chiller architectures in diagnostic imaging networks.
Market Restraints
- Specialized copper and aluminum alloy sourcing:Heat exchanger fabricators face input cost volatility as electrification demand across automotive and energy storage sectors competes for identical thermal-grade metals.
- European refrigerant supply concentration:F-Gas phase-down quotas are consolidating production among three major chemical suppliers, creating allocation risk for chiller OEMs dependent on R-134a and R-410A alternatives.
- Thermoelectric efficiency ceiling:Peltier device coefficient of performance remains fundamentally bounded by material physics, limiting thermoelectric cooling to sub-kilowatt medical applications regardless of manufacturing advances.
Strategic Opportunities
- Indian diagnostic imaging fleet expansion:CDSCO medical device registration reforms are accelerating MRI and CT scanner imports, creating first-mover advantage for cooling suppliers establishing local service infrastructure.
- Point-of-care ultrasound thermal management:Handheld imaging devices with embedded AI processors are generating localized heat loads that exceed passive dissipation, opening miniaturized active cooling module demand.
- Japan METI carbon neutrality roadmap:Hospital energy efficiency mandates are creating retrofit incentives for magnetic bearing chillers that eliminate oil lubricants and reduce maintenance intervals in imaging suites.
Industry Challenges
- Dual-competency engineering scarcity:Refrigeration technicians fluent in both vapor-compression physics and FDA 21 CFR Part 820 quality documentation are concentrated among a handful of contract manufacturers, constraining scaling capacity.
- Legacy chiller integration complexity:Hospital infrastructure teams face mechanical incompatibility when retrofitting modern low-GWP refrigerant systems onto existing piping networks designed for phased-out chemistries.
- ISO 13485 certification timeline compression:Contract manufacturers must complete quality system audits while simultaneously requalifying thermal hardware for new refrigerant portfolios, stretching engineering bandwidth across parallel workstreams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Medical Equipment Cooling Market |
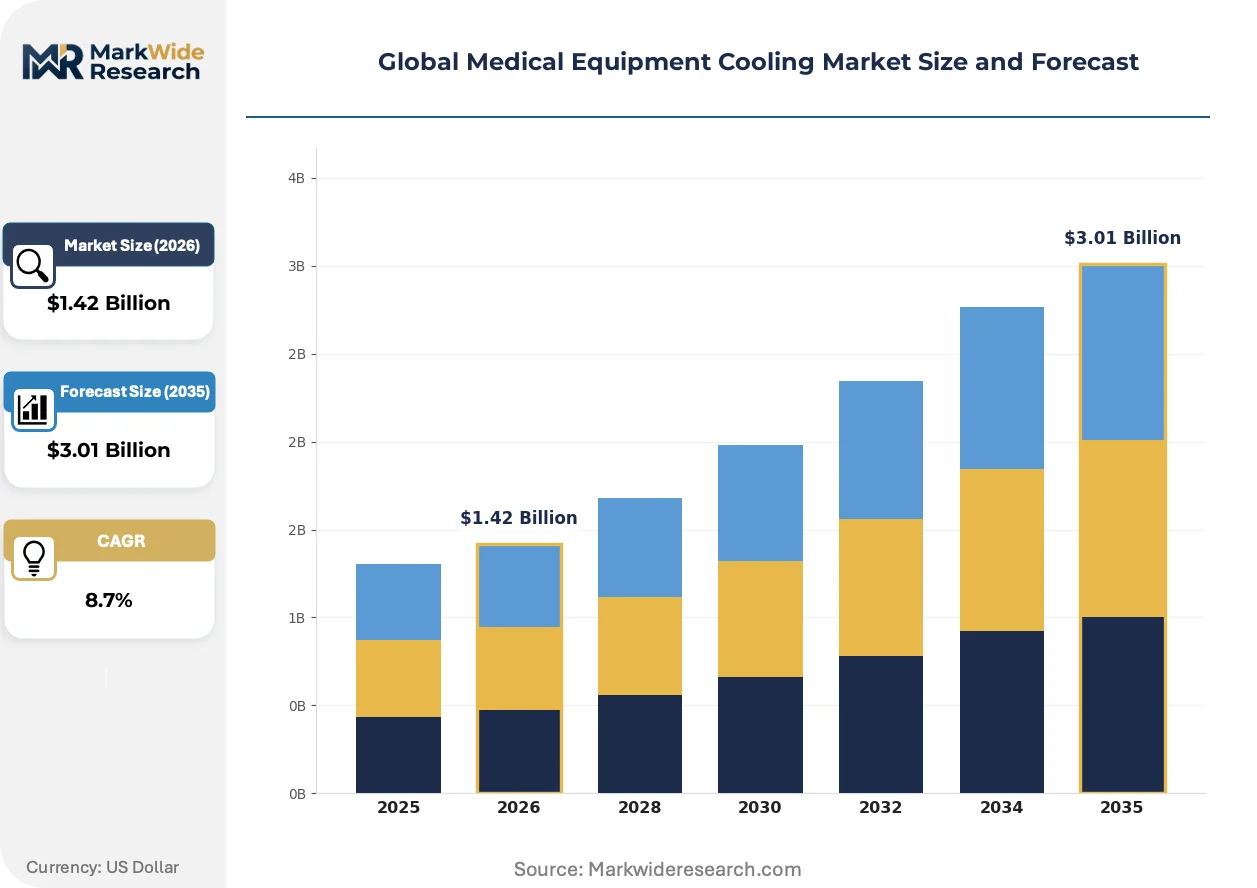
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $3.01 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chillers, Thermoelectric Coolers, Heat Exchangers, Compressor Coolers, Liquid Cooling Systems Cooling Technology: Air Cooling, Liquid Cooling, Phase Change Material, Magnetic Cooling, Spray Cooling Application: Diagnostic Imaging, Surgical Equipment, Laboratory Devices, Patient Monitoring Systems, Dental Equipment End User: Hospitals, Diagnostic Centers, Research Institutes, Outpatient Facilities, Specialty Clinics |
| Companies Covered | Laird Thermal Systems, Filtrine Manufacturing Company, Glen Dimplex Group, Johnson Thermal Systems, General Air Products, KKT Chillers, Drake Refrigeration, Motivair Corporation, American Chillers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Medical Equipment Cooling Market Shifts & Advancements
Medical equipment cooling is experiencing architectural fragmentation as thermal loads diverge across imaging modalities and regulatory pressures force refrigerant portfolio diversification. Three distinct vectors are reshaping supplier strategies and buyer procurement patterns.
Dielectric fluid immersion cooling is bifurcating the high-power imaging segment. This technology submerges power electronics directly in engineered fluids with high heat capacity and electrical insulation properties. Proton therapy system manufacturers in Germany and the United States are adopting immersion architectures for beam steering assemblies that generate megawatt-scale thermal pulses. The market is bifurcating between air-cooled legacy installations and liquid-cooled next-generation platforms, with the latter commanding premium positioning in radiation oncology procurement.
REACH authorization requirements for per- and polyfluoroalkyl substances are forcing refrigerant chemistry transitions across European supply chains. ECHA has listed several legacy heat transfer fluids as substances of very high concern, compelling chiller OEMs to reformulate thermal loops before 2026 sunset dates. Diagnostic imaging equipment manufacturers with European installed bases are accelerating validation programs for hydrofluoroolefin and natural refrigerant alternatives, compressing supplier qualification timelines.
Hospital procurement teams are unbundling cooling hardware from imaging system OEM contracts to secure independent service lifecycle control. Large integrated delivery networks in the United States are negotiating direct chiller supply agreements separate from MRI and CT scanner purchases, then contracting third-party thermal specialists for maintenance. This disintermediation is most visible in Texas and California health systems where energy cost volatility has elevated cooling efficiency to C-suite capital planning visibility.
Global Medical Equipment Cooling Market Segmentation
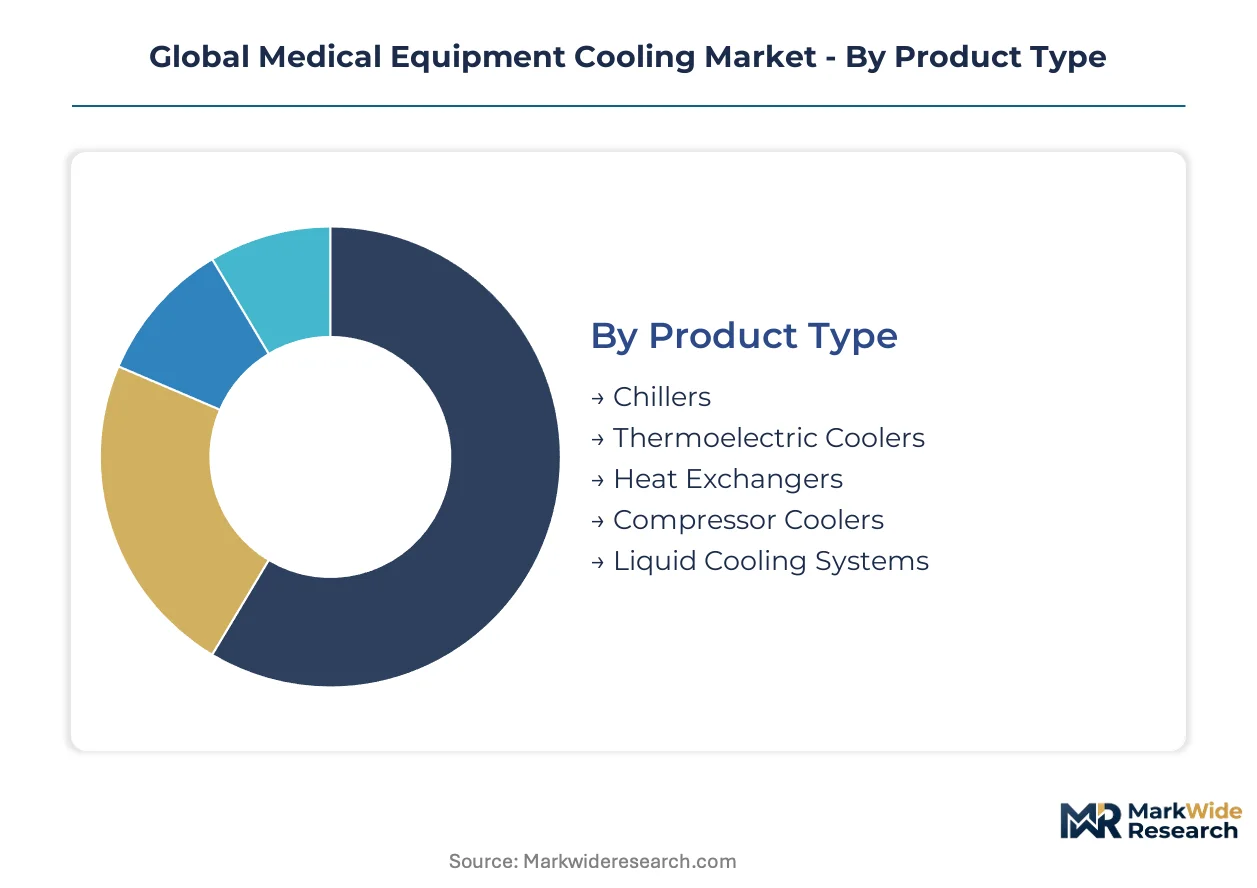
Thermal load profiles diverge sharply across imaging modalities, forcing cooling architectures to specialize by power density and precision requirements. Segmentation clarity enables suppliers to align refrigerant portfolios and validation investments against specific regulatory and performance thresholds.
Product Type:
Liquid cooling systems face the strongest substitution pressure as dielectric immersion architectures encroach on high-power imaging applications, while thermoelectric coolers confront fundamental material efficiency limits that cap addressable load ranges.
- Chillers:Vapor-compression systems using R-134a, R-410A, or low-GWP alternatives circulate chilled water or glycol through MRI and CT scanner thermal loops. Hospital networks in Germany and the United States anchor installed base renewal cycles as FDA and EU MDR validation timelines compress procurement windows.
- Liquid Cooling Systems:Pumped dielectric fluid architectures handle heat flux densities exceeding 500 W/cm² in proton therapy beam steering assemblies. Oncology centers in Japan and the United States are retrofitting radiation suites as beam current escalation outpaces air-cooled dissipation capacity.
- Thermoelectric Coolers:Solid-state Peltier devices provide sub-kilowatt precision cooling for patient monitoring modules and portable diagnostic equipment.
- Heat Exchangers:Brazed aluminum or copper-fin assemblies transfer thermal energy between primary and secondary loops in hybrid cooling architectures.
- Compressor Coolers:Compact refrigeration units serve dental equipment and benchtop laboratory devices with wider specification tolerance bands.
Chillers anchor the volume base while liquid cooling systems gain share at the steepest rate.
Cooling Technology:
Cost tier stratification separates premium liquid-cooled installations from economy air-cooled alternatives, with phase change and magnetic architectures occupying mid-tier positioning for specialized applications.
- Liquid Cooling:Forced convection through cold plates or immersion baths manages megawatt-scale thermal pulses in proton therapy and high-field MRI systems. German and U.S. equipment manufacturers specify these architectures for installations exceeding 7 Tesla magnet bore densities.
- Air Cooling:Finned heat sinks and blower assemblies serve lower-power dental and laboratory equipment where space constraints and maintenance simplicity outweigh efficiency premiums.
- Phase Change Material:Latent heat absorption buffers transient thermal spikes in portable ultrasound and point-of-care devices.
- Magnetic Cooling:Magnetocaloric effect systems eliminate refrigerant gases entirely, aligning with Japan METI carbon neutrality mandates for hospital energy efficiency retrofits.
- Spray Cooling:Atomized dielectric fluid impingement targets hot spots in laser surgical equipment with localized heat flux concentration.
Air cooling retains the widest installed footprint though liquid cooling climbs the fastest as imaging power densities escalate.
Application:
Customer procurement maturity varies by clinical setting, with diagnostic imaging commanding capital-intensive thermal infrastructure while dental and laboratory segments prioritize equipment cost over lifecycle efficiency.
- Diagnostic Imaging:MRI, CT, and PET-CT systems require continuous temperature stability within ±0.5°C to prevent image artifact and magnet quench. Hospital networks in Japan and Germany lead fleet renewal investments as superconducting coil densities increase thermal loads.
- Surgical Equipment:Laser and electrosurgical systems generate localized heat requiring active dissipation to maintain cut precision and tissue safety margins.
- Patient Monitoring Systems:Thermoelectric modules manage processor temperatures in bedside and wearable devices with embedded AI inference engines.
- Laboratory Devices:PCR thermal cyclers and analytical instrumentation use compressor or thermoelectric cooling for reagent temperature stability.
- Dental Equipment:CAD/CAM milling systems and curing lights operate with wider thermal tolerances, accepting simpler air-cooled or compressor-based solutions.
Diagnostic imaging commands the largest capital allocation while patient monitoring systems expand most quickly through point-of-care device proliferation.
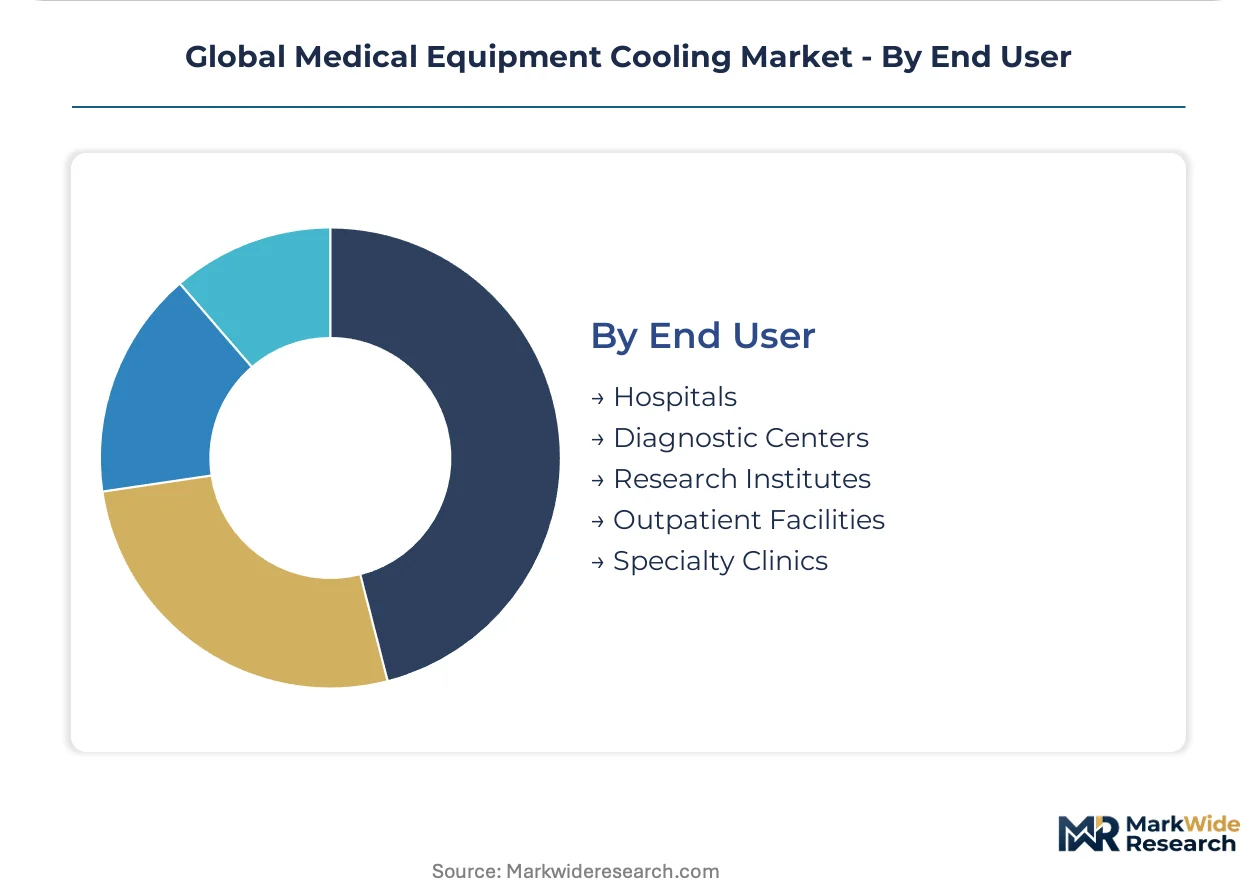
End User:
Geographic concentration of procurement authority shapes supplier engagement models, with integrated delivery networks in mature markets disintermediating cooling hardware from imaging OEM bundles.
- Hospitals:Acute care facilities with imaging fleet ownership negotiate direct chiller supply agreements separate from MRI and CT scanner purchases. Texas and California health systems have pioneered this unbundling to secure independent service lifecycle control.
- Diagnostic Centers:Specialized imaging facilities concentrate CT and MRI throughput, driving higher utilization rates and more demanding thermal reliability requirements.
- Research Institutes:Preclinical imaging and proton therapy development sites specify custom thermal architectures for experimental beam parameters.
- Outpatient Facilities:Ambulatory surgical centers and urgent care clinics deploy compact cooling solutions for point-of-care ultrasound and minor surgical equipment.
- Specialty Clinics:Cardiology, oncology, and orthopedic focused practices install modality-specific cooling for catheterization labs and radiation therapy suites.
Hospitals dominate current procurement volume though diagnostic centers are expanding capacity fastest as imaging services decentralize from acute care campuses.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German hospital networks command 15-20% pricing premiums on chiller service contracts versus comparable installations in India, reflecting divergent regulatory validation burdens and engineering labor scarcity. This asymmetry shapes supplier footprint decisions across mature and emerging markets.
United States
Integrated delivery networks in Texas and California pioneered unbundled chiller procurement from MRI and CT scanner OEM contracts. EPA AIM Act refrigerant phase-down timelines compress thermal hardware requalification cycles. The Greater Boston corridor concentrates proton therapy center construction, pulling liquid cooling infrastructure into radiation oncology suites.
Germany
EU F-Gas Regulation quota allocations concentrate refrigerant supply among three chemical suppliers, elevating input cost volatility for chiller OEMs. REACH authorization requirements for per- and polyfluoroalkyl substances force heat transfer fluid reformulation before 2026 sunset dates. Bavaria's medical technology cluster around Erlangen anchors superconducting magnet manufacturing, driving specialized chiller demand.
Japan
METI carbon neutrality mandates create retrofit incentives for magnetic bearing chillers that eliminate oil lubricants in imaging suites. Superconducting coil density increases in 7 Tesla MRI systems exceed air-cooled thermal thresholds. The Kansai region around Osaka concentrates diagnostic imaging fleet renewal investments.
India
CDSCO medical device registration reforms accelerate MRI and CT scanner imports into diagnostic imaging networks. Maharashtra and Karnataka states attract first-mover cooling suppliers establishing local service infrastructure. Mumbai-Pune corridor hospitals concentrate procurement authority for imported imaging equipment.
China
NMPA medical device quality management standards tighten thermal validation documentation requirements for imported cooling subsystems. Yangtze River Delta hospital networks accelerate imaging fleet expansion. Shanghai's medical equipment distribution hubs concentrate chiller import logistics and technical service capacity.
Global Medical Equipment Cooling Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the medical equipment cooling market. European engineering-intensive specialists dominate thermoelectric and precision liquid cooling segments where FDA and EU MDR validation traceability commands premium positioning. North American fabricators anchor hospital infrastructure through stainless-steel chiller systems designed for diagnostic imaging reliability. Scale-driven Asian manufacturers compete on component cost for compressor-based dental and laboratory equipment. Consolidation pressure intensifies as refrigerant chemistry transitions and ISO 13485 certification timelines compress engineering bandwidth across parallel workstreams.
Among European engineering-intensive specialists, Laird Thermal Systems and KKT Chillers occupy positions emphasizing thermal subsystem integration for patient monitoring and diagnostic imaging applications. Glen Dimplex Group exemplifies geographic breadth strategies, sustaining manufacturing presence across multiple continents to reduce lead times for liquid cooling hardware. North American fabricators including Filtrine Manufacturing Company and Motivair Corporation represent infrastructure-anchored archetypes focused on hospital network service lifecycle control. These named entities illustrate competitive positioning around validation capability, geographic coverage, and installed base maintenance rather than homogeneous product competition.
| Leading Market Players |
|---|
| Laird Thermal Systems |
| Filtrine Manufacturing Company |
| Glen Dimplex Group |
| Johnson Thermal Systems |
| General Air Products |
| KKT Chillers |
| Drake Refrigeration |
| Motivair Corporation |
| American Chillers |
| Others |
Supply & Pricing Matrix
Twelve-to-sixteen-week lead times for specialized copper-aluminum heat exchangers concentrate pricing power among German and Japanese fabricators serving FDA-validated chiller OEMs, compressing margin buffers for second-tier suppliers competing on standard compressor-based dental equipment.
Pricing Analysis
German hospital networks pay fifteen-to-twenty percent service contract premiums versus comparable Indian installations. Three-tier pricing structure across premium, standard, and economy levels separates ISO 13485-certified thermal subsystems from commodity compressor units. Pricing pressure stems from F-Gas quota allocations consolidating refrigerant supply among three European chemical suppliers. Diagnostic imaging OEMs show least price sensitivity due to bundled validation liability, while dental equipment distributors face acute cost compression.
Supply Chain Analysis
Ninety-day inventory cycles for R-134a and R-410A alternatives expose chiller OEMs to allocation risk under EU F-Gas phase-down quotas. Manufacturing concentrates in Germany, the United States, and China, with Bavaria's medical technology cluster anchoring superconducting magnet thermal subsystem production. Supply chains draw from specialized copper and aluminum alloy mills, refrigerant chemical suppliers, and precision pump manufacturers. Single-source vulnerability runs through European heat transfer fluid producers facing REACH authorization deadlines. Distribution runs through hospital GPO contracts, imaging OEM bundling agreements, and third-party thermal service specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment defensive moat. ISO 13485 certification timelines and FDA 21 CFR Part 820 validation documentation create switching costs that protect incumbent positions against unqualified entrants.
For Market Incumbents: Secure refrigerant portfolio transition capacity before EU F-Gas sunset deadlines compress requalification windows. Anchor hospital service lifecycle control through direct chiller supply agreements that disintermediate imaging OEM bundling. Vertical integration into magnetic bearing compressor manufacturing captures Japan METI retrofit incentives while eliminating oil-lubricant maintenance liabilities. For New Entrants and Emerging Players: Differentiate on dielectric fluid immersion architectures for proton therapy beam steering assemblies where thermal flux densities exceed legacy air-cooled thresholds. Target Maharashtra and Karnataka states in India where CDSCO registration reforms accelerate MRI and CT scanner imports without established local cooling service infrastructure. Lead with rapid-response field service capabilities rather than equipment cost positioning. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because refrigerant chemistry transitions and ISO 13485 certification compression are stretching engineering bandwidth across parallel workstreams. Target contract manufacturers with dual-competency talent pools spanning vapor-compression physics and FDA quality documentation. Monitor EU F-Gas quota allocation announcements as inflection indicators for input cost volatility and supplier distress.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Portfolio Transition | EU F-Gas phase-down quotas force heat transfer fluid reformulation before REACH authorization deadlines. |
| Hospital GPO Contracting | Texas and California health systems unbundle cooling hardware from MRI and CT scanner OEM purchases. |
| Magnetic Bearing Chiller Development | Japan METI carbon neutrality mandates create retrofit demand for oil-free compressor architectures. |
| Indian Service Infrastructure Buildout | CDSCO reforms accelerate diagnostic imaging imports into Maharashtra and Karnataka hospital networks. |
| Dielectric Immersion Cooling Partnership | German and U.S. proton therapy manufacturers specify submerged power electronics for megawatt-scale thermal pulses. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with thermal subsystem engineers, hospital biomedical equipment managers, GPO contracts administrators, and refrigerant supply specialists; and secondary validation through FDA 510(k) filings, EU MDR technical documentation databases, EPA AIM Act regulatory dockets, and customs trade records for heat exchanger alloy imports. Bottom-up equipment installation tracking triangulated against top-down hospital capital expenditure surveys across the analysis window.
Across the projection horizon, the analytical framework modeled demand by product type, cooling technology, application modality, and end-user procurement authority. CAGRs derived from imaging fleet renewal cycle analysis, superconducting magnet density trajectories, and proton therapy beam current escalation patterns. Forecast inputs incorporated REACH authorization timelines, F-Gas quota allocation schedules, and METI energy efficiency mandate compliance pathways.
The analysis sits within stated boundaries; outcomes outside sustained hospital capital expenditure commitment or accelerated refrigerant phase-down schedules would require recalibration. Forecasts reflect documented assumptions regarding regulatory timeline adherence and thermal load density trajectories. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Floor-Standing Platelet Agitator Market
Medical Equipment
Europe Medical Automation Market
Medical Equipment
Medical Whirlpool Market
Medical Equipment
Global Optometry Equipment Market
Medical Equipment
Global Oxygen Flow Meters Market
Medical Equipment
Benchtop Platelet Agitator Market
Medical Equipment
Medical Vending Machines Market
Medical Equipment
ECG Equipment Market
Medical Equipment
North America Radiotherapy Market
Medical Equipment
Dual Energy X-Ray Absorptiometry (Dexa) Equipment Market
Medical Equipment
Proctologic Table Market
Medical Equipment
Irradiation Apparatus Market
Medical Equipment
Next Generation Centrifuge Market
Medical Equipment
Intensive Care Unit (ICU) Equipment Market
Medical Equipment
Brain Mapping Instruments Market
Medical Equipment
Medical Air Sterilizer Market