
 US Medical Billing Outsourcing Market | 2026-2036
US Medical Billing Outsourcing Market Size, Share, and Industry Trends Forecast 2026-2036
US Medical Billing Outsourcing Market Intelligence
Buyer concentration among hospital networks and large physician groups is pivoting toward consolidated outsourcing contracts that span multiple facilities. Athenahealth leverages cloud-native infrastructure to anchor enterprise-scale engagements with integrated delivery networks. CareCloud competes through specialized revenue cycle modules tailored to ambulatory surgery centers. Access Healthcare sustains cost advantages via captive offshore processing centers combined with domestic account management.
Medical billing outsourcing encompasses the delegation of claims submission, payment posting, denial management, and patient billing functions to third-party specialists, typically operating through HIPAA-compliant electronic data interchange protocols with 837 claim formats and 835 remittance standards. The primary commercial purpose centers on reducing days in accounts receivable while ensuring compliance with evolving payer-specific documentation requirements. Full-Service Billing dominates contract value as health systems seek unified accountability across the revenue cycle, while Cloud-Based Solutions represent the fastest-expanding technology dimension as legacy on-premise installations face replacement pressure. Revenue Cycle Management commands the deepest margin pools due to its outcome-linked pricing structures and long-term contract tenures.
FDA oversight of clinical documentation integrity intersects with CMS reimbursement rules and HIPAA privacy mandates to create a compliance environment where specialized expertise carries premium value. The Office of the National Coordinator for Health IT further shapes demand through interoperability standards that require sophisticated billing-IT integration. Stakeholders must weigh the trade-offs between vendor consolidation for operational simplicity versus multi-vendor strategies that preserve pricing leverage and technological flexibility.
Market Dynamics
Hospital revenue cycle departments face mounting pressure from ICD-10-CM code proliferation and payer-specific documentation requirements that outpace internal training capacity. This structural gap between clinical complexity and billing expertise is accelerating the shift toward specialized external partners who maintain dedicated compliance teams.
Growth Catalysts
- Value-Based Reimbursement:CMS frameworks tie payment to quality metrics, requiring sophisticated documentation that physician practices struggle to manage internally. Outsourcing partners invest in specialized coding talent to capture these performance-linked payments.
- Cloud-Native Infrastructure:Multi-specialty physician groups across Texas and Florida are migrating billing operations to platforms enabling real-time claim scrubbing and denial prediction. This technology shift reduces days in accounts receivable by enabling continuous workflow optimization.
- HIPAA Compliance Burden:The Office for Civil Rights enforcement actions create liability exposure that smaller practices cannot absorb. External specialists spread compliance infrastructure costs across thousands of clients.
Market Restraints
- Offshore Labor Cost Volatility:Captive processing centers in India face wage inflation and rupee fluctuation that compress margin structures for US-focused vendors.
- Payer Concentration Risk:Dominance of Medicare Advantage plans administered by UnitedHealthcare, Humana, and CVS Aetna creates dependency on a narrow set of reimbursement rulebooks.
- Interoperability Friction:ONC certification requirements for electronic health record integration impose technical barriers that delay contract implementations.
Strategic Opportunities
- Rural Hospital Networks:Critical access hospitals across Mississippi, Alabama, and Georgia operate with minimal revenue cycle staff. Outsourcing penetration remains below fifteen percent in these facilities.
- Prior Authorization Automation:Convergence of robotic process automation with natural language processing enables real-time eligibility verification. Vendors capturing this workflow gain sticky relationships with ambulatory surgery centers.
- Surprise Billing Legislation:The No Surprises Act creates patient billing complexity that specialists can monetize through transparent pricing modules.
Industry Challenges
- Certified Medical Coder Scarcity:AAPC-credentialed professionals command premium compensation in tight labor markets across the Southeast.
- Legacy EHR Integration:Epic and Cerner deployments require custom API development that extends implementation timelines and strains vendor engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Medical Billing Outsourcing Market |
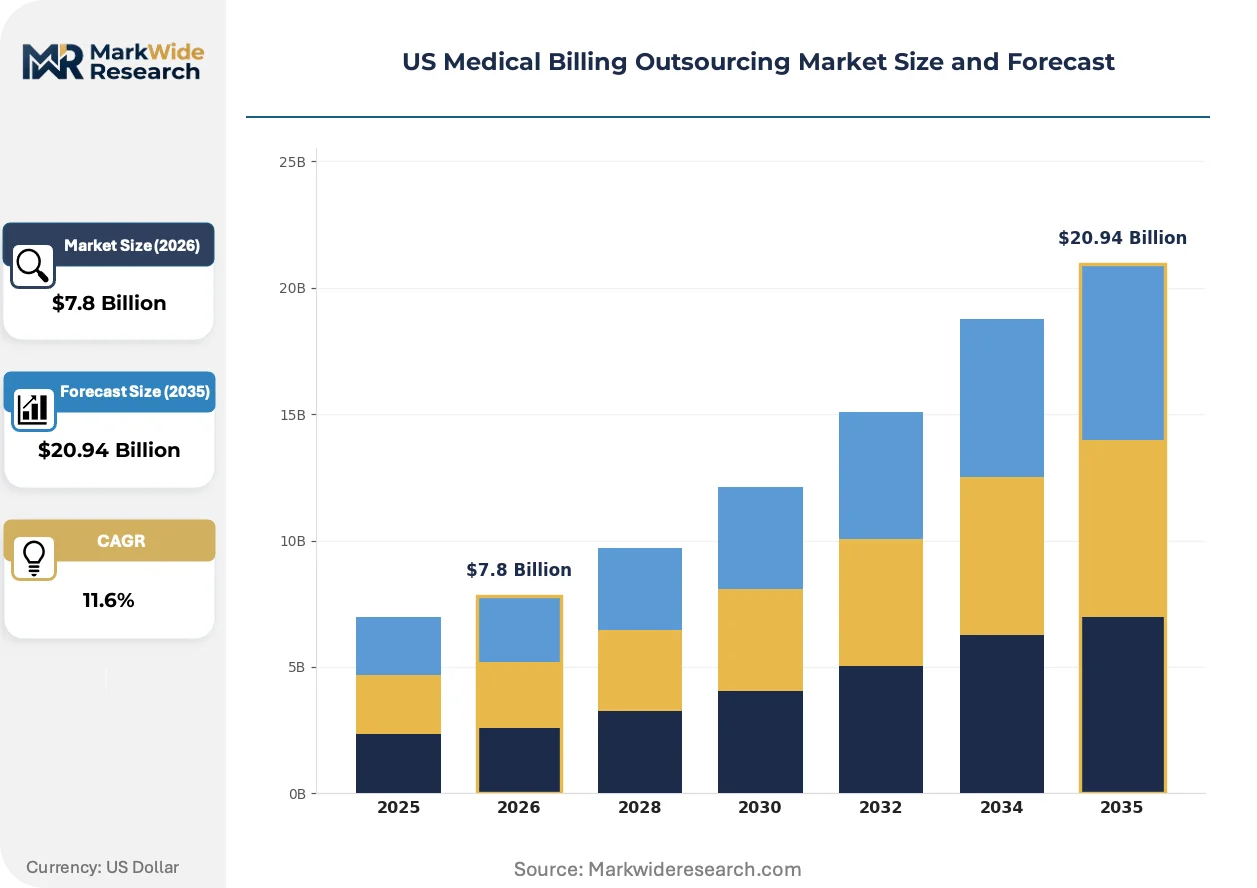
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $20.94 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Full-Service Billing, Software Services, Consulting Services, Revenue Cycle Management End User: Hospitals, Clinics, Private Practices, Specialty Centers Billing Model: Fee-for-Service, Value-Based Billing, Capitation, Hybrid Model Technology: Cloud-Based Solutions, On-Premise Software, Automated Systems, Hybrid Models |
| Companies Covered | CareCloud, Practolytics, Transcure, Promantra, ChartLogic, Athenahealth, Access Healthcare, Absolute Solutions, AdvancedMD, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Medical Billing Outsourcing Market Strategic Shifts & Innovations
Artificial intelligence is reshaping how billing operations prioritize denial prevention over post-denial recovery. This shift demands new vendor capabilities in predictive analytics and real-time clinical documentation feedback.
Machine learning platforms trained on historical denial patterns are unifying previously siloed functions of coding, charge capture, and claims scrubbing. Regional hospital networks in the Carolinas and Tennessee are deploying these systems at enterprise scale. The technology is unifying accountability across the revenue cycle by collapsing handoff points where errors historically multiplied.
CMS interoperability mandates under the 21st Century Cures Act are forcing billing vendors to standardize API connections with diverse EHR platforms. This regulatory pressure is compressing implementation timelines and raising compliance costs. Ambulatory surgery centers in Texas and Arizona face the steepest adaptation curves due to fragmented practice management system landscapes.
Consolidated outsourcing contracts are displacing single-facility arrangements as integrated delivery networks seek unified reporting and accountability. Multi-hospital systems in Florida and Georgia now demand single-vendor coverage across twenty-plus sites. This concentration trend is visible most acutely in the southeastern United States where private equity-backed physician roll-ups create large, homogeneous buyer pools.
US Medical Billing Outsourcing Market Segmentation
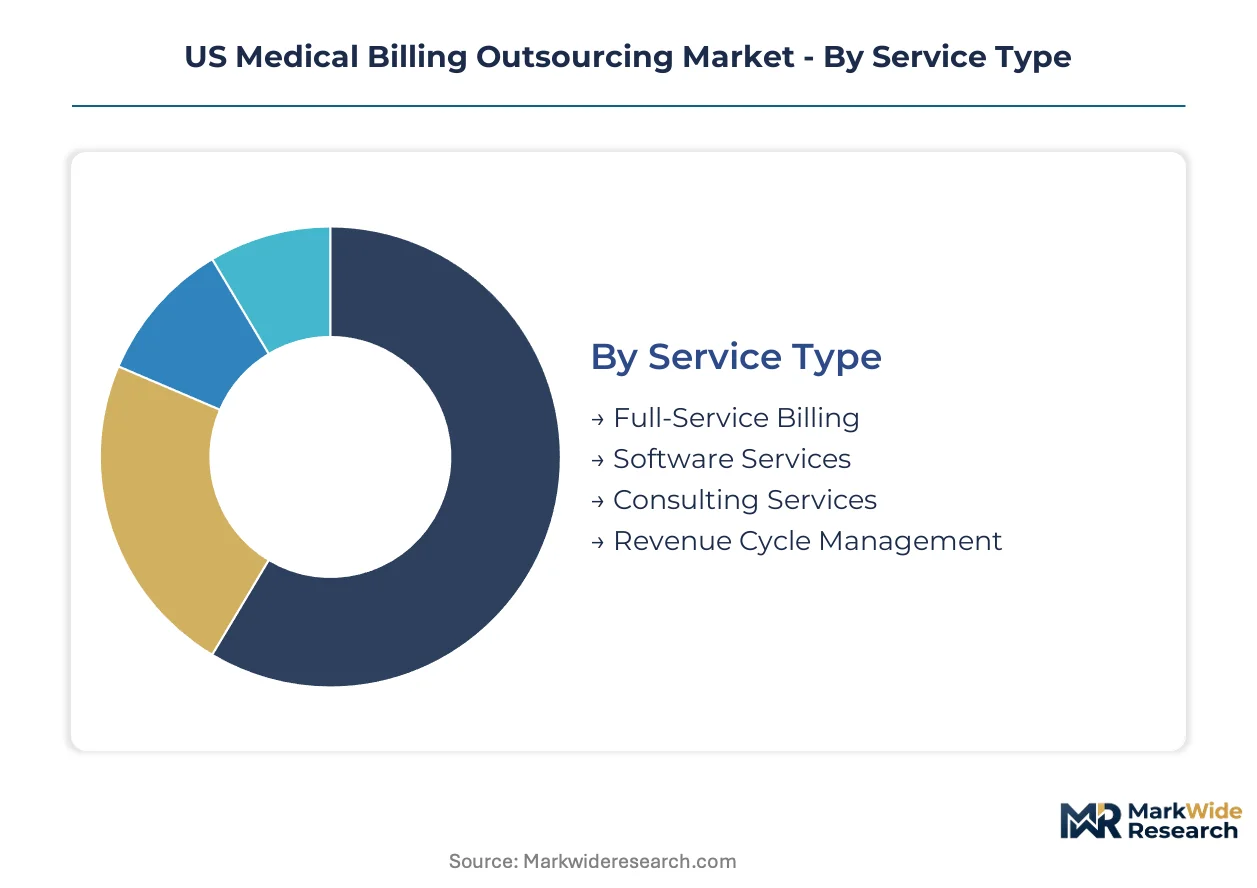
Segmentation in US medical billing outsourcing reveals how provider scale, reimbursement complexity, and technology infrastructure shape vendor selection. Buyers prioritize different service bundles based on their internal revenue cycle maturity and payer mix concentration.
Service Type:
Hospital systems and physician groups differentiate themselves by how much of the revenue cycle they retain versus delegate.
- Full-Service Billing:Comprehensive delegation spanning claims submission, payment posting, denial management, and patient billing through HIPAA-compliant electronic data interchange. Demand concentrates among multi-hospital integrated delivery networks in Florida and Georgia seeking unified accountability across twenty-plus sites.
- Revenue Cycle Management:Outcome-linked pricing structures tied to net patient revenue or collections improvement. Regional hospital networks in the Carolinas favor these arrangements for long-term contract tenures and shared risk alignment.
- Software Services:Cloud-native platforms enabling real-time claim scrubbing and denial prediction for practices with internal coding staff.
- Consulting Services:Specialized advisory on ICD-10-CM documentation and CMS compliance for organizations undergoing reimbursement model transitions.
Full-Service Billing leads volumes today; Revenue Cycle Management is gaining share fastest.
End User:
Facility scale determines outsourcing penetration and contract structure complexity.
- Hospitals:Enterprise-scale engagements requiring EHR integration with Epic or Cerner deployments and dedicated account management. Academic medical centers in Texas and Tennessee drive demand for specialized coding talent to capture value-based payments.
- Private Practices:Solo and small-group physicians outsourcing entire revenue cycles due to HIPAA compliance burden and certified coder scarcity. Multi-specialty groups across the Southwest favor cloud-based solutions reducing days in accounts receivable.
- Clinics:Federally qualified health centers and urgent care chains seeking modular billing support for high patient throughput.
- Specialty Centers:Ambulatory surgery centers in Arizona and Texas requiring prior authorization automation and transparent pricing modules under the No Surprises Act.
Hospitals dominate contract value; Specialty Centers show the steepest expansion trajectory.
Billing Model:
Reimbursement methodology alignment shapes vendor capability requirements and pricing structures.
- Fee-for-Service:Traditional volume-based claims processing with per-encounter or percentage-of-collections pricing. Dominates in private practices and specialty centers with straightforward payer contracts.
- Value-Based Billing:Documentation and reporting tied to CMS quality metrics and performance-linked payments. Hospital systems transitioning under Medicare Advantage contracts require specialized coding for HCC capture.
- Capitation:Fixed per-member-per-month arrangements demanding sophisticated utilization management and risk adjustment expertise.
- Hybrid Model:Blended structures combining fee-for-service infrastructure with value-based reporting capabilities for organizations managing multiple contract types simultaneously.
Fee-for-Service retains the largest installed base; Value-Based Billing is climbing the fastest.
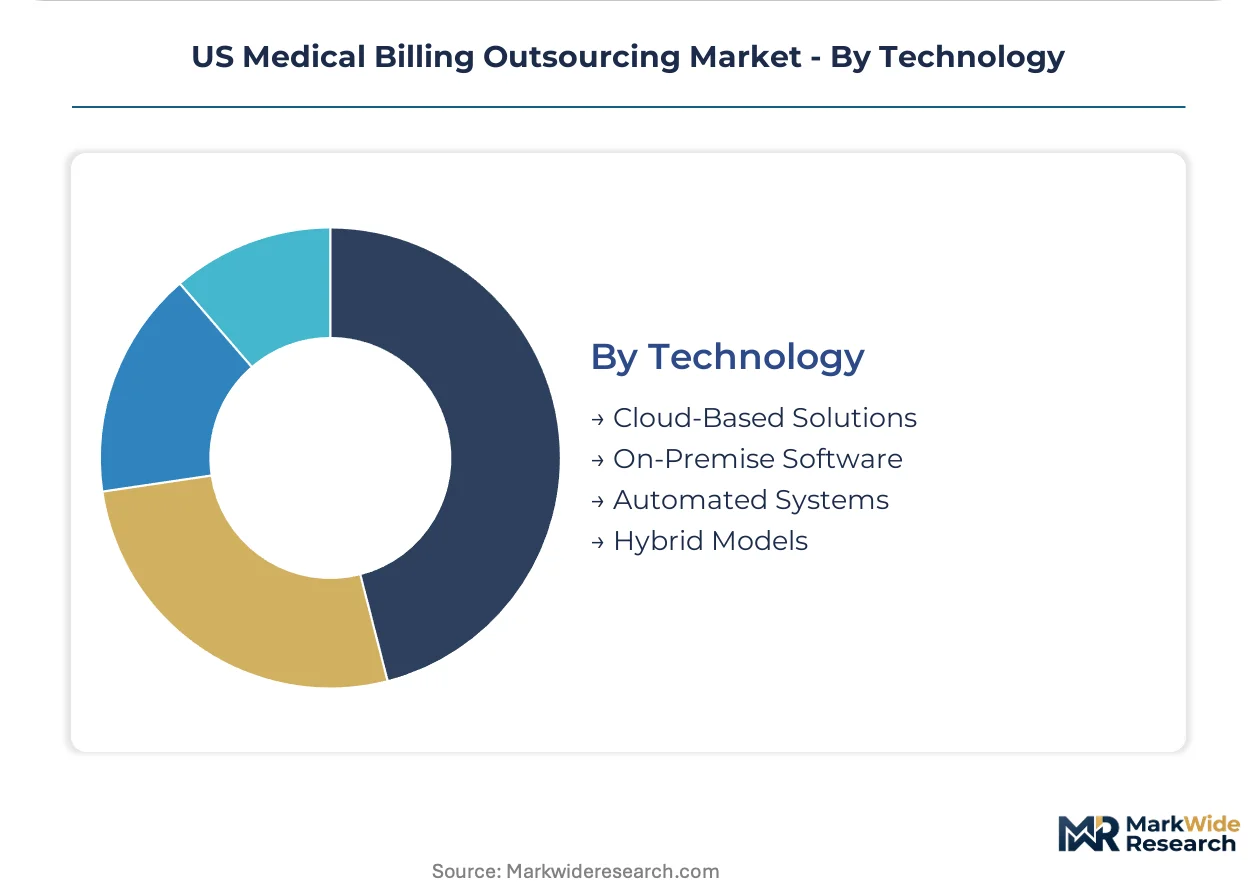
Technology:
Infrastructure decisions reflect legacy system constraints and interoperability mandate pressures.
- Cloud-Based Solutions:Real-time workflow optimization and continuous software updates without on-premise maintenance. Multi-specialty physician groups in Florida and Texas are migrating rapidly to reduce IT overhead and enable denial prediction.
- Automated Systems:Machine learning platforms unifying coding, charge capture, and claims scrubbing through predictive analytics. Regional networks in the Carolinas deploy these at enterprise scale to collapse error-prone handoff points.
- On-Premise Software:Legacy installations retained by health systems with stringent data sovereignty requirements or customized EHR integrations.
- Hybrid Models:Cloud-hosted core platforms with localized redundancy for critical functions, bridging compliance and flexibility needs.
On-Premise Software still anchors the largest installed base; Cloud-Based Solutions are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified medical coders and revenue cycle specialists concentrate in the southeastern and southwestern United States, where hospital network consolidation and private equity-backed physician roll-ups create dense demand clusters for external billing expertise.
Southeast
Florida and Georgia anchor enterprise-scale outsourcing contracts as integrated delivery networks consolidate billing across twenty-plus facilities. HIPAA enforcement actions by the Office for Civil Rights drive smaller practices toward external compliance specialists. Atlanta and Miami metropolitan areas host the densest concentration of multi-specialty physician groups migrating to cloud-native platforms.
Southwest
Texas and Arizona exhibit the steepest expansion trajectory for ambulatory surgery centers requiring prior authorization automation. CMS interoperability mandates under the 21st Century Cures Act compress implementation timelines for fragmented practice management systems. Dallas-Fort Worth and Phoenix medical corridors concentrate specialty centers adapting to No Surprises Act patient billing requirements.
Mid-Atlantic
Virginia and North Carolina hospital networks deploy machine learning platforms at enterprise scale to unify coding and claims scrubbing functions. Value-based reimbursement transitions under Medicare Advantage contracts demand specialized HCC capture talent. Research Triangle and Richmond regional systems lead in denial prediction technology adoption.
West Coast
California academic medical centers drive demand for sophisticated documentation supporting quality-linked payments. Epic and Cerner EHR integrations require custom API development that strains vendor engineering resources. Los Angeles and San Francisco Bay Area health systems prioritize real-time clinical documentation feedback capabilities.
Midwest
Illinois and Ohio critical access hospitals operate with minimal revenue cycle staff, leaving outsourcing penetration below fifteen percent. Rural hospital networks across Mississippi and Alabama present untapped vendor expansion opportunities. Chicago metropolitan health systems balance legacy on-premise installations against cloud migration pressures.
US Medical Billing Outsourcing Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across a fragmented vendor landscape where no single participant commands decisive share. The market structures around three tiers: cloud-native platform providers anchoring enterprise engagements, modular specialists capturing ambulatory surgery centers, and offshore-integrated operators sustaining cost advantages. Strategic consolidation through multi-facility contract aggregation and captive offshore capacity expansion represent the dominant competitive moves reshaping vendor positioning.
Within the cloud-native tier, Athenahealth exemplifies platform-scale delivery to integrated delivery networks, while CareCloud occupies a position among modular specialists tailoring revenue cycle components to specific facility types. Access Healthcare represents the offshore-integrated archetype, combining captive processing capabilities with domestic account management structures.
| Leading Market Players |
|---|
| CareCloud |
| Practolytics |
| Transcure |
| Promantra |
| ChartLogic |
| Athenahealth |
| Access Healthcare |
| Absolute Solutions |
| AdvancedMD |
| Others |
Cost & Logistics Intelligence
Hospital procurement committees consolidating vendor rosters into single-source enterprise contracts are compressing pricing flexibility for billing specialists who must absorb compliance infrastructure costs across narrower client bases. This buyer-side consolidation forces supply-side restructuring toward captive offshore capacity and cloud-native platform standardization.
Pricing Analysis
Capacity additions in India and the Philippines are reshaping price floors for transaction processing tiers while domestic account management commands premium positioning. Three-tier pricing structure across enterprise, mid-market, and small-practice levels reflects certification density and EHR integration complexity. Pricing pressure stems from rupee volatility and wage inflation in offshore processing centers. Small private practices exhibit highest price sensitivity; integrated delivery networks prioritize outcome-linked contracts over per-claim rates.
Supply Chain Analysis
Domestic-content requirements for HIPAA data residency are reshaping sourcing toward US-based cloud infrastructure with offshore processing redundancy. Supply concentrates in India for back-office coding, the United States for client-facing account management, and Ireland for European data routing compliance. The supply chain draws from certified medical coder labor pools, EHR API integration modules, and robotic process automation platforms. Single-source vulnerability runs through concentrated Epic and Cerner integration partnerships. Distribution runs through direct enterprise sales teams supplemented by GPO contracts for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
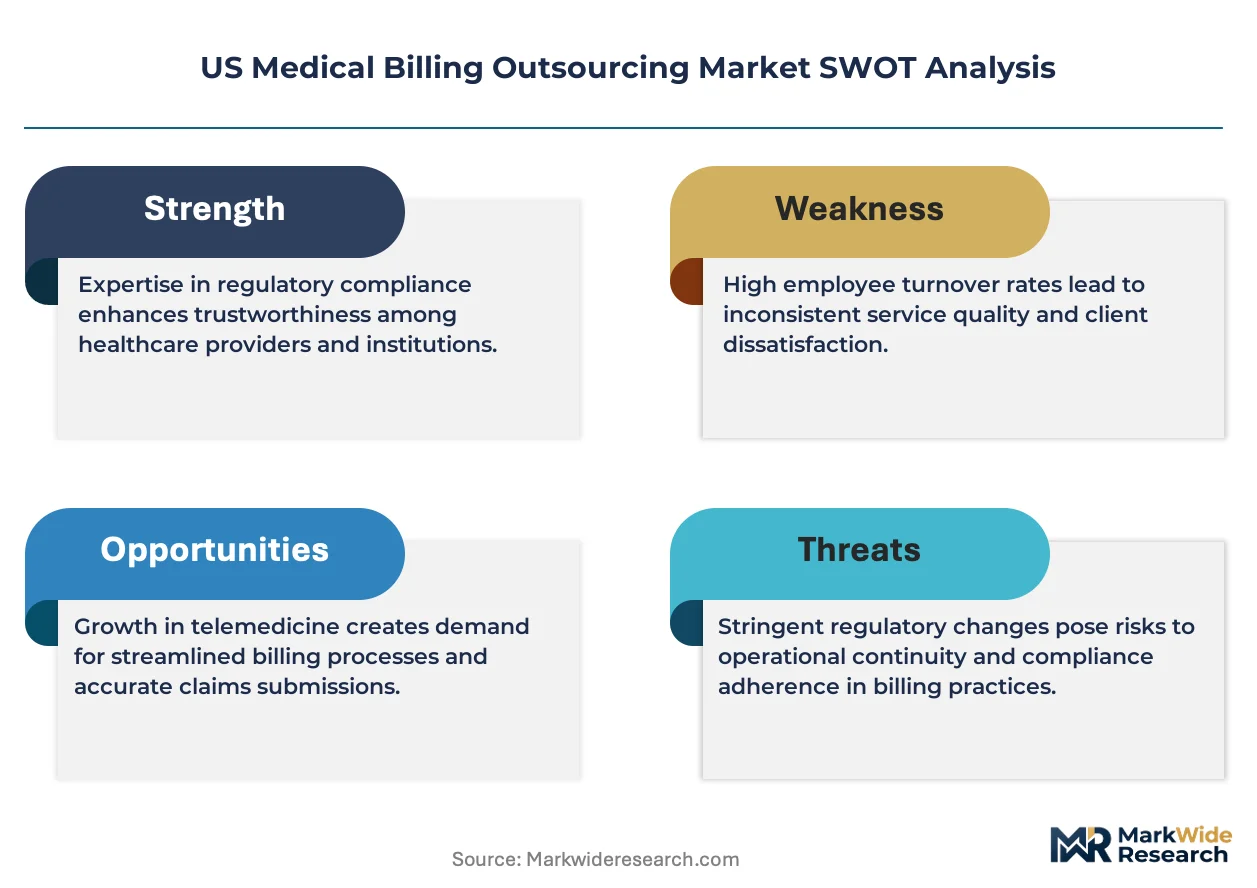
The US Medical Billing Outsourcing Market functions as a regulatory compounder where CMS interoperability mandates and No Surprises Act compliance obligations continuously expand addressable demand for specialized expertise.
For Market Incumbents: To counter cloud-native platform entrants, established vendors should deepen captive offshore processing capacity in secondary Indian cities and secure exclusive EHR integration certifications with Epic and Cerner. Prior authorization automation capabilities represent the critical defensive lever for ambulatory surgery center retention. For New Entrants and Emerging Players: Direct-to-specialist-center digital channels enable rapid penetration of Arizona and Texas ambulatory surgery centers where legacy vendor relationships remain shallow. Rural critical access hospitals across Mississippi and Alabama present the most penetrable geography with sub-fifteen-percent outsourcing saturation. A modular pricing strategy targeting transparent patient billing under No Surprises Act requirements opens initial contract conversations. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale revenue cycle management specialists possessing established Medicare Advantage value-based billing capabilities. Long-term viability hinges on regulatory tailwinds persisting through CMS framework evolution. Cloud-native platform architecture with real-time denial prediction serves as the critical inflection signal for acquisition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Prior Authorization Automation | Captures sticky ASC relationships through real-time eligibility verification workflows. |
| Captive Offshore Expansion | Absorbs wage inflation pressure while maintaining HIPAA-compliant processing redundancy. |
| EHR Platform Integration | Secures exclusive API development partnerships with Epic and Cerner deployments. |
| Value-Based Billing Specialization | Positions for HCC capture revenue under Medicare Advantage quality-linked contracts. |
| Rural Hospital Network Penetration | Addresses sub-fifteen-percent outsourcing saturation across Mississippi and Alabama. |
Research Approach
Direct dialogue with revenue cycle executives at regional hospital networks, ambulatory surgery center administrators, certified medical coders, GPO contracts managers, and HIPAA compliance officers anchored qualitative findings. Secondary validation drew from CMS Medicare cost reports, hospital procurement databases, ONC interoperability certification records, and AAPC credentialing statistics. Bottom-up facility-level demand assessment triangulated against top-down market sizing.
Segmented outputs across service type, end user, billing model, and technology deployment reflect granular modeling of outsourcing penetration rates and contract value distributions. Revenue cycle management pricing structures and full-service billing contract tenures informed CAGR derivation through the projection horizon. Cloud migration velocity and certified coder scarcity served as primary industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for legacy on-premise EHR retention would alter the outlook. Forecasts reflect assumptions regarding CMS regulatory enforcement continuity and payer consolidation trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Healthcare Third-Party Logistics Market
Healthcare Services
Europe Medical Affairs Outsourcing Market
Healthcare Services
US Registered Nurses Market
Healthcare Services
Nutraceutical Contract Manufacturing Services Market
Healthcare Services
Care Services Market
Healthcare Services
Acute Care Market
Healthcare Services
Inhaled and Intranasal Products Contract Service Providers Market
Healthcare Services
Sterilization Services Market
Healthcare Services
Escort Bed Sharing Market
Healthcare Services
Global Sperm Bank Market
Healthcare Services
Chronic Disease Management Service Market
Healthcare Services
Global Healthcare Services Market
Healthcare Services
Global Operating Room Management Market
Healthcare Services
Healthcare Patent Filing Outsourcing Market
Healthcare Services
United States Senior Living Market
Healthcare Services
Prescription Delivery Services Market