
 Care Services Market | 2026-2036
Care Services Market Size, Share, and Industry Trends Forecast 2026-2036
Care Services Market Analysis
North America is reshaping competitive dynamics in care services through expanded home-based capacity and regulatory-driven facility modernization. Brookdale Senior Living leverages its geographic scale across senior housing markets to sustain occupancy advantages in institutional settings. Amedisys anchors its position through specialized clinical protocols for chronic disease management in home health. Kindred Healthcare differentiates via post-acute integration strategies that bridge hospital discharge and long-term recovery settings.
Care services encompass medical and non-medical assistance delivered across institutional, community, and residential settings, typically involving licensed nursing, personal care assistance, therapy, and palliative support structured around individualized care plans with documented clinical outcomes. The primary purpose centers on maintaining patient functional status, delaying institutionalization, and reducing acute care utilization through coordinated longitudinal support. Home Health Care leads service type revenue generation due to Medicare fee-for-service volume and shifting site-of-care preferences, while Telemedicine within delivery models shows the fastest structural ascent as remote monitoring and virtual consultation capabilities mature. Palliative Care occupies concentrated margin pools where specialized interdisciplinary teams command premium reimbursement for complex symptom management.
FDA oversight shapes clinical service standards for medication management and device integration in home settings, while CMS reimbursement rules directly determine provider viability through Medicare Advantage rate-setting and value-based purchasing thresholds. State Medicaid agencies regulate access and payment for long-term services and supports, creating fragmented eligibility landscapes that operators must navigate market-by-market. Stakeholders should monitor how CMS innovation center demonstrations for home-based acute care alter traditional facility admission patterns and capital allocation priorities.
Market Dynamics
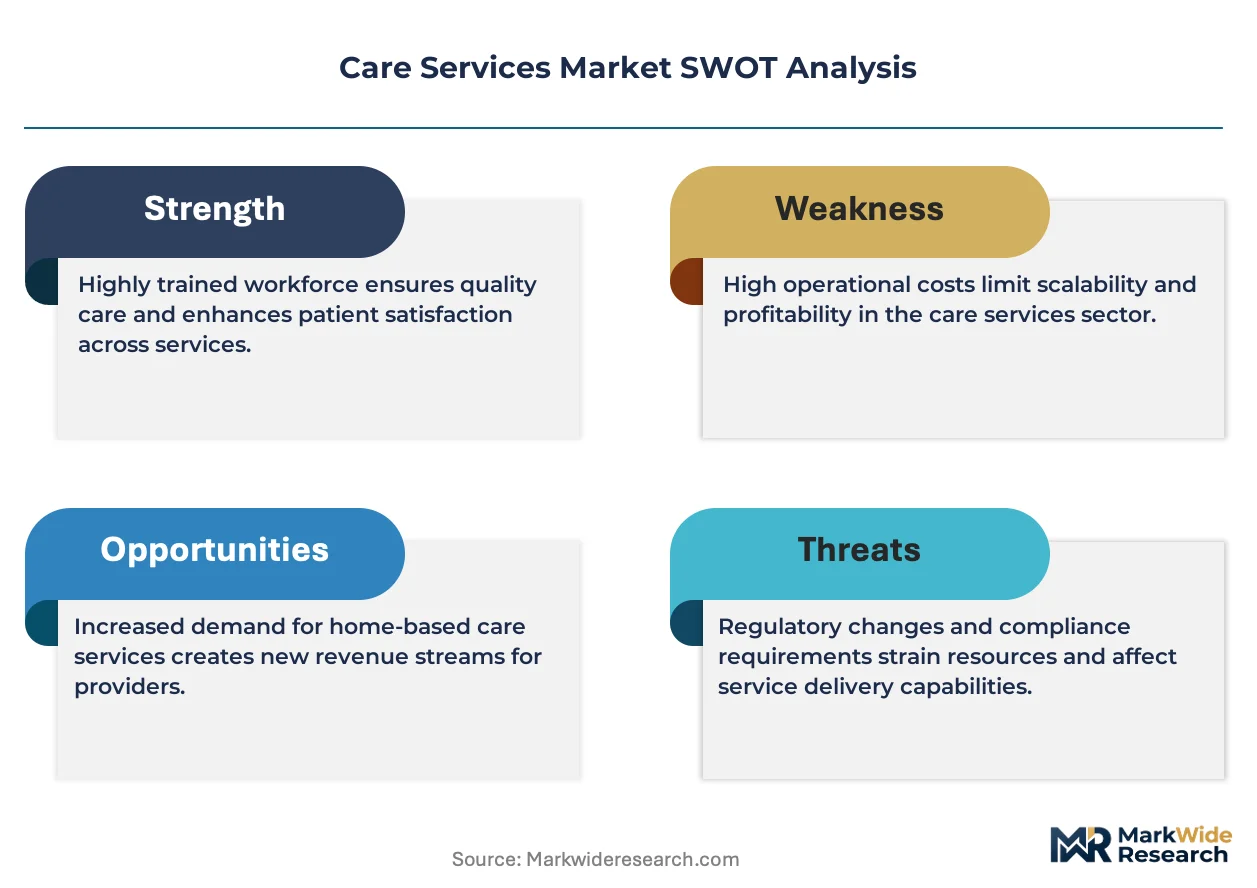
Medicare's site-neutral payment reforms are compressing reimbursement differentials between institutional and home-based settings, forcing capital reallocation across delivery networks.
Growth Catalysts
- CMS Innovation Center Demonstrations:Home-based acute care pilots expand Medicare coverage for hospital-at-home models, diverting admissions from skilled nursing facilities.
- Aging Demographics:The United States population aged 85-plus concentrates demand for chronic disease management and functional support services.
- Remote Patient Monitoring:Wearable biosensors and cellular-enabled devices enable real-time clinical surveillance outside facility walls.
Market Restraints
- Labor Cost Escalation:Registered nurse and certified nursing assistant wages absorb disproportionate share of operating budgets across home health and institutional segments.
- State Medicaid Fragmentation:Eligibility criteria and reimbursement rates vary across 50 state programs, complicating multi-market expansion strategies.
- Family Informal Care Substitution:Unpaid caregiver support reduces paid service penetration in lower-acuity functional assistance categories.
Strategic Opportunities
- Medicare Advantage Penetration:MA plan enrollment growth creates capitated contracting opportunities with integrated care organizations seeking downstream cost control.
- Palliative Care Expansion:Concurrent care models allow curative and comfort-focused interventions, opening reimbursement for earlier specialist engagement.
- AI-Enabled Triage:Natural language processing and predictive algorithms converge with electronic health record systems to stratify patient risk and optimize visit scheduling.
Industry Challenges
- Licensed Clinician Recruitment:Home health agencies face persistent vacancies for physical therapists and occupational therapists in rural service territories.
- Interoperability Standards:Data exchange between proprietary electronic health record platforms and state Medicaid management information systems requires costly interface development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Care Services Market |
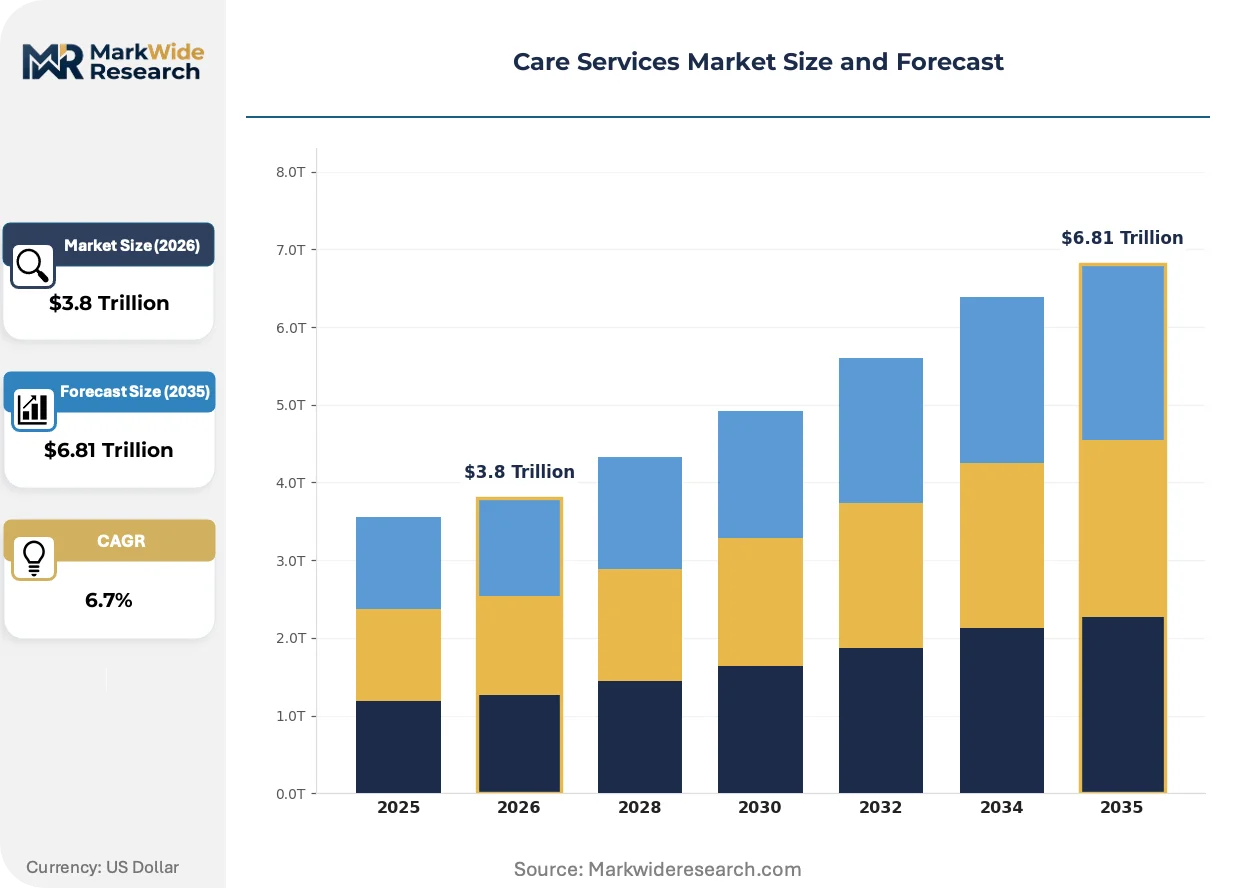
| Market Size in 2026 | $3.8 Trillion |
| Market Size in 2035 | $6.81 Trillion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Home Health Care, Palliative Care, Hospice Services, Rehabilitation Services Delivery Model: In-Home Services, Community-Based Services, Telemedicine, Facility-Based Services Patient Type: Elderly, Disabled Individuals, Chronically Ill Patients, Post-Surgery Patients Funding Source: Private Insurance, Medicare, Medicaid, Out-of-Pocket |
| Companies Covered | Brookdale Senior Living, Amedisys, Kindred Healthcare, Home Instead, Interim HealthCare, Visiting Angels, Right at Home, BAYADA Home Health Care, LHC Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Care Services Market Emerging Trajectories
Digital infrastructure is reconfiguring where clinical encounters occur and how outcomes are measured across institutional and community settings.
Telehealth platforms are virtualizing routine follow-up and medication reconciliation encounters. Medicare Advantage plans and Medicaid managed care organizations deploy these tools to extend specialist reach into underserved counties. The technology is virtualizing geographic access barriers that previously required facility-based appointments.
CMS site-neutral payment rules eliminate reimbursement premiums for hospital-based outpatient departments. Skilled nursing facilities and home health agencies absorb redirected surgical recovery volumes as health systems consolidate lower-acuity capacity. Post-acute providers in the United States restructure staffing ratios to capture these shifting referral patterns.
Family caregivers increasingly coordinate paid service procurement through digital marketplaces and employer-sponsored support platforms. Insurance benefit administrators and aging-services technology vendors displace traditional agency-based intake processes. This pattern concentrates in metropolitan United States markets where workforce participation rates among adult children remain elevated.
Care Services Market Segmentation
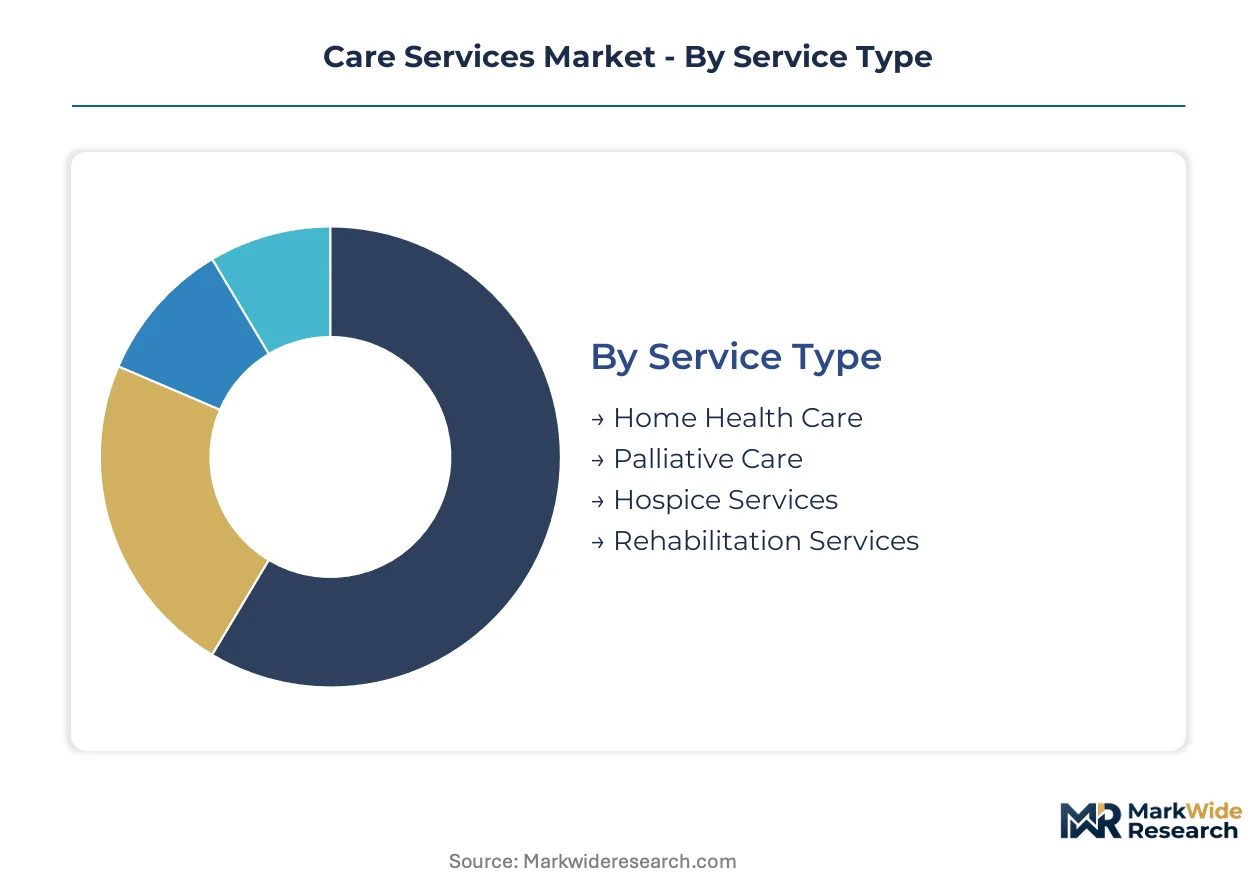
Care services segmentation reveals how reimbursement flows, clinical acuity, and site-of-care preferences fragment demand across distinct operational models. Each category maps to different capital requirements, regulatory exposure, and margin profiles that shape provider strategy.
Service Type:
Mature clinical categories dominate revenue capture while emerging specialties reshape growth trajectories across the forecast window.
- Home Health Care:Licensed nursing, therapy, and aide services delivered in residential settings under Medicare fee-for-service and Medicare Advantage capitation. Demand concentrates among elderly patients with chronic conditions in the United States where CMS site-neutral reforms accelerate hospital-at-home diversion.
- Palliative Care:Interdisciplinary symptom management and care coordination for serious illness, distinct from hospice through concurrent curative treatment. Post-surgery patients in academic medical centers drive adoption as value-based contracts reward reduced emergency department utilization.
- Hospice Services:End-of-life comfort care with 24/7 nursing availability and bereavement support, typically triggered by six-month prognosis certification. Medicare hospice benefit structures reimbursement around per-diem rates for routine and continuous care levels.
- Rehabilitation Services:Physical, occupational, and speech therapy targeting functional restoration after acute events. Skilled nursing facilities and outpatient clinics compete for stroke and joint replacement recovery volumes.
Home Health Care retains volume leadership; Palliative Care holds the steepest expansion curve.
Delivery Model:
Cost tier stratification separates capital-intensive facility operations from asset-light virtual and community-based alternatives.
- In-Home Services:Direct clinical and personal care provision at patient residences, requiring mobile workforce logistics and remote supervision infrastructure. Chronically ill patients in metropolitan United States markets absorb capacity as hospital readmission penalties tighten.
- Community-Based Services:Adult day programs, senior centers, and meal delivery coordinating non-medical support outside institutional walls. Medicaid HCBS waivers fund disabled individuals seeking alternatives to nursing facility placement.
- Telemedicine:Virtual consultation, remote monitoring, and digital care coordination eliminating geographic access barriers. Rural elderly populations gain specialist reach as Medicare Advantage plans expand asynchronous coverage.
- Facility-Based Services:Nursing homes, assisted living, and inpatient rehabilitation centers delivering 24-hour supervised care. Capital intensity and state licensing requirements create high barriers to greenfield development.
Facility-Based Services retain volume leadership; Telemedicine is climbing the fastest.
Patient Type:
Application urgency varies from elective post-acute recovery to continuous chronic disease management and terminal care.
- Elderly:Adults aged 65-plus requiring functional assistance, medication management, and fall prevention across the care continuum. Medicare eligibility thresholds and supplemental coverage patterns shape service mix preferences.
- Disabled Individuals:Working-age adults with physical, developmental, or cognitive impairments needing long-term services and supports. State Medicaid programs administer waiver programs with varying eligibility and provider rates.
- Chronically Ill Patients:Persons with diabetes, heart failure, COPD, or other conditions demanding ongoing clinical surveillance and self-management education. Medicare Advantage chronic care management billing codes expand reimbursement for proactive outreach.
- Post-Surgery Patients:Individuals recovering from orthopedic, cardiac, or abdominal procedures requiring short-term rehabilitation and wound care. Bundled payment models align skilled nursing facility and home health incentives around episode cost targets.
Elderly retains volume leadership; Chronically Ill Patients gain share fastest.
Funding Source:
Margin profiles diverge sharply between administratively set government rates and commercially negotiated premiums.
- Private Insurance:Employer-sponsored and individual market coverage for home health, skilled nursing, and hospice with prior authorization requirements. United States metropolitan markets with high median incomes sustain out-of-network billing for premium facilities.
- Medicare:Federal health insurance for aged and disabled populations, dominating reimbursement for home health and hospice through fee-for-service and Advantage capitation. CMS annual rulemaking updates payment classifications and quality reporting mandates.
- Medicaid:State-federal partnership covering long-term services and supports for low-income elderly and disabled individuals. Fifty separate state programs create eligibility and rate fragmentation complicating multi-state operator expansion.
- Out-of-Pocket:Direct consumer payment for private-duty nursing, non-medical home care, and assisted living room-and-board components. Wealth concentration in coastal United States markets sustains premium pricing for concierge care models.
Medicare retains volume leadership; Medicare Advantage within Medicare shows the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Care services consumption patterns diverge sharply across geographies, with the United States driving institutional-to-home transitions while European systems emphasize community-based integration and Asian markets grapple with informal family care legacies.
United States
Medicare Advantage enrollment growth and CMS site-neutral payment reforms accelerate hospital-at-home diversion models. The federal agency's Innovation Center pilots expand coverage for acute-level care in residential settings. Texas and Florida metropolitan corridors absorb disproportionate capacity expansion as retiree migration concentrates demand in Sun Belt markets.
Germany
Long-term care insurance reforms since 2017 have shifted reimbursement toward home-based and community-integrated services. The country's national social care regulator oversees quality standards across statutory and private insurance tiers. Bavaria and North Rhine-Westphalia host the densest networks of ambulatory care services, with Munich-based provider associations driving digital care documentation adoption.
Japan
Super-aged demographic profiles compress family-based informal care capacity, expanding paid service penetration. METI coordinates robotics integration standards for eldercare facilities under national productivity initiatives. The Kanto region surrounding Tokyo exhibits highest per-capita utilization of certified care manager services, with prefectural governments managing supply-side capacity licensing.
United Kingdom
Integrated care systems reorganize commissioning around place-based population health budgets, blurring historical NHS-social care boundaries. The Care Quality Commission enforces single-inspection frameworks across registered providers. Southeast England and Greater Manchester pilot capitated payment models that merge acute, primary, and social care funding streams.
Australia
Home Care Packages and Residential Aged Care reforms since 2021 redirect consumer-directed funding toward independent living support. The national aged care quality and safety commissioner mandates new transparency requirements for provider governance. New South Wales and Victoria concentrate specialist dementia care capacity, with Sydney and Melbourne health districts testing hospital-in-the-home protocols for complex chronic conditions.
Care Services Market Vendor Landscape
Capability concentration sits with specialized clinical operators; scale advantage sits with multi-site facility networks. The market structures around three tiers: national institutional chains with real estate portfolios, regional home health specialists with therapy workforce depth, and technology-enabled platforms aggregating independent caregivers. Dominant competitive moves include Medicare Advantage contracting consolidation and vertical integration into physician practice management.
Among institutional-scale operators, Brookdale Senior Living and Amedisys occupy positions representing geographic diversification and clinical specialization archetypes respectively. Kindred Healthcare exemplifies the post-acute integration model bridging hospital discharge and long-term recovery settings.
| Leading Market Players |
|---|
| Brookdale Senior Living |
| Amedisys |
| Kindred Healthcare |
| Home Instead |
| Interim HealthCare |
| Visiting Angels |
| Right at Home |
| BAYADA Home Health Care |
| LHC Group |
| Others |
Supply Flow & Price Mechanics
CMS site-neutral payment reforms compressing reimbursement differentials between institutional and home-based settings determine both margin tier spreads and capital reallocation patterns across provider networks. Labor cost escalation for registered nurses and certified nursing assistants absorbs disproportionate operating budget share, forcing tiered service packaging that segments markets by acuity level and payer mix.
Pricing Analysis
Metropolitan United States markets command 15-25% premium over rural territories for identical Medicare-reimbursed home health episodes due to workforce scarcity and travel logistics. Pricing stratifies across premium concierge models, standard Medicare Advantage capitation, and economy Medicaid waiver tiers based on clinical intensity and after-hours availability. Cost compression in the Medicaid tier intensifies because state rate-setting lags wage inflation, while Medicare Advantage penetration reduces price sensitivity among integrated plan sponsors seeking downstream cost control. Private-pay assisted living operators in coastal markets exhibit lowest price sensitivity; Medicaid-dependent home health agencies face greatest margin pressure.
Supply Chain Analysis
Extended payment terms from Medicare Advantage plans and supply-chain finance facilities strain working capital for regional home health operators competing with national chains. Clinical workforce supply concentrates in the Philippines, India, and Eastern Europe for imported nursing talent, while durable medical equipment sourcing rests on Chinese manufacturing for monitoring devices and Mexican assembly for mobility aids. Single-source vulnerability in remote patient monitoring platforms creates concentration risk as cellular-enabled biosensor vendors consolidate. Distribution runs through centralized GPO contracts for institutional operators and direct-to-patient logistics for home-based services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Care services function as a service-attach opportunity where chronic care management subscriptions and remote monitoring recurring revenue expand faster than episodic clinical encounters. The shift from fee-for-service to value-based contracting elevates ongoing patient relationship economics over discrete visit reimbursement.
For Market Incumbents: Build geographic density moats through clustered home health agency acquisitions in Medicare Advantage penetration corridors. Consolidate therapy workforce in Sun Belt metropolitan markets to capture hospital-at-home diversion volumes. Defensive positioning requires backward integration into physician practice management to secure referral control against emerging telehealth-enabled entrants. For New Entrants and Emerging Players: Pursue rural telemedicine deployment where specialist access gaps and Medicare Advantage expansion create addressable white space. Target chronically ill patient segments in non-expansion Medicaid states with direct-to-employer contracting models. Go-to-market execution hinges on employer-sponsored care navigation platforms displacing traditional agency intake. For Investors and Strategic Acquirers: CMS Innovation Center hospital-at-home demonstration expansion reshapes the acquisition landscape by validating capital-light acute care models outside facility walls. Five-to-ten year viability centers on operators with proven Medicare Advantage contracting infrastructure and remote monitoring integration. Target acquisition archetype: regional home health specialists with therapy workforce depth and established MA plan relationships. Watch Medicare Advantage star rating methodology revisions as inflection signal for reimbursement rate volatility.| Strategic Initiative | Industry Significance |
|---|---|
| Medicare Advantage Contracting Consolidation | Capitated rate structures with UnitedHealthcare and Humana lock in predictable revenue streams. |
| Remote Monitoring Platform Integration | Cellular-enabled biosensors from BioIntelliSense and Current Health extend clinical surveillance beyond facility walls. |
| Hospital-at-Home Capability Buildout | Acute-level care in residential settings diverts admissions from skilled nursing facilities under CMS waiver authority. |
| Therapy Workforce Acquisition | Physical and occupational therapist recruitment in Texas and Florida corridors captures post-surgery recovery volumes. |
| Palliative Care Service Line Expansion | Concurrent curative and comfort-focused interventions open earlier specialist engagement under value-based contracts. |
Methodological Framework
A spread of perspectives from home health agency executives, Medicare Advantage plan contracting officers, state Medicaid waiver administrators, and skilled nursing facility operators converged on the working assumptions. Primary interviews with clinical workforce recruiters and remote patient monitoring platform engineers supplemented secondary validation through CMS Medicare cost report data, state Medicaid managed care rate filings, and hospital discharge pattern databases. Bottom-up service line volume estimates triangulated against top-down reimbursement flow analysis across the care continuum.
Demand-supply balance framing anchored the analytical framework, modeling patient acuity distributions against licensed clinician availability across metropolitan and rural service territories. Segmentation dimensions included service type, delivery model, patient category, and funding source, with regional regulatory cluster and Medicare Advantage penetration rate as additional industry-specific variables. CAGRs derived from historical reimbursement trend analysis and projected site-of-care shift assumptions. Forecast inputs incorporated CMS site-neutral payment phase-in schedules and state Medicaid HCBS waiver expansion trajectories.
Sensitivities concentrate around Medicare Advantage rate-setting volatility, state Medicaid eligibility expansion decisions, and remote monitoring technology adoption curves. Forecasts reflect documented assumptions regarding demographic aging trajectories and policy demonstration permanence. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Canada Corporate Wellness Market
Healthcare Services
Europe Medical Affairs Outsourcing Market
Healthcare Services
Eastern Europe Online Pharmacy Market
Healthcare Services
China Fertility Services Market
Healthcare Services
US Concierge Medicine Market
Healthcare Services
Healthcare Transportation Services Market
Healthcare Services
Healthcare Logistics Market
Healthcare Services
Medical Social Working Services Market
Healthcare Services
Audiology Services Market
Healthcare Services
US Care Services Market
Healthcare Services
Global Geriatric Care Services Market
Healthcare Services
Global Ambulatory Services Market
Healthcare Services
Acute Care Market
Healthcare Services
US Hospice Care Market
Healthcare Services
Assisted Living Market
Healthcare Services
Direct-To-Patient Healthcare Logistics Market