
 Global Sperm Bank Market | 2026-2036
Global Sperm Bank Market Size, Share, and Industry Trends Forecast 2026-2036
Global Sperm Bank Market Foresight
Modular service bundling is restructuring how fertility clinics procure donor sperm, with cryopreservation, genetic screening, and shipping logistics increasingly packaged as unified offerings rather than discrete transactions. Cryos International leverages its Nordic donor base and extensive international shipping infrastructure to sustain cross-border market presence. Fairfax Cryobank anchors its competitive position through comprehensive genetic testing protocols and broad phenotype cataloging. California Cryobank differentiates via strict donor qualification standards and long-standing relationships with major US fertility networks.
A sperm bank is a specialized reproductive tissue repository that collects, screens, cryopreserves, and distributes human spermatozoa for assisted reproduction or research, requiring liquid nitrogen storage at minus 196 degrees Celsius to maintain viability over extended periods. Its primary commercial purpose is to enable fertility treatments for individuals and couples facing male factor infertility, genetic risk, or non-traditional family formation. Frozen sperm occupies the dominant volume position due to extended shelf stability and regulatory compatibility with quarantine protocols, while online platforms represent the fastest-growing distribution channel as telehealth integration reduces geographic barriers to donor selection. Donor sperm commands premium positioning relative to patient-directed cryopreservation because of the extensive screening, legal documentation, and phenotypic matching services embedded in the product.
The FDA enforces donor screening and testing requirements under 21 CFR Part 1271, while the EU Tissue and Cells Directive harmonizes quality and safety standards across member states, and Health Canada regulates semen processing through its Processing and Distribution of Semen for Assisted Conception Regulations. These frameworks shape market access by mandating infectious disease testing windows, donor eligibility intervals, and facility inspection schedules that determine operational costs and geographic service radius. Stakeholders must monitor evolving donor anonymity legislation in Denmark and the United Kingdom, where policy shifts toward open-identity donation could reshape inventory composition and pricing structures within established donor pools.
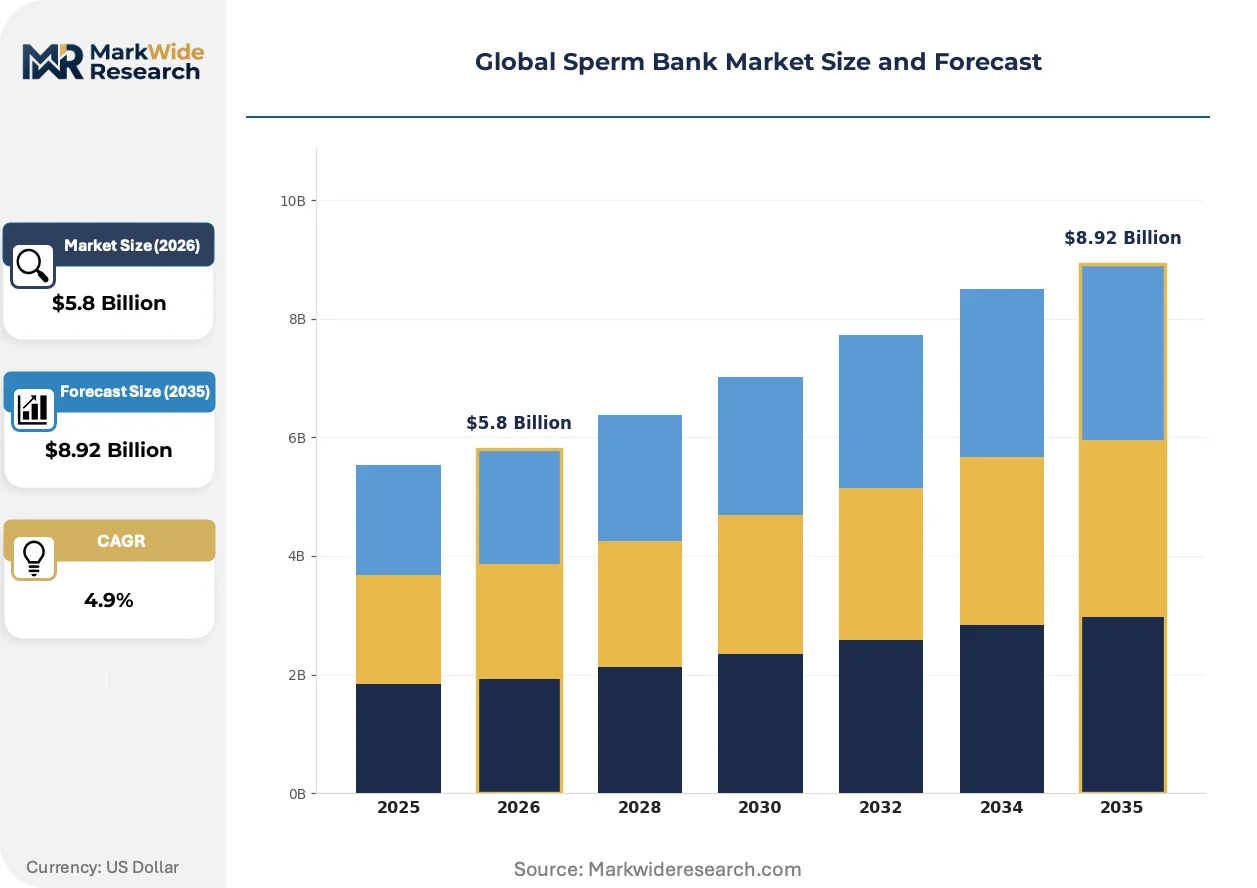
Market Dynamics
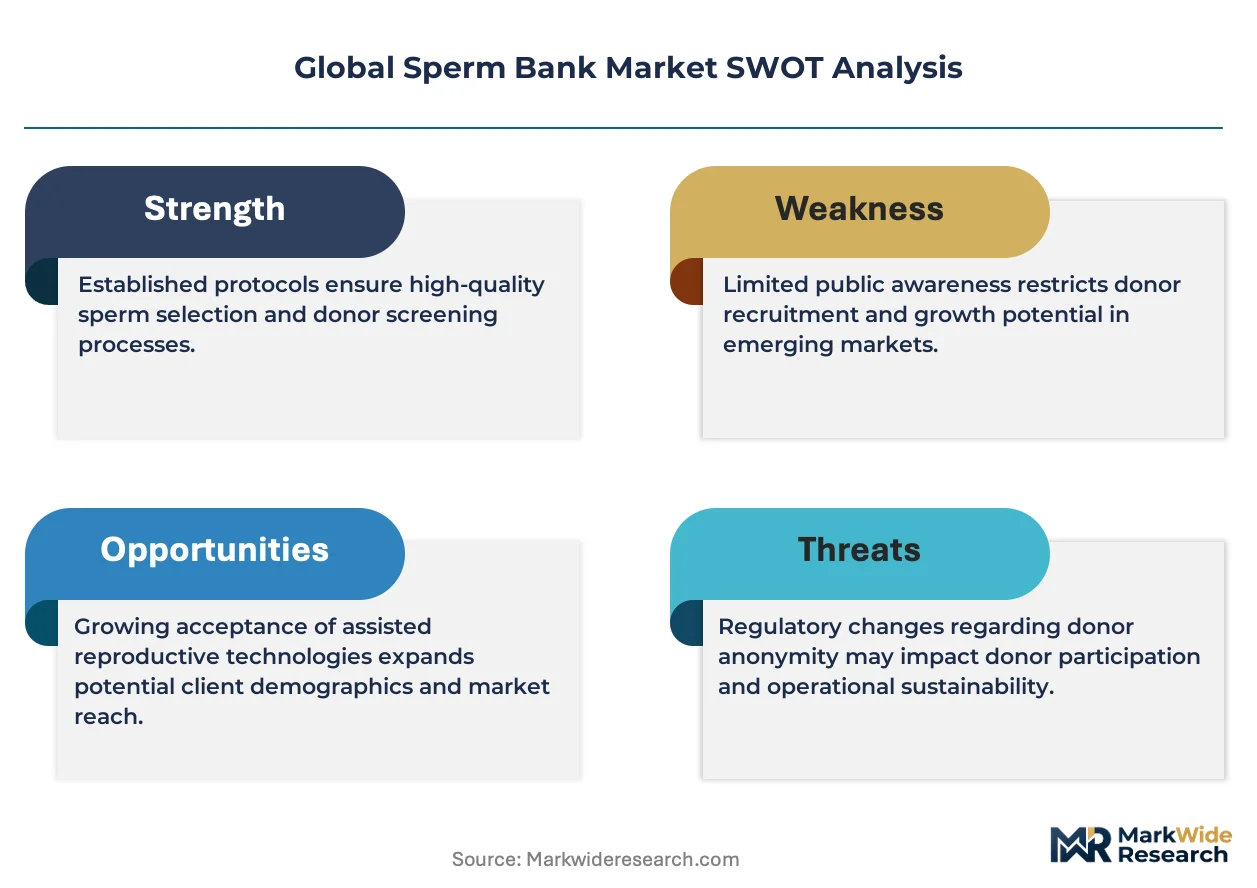
Donor anonymity erosion across Denmark and the United Kingdom is restructuring inventory economics, as open-identity donation mandates lengthen donor recruitment cycles and compress available phenotype diversity within established cryobank networks.
Growth Catalysts
- EU Tissue and Cells Directive:Harmonized quality standards across member states reduce cross-border friction, enabling Danish and Spanish cryobanks to scale donor base access into France and Germany without facility duplication.
- Single-parent demand:Fertility clinics in urban United States markets report rising utilization of donor sperm for intentional solo parenthood, expanding addressable patient population beyond traditional infertility diagnosis.
- Liquid nitrogen logistics:Cryogenic shipping infrastructure investments by specialized cold-chain operators now sustain viability across 72-hour international transits, unlocking remote clinic procurement from Nordic donor pools.
Market Restraints
- Donor supply concentration:Denmark and the United States collectively dominate phenotypically diverse donor availability, creating geographic dependency risk for clinics in Australia and Canada seeking specific ethnic matching profiles.
- Genetic screening cost inflation:Expanded carrier testing panels for spinal muscular atrophy and cystic fibrosis now add substantial per-donor processing overhead, compressing margin structures for mid-tier cryobank operations.
- Quarantine protocol rigidity:FDA-mandated six-month infectious disease hold periods under 21 CFR Part 1271 delay inventory monetization and increase working capital intensity for United States-based facilities.
Strategic Opportunities
- Telehealth-integrated donor selection:Online phenotype browsing with real-time genetic counselor consultation is expanding into Brazil and Mexico, reducing geographic barriers for Latin American fertility clinics previously dependent on United States shipping.
- Known-donor cryopreservation services:Friend-and-family sperm banking for LGBTQ+ couples represents underdeveloped white space in France and Germany, where regulatory frameworks now accommodate directed donation outside anonymous systems.
- Artificial intelligence matching:Facial recognition algorithms paired with genetic compatibility scoring are converging with electronic health record integration, enabling phenotype prediction from recipient partner photographs.
Industry Challenges
- Donor recruitment specialist scarcity:Licensed mental health professionals qualified for FDA-mandated psychological screening face acute shortage in United States Midwest and Mountain West regions, elongating donor onboarding timelines.
- Liquid nitrogen infrastructure capex:Facility expansion for minus 196 degrees Celsius storage requires specialized vapor-phase tank installations with seismic certification, creating capital barriers for new market entrants in earthquake-prone California and Japan.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Sperm Bank Market |
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $8.92 Billion |
| CAGR (2026 – 2036) | 4.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen Sperm, Fresh Sperm, Cryopreserved Samples, Donor Sperm, Processed Sperm Application: Fertility Treatments, Research & Development, Genetic Testing, Surrogacy Services, Artificial Insemination End User: Fertility Clinics, Hospitals, Research Institutions, Surrogacy Agencies, Biotech Firms Distribution Channel: Direct Sales, Online Platforms, Medical Distributors, Clinics, Telehealth Services |
| Companies Covered | Cryos International, Fairfax Cryobank, European Sperm Bank, New England Cryogenic Center, Xytex Corporation, California Cryobank, Seattle Sperm Bank, The London Sperm Bank, Androcryos, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Sperm Bank Market Shifts & Advancements
Next-generation genetic screening and digital distribution infrastructure are compressing the traditional cryobank value chain, collapsing donor discovery, phenotypic matching, and logistics coordination into unified platform experiences that bypass legacy clinic intermediation.
Expanded carrier screening panels incorporating whole-exome sequencing are expanding into standard donor qualification protocols, replacing targeted single-gene assays. Fertility networks in the United Kingdom and Netherlands now require this depth as table stakes for network inclusion. The technology is expanding into premium donor tier construction, enabling price stratification based on genomic comprehensiveness rather than phenotype alone.
Denmark's 2023 legislative pivot toward mandatory open-identity donation for all new registrants establishes regulatory precedent now under review in Norway and Sweden. The policy compresses anonymous donor inventory value and accelerates premium pricing for grandfathered anonymous specimens. Cryobanks with large legacy anonymous reserves in Copenhagen and Aarhus hold transitional competitive advantage as supply-constrained markets absorb price premiums.
Direct-to-consumer donor browsing with at-home fertility kit integration is displacing traditional clinic-mediated selection in urban United States and Australian markets. Younger demographic cohorts prefer self-directed digital interfaces over physician-facilitated catalog review, forcing fertility clinics to unbundle sperm procurement from treatment service packaging. This behavioral shift concentrates most visibly in Melbourne, Sydney, Los Angeles, and New York metropolitan corridors where telehealth penetration already exceeds national averages.
Global Sperm Bank Market Segmentation
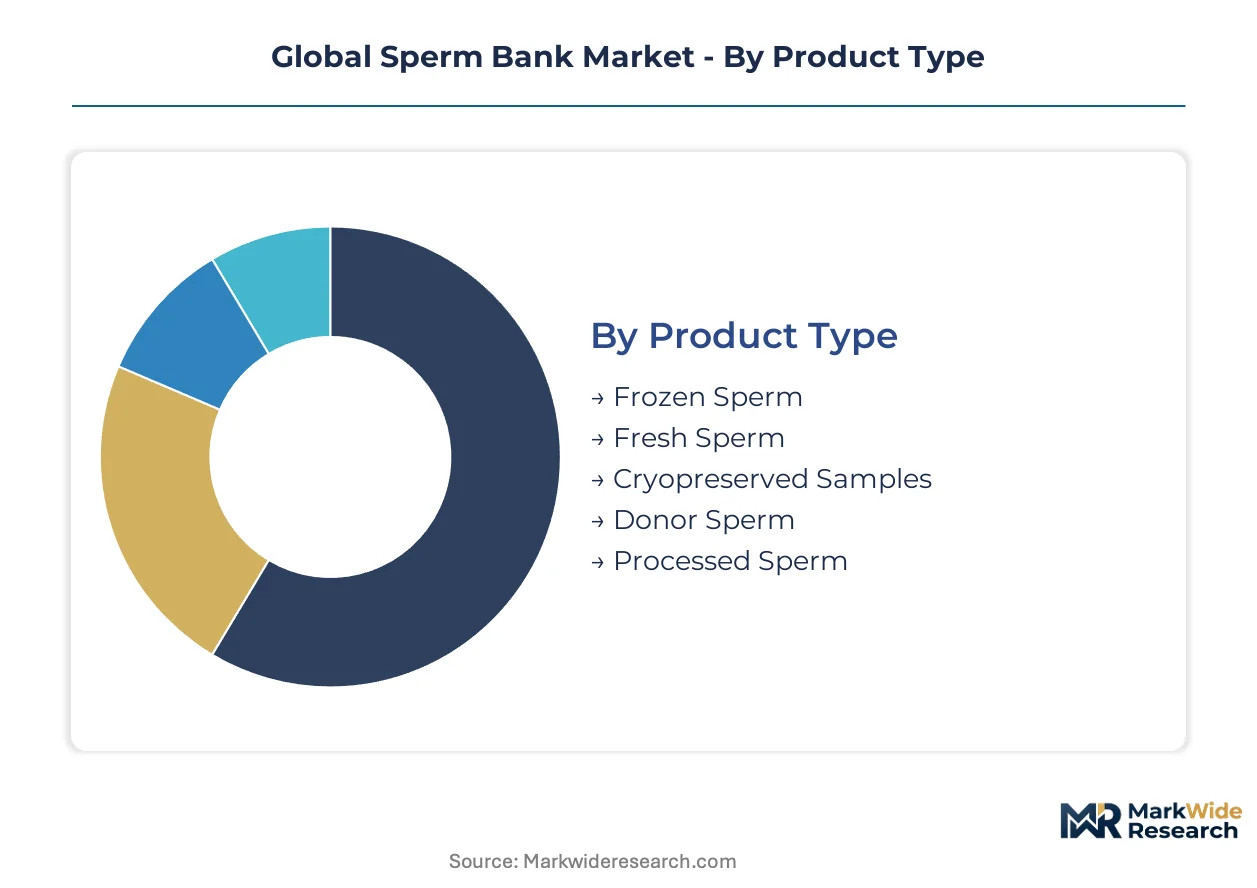
Segmentation in the sperm bank market reveals how procurement priorities diverge across clinical versus research buyers, with cryopreservation requirements and regulatory compliance needs driving distinct purchasing patterns. Understanding these divides enables suppliers to align inventory depth, screening protocols, and logistics infrastructure with specific customer workflows.
Product Type:
Buyers differentiate primarily by shelf stability requirements and quarantine flexibility, with clinical fertility networks prioritizing inventory predictability over specimen freshness.
- Frozen Sperm:Cryopreserved at minus 196 degrees Celsius using liquid nitrogen vapor-phase storage, this format enables six-month infectious disease quarantine compliance under FDA 21 CFR Part 1271. Demand concentrates in United States fertility networks and Danish export operations where extended inventory holding and international shipping viability are essential.
- Donor Sperm:Extensively screened specimens with complete phenotypic profiles, genetic carrier testing, and legal documentation packages embedded. United Kingdom and Netherlands fertility clinics drive premium positioning as open-identity mandates reshape inventory economics and compress available donor pools.
- Fresh Sperm:Limited to same-day clinical use with minimal processing, primarily serving known-directed donation arrangements outside anonymous bank systems.
- Cryopreserved Samples:Patient-directed fertility preservation for oncology patients or gender transition protocols, with demand clustering in major metropolitan hospital networks.
- Processed Sperm:Washed, gradient-separated specimens optimized for intrauterine insemination procedures, reducing uterine cramping and improving motility concentration per milliliter.
Volume sits with Frozen Sperm; growth tilts toward Donor Sperm as regulatory anonymity erosion tightens supply.
Application:
Revenue concentration tracks reimbursement pathways, with fertility treatments commanding premium pricing while research applications compete on volume and specimen throughput.
- Fertility Treatments:Clinical insemination and in vitro fertilization cycles utilizing donor or partner sperm, requiring comprehensive genetic screening and infectious disease clearance. United States urban fertility networks and Spanish reproductive medicine centers anchor demand as single-parent and same-sex couple utilization expands.
- Artificial Insemination:Less invasive, lower-cost procedure with higher cycle frequency and corresponding specimen throughput requirements. Australian and Canadian clinic networks favor this approach for cost-conscious patients, driving demand for mid-tier donor inventory with standard screening packages.
- Research & Development:Academic and commercial studies on spermatogenesis, cryobiology, and reproductive toxicology, with procurement prioritizing volume discounts and batch consistency over individual donor profiling.
- Genetic Testing:Validation studies for expanded carrier screening panels and whole-exome sequencing protocols, concentrated in United Kingdom and Netherlands fertility networks requiring research-grade specimen quality.
- Surrogacy Services:Third-party reproduction arrangements with complex legal coordination, primarily serving United States and Ukrainian surrogacy agency networks before regulatory disruptions.
Fertility Treatments capture the revenue base; Artificial Insemination climbs the fastest as cost sensitivity reshapes clinical protocol selection.
End User:
Procurement sophistication varies sharply, with fertility clinics demanding full-service bundling while research institutions prioritize specimen flexibility and pricing transparency.
- Fertility Clinics:Specialized reproductive medicine centers requiring integrated donor selection, genetic counseling, and cryogenic logistics. United States metropolitan networks and Copenhagen-based Nordic operations concentrate procurement volume as telehealth integration reshapes patient acquisition.
- Research Institutions:Universities and government laboratories studying male infertility mechanisms and cryopreservation optimization, with procurement favoring bulk agreements and minimal phenotypic documentation overhead.
- Hospitals:General medical centers with oncology fertility preservation programs, requiring rapid-turnaround patient-directed banking services alongside donor specimen access.
- Surrogacy Agencies:Coordination intermediaries managing third-party reproduction logistics, with procurement concentrated in jurisdictions permitting commercial surrogacy arrangements.
- Biotech Firms:Commercial developers of reproductive health diagnostics and therapeutics, sourcing specimens for assay validation and biomarker discovery programs.
Fertility Clinics dominate transaction volume; Research Institutions gain share fastest as expanded genetic screening protocols proliferate.
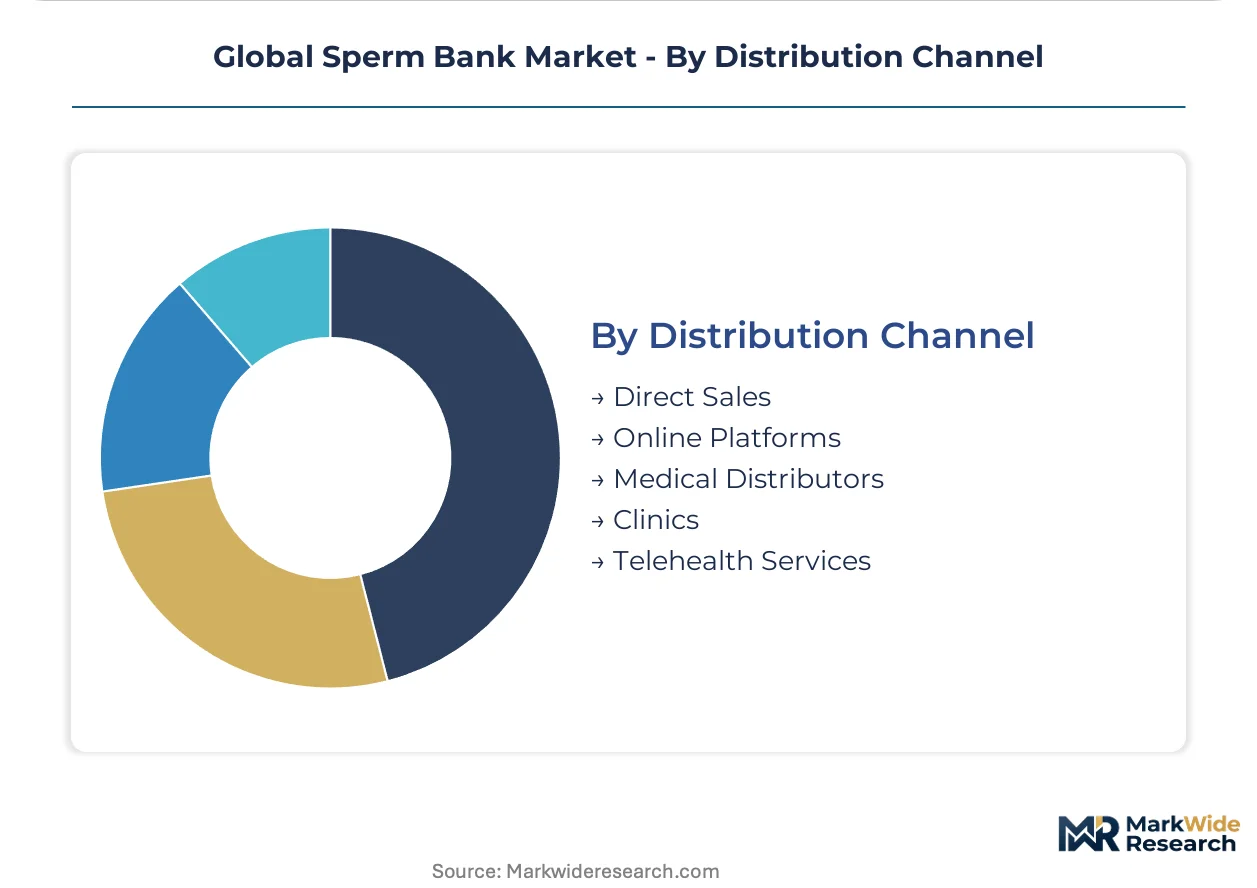
Distribution Channel:
Channel selection reflects geographic isolation and patient demographic preferences, with digital platforms displacing traditional clinic-mediated selection in urban, telehealth-penetrated markets.
- Online Platforms:Direct-to-consumer donor browsing with phenotype filtering, genetic report access, and at-home fertility kit integration. Melbourne, Sydney, Los Angeles, and New York metropolitan corridors drive steepest expansion trajectory as younger demographics prefer self-directed selection.
- Direct Sales:Cryobank-to-clinic relationships with dedicated account management and customized inventory allocation. Established United States fertility networks and Danish export operations rely on this channel for predictable supply security.
- Medical Distributors:Regional intermediaries consolidating procurement for smaller clinic networks, particularly in Australian and Canadian markets lacking direct cryobank presence.
- Clinics:Traditional physician-facilitated catalog review and donor selection, retaining dominance in jurisdictions with limited telehealth penetration or regulatory restrictions on direct patient access.
- Telehealth Services:Integrated virtual consultation with genetic counselor support and remote prescription fulfillment, expanding into Brazil and Mexico to reduce geographic barriers for Latin American fertility networks.
Direct Sales holds the volume base; Online Platforms expand most quickly as patient self-direction reshapes procurement behavior.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Denmark and the United States concentrate donor supply infrastructure while consumption spreads across fertility networks in Australia, Canada, and Western Europe. Cryogenic logistics networks now bridge this geographic divide, enabling Nordic donor pools to reach clinics in São Paulo and Sydney within 72-hour viability windows.
United States
Urban fertility networks in Los Angeles, New York, and Chicago drive donor sperm utilization for single-parent and same-sex couple family formation. FDA enforces donor screening under 21 CFR Part 1271, mandating six-month infectious disease quarantine periods that delay inventory monetization. California Cryobank anchors West Coast supply chains through established relationships with metropolitan clinic networks.
Denmark
Copenhagen and Aarhus host the world's most phenotypically diverse anonymous donor reserves, though 2023 open-identity legislation compresses future supply economics. The EU Tissue and Cells Directive harmonizes quality standards, enabling Danish cryobanks to scale into Germany and France without facility duplication. Cryos International leverages Nordic donor bases and international shipping infrastructure to sustain cross-border market presence.
United Kingdom
London fertility clinics report tightening donor availability as open-identity mandates reshape inventory composition and pricing structures. The Human Fertilisation and Embryology Authority regulates donor anonymity transitions, accelerating premium pricing for grandfathered anonymous specimens. The London Sperm Bank concentrates procurement volume within metropolitan reproductive medicine networks.
Australia
Melbourne and Sydney metropolitan corridors exhibit fastest-growing direct-to-consumer donor browsing adoption, with younger demographics preferring self-directed digital interfaces. The Therapeutic Goods Administration regulates semen processing standards, creating compliance barriers for mid-tier cryobank market entry. Online platforms displace traditional clinic-mediated selection in telehealth-penetrated urban markets.
Germany
Berlin and Munich fertility networks increasingly source donor specimens from Danish and Spanish cryobanks under EU harmonized standards. The German Medicines Act and transplant regulations govern directed donation frameworks, creating white space for known-donor cryopreservation services. Friend-and-family sperm banking for LGBTQ+ couples represents underdeveloped market opportunity.
Global Sperm Bank Market Competitive Landscape
The competitive structure tilts toward specialized cryobank operators with integrated genetic screening and logistics capabilities rather than diversified healthcare conglomerates. Market concentration remains moderate, with Nordic and North American facilities commanding premium positioning through donor phenotype diversity and regulatory compliance depth. Three archetypes dominate: international shipping specialists with extensive donor catalogs, regional clinics with captive banking services, and technology-integrated platforms enabling direct patient selection. Geographic expansion through cryogenic logistics partnerships and portfolio diversification into genetic counseling represent dominant competitive moves.
Within the international shipping specialist tier, Cryos International and Fairfax Cryobank exemplify scale-driven positioning through extensive donor base access and cross-border infrastructure. California Cryobank anchors the premium-tier vector for United States fertility networks. European Sperm Bank occupies a position bridging Nordic supply concentration with Western European demand expansion. These operators represent the transition from clinic-mediated procurement toward platform-integrated patient self-direction.
| Leading Market Players |
|---|
| Cryos International |
| Fairfax Cryobank |
| European Sperm Bank |
| New England Cryogenic Center |
| Xytex Corporation |
| California Cryobank |
| Seattle Sperm Bank |
| The London Sperm Bank |
| Androcryos |
| Others |
Supply & Pricing Matrix
Liquid nitrogen storage and cryogenic logistics costs cascade through donor sperm pricing tiers, with specialized vapor-phase tank infrastructure and 72-hour international shipping viability commanding premium positioning for Nordic-sourced specimens against domestic alternatives.
Pricing Analysis
Cost compression in mid-tier donor inventory accelerates as expanded carrier screening panels for spinal muscular atrophy and cystic fibrosis inflate per-donor processing overhead. Three-tier pricing structure across premium, standard, and economy levels stratifies by genetic screening comprehensiveness and phenotype documentation depth. Price differentiation hinges on whole-exome sequencing inclusion and open-identity donation status. Australian and Canadian clinic networks exhibit highest price sensitivity due to geographic dependency on imported donor pools, while United Kingdom fertility clinics absorb premiums for grandfathered anonymous specimens.
Supply Chain Analysis
Returns of compromised cryogenic shipments trigger complex reverse-logistics protocols requiring specialized hazardous materials handling and donor specimen destruction documentation under FDA 21 CFR Part 1271. Supply concentrates in Denmark and the United States as the dominant phenotypically diverse donor sources, with Spain emerging as a secondary hub under EU Tissue and Cells Directive harmonization. Raw material dependencies center on liquid nitrogen supply security, vapor-phase storage tank manufacturing, and licensed mental health professional availability for psychological screening. Single-source vulnerability concentrates in Nordic donor pool access for Asia-Pacific clinics. Distribution runs through direct cryobank-to-clinic relationships with dedicated account management, supplemented by regional medical distributors in Australian and Canadian markets lacking direct cryobank presence.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Donor recruitment specialist scarcity functions as the binding capacity constraint, elongating onboarding timelines and propping pricing for qualified specimens as open-identity mandates compress available supply.
For Market Incumbents: Hedge against anonymous donor inventory obsolescence by accelerating premium tier construction around genomic comprehensiveness rather than phenotype alone. Secure backward integration into liquid nitrogen logistics infrastructure to defend margin position against specialized cold-chain operator pricing power. Prioritize captive supply of licensed mental health screening capacity in United States Midwest and Mountain West regions where specialist scarcity elongates donor recruitment cycles most acutely. For New Entrants and Emerging Players: LGBTQ+ couples seeking known-donor cryopreservation services in France and Germany represent the most penetrable white-space target, as regulatory frameworks now accommodate directed donation outside anonymous systems. Telehealth-integrated donor selection platforms for Latin American fertility networks offer secondary entry vector. Pursue partnership-based go-to-market with established Nordic cryobanks for immediate donor catalog access rather than de novo recruitment. For Investors and Strategic Acquirers: Denmark's 2023 legislative pivot toward mandatory open-identity donation is the leading indicator that inventory economics will permanently favor cryobanks holding large legacy anonymous reserves. Position acquisition screening toward facilities with transitional competitive advantage in supply-constrained markets. Monitor Norwegian and Swedish regulatory review timelines for open-identity mandate expansion as the primary inflection signal for anonymous inventory valuation compression.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Integrated Donor Matching Platform | Facial recognition algorithms paired with genetic compatibility scoring enable phenotype prediction from recipient partner photographs. |
| Cryogenic Logistics Infrastructure Expansion | Specialized cold-chain operator investments sustain 72-hour international transit viability for Nordic donor pool access. |
| Whole-Exome Sequencing Protocol Adoption | Expanded carrier screening panels replace single-gene assays, enabling premium tier construction in United Kingdom and Netherlands networks. |
| Telehealth-Integrated Donor Selection | Virtual consultation with genetic counselor support reduces geographic barriers for Brazil and Mexico fertility clinics. |
| Known-Donor Cryopreservation Service Launch | Friend-and-family sperm banking addresses underdeveloped white space for LGBTQ+ couples in France and Germany regulatory frameworks. |
Research Methodology
Independent corroboration across cryobank operations directors, fertility clinic procurement managers, and reproductive endocrinologists underwrites the qualitative findings presented in this study. Primary interviews with liquid nitrogen logistics specialists, genetic counseling program leads, and regulatory affairs officers at facilities under FDA 21 CFR Part 1271 and EU Tissue and Cells Directive jurisdiction were cross-referenced against secondary validation from FDA inspection databases, EUDAMED vigilance reports, and national fertility society registry data. Bottom-up donor inventory analysis and top-down market sizing triangulation ensure consistency across volume and value estimates.
Comparable-period anchoring to historical donor utilization patterns and cryogenic shipping volume trends established the forecast window baseline. Segmentation modeling incorporated product type, application, end user, and distribution channel dimensions alongside geographic regulatory cluster differentiation. CAGRs were derived from trend extrapolation adjusted for policy inflection points including Denmark's open-identity mandate. Industry-specific inputs encompassed donor recruitment cycle duration data and genetic screening cost inflation trajectories.
Revisions become necessary when donor anonymity legislation spreads beyond Denmark to Norway and Sweden, or when expanded carrier screening panel requirements proliferate through additional EU member state transpositions. Practitioners should monitor regulatory filing timelines for open-identity mandates and liquid nitrogen supply chain disruption indicators for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Global Concierge Medicine Market
Healthcare Services
Medical Recruitment Market
Healthcare Services
Hair Restoration Services Market
Healthcare Services
Vaccine Transport Carrier Market
Healthcare Services
US Post-Acute Care (PAC) Market
Healthcare Services
US Acute Hospital Care Market
Healthcare Services
Healthcare CMO Market
Healthcare Services
Medical Devices and Equipment Logistics Market
Healthcare Services
Global Funeral Homes and Funeral Services Market
Healthcare Services
Chronic Disease Management Service Market
Healthcare Services
Asia-Pacific Healthcare Cold Chain Logistics Market
Healthcare Services
Nutraceutical Contract Manufacturing Services Market
Healthcare Services
US Cord Blood Banking Services Market
Healthcare Services
Escort Bed Sharing Market
Healthcare Services
IVD Contract Manufacturing Services Market
Healthcare Services
Transitional Care Management Services Market