
 Sterilization Services Market | 2026-2036
Sterilization Services Market Size, Share, and Industry Trends Forecast 2026-2036
Sterilization Services Market Intelligence
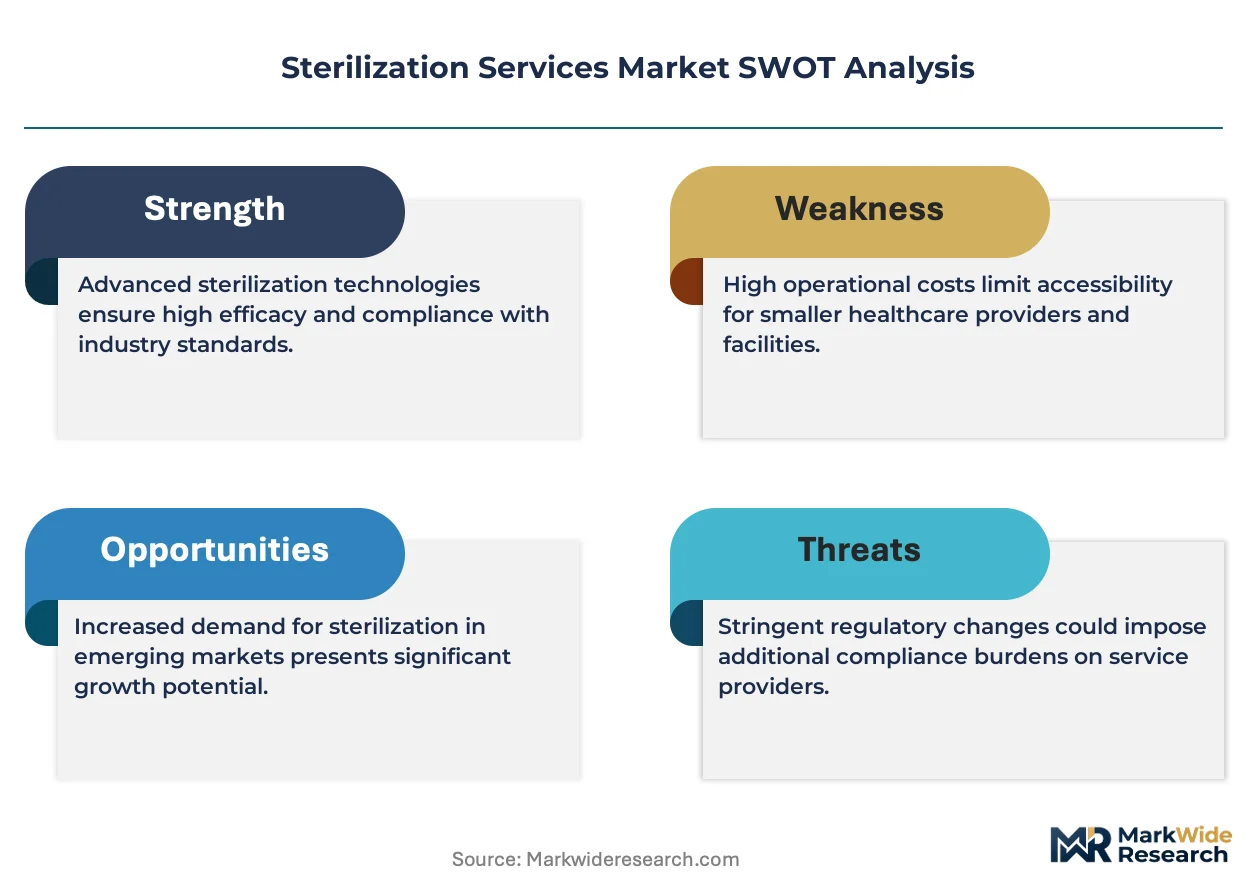
A capital-intensity divergence between gamma irradiation and electron beam operators is reorganizing competitive tiers in sterilization services. STERIS leverages its integrated equipment-manufacturing and service network to control lifecycle costs across hospital and industrial accounts. Sotera Health anchors North American ethylene oxide capacity while navigating EPA emissions scrutiny through facility modernization. Getinge competes on autoclave technology leadership, extending its installed base into recurring service contracts.
Sterilization services encompass validated microbial elimination processes applied to medical devices, pharmaceuticals, and packaging materials using ionizing radiation, chemical agents, thermal energy, or oxidative gases to achieve specified sterility assurance levels, typically SAL 10^-6. Ethylene oxide dominates porous and heat-sensitive medical device applications, while radiation sterilization captures high-volume disposable product lines where polymer compatibility permits. Steam sterilization occupies mature hospital central supply departments with thin margins, whereas hydrogen peroxide vapor systems are gaining share in temperature-critical pharmaceutical isolator applications. Laboratory equipment sterilization represents a fragmented, regionally served segment with lower compliance barriers.
FDA, EPA, and ISO 11135 standards govern ethylene oxide residuals, emissions limits, and validation protocols in the United States, forcing facility relocations and alternative technology investments. The EU MDR and REACH frameworks impose parallel documentation and chemical restriction requirements on European service providers. Stakeholders must monitor regulatory divergence between residual gas limits and emissions caps, as these dual pressures will determine which sterilization modalities capture displaced ethylene oxide volume.
Market Dynamics
EPA emissions enforcement against ethylene oxide sterilizers is decomposing established facility networks and forcing capital redeployment toward electron beam and hydrogen peroxide vapor alternatives.
Growth Catalysts
- Surgical backlog normalization:Hospital systems in the United States are expanding outsourced sterilization contracts to clear deferred procedures accumulated during pandemic disruptions.
- FDA residual gas limits:Updated validation protocols under ISO 11135 are compelling medical device manufacturers to upgrade sterilization assurance documentation.
- Polymer-compatible irradiation:Gamma and electron beam technologies are capturing volume from heat-sensitive device categories previously reserved for ethylene oxide.
Market Restraints
- Ethylene oxide supply concentration:North American sterilization capacity clusters around legacy ethylene oxide infrastructure vulnerable to EPA facility shutdowns.
- Cobalt-60 sourcing dependency:Gamma irradiation operators face isotope supply constraints tied to limited commercial reactor capacity in Canada and Russia.
- Capital intensity of beam conversion:Electron beam sterilization requires high-energy accelerator investment that mid-scale contract sterilizers cannot finance.
Strategic Opportunities
- Pharmaceutical isolator sterilization:Hydrogen peroxide vapor systems are penetrating aseptic filling line applications where thermal methods destroy biologic drug stability.
- EU MDR documentation services:Sterilization validation outsourcing is expanding in Germany and Ireland as device manufacturers absorb new conformity assessment burdens.
- Regional electron beam hubs:Industrial sterilization demand in Mexico and Costa Rica is attracting accelerator investment to serve medical device manufacturing migration.
Industry Challenges
- Validation engineer scarcity:Microbiological sterilization assurance expertise is concentrated among aging specialists with limited training pipeline replacement.
- Legacy ethylene oxide remediation:Facility decommissioning and site restoration costs are absorbing capital that could deploy alternative sterilization capacity.
- Cross-modal equivalence documentation:Switching sterilization methods requires extensive bioburden and sterility assurance level revalidation under FDA and ISO frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sterilization Services Market |
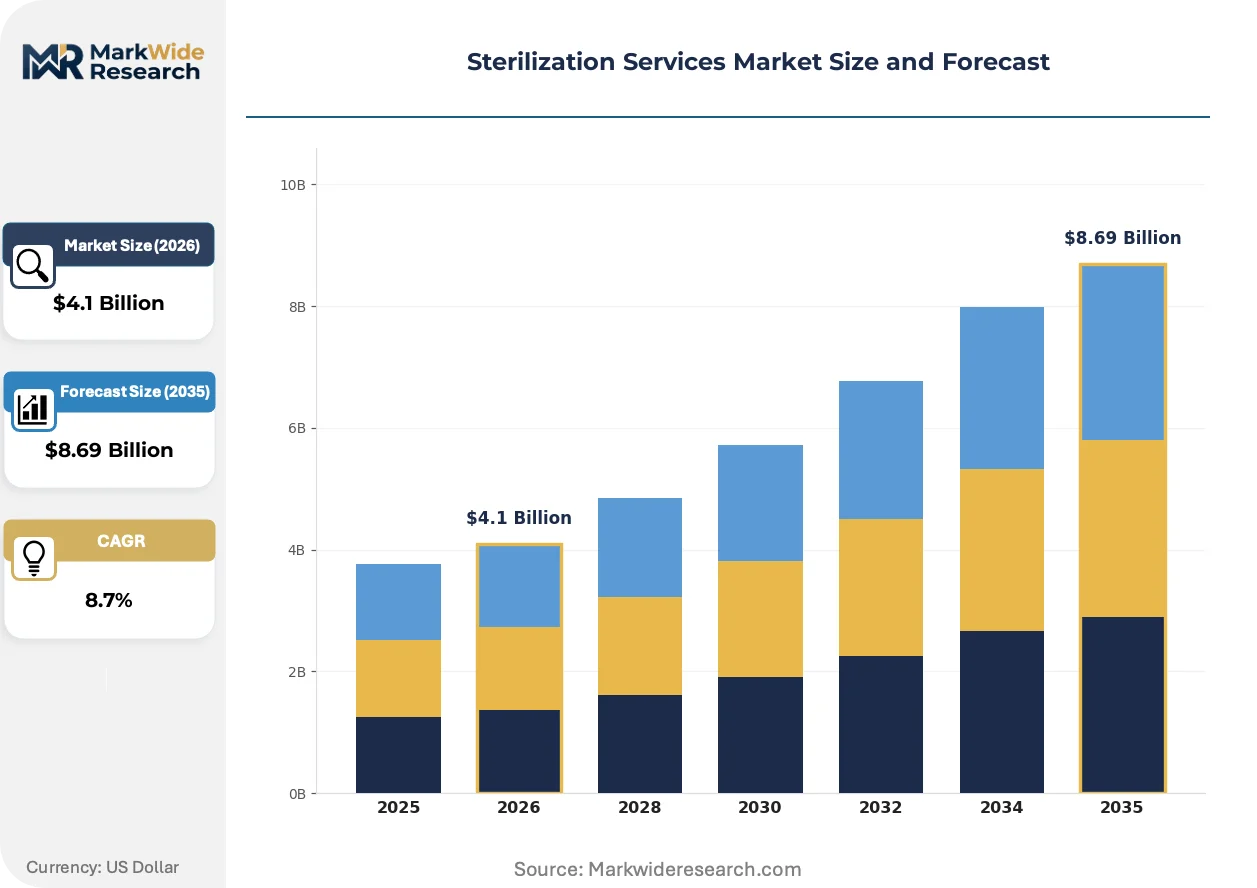
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $8.69 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Ethylene Oxide, Steam Sterilization, Radiation Sterilization, Hydrogen Peroxide End User: Hospitals, Clinics, Laboratories, Pharmaceutical Companies Application: Medical Devices, Pharmaceutical Products, Laboratory Equipment, Packaging Materials Technology: Vaporized Hydrogen Peroxide, UV Sterilization, Autoclave Processing, Dry Heat Sterilization |
| Companies Covered | STERIS, Sotera Health, Servizi Italia S.p.A, E-BEAM Services, Inc., BGS Beta-Gamma-Service GmbH & Co. KG, Medistri SA, Getinge, Solventum Corporation, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sterilization Services Market Strategic Shifts & Innovations
Technology substitution is accelerating as regulatory pressure compounds against legacy chemical sterilization while radiation and vapor methods achieve validation parity for sensitive device categories.
X-ray sterilization is decomposing the cobalt-60 dependency that has constrained gamma irradiation expansion for decades. High-power electron accelerators converted to bremsstrahlung X-ray output are penetrating medical device sterilization contracts in the United States where isotope supply uncertainty has disrupted scheduling. This technology is decomposing the geographic concentration of sterilization capacity around nuclear reactor-sourced cobalt.
REACH chemical restriction proposals are forcing ethylene oxide sterilizers toward closed-loop emissions capture and catalytic oxidation systems in European Union member states. The industrial consequence is elevated operating cost structures that disadvantage smaller contract sterilizers against integrated multinationals. Germany and the Netherlands are seeing the most facility consolidation as operators absorb compliance investment.
Consolidated procurement of sterilization services by hospital purchasing alliances is compressing contract margins and extending performance guarantee terms. Group purchasing organizations are unbundling validation documentation from core sterilization pricing and awarding contracts to lowest-validated-bid vendors. This pattern is most visible in United States health system networks where central supply standardization has reduced supplier counts by half.
Sterilization Services Market Segmentation
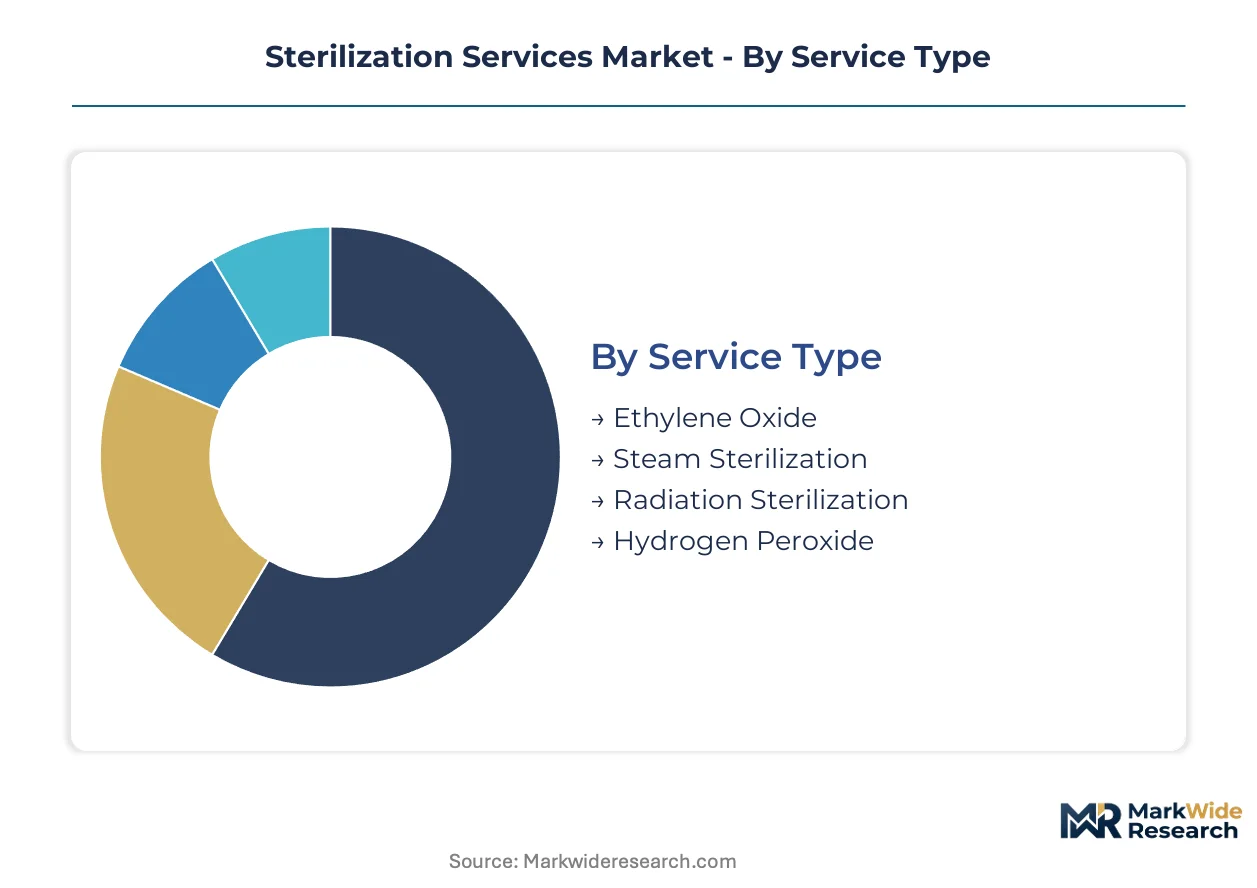
Sterilization service providers compete across distinct technical modalities and customer workflows. Segmentation reveals where regulatory pressure, capital requirements, and validation complexity create sustainable competitive advantages.
Service Type:
FDA residual limits and EPA emissions caps differentiate compliance burdens across modalities.
- Ethylene Oxide:Gas-phase sterilization penetrates porous packaging and complex device geometries at ambient temperatures. Hospital systems in the United States rely on outsourced ethylene oxide capacity as EPA facility closures concentrate supply among modernized operators.
- Radiation Sterilization:Gamma and electron beam irradiation eliminate microbial contamination through ionizing energy without thermal stress. Medical device manufacturers in Costa Rica and Mexico are expanding radiation contracts as manufacturing migrates to regional hubs.
- Steam Sterilization:Saturated vapor under pressure destroys vegetative cells and spores in heat-tolerant instruments. Hospital central supply departments deploy steam autoclaves for immediate-use surgical instruments with thin-margin service economics.
- Hydrogen Peroxide:Vaporized oxidative chemistry sterilizes temperature-sensitive biologics and electronic components. Pharmaceutical isolator applications in Germany are absorbing hydrogen peroxide capacity as biologic drug production expands.
Ethylene Oxide handles the majority of throughput; Hydrogen Peroxide is the fastest mover on share.
End User:
Customer scale determines contract structure from transactional validation to integrated managed services.
- Hospitals:Health systems purchase sterilization assurance for surgical instrument reprocessing and implantable device preparation. United States purchasing alliances are consolidating vendor counts and unbundling documentation from core pricing.
- Pharmaceutical Companies:Drug manufacturers require validated sterilization for aseptic filling components and final container closure systems. Ireland and Germany device manufacturers are outsourcing EU MDR documentation burdens to specialized service providers.
- Clinics:Ambulatory surgery centers contract for limited-volume instrument sterilization with rapid turnaround requirements. Regional service networks serve dispersed clinic locations with mobile sterilization units.
- Laboratories:Research and diagnostic facilities sterilize media, glassware, and biological safety equipment. This segment operates with lower compliance barriers and fragmented regional competition.
Hospitals anchor contract value; Pharmaceutical Companies are expanding most quickly as biologic manufacturing scales.
Application:
Product characteristics dictate sterilization modality selection and validation protocol complexity.
- Medical Devices:Implantable and single-use instruments require SAL 10^-6 assurance with documented bioburden control. FDA updated validation protocols are forcing manufacturers to upgrade sterilization assurance documentation across device categories.
- Pharmaceutical Products:Parenteral drugs and biologics demand sterile manufacturing components without pyrogen or residual contamination. Hydrogen peroxide vapor systems are penetrating aseptic filling lines where thermal methods compromise drug stability.
- Packaging Materials:Barrier films and sterile containers require surface sterilization without material degradation. Gamma irradiation captures high-volume disposable packaging where polymer compatibility permits energy-based processing.
- Laboratory Equipment:Pipettes, culture vessels, and analytical instruments need decontamination for research integrity. Steam and dry heat methods dominate this application with established protocol libraries.
Medical Devices commands the largest validation volume; Pharmaceutical Products shows the steepest expansion trajectory.
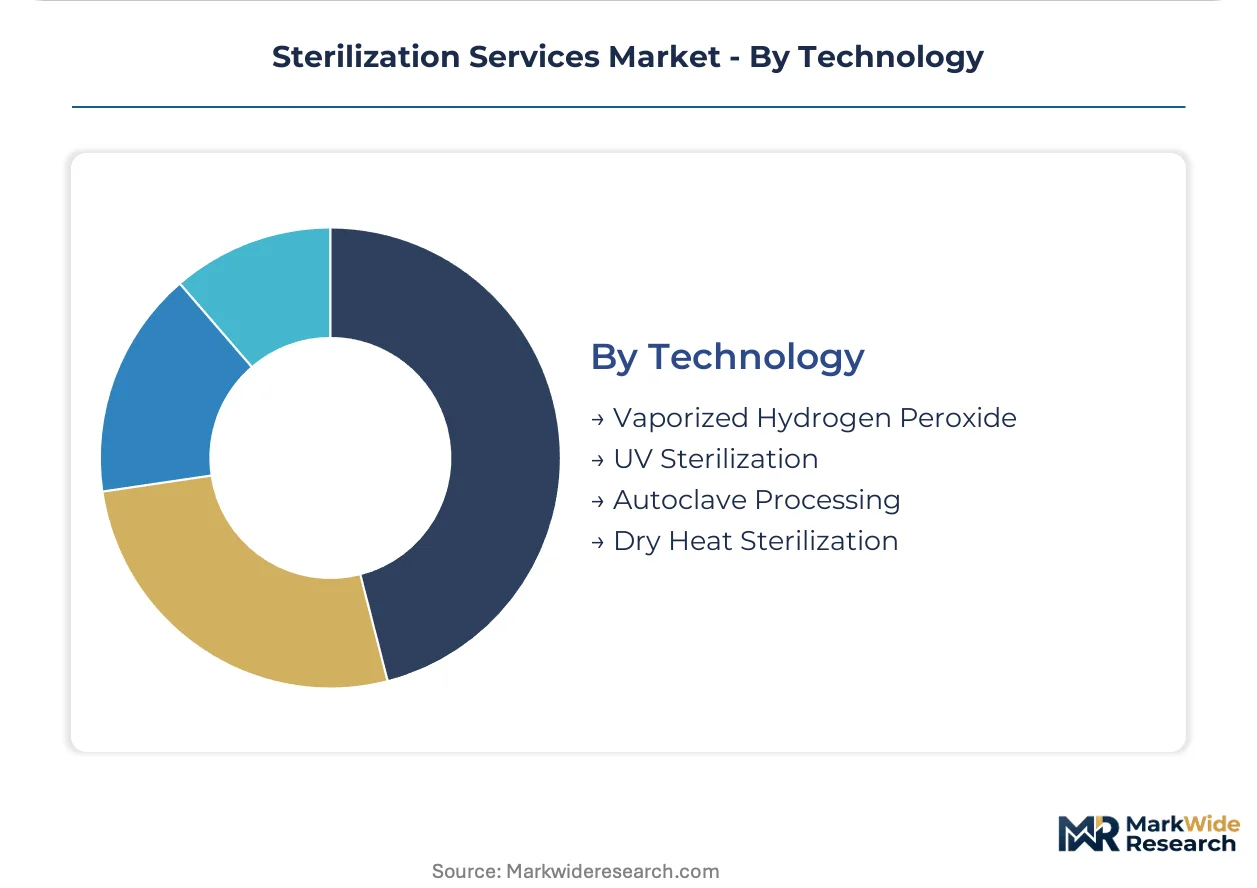
Technology:
Equipment platform selection locks operators into specific capital cycles and maintenance ecosystems.
- Autoclave Processing:Pressurized steam systems deliver reliable sterilization for heat-stable loads with mature operational protocols. Getinge extends its installed equipment base into recurring service contracts through validation expertise.
- Vaporized Hydrogen Peroxide:Low-temperature oxidative systems sterilize electronics and biologics incompatible with heat or radiation. Isolator-integrated applications in pharmaceutical manufacturing are displacing legacy ethylene oxide for sensitive product categories.
- UV Sterilization:Ultraviolet-C irradiation destroys surface and airborne pathogens without chemical residues. Surface disinfection applications in cleanroom environments are adopting UV as a rapid non-contact method.
- Dry Heat Sterilization:Convection or radiant heat eliminates pyrogens and moisture-sensitive contaminants. Depyrogenation tunnels in pharmaceutical finishing lines utilize dry heat for glassware and metal instruments.
Autoclave Processing maintains the broadest installed base; Vaporized Hydrogen Peroxide is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in sterilization services pivot on medical device manufacturing clusters seeking validated processing near production sites. The United States runs a substantial services trade surplus as domestic capacity serves offshore device assembly. Germany and Ireland balance cross-border pharmaceutical sterilization flows within the European regulatory zone.
United States
Hospital purchasing alliances in the United States are consolidating sterilization vendor counts while expanding contract volumes to clear surgical backlogs. EPA emissions enforcement against ethylene oxide facilities is forcing capacity relocation toward modernized sites. The Minneapolis-Saint Paul corridor hosts concentrated medical device manufacturing that feeds regional radiation and gas sterilization infrastructure.
Germany
Pharmaceutical isolator sterilization demand in Germany is accelerating as biologic drug production scales under EU MDR documentation requirements. REACH chemical restriction proposals are compelling ethylene oxide operators toward closed-loop emissions capture systems. The Rhine-Main region around Frankfurt clusters contract sterilizers serving parenteral drug manufacturers with hydrogen peroxide vapor capacity.
Ireland
Medical device manufacturers in Ireland are outsourcing sterilization validation burdens to specialized service providers navigating EU MDR conformity assessments. The national pharmaceutical regulator enforces documentation standards that elevate compliance costs for standalone operators. The Galway-Dublin corridor concentrates sterile manufacturing that draws electron beam and ethylene oxide processing from dedicated contract facilities.
Costa Rica
Radiation sterilization contracts in Costa Rica are expanding as medical device manufacturing migrates to regional export hubs serving North American markets. The country's investment promotion agency has targeted sterile processing infrastructure to anchor medical technology supply chains. The Central Valley around San José hosts multinational device assembly operations that contract with regional gamma irradiation providers.
Netherlands
Ethylene oxide facility consolidation in the Netherlands is absorbing compliance investment as REACH frameworks elevate operating cost structures. The national environmental agency enforces emissions caps that disadvantage smaller contract sterilizers against integrated multinationals. The Rotterdam-Antwerp port corridor supports chemical sterilization logistics for European pharmaceutical distribution networks.
Sterilization Services Market Key Industry Players
Concentration sits with integrated equipment-service operators and specialized radiation providers that control validation expertise and capital-intensive processing platforms. The vendor base organizes around three archetypes: multinational sterilization service networks with captive equipment manufacturing, regional contract irradiation specialists dependent on isotope or accelerator supply, and pharmaceutical-focused vapor sterilization operators serving isolator applications. Capacity expansion and technology licensing represent the dominant competitive moves as participants reposition away from embattled ethylene oxide infrastructure.
Within the integrated multinational tier, STERIS and Sotera Health occupy positions that exemplify divergent strategic postures toward regulatory pressure. STERIS leverages its equipment manufacturing heritage to anchor service contracts through lifecycle cost control, while Sotera Health represents the specialized ethylene oxide operator navigating EPA emissions scrutiny through facility modernization programs. Among European radiation specialists, BGS Beta-Gamma-Service GmbH & Co. KG and Medistri SA sit within the regional contract sterilization segment where cobalt-60 sourcing constraints and electron beam accelerator investments determine competitive viability.
| Leading Market Players |
|---|
| STERIS |
| Sotera Health |
| Servizi Italia S.p.A |
| E-BEAM Services, Inc. |
| BGS Beta-Gamma-Service GmbH & Co. KG |
| Medistri SA |
| Getinge |
| Solventum Corporation |
| Johnson & Johnson |
| Others |
Cost & Logistics Intelligence
Capacity reservation contracts with take-or-pay structures dominate sterilization service procurement, locking hospital systems and device manufacturers into multi-year supply access while providing cost visibility against cobalt-60 and ethylene oxide feedstock volatility. United States purchasing alliances leverage these arrangements to secure priority scheduling at modernized EPA-compliant facilities, insulating contracted volumes from spot-market disruption when legacy plants face emissions enforcement.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing stratification across premium validated services, standard contract sterilization, and economy spot processing. FDA certification tier and cobalt-60 supply security differentiate price levels, with gamma irradiation commanding premiums over electron beam alternatives. Cost compression in standard-tier contracts is intensifying as GPOs unbundle validation documentation from core sterilization fees. Ambulatory surgery centers exhibit highest price sensitivity, while pharmaceutical isolator operators accept premium positioning for hydrogen peroxide vapor assurance.
Supply Chain Analysis
Inventory buffers for cobalt-60 isotope extend lead times to 12-18 months, constraining gamma irradiation operators' capacity responsiveness. Supply concentrates in Canada and Russia for radioisotope sourcing, with Mexico and Costa Rica anchoring regional radiation hub expansion. Electron beam accelerator components draw from specialized German and Japanese precision engineering suppliers. Single-source vulnerability sits with cobalt-60 reactor dependence. Distribution runs through dedicated cold-chain logistics networks serving medical device manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sterilization services exhibit platform-economics inflection as validation data interoperability between device manufacturers and contract operators replaces transactional processing relationships. FDA's electronic submission mandates for ISO 11135 documentation accelerate this ecosystem shift.
For Market Incumbents: Compound defensive positioning through backward integration into electron beam accelerator manufacturing and captive cobalt-60 sourcing partnerships. Absorb EPA facility consolidation pressure by acquiring distressed ethylene oxide capacity in the United States for modernization. Prioritize validation engineer retention programs against specialist scarcity.
For New Entrants and Emerging Players: Lead with hydrogen peroxide vapor sterilization for pharmaceutical isolator applications where thermal sensitivity creates protected margin pools. Target Costa Rica and Mexico regional hub expansion as medical device manufacturing migrates toward tariff-advantaged export platforms. Deploy mobile sterilization units for dispersed ambulatory surgery center networks.
For Investors and Strategic Acquirers: Regional radiation specialists with electron beam accelerator deployments represent prime acquisition targets as technology substitution accelerates. Long-term viability hinges on modality diversification away from embattled ethylene oxide infrastructure. Monitor EPA enforcement patterns as inflection signal for capacity repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| Electron Beam Capacity Expansion | Reduces cobalt-60 dependency while capturing polymer-compatible device volume from ethylene oxide displacement. |
| Backward Integration into Accelerator Manufacturing | STERIS-style equipment-service integration locks lifecycle cost control across hospital and industrial accounts. |
| Hydrogen Peroxide Vapor System Deployment | Penetrates biologic drug isolator applications where FDA thermal stability requirements exclude legacy methods. |
| EU MDR Documentation Service Licensing | Captures validation outsourcing demand from Ireland and Germany device manufacturers absorbing conformity burdens. |
| Regional Hub Joint Venture | Costa Rica and Mexico accelerator partnerships anchor medical device manufacturing migration with sterilization co-location. |
Research Approach
A spread of perspectives from sterilization operations managers, hospital GPO contract directors, biomedical validation engineers, and EPA compliance officers converged on the working assumptions driving modality substitution trajectories. Primary fieldwork combined with FDA 483 inspection databases, ISO 11135 implementation filings, and customs records for cobalt-60 isotope imports. Bottom-up facility capacity assessments triangulated against top-down medical device production forecasts across the analysis window.
Segmentation dimensions modeled encompass sterilization modality, end-user vertical, device material compatibility class, and regional regulatory cluster. CAGRs derived from installed base expansion rates, surgical procedure normalization curves, and technology substitution elasticity parameters. Forecast inputs incorporate EPA enforcement probability weightings and EU MDR documentation burden absorption rates.
The analysis sits within stated boundaries; outcomes outside sustained EPA emissions cap enforcement or accelerated cobalt-60 supply disruption would require recalibration. Forecasts reflect documented assumptions regarding modality validation parity timelines and hospital outsourcing elasticity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Hair Restoration Services Market
Healthcare Services
Life Science Trade Lane Design and Qualification Services Market
Healthcare Services
Global Infusion Pharmacy Management Market
Healthcare Services
Per Diem Nurse Staffing Market
Healthcare Services
Global Perfusion Services Market
Healthcare Services
Transitional Care Management Services Market
Healthcare Services
Health Care Supply Chain Management Market
Healthcare Services
In-Home Senior Care Franchises Market
Healthcare Services
Healthcare Cold Chain Logistics Market
Healthcare Services
Western Europe Medical Recruitment Market
Healthcare Services
Hospice Market
Healthcare Services
Biopharmaceutical Third Party Logistics (3PL) Market
Healthcare Services
Healthcare Revenue Cycle Management (RCM) Outsourcing Market
Healthcare Services
Medical Spa Market
Healthcare Services
Blood Bank Market
Healthcare Services
IVD Contract Manufacturing Services Market