
 AI in Medical Billing Market | 2026-2036
AI in Medical Billing Market Size, Share, and Industry Trends Forecast 2026-2036
AI in Medical Billing Market Insights
Claims adjudication revenue is rewriting the economics of healthcare IT procurement, pulling capital away from legacy practice management suites into autonomous coding platforms. Waystar leverages its clearinghouse dominance to embed AI scoring directly at the point of claim submission. Optum sustains competitive pressure through its payer-provider vertical, using denial prediction models trained across both sides of the reimbursement cycle. Nym Health specializes in autonomous medical coding with clinical language models that operate without human-in-the-loop abstraction.
AI in medical billing encompasses software systems that apply natural language processing and machine learning to extract clinical concepts from unstructured documentation, map them to standardized code sets such as ICD-10-CM and CPT, and predict payer adjudication outcomes with quantified confidence intervals. These systems reduce administrative labor in revenue cycle operations while improving claim acceptance rates and compliance posture. Natural language processing leads technology adoption because clinical documentation remains predominantly free-text, yet robotic process automation captures the fastest growth as health systems retrofit existing electronic health record workflows without replacing core infrastructure. Cloud-based deployment anchors new implementations, though hybrid architectures persist among large hospital networks with legacy mainframe dependencies.
The US Department of Health and Human Services and the Office of the National Coordinator for Health IT shape demand through interoperability mandates and information blocking penalties that require standardized claim attachments. HIPAA security rules and state-level consumer protection statutes constrain how billing AI vendors handle protected health information, creating compliance moats around established platforms. Stakeholders must monitor whether CMS extends prior authorization automation requirements to Medicare Advantage plans, as this would force mid-size clinics to adopt AI billing tools or outsource to billing service providers with embedded technology.
Market Dynamics
Hospital revenue cycle departments are consolidating purchasing authority around autonomous coding platforms that compress claim-to-cash cycles, displacing fragmented point solutions with unified AI-native stacks.
Growth Catalysts
- Prior authorization automation:CMS tightened documentation requirements for Medicare Advantage plans, forcing providers to adopt NLP systems that extract clinical concepts from unstructured notes.
- Cloud infrastructure:Health systems are migrating revenue cycle operations to AWS and Azure environments, enabling elastic scaling for seasonal claim volume spikes without legacy mainframe dependencies.
- United States:Administrative complexity and reimbursement pressure concentrate demand in this market, where denial rates exceed 10% and labor costs for manual coding have reached unsustainable levels.
Market Restraints
- HIPAA compliance costs:Security rule constraints on protected health information handling create compliance moats that favor established vendors with dedicated legal infrastructure.
- Legacy EHR integration:Epic and Cerner deployments require expensive middleware development, extending implementation timelines and consuming IT capital that could fund net-new AI procurement.
- Clinical validation requirements:Autonomous coding systems must demonstrate physician-equivalent accuracy across subspecialties before health systems accept human-out-of-the-loop operation.
Strategic Opportunities
- Rural health clinics:Federally qualified health centers in underserved regions lack dedicated revenue cycle staff, creating white space for AI-enabled billing service providers with embedded technology.
- Real-time adjudication:Payers are piloting instant claim scoring APIs that converge robotic process automation with predictive models, enabling same-day payment for clean claims.
- State Medicaid expansion:Newly eligible populations in holdout states will generate millions of additional encounters requiring automated coding to prevent backlogs.
Industry Challenges
- Clinical informaticist shortage:Health systems cannot hire sufficient staff to validate AI-generated codes against source documentation, creating bottlenecks in go-live timelines.
- Interoperability fragmentation:Information blocking penalties from ONC have not produced uniform data standards, forcing vendors to maintain multiple integration pipelines for identical EHR workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI in Medical Billing Market |
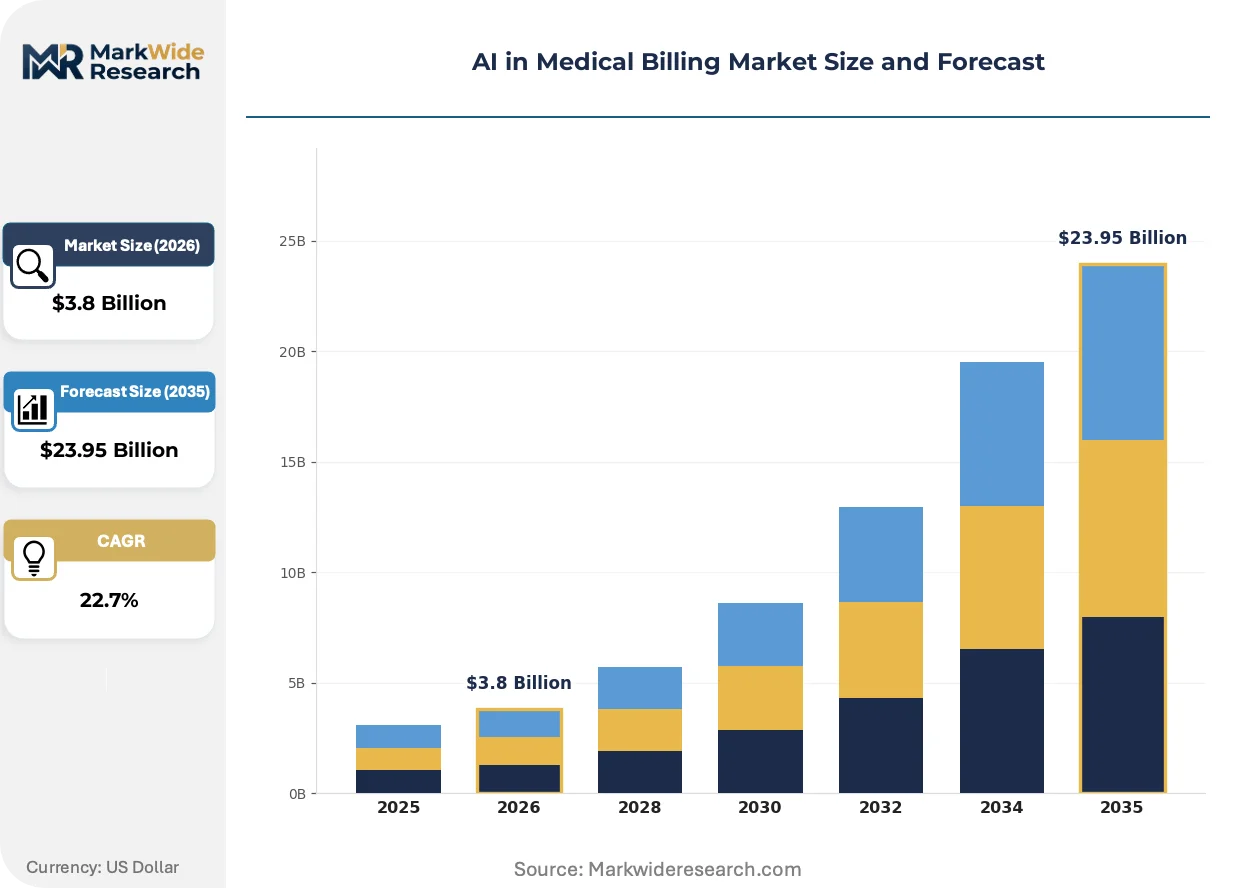
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $23.95 Billion |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Natural Language Processing, Machine Learning, Robotic Process Automation, Computer Vision End User: Clinics, Hospitals, Laboratories, Billing Service Providers Deployment: On-Premises, Cloud-Based, Hybrid, SaaS Application: Claim Management, Revenue Cycle Management, Payment Processing, Fraud Detection |
| Companies Covered | Waystar, Optum, athenahealth, NextGen Healthcare, R1 RCM, Epic Systems Corporation, AdvancedMD, RapidClaims.Ai, Nym Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI in Medical Billing Market Trends and Innovations
Natural language processing architectures are compressing the abstraction layer between clinical documentation and billing codes, eliminating manual translation steps that previously consumed 40% of revenue cycle labor.
Large language models trained on clinical corpora are collapsing the distinction between coding and clinical documentation improvement, enabling simultaneous code generation and physician query resolution. Academic medical centers are deploying these systems across emergency medicine and surgical subspecialties where documentation complexity previously required dedicated coding teams. The structural consequence is a compression of FTE requirements in hospital revenue cycle departments.
CMS interoperability mandates and information blocking penalties from ONC are forcing standardized claim attachments and API-based data exchange. Vendors must now support FHIR-based workflows or lose procurement eligibility at health systems receiving federal funding. The United States market is responding with accelerated cloud migration to meet attestation deadlines.
Subscription pricing for AI coding platforms is displacing traditional per-claim transaction models, aligning vendor incentives with client outcomes rather than volume. Health systems in competitive metropolitan markets are negotiating multi-year contracts with guaranteed denial rate reductions. This shift is most visible in California and Texas, where consolidation among billing service providers has created leverage for outcome-based contracting.
AI in Medical Billing Market Segmentation
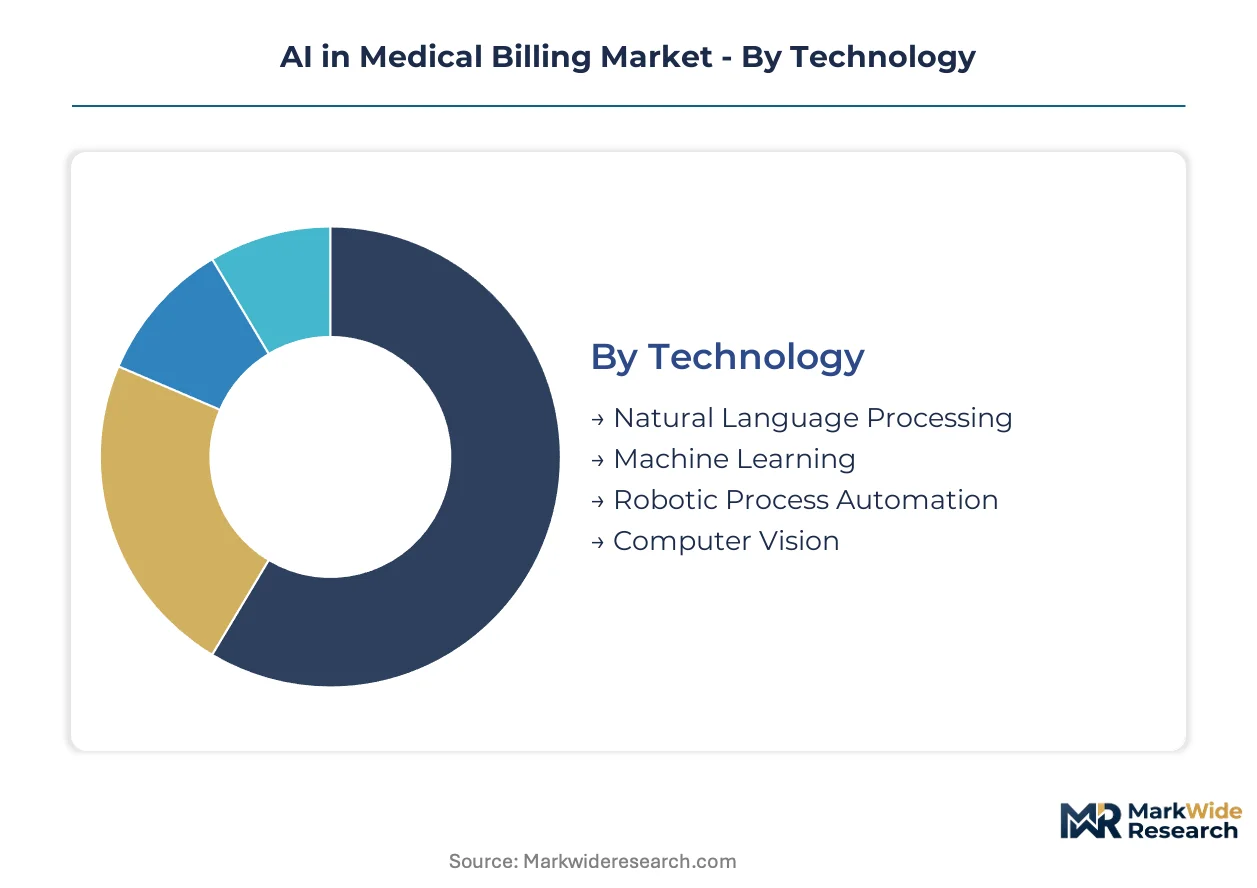
Technology selection in AI medical billing determines integration complexity, compliance overhead, and staffing requirements across revenue cycle operations. Deployment architecture and application focus further stratify vendor capabilities and client outcomes in this procurement-intensive market.
Technology:
After-sales service intensity varies sharply by technology type, with NLP and machine learning platforms requiring continuous model retraining and clinical validation support.
- Natural Language Processing:Clinical language models extract unstructured concepts from physician notes and map them to ICD-10-CM and CPT code sets without human abstraction layers. United States hospital systems concentrate procurement here, driven by CMS prior authorization documentation mandates that demand automated concept extraction from free-text records.
- Robotic Process Automation:Software bots execute repetitive revenue cycle tasks including eligibility verification, claim status checking, and remittance posting within existing EHR workflows. Cloud migration among health systems accelerates RPA adoption, as elastic infrastructure accommodates seasonal claim volume spikes without mainframe dependencies.
- Machine Learning:Predictive algorithms score claim acceptance probability and flag high-risk submissions before payer transmission.
- Computer Vision:Image recognition systems digitize paper-based documentation and handwritten clinical notes for downstream coding.
Natural Language Processing holds the largest share; momentum sits with Robotic Process Automation.
End User:
Customer type dictates pricing architecture and implementation support levels, with hospitals demanding enterprise-grade SLAs while clinics prioritize rapid deployment.
- Hospitals:Integrated delivery networks deploy autonomous coding platforms across emergency medicine and surgical subspecialties where documentation complexity previously required dedicated coding teams. United States metropolitan health systems drive procurement volume, facing denial rates exceeding 10% and unsustainable manual coding labor costs.
- Billing Service Providers:Third-party revenue cycle vendors embed AI tools to serve mid-size clinic clients without dedicated internal IT staff. Rural health clinics and federally qualified health centers create white space demand, as these underserved regions lack dedicated revenue cycle personnel.
- Clinics:Independent physician practices adopt SaaS coding platforms with minimal implementation overhead.
- Laboratories:Diagnostic testing facilities automate high-volume, repetitive coding for molecular and pathology services.
Hospitals command the dominant revenue position; billing service providers are climbing the fastest as outsourcing accelerates.
Deployment:
Volume concentration favors cloud architectures, though legacy infrastructure in large networks sustains hybrid demand.
- Cloud-Based:AWS and Azure environments host elastic revenue cycle operations, enabling health systems to scale processing capacity during quarterly reporting periods without capital expenditure on physical infrastructure. United States providers migrating to meet ONC interoperability attestation deadlines anchor this segment's expansion.
- Hybrid:Large hospital networks with mainframe dependencies maintain on-premises components for PHI-sensitive operations while offloading burst processing to cloud instances. HIPAA security rule constraints on protected health information handling favor established vendors with dedicated legal infrastructure capable of navigating complex compliance architectures.
- On-Premises:Fully localized deployments persist in highly regulated environments with strict data residency requirements.
- SaaS:Subscription pricing models align vendor incentives with client outcomes, displacing per-claim transaction structures.
Cloud-Based deployment holds the largest share; Hybrid architectures show the steepest expansion trajectory among large network implementations.
Application:
Margin profiles diverge by application, with fraud detection commanding premium pricing while claim management scales through volume.
- Claim Management:End-to-end platforms automate coding, scrubbing, submission, and denial management within unified workflows. United States revenue cycle departments consolidate purchasing authority here, seeking to compress claim-to-cash cycles and displace fragmented point solutions.
- Revenue Cycle Management:Comprehensive suites span patient access through collections, integrating AI scoring across the reimbursement lifecycle. Payers piloting instant claim scoring APIs converge RPA with predictive models, enabling same-day payment for clean claims and reshaping provider cash flow expectations.
- Payment Processing:Automated remittance posting and patient financial engagement tools reduce manual reconciliation.
- Fraud Detection:Anomaly detection algorithms flag suspicious billing patterns before payer submission.
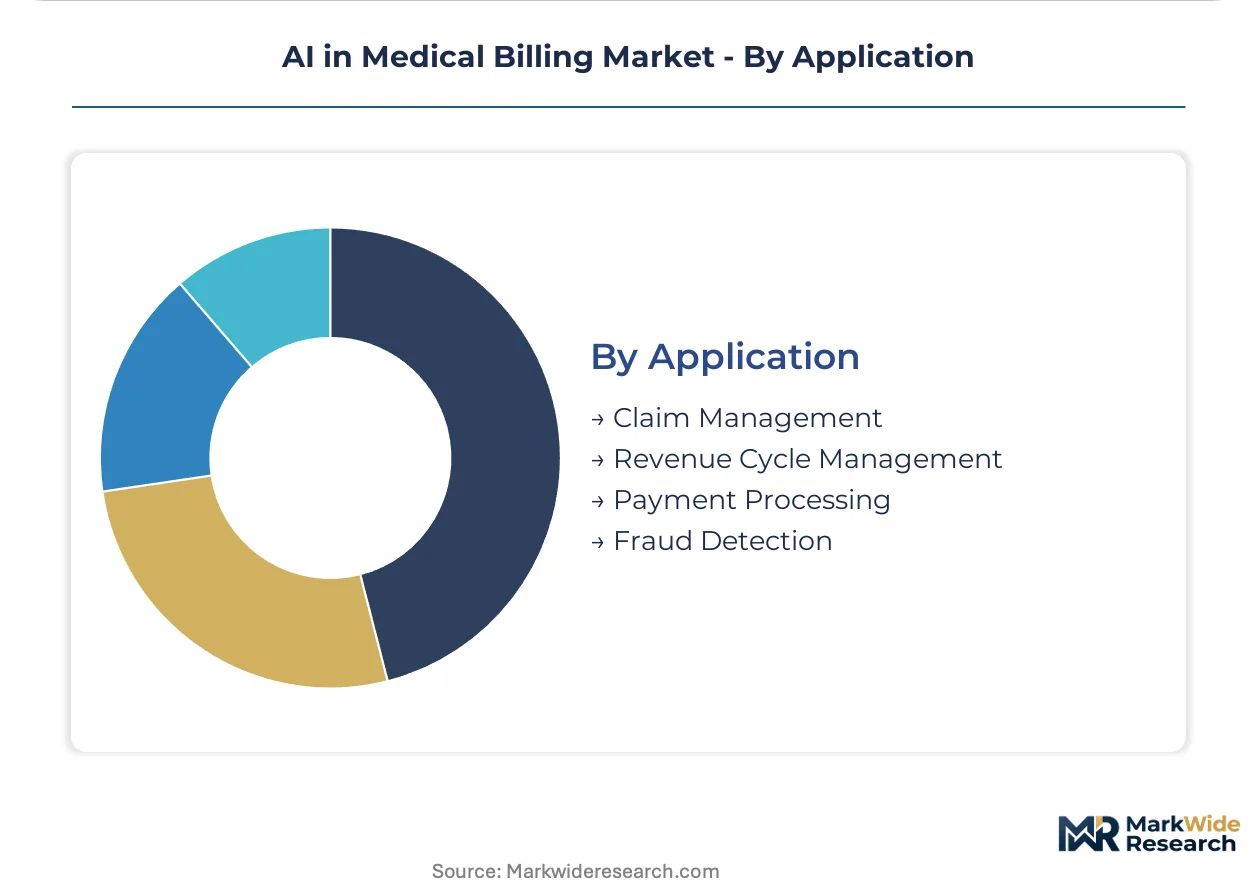
Claim Management holds the largest share; Revenue Cycle Management is gaining share fastest through platform consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for AI medical billing solutions varies sharply by market maturity. The United States absorbs premium pricing for autonomous coding platforms, while emerging markets prioritize cost-efficient robotic process automation that retrofits existing infrastructure.
United States
Hospital revenue cycle departments drive procurement volume as denial rates exceed 10% and manual coding labor costs become unsustainable. CMS tightened prior authorization documentation requirements for Medicare Advantage plans, forcing providers toward NLP systems that extract clinical concepts from unstructured physician notes. The Dallas-Fort Worth metroplex anchors health system consolidation activity, with integrated delivery networks deploying unified AI-native stacks across emergency medicine and surgical subspecialties.
Germany
Statutory health insurance funds pressure providers to reduce administrative overhead through automated coding and claims processing. The EU AI Act and GDPR impose strict compliance requirements on clinical language models handling protected health information, favoring established vendors with dedicated legal infrastructure. The Rhine-Ruhr region concentrates health IT procurement, with university hospitals in Cologne and Düsseldorf piloting autonomous coding platforms for inpatient documentation.
United Kingdom
NHS England's administrative efficiency mandates accelerate procurement of revenue cycle automation to reduce back-office staffing costs. The National Data Guardian and Information Commissioner's Office enforce stringent data protection standards on AI systems processing patient records. London's health tech cluster dominates vendor selection, with NHS trusts in the capital negotiating multi-year contracts for cloud-based claim management platforms.
India
Medical billing service providers serving US healthcare clients drive demand for AI coding platforms that compress labor costs while maintaining accuracy standards. The Digital Personal Data Protection Act constrains cross-border health data flows, pushing domestic development of compliant clinical language models. Hyderabad and Bengaluru anchor the revenue cycle outsourcing industry, with third-party vendors embedding autonomous coding tools to serve mid-size clinic clients without internal IT staff.
Canada
Provincial health authorities face budget pressure to modernize legacy billing systems without replacing core electronic health record infrastructure. Health Canada and provincial privacy commissioners regulate AI deployment in clinical documentation, creating compliance moats around established platforms. The Toronto-Waterloo corridor concentrates health AI development, with hospital networks piloting hybrid cloud architectures that maintain on-premises components for PHI-sensitive operations.
AI in Medical Billing Market Competitive Landscape
Capability concentration sits with specialized autonomous coding vendors; scale advantage sits with diversified health IT conglomerates. The market structures around three tiers: clearinghouse-integrated platforms, payer-provider verticals, and pure-play clinical language model specialists. Consolidation pressure intensifies as health systems demand unified stacks over fragmented point solutions. Dominant competitive moves include strategic partnerships with electronic health record vendors and outcome-based contracting that ties vendor compensation to denial rate reductions.
Within the specialized autonomous coding tier, Nym Health exemplifies clinical language model development without human-in-the-loop abstraction. Among diversified health IT platforms, Waystar and Optum occupy positions that leverage existing infrastructure dominance to embed AI scoring at critical workflow junctures. These three represent distinct archetypes: pure-play specialization, clearinghouse integration, and payer-provider vertical integration.
| Leading Market Players |
|---|
| Waystar |
| Optum |
| athenahealth |
| NextGen Healthcare |
| R1 RCM |
| Epic Systems Corporation |
| AdvancedMD |
| RapidClaims.Ai |
| Nym Health |
| Others |
Pricing and Supply Chain Analysis
Cloud infrastructure concentration in the United States creates asymmetric margin capture between hyperscaler-dependent vendors and clients with captive data center capacity. AWS and Azure pricing power in compute-intensive model training feeds directly into SaaS subscription tiers, while HIPAA-compliant hosting premiums sustain margin pools for established platforms with dedicated legal infrastructure.
Pricing Analysis
Continuous model retraining and clinical validation support drive lifetime value across NLP and machine learning deployments. Subscription pricing for AI coding platforms dominates procurement, displacing per-claim transaction structures and aligning vendor incentives with denial rate outcomes. Price differentiation rests on certification depth—platforms with FDA-recognized clinical decision support or ONC interoperability attestation command 20-40% premiums over unvalidated alternatives. Cost compression in mid-market SaaS tiers intensifies as billing service providers consolidate and negotiate volume discounts. Rural health clinics and federally qualified health centers exhibit highest price sensitivity, while integrated delivery networks prioritize outcome guarantees over unit economics.
Supply Chain Analysis
US export controls on advanced GPU clusters and AI training hardware constrain vendor capacity expansion and model development timelines. Compute infrastructure draws from Taiwan, South Korea, and domestic US foundries, while clinical language model training data sources from US hospital networks and academic medical centers. Supply chain risk centers on single-source vulnerability to NVIDIA datacenter GPU allocations, where healthcare AI vendors compete with hyperscalers for constrained H100 and Blackwell shipments. Distribution runs through direct enterprise sales to hospital revenue cycle departments, with channel partners serving mid-size clinic segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clinical informaticist scarcity constrains go-live velocity for autonomous coding platforms, creating a bottleneck where vendor delivery capacity outstrips health system validation bandwidth. This skill gap determines which implementations achieve human-out-of-the-loop operation versus perpetual physician oversight requirements.
For Market Incumbents: Entrench clearinghouse-integrated positions by embedding AI scoring at submission endpoints before competitors replicate workflow access. Deepen backward integration into clinical documentation improvement through large language model acquisitions that collapse coding and physician query resolution into unified platforms. Defend against pure-play clinical language model specialists by guaranteeing denial rate reductions in outcome-based contracts that tie compensation to measurable revenue cycle outcomes. For New Entrants and Emerging Players: Build out white-space presence in rural health clinics and federally qualified health centers lacking dedicated revenue cycle staff, where incumbent platforms prove over-engineered for resource-constrained environments. Target state Medicaid expansion markets in holdout states generating millions of additional encounters requiring automated coding. Pursue embedded technology partnerships with billing service providers serving mid-size clinic clients without internal IT staff, leveraging their existing client relationships for distribution leverage. For Investors and Strategic Acquirers: Capital is best deployed toward clinical language model specialists with physician-equivalent accuracy across surgical subspecialties, where technical moats resist rapid replication. Long-term viability hinges on platforms achieving autonomous operation without human-in-the-loop abstraction, compressing FTE requirements in ways that justify premium pricing. Monitor CMS extension of prior authorization automation requirements to Medicare Advantage plans as the inflection signal forcing mid-size clinic adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Strategic Partnership with EHR Vendor | Epic and Cerner integration access determines procurement eligibility at health systems receiving federal funding. |
| Acquisition of Clinical Language Model Specialist | Nym Health's autonomous coding architecture eliminates human abstraction layers competitors cannot replicate quickly. |
| Outcome-Based Contracting Structure | Guaranteed denial rate reductions align vendor compensation with client revenue cycle performance metrics. |
| Cloud Infrastructure Expansion | AWS and Azure elastic scaling accommodates seasonal claim volume spikes without mainframe capital expenditure. |
| ONC Interoperability Attainment | FHIR-based workflow support preserves procurement eligibility under information blocking penalty frameworks. |
Research Methodology
Desk research of SEC filings from health IT conglomerates, CMS Medicare cost report databases, and ONC interoperability attestation records preceded structured interviews with hospital revenue cycle executives, clinical informaticists, and billing service provider operations leaders. Primary fieldwork with AI coding platform vendors and payer denial management teams combined with secondary validation against GPO contract databases and health system RFP archives. Bottom-up deployment estimates across technology segments triangulated against top-down health IT procurement surveys.
Assumptions held fixed include HIPAA security rule enforcement intensity and ONC information blocking penalty structures, while CMS prior authorization automation mandates and Medicare Advantage plan expansion varied across scenarios. Segmentation modeling spanned technology type, deployment architecture, end-user category, and application focus across the projection horizon. CAGRs derived from weighted average of vendor booking growth rates and health system AI procurement survey responses, with clinical validation timelines and EHR integration complexity as key forecast inputs.
Stress conditions across clinical informaticist hiring rates, GPU allocation availability, and CMS regulatory enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and scenario boundaries. Material shifts in Medicare Advantage prior authorization automation timelines or export control expansion to clinical AI training hardware would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Information Systems
Ophthalmology EMR Software Market
Medical Information Systems
Global Clinical EHR Systems Market
Medical Information Systems
Healthcare Information Software Market
Medical Information Systems
Global Oncology Information System Market
Medical Information Systems
Medical Simulation Software Market
Medical Information Systems
India EMR (Electronic Medical Records) Market
Medical Information Systems
Dentistry EMR Software Market
Medical Information Systems
Medical Saas System Market
Medical Information Systems
Anesthesia Information Management Systems Market
Medical Information Systems
Medical Coding Market
Medical Information Systems
Middle East Secure Messaging in Healthcare Market
Medical Information Systems
Urology EMR Software Market
Medical Information Systems
Healthcare Information Governance Solution Market
Medical Information Systems
Global Computerized Physician Order Entry Market
Medical Information Systems
Global Allergy EMR Software Market
Medical Information Systems
Global Clinical Information System Market