
 Healthcare Third-Party Logistics Market | 2026-2036
Healthcare Third-Party Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare Third-Party Logistics Market Intelligence
The EU F-Gas Regulation is hardening cold chain requirements for fluorinated greenhouse gases used in pharmaceutical transport refrigeration. DHL Group leverages its European GDP-certified network to sustain temperature-validated lane coverage across the continent. FedEx anchors its healthcare portfolio with dedicated temperature-controlled facilities in Memphis and Cologne. Kuehne + Nagel differentiates through proprietary pharma platforms that integrate real-time monitoring with risk-based lane qualification.
Healthcare third-party logistics encompasses the outsourced management of pharmaceutical and medical product flows, encompassing temperature-controlled transport, regulatory-compliant warehousing, serialization tracking, and last-mile delivery to clinical endpoints. Cold chain monitoring technology governs the most technically demanding segment, requiring validated thermal packaging, continuous data loggers, and alarm-triggered deviation protocols to maintain 2-8°C or cryogenic conditions for biologics. Warehousing services occupy the largest value pool given high fixed-asset intensity and GDP certification barriers, while order fulfillment is expanding fastest as direct-to-patient distribution models gain traction among specialty pharmacies.
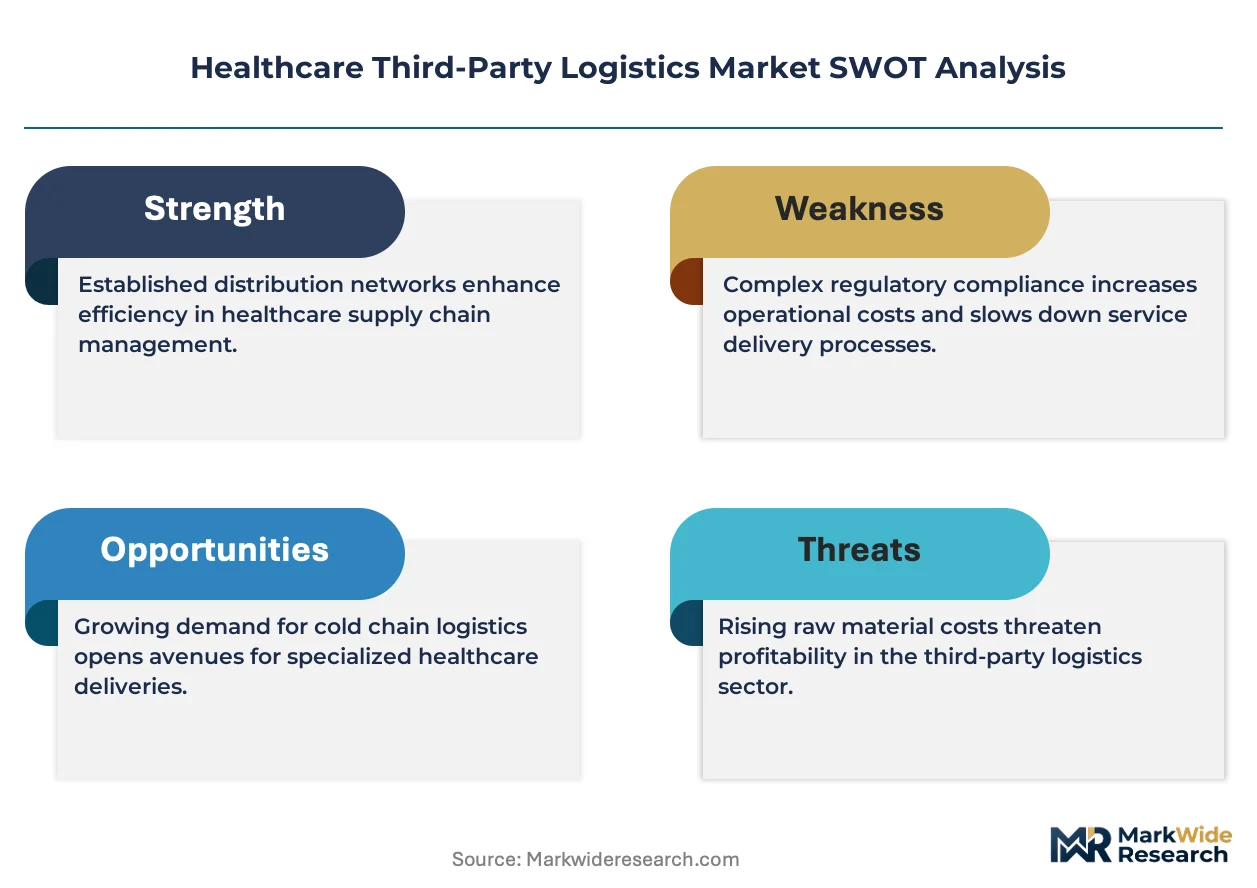
FDA's Drug Supply Chain Security Act and the EU's Good Distribution Practice guidelines jointly mandate unit-level traceability and temperature documentation, forcing 3PL providers to upgrade validation infrastructure or exit the pharma segment. The EU AI Act and emerging FDA guidance on artificial intelligence in supply chain analytics will soon shape competitive access by requiring algorithmic transparency in demand forecasting and route optimization systems. Stakeholders must decide whether to build in-house regulatory affairs capabilities or partner with specialized compliance consultancies as serialization deadlines tighten across multiple jurisdictions.
Market Dynamics
Biopharmaceutical cold chain complexity is restructuring competitive requirements as cell therapies and personalized medicines proliferate, forcing logistics providers to validate cryogenic lanes and real-time monitoring infrastructure that generic 3PL networks cannot replicate.
Growth Catalysts
- FDA DSCSA serialization mandates:Unit-level traceability requirements compel pharmaceutical manufacturers to outsource track-and-trace infrastructure to specialized 3PL providers with validated IT systems.
- Cell therapy commercialization:CAR-T and gene therapy manufacturers require time-critical, temperature-validated logistics that in-house distribution networks cannot scale.
- Germany's pharma logistics clustering:Specialized hubs around Frankfurt and Cologne concentrate European cold chain expertise, attracting biopharmaceutical distribution contracts.
Market Restraints
- EU F-Gas Regulation compliance costs:Phase-down of fluorinated refrigerants forces fleet retrofits and alternative cooling technology investments that compress margins for temperature-controlled transport operators.
- GDP certification scarcity:Limited third-party auditors and extended validation timelines create bottlenecks for warehousing capacity expansion in regulated markets.
- Dry ice supply volatility:Cryogenic shipping dependence on carbon dioxide byproduct from ammonia production exposes cell therapy logistics to fertilizer plant output fluctuations.
Strategic Opportunities
- Direct-to-patient distribution:Specialty pharmacy home delivery models create demand for last-mile cold chain capabilities with patient-facing compliance documentation.
- EU AI Act algorithmic transparency:Predictive demand forecasting and route optimization systems that meet explainability requirements gain preferential access to pharmaceutical contracts.
- India's biologics manufacturing expansion:Contract development and manufacturing organizations in Hyderabad and Bangalore require export cold chain partnerships to reach European and North American markets.
Industry Challenges
- Qualified Person certification gaps:Shortage of GDP-trained personnel with pharmaceutical supply chain expertise constrains operational scaling for mid-tier 3PL providers.
- Serialization system interoperability:Fragmented data exchange standards between manufacturer ERP platforms and 3PL warehouse management systems create integration delays.
- Thermal packaging validation cycles:Extended lane qualification protocols for seasonal temperature extremes compress operational flexibility for international shipments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare Third-Party Logistics Market |
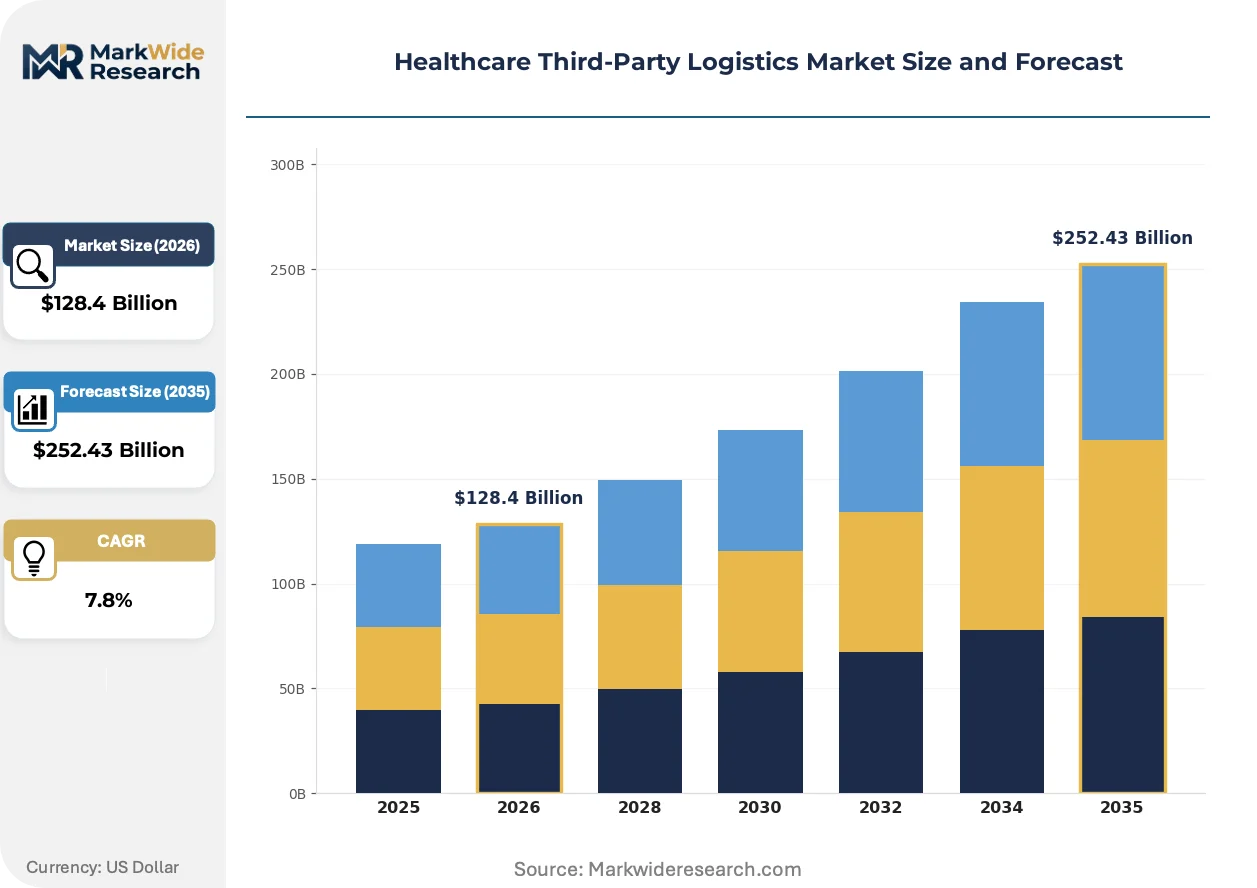
| Market Size in 2026 | $128.4 Billion |
| Market Size in 2035 | $252.43 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Order Fulfillment, Inventory Management Product Type: Pharmaceuticals, Medical Devices, Biologics, Diagnostics End User: Hospitals, Pharmacies, Clinics, Laboratories Technology: Cold Chain Monitoring, RFID, Track & Trace, Automation |
| Companies Covered | AmerisourceBergen Corporation, DB Schenker, Cardinal Health, Agility, FedEx, DHL Group, Kuehne + Nagel, Kerry Logistics Network Ltd., United Parcel Service, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare Third-Party Logistics Market Strategic Shifts & Innovations
Digital integration of cold chain monitoring with regulatory documentation systems is compressing the gap between operational execution and compliance verification, reshaping how pharmaceutical logistics contracts are structured and audited.
Real-time temperature logging with cellular-connected data loggers is consolidating fragmented visibility into continuous shipment monitoring. Biopharmaceutical manufacturers now require lane-level thermal performance data as a standard contract term. This capability is consolidating competitive differentiation around validated infrastructure rather than geographic coverage alone.
The EU AI Act's risk-based classification of supply chain analytics algorithms is tightening documentation requirements for demand forecasting systems. Pharmaceutical 3PL providers must demonstrate explainability in machine learning models used for inventory positioning. Cold chain operators with established algorithmic governance frameworks are securing preferred vendor status with EU-headquartered manufacturers.
Hospital and pharmacy procurement departments are unbundling transportation from warehousing to optimize working capital. Buyers now contract lane-specific transport separately from inventory storage, forcing 3PL providers to price components transparently. This unbundling is most pronounced in Germany and the Netherlands, where consolidated purchasing organizations negotiate multi-year logistics agreements.
Healthcare Third-Party Logistics Market Segmentation
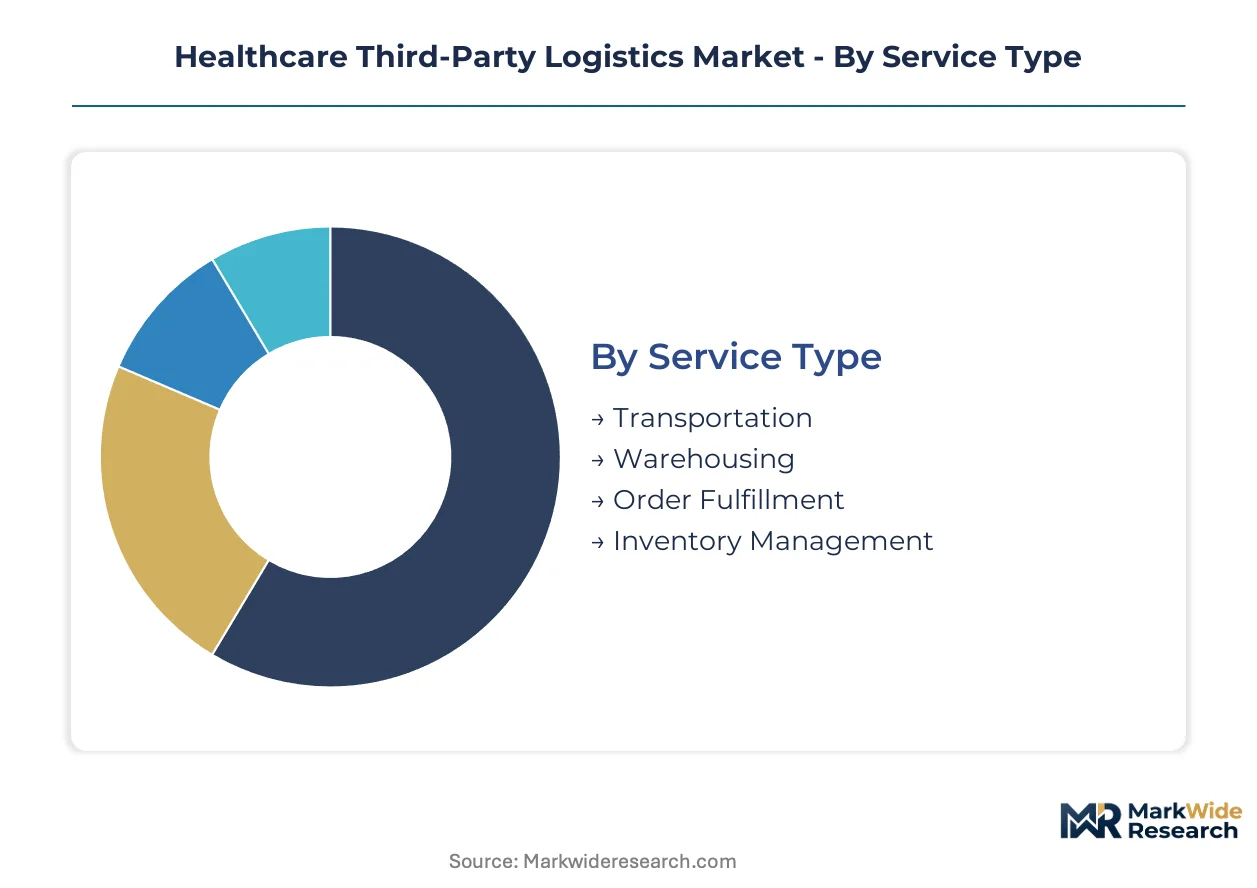
Healthcare third-party logistics providers configure service portfolios around regulatory complexity tiers, with cold chain infrastructure investments separating premium-certified operators from commodity freight handlers. Segmentation reveals how GDP compliance requirements and temperature sensitivity reshape contract structures across service lines.
Service Type:
Service line upgrades follow pharmaceutical manufacturers' outsourcing cycles as FDA DSCSA deadlines and EU GDP recertification windows force infrastructure refresh decisions.
- Transportation:Temperature-validated lane networks with continuous data logging and deviation protocols. Demand concentrates in Germany's Rhine-Main corridor, where Frankfurt and Cologne hubs anchor European biologics distribution for cell therapy manufacturers requiring cryogenic truck and air freight options.
- Warehousing:GDP-certified facilities with segregated temperature zones, qualified equipment, and dedicated pharmaceutical personnel. Hospital and pharmacy procurement departments in the Netherlands unbundle storage from transport to optimize working capital, compressing contract lengths and demanding transparent component pricing.
- Order Fulfillment:Direct-to-patient distribution with last-mile cold chain capabilities and patient-facing compliance documentation.
- Inventory Management:Serialization-tracked stock positioning with demand forecasting integration.
Warehousing sits at the top of the volume ranking, with order fulfillment climbing the fastest.
Product Type:
Product categories map to margin tiers, with temperature sensitivity and regulatory burden determining pricing power and customer stickiness.
- Biologics:Monoclonal antibodies, vaccines, and cell therapies requiring validated 2-8°C or cryogenic conditions throughout distribution. CAR-T manufacturers in the United States outsource time-critical logistics to specialized 3PL networks with real-time monitoring infrastructure that generic providers cannot replicate.
- Pharmaceuticals:Small-molecule drugs with serialization and temperature documentation requirements under FDA DSCSA and EU GDP mandates.
- Medical Devices:Sterile and implantable products with cleanroom handling protocols.
- Diagnostics:Reagents and test kits with stability-dependent shelf life management.
Biologics command premium pricing tiers, with pharmaceuticals providing the broadest revenue base across customer segments.
End User:
End-user segmentation reflects procurement centralization trends, with consolidated purchasing organizations reshaping vendor selection criteria.
- Hospitals:Integrated delivery networks with consolidated logistics contracts spanning multiple facilities.
- Pharmacies:Specialty and retail chains expanding home delivery models.
- Clinics:Outpatient facilities with fragmented ordering patterns and limited cold chain infrastructure.
- Laboratories:Clinical and research sites with time-sensitive specimen and reagent logistics requirements.
Hospitals anchor contract value, with specialty pharmacies expanding most quickly into direct-to-patient services.
Technology:
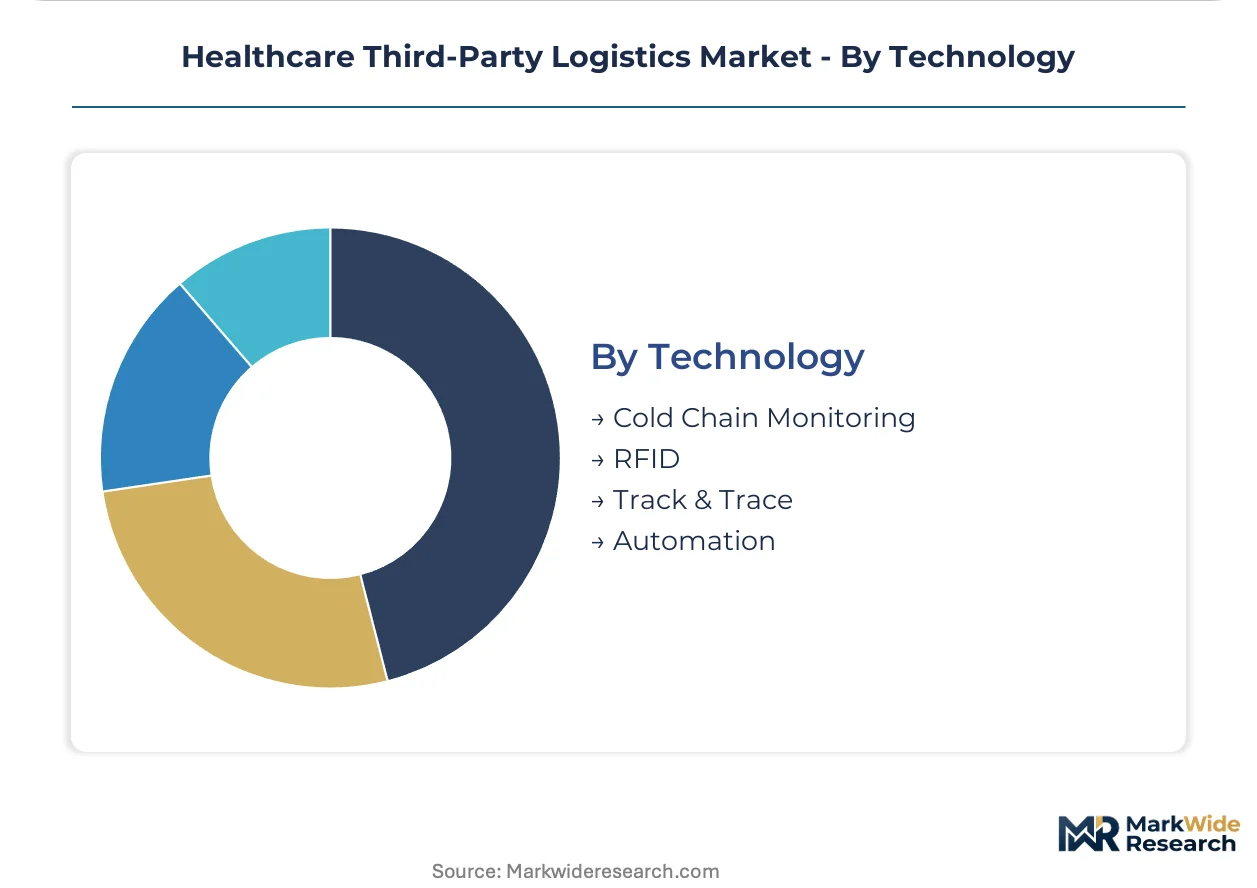
Technology adoption separates compliance-capable providers from those facing exit pressures as regulatory documentation requirements harden.
- Cold Chain Monitoring:Cellular-connected data loggers with continuous temperature recording and alarm-triggered deviation protocols. Lane-level thermal performance data is now a standard contract term for biopharmaceutical manufacturers, consolidating differentiation around validated infrastructure.
- Track & Trace:Unit-level serialization systems meeting FDA DSCSA and EU GDP interoperability requirements.
- RFID:Automated inventory tracking with real-time location systems in warehouse environments.
- Automation:Robotic picking and automated storage retrieval systems for high-throughput pharmaceutical distribution.
Cold chain monitoring leads technology investment, with track and trace systems gaining urgency as serialization deadlines approach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Healthcare third-party logistics originated in the United States pharmaceutical distribution networks of the 1960s, then migrated to Europe as biopharmaceutical manufacturing clustered around Basel and Frankfurt. Today, specialized cold chain infrastructure concentrates in five national markets where regulatory density and biologics production overlap.
United States
FDA DSCSA serialization deadlines and CAR-T therapy commercialization drive demand for validated track-and-trace infrastructure. The FDA mandates unit-level traceability with interoperable data exchange by 2028. Memphis anchors air freight cold chain capabilities for time-critical biologics distribution.
Germany
EU GDP recertification cycles and cell therapy import volumes sustain premium logistics demand. The EU F-Gas Regulation phases down fluorinated refrigerants used in pharmaceutical transport. Frankfurt and Cologne host specialized pharma logistics hubs serving as European distribution gateways for temperature-sensitive biologics.
Switzerland
Swissmedic oversight of biologics exports and precision medicine clustering create high-compliance logistics requirements. The country's pharmaceutical regulator enforces stringent temperature documentation for cross-border shipments. Basel concentrates contract manufacturing organizations requiring cryogenic lane validation.
India
Hyderabad and Bangalore biologics manufacturing expansion generates export cold chain partnerships. CDSCO serialization requirements align with EU GDP standards for pharmaceutical exports. Contract development organizations seek European and North American market access through validated temperature-controlled logistics.
United Kingdom
Post-Brexit customs complexity and MHRA regulatory divergence reshape pharmaceutical import logistics. The country's national pharmaceutical regulator maintains distinct good distribution practice requirements. London and the Southeast concentrate specialty pharmacy distribution networks with direct-to-patient cold chain capabilities.
Healthcare Third-Party Logistics Market Key Industry Players
Premium-margin players sit above commodity-margin players across certification intensity, with GDP-validated cold chain infrastructure separating price-setters from price-takers. The market exhibits tiered concentration where integrated logistics networks coexist with specialized pharmaceutical boutiques. Three archetypes dominate: diversified express carriers with healthcare divisions, dedicated pharma logistics specialists, and healthcare-focused distributors with captive logistics. Competitive moves concentrate on M&A for cold chain capabilities and strategic partnerships for last-mile patient delivery.
Within the diversified carrier tier, FedEx, DHL Group, and United Parcel Service exemplify scale-driven infrastructure plays. These companies anchor their positioning through dedicated temperature-controlled facilities and real-time monitoring networks. Kuehne + Nagel and DB Schenker occupy the specialized logistics tier, representing European-originated operators with proprietary pharma platforms. Cardinal Health and AmerisourceBergen exemplify healthcare-integrated distributors whose logistics capabilities serve captive pharmaceutical distribution demand.
| Leading Market Players |
|---|
| AmerisourceBergen Corporation |
| DB Schenker |
| Cardinal Health |
| Agility |
| FedEx |
| DHL Group |
| Kuehne + Nagel |
| Kerry Logistics Network Ltd. |
| United Parcel Service |
| Others |
Cost & Logistics Intelligence
GDP-trained logistics personnel scarcity in the Rhine-Main corridor widens labor-cost spreads between German-certified operators and Eastern European alternatives, compressing margins for mid-tier providers while premium-tier players capture pricing power through qualified-personnel retention.
Pricing Analysis
Component-unbundled contract structures separate warehousing from transportation pricing, with hospital procurement departments in the Netherlands and Germany demanding transparent lane-specific rates. Price differentiation rests on GDP certification tier and real-time monitoring infrastructure grade. Cost compression in standard transport tiers intensifies because generic 3PL networks face exit pressures from serialization compliance investments. Specialty pharmacies with direct-to-patient requirements show least price sensitivity, while retail pharmacy chains exhibit highest bargaining leverage.
Supply Chain Analysis
Dual-sourcing mandates from CAR-T manufacturers require validated cryogenic lane partnerships with at least two qualified 3PL providers per trade corridor. Supply concentrates in Germany, the United States, and Switzerland, where regulatory density sustains premium infrastructure investment. Raw material dependencies span dry ice feedstock from ammonia production, validated thermal packaging substrates, and cellular-connected data logger components. Single-source vulnerability in qualified-person certification creates operational bottlenecks for network expansion. Distribution runs through hub-and-spoke models anchored at Frankfurt, Memphis, and Cologne.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU F-Gas Regulation compliance costs in Germany create cost advantages for Indian cold chain operators serving export biologics markets with equivalent GDP certification at lower labor rates.
For Market Incumbents: Hedge against dry ice supply volatility by securing multi-source carbon dioxide offtake agreements with fertilizer producers across three or more production regions. Deepen backward integration into proprietary thermal packaging manufacturing to defend margin position from commodity input swings. Accelerate qualified-person training pipelines in Poland and Hungary to offset certification scarcity bottlenecks in core German hubs. For New Entrants and Emerging Players: Mid-sized contract development organizations in Hyderabad and Bangalore represent the most penetrable buyer archetype, as these biologics exporters require EU-validated cold chain partnerships but face incumbent capacity constraints. Target direct-to-patient last-mile capabilities for specialty pharmacy networks in the United Kingdom, where post-Brexit customs complexity has fragmented incumbent service continuity. Lead with algorithmic transparency credentials aligned to EU AI Act requirements as a differentiated go-to-market angle. For Investors and Strategic Acquirers: Diversified express carriers with healthcare divisions are the most active acquirer in this space, consolidating specialized pharma logistics boutiques to fill cryogenic capability gaps. Long-term viability favors operators with integrated serialization-track-and-trace infrastructure spanning multiple regulatory jurisdictions. Watch for FDA DSCSA interoperability deadline enforcement as an inflection indicator that will force margin compression on non-compliant mid-tier players and accelerate acquisition premiums for validated networks.| Strategic Initiative | Industry Significance |
|---|---|
| GDP Certification Investment | EMA recertification windows in Germany and Switzerland create first-mover advantages for compliant warehouse capacity. |
| Cryogenic Lane Validation | CAR-T therapy commercialization in the United States demands time-critical infrastructure that generic 3PL networks cannot replicate. |
| Algorithmic Governance Framework | EU AI Act explainability requirements confer preferred vendor status with Basel-headquartered biopharmaceutical manufacturers. |
| Direct-to-Patient Capability Buildout | Specialty pharmacy home delivery models in the Netherlands and United Kingdom expand addressable market for last-mile cold chain operators. |
| Multi-Source Dry Ice Supply Agreement | Fertilizer plant output fluctuations in carbon dioxide production regions expose cell therapy logistics to temperature excursion risks. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Interviews with pharmaceutical logistics directors, regulatory affairs leads, hospital procurement managers, and cold chain operations heads informed operational assumptions. Secondary sources include FDA DSCSA guidance documents, EU GDP recertification records, EMA inspection databases, and customs trade flow data. Bottom-up capacity modeling and top-down market sizing were triangulated to derive segment-level outputs.
Granularity-level modeling disaggregated revenue across service type, product temperature sensitivity, end-user procurement centralization, and technology adoption tier, with additional segmentation by regional regulatory cluster. CAGRs were derived from trend extrapolation of outsourcing penetration rates and infrastructure investment cycles. Forecast inputs incorporated biologics manufacturing capacity expansion timelines and serialization compliance deadline schedules across FDA and EMA jurisdictions.
Underlying measurement precision varies by segment; cold chain monitoring technology and German logistics hub activity carry tighter precision than emerging market export corridors. Forecasts reflect assumptions regarding regulatory enforcement consistency and qualified-person certification throughput. Deviation in EU F-Gas Regulation phase-down schedules or FDA DSCSA interoperability rulings would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Direct-To-Patient Healthcare Logistics Market
Healthcare Services
Primary Care Physicians Market
Healthcare Services
Global Cath Lab Services Market
Healthcare Services
Regulatory Affairs Outsourcing Market
Healthcare Services
Global Value Based Healthcare Services Market
Healthcare Services
Medical Devices and Equipment Logistics Market
Healthcare Services
US Hospice Market
Healthcare Services
Medical Peer & External Physician Review Services Market
Healthcare Services
Global Operating Room Management Market
Healthcare Services
Surgical Fluid Disposal Market
Healthcare Services
Global Corporate Wellness Solutions Market
Healthcare Services
US Integrated Delivery Network Market
Healthcare Services
North America Healthcare Cold Chain Logistics Market
Healthcare Services
Tissue Banking Market
Healthcare Services
US Care Services Market
Healthcare Services
Europe Pharmaceutical Logistics Market