
 US Registered Nurses Market | 2026-2036
US Registered Nurses Market Size, Share, and Industry Trends Forecast 2026-2036
US Registered Nurses Market Intelligence
Subscription-based workforce management platforms is shifting how health systems procure nursing talent, bundling credential verification, scheduling optimization, and compliance tracking into recurring contracts. AMN Healthcare anchors its market presence through proprietary vendor management systems that integrate directly with hospital ERP infrastructure. Aya Healthcare competes on geographic density, sustaining exclusive relationships with academic medical centers across multiple states. Fastaff differentiates through rapid-response deployment, specializing in strike coverage and crisis surge staffing with guaranteed arrival windows.
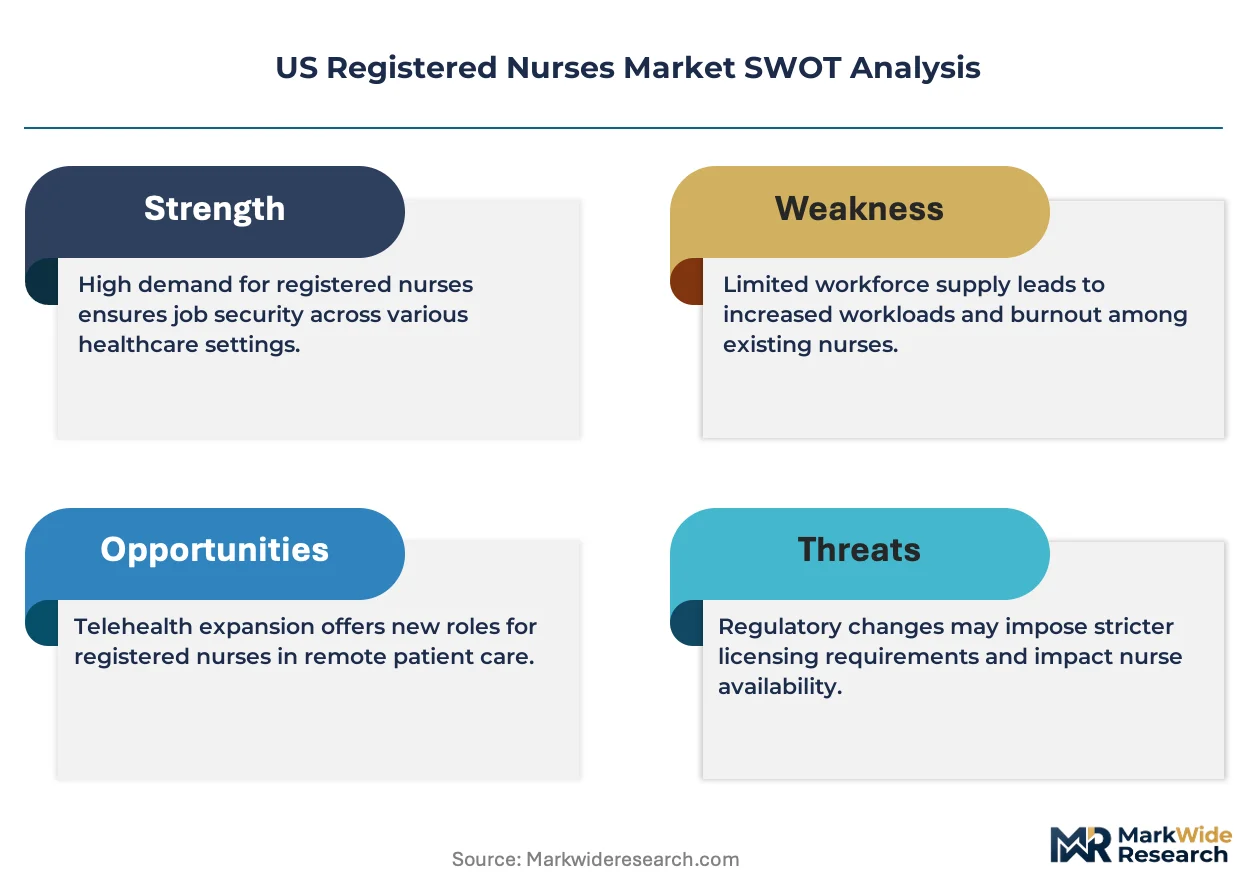
A registered nurse constitutes a licensed healthcare practitioner who completes accredited nursing education, passes the National Council Licensure Examination, and maintains state board certification to deliver patient care, administer treatments, and coordinate clinical services across acute and community settings. The profession requires ongoing clinical competency validation through continuing education units and specialized credentialing for advanced practice roles. Inpatient care remains the dominant service type by revenue commitment, though telehealth nursing expands fastest as remote patient monitoring protocols mature and reimbursement codes stabilize. Critical care specialization commands premium placement rates due to certification scarcity and high-stakes clinical environments, while geriatrics deepens its talent pool as the US population ages.
Federal oversight from CMS shapes payment structures that directly determine hospital staffing budgets, while state boards of nursing enforce licensure mobility frameworks under the Nurse Licensure Compact. OSHA workplace safety standards and HIPAA privacy requirements constrain how staffing platforms deploy personnel and manage patient data access. Stakeholders must monitor evolving interstate licensure reciprocity and emerging AI governance standards that could redefine scope-of-practice boundaries and liability allocation in contingent workforce models.
Market Dynamics
Medicare reimbursement rules are pivoting hospital staffing models toward value-based care, forcing acute care facilities to redistribute nursing hours across inpatient and community settings while home healthcare agencies absorb the workforce expansion.
Growth Catalysts
- CMS Value-Based Purchasing:Medicare reimbursement incentives now reward reduced readmission rates, compelling hospitals to invest in transitional care nursing teams that bridge acute and post-acute settings.
- Texas Demographic Pressure:Rapid population aging in Dallas-Fort Worth and Houston corridors strains hospital capacity, generating sustained demand for critical care and geriatric specialization.
- AI Scheduling Platforms:Predictive workforce management tools optimize shift allocation across health systems, reducing vacancy periods and improving nurse utilization rates.
Market Restraints
- Nurse Educator Shortage:Limited clinical faculty capacity constrains annual nursing school graduations, creating a structural bottleneck in new license issuance that lags behind replacement demand.
- California Licensing Friction:Non-Compact state status creates interstate mobility barriers, forcing staffing agencies to maintain redundant credential verification processes for cross-border deployments.
- Compensation Compression:Travel nursing rate normalization after pandemic surge pricing reduces margin flexibility for contingent workforce platforms serving mid-tier community hospitals.
Strategic Opportunities
- Telehealth Protocol Maturation:Stabilized CPT reimbursement codes for remote patient monitoring enable licensed nurses to manage chronic conditions across state lines under Compact licensure frameworks.
- Florida Retirement Migration:Concentrated aging inflows to the Villages and Sarasota-Bradenton corridor create localized demand surges for home health and hospice nursing specialization.
- Nurse Licensure Compact Expansion:Pending state adoptions of mutual recognition agreements would unlock cross-border staffing liquidity for multi-state health systems and travel nursing platforms.
Industry Challenges
- Clinical Competency Validation:Continuing education unit requirements vary across 50 state boards, forcing staffing platforms to maintain fragmented compliance tracking systems.
- Legacy ERP Integration:Hospital information systems built on outdated architectures resist real-time data exchange with modern vendor management systems, delaying credential verification workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Registered Nurses Market |
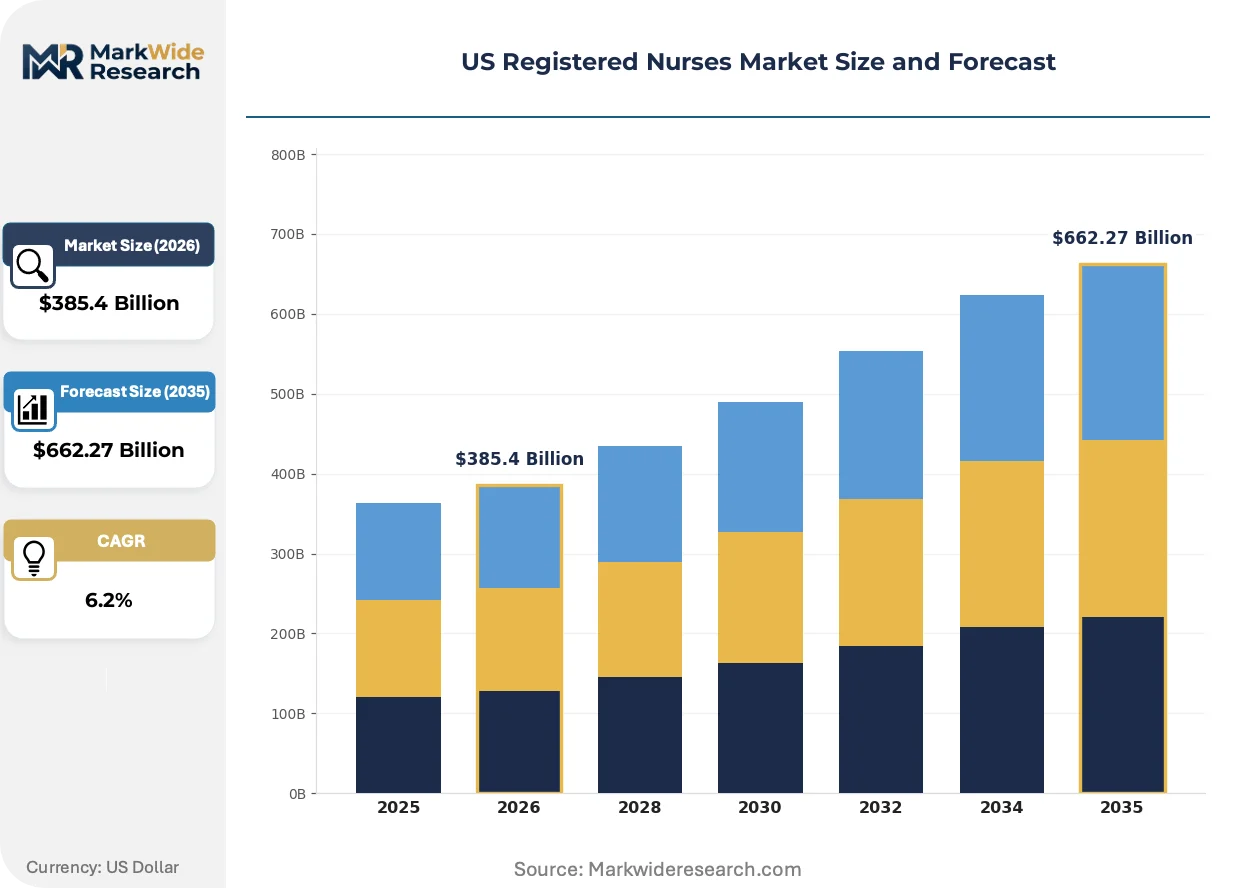
| Market Size in 2026 | $385.4 Billion |
| Market Size in 2035 | $662.27 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Inpatient Care, Outpatient Care, Home Healthcare, Telehealth Specialization: Critical Care, Emergency Medicine, Pediatrics, Geriatrics Practice Setting: Hospitals, Clinics, Nursing Homes, Community Health Centers Certification Level: RN, BSN, MSN, NP |
| Companies Covered | Amergis, Axis Medical Staffing, Aya Healthcare, Fastaff, Host Healthcare, AMN Healthcare, Travel Nurses Inc., HealthTrust, Advantis Medical, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Registered Nurses Market Strategic Shifts & Innovations
Workforce deployment models are fragmenting across subscription platforms, rapid-response strike teams, and embedded vendor management systems that compete for hospital procurement budgets.
AI-driven scheduling algorithms are rewriting how nursing hours get allocated across emergency departments, surgical units, and step-down facilities. Academic medical centers in California and Texas are piloting predictive staffing tools that match patient acuity scores to certification levels. The technology is compressing reliance on last-minute overtime premiums and external agency markup.
OSHA workplace safety standards for healthcare violence prevention are tightening documentation requirements for incident reporting and staffing ratios in high-risk units. Hospital systems must now maintain granular records of nurse-patient interactions in behavioral health and emergency settings. California and New York facilities face the steepest compliance burdens as state-level mandates exceed federal baselines.
Subscription-based talent procurement is displacing transactional per-diem contracts as the dominant staffing channel for integrated delivery networks. Health systems in Florida and Arizona are bundling credential verification, scheduling optimization, and compliance tracking into recurring annual contracts. The shift is most visible among faith-based hospital networks seeking workforce stability over cost minimization.
US Registered Nurses Market Segmentation
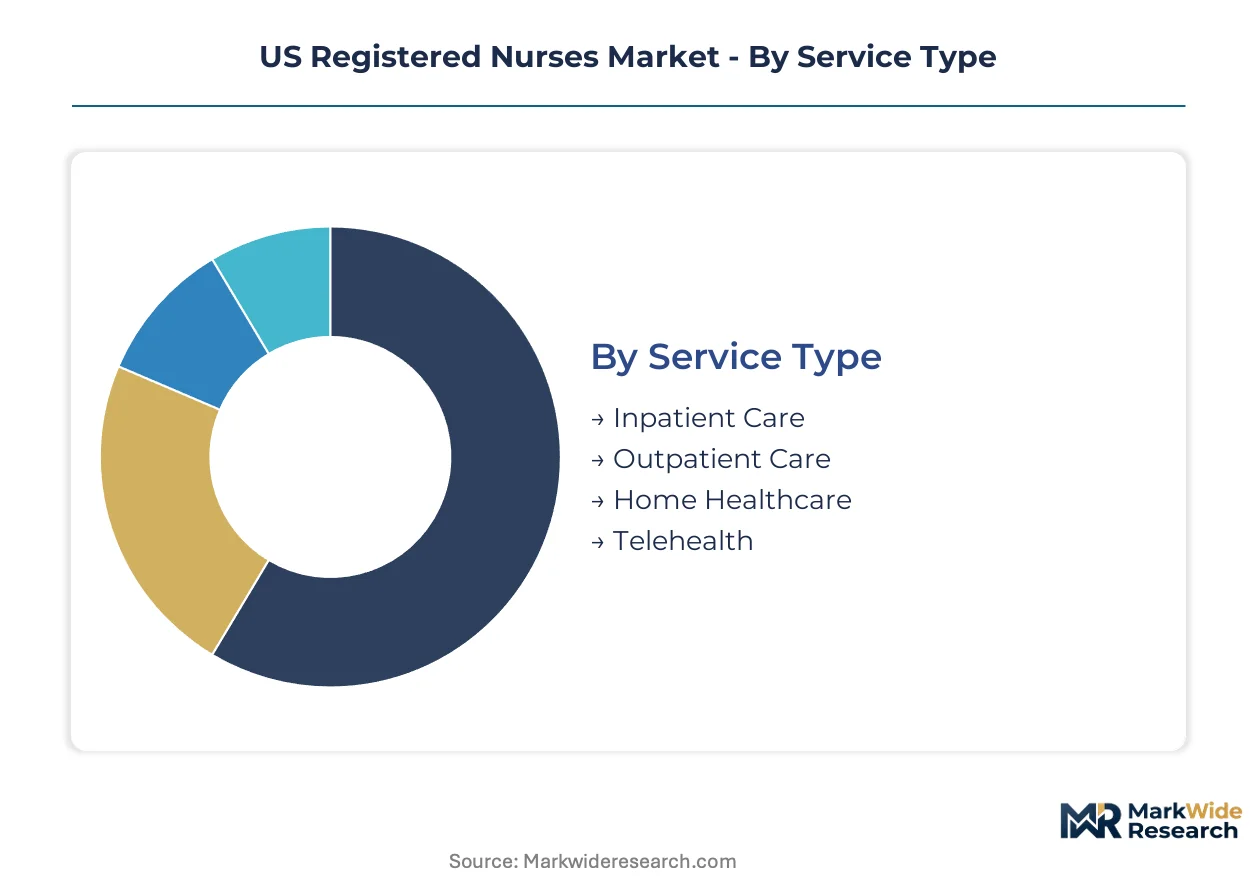
Service type and specialization splits determine where staffing platforms deploy premium versus commodity pricing. Certification tiers create parallel labor markets with distinct mobility constraints and reimbursement eligibility.
Service Type:
Volume concentration favors bedside acute care, while premium rates attach to distributed and remote delivery models.
- Inpatient Care:Continuous bedside monitoring across medical-surgical units, ICUs, and step-down floors absorbs the majority of hospital staffing budgets. Texas and California health systems concentrate replacement hiring here due to aging demographics and surgical volume expansion.
- Home Healthcare:Skilled nursing visits for wound care, infusion therapy, and post-acute monitoring command placement premiums under Medicare's value-based purchasing incentives. CMS reimbursement rule shifts are accelerating workforce migration from facilities to community settings.
- Outpatient Care:Ambulatory surgery centers and specialty clinics require rapid-turnover nursing protocols for same-day procedures.
- Telehealth:Remote patient monitoring and chronic disease management via video and asynchronous platforms.
Mature deployment sits with Inpatient Care. Newer deployment is concentrated in Telehealth.
Specialization:
Certification scarcity drives rate stratification, with life-support credentials commanding sustained premiums over generalist licenses.
- Critical Care:CCRN-certified nurses manage ventilator-dependent patients, hemodynamic monitoring, and vasoactive titration in ICUs and cardiac units. Academic medical centers in Houston and Dallas sustain exclusive contracts for this specialization due to trauma volume and transplant programs.
- Geriatrics:GNP and geriatric-certified RNs coordinate polypharmacy management, fall prevention, and advance care planning. Florida's retirement migration corridors generate localized demand surges exceeding national replacement rates.
- Emergency Medicine:CEN-certified nurses triage trauma, cardiac, and behavioral health presentations across ED throughput.
- Pediatrics:CPN-certified practitioners deliver family-centered care across neonatal, oncology, and chronic disease populations.
Critical Care anchors premium pricing tiers. Geriatrics is expanding most quickly as demographic weight shifts.
Practice Setting:
Facility ownership structure determines procurement channel selection, with integrated networks favoring subscription platforms over transactional agencies.
- Hospitals:Acute care facilities with emergency departments, surgical suites, and intensive care units maintain the largest absolute headcounts. California's non-Compact licensure status forces redundant credential verification for interstate staffing.
- Nursing Homes:Skilled nursing facilities and long-term care centers face CMS staffing minimum mandates.
- Clinics:Physician-owned and hospital-affiliated outpatient sites require flexible per-diem coverage.
- Community Health Centers:Federally qualified health centers serving underserved populations rely on National Health Service Corps loan repayment incentives.
Hospitals dominate legacy staffing relationships. Community Health Centers represent the steepest expansion trajectory for mission-aligned recruitment.
Certification Level:
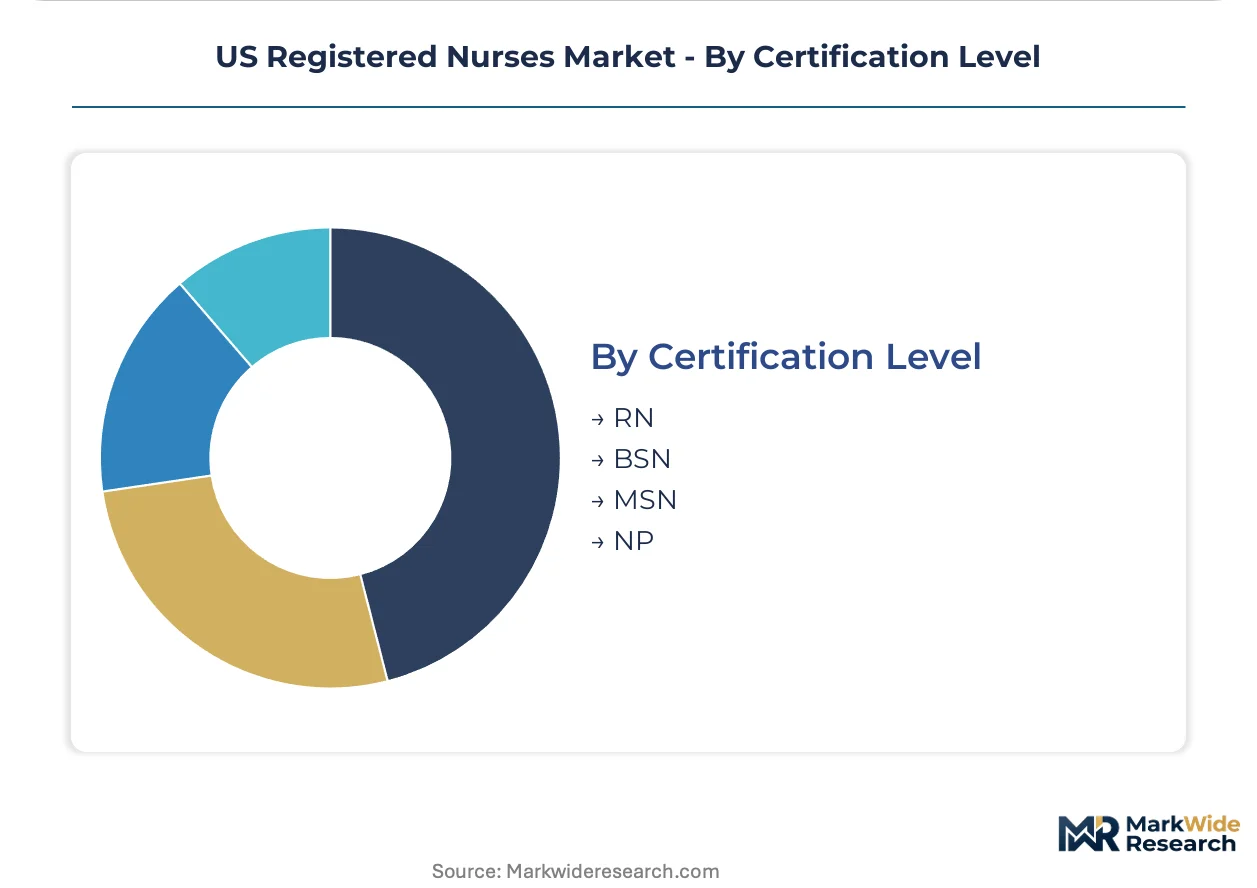
Educational attainment creates scope-of-practice boundaries that segment prescriptive authority and reimbursement eligibility.
- RN:Associate or diploma-prepared licensed nurses deliver direct patient care, medication administration, and care coordination across all settings. Texas and Florida health systems bulk-hire at this tier for medical-surgical backfill.
- NP:Doctorally or master's-prepared advanced practice nurses with independent prescriptive authority in full-practice states. Rural health clinics and retail health settings deploy NPs to extend physician capacity under collaborative agreements.
- BSN:Baccalaureate-prepared nurses with leadership and evidence-based practice training.
- MSN:Master's-prepared nurses specializing in administration, education, or clinical nurse leader roles.
RN licensure constitutes the volume base. NP scope expansion is gaining share fastest as states adopt full-practice authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Houston's Texas Medical Center anchors the nation's largest nursing labor pool, with the Dallas-Fort Worth corridor and Greater Boston's hospital cluster following as concentration nodes.
Texas
Dallas-Fort Worth and Houston corridors generate sustained demand for critical care and geriatric specialization as rapid population aging strains hospital capacity. CMS value-based purchasing incentives reward reduced readmission rates, compelling investment in transitional care nursing teams. The Texas Medical Center in Houston sustains exclusive contracts for CCRN-certified nurses due to trauma volume and transplant programs.
California
Academic medical centers in Los Angeles and the San Francisco Bay Area pilot predictive staffing tools matching patient acuity scores to certification levels. Non-Compact state status creates interstate mobility barriers, forcing staffing agencies to maintain redundant credential verification processes. Kaiser Permanente's integrated networks in Southern California bundle credential verification into recurring annual contracts.
Florida
The Villages and Sarasota-Bradenton corridor experience concentrated aging inflows creating localized demand surges for home health and hospice nursing specialization. Faith-based hospital networks seek workforce stability through subscription-based talent procurement over cost minimization. Tampa General Hospital and Moffitt Cancer Center anchor premium placement rates for oncology-certified RNs.
New York Metro
Behavioral health and emergency departments face steep compliance burdens as state-level mandates exceed federal OSHA baselines for healthcare violence prevention. Continuing education unit requirements vary across state boards, forcing fragmented compliance tracking systems. NewYork-Presbyterian and Mount Sinai Health System maintain granular records of nurse-patient interactions in high-risk units.
Illinois
Chicago's academic medical centers absorb the majority of hospital staffing budgets for medical-surgical backfill as surgical volume expands. The Nurse Licensure Compact enables cross-border staffing liquidity for multi-state health systems operating across the Midwest. Northwestern Medicine and Rush University Medical Center concentrate replacement hiring for associate-prepared licensed nurses.
US Registered Nurses Market Key Industry Players
Capital-heavy staffing platforms with proprietary vendor management systems compete with asset-light rapid-response agencies for hospital procurement budgets. The market structure fragments across subscription-based workforce management, embedded ERP integration, and transactional per-diem contracts. Three archetypes dominate: integrated delivery network partners, geographic density specialists, and crisis surge deployment firms. Consolidation pressures favor multi-state platforms with direct hospital ERP infrastructure, while mid-tier agencies defend position through strike coverage exclusivity and guaranteed arrival windows.
Within the integrated delivery network tier, AMN Healthcare anchors market presence through proprietary vendor management systems, while Aya Healthcare competes on geographic density sustaining exclusive relationships with academic medical centers. Fastaff occupies the rapid-response archetype specializing in strike coverage with guaranteed arrival windows. These three exemplify how scale, technology integration, and speed-to-deployment segment competitive positioning across procurement channels.
| Leading Market Players |
|---|
| Amergis |
| Axis Medical Staffing |
| Aya Healthcare |
| Fastaff |
| Host Healthcare |
| AMN Healthcare |
| Travel Nurses Inc. |
| HealthTrust |
| Advantis Medical |
| Others |
Cost & Logistics Intelligence
Healthcare labor cost indices cascade through staffing platforms into rate stratification, with contingent workforce markups compressing as hospital procurement shifts from transactional per-diem to subscription-based vendor management systems. CMS reimbursement benchmarks tether pricing power to value-based purchasing outcomes, forcing agencies to absorb credential verification costs within recurring contract structures rather than pass-through fees.
Pricing Analysis
Margin tightening in travel nursing reflects pandemic surge pricing normalization and hospital budget consolidation. Three-tier pricing structure across premium certification, standard licensure, and economy backfill tiers segments buyer willingness-to-pay. Cost-down pressure on rapid-response deployments accelerates because strike coverage exclusivity commands guaranteed arrival premiums. Community hospitals exhibit highest price sensitivity; academic medical centers anchored by transplant and trauma programs demonstrate lowest.
Supply Chain Analysis
Single-source vulnerability sits with nursing school clinical faculty capacity constraining annual license issuance. Geographic supply concentration clusters in Texas, Florida, and California where aging demographics strain replacement hiring. Raw material dependencies rest on NCLEX examination slots, state board processing bandwidth, and continuing education unit providers. Regulatory restriction risk emerges from California's non-Compact status forcing redundant credential verification. Distribution runs through proprietary vendor management systems integrating directly with hospital ERP infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure intensifies as AI scheduling platforms and subscription procurement models squeeze mid-tier agencies lacking direct hospital ERP integration or geographic density.
For Market Incumbents: Anticipate margin compression from predictive workforce tools by deepening proprietary vendor management system penetration and securing exclusive strike coverage contracts. Anchor defensive positioning through multi-year subscription agreements with faith-based hospital networks seeking workforce stability over cost minimization. For New Entrants and Emerging Players: Rural health clinics and federally qualified health centers represent underserved buyer archetypes with mission-aligned recruitment needs and National Health Service Corps loan repayment leverage. Penetrate telehealth nursing protocols maturing under stabilized CPT reimbursement codes. Deploy compact-licensure mobility as go-to-market wedge against incumbents burdened by California verification redundancy. For Investors and Strategic Acquirers: Distressed-cycle entries favor rapid-response deployment specialists with guaranteed arrival window capabilities in Texas and Florida corridor markets. Long-term viability hinges on AI governance standards reshaping scope-of-practice boundaries and liability allocation. Monitor Nurse Licensure Compact expansion adoptions as inflection signal unlocking cross-border staffing liquidity.| Strategic Initiative | Industry Significance |
|---|---|
| AI Scheduling Platform Integration | Predictive tools matching patient acuity scores to certification levels compress overtime premiums at Houston's Texas Medical Center. |
| Nurse Licensure Compact Expansion | Pending state adoptions unlock cross-border staffing liquidity for multi-state health systems operating across Midwest corridors. |
| Subscription-Based Talent Procurement | Recurring annual contracts bundle credential verification and compliance tracking for Florida faith-based hospital networks. |
| Telehealth Protocol Maturation | Stabilized CPT reimbursement codes enable licensed nurses to manage chronic conditions across state lines under Compact frameworks. |
| Critical Care Certification Investment | CCRN scarcity commands sustained placement premiums at academic medical centers with trauma volume and transplant programs. |
Research Approach
Document review covered CMS reimbursement rulemaking, state board of nursing licensure data, and OSHA workplace safety standards, complemented by interviews with hospital procurement directors, staffing agency operations leads, and nurse educators. Secondary validation drew from GPO contracts, hospital procurement databases, and CMS Medicare payment data. Bottom-up triangulation across service type and specialization segments informed aggregate market sizing.
Cross-referencing historical staffing deployment patterns against panel input from workforce management platform executives shaped analytical framework construction across the projection horizon. Segmentation dimensions modeled include service type, specialization, practice setting, and certification level. CAGRs derived from supply-demand gap analysis incorporating nursing school graduation rates, retirement attrition, and interstate mobility constraints.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to AI governance standards, Nurse Licensure Compact adoption timelines, and CMS value-based purchasing rule evolution. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Hair Transplant Services Market
Healthcare Services
Asia-Pacific Healthcare Cold Chain Logistics Market
Healthcare Services
Eastern Europe Online Pharmacy Market
Healthcare Services
Europe Pharmaceutical Cold Chain Logistics Market
Healthcare Services
US Hospice Market
Healthcare Services
Global Healthcare Provider Network Management Market
Healthcare Services
Hospice and Palliative Care Centers Market
Healthcare Services
Europe Pharmaceutical Logistics Market
Healthcare Services
Care Services Market
Healthcare Services
US Value-Based Healthcare Service Market
Healthcare Services
Per Diem Nurse Staffing Market
Healthcare Services
Health Care Supply Chain Management Market
Healthcare Services
Healthcare Physician Staffing Market
Healthcare Services
North America Healthcare Cold Chain Logistics Market
Healthcare Services
Global Pharmaceutical Contract Sales Outsourcing (CSO) Market
Healthcare Services
US Care Services Market