
 Ambulatory Surgical Centers IT Services Market | 2026-2036
Ambulatory Surgical Centers IT Services Market Size, Share, and Industry Trends Forecast 2026-2036
Ambulatory Surgical Centers IT Services Market Intelligence
Multi-specialty ASC chains are redrawing procurement priorities across the IT services landscape, pulling vendor roadmaps toward integrated perioperative platforms. Cerner Corporation leverages its acute-care heritage to anchor enterprise contracts that span hospital outpatient departments and affiliated ASCs. Epic Systems Corporation sustains dominance in physician-owned networks through deep EHR interoperability with hospital systems. NextGen Healthcare competes on ambulatory-specific workflow specialization that reduces administrative burden for smaller ASC operators.
Ambulatory Surgical Centers IT Services encompass the software, infrastructure, and managed services that automate clinical documentation, revenue capture, and operational coordination in same-day surgical facilities, typically requiring HIPAA-compliant data architectures with sub-second latency for real-time scheduling synchronization. Electronic Health Records and Revenue Cycle Management represent the most mature revenue pools, though margin expansion is concentrating in Telehealth Solutions and AI-driven analytics modules that reduce no-show rates and optimize block-time utilization. Cloud Computing deployments now outpace On-Premises installations among de novo ASCs, while Cybersecurity Solutions command premium pricing as breach liability shifts to facility operators under evolving state privacy laws.
FDA oversight of clinical decision support algorithms and HIPAA enforcement by the Office for Civil Rights directly shape product development timelines and liability structures for ASC IT vendors. State-level certificate-of-need regulations and CMS Conditions for Coverage create fragmented compliance requirements that favor vendors with modular, jurisdictionally adaptive platforms. Stakeholders must monitor how ONC interoperability rulemaking redefines data exchange obligations between ASCs and referring hospitals.
Market Dynamics
Federal interoperability mandates under the 21st Century Cures Act are compressing procurement cycles for ASC IT vendors, forcing modular platform architectures that bridge acute-care and ambulatory environments.
Growth Catalysts
- CMS Conditions for Coverage:Tightening documentation requirements for reimbursement eligibility are compelling multi-specialty ASC chains to expand IT budgets for integrated perioperative platforms.
- Cloud Computing:De novo ASCs are abandoning on-premises infrastructure in favor of HIPAA-compliant cloud deployments that reduce capital expenditure and accelerate implementation timelines.
- AI-powered surgical scheduling:Machine learning modules that optimize block-time utilization and reduce no-show rates are pulling demand from physician-owned networks seeking operational efficiency gains.
Market Restraints
- Cybersecurity liability concentration:State privacy laws are shifting breach liability directly to facility operators, forcing premium pricing for endpoint protection and incident response services that strain smaller ASC budgets.
- Certificate-of-need fragmentation:Jurisdictionally variable CON regulations create compliance complexity that favors vendors with adaptive platforms but disadvantages modular specialists lacking legal resources.
- Interoperability implementation costs:ONC data exchange obligations between ASCs and referring hospitals require expensive interface engines and custom mapping that delay ROI realization.
Strategic Opportunities
- Telehealth Solutions:Remote pre-operative assessment and post-discharge monitoring modules represent underpenetrated revenue pools with margin expansion potential for vendors with FDA-cleared digital health platforms.
- AI-driven analytics convergence:Integration of predictive scheduling algorithms with revenue cycle management workflows creates white space for vendors bridging operational and financial data silos.
- State Medicaid expansion:Coverage expansion in select states is generating demand for IT infrastructure among ASCs previously excluded from managed care networks.
Industry Challenges
- Health informatics talent scarcity:ASCs face acute shortages of analysts capable of configuring HL7 FHIR interfaces and managing API governance for hospital system connectivity.
- Legacy EHR migration friction:Physician-owned single-specialty operators struggle with data extraction and workflow reengineering when transitioning from aging practice management systems.
- FDA algorithm validation timelines:Clinical decision support tools face extended 510(k) review cycles that compress vendor cash flows and delay commercialization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ambulatory Surgical Centers IT Services Market |
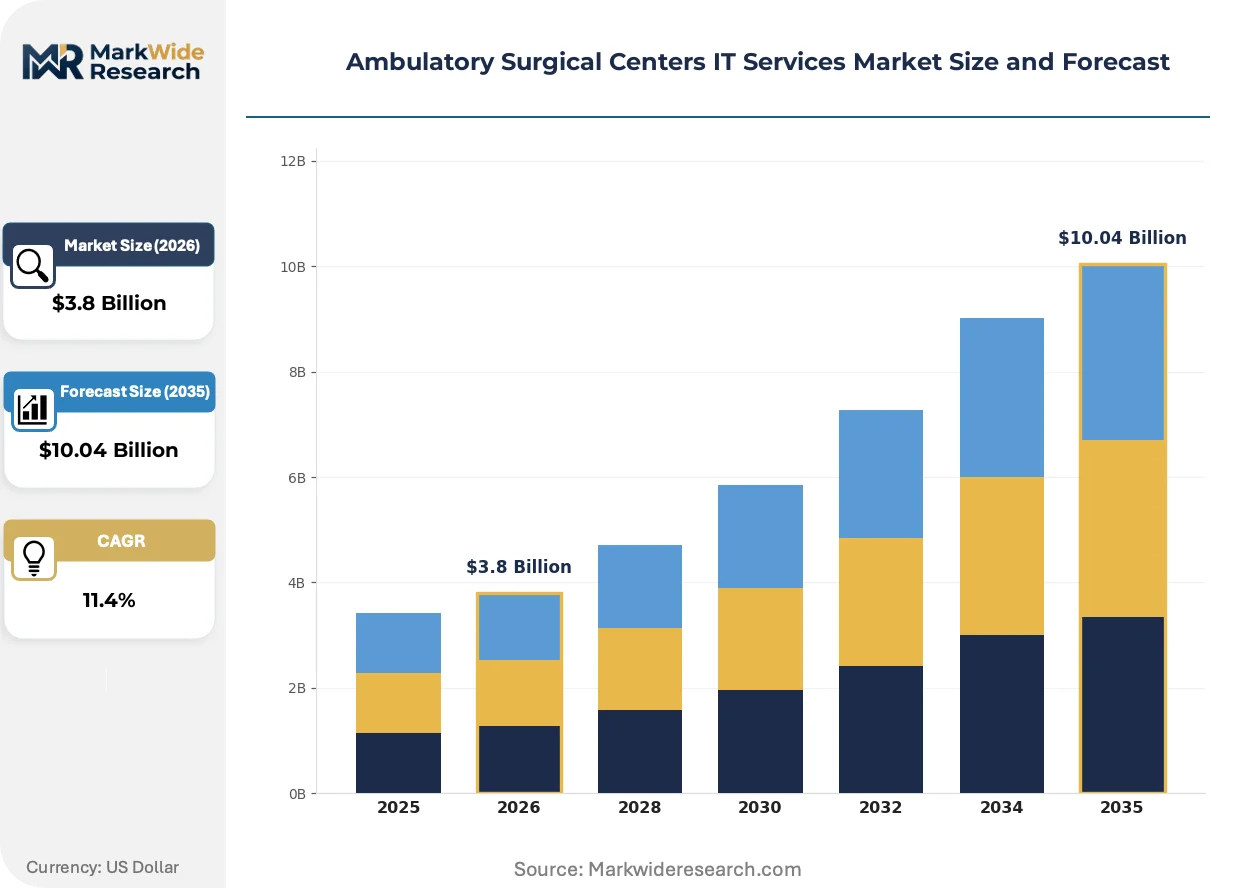
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Practice Management, Electronic Health Records, Revenue Cycle Management, Telehealth Solutions Technology: Cloud Computing, Data Analytics, Artificial Intelligence, Cybersecurity Solutions End User: Physicians, Administrative Staff, IT Professionals, Healthcare Administrators Deployment Model: On-Premises, SaaS, Hybrid, Mobile Solutions |
| Companies Covered | Cerner Corporation, Allscripts Healthcare Solutions, McKesson Corporation, NextGen Healthcare, Epic Systems Corporation, Surgical Information Systems, eClinical Works, Athenahealth, Medical Information Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ambulatory Surgical Centers IT Services Market Strategic Shifts & Innovations
Real-time data synchronization architectures are displacing batch-processing legacy systems across ambulatory surgical environments, compressing latency requirements and reshaping vendor competitive positioning.
Edge computing infrastructure is miniaturizing perioperative data capture at the point of care. Single-specialty ASCs in rural markets are deploying compact surgical documentation appliances that eliminate dependency on hospital data centers. This technology is miniaturizing the physical and economic footprint required for enterprise-grade interoperability.
The Office for Civil Rights is intensifying HIPAA enforcement against business associates serving ASCs, extracting multi-million dollar settlements for encryption failures. Vendors are responding by embedding zero-trust architectures into practice management platforms. Cybersecurity compliance is now the primary procurement filter for mid-sized ASC chains evaluating new IT contracts.
Subscription-based managed services are displacing perpetual license models as the dominant procurement mechanism. Physician-owned networks favor all-inclusive per-procedure pricing that bundles software, infrastructure, and compliance support. This shift is most visible in the southeastern United States, where private equity-backed ASC roll-ups are standardizing vendor relationships across facility portfolios.
Ambulatory Surgical Centers IT Services Market Segmentation
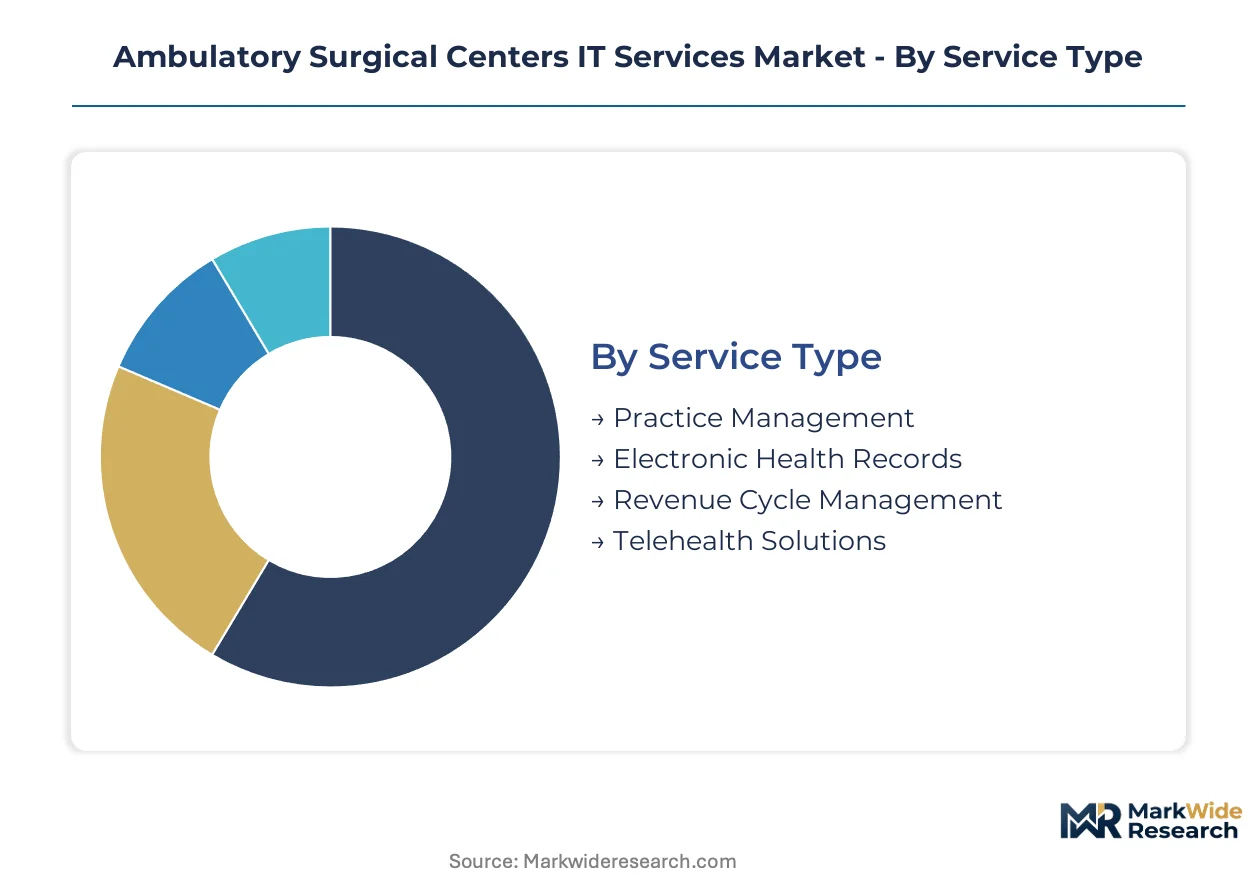
ASC IT procurement splits sharply between integrated enterprise suites and modular point solutions. Channel strategy determines which segments dominate facility budgets.
Service Type:
Direct sales teams capture large multi-specialty chains for core platforms, while value-added resellers penetrate smaller physician-owned networks.
- Practice Management:Scheduling, billing, and operational workflow automation form the foundational layer of ASC technology stacks. Demand concentrates in southeastern United States private equity roll-ups standardizing vendor relationships across facility portfolios, driven by subscription-based managed services displacing perpetual licenses.
- Electronic Health Records:Clinical documentation systems with perioperative templates and anesthesia integration dominate procurement cycles. Physician-owned networks in the United States prioritize deep interoperability with referring hospital systems, compelled by ONC data exchange mandates under the 21st Century Cures Act.
- Revenue Cycle Management:Claims processing and denial management modules with CMS documentation compliance features.
- Telehealth Solutions:Remote pre-operative assessment and post-discharge monitoring platforms with FDA-cleared digital health pathways.
Electronic Health Records dominates installed base. Telehealth Solutions is where expansion concentrates.
Technology:
Margin profiles diverge sharply between commodity infrastructure and premium intelligence layers.
- Cloud Computing:HIPAA-compliant multi-tenant architectures with sub-second latency for real-time scheduling synchronization. De novo ASCs in the United States abandon on-premises infrastructure, reducing capital expenditure and accelerating implementation timelines.
- Artificial Intelligence:Machine learning modules optimizing block-time utilization and predicting no-show rates. Multi-specialty chains in the United States deploy predictive scheduling algorithms, extracting operational efficiency gains from perioperative data.
- Data Analytics:Business intelligence dashboards consolidating operational and financial performance metrics.
- Cybersecurity Solutions:Zero-trust architectures and endpoint protection responding to OCR HIPAA enforcement against business associates.
Cloud Computing anchors current spending. Artificial Intelligence commands the steepest expansion trajectory.
End User:
Workflow complexity and technical sophistication determine purchasing authority distribution.
- Healthcare Administrators:C-suite executives controlling capital allocation for enterprise-wide platform decisions. Multi-specialty ASC chains in the United States expand IT budgets fastest, responding to tightening CMS reimbursement documentation requirements.
- Physicians:Surgeon-owners driving EHR selection based on interoperability with hospital admitting privileges. Single-specialty operators in the United States struggle with legacy migration friction when transitioning from aging practice management systems.
- Administrative Staff:Front-desk and billing personnel consuming practice management interfaces daily.
- IT Professionals:Technical staff configuring HL7 FHIR interfaces and managing API governance for hospital connectivity.
Healthcare Administrators control budget authority. Physicians drive clinical workflow requirements.
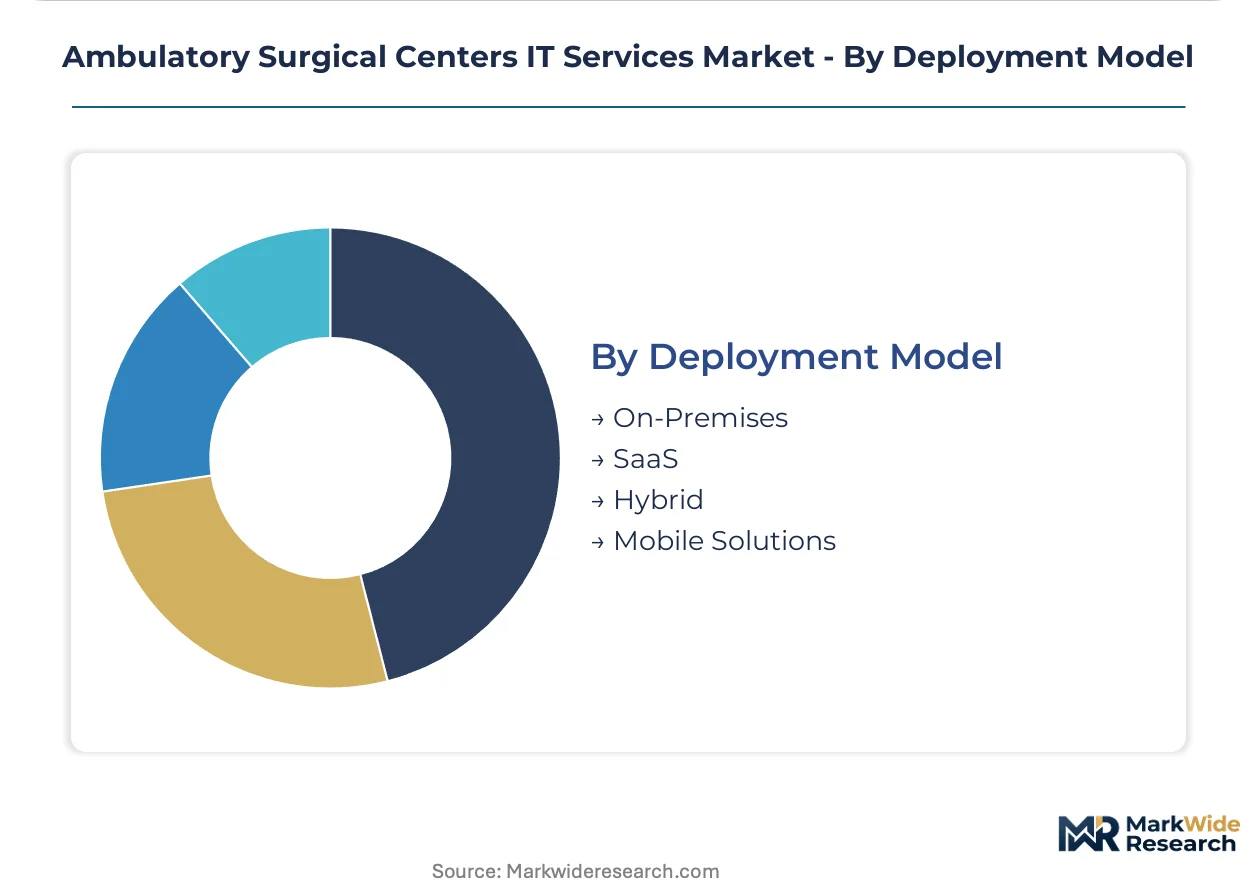
Deployment Model:
Capital availability and risk tolerance shape infrastructure preferences across facility types.
- SaaS:Subscription-based delivery eliminating server maintenance and compliance overhead. De novo ASCs in the United States favor all-inclusive per-procedure pricing bundling software, infrastructure, and compliance support.
- Hybrid:Split architectures keeping sensitive data on-premises while leveraging cloud scalability for non-critical workloads. Mid-sized chains in the United States deploy edge computing appliances for perioperative data capture without hospital data center dependency.
- On-Premises:Legacy server installations retained by established facilities with sunk infrastructure investments.
- Mobile Solutions:Tablet and smartphone interfaces for bedside documentation and remote monitoring.
On-Premises retains legacy footprint. SaaS is gaining share fastest among new entrants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based IT vendors export cloud-based perioperative platforms to Canadian and Mexican ASC chains, while European buyers source AI scheduling modules from American developers. Federal interoperability mandates in North America accelerate cross-border procurement standardization.
United States
Multi-specialty ASC chains in Texas and Florida expand IT budgets fastest under tightening CMS Conditions for Coverage. The 21st Century Cures Act drives ONC interoperability rulemaking that reshapes data exchange obligations between ambulatory facilities and referring hospitals. Nashville hosts concentrated vendor development activity for revenue cycle management platforms serving southeastern private equity roll-ups.
Germany
Outpatient surgical clinics in Bavaria and North Rhine-Westphalia adopt cloud-based practice management systems to meet EU MDR documentation requirements. The Bundesamt für Sicherheit in der Informationstechnik enforces healthcare cybersecurity standards that elevate procurement filters for zero-trust architectures. Berlin anchors startup development of AI-driven surgical scheduling tools targeting mid-sized clinic chains.
United Kingdom
NHS England's push toward independent sector treatment centers generates demand for integrated EHR platforms in Greater London and the Midlands. The Care Quality Commission inspects IT governance as part of facility licensing, compelling investment in audit-ready documentation systems. Manchester clusters health informatics talent configuring HL7 FHIR interfaces for hospital-ASC connectivity.
Japan
Aging demographics drive ASC IT adoption in Osaka and Nagoya metropolitan areas seeking operational efficiency gains. The Ministry of Health, Labour and Welfare promotes digital health infrastructure subsidies that accelerate cloud migration among physician-owned surgical clinics. Tokyo concentrates vendor partnerships between domestic system integrators and American platform providers.
Australia
Private day surgery facilities in New South Wales and Victoria deploy telehealth modules for remote pre-operative assessment. The Therapeutic Goods Administration regulates clinical decision support algorithms, extending validation timelines for AI-powered scheduling tools. Sydney hosts regional headquarters for multinational vendors targeting Asia-Pacific ambulatory expansion.
Ambulatory Surgical Centers IT Services Market Key Industry Players
Listed leaders compete with private specialists across platform integration depth, with public companies anchoring enterprise contracts while physician-owned networks favor agile workflow specialists. The vendor base stratifies into three tiers: acute-care heritage platforms, ambulatory-native specialists, and cloud-native challengers. Dominant competitive moves include M&A roll-ups consolidating regional resellers and strategic partnerships bridging EHR interoperability gaps.
Within the acute-care heritage tier, Cerner Corporation and Epic Systems Corporation occupy positions leveraging hospital system relationships to capture affiliated ASC contracts. NextGen Healthcare exemplifies the ambulatory-native archetype, sitting within the workflow specialization segment that targets smaller operator administrative burden reduction.
| Leading Market Players |
|---|
| Cerner Corporation |
| Allscripts Healthcare Solutions |
| McKesson Corporation |
| NextGen Healthcare |
| Epic Systems Corporation |
| Surgical Information Systems |
| eClinical Works |
| Athenahealth |
| Medical Information Technology |
| Others |
Cost & Logistics Intelligence
HIPAA enforcement actions by the Office for Civil Rights gate both vendor qualification and price differentiation simultaneously, embedding compliance architecture costs into platform tiers while elevating zero-trust security modules to premium positioning. Subscription-based managed services now dominate procurement, with per-procedure bundling compressing upfront capital requirements and flattening price curves across facility portfolios.
Pricing Analysis
Next-generation AI-powered surgical scheduling modules command substantial premiums over legacy batch-processing systems, while current-generation cloud-based practice management platforms occupy the mid-market sweet spot. Pricing stratifies across enterprise-grade interoperability suites, standard HIPAA-compliant cloud deployments, and economy-tier modular point solutions, with differentiation driven by FHIR interface certification depth and after-sales compliance support intensity. Cost compression in the economy tier is intensifying because physician-owned single-specialty operators face acute budget constraints. Multi-specialty ASC chains exhibit the least price sensitivity due to private equity backing and scale efficiencies.
Supply Chain Analysis
Inbound logistics costs for edge computing appliances and surgical documentation hardware have stabilized following pandemic-era port congestion, though semiconductor component availability remains variable across Asian manufacturing hubs. Software development concentrates in the United States, India, and Germany, with cloud infrastructure provisioning drawing from hyperscaler data center networks in Virginia, Frankfurt, and Singapore. Raw material dependencies span silicon chips for perioperative devices, encryption modules for zero-trust architectures, and specialized displays for bedside documentation terminals. Single-source vulnerability in FHIR interface engine components poses structural risk for smaller vendors lacking diversified supplier relationships. Distribution runs through direct enterprise sales teams for large chains and value-added reseller networks for physician-owned facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment, where HIPAA compliance complexity and ONC interoperability mandates erect formidable barriers against unqualified entrants while cementing incumbent relationships through switching-cost accumulation.
For Market Incumbents: Shield enterprise contract positions by deepening vertical integration into FHIR interface engine development, eliminating third-party dependency risks that emerging cloud-native challengers exploit. Fortify against substitution threats from AI-native scheduling specialists by embedding predictive analytics modules directly into core EHR workflows, leveraging existing data architecture investments as retention leverage.
For New Entrants and Emerging Players: Anchor in the telehealth solutions segment, where FDA-cleared digital health pathways remain underpenetrated and physician-owned networks seek remote pre-operative assessment capabilities without full platform replacement. Target southeastern United States private equity roll-ups with modular, jurisdictionally adaptive compliance tools that address certificate-of-need fragmentation without requiring enterprise-scale implementation resources.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with physician-owned single-specialty operators approaching succession events, presenting consolidation opportunities for platforms with proven legacy migration tooling. Long-term viability across the analysis window hinges on interoperability depth rather than feature breadth, favoring acquisition targets with established hospital system connectivity. Monitor ONC rulemaking velocity as the critical inflection signal for vendor valuation repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| FHIR Interface Engine Development | Deep ONC interoperability compliance with hospital EHR systems anchors enterprise retention. |
| Zero-Trust Architecture Embedding | OCR HIPAA enforcement elevates cybersecurity modules to primary procurement filters. |
| AI Scheduling Module Integration | Predictive block-time optimization extracts operational efficiency gains for multi-specialty chains. |
| Per-Procedure Pricing Rollout | Subscription bundling reduces capital barriers for physician-owned network expansion. |
| Telehealth Platform Certification | FDA-cleared remote monitoring pathways open underpenetrated revenue pools in perioperative care. |
Research Approach
A standing panel of ASC operations directors, health informatics officers, GPO contracts managers, and EHR integration specialists provided ongoing calibration across the research cycle. Primary fieldwork combined structured interviews with secondary validation against CMS Medicare cost reports, ONC interoperability rulemaking dockets, hospital procurement databases, and vendor SEC disclosures. Bottom-up facility-level IT spending estimates triangulated against top-down market sizing derived from ambulatory surgery center licensing records.
Consistency checks validated volume and value outputs against external benchmarks including ambulatory surgical procedure volume trends and healthcare IT capital expenditure surveys. The analytical framework modeled segmentation across service type, deployment model, technology layer, and end-user purchasing authority throughout the forecast period. CAGRs were derived from regression analysis of historical IT budget expansion patterns and projected CMS documentation requirement tightening. Industry-specific inputs included certificate-of-need regulatory density indices and private equity roll-up transaction velocity.
Material uncertainties — ONC rulemaking delays, state-level privacy law divergence, and AI algorithm FDA validation timeline extensions — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding interoperability mandate implementation schedules and cloud migration adoption curves. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Global Dermatology EMR Software Market
Healthcare IT
IP-Based Nurse Call System Market
Healthcare IT
Metabolic Rate Analysis System Market
Healthcare IT
Commercial Pharmaceutical Analytics Market
Healthcare IT
Global Emergency Department Information System Market
Healthcare IT
Operating Room Software Market
Healthcare IT
Healthcare IT Outsourcing Market
Healthcare IT
High-Value Healthcare Asset Tracking and Recovery Platforms Market
Healthcare IT
Femtech Market
Healthcare IT
Revenue Cycle Management (RCM) Market
Healthcare IT
US Healthcare IT Market
Healthcare IT
Clinical Healthcare IT Market
Healthcare IT
Interactive Patient Care Systems Market
Healthcare IT
Global Telepharmacy Market
Healthcare IT
Europe Outpatient Software Market
Healthcare IT
Global Hospital Asset Tracking and Inventory Management Systems Market