
 Healthcare Electronic Data Interchange (EDI) Market | 2026-2036
Healthcare Electronic Data Interchange (EDI) Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare Electronic Data Interchange (EDI) Market Intelligence
North American health IT infrastructure is expanding transaction processing capacity to accommodate rising claim volumes. Optum Inc. leverages its payer-provider data connectivity to anchor large-scale eligibility verification networks. McKesson Corporation sustains dominant channel control through pharmacy benefit management integrations. Change Healthcare competes on interoperability density across clearinghouse operations.
Healthcare Electronic Data Interchange denotes the structured computer-to-computer transmission of standardized healthcare transactions using ANSI X12 or EDIFACT message formats, replacing paper-based claims, remittances, and eligibility inquiries. Cloud-based deployment leads structural momentum as health systems migrate from on-premises legacy systems to reduce capital intensity and enable API-driven interoperability. Claims management occupies the largest application segment due to persistent volume density, while payment processing represents the fastest-expanding category as real-time adjudication models displace batch-cycle legacy workflows.
US HIPAA transaction standards, enforced by CMS and overseen by OCR, mandate specific electronic formats for claims and remittances, directly shaping vendor product architecture and health plan procurement criteria. The FDA's evolving guidance on digital health data integrity intersects with EDI audit trail requirements for pharmaceutical supply chain documentation. Stakeholders must monitor whether emerging federal interoperability rules will force consolidation among regional clearinghouses or create openings for API-native platform entrants.
Market Dynamics
Cloud-based API architectures are compressing the clearinghouse layer as health systems abandon on-premises legacy stacks for real-time transaction processing.
Growth Catalysts
- HIPAA transaction mandates:CMS enforcement of standardized electronic formats for claims and remittances compels health plan technology procurement toward certified EDI platforms.
- Real-time eligibility verification:Payer-provider data connectivity networks expand transaction volume density as integrated delivery networks demand instant patient coverage confirmation.
- Pharmacy benefit management integration:Retail pharmacy chains anchor prescription claim routing through consolidated EDI gateways, driving platform consolidation.
Market Restraints
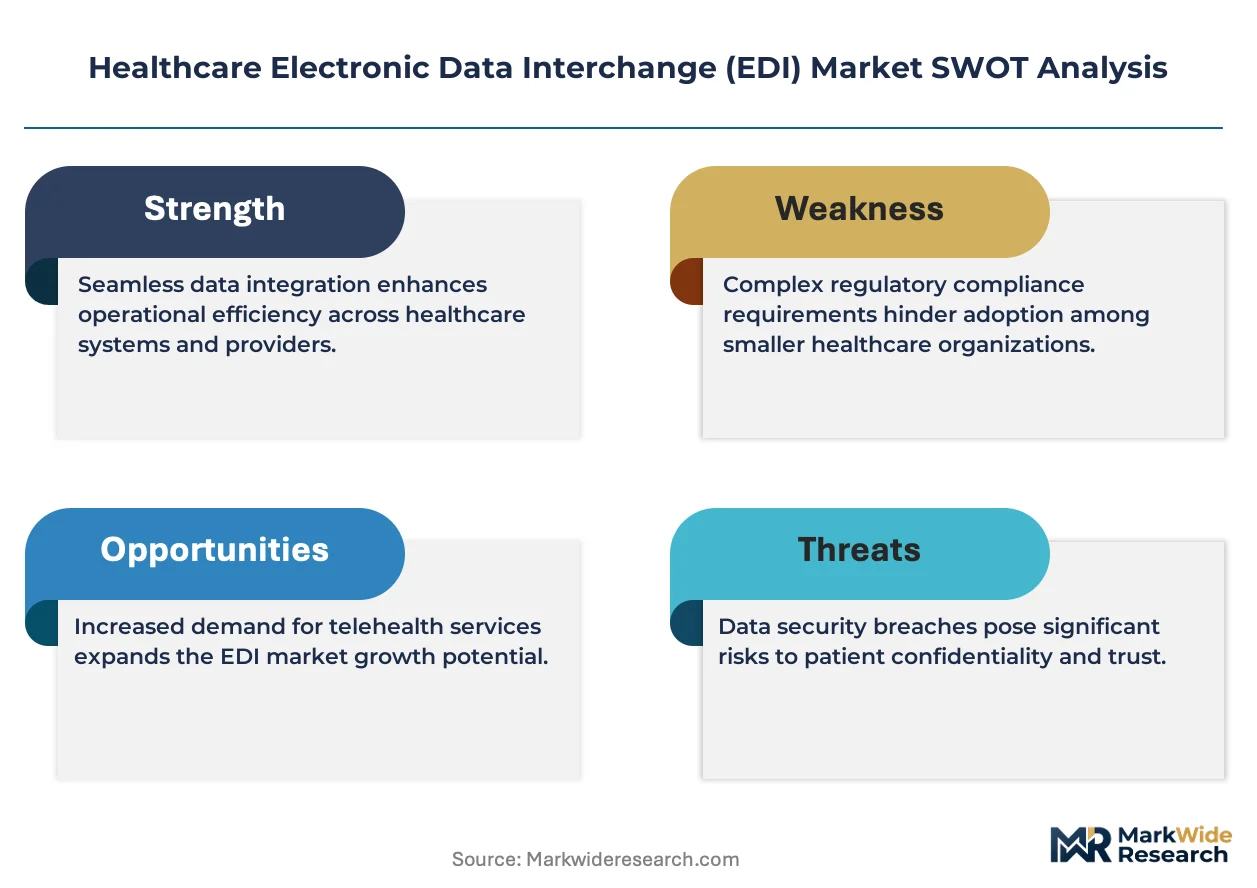
- Legacy system migration costs:Health system capital allocation constraints delay retirement of mainframe-based claims processing infrastructure.
- Clearinghouse concentration risk:Three dominant intermediaries control over 75% of US transaction routing, creating single-point-of-failure vulnerability.
- ANSI X12 version fragmentation:Inconsistent adoption of 5010 versus 6020 standards across state Medicaid programs forces dual-format maintenance.
Strategic Opportunities
- Medicaid managed care expansion:State-level privatization of Medicaid administration creates new payer EDI procurement cycles in Texas, Florida, and California.
- Prior authorization automation:FHIR API convergence with EDI workflows enables real-time medical necessity verification, reducing administrative burden.
- Value-based payment processing:Bundled payment and episode-of-care models require new remittance advice formats, opening niche vendor positioning.
Industry Challenges
- Interoperability engineer scarcity:Health IT labor markets lack sufficient talent versed in both HL7 FHIR and ANSI X12 transaction mapping.
- Multi-payer portal fatigue:Provider organizations struggle to maintain credentials and connectivity across dozens of payer-specific EDI endpoints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare Electronic Data Interchange (EDI) Market |
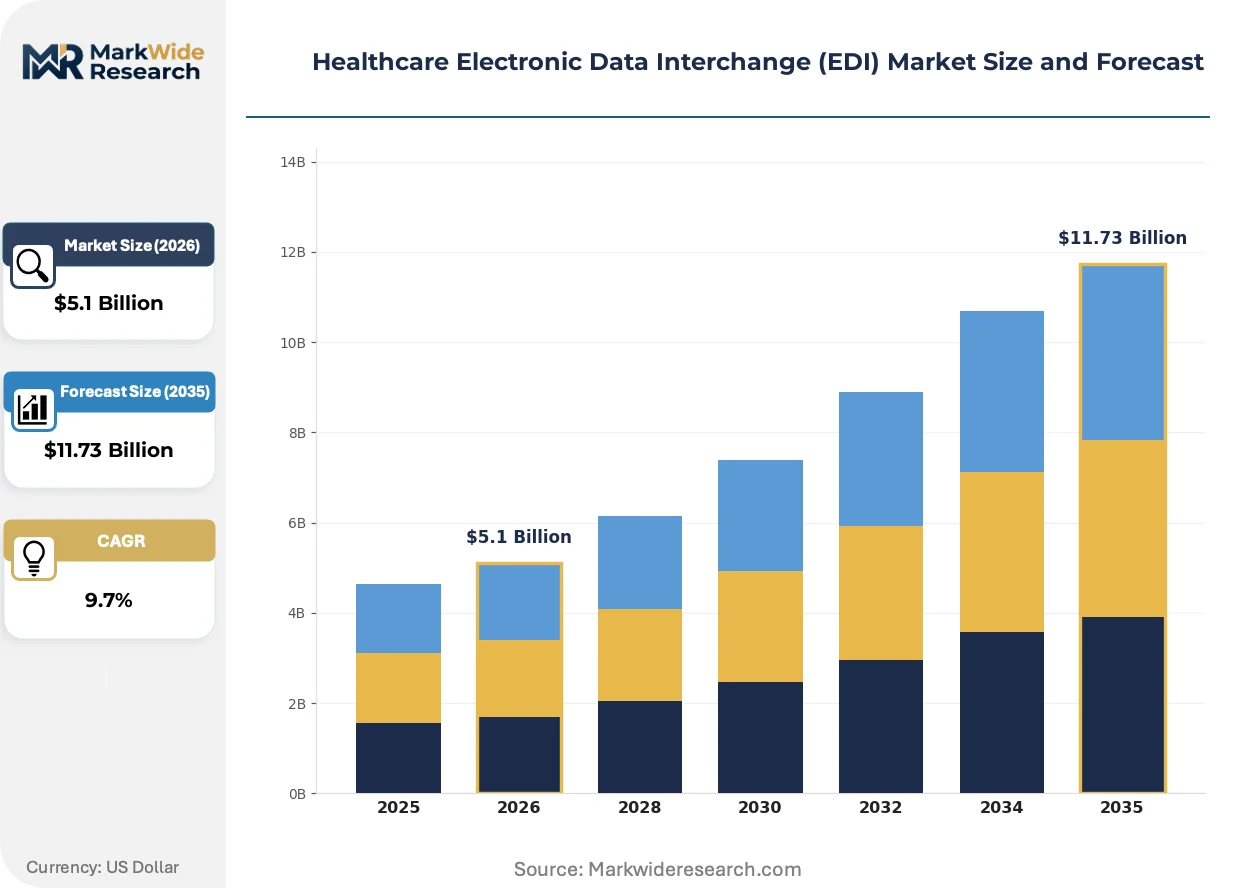
| Market Size in 2026 | $5.1 Billion |
| Market Size in 2035 | $11.73 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software Solutions, Middleware, Network Services, Compliance Tools Application: Claims Management, Eligibility Verification, Payment Processing, Referral Authorizations End User: Hospitals, Physician Practices, Pharmacy Providers, Health Plans Deployment: On-Premises, Cloud-Based, Hybrid, Managed Services |
| Companies Covered | Allscripts Healthcare Solutions Inc., Siemens Healthineers, Change Healthcare, ZirMed Inc., The SSI Group LLC, Optum Inc., GE Healthcare, eClinicalWorks, McKesson Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare Electronic Data Interchange (EDI) Market Strategic Shifts & Innovations
Healthcare data exchange is pivoting from batch-file transmission to event-driven API architectures, compressing transaction latency from days to seconds while forcing vendor repositioning.
FHIR R4 APIs are unifying clinical and financial data flows by embedding eligibility, claims, and prior authorization within single RESTful endpoints. Large health systems deploy these interfaces to bypass traditional clearinghouse batch cycles. The technology is unifying previously siloed revenue cycle and clinical operations teams under shared real-time data infrastructure.
CMS interoperability rules now mandate patient access APIs and payer-to-payer data exchange, extending HIPAA transaction requirements into consumer-directed data portability. Health plans must expose claims and encounter data through standardized interfaces by 2026. Medicare Advantage organizations face the steepest compliance timeline, with OCR audit protocols already testing technical implementation.
Provider procurement patterns now prioritize subscription-based platform pricing over per-transaction fees, compressing vendor revenue models toward flat-rate SaaS structures. Health system CFOs negotiate multi-year EDI platform contracts with embedded professional services. This shift concentrates procurement authority within integrated delivery network headquarters rather than departmental IT budgets.
Healthcare Electronic Data Interchange (EDI) Market Segmentation
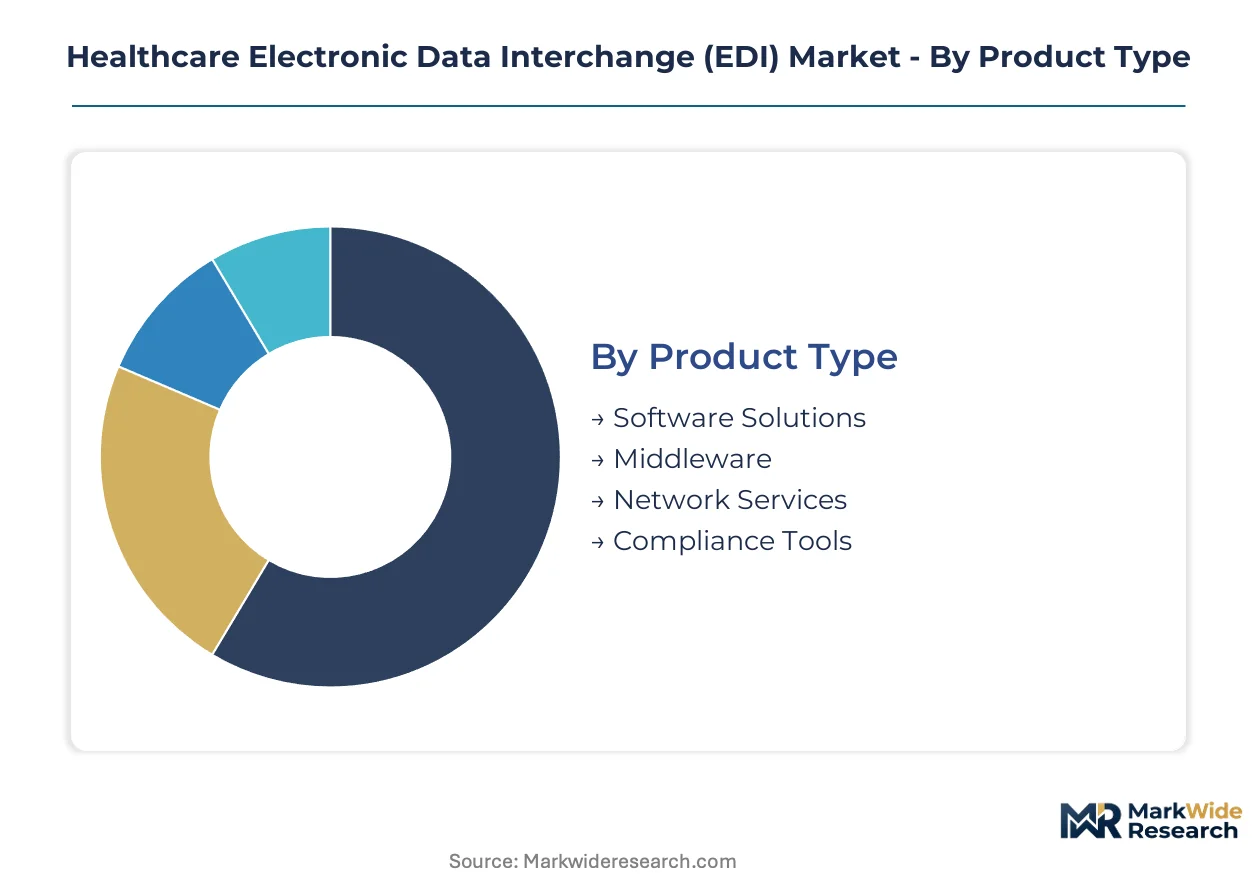
Healthcare EDI procurement decisions hinge on interoperability requirements, capital intensity tolerance, and regulatory compliance burdens. Segmentation reveals how vendor architectures align with distinct buyer workflows across the revenue cycle.
Product Type:
Buyers prioritize total cost of ownership over upfront licensing when evaluating EDI infrastructure components.
- Software Solutions:Core transaction processing platforms handle ANSI X12 message translation, mapping, and validation. Demand concentrates among large integrated delivery networks replacing legacy mainframe installations. CMS certification requirements for HIPAA compliance drive procurement toward vendors with pre-validated rule sets.
- Middleware:Integration engines bridge EDI workflows with EHR systems, ERP platforms, and payer portals through protocol adapters. Health systems with heterogeneous IT estates deploy these layers to avoid rip-and-replace scenarios. FHIR API conversion modules represent the fastest-adopted capability within this tier.
- Network Services:Secure data transmission infrastructure including VAN connectivity and AS2 protocol support.
- Compliance Tools:Audit logging, error tracking, and regulatory reporting modules for OCR readiness.
Volume sits with Software Solutions; growth tilts toward Middleware.
Application:
Transaction volume density determines platform sizing and throughput engineering priorities.
- Claims Management:The highest-throughput EDI application encompassing professional, institutional, and dental claim submission with companion documentation. Large physician groups and hospitals route millions of transactions monthly through clearinghouse gateways. Denial management analytics now embed within these platforms to reduce revenue leakage.
- Eligibility Verification:Real-time patient coverage confirmation through 270/271 transaction pairs. Retail pharmacy chains and urgent care networks drive demand for sub-second response latency. Payer-provider data connectivity investments expand addressable volume as instant verification becomes standard.
- Payment Processing:Electronic remittance advice and funds transfer automation. Real-time adjudication pilots are displacing batch-cycle workflows in Medicare Advantage contracts.
- Referral Authorizations:Prior authorization and referral request routing between primary and specialty care.
Claims Management dominates transaction counts; Payment Processing gains share fastest.
End User:
Organizational scale dictates integration complexity and vendor relationship models.
- Hospitals:Enterprise EDI deployments spanning inpatient, outpatient, and emergency department revenue cycles. Multi-facility health systems require centralized transaction monitoring across dozens of payer connections. Capital constraints delay cloud migration for rural and critical access hospitals.
- Physician Practices:Ambulatory EDI needs center on eligibility verification and claim scrubbing. Group practices with 50+ providers increasingly demand API-native platforms over traditional clearinghouse relationships.
- Pharmacy Providers:Prescription claim routing and DUR transaction processing for retail and specialty pharmacies.
- Health Plans:Inbound claim adjudication and outbound payment distribution infrastructure.
Hospitals anchor installed base; Physician Practices show steepest expansion trajectory.
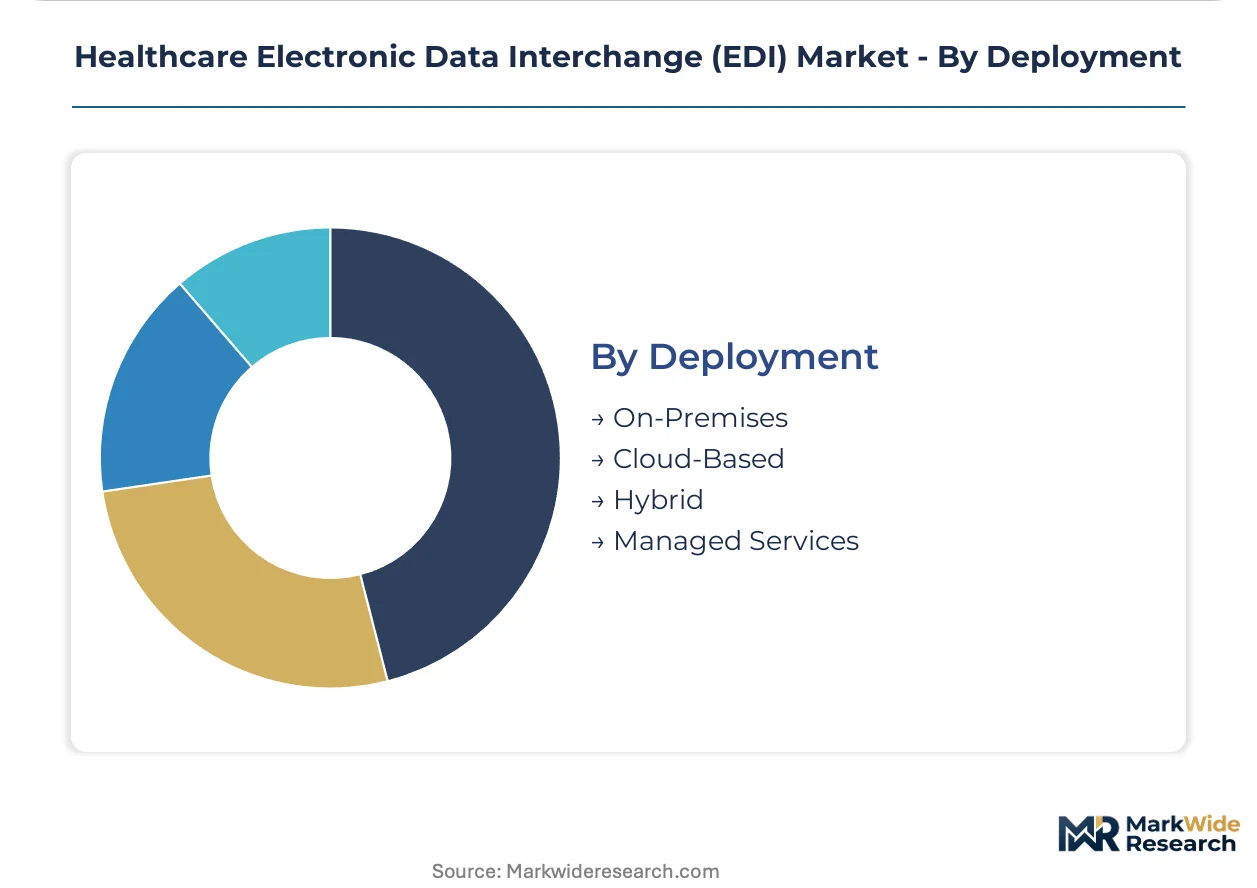
Deployment:
IT governance models and cybersecurity risk tolerance shape infrastructure location decisions.
- Cloud-Based:SaaS EDI platforms with elastic transaction capacity and API-first architectures. Health system CFOs favor subscription pricing over capital expenditure for legacy hardware refresh cycles. AWS, Azure, and Google Cloud health data compliance certifications enable payer acceptance of off-premise processing.
- On-Premises:Dedicated hardware installations within health system data centers. Organizations with strict data residency requirements or bespoke integration needs maintain these configurations despite higher total cost of ownership.
- Hybrid:Split deployments with sensitive transactions on-premise and standard workflows in cloud.
- Managed Services:Outsourced EDI operations including transaction monitoring, error resolution, and payer enrollment.
Cloud-Based commands new procurement; Hybrid retains foothold among risk-averse incumbents.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Healthcare data infrastructure investment clusters around metropolitan health IT corridors where payer-provider density creates transaction volume gravity. Cloud migration patterns and regulatory compliance timelines vary substantially across national healthcare financing systems.
United States
Integrated delivery networks in Nashville and Minneapolis drive clearinghouse consolidation as health systems demand real-time eligibility APIs. CMS enforces HIPAA transaction standards through escalating OCR audit protocols. The Dallas-Fort Worth corridor anchors pharmacy benefit management EDI routing for retail chains processing millions of daily prescription claims.
Germany
Hospital federations in North Rhine-Westphalia accelerate cloud-based claims processing adoption to meet Diagnosis-Related Group billing deadlines. The country's national telematics infrastructure mandates standardized electronic health record exchange formats. Berlin hosts emerging middleware vendors bridging legacy hospital information systems with FHIR-compliant interfaces.
United Kingdom
NHS Integrated Care Systems in Greater Manchester and London procure centralized EDI platforms to unify previously fragmented trust-level revenue cycles. NHS Digital mandates specific message standards for secondary care billing and primary care payments. The Cambridge-Oxford-London triangle concentrates health tech startups developing API-native prior authorization tools.
Japan
Metropolitan hospital chains in Tokyo and Osaka migrate from proprietary medical fee claim systems toward standardized electronic submission formats. METI promotes healthcare data exchange interoperability guidelines aligned with international standards. The Kansai region hosts pharmaceutical distributors implementing EDI-tracked cold chain documentation for biologics.
Australia
State health departments in New South Wales and Victoria deploy cloud-based eligibility verification for public hospital outpatient services. The Australian Digital Health Agency enforces secure messaging standards for healthcare provider identifier authentication. Melbourne's health tech cluster develops middleware solutions connecting private practice management software with Medicare claims channels.
Healthcare Electronic Data Interchange (EDI) Market Key Industry Players
Global majors compete with regional champions across clearinghouse density and payer connectivity depth. Three intermediaries control dominant transaction routing share, creating tiered competitive dynamics between scale-driven incumbents and API-native challengers. Strategic archetypes include payer-affiliated platforms, independent clearinghouses, and EHR-integrated workflow vendors. Consolidation through vertical capability acquisition and cloud infrastructure partnerships represents the dominant competitive trajectory.
Among payer-affiliated platform operators, Optum Inc. and Change Healthcare exemplify integrated data connectivity strategies spanning eligibility verification through payment processing. McKesson Corporation anchors pharmacy-centric EDI routing through benefit management channel control. These three entities represent distinct scale archetypes: vertically integrated payer assets, independent clearinghouse specialists, and supply chain-anchled transaction networks.
| Leading Market Players |
|---|
| Allscripts Healthcare Solutions Inc. |
| Siemens Healthineers |
| Change Healthcare |
| ZirMed Inc. |
| The SSI Group LLC |
| Optum Inc. |
| GE Healthcare |
| eClinicalWorks |
| McKesson Corporation |
| Others |
Cost & Logistics Intelligence
Cloud infrastructure subscription costs cascade through Healthcare EDI vendor pricing tiers, with AWS and Azure health data compliance certifications enabling payer acceptance of off-premise processing at lower total cost of ownership than legacy mainframe maintenance. Health system CFOs negotiate multi-year platform contracts where embedded professional services bundles separate premium-tier offerings from standard SaaS subscriptions.
Pricing Analysis
Professional services bundling distinguishes premium EDI platform tiers from standard SaaS subscriptions, with implementation support and dedicated interoperability engineering commanding 40-60% price premiums. Three-tier pricing structure across premium, standard, and economy levels tracks transaction volume commitments and API complexity requirements. Pricing pressure stems from provider procurement teams consolidating vendor relationships to reduce multi-payer portal maintenance overhead. Rural and critical access hospitals exhibit highest price sensitivity due to capital constraint severity, while integrated delivery networks with 10+ facilities leverage scale for flat-rate enterprise licensing.
Supply Chain Analysis
Regional data center distribution across AWS us-east-1, Azure East US, and Google Cloud us-central1 creates hub-and-spoke latency optimization for sub-second eligibility verification response times. Cloud infrastructure draws from semiconductor fabrication concentrated in Taiwan, South Korea, and USA, with server hardware assembly anchored in Mexico and China. Single-source vulnerability concentrates in hyperscaler backbone dependencies, where three providers control 85% of health system cloud migration capacity. Distribution runs through direct vendor-to-health-system contracts, bypassing traditional value-added network intermediaries for API-native deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Healthcare EDI capacity constraints center on certified interoperability engineer scarcity, with HL7 FHIR and ANSI X12 dual-competency labor shortages propping vendor pricing power and implementation timeline premiums. This supply bottleneck favors incumbent platform consolidation over greenfield entry.
For Market Incumbents: Acquire API-native middleware specialists to fill FHIR R4 conversion capability gaps before cloud-native challengers capture integrated delivery network procurement cycles. Consolidate regional clearinghouse relationships to reduce multi-payer portal fragmentation threatening customer retention. Optum Inc. and Change Healthcare demonstrate vertical integration into payer-provider data connectivity as the defensive template; McKesson Corporation's pharmacy benefit management channel control offers parallel consolidation logic. Threat substitution from FHIR-native platform entrants demands pre-emptive capability absorption. For New Entrants and Emerging Players: CMS interoperability rules mandating patient access APIs and payer-to-payer data exchange by 2026 open a window for API-first platform positioning in Medicare Advantage eligibility verification. Target Medicaid managed care expansion states—Texas, Florida, California—where state-level privatization creates procurement cycles unencumbered by incumbent relationship lock-in. Prior authorization automation represents the most penetrable white-space segment, with FHIR-EDI convergence enabling real-time medical necessity verification that legacy batch-cycle vendors cannot match. For Investors and Strategic Acquirers: Distressed-cycle entries favor cloud-migration-stalled regional clearinghouses in secondary US metropolitan corridors where capital constraints delayed SaaS transition. Long-term viability hinges on API-native architecture possession and CMS certification maintenance through evolving HIPAA transaction standards. Watch Medicare Advantage OCR audit protocol enforcement intensity as inflection indicator—technical implementation failures will force vendor consolidation and create acquisition targets at compressed valuations.| Strategic Initiative | Industry Significance |
|---|---|
| FHIR API Platform Integration | Enables real-time eligibility verification bypassing traditional clearinghouse batch cycles for large health systems. |
| Medicaid Managed Care Expansion | Captures state-level privatization procurement cycles in Texas, Florida, and California payer EDI markets. |
| Prior Authorization Automation | Reduces administrative burden through FHIR-EDI convergence for medical necessity verification workflows. |
| Cloud Infrastructure Partnership | Secures AWS, Azure, and Google Cloud health data compliance certifications enabling payer acceptance. |
| Interoperability Engineer Acquisition | Addresses HL7 FHIR and ANSI X12 dual-competency scarcity constraining implementation capacity. |
Research Approach
CMS Medicare claims databases, HIPAA transaction standard enforcement records, and GPO contracts formed the secondary backbone, supplemented by SEC filings from publicly traded health IT vendors and hyperscaler health data compliance certifications. Primary interviews with revenue cycle executives, interoperability engineers, health plan technology procurement officers, and clearinghouse operations directors validated segmentation assumptions and pricing dynamics. Bottom-up transaction volume modeling and top-down payer IT spending analysis provided triangulation across the analysis window.
Historical trendline analysis of cloud migration patterns and real-time adjudication pilot adoption informed projection frameworks across deployment model, organization scale, application type, and regional regulatory cluster dimensions. CAGRs derived from segmented growth rate reconciliation against aggregate market expansion assumptions. Industry-specific inputs included ANSI X12 version adoption curves, FHIR R4 implementation timelines, and OCR audit protocol enforcement intensity.
The model assumes a particular technology adoption path; alternative pathways for FHIR-native platform displacement of legacy EDI clearinghouses would alter the outlook. Forecasts reflect stated assumptions regarding CMS interoperability rule compliance timelines and hyperscaler health data certification maintenance. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Informatics
Global Non Clinical Information System Market
Health Informatics
Global Health IT Security Market
Health Informatics
Global Healthcare Integration Market
Health Informatics
Healthcare API Market
Health Informatics
Healthcare Clinical Analytics Market
Health Informatics
United States Healthcare Information Exchange Market
Health Informatics
AI-Powered Formulary Management Market
Health Informatics
Global Laboratory Information System Market
Health Informatics
High Acuity Information Systems Market
Health Informatics
Health Information Exchange (HIE) Market
Health Informatics
Global Cardiology Information System Market
Health Informatics
Healthcare Interoperability Market
Health Informatics
Healthcare Automatic Identification and Data Capture (AIDC) Market
Health Informatics
AI in Epidemiology Market
Health Informatics
EHR EMR Market
Health Informatics
Global Ambulatory EHR Market