
 United States Senior Living Market | 2026-2036
United States Senior Living Market Size, Share, and Industry Trends Forecast 2026-2036
United States Senior Living Market Analytics
Market Context with Strategic Players
Multi-source care contracting is hardening as operators diversify service partnerships across therapy, pharmacy, and technology vendors. Brookdale Senior Living leverages its national footprint to sustain occupancy rates across diversified markets. Sunrise Senior Living anchors premium positioning through specialized memory care programming. Erickson Senior Living competes with large-scale continuing care retirement communities that integrate independent living through skilled nursing on single campuses.
Technical Definition and Structural Segments
United States Senior Living encompasses licensed residential facilities providing housing, personal care, and health services to adults aged 65 and older, with physical plant standards governing square footage per resident, staffing ratios, and life safety systems. The sector serves primarily non-acute care needs, bridging home-based independence and hospital-level intervention. Assisted living and memory care categories command expanding margin pools as acuity rises and private-pay capacity deepens, while skilled nursing faces structural pressure from Medicare reimbursement compression and diversion to home-based alternatives. Payment model segmentation reveals growing reliance on private pay and long-term care insurance as Medicaid-dependent operators confront state fiscal constraints.
Regulatory Framework and Outlook
CMS, state departments of health, and OSHA shape operational compliance through Medicare and Medicaid certification requirements, life safety code enforcement, and workplace safety mandates. State licensure standards vary considerably, creating fragmented market access conditions that favor operators with dedicated regulatory affairs capabilities. Stakeholders must monitor CMS innovation center demonstrations and state Medicaid waiver expansions that could accelerate value-based reimbursement transitions across facility types.
Market Dynamics
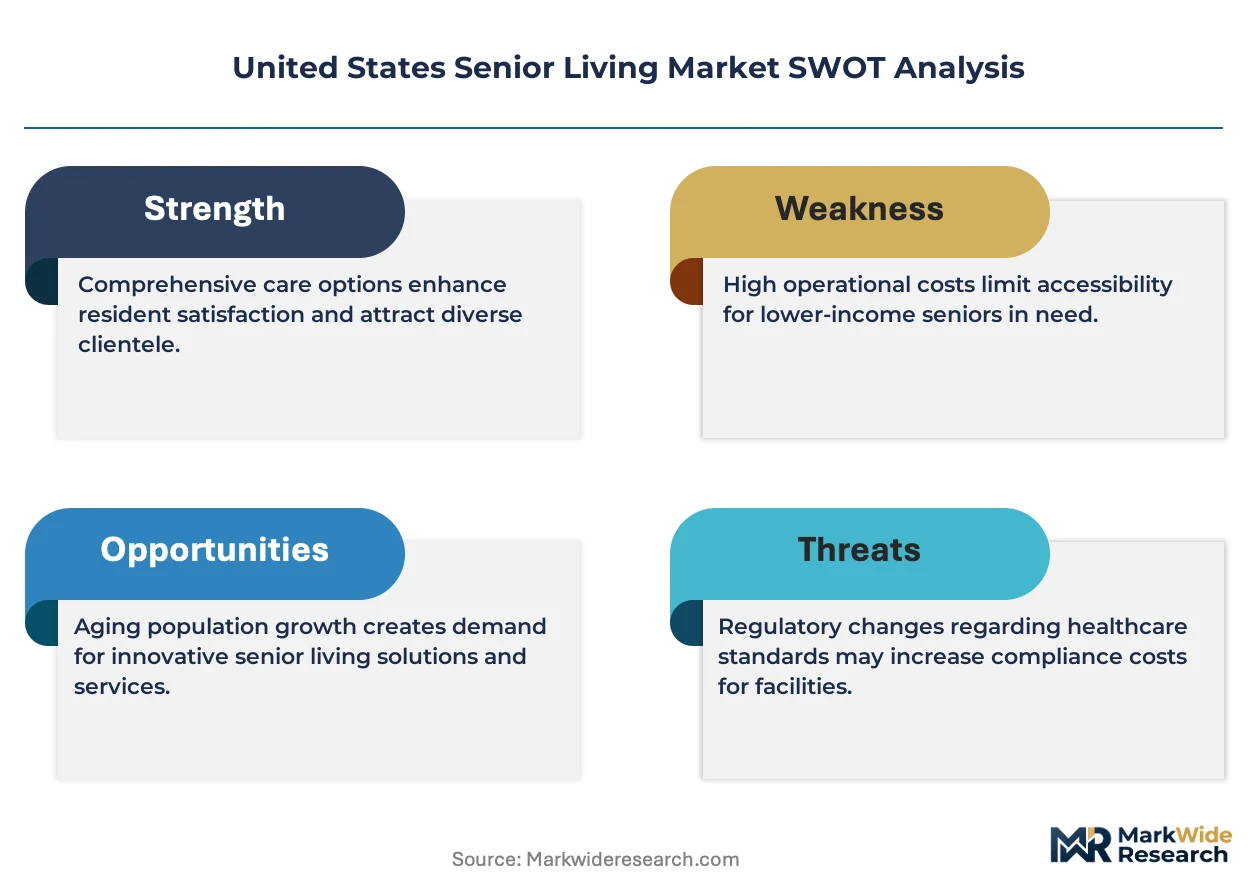
CMS reimbursement compression toward home and community-based services is forcing capital redeployment away from institutional skilled nursing beds toward assisted living and memory care capacity.
Growth Catalysts
- Medicaid 1915(c) Waivers:State waiver expansions in Texas and Florida are channeling federal matching funds into community-based senior housing alternatives.
- Aging-in-Place Technology:Remote patient monitoring platforms are extending resident length-of-stay by reducing preventable hospital transfers.
- Sun Belt Migration:Retiree relocation to Arizona and the Carolinas is concentrating new development permits in lower-cost operational markets.
Market Restraints
- Labor Cost Escalation:Certified nursing assistant wages in California and New York are compressing operating margins below sustainable thresholds.
- Medicaid Rate Stagnation:State budget constraints in Illinois and Connecticut are freezing reimbursement rates while input costs rise.
- Site Control Scarcity:Zoning restrictions in suburban Boston and Seattle metros are limiting greenfield development opportunities.
Strategic Opportunities
- Continuing Care at Home:Unbundled membership models in Pennsylvania and Ohio are capturing seniors earlier in the acuity curve.
- HUD Section 202 Expansion:Federal capital advances for affordable senior housing are unlocking below-market financing in secondary metros.
- AI Fall Detection:Computer vision systems paired with ambient sensors are reducing liability exposure and insurance premiums.
Industry Challenges
- Workforce Pipeline Collapse:Geriatric nursing programs in Michigan and Wisconsin are producing insufficient graduates to replace retiring staff.
- Technology Integration Debt:Electronic health record migrations from legacy platforms are disrupting billing cycles and census management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Senior Living Market |
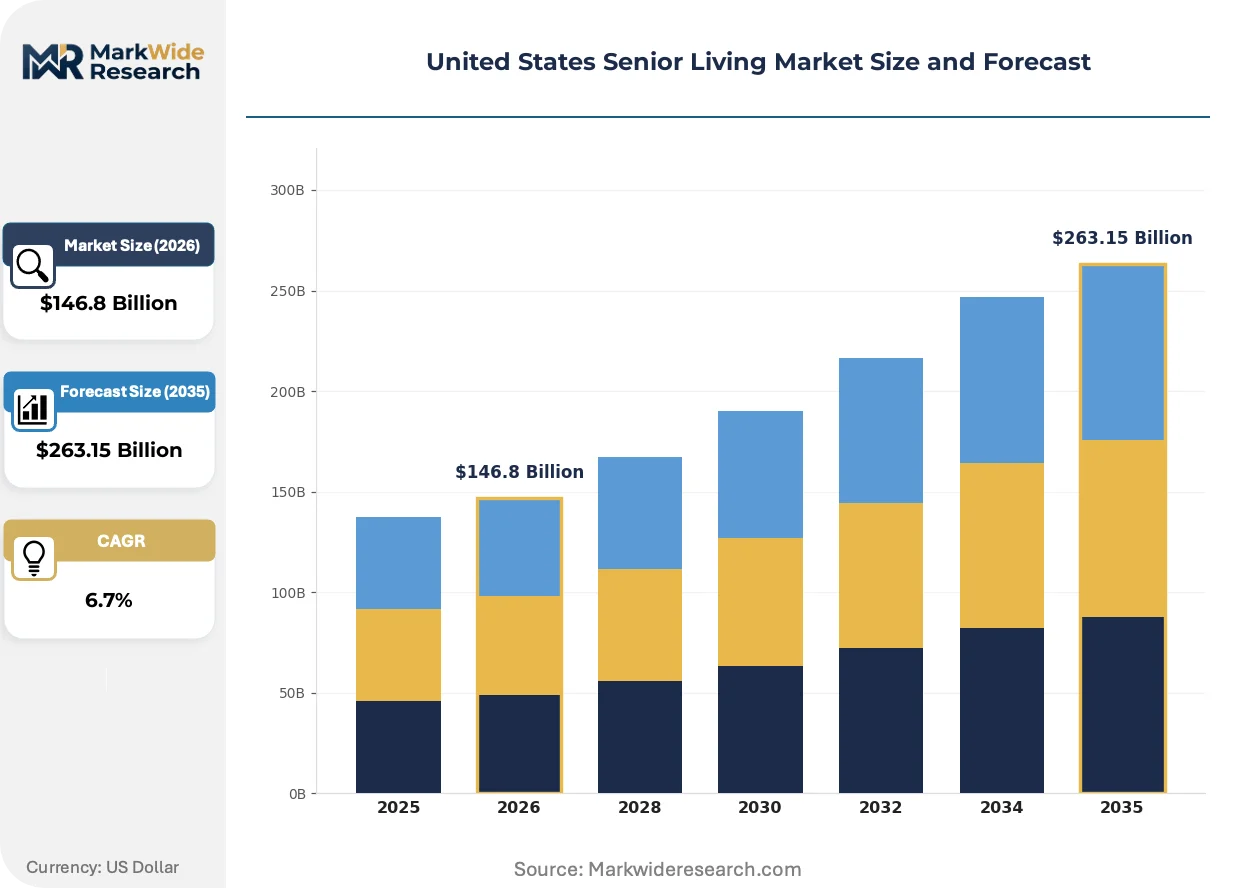
| Market Size in 2026 | $146.8 Billion |
| Market Size in 2035 | $263.15 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Facility Type: Independent Living, Assisted Living, Skilled Nursing, Memory Care Service Plan: Basic Care, Comprehensive Care, Respite Care, Customized Plans Payment Model: Private Pay, Long-term Care Insurance, Medicaid, Medicare Resident Type: Active Seniors, Seniors with Disabilities, Memory Care Residents, Short-term Residents |
| Companies Covered | Erickson Senior Living, Sunrise Senior Living, Brookdale Senior Living, Integral Senior Living, Senior Lifestyle Corp, Discovery Senior Living, Atria Senior Living, Watermark Retirement Communities, Life Care Services, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Senior Living Market Evolving Landscape
Operational models are compressing around resident acuity segmentation, with technology and regulatory pressure converging to reshape physical plant design and staffing ratios.
Sensor-based ambient monitoring is electrifying resident safety protocols. Fall prediction algorithms process gait pattern data from floor sensors and wearable devices. Large operators in Florida and Texas are deploying these systems across memory care wings to reduce nighttime staffing ratios while maintaining state compliance.
OSHA workplace violence prevention mandates are reshaping facility design standards. New construction in California and Washington must incorporate secure nurse stations and duress alarm systems. Skilled nursing operators are absorbing capital costs to avoid citation exposure and workers compensation premium spikes.
Adult children are consolidating decision-making authority over parent placement. Digital referral platforms are displacing traditional placement agency relationships. This pattern concentrates in coastal metros where out-of-state children coordinate care remotely for aging parents.
United States Senior Living Market Segmentation
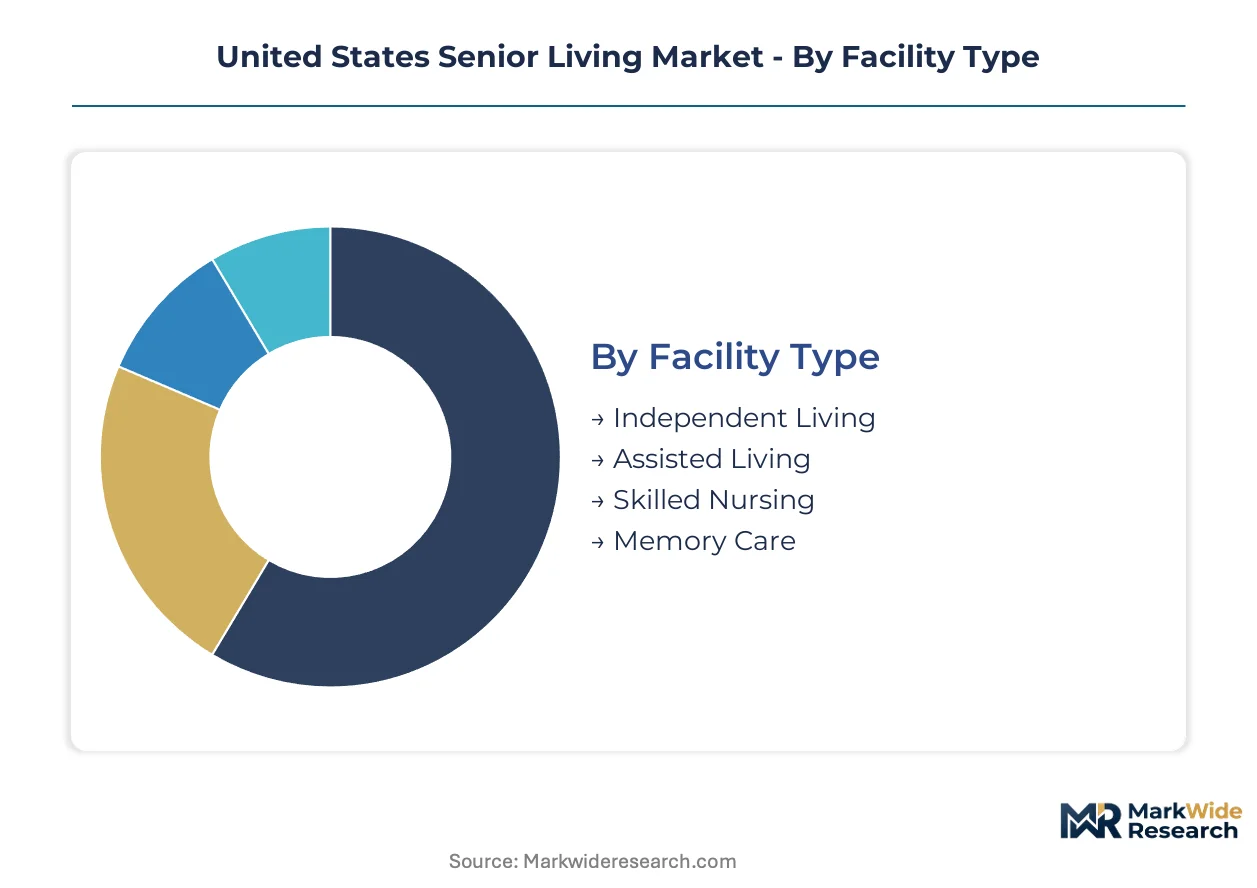
Senior living operators configure capacity across facility types and payment models to match regional demographics and reimbursement landscapes. Segmentation discipline separates private-pay premium capture from Medicaid-dependent volume plays.
Facility Type:
Volume concentrates in mid-acuity assisted living while premium margins cluster in specialized memory care wings.
- Independent Living:Age-restricted apartments and cottages with minimal medical oversight target mobile retirees seeking social infrastructure. Demand clusters in Florida and Arizona where amenity-rich campuses attract inbound migration from high-tax northern states.
- Assisted Living:Licensed residential settings deliver medication management, ADL assistance, and 24-hour staffing without skilled nursing intensity. Texas and the Carolinas are absorbing the fastest development pipelines as operators chase lower land costs and lighter regulatory burdens than coastal markets.
- Skilled Nursing:Post-acute rehabilitation and long-term custodial care operate under Medicare Part A and Medicaid reimbursement. CMS site-neutral payment rules are compressing margins and accelerating bed closures in Illinois and Connecticut.
- Memory Care:Secured units with specialized staffing ratios and environmental design serve Alzheimer's and dementia populations. Secured-door architecture and Snoezelen therapy rooms command 40-60% monthly premiums over standard assisted living in California and Washington metros.
Today's leader: Assisted Living. Tomorrow's challenger: Memory Care.
Service Plan:
Margin structure separates bundled comprehensive contracts from unbundled fee-for-service arrangements.
- Basic Care:Tiered assistance with bathing, dressing, and medication reminders supports lower-acuity residents. Arizona operators deploy basic care tiers to extend length-of-stay before residents require comprehensive transitions.
- Comprehensive Care:All-inclusive packages covering ADLs, medication administration, and care coordination. Florida campuses report highest attachment rates where adult children purchase certainty over itemized billing complexity.
- Respite Care:Short-stay options of 7-30 days for post-hospital recovery or family caregiver relief. Texas Medicaid 1915(c) waivers are expanding respite reimbursement to reduce nursing home diversion.
- Customized Plans:Modular service menus allowing residents to purchase specific assistance hours à la carte. Pennsylvania continuing-care-at-home programs are piloting unbundled membership models upstream of facility placement.
Comprehensive plans dominate revenue concentration. Customized plans are gaining share fastest among tech-forward operators.
Payment Model:
Capital deployment tracks the private-pay to Medicaid ratio in each target metro.
- Private Pay:Out-of-pocket spending from personal assets, home sale proceeds, and family contributions. Sun Belt development prioritizes private-pay capacity where retiree wealth migration concentrates.
- Long-term Care Insurance:Policy-triggered benefits covering facility and home care after elimination periods. California and New York show highest policy density among residents entering care now, though new policy sales have collapsed since 2000.
- Medicaid:State-federal matching funds for low-income seniors meeting functional and financial eligibility. Texas and Florida waiver expansions are shifting Medicaid dollars toward community-based settings away from institutional nursing.
- Medicare:Limited post-acute skilled nursing coverage under Part A following hospital stays. Site-neutral reimbursement cuts are reducing Medicare-funded lengths of stay and pushing operators toward managed care contracting.
Private pay anchors margin stability. Medicaid represents the fastest-expanding payer in waiver-active states.
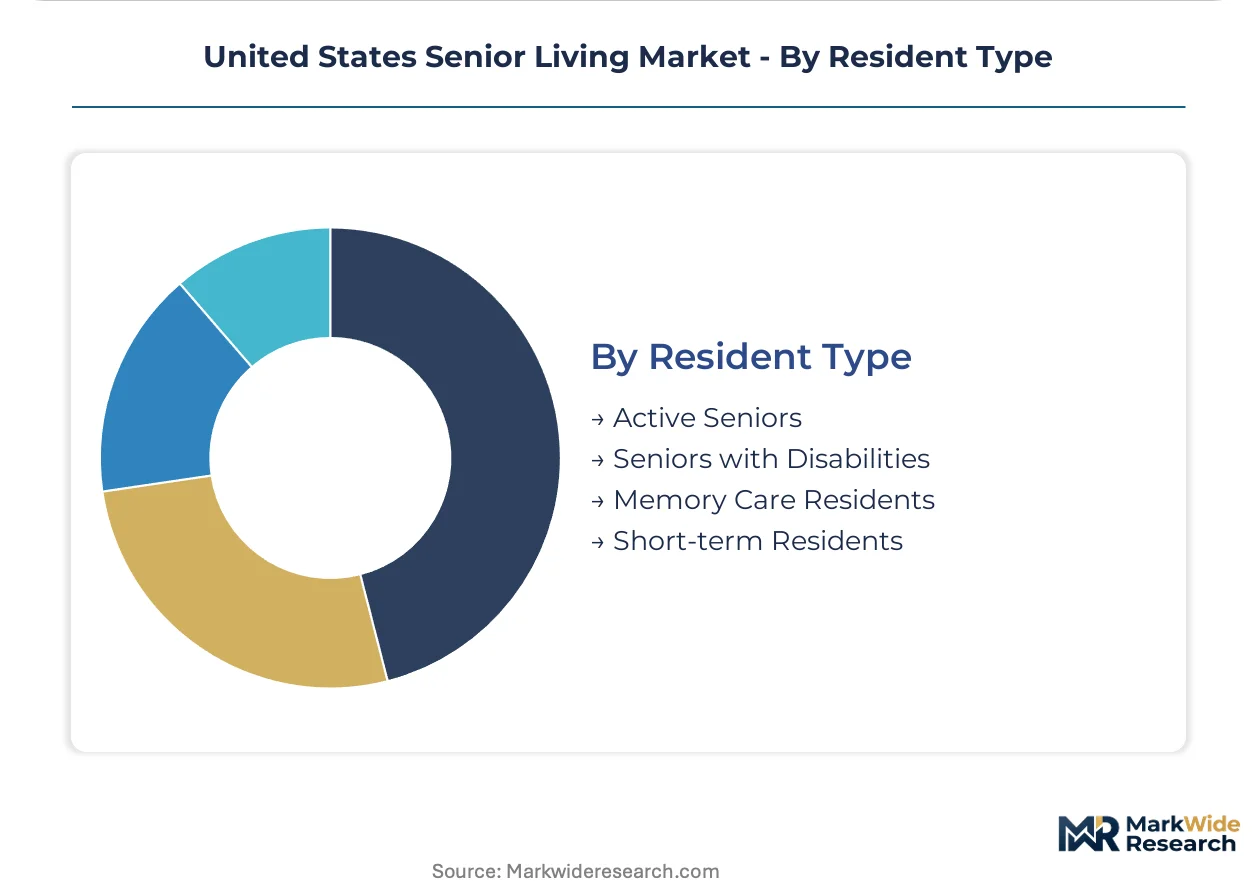
Resident Type:
Acuity segmentation determines staffing ratios, liability exposure, and average length-of-stay economics.
- Active Seniors:Independent living residents requiring no hands-on care but seeking community and maintenance-free housing. Arizona and Florida campuses target this segment earliest in the consumer journey to capture lifetime value.
- Seniors with Disabilities:Residents with mobility, sensory, or chronic condition limitations needing ADL support. ADA-compliant unit design and roll-in showers are standard in new California construction.
- Memory Care Residents:Dementia-diagnosed individuals requiring secured environments and specialized programming. Wander-guard systems and circadian lighting are becoming capital requirements in Washington and Oregon.
- Short-term Residents:Post-acute rehabilitation patients and respite stays with defined discharge horizons. Texas operators are building short-stay wings to capture hospital referral relationships and Medicare Advantage network inclusion.
Active seniors deliver longest tenures. Short-term residents provide highest per-day revenue velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping capital deployment as operators migrate toward states with lighter licensure burdens and expanding Medicaid waiver programs. CMS reimbursement compression accelerates this geographic sorting.
Florida
Retiree wealth migration from high-tax northern states sustains private-pay occupancy rates above national averages. The Agency for Health Care Administration oversees assisted living licensure with streamlined memory care add-on approvals. Tampa-St. Petersburg and Orlando corridors absorb the fastest greenfield development pipelines.
Texas
Medicaid 1915(c) waiver expansions are channeling federal matching funds into community-based alternatives at scale. The Texas Health and Human Services Commission administers STAR+PLUS managed care integration for dual-eligible seniors. Dallas-Fort Worth and Austin metros concentrate new assisted living capacity targeting middle-market price points.
Arizona
Inbound migration of active seniors seeking maintenance-free housing extends independent living length-of-stay economics. The Arizona Department of Health Services regulates assisted living with staffing ratio flexibility that reduces operational overhead. Phoenix and Tucson suburbs anchor amenity-rich campus development.
California
OSHA workplace violence prevention mandates and stringent life safety codes elevate capital costs for new construction. The California Department of Social Services enforces some of the nation's tightest square-footage and staffing standards. San Diego and Inland Empire sub-markets attract operators escaping coastal land scarcity.
North Carolina
Lower land costs and right-to-work labor frameworks compress operating expenses versus northeastern competitors. The North Carolina Department of Health and Human Services licenses adult care homes with tiered care level designations. Charlotte and Research Triangle metros draw regional operators expanding from Virginia and South Carolina bases.
United States Senior Living Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized acuity segments and technology-enabled care models. The vendor base stratifies across national scale operators, regional consolidators, and niche memory care specialists. Three archetypes dominate: diversified portfolio managers, continuing care campus developers, and boutique lifestyle-positioned brands. Competitive moves center on geographic fill-in acquisitions and Medicare Advantage network contracting.
Within the national-scale tier, Brookdale Senior Living, Sunrise Senior Living, and Erickson Senior Living exemplify divergent strategic positioning. Brookdale represents diversified market coverage across facility types and payment models. Sunrise occupies premium-tier specialization through dedicated memory care programming. Erickson anchors large-scale continuing care retirement community development with integrated service continuums.
| Leading Market Players |
|---|
| Erickson Senior Living |
| Sunrise Senior Living |
| Brookdale Senior Living |
| Integral Senior Living |
| Senior Lifestyle Corp |
| Discovery Senior Living |
| Atria Senior Living |
| Watermark Retirement Communities |
| Life Care Services |
| Others |
Value Network & Pricing Analysis
Construction labor cost indices and medical equipment price benchmarks cascade through senior living development economics, compressing project budgets in California and New York while enabling margin expansion in Texas and Florida where input costs remain subdued.
Pricing Analysis
Input-cost pass-through from certified nursing assistant wage inflation and building material escalation is forcing operators toward three-tier pricing structures across premium, standard, and economy levels. Price differentiation hinges on acuity tier and geographic labor market conditions, with memory care wings in Washington and Oregon commanding substantial premiums over basic assisted living. Pricing pressure stems from Medicaid rate stagnation in Illinois and Connecticut, where state budget constraints prevent reimbursement adjustments. Adult children purchasing for coastal parents exhibit lowest price sensitivity, while self-pay retirees in Sun Belt markets demonstrate highest elasticity to monthly rate increases.
Supply Chain Analysis
Specialized medical equipment supply rests on domestic manufacturers in Ohio and Pennsylvania, Canadian mobility device producers, and Mexican component assembly operations for fall detection sensors and nurse call systems. Key dependencies include hospital-grade mattresses, motorized patient lifts, and pharmaceutical dispensing cabinets. Supply chain risk centers on tariff exposure for Chinese-sourced electronic components in ambient monitoring systems. Distribution runs through regional medical equipment distributors serving multi-facility operators, with direct manufacturer relationships emerging for large-scale continuing care campus developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in technology-enabled acuity management and private-pay memory care positioning, with remote patient monitoring deployment reducing labor intensity while extending length-of-stay economics.
For Market Incumbents: Anchor occupancy stability through Medicare Advantage network contracting and hospital system referral partnerships. Defend against home-based care substitution by embedding sensor-based monitoring and telehealth access into standard service plans. Prioritize regulatory affairs capabilities to navigate state Medicaid waiver expansions in Texas and Florida. For New Entrants and Emerging Players: Capture middle-market assisted living demand in Austin and Raleigh-Durham corridors where land costs and licensure burdens remain favorable against coastal competitors. Target respite care and short-stay rehabilitation segments where Texas Medicaid 1915(c) waivers are expanding reimbursement. Deploy digital referral platform partnerships to displace traditional placement agency relationships. For Investors and Strategic Acquirers: Asymmetric upside sits with regional consolidators possessing dedicated regulatory capabilities and existing Medicaid waiver relationships. Long-term viability favors operators with technology infrastructure already deployed rather than legacy platforms requiring migration. Monitor CMS innovation center demonstrations as signals for accelerated value-based reimbursement transitions.| Strategic Initiative | Industry Significance |
|---|---|
| Medicare Advantage Network Contracting | Hospital referral relationships in Texas and Florida secure census stability amid site-neutral reimbursement compression. |
| Memory Care Wing Expansion | Secured-door architecture and Snoezelen therapy rooms in California metros capture 40-60% monthly rate premiums. |
| Ambient Monitoring Deployment | Computer vision fall detection in Florida and Texas reduces liability exposure and enables nighttime staffing ratio optimization. |
| Continuing Care at Home Pilot | Unbundled membership models in Pennsylvania and Ohio capture seniors upstream of facility placement decisions. |
| HUD Section 202 Financing Access | Federal capital advances unlock below-market construction financing in secondary metros with aging demographics. |
Research Methodology
Multiple input streams — senior living operator executives, state Medicaid waiver administrators, hospital discharge planners, and long-term care insurance specialists — were reconciled against secondary validation from CMS reimbursement databases, state licensure filings, and HUD housing program records. Bottom-up facility census data and top-down demographic projections were triangulated to establish market sizing and growth trajectories.
Data-stream reconciliation across the analysis window applied segmentation dimensions spanning facility type, service plan tier, payment model, and resident acuity level. CAGRs were derived from cohort-based modeling of occupancy trends, development pipeline tracking, and reimbursement rate evolution. Forecast inputs incorporated baby boomer age-cohort progression, retiree migration patterns, and state Medicaid waiver expansion schedules.
Medicaid rate freeze decisions, CMS site-neutral payment rule extensions, and technology adoption velocity in remote monitoring are the dominant revision risks to modeled projections. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Global Acute Hospital Care Market
Healthcare Services
Contract Research Organization (CRO) Services Market
Healthcare Services
Global Operating Room Management Market
Healthcare Services
Global Mobile Clinics Market
Healthcare Services
Medical Peer & External Physician Review Services Market
Healthcare Services
Global Corporate Wellness Solutions Market
Healthcare Services
Bruxism Management Market
Healthcare Services
Hair Restoration Services Market
Healthcare Services
Medically Supervised Weight Loss Services Market
Healthcare Services
Global Ambulatory Services Market
Healthcare Services
US Long Term Care Market
Healthcare Services
Global Cord Blood Banking Services Market
Healthcare Services
Chronic Disease Management Service Market
Healthcare Services
US Cord Blood Banking Services Market
Healthcare Services
Aged Care Market
Healthcare Services
Medical Transcription Services Market