
 Prescription Delivery Services Market | 2026-2036
Prescription Delivery Services Market Size, Share, and Industry Trends Forecast 2026-2036
Prescription Delivery Services Market Outlook
The EU Green Deal's pharmaceutical waste reduction targets is realigning logistics priorities toward reusable cold-chain packaging and consolidated delivery rounds. CVS Pharmacy anchors its position through dense retail-to-doorstep networks that compress last-mile costs. Amazon Pharmacy leverages predictive inventory placement to pre-position specialty medications near patient clusters. Walgreens competes on pharmacist-access integration, embedding clinical consultations within its delivery app workflow.
Prescription delivery services encompass the end-to-end distribution of dispensed medications from licensed pharmacies to patients through courier, postal, or dedicated logistics networks, requiring temperature-controlled handling for biologics and controlled-substance chain-of-custody protocols. Their commercial purpose centers on eliminating patient travel burden while maintaining therapeutic adherence for chronic, acute, and specialty drug regimens. Same-day service and express delivery segments command premium positioning due to urgency-driven willingness to pay, particularly in oncology and antiviral categories. Mail order sustains volume leadership in maintenance medication refills where planning horizons allow batch fulfillment economies. Pharmacy chains dominate service provider share by converting existing prescription volume into captive delivery streams.
The FDA enforces track-and-trace serialization under DSCSA, compelling platforms to upgrade scanning infrastructure at every handoff point. HIPAA privacy rules constrain telehealth-integrated delivery data flows, creating compliance architecture costs that favor scaled operators over independents. The DEA's controlled-substance shipping protocols add logistical complexity for Schedule II-V medications, segmenting provider capabilities. Stakeholders must monitor how state-level pharmacy board teleprescribing flexibilities expire or extend, as these permissions directly determine addressable prescription volume for remote-first platforms.
Market Dynamics
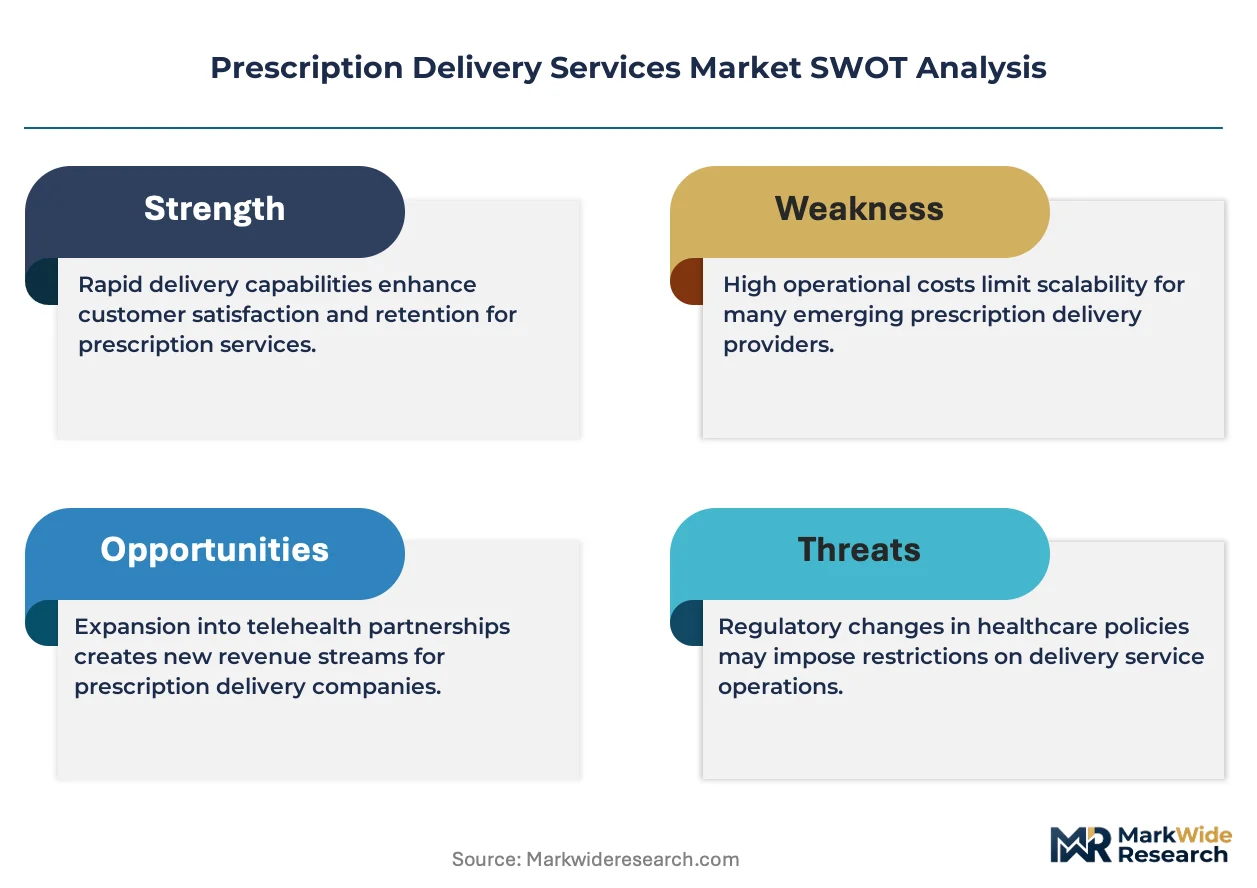
The FDA's Drug Supply Chain Security Act is forcing prescription delivery platforms to rebuild scanning infrastructure at every handoff point, compressing margins for operators lacking scale to absorb serialization compliance costs while advantaging integrated pharmacy chains with captive volume.
Growth Catalysts
- Telehealth integration:Chronic disease management programs in the United States are expanding home-based medication fulfillment, creating captive prescription flow for integrated delivery platforms.
- EU Green Deal:Pharmaceutical waste reduction targets are realigning logistics priorities toward reusable cold-chain packaging and consolidated delivery rounds across European markets.
- Urban corridor density:Same-day infrastructure and telehealth integration are converging in metropolitan clusters, concentrating demand where last-mile economics compress delivery costs per unit.
Market Restraints
- Compliance cost escalation:The FDA's DSCSA mandates unit-level traceability, elevating fixed costs for scanning infrastructure that independents cannot amortize across thin prescription volumes.
- Controlled-substance complexity:DEA shipping protocols for Schedule II-V medications segment provider capabilities, restricting addressable market for platforms lacking specialized chain-of-custody infrastructure.
- Biologics handling requirements:Temperature-controlled logistics for specialty pharmaceuticals concentrate fulfillment in facilities with validated cold-chain certification, limiting geographic coverage expansion.
Strategic Opportunities
- Rural underpenetration:Mail-order maintenance medication refills retain volume leadership in planning-horizon segments, offering batch fulfillment economies in regions lacking same-day infrastructure.
- Pharmacist-access integration:Clinical consultation embedding within delivery app workflows creates service differentiation beyond pure logistics speed.
- State teleprescribing flexibilities:Pharmacy board permissions directly determine addressable prescription volume for remote-first platforms, creating regulatory arbitrage opportunities where flexibilities extend.
Industry Challenges
- HIPAA architecture costs:Privacy rules constrain telehealth-integrated delivery data flows, creating compliance infrastructure investments that favor scaled operators over independents.
- Inventory pre-positioning complexity:Predictive placement of specialty medications near patient clusters requires demand forecasting capabilities and working capital intensity that strains mid-cap platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Prescription Delivery Services Market |
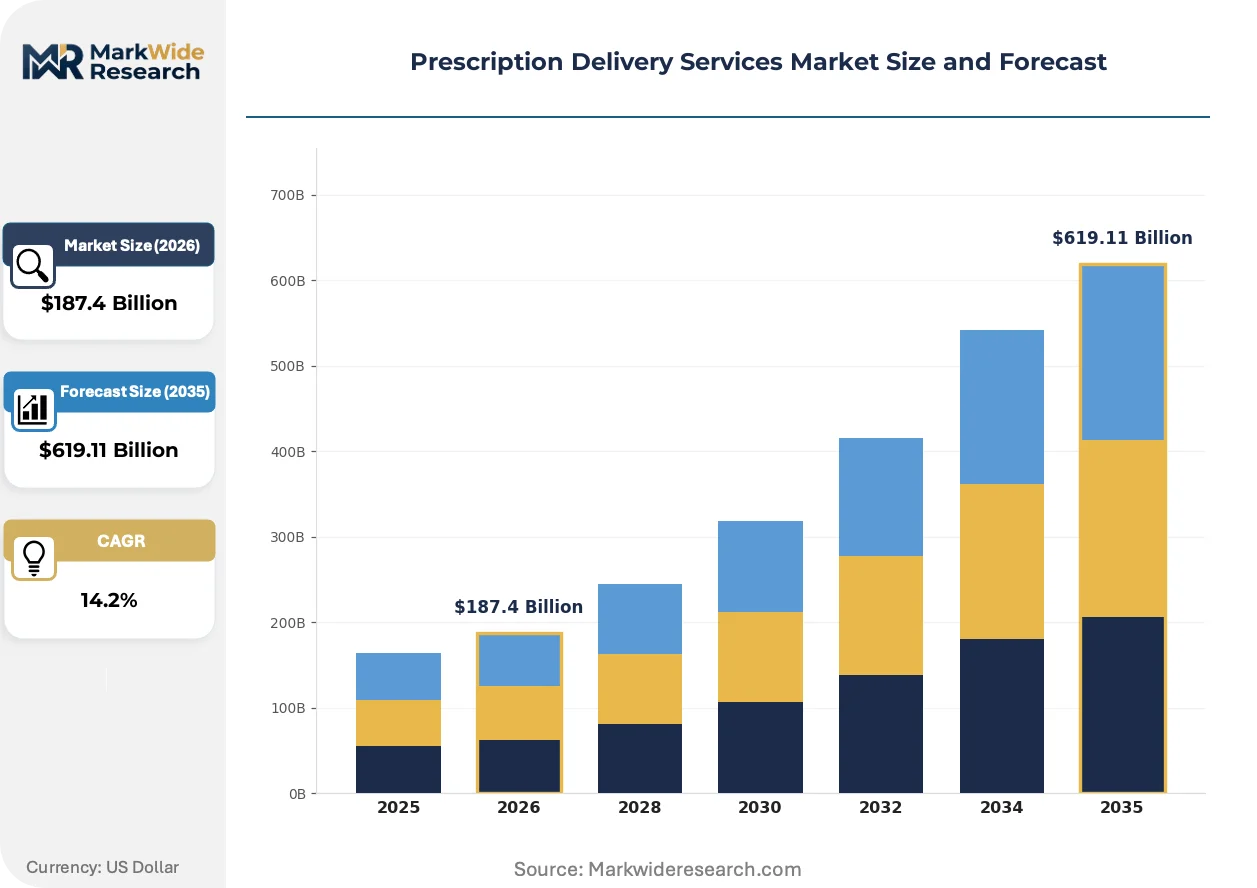
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $619.11 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Delivery Method: Standard Shipping, Express Delivery, Same-Day Service, Mail Order Prescription Type: Refill Prescriptions, New Prescriptions, Specialty Medications, Over-the-Counter Service Provider: Pharmacy Chains, Independent Pharmacies, Online Pharmacies, Hospital Pharmacies Technology Platform: Mobile Apps, Web-Portals, Automated Systems, Telehealth Integration |
| Companies Covered | Honeybee Health, Costco Pharmacy, Amazon Pharmacy, CVS Pharmacy, Walgreens, Blink Health, Health Warehouse, PillPack, GeniusRx, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Prescription Delivery Services Market Strategic Shifts
Prescription delivery is shifting from pure logistics toward integrated medication management, with technology convergence and regulatory serialization demands compressing competitive differentiation into data infrastructure and clinical workflow embedding.
Blockchain-based track-and-trace systems are converging with last-mile routing algorithms to create immutable custody records while optimizing driver dispatch. Large pharmacy chains are deploying these hybrid platforms across high-volume urban corridors. This convergence is compressing audit timelines from days to minutes while elevating infrastructure requirements beyond independent operator reach.
The EU Green Deal's pharmaceutical waste reduction targets are mandating reusable packaging return loops and consolidated delivery rounds. Logistics providers must redesign route density around packaging recovery cycles rather than pure delivery speed. Specialty biologics segments face the steepest adaptation costs given temperature-validated container scarcity.
Patients managing chronic conditions are consolidating prescription procurement through single-platform subscription models, displacing episodic pharmacy visits. This pattern concentrates lifetime value in integrated delivery-plus-adherence programs. United States Medicare Advantage plans show the fastest adoption of these bundled medication management contracts.
Prescription Delivery Services Market Segmentation
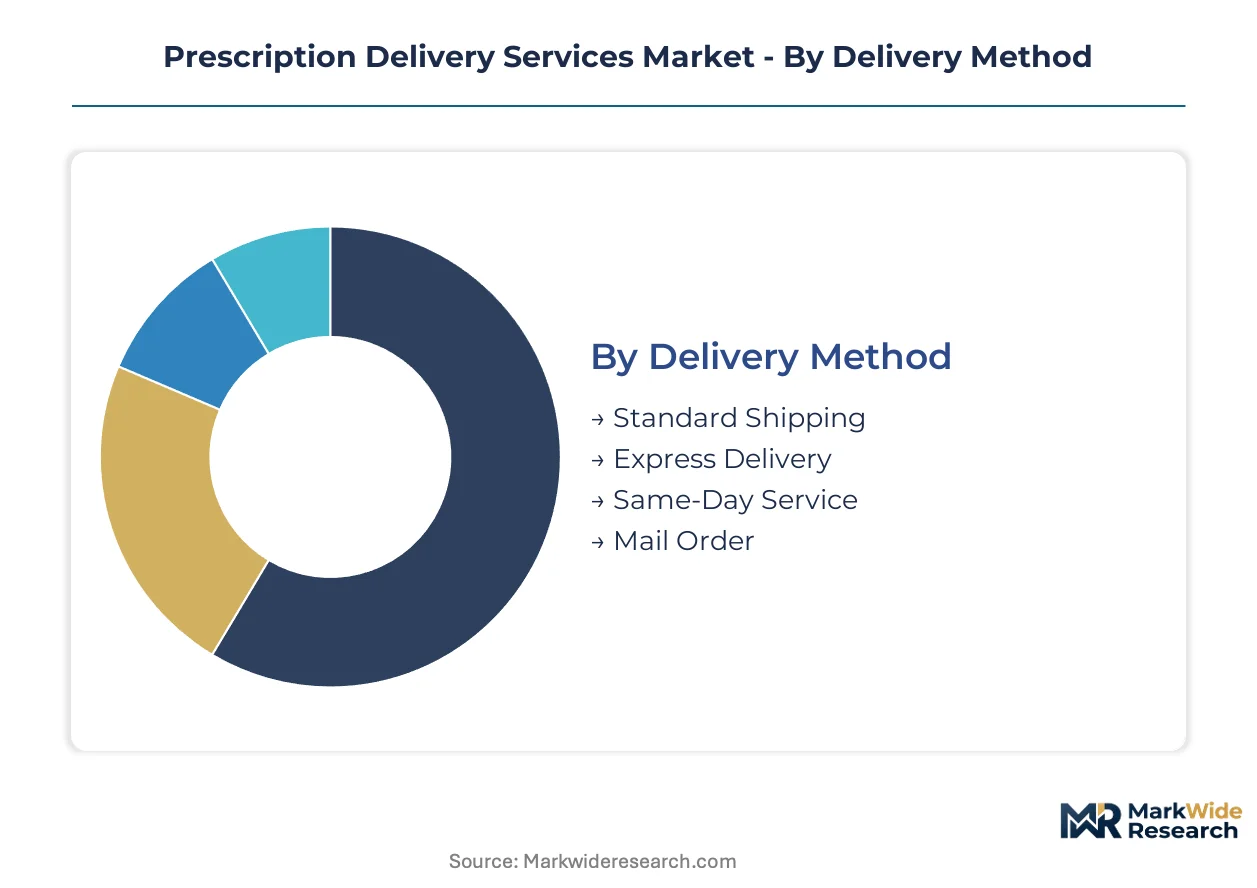
Prescription delivery services fragment across operational methods, medication categories, and platform architectures. Each segmentation axis carries distinct margin profiles and regulatory exposure that shape competitive positioning.
Delivery Method:
Speed specifications define the technology and infrastructure investment required across fulfillment tiers.
- Standard Shipping:Batch consolidation enables cost-efficient distribution of maintenance medications through postal networks. Volume concentrates in Medicare Advantage chronic disease programs across United States retirement corridors where planning horizons accommodate multi-day fulfillment windows.
- Express Delivery:24-48 hour courier networks balance urgency against cost for acute antibiotic and post-surgical pain regimens. Demand clusters in suburban United States markets where pharmacy chain density supports hub-and-spoke distribution without same-day infrastructure premiums.
- Same-Day Service:Urban corridor density requirements limit viable deployment to metropolitan United States clusters with telehealth integration.
- Mail Order:Centralized fulfillment of 90-day maintenance supplies dominates United States commercial insurance formularies.
Mail order leads on scale; same-day service leads on momentum.
Prescription Type:
Medication complexity determines cold-chain requirements, DEA custody protocols, and reimbursement pathways.
- Refill Prescriptions:Automated adherence programs drive recurring revenue through 90-day maintenance cycles for hypertension and diabetes therapies. United States Medicare Part D plans mandate mail-order incentives that concentrate volume in pharmacy chain captive networks.
- New Prescriptions:First-fill verification requirements and prescriber consultation protocols create higher touch costs. United States state pharmacy board teleprescribing flexibilities directly expand addressable volume for remote-first platforms in jurisdictions with extended permissions.
- Specialty Medications:Biologics requiring temperature-validated handling concentrate fulfillment in certified United States facilities.
- Over-the-Counter:Lower regulatory burden permits broader logistics provider participation in United States markets.
Refill prescriptions lead on scale; specialty medications lead on momentum.
Service Provider:
Ownership of prescription origin and patient relationship depth differentiates competitive economics.
- Pharmacy Chains:CVS Pharmacy and Walgreens convert existing prescription volume into captive delivery streams with minimal customer acquisition cost. Dense United States retail footprints compress last-mile economics through store-as-hub fulfillment models.
- Independent Pharmacies:Community-based relationships sustain local chronic disease management contracts despite DSCSA compliance cost disadvantages. United States rural markets retain penetration where pharmacy chain presence remains thin.
- Online Pharmacies:Amazon Pharmacy deploys predictive inventory placement near United States patient clusters.
- Hospital Pharmacies:Discharge medication fulfillment integrates with United States health system electronic records.
Pharmacy chains lead on scale; online pharmacies lead on momentum.
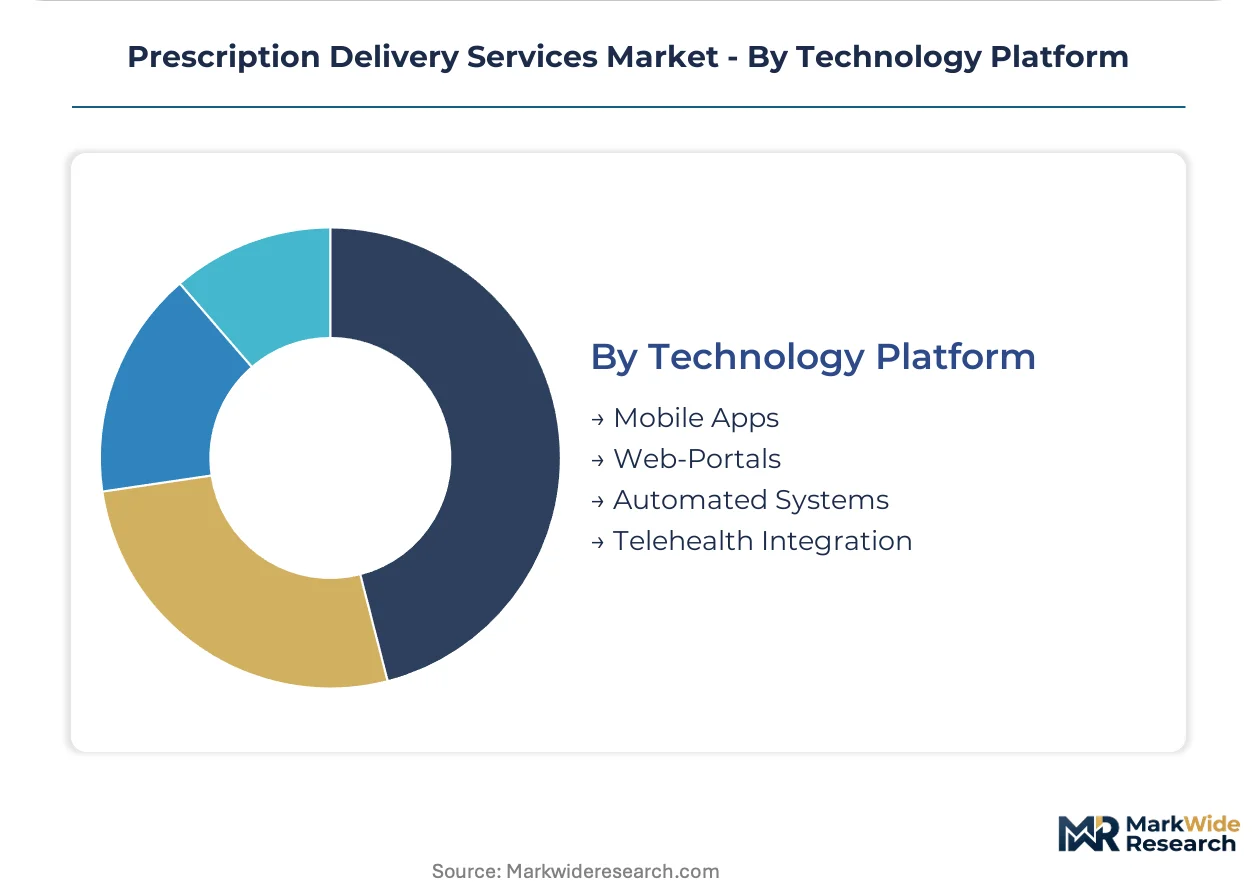
Technology Platform:
Patient interface architecture determines data capture depth and clinical workflow embedding potential.
- Mobile Apps:Push notification adherence algorithms and real-time delivery tracking dominate United States urban consumer expectations. Pharmacy chains embed pharmacist chat and video consultation within native application workflows to differentiate beyond logistics speed.
- Web-Portals:Browser-based ordering retains preference among United States Medicare populations less inclined toward smartphone dependency. Simplified refill interfaces reduce abandonment rates for maintenance medication cohorts.
- Automated Systems:Interactive voice response and pharmacy management system integration streamline United States high-volume processing.
- Telehealth Integration:Prescriber-to-pharmacy data pipes enable same-day fulfillment initiation within United States virtual visit workflows.
Mobile apps lead on scale; telehealth integration leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States pioneered mail-order pharmacy fulfillment through Medicare Part D expansion, establishing the operational template that European and Asia-Pacific markets now adapt to local regulatory frameworks.
United States
Chronic disease management programs and Medicare Advantage bundled contracts drive home-based medication fulfillment. The FDA's Drug Supply Chain Security Act mandates unit-level traceability at every handoff point. Dense urban corridors in New York, Los Angeles, and Chicago concentrate same-day infrastructure where telehealth integration compresses last-mile delivery costs.
Germany
Pharmaceutical waste reduction targets under the EU Green Deal accelerate reusable cold-chain packaging adoption. The country's national pharmaceutical regulator enforces strict temperature-validation protocols for biologics distribution. The Rhine-Ruhr metropolitan cluster anchors consolidated delivery round pilots that prioritize packaging recovery cycles over pure speed.
United Kingdom
National Health Service long-term condition management programs expand remote prescription fulfillment for diabetes and hypertension cohorts. The Medicines and Healthcare products Regulatory Agency aligns with EMA serialization standards for cross-border distribution. Greater London's pharmacy chain density enables store-as-hub fulfillment models that reduce per-unit delivery economics.
Japan
Aging demographics and rural depopulation elevate demand for maintenance medication delivery to isolated elderly populations. The Pharmaceuticals and Medical Devices Agency maintains stringent cold-chain certification requirements for specialty biologics. The Kanto region surrounding Tokyo concentrates predictive inventory placement infrastructure near patient clusters.
India
Telemedicine expansion following pandemic-era regulatory flexibilities unlocks addressable prescription volume for remote-first platforms. The Central Drugs Standard Control Organization mandates increasing traceability for exported pharmaceuticals that domestic delivery networks must mirror. Maharashtra and Karnataka's urban corridors attract pharmacy chain investment in same-day fulfillment infrastructure.
Prescription Delivery Services Market Competitive Environment
Capital-heavy pharmacy chains compete with asset-light digital platforms for prescription fulfillment dominance, creating a bifurcated structure where physical infrastructure investments separate scaled operators from technology-native entrants. The vendor base concentrates around integrated retail-to-doorstep networks, pure-play online pharmacies, and hospital-affiliated discharge fulfillment services. Three archetypes define competitive positioning: dense retail footprint operators leveraging store-as-hub economics, predictive logistics specialists pre-positioning inventory near demand clusters, and clinical workflow integrators embedding pharmacist consultation within delivery applications. Dominant competitive moves include geographic densification through retail expansion and telehealth partnership formations that capture prescription origination upstream.
Among integrated pharmacy chains, CVS Pharmacy and Walgreens occupy positions that exemplify retail-to-doorstep conversion strategies, while Amazon Pharmacy represents the predictive inventory placement archetype within the pure-play segment.
| Leading Market Players |
|---|
| Honeybee Health |
| Costco Pharmacy |
| Amazon Pharmacy |
| CVS Pharmacy |
| Walgreens |
| Blink Health |
| Health Warehouse |
| PillPack |
| GeniusRx |
| Others |
Value Chain & Pricing Dynamics
Captive retail-to-doorstep networks anchor both supply position and pricing power for integrated pharmacy chains, converting existing prescription volume into delivery streams that independents cannot replicate at comparable unit economics. This integration choice compresses last-mile costs through store-as-hub fulfillment while insulating against DSCSA compliance cost escalation that fragments smaller operators.
Pricing Analysis
Subscription-based adherence programs dominate pricing architecture across chronic disease management segments, separating premium same-day oncology delivery from standard mail-order maintenance cycles. Price differentiation hinges on cold-chain certification grade and telehealth integration depth, with urban corridor density enabling cost absorption that rural markets cannot match. Cost compression in express delivery tiers intensifies as Amazon Pharmacy's predictive inventory placement raises working capital requirements for mid-cap competitors. Medicare Advantage plans exhibit lowest price sensitivity due to bundled contract structures, while cash-pay patients in commercial insurance gaps drive economy-tier volume.
Supply Chain Analysis
Workforce availability for validated cold-chain technicians concentrates pharmaceutical fulfillment infrastructure in the United States, Germany, and Japan, where regulatory certification requirements create specialized labor pools that emerging markets cannot yet replicate. Temperature-controlled packaging materials and serialization scanning hardware draw from concentrated medical device manufacturing bases in China and Mexico. Single-source vulnerability in biologics-grade container supply elevates risk exposure for specialty medication segments. Distribution runs through pharmacy chain captive networks in dense metropolitan clusters, with postal consolidation handling residual rural volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Prescription delivery services function as a geographic-arbitrage play where EU Green Deal packaging recovery mandates impose cost structures that US operators avoid, creating margin expansion opportunities for transatlantic platform architectures.
For Market Incumbents: To counter Amazon Pharmacy's predictive inventory placement, CVS Pharmacy and Walgreens should deepen backward integration into specialty pharmacy distribution and secure exclusive telehealth partnership pipelines that capture prescription origination upstream. DSCSA serialization infrastructure investments must extend to blockchain-based custody verification that independents cannot match. For New Entrants and Emerging Players: Launch via white-label pharmacist-access platforms targeting rural United States corridors where pharmacy chain presence remains thin and mail-order maintenance volumes retain batch fulfillment economies. State-level teleprescribing flexibility extensions offer regulatory arbitrage entry points for remote-first platforms. For Investors and Strategic Acquirers: Consolidation pressure builds where DSCSA compliance costs exceed independent pharmacy cash flow generation, creating distressed acquisition opportunities for scaled operators with amortized scanning infrastructure. Target mid-cap platforms with validated cold-chain certification and existing Medicare Advantage contracts. Monitor state pharmacy board teleprescribing permission expirations as volume inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Telehealth Partnership Formation | Captures prescription origination upstream through embedded pharmacy workflows in virtual visit platforms. |
| Cold-Chain Certification Investment | Unlocks specialty biologics fulfillment margins requiring temperature-validated handling protocols under FDA oversight. |
| Blockchain Track-and-Trace Deployment | Compresses DSCSA audit timelines from days to minutes while elevating infrastructure barriers for competitors. |
| Reusable Packaging Return Loop | Aligns EU Green Deal compliance with consolidated delivery round economics across Rhine-Ruhr metropolitan pilots. |
| Medicare Advantage Contract Expansion | Concentrates lifetime value in bundled medication management programs with adherence monitoring integration. |
Study Parameters
Direct dialogue with pharmacy operations directors, DSCSA compliance officers, telehealth platform executives, and Medicare Advantage formulary managers grounded qualitative findings in operational reality. Secondary validation drew from FDA DSCSA guidance documents, CMS Medicare Part D enrollment data, state pharmacy board teleprescribing bulletins, and EU Green Deal pharmaceutical waste reduction directives. Bottom-up prescription volume modeling triangulated against top-down market sizing across delivery method, prescription type, and service provider segmentation dimensions.
Segmented outputs across the projection horizon reflect discrete modeling of same-day service penetration in urban United States corridors, mail-order maintenance refill cycles, and specialty biologics cold-chain requirements. CAGRs derived from patient population growth, chronic disease prevalence trajectories, and telehealth integration adoption curves. Forecast inputs incorporated Medicare Advantage plan expansion rates and state-level regulatory flexibility timelines without year-specific anchoring.
Forecast precision tightens around the base case; tail outcomes carry wider variance under DEA controlled-substance shipping protocol revisions or EU packaging mandate acceleration. Practitioners should monitor FDA DSCSA enforcement intensity and state pharmacy board teleprescribing rulemaking for early signals of competitive repositioning requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
US Healthcare Staffing Market
Healthcare Services
Asia-Pacific Healthcare Cold Chain Logistics Market
Healthcare Services
Escort Bed Sharing Market
Healthcare Services
China Fertility Services Market
Healthcare Services
Healthcare Logistics Market
Healthcare Services
United States Senior Living Market
Healthcare Services
Global Healthcare Provider Network Management Market
Healthcare Services
India Senior Living Market
Healthcare Services
Global Cath Lab Services Market
Healthcare Services
Vaccine Logistics Market
Healthcare Services
Life Science Trade Lane Design and Qualification Services Market
Healthcare Services
Europe Medical Affairs Outsourcing Market
Healthcare Services
Global Infusion Pharmacy Management Market
Healthcare Services
Kids Sports Injury Treatment Market
Healthcare Services
UK Pharmaceutical Logistics Market
Healthcare Services
US Value-Based Healthcare Service Market