
 Healthcare Contract Sales Organizations Market | 2026-2036
Healthcare Contract Sales Organizations Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare Contract Sales Organizations Market Intelligence
Asset-light outsourcing models are reconfiguring capital deployment across the healthcare CSO landscape, allowing mid-sized biotech firms to access enterprise-grade commercialization without fixed cost burdens. IQVIA leverages its integrated data and deployment platform to dominate full-service engagements. Syneos Health anchors its position through therapeutic specialization across oncology and rare diseases. EVERSANA differentiates via outcome-based contracting structures that align fees with product performance.
Healthcare Contract Sales Organizations are external service providers that deploy trained sales representatives, medical science liaisons, and market access specialists to promote pharmaceuticals, devices, and diagnostics on behalf of manufacturers under contractual arrangements. These organizations operate through dedicated teams or hybrid engagement structures, managing regulatory-compliant field forces, key opinion leader networks, and payer negotiation protocols to accelerate product uptake and expand geographic coverage for clients. Sales outsourcing and market access services command the largest revenue pools, reflecting pharmaceutical manufacturers' preference to externalize high-cost field organizations while retaining strategic control. Oncology specialization within the CSO segment is expanding fastest, driven by complex physician education requirements and biomarker-driven prescribing protocols that demand scientifically trained representatives.
FDA oversight of promotional materials and off-label communication directly shapes CSO training investments and compliance infrastructure, while EMA's Medical Device Regulation extends outsourcing demand for European market access support. The EU AI Act introduces new governance layers for algorithmic sales targeting and physician engagement analytics, compelling CSO operators to rebuild data handling protocols. Stakeholders must monitor how evolving pharmacovigilance obligations and digital engagement rules reshape the cost structure of compliant field deployment.
Market Dynamics
Pharmaceutical manufacturers are dismantling captive sales infrastructure in favor of variable-cost outsourcing models, driven by FDA enforcement of promotional compliance and the capital efficiency demands of biotech venture financing.
Growth Catalysts
- Biomarker-driven oncology protocols:Complex prescribing workflows require scientifically trained field forces that CSOs deploy faster than in-house hiring cycles permit.
- FDA promotional oversight:Intensified scrutiny of off-label communications compels manufacturers to externalize compliance liability to specialized third-party operators.
- European market access fragmentation:EMA's Medical Device Regulation and national HTA divergences create demand for outsourced payer negotiation expertise across Germany, France, and Italy.
Market Restraints
- Compliance infrastructure costs:CSO operators must maintain redundant pharmacovigilance systems and promotional material repositories that compress service margins.
- Talent pool concentration:Experienced medical science liaisons cluster in Boston, San Francisco, and Basel, creating wage inflation and recruitment bottlenecks.
- Direct-to-physician digital platforms:Manufacturer-owned tele-detailing tools threaten to disintermediate traditional field-based CSO engagements for routine product education.
Strategic Opportunities
- EU AI Act compliance services:Algorithmic physician targeting and engagement analytics require rebuilt data governance protocols that CSOs can productize as advisory offerings.
- Rare disease commercialization:Ultra-small patient populations and dispersed specialist networks favor outsourced commercial infrastructure over fixed-cost field organizations.
- Outcome-based contracting:Fee structures tied to prescription volume or market share gains align CSO incentives with manufacturer performance metrics.
Industry Challenges
- Representative training latency:Scientific complexity in cell and gene therapies extends onboarding timelines for field forces, delaying campaign launches.
- Legacy CRM integration:CSO-deployed teams must synchronize with manufacturer systems for activity reporting and sample accountability, creating data friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare Contract Sales Organizations Market |
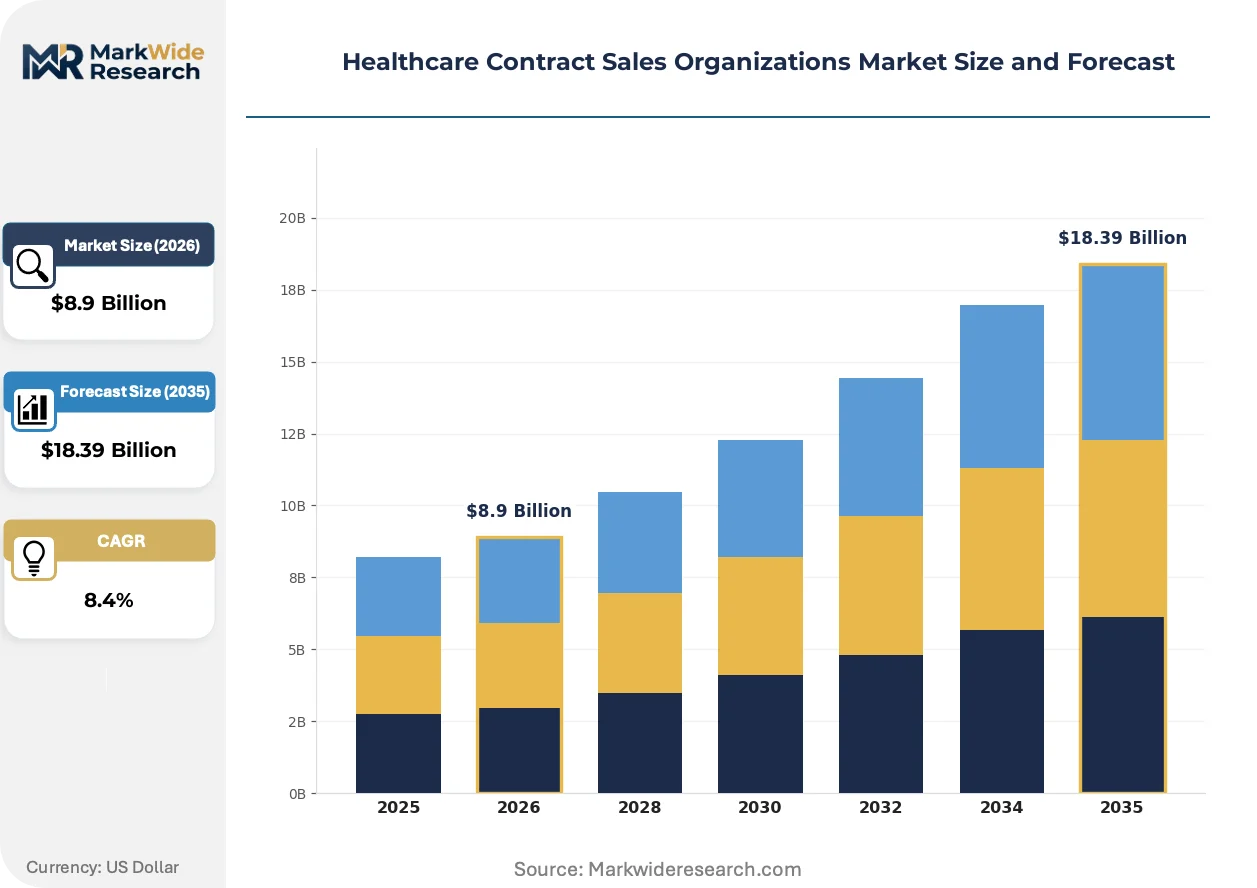
| Market Size in 2026 | $8.9 Billion |
| Market Size in 2035 | $18.39 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Sales Outsourcing, Marketing Services, Regulatory Affairs, Market Access End User: Pharmaceutical Companies, Medical Device Firms, Biotechnology Companies, Diagnostics Organizations Engagement Model: Full-Service Engagement, Project-Based Engagement, Hybrid Model, Dedicated Teams Specialization: Oncology, Cardiovascular, Neurology, Rare Diseases |
| Companies Covered | IQVIA, Syneos Health, Ashfield Medcomms, ICON plc, CMIC HOLDINGS, EPS Corporation, Axxelus, EVERSANA, Publicis Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare Contract Sales Organizations Market Strategic Shifts & Innovations
Digital engagement infrastructure is compressing the traditional field-sales model, replacing face-to-face physician interactions with orchestrated multichannel touchpoints that demand new capability stacks from outsourced providers.
Artificial intelligence is digitizing physician segmentation and message personalization across the CSO value chain. Machine learning models trained on prescription data and clinical encounter records now guide representative prioritization and call planning. Mid-sized biotech sponsors in the United States are adopting these tools fastest, collapsing the cycle time between launch and peak sales velocity.
EMA's Medical Device Regulation is extending outsourcing demand for European market access support. The regulation's strengthened clinical evidence requirements and notified body scrutiny timelines are forcing device manufacturers to externalize reimbursement strategy and health technology assessment navigation. German and French market entry now requires specialized CSO capabilities that few manufacturers maintain in-house.
Physician engagement preferences are fragmenting across channel and timing dimensions. Younger specialists in academic medical centers increasingly favor asynchronous digital content over scheduled in-person detailing, while community practitioners retain higher receptivity to traditional representative visits. This bifurcation is most pronounced in United States oncology networks, where CSOs must deploy hybrid engagement models that blend virtual and field-based touchpoints.
Healthcare Contract Sales Organizations Market Segmentation
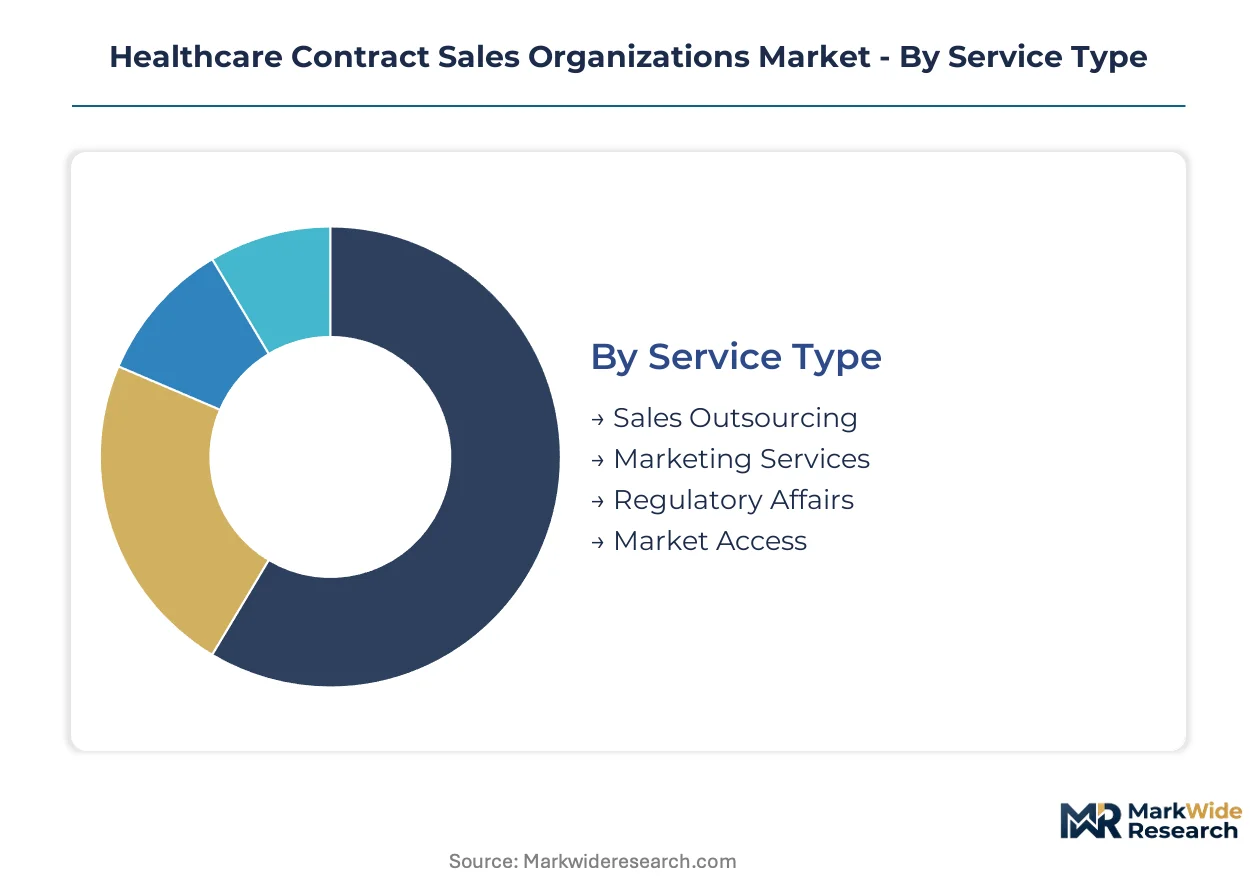
CSO procurement decisions hinge on service modularity, therapeutic complexity, and capital efficiency. Manufacturers match engagement structures to product lifecycle stages and regulatory exposure, creating distinct demand pools across the outsourcing spectrum.
Service Type:
Cost tier determines how pharmaceutical manufacturers externalize commercial functions versus retaining strategic control.
- Sales Outsourcing:Deploys trained field representatives and medical science liaisons under contractual arrangements for physician detailing and sample distribution. United States biotech startups lacking captive commercial infrastructure drive concentrated demand here, with FDA promotional compliance requirements intensifying reliance on specialized third-party operators.
- Marketing Services:Encompasses promotional material development, digital campaign orchestration, and key opinion leader programming. Demand concentrates among mid-sized manufacturers seeking variable-cost alternatives to fixed marketing departments, particularly for multichannel physician engagement.
- Regulatory Affairs:Manages FDA submission support, promotional review, and pharmacovigilance integration for outsourced field forces. This segment addresses liability externalization needs as off-label communication scrutiny tightens.
- Market Access:Delivers payer negotiation, health technology assessment navigation, and reimbursement strategy across fragmented European systems. EMA's Medical Device Regulation and national HTA divergences in Germany, France, and Italy amplify demand.
Sales Outsourcing commands the established base. The steepest expansion runs through Market Access.
End User:
Customer type shapes contract scope, with capital constraints and commercial maturity dictating outsourcing depth.
- Pharmaceutical Companies:Span established multinationals dismantling captive sales infrastructure and specialty firms launching first products. Large manufacturers favor hybrid models preserving strategic control; emerging players require full-service commercialization partnerships.
- Biotechnology Companies:Venture-backed firms without revenue streams represent the fastest-climbing demand trajectory. These sponsors externalize entire commercial functions to preserve runway, with United States clusters in Boston and San Francisco showing highest CSO attachment rates.
- Medical Device Firms:Manufacturers navigating EMA's Medical Device Regulation and notified body scrutiny timelines seek outsourced European market entry support. Reimbursement complexity exceeds in-house capabilities for mid-tier device makers.
- Diagnostics Organizations:Companies commercializing biomarker-driven testing platforms require specialized field forces trained in laboratory and pathology engagement. Demand tracks oncology companion diagnostic launches.
Pharmaceutical Companies anchor contract volume. Biotechnology Companies are climbing the fastest.
Engagement Model:
Maturity of manufacturer commercial infrastructure determines whether relationships assume full delegation or targeted supplementation.
- Full-Service Engagement:Transfers entire commercial responsibility including hiring, training, deployment, and performance management to the CSO. Biotech first-time launchers in the United States adopt this model exclusively, trading margin for speed-to-market and compliance certainty.
- Dedicated Teams:Assigns exclusive representative cohorts to single manufacturers under long-term arrangements. Preserves institutional knowledge and therapeutic specialization while avoiding fixed employment costs.
- Project-Based Engagement:Delivers discrete commercial support for indication expansions, geographic extensions, or competitive defense campaigns. Large pharmaceutical companies deploy this for tactical flexibility.
- Hybrid Model:Blends CSO-deployed resources with manufacturer-retained strategic personnel and systems. Balances external cost efficiency with internal control over messaging and KOL relationships.
Full-Service Engagement holds the revenue base. Hybrid Model adoption is expanding most quickly.
Specialization:
Therapeutic complexity dictates field force training intensity and scientific credential requirements.
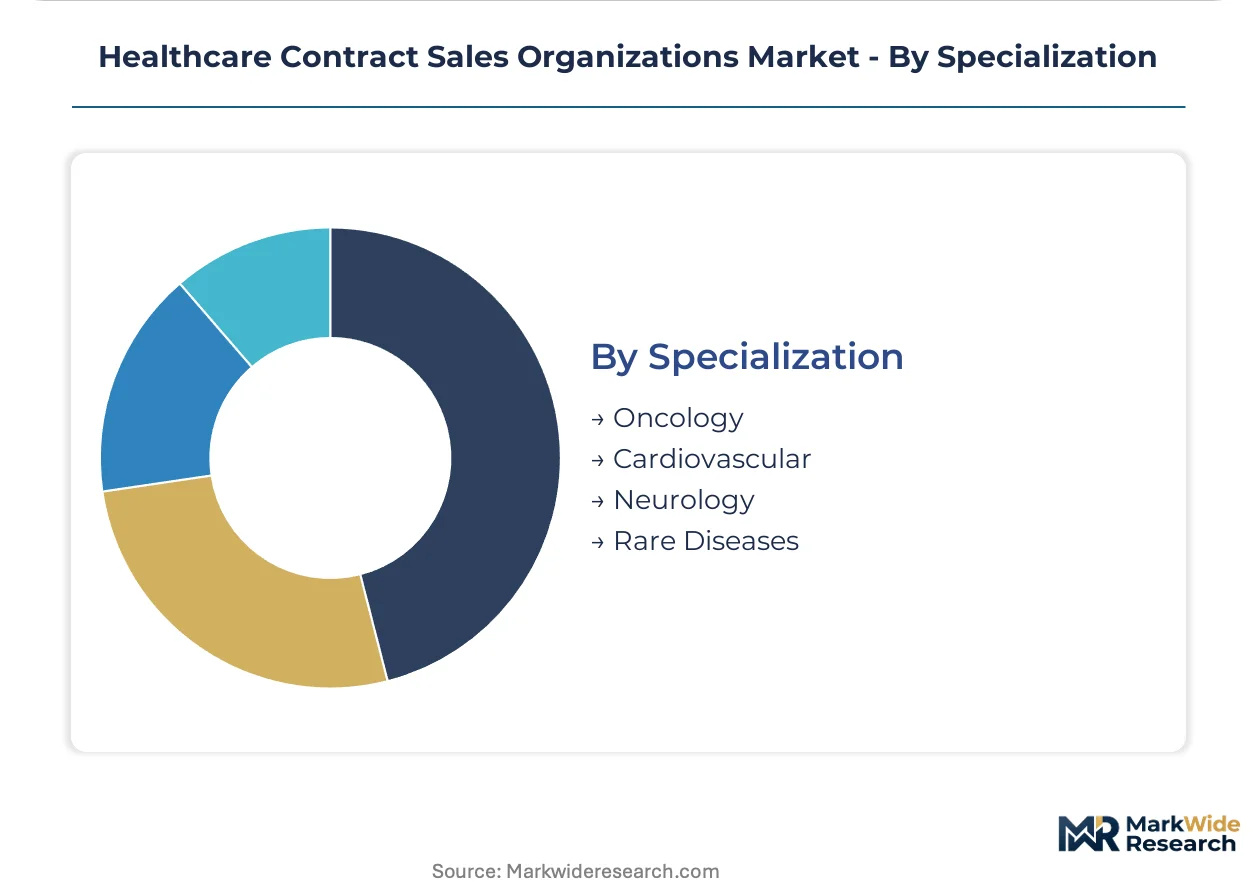
- Oncology:Demands representatives fluent in biomarker-driven prescribing protocols, clinical trial data, and pathology workflows. United States academic medical centers and community oncology networks require distinct engagement approaches, with hybrid virtual-field models gaining traction among younger specialists.
- Rare Diseases:Serves ultra-small patient populations dispersed across geography, favoring outsourced commercial infrastructure over fixed-cost field organizations. Medical science liaisons require deep genetic and mechanistic expertise.
- Neurology:Addresses psychiatrists, neurologists, and movement disorder specialists with products requiring sophisticated adverse event profiling and cognitive outcome communication.
- Cardiovascular:Targets primary care and cardiology networks with established prescribing patterns, permitting faster representative onboarding but demanding formulary navigation expertise.
Oncology dominates current contract value. Rare Diseases shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in healthcare commercial services favor net-importing jurisdictions with concentrated biopharma R&D activity. The United States runs the largest services trade surplus in contract sales, while European markets import specialized market access expertise to navigate fragmented reimbursement systems.
United States
Venture-backed biotech startups in Boston and San Francisco drive concentrated demand for full-service commercialization partnerships. FDA promotional oversight intensifies liability externalization to specialized third-party operators. The Greater Boston cluster anchors oncology-focused CSO deployment, with medical science liaisons clustering around Cambridge biotech corridors.
Germany
EMA's Medical Device Regulation and national HTA divergences create sustained demand for outsourced payer negotiation expertise. The country's statutory health insurance system requires specialized reimbursement navigation that mid-tier device manufacturers rarely maintain in-house. Bavaria and North Rhine-Westphalia concentrate CSO market access operations serving European launch sequences.
Switzerland
Swissmedic's streamlined approval pathways attract multinational manufacturers seeking early European market entry, generating demand for localized commercial infrastructure. Basel's pharmaceutical density supports specialized medical science liaison networks for rare disease portfolios. The country's cantonal healthcare autonomy necessitates regionally tailored field deployment strategies.
Japan
PMDA's stringent promotional material review and pharmacovigilance requirements compel foreign manufacturers to externalize compliance-heavy field operations. The Tokyo-Osaka corridor concentrates demand for hybrid engagement models blending traditional detailing with digital physician platforms. METI's healthcare digitization initiatives accelerate multichannel adoption among domestic CSO operators.
United Kingdom
NICE's health technology assessment processes and post-Brexit regulatory divergence from EMA frameworks sustain demand for specialized market access advisory. London's financial and regulatory hub status attracts CSO advisory functions serving European launch planning. The NHS's centralized procurement creates distinct payer engagement requirements favoring outsourced expertise.
Healthcare Contract Sales Organizations Market Key Industry Players
On the supply side, the industry is consolidating around integrated data platforms and therapeutic specialization vectors. Three distinct strategic archetypes have emerged: full-service commercialization partners, therapeutic-focused specialists, and outcome-based fee innovators. Consolidation through vertical capability acquisition and geographic expansion into European market access services represents the dominant competitive pattern.
Within the integrated platform tier, IQVIA anchors data-driven full-service engagements through its deployment infrastructure. Syneos Health occupies a position exemplifying therapeutic specialization, with rare disease and oncology capabilities concentrated in key biotech clusters. EVERSANA represents outcome-based contracting structures that align fee models with manufacturer performance metrics, situating itself within the value-based services archetype.
| Leading Market Players |
|---|
| IQVIA |
| Syneos Health |
| Ashfield Medcomms |
| ICON plc |
| CMIC HOLDINGS |
| EPS Corporation |
| Axxelus |
| EVERSANA |
| Publicis Health |
| Others |
Cost & Logistics Intelligence
Medical science liaison talent pools in Boston, San Francisco, and Basel concentrate wage costs for CSO operators, pushing margin capture toward outcome-based contracting structures that pharmaceutical manufacturers favor for variable-cost efficiency.
Pricing Analysis
Biotechnology companies lacking captive commercial infrastructure anchor pricing structures around full-service engagement fees that bundle field deployment, compliance infrastructure, and performance guarantees. Three-tier pricing separates premium oncology-specialized teams from standard primary care field forces and economy project-based support tiers. Cost compression in standard-tier services is intensifying because direct-to-physician digital platforms disintermediate routine detailing engagements. Early-stage biotech sponsors show highest price sensitivity, while established pharmaceutical manufacturers prioritize compliance certainty over rate negotiation.
Supply Chain Analysis
Extended payment terms from venture-backed biotech sponsors strain CSO working capital, prompting supply-chain finance facilities that bridge cash flow gaps between campaign launch and milestone-based client payments. Representative talent draws from the United States, Switzerland, and Japan, where regulatory expertise clusters around FDA, Swissmedic, and PMDA compliance frameworks. Training infrastructure and pharmacovigilance systems create single-source vulnerability for smaller operators lacking redundant compliance repositories. Distribution runs through dedicated team deployments that embed CSO personnel within manufacturer CRM systems for activity synchronization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Healthcare Contract Sales Organizations Market functions as a service-attach opportunity where outcome-based contracting layers expand faster than traditional fee-for-service structures, aligning vendor economics with manufacturer prescription volume and market share performance.
For Market Incumbents: Insulate market position by deepening therapeutic specialization in oncology and rare diseases where scientific credentialing creates defensible moats against generalist competitors. Acquire European market access capabilities to capture EMA Medical Device Regulation-driven outsourcing demand from device manufacturers lacking in-house reimbursement expertise. Build redundant pharmacovigilance infrastructure to absorb compliance cost compression without margin erosion.
For New Entrants and Emerging Players: Pursue white-space opportunities in EU AI Act compliance advisory services, where algorithmic physician targeting governance remains underdeveloped among established operators. Target mid-sized medical device manufacturers navigating German and French HTA divergences as the most penetrable client segment. Deploy hybrid engagement models blending virtual and field-based touchpoints as the primary go-to-market angle for younger specialist demographics.
For Investors and Strategic Acquirers: Capital is best deployed toward CSO operators with integrated data platforms and outcome-based fee structures that demonstrate recurring revenue durability across the analysis window. Acquisition targets should combine therapeutic specialization with geographic expansion capability into European market access services. Watch FDA enforcement intensity around off-label communications as the signal indicating accelerated liability externalization demand from risk-averse manufacturers.
| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Services | Rebuilds data governance protocols for algorithmic physician targeting under European artificial intelligence regulation. |
| Oncology Specialization Expansion | Captures biomarker-driven prescribing protocol demand from academic medical centers and community networks. |
| Outcome-Based Contracting Structures | Aligns CSO fee models with manufacturer prescription volume and market share performance metrics. |
| European Market Access Capability Buildout | Addresses EMA Medical Device Regulation reimbursement complexity across German, French, and Italian systems. |
| Hybrid Engagement Model Deployment | Blends virtual and field-based touchpoints for fragmented physician channel preferences in United States oncology. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with CSO executives, pharmaceutical commercialization leads, medical science liaisons, and payer access specialists; and secondary validation through FDA promotional material filings, EMA regulatory submissions, ClinicalTrials.gov protocols, and hospital procurement databases. Bottom-up triangulation across service type, engagement model, and therapeutic specialization dimensions anchored volume estimates, while top-down cross-checks against disclosed contract values refined revenue projections.
Forecast inputs considered biomarker-driven oncology protocol expansion, FDA promotional oversight enforcement trends, and European HTA fragmentation across the projection horizon. Segmentation modeling captured service modularity, therapeutic complexity, and capital efficiency dimensions alongside regional regulatory cluster variations. CAGRs derived from historical outsourcing penetration rates and forward-looking biotech venture financing patterns across the analysis window.
Sensitivities concentrate around regulatory enforcement intensity, digital platform disintermediation velocity, and talent pool wage inflation in concentrated geographic clusters. Forecasts reflect assumptions regarding sustained biotech capital constraints and compliance liability externalization preferences. Macroeconomic tightening in venture financing, accelerated FDA enforcement actions, or breakthrough digital engagement platform adoption would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Consulting
Healthcare ERP Consulting Services Market
Healthcare Consulting
Healthcare Regulatory Affairs Outsourcing Market
Healthcare Consulting
Pharmaceutical Regulatory Affairs Market
Healthcare Consulting
Global Regulatory Affairs Market
Healthcare Consulting
UK Healthcare Consulting Market
Healthcare Consulting
Consulting Service Market
Healthcare Consulting
Italy Operations Service Consulting Market
Healthcare Consulting
Global Healthcare Consulting Services Market
Healthcare Consulting
Europe Medical Device Regulatory Affairs Outsourcing Market
Healthcare Consulting
Africa Pharmaceutical Regulatory Affairs Market
Healthcare Consulting
Global Strategic Consulting Services Market
Healthcare Consulting
Global Public Sector Consulting and Advisory Services Market
Healthcare Consulting
Global Healthcare IT Consulting Market
Healthcare Consulting
Global Medical Device Regulatory Affairs Outsourcing Market