
 Global Healthcare Services Market | 2026-2036
Global Healthcare Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global Healthcare Services Market Analysis
Subscription-based care coordination is recalibrating how providers monetize longitudinal patient relationships. UnitedHealth Group leverages its Optum platform to integrate pharmacy benefits with medical management. CVS Health anchors community-based delivery through retail clinic networks and payer partnerships. Mayo Clinic sustains premium positioning via destination specialty care and intellectual property licensing.
Healthcare services encompass the organized provision of preventive, curative, rehabilitative, and palliative interventions delivered by licensed professionals across facility and non-facility settings, typically measured by patient encounters, bed-days, or covered lives. The primary purpose is maintaining population health while managing per-capita expenditure through risk-pooled financing and outcome-based reimbursement. Home Healthcare and Telemedicine command accelerating capital allocation as reimbursement parity expands and remote monitoring infrastructure matures. Diagnostic Services retains margin concentration due to capital intensity and proprietary testing protocols. AI Diagnostics within the Technology dimension is attracting venture funding for algorithmic triage and imaging interpretation.
FDA digital health guidance and CMS reimbursement rules shape US market access for software-enabled services. EMA's Medical Device Regulation and GDPR compliance requirements constrain European telemedicine platform deployment. Japan's PMDA and METI promote standardization of wearable-derived clinical data. Stakeholders must monitor regulatory divergence between jurisdictions to avoid fragmented compliance architectures and duplicated validation costs.
Market Dynamics
Reimbursement parity between virtual and in-person care is dismantling facility-centric revenue models and redistributing capital toward remote monitoring infrastructure and algorithmic triage platforms.
Growth Catalysts
- CMS reimbursement parity mandates:Medicare's expansion of telehealth coverage codes is accelerating provider investment in remote patient monitoring platforms across the United States.
- Japan METI wearable standardization:METI's clinical data interoperability protocols are enabling cross-platform integration of consumer health devices into formal care pathways.
- Home-based acute care:Hospital-at-home programs are capturing high-acuity episodes previously confined to inpatient settings, driven by capitated risk arrangements.
Market Restraints
- EMA MDR compliance costs:Software-as-medical-device reclassification under the EU Medical Device Regulation is imposing validation burdens that delay European market entry for AI diagnostic tools.
- Specialized nursing labor scarcity:Home health agencies face recruitment bottlenecks for licensed practical nurses in rural United States markets.
- Legacy EHR interoperability gaps:Proprietary data formats between Epic and Cerner systems create friction in care coordination networks.
Strategic Opportunities
- Brazil's SUS digitization:The national health system's telemedicine infrastructure buildout creates procurement windows for remote consultation platforms.
- FDA breakthrough device designation:Expedited review pathways for AI diagnostic algorithms are compressing time-to-revenue for software developers.
- Germany's DiGA fast-track:The BfArM's digital health application approval process is creating a reimbursable channel for prescription software.
Industry Challenges
- Algorithmic bias validation:Demonstrating equitable performance across demographic subgroups in FDA submissions requires expanded clinical trial designs.
- Cross-border data governance:GDPR health data localization requirements conflict with cloud-based AI training pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Healthcare Services Market |
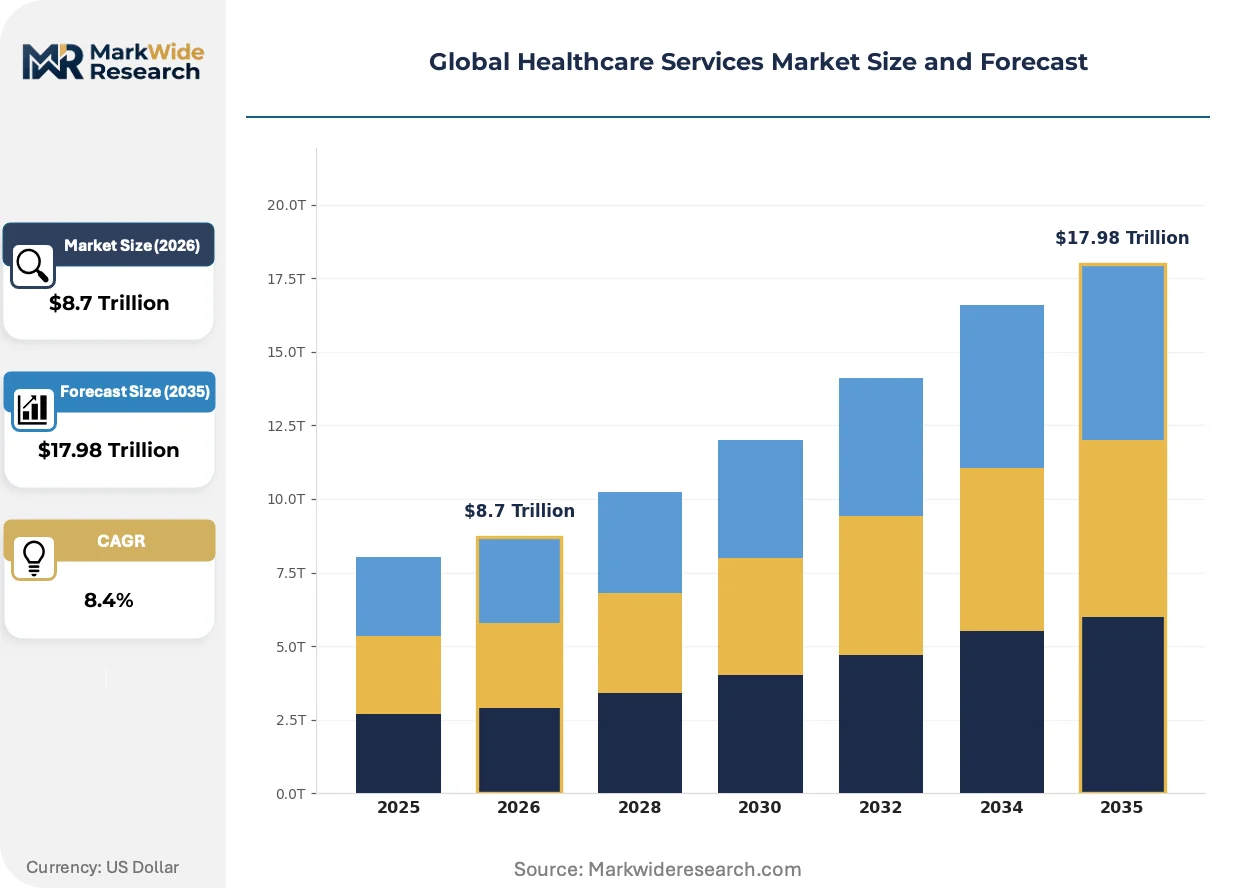
| Market Size in 2026 | $8.7 Trillion |
| Market Size in 2035 | $17.98 Trillion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Home Healthcare, Diagnostic Services, Telemedicine, Rehabilitation Services Delivery Model: Private Clinics, Public Hospitals, ACOs, Remote Monitoring End User: Individuals, Healthcare Providers, Payers, Organizations Technology: Wearables, Mobile Health Apps, Electronic Health Records, AI Diagnostics |
| Companies Covered | Centene, Molina Healthcare, UnitedHealth Group, Mayo Clinic, CVS Health, Elevance Health, Cigna, Northwell Health, Humana, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Healthcare Services Market Emerging Trajectories
Clinical artificial intelligence is fragmenting diagnostic expertise into discrete, reimbursable software components that challenge traditional radiology and pathology practice economics.
Machine learning-based imaging interpretation is modularizing radiologist workflows into pre-screening, flagging, and measurement tasks. Academic medical centers in the United States are deploying FDA-cleared algorithms for intracranial hemorrhage detection and mammography triage. This modularization is compressing turnaround times for emergent reads while reallocating specialist attention toward complex cases.
EMA's Medical Device Regulation is reclassifying clinical decision support software as Class IIa or higher medical devices. Manufacturers must now submit clinical evidence and quality management documentation previously exempted under legacy directives. German and French notified bodies are experiencing backlog-induced delays that favor larger developers with dedicated regulatory affairs functions.
Subscription-based care coordination is displacing fee-for-service billing in Medicare Advantage contracts. United States-based payers are bundling pharmacy benefits, remote monitoring, and nurse navigation into per-member-per-month arrangements. This shift concentrates procurement authority with payer medical management departments rather than individual physician practices.
Global Healthcare Services Market Segmentation
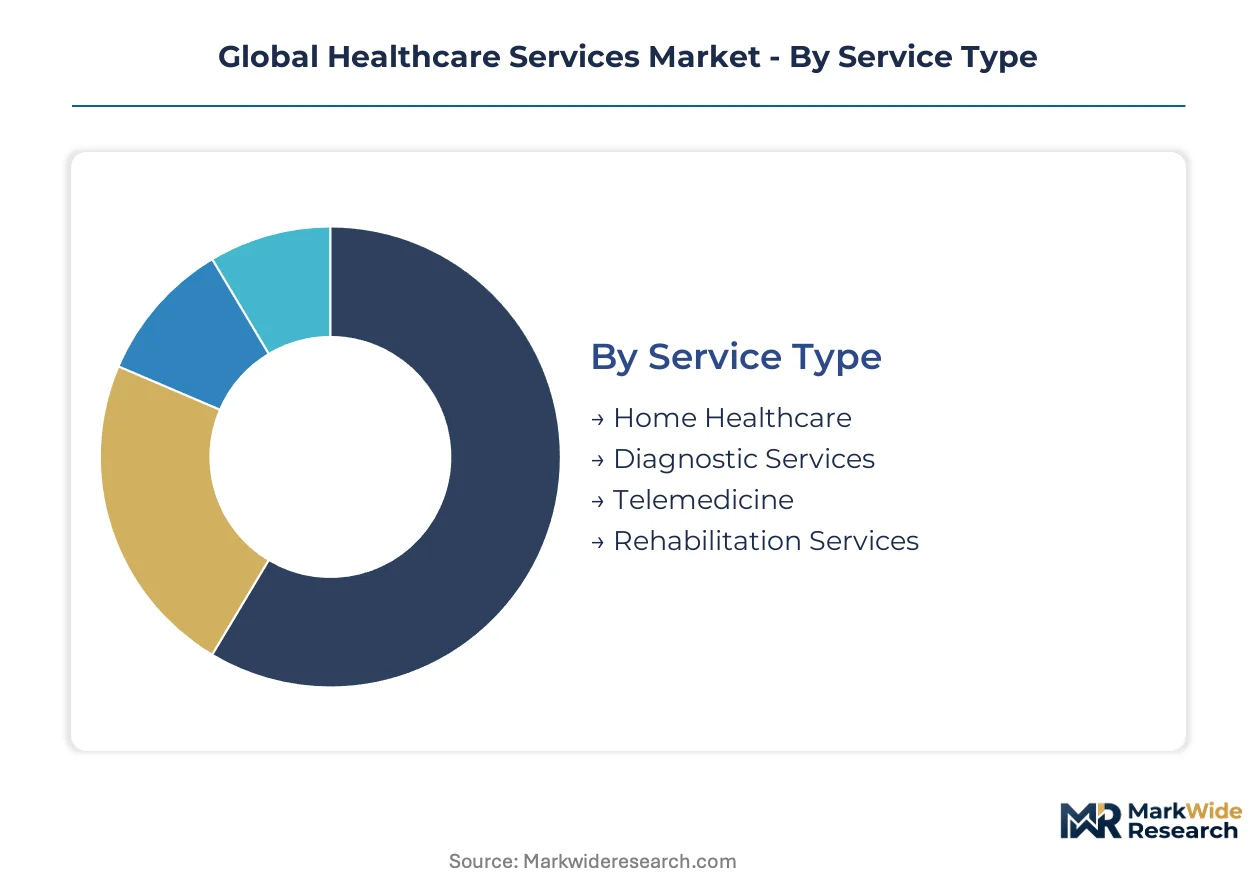
Segmentation in healthcare services reveals how capital allocation and regulatory frameworks diverge across intervention modalities. Understanding these partitions exposes where reimbursement parity, technology integration, and workforce constraints create divergent margin structures.
Service Type:
Technology intensity and site-of-care migration define competitive positioning across intervention categories.
- Home Healthcare:Skilled nursing, infusion therapy, and wound care delivered in residential settings. Demand concentrates in post-acute transitions among aging populations in Germany and Japan, constrained by licensed practical nurse scarcity in rural United States markets.
- Diagnostic Services:Laboratory testing, imaging, and pathology delivered through centralized and point-of-care infrastructure. Capital intensity and proprietary testing protocols sustain margin concentration in academic medical centers and reference laboratories.
- Telemedicine:Synchronous and asynchronous clinical consultation via video, audio, or messaging platforms. CMS reimbursement parity mandates are accelerating platform investment across Medicare Advantage contracts.
- Rehabilitation Services:Physical, occupational, and speech therapy delivered across inpatient, outpatient, and home-based settings. Payer bundling into post-acute episodes is compressing standalone facility economics.
Diagnostic Services leads on scale; Telemedicine leads on momentum.
Delivery Model:
Capital deployment patterns track risk-bearing arrangements and facility ownership structures.
- Private Clinics:Physician-owned or investor-backed ambulatory facilities delivering specialty and primary care. United States dermatology and orthopedics platforms are consolidating through private equity roll-ups.
- Public Hospitals:Government-operated acute and specialty facilities serving safety-net populations. Brazil's SUS digitization is creating procurement windows for telemedicine infrastructure integration.
- ACOs:Accountable Care Organizations bearing capitated risk for attributed patient populations. Medicare Shared Savings Program participation is driving EHR interoperability investments.
- Remote Monitoring:Continuous physiologic surveillance via connected devices and algorithmic triage. METI's wearable standardization protocols in Japan are enabling cross-platform clinical data integration.
Public Hospitals anchors volume; Remote Monitoring captures the steepest expansion trajectory.
End User:
Purchasing authority fragmentation shapes contract structure and sales cycle duration.
- Individuals:Direct-pay consumers accessing wellness, cosmetic, and concierge services. High-deductible health plan proliferation is expanding price transparency tool adoption.
- Healthcare Providers:Hospitals, clinics, and physician practices procuring outsourced services and technology. Epic and Cerner interoperability gaps create friction in care coordination network formation.
- Payers:Insurance carriers and government programs managing population health expenditure. UnitedHealth Group's Optum platform exemplifies vertical integration of pharmacy benefits with medical management.
- Organizations:Self-insured employers and government agencies purchasing occupational health and wellness programs. CVS Health's retail clinic networks target this channel through community-based delivery.
Payers concentrate procurement authority; Individuals are gaining share fastest.
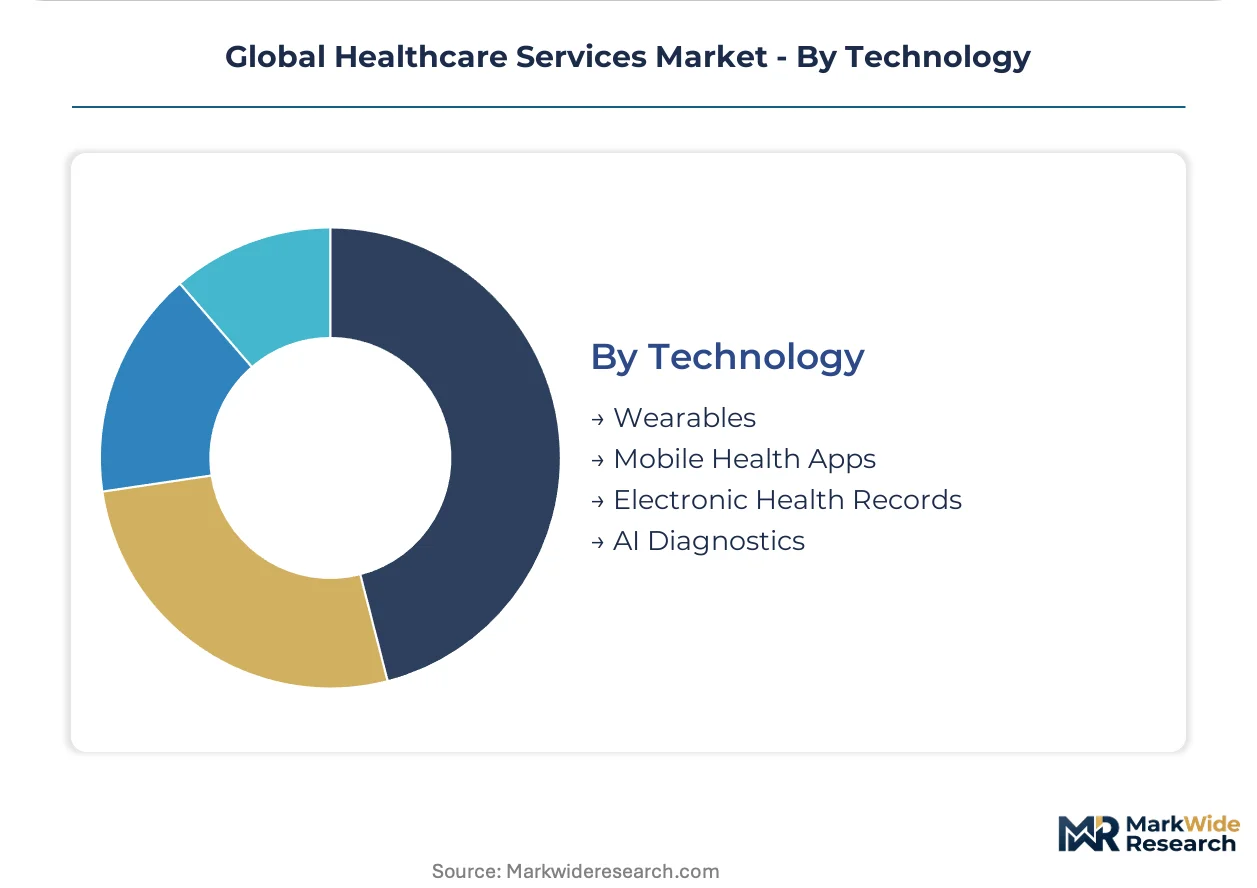
Technology:
Regulatory classification and clinical validation requirements segment investment risk profiles.
- Wearables:Consumer and medical-grade devices capturing physiologic data for clinical decision support. PMDA and METI standardization efforts in Japan are formalizing wearable-derived data pathways.
- Mobile Health Apps:Software applications for medication adherence, symptom tracking, and patient education. Germany's BfArM DiGA fast-track is creating reimbursable prescription channels.
- Electronic Health Records:Clinical documentation and interoperability platforms enabling care coordination. Legacy proprietary data formats between dominant vendors impede network formation.
- AI Diagnostics:Machine learning algorithms for imaging interpretation, risk stratification, and triage. FDA breakthrough device designation pathways are compressing time-to-revenue for algorithm developers.
Electronic Health Records dominates installed base; AI Diagnostics leads on venture funding velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's DiGA fast-track creates reimbursable digital health channels faster than Japan's wearable standardization protocols mature, while Brazil's public system digitization lags both on procurement sophistication.
United States
Medicare Advantage enrollment expansion and CMS telehealth parity mandates drive outpatient migration. FDA breakthrough device designation accelerates AI diagnostic commercialization. Mayo Clinic anchors destination specialty care in Rochester, Minnesota, while CVS Health scales retail clinic networks across metropolitan markets.
Germany
Hospital-at-home program adoption and post-acute care bundling reshape service delivery economics. BfArM's DiGA fast-track creates prescription reimbursement pathways for digital therapeutics. Berlin-Brandenburg clusters telemedicine platform development alongside established pharmaceutical research infrastructure.
Japan
Aging demographics concentrate demand in home-based skilled nursing and remote monitoring services. METI wearable standardization protocols enable consumer device data integration into clinical workflows. Kanto region hospitals in Tokyo deploy PMDA-aligned AI imaging tools for workforce augmentation.
Brazil
SUS digitization creates procurement windows for telemedicine infrastructure in underserved regions. ANVISA regulatory harmonization with IMDRF standards accelerates software-as-medical-device approvals. São Paulo anchors private health plan innovation while Minas Gerais tests rural connectivity solutions.
United Kingdom
NHS Long Term Plan targets shift elective procedures toward community-based settings. MHRA recognition of FDA-cleared AI diagnostics streamlines market access for algorithmic triage tools. London's academic medical centers concentrate digital health venture funding alongside Manchester's devolved health system pilots.
Global Healthcare Services Market Vendor Landscape
Top-tier vendors anchor integrated payer-provider platforms, while mid-tier specialists compete on geographic density and service-line focus. The vendor base stratifies across three tiers: national payers with captive care delivery, regional health systems with specialty destination positioning, and technology-enabled service platforms. Dominant competitive moves include vertical integration of pharmacy benefits with medical management and consolidation of physician practices into platform networks.
Among US-based integrated enterprises, UnitedHealth Group, CVS Health, and Mayo Clinic exemplify three distinct archetypes. UnitedHealth Group occupies the payer-led integration position through its Optum platform. CVS Health represents the retail-anchored community access model. Mayo Clinic sits within the academic medical center tier, sustaining premium positioning through intellectual property licensing and destination specialty concentration. These three entities illustrate how reimbursement model shifts favor scale and coordination capabilities over standalone service delivery.
| Leading Market Players |
|---|
| Centene |
| Molina Healthcare |
| UnitedHealth Group |
| Mayo Clinic |
| CVS Health |
| Elevance Health |
| Cigna |
| Northwell Health |
| Humana |
| Others |
Supply Flow & Price Mechanics
Licensed practical nurse concentration in rural United States markets widens pricing-tier spreads between premium home health agencies and economy-tier providers, as labor-cost differentials compound reimbursement rate variations across Medicare Advantage contracts.
Pricing Analysis
Capacity additions in Brazil's SUS telemedicine infrastructure are reshaping price floors for remote consultation platforms. Three-tier pricing structure across premium concierge, standard insured, and economy direct-pay levels separates Mayo Clinic's destination specialty positioning from CVS Health's retail-access tier. Price differentiation hinges on certification level—FDA breakthrough device designation commands premium algorithm licensing—and geographic delivery cost. Pricing pressure stems from CMS reimbursement parity mandates compressing virtual visit margins. Direct-pay individuals exhibit highest price sensitivity; payer medical management departments demonstrate lowest sensitivity due to bundled per-member-per-month arrangements.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for semiconductor components in wearable devices and remote monitoring hardware. The supply chain draws from Germany for precision diagnostic equipment, India for pharmaceutical API inputs, and China for consumer-grade device manufacturing. Raw material dependencies include lithium-ion battery cells, medical-grade sensors, and cloud computing infrastructure. Tariff exposure on Chinese-manufactured hardware creates procurement risk for platform developers. Distribution runs through GPO contracts for hospital systems, direct sales for payers, and retail pharmacy networks for consumer-facing services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, justified by demand-shift toward AI-augmented diagnostic specifications that reward clinical validation depth over speed-to-market.
For Market Incumbents: Deploy backward integration into remote monitoring hardware manufacturing to capture device-margin pools currently leaking to third-party suppliers. UnitedHealth Group's Optum platform exemplifies channel control through pharmacy-medical benefit integration. Defensive consolidation targets include home health agencies in rural United States markets facing nursing scarcity. Certification investment in FDA breakthrough device pathways protects against algorithm commoditization by venture-funded entrants.
For New Entrants and Emerging Players: The price-point gap between premium academic medical center pricing and economy-tier retail clinic rates creates white-space opportunity for mid-market platform plays. Brazil's SUS digitization represents the most penetrable geography, with procurement windows for telemedicine infrastructure in underserved Minas Gerais regions. Germany's DiGA fast-track offers the most favorable go-to-market angle, converting prescription software into reimbursable channels faster than FDA pathways.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional health systems with specialty destination positioning but underdeveloped digital infrastructure. Long-term viability over the coming decade hinges on successful migration from fee-for-service to capitated risk-bearing arrangements. Target acquisition archetype: home health platforms with licensed practical nurse training pipelines and established Medicare Advantage contracts. The signal to watch is CMS expansion of hospital-at-home reimbursement codes as inflection indicator for acute-care decentralization.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Submission | Expedited review compresses time-to-revenue for AI diagnostic algorithms seeking Medicare coverage. |
| Hospital System Partnership | Mayo Clinic's destination specialty model demonstrates premium positioning through intellectual property licensing. |
| Software Companion Development | DiGA fast-track in Germany creates reimbursable prescription channels for digital therapeutic applications. |
| Reimbursement Strategy | CMS telehealth parity mandates redistribute capital toward remote monitoring infrastructure investment. |
| CE Marking Pathway | EMA MDR compliance costs favor larger developers with dedicated regulatory affairs functions over mid-tier entrants. |
Methodological Framework
Coverage spans the United States, Germany, Japan, Brazil, and the United Kingdom, with primary inputs from each market informing cross-border pattern identification. The approach combines structured interviews with hospital purchasing committees, GPO contracts managers, payer medical management directors, and biomedical engineers with secondary validation against CMS Medicare data, FDA 510(k) filings, EMA MDR submission databases, and hospital procurement records. Bottom-up service-line modeling and top-down macroeconomic triangulation anchor volume and value estimates.
Granularity-level framing applies service-type segmentation at the country level, delivery-model splits at the regional cluster level, and technology adoption curves at the metropolitan statistical area level. Modeled dimensions include intervention modality, site-of-care migration, risk-bearing arrangement type, and regulatory approval pathway. CAGRs derive from patient encounter volume projections, reimbursement rate trajectories, and capital allocation patterns across the analysis window. Forecast inputs incorporate METI wearable standardization timelines and ANVISA harmonization progress with IMDRF standards.
Caveats apply where EMA MDR backlog delays, GDPR health data localization conflicts with cloud-based AI training, or algorithmic bias validation requirements could materially shift the outlook. Forecasts reflect assumptions about reimbursement parity sustainability and workforce supply elasticity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Hospital Resource Management Market
Healthcare Services
US Biopharmaceutical Third-Party Logistics Market
Healthcare Services
Funeral Products and Services Market
Healthcare Services
Ambulatory Healthcare Service Market
Healthcare Services
Global Retirement Home Services Market
Healthcare Services
Global Healthcare Provider Network Management Market
Healthcare Services
Contract Manufacturing Services Market
Healthcare Services
Medical Waste Disposal Services Market
Healthcare Services
Medically Supervised Weight Loss Services Market
Healthcare Services
Global Offsite Medical Case Management Market
Healthcare Services
Western Europe Medical Recruitment Market
Healthcare Services
US Integrated Delivery Network Market
Healthcare Services
Global Cord Blood Banking Services Market
Healthcare Services
Global Value Based Healthcare Services Market
Healthcare Services
US Medical Billing Outsourcing Market
Healthcare Services
United States Pharmaceutical Logistic Services Market