
 Inhaled and Intranasal Products Contract Service Providers Market | 2026-2036
Inhaled and Intranasal Products Contract Service Providers Market Size, Share, and Industry Trends Forecast 2026-2036
Inhaled and Intranasal Products Contract Service Providers Market Intelligence
Buyer concentration among large pharmaceutical sponsors is recalibrating procurement leverage across the contract services landscape. Catalent, Inc. leverages integrated development-to-commercial platforms to anchor long-term client relationships. Quotient Sciences competes through rapid integrated formulation and clinical testing cycles. Recipharm AB specializes in sterile respiratory manufacturing across European and North American facilities.
Inhaled and intranasal products contract service providers deliver outsourced development, manufacturing, and analytical services for drug-device combinations targeting pulmonary and nasal mucosal delivery, typically requiring particle engineering below five micrometers and validated aseptic processing. Their primary commercial purpose is enabling pharmaceutical sponsors to access specialized respiratory expertise without captive capital investment. Formulation Development captures premium margins due to complex physicochemical characterization requirements for lung deposition. Manufacturing scales through multi-client inhaler and nebulizer assembly lines. Nasal Sprays lead product type demand, driven by expanding migraine and vaccine delivery applications.
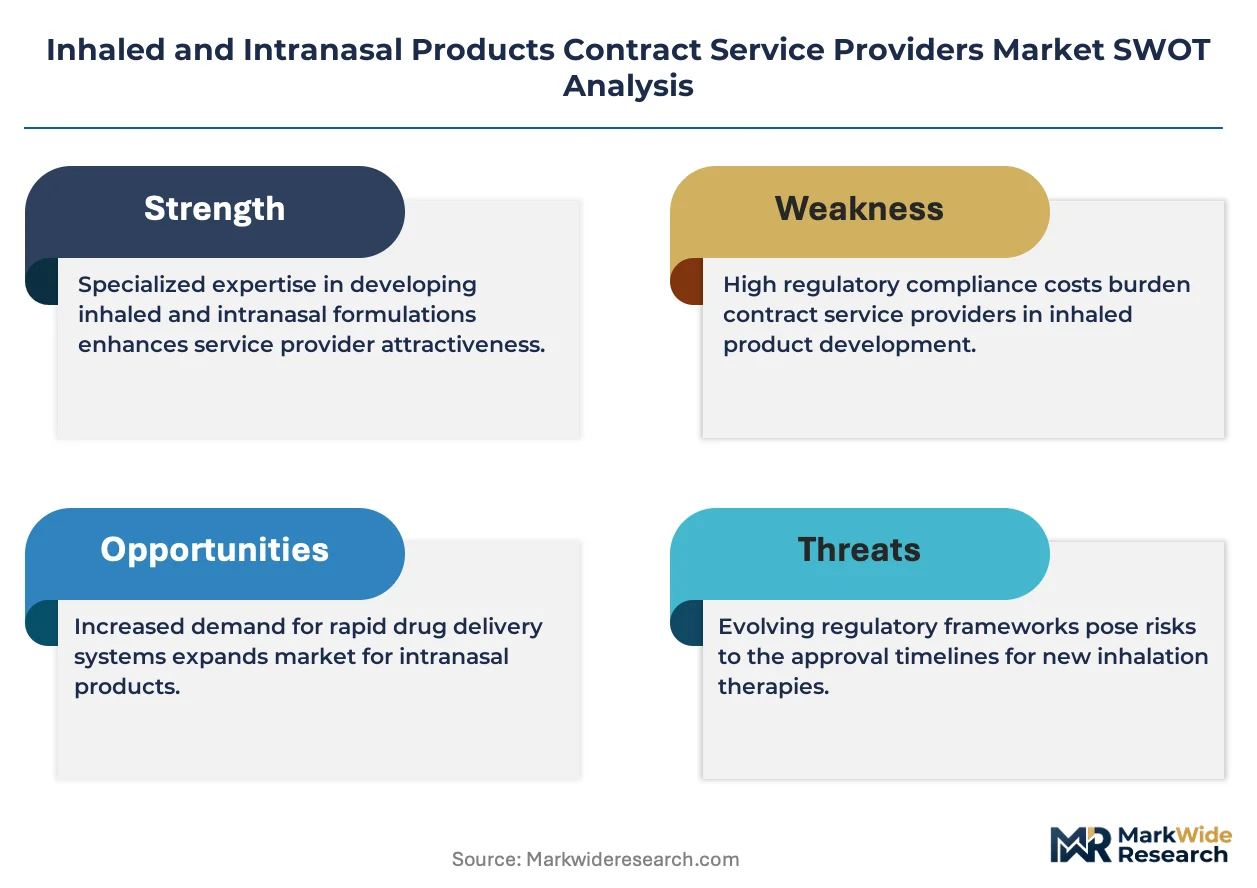
FDA quality standards for orally inhaled and nasal drug products shape bioequivalence study designs and device bridging requirements for generic entrants. EPA regulations govern propellant transitions in metered-dose inhalers, forcing reformulation investments across contractor networks. EMA and national European regulators enforce Good Manufacturing Practice Annex 1 updates for sterile respiratory products. Stakeholders must monitor evolving device-agnostic platform strategies as regulators tighten interchangeability standards for complex drug-device combinations.
Market Dynamics
Biotech sponsors are consolidating development partnerships around integrated respiratory platforms, forcing contract providers to bundle particle engineering, device assembly, and regulatory filing capabilities under single accountability structures.
Growth Catalysts
- Generic Inhaler Approvals:The FDA's evolving bioequivalence pathways for complex drug-device combinations are expanding the addressable pipeline for contract analytical and clinical services.
- Propellant Transition Mandates:EPA regulations phasing out hydrofluorocarbon propellants in metered-dose inhalers are triggering reformulation projects across contractor networks.
- Vaccine Intranasal Delivery:Pandemic-era investments in mucosal immunization platforms are sustaining demand for sterile nasal spray manufacturing capacity.
Market Restraints
- Specialized Equipment Costs:Next-generation cascade impactors and laser diffraction systems for particle size distribution analysis require seven-figure capital commitments.
- Single-Source Device Dependencies:Proprietary inhaler platform technologies concentrate supply risk with a limited pool of European and North American licensors.
- Bridging Study Complexity:The FDA's device-agnostic platform requirements for generic substitution are extending development timelines and freezing sponsor commitments.
Strategic Opportunities
- Gene Therapy Pulmonary Delivery:Lipid nanoparticle formulations for cystic fibrosis and primary ciliary dyskinesia are opening high-margin development partnerships.
- India Manufacturing Expansion:CDSCO's streamlined approval pathways for inhaled generics are attracting facility investments to serve domestic and export markets.
- Continuous Manufacturing Adoption:Real-time release testing integration with powder blending operations is compressing batch release cycles for multi-client respiratory lines.
Industry Challenges
- Aseptic Processing Workforce:Qualified personnel for isolator-based filling and environmental monitoring remain scarce relative to sterile respiratory capacity expansion plans.
- Device-Drug Master File Alignment:Sponsors and contract providers face coordination friction when proprietary inhaler designs require simultaneous updates to drug and device regulatory submissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Inhaled and Intranasal Products Contract Service Providers Market |
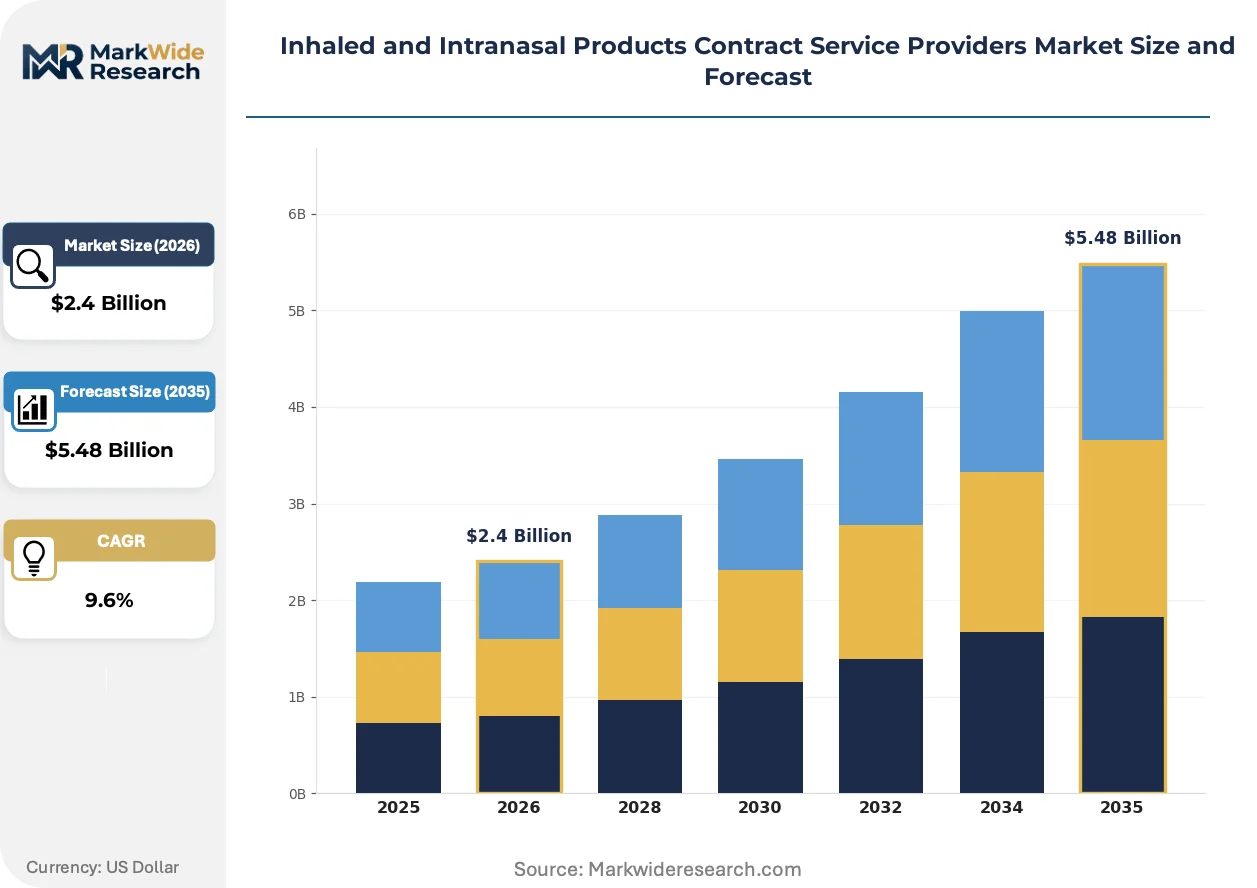
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.48 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Formulation Development, Manufacturing, Packaging, Quality Control Product Type: Nasal Sprays, Inhalers, Powder Inhalation, Nebulizers End User: Pharmaceutical Companies, Biotech Firms, Research Institutions, Contract Manufacturers Delivery Mode: Direct Delivery, Self-Administration, In-Clinical Administration, Home Use |
| Companies Covered | Recipharm AB, Quotient Sciences, Catalent, Inc., Colep Healthcare, Beximco Pharmaceuticals Ltd., Lonza Group, Hovione, Aptar Pharma, Kindeva Drug Delivery, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Inhaled and Intranasal Products Contract Service Providers Market Strategic Shifts & Innovations
Dry powder inhaler platforms are converging with connected health ecosystems, embedding sensors and data transmission modules that transform dosing adherence from a clinical variable into a monetizable service layer.
Engineered porous particles produced by spray-drying are absorbing the functional requirements previously addressed by lactose carrier blends, enabling simpler formulations with improved lung deposition efficiency. Biotech sponsors developing biologic therapies for pulmonary delivery are adopting these excipient-free architectures to reduce immunogenicity risk. The shift is absorbing development capacity at specialized particle engineering facilities and compressing timelines for first-in-human respiratory studies.
The EPA's Significant New Alternatives Policy program is accelerating hydrofluorocarbon propellant phase-outs in pressurized metered-dose inhalers, forcing reformulation investments across contract manufacturing networks. European contract providers face parallel pressure from the EU F-Gas Regulation's tightening quotas on fluorinated greenhouse gases. Generic sponsors are responding by prioritizing dry powder and soft mist alternatives that circumvent propellant chemistry entirely.
Large pharmaceutical sponsors are consolidating preferred provider agreements around full-service respiratory platforms that span preformulation through commercial supply. Mid-cap biotech firms are displacing fragmented sourcing models with single-accountability partnerships that bundle device selection, stability testing, and regulatory strategy. The concentration is most visible in the United States, where complex respiratory pipelines and specialized CDMO infrastructure cluster in the Boston-Cambridge and Research Triangle corridors.
Inhaled and Intranasal Products Contract Service Providers Market Segmentation
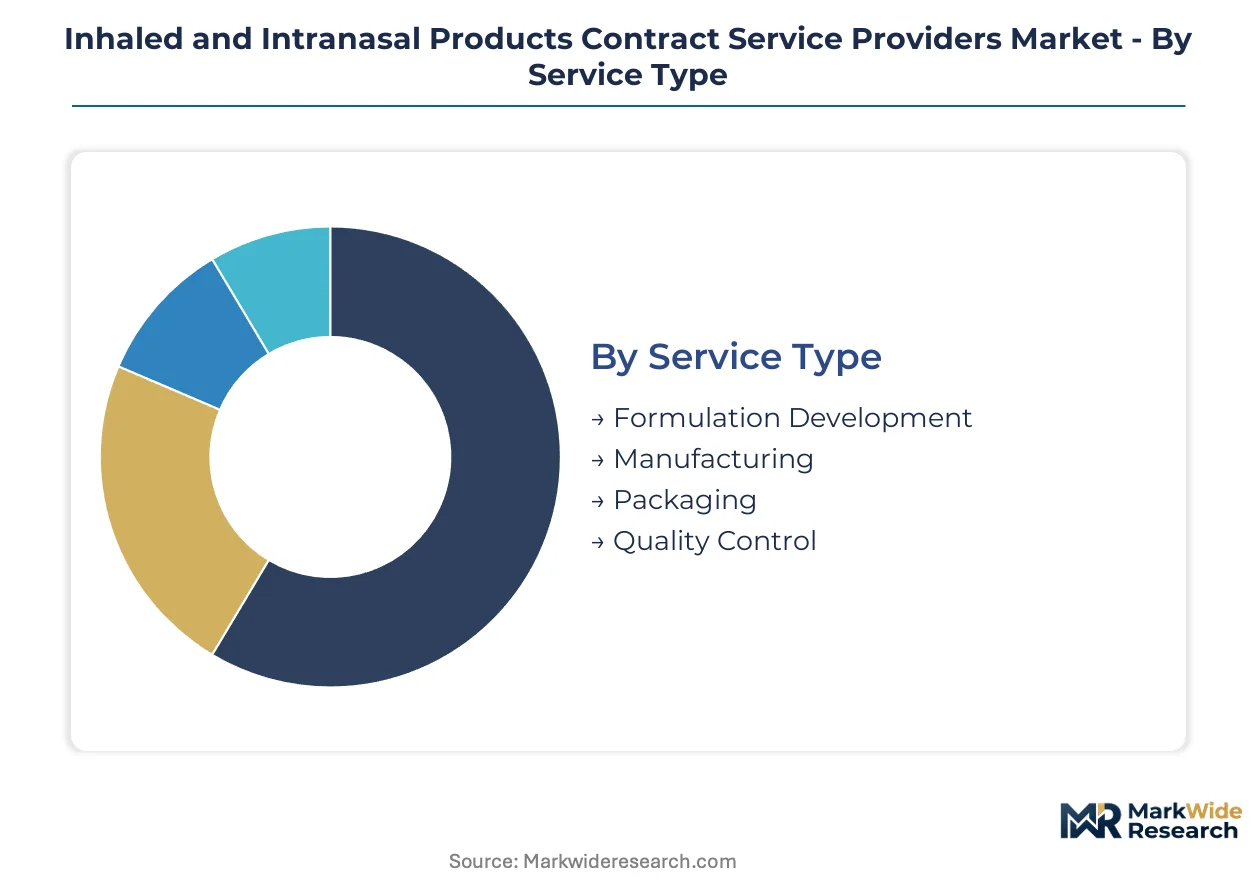
Segmentation in the inhaled and intranasal contract services market reveals how specialized capabilities align with distinct sponsor risk profiles and regulatory pathways. Service providers structure their offerings around the technical intensity of particle engineering, device integration complexity, and the sterility requirements that separate preclinical feasibility from commercial-scale respiratory manufacturing.
Service Type:
Particle engineering sophistication and aseptic processing validation define the capability tiers that sponsors evaluate when outsourcing respiratory development.
- Formulation Development:Spray-drying, jet milling, and cascade impaction characterization for lung deposition optimization absorb the highest margins in the contract services portfolio. Demand concentrates among mid-cap biotech firms in the United States seeking to compress timelines for first-in-human respiratory studies.
- Manufacturing:Multi-client inhaler and nebulizer assembly lines scale through isolator-based filling and real-time release testing integration. Capacity expansion is accelerating in India as CDSCO streamlines approval pathways for inhaled generics serving domestic and export markets.
- Packaging:Device-assembly and secondary packaging for drug-device combinations requires alignment with proprietary inhaler platform technologies. Sponsors face coordination friction when device master files require simultaneous updates to drug regulatory submissions.
- Quality Control:Next-generation cascade impactors and laser diffraction systems for particle size distribution analysis demand seven-figure capital commitments that concentrate analytical capacity among established providers.
Mature deployment sits with Manufacturing. Newer deployment is concentrated in Formulation Development.
Product Type:
Device architecture and propellant chemistry create divergent outsourcing requirements across respiratory delivery platforms.
- Nasal Sprays:Sterile aqueous and powder formulations for migraine therapeutics and mucosal vaccine delivery command dedicated manufacturing suites. Applications are expanding fastest in vaccine intranasal platforms sustained by pandemic-era immunization investments.
- Inhalers:Pressurized metered-dose devices face EPA-mandated hydrofluorocarbon propellant phase-outs forcing reformulation projects across contract networks. European providers face parallel pressure from EU F-Gas Regulation tightening quotas on fluorinated greenhouse gases.
- Powder Inhalation:Engineered porous particles produced by spray-drying are absorbing functional requirements previously addressed by lactose carrier blends. Biologic therapy developers adopt these excipient-free architectures to reduce immunogenicity risk in cystic fibrosis indications.
- Nebulizers:Continuous manufacturing adoption with real-time release testing integration is compressing batch release cycles for multi-client respiratory lines serving hospital and home care segments.
Established volume sits with Inhalers. Steepest expansion trajectory belongs to Powder Inhalation.
End User:
Capital constraints and pipeline complexity determine whether sponsors access respiratory expertise through fragmented sourcing or integrated platform partnerships.
- Pharmaceutical Companies:Large sponsors consolidate preferred provider agreements around full-service respiratory platforms spanning preformulation through commercial supply. Procurement leverage is recalibrating as buyer concentration intensifies among top-tier sponsors.
- Biotech Firms:Mid-cap developers displace fragmented sourcing with single-accountability partnerships bundling device selection, stability testing, and regulatory strategy. Gene therapy pulmonary delivery programs for primary ciliary dyskinesia are opening high-margin development partnerships.
- Research Institutions:Academic pulmonary delivery programs access specialized particle engineering through fee-for-service arrangements without captive capital investment in isolator infrastructure.
- Contract Manufacturers:CDMO-to-CDMO subcontracting addresses capacity bottlenecks in sterile respiratory filling during sponsor pipeline surges.
Dominant procurement volume sits with Pharmaceutical Companies. Fastest partnership formation is occurring with Biotech Firms.
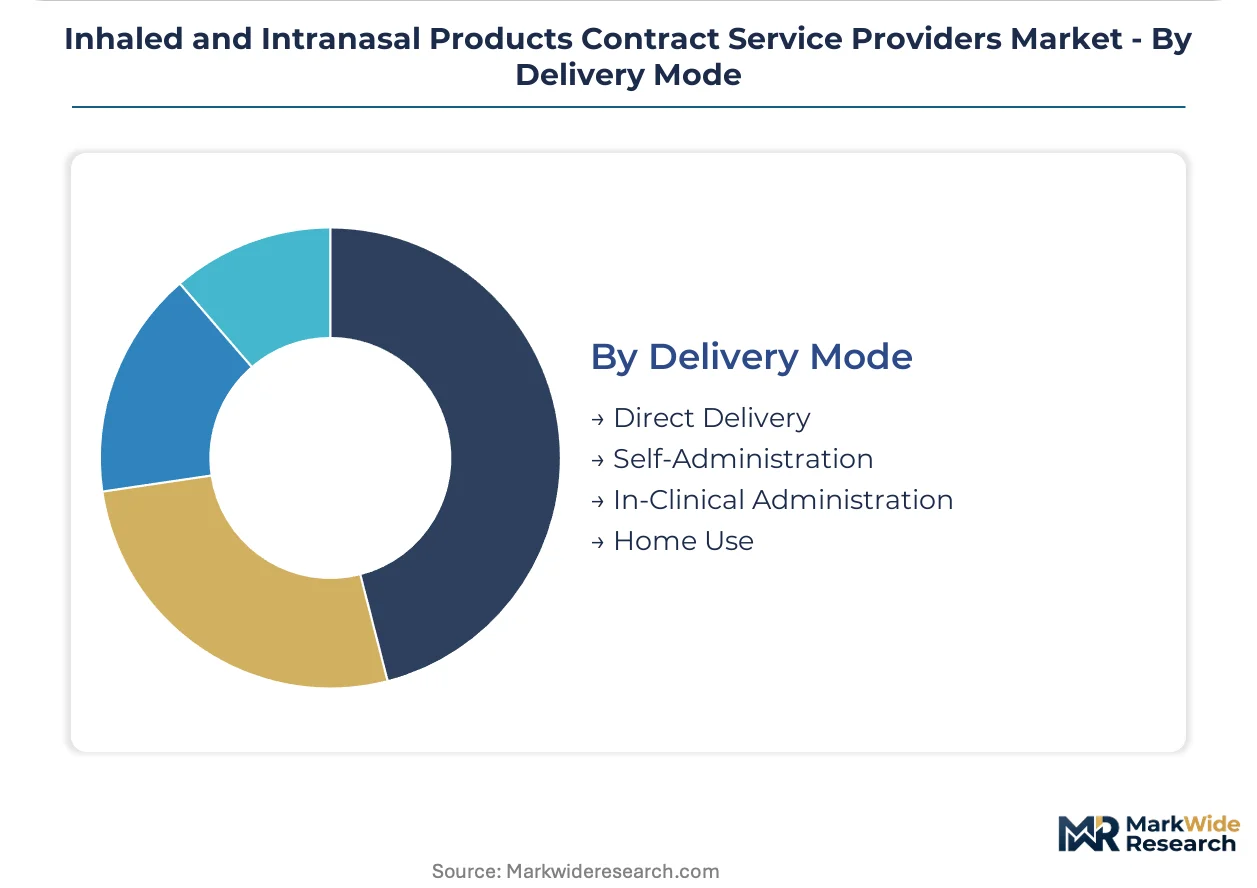
Delivery Mode:
Site-of-care requirements and patient compliance monitoring reshape device selection and connected health integration strategies.
- Direct Delivery:Clinical trial settings and hospital-administered nebulization require validated dosing documentation and adverse event capture protocols.
- Self-Administration:Dry powder inhaler platforms converge with connected health ecosystems embedding sensors and data transmission modules that transform dosing adherence into monetizable service layers.
- In-Clinical Administration:Controlled environments for complex drug-device combinations satisfy FDA bridging study requirements for generic substitution.
- Home Use:Patient training burden and device misuse risk drive demand for intuitive inhaler designs with feedback mechanisms.
Regulatory validation maturity sits with In-Clinical Administration. Connected health integration is advancing fastest in Self-Administration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for inhaled and intranasal contract services concentrates in the United States, where complex respiratory pipelines and specialized CDMO infrastructure cluster around Boston-Cambridge and Research Triangle corridors. Biotech sponsors in these hubs drive premium pricing for particle engineering and aseptic processing capabilities. Regulatory stringency from the FDA elevates compliance barriers that favor established providers with validated sterile manufacturing networks.
United States
Specialty CDMO infrastructure for respiratory drug-device combinations clusters in Massachusetts and North Carolina, serving mid-cap biotech firms developing cystic fibrosis and primary ciliary dyskinesia therapies. The FDA's advancing bioequivalence standards for inhaled generics extend development timelines and concentrate procurement among providers with integrated regulatory filing capabilities. Boston-Cambridge corridor facilities absorb the highest-margin formulation development projects.
Germany
Pressurized metered-dose inhaler reformulation projects accelerate as the EU F-Gas Regulation tightens quotas on fluorinated greenhouse gas propellants. EMA enforcement of Good Manufacturing Practice Annex 1 updates drives sterile respiratory capacity investments across Baden-Württemberg and Bavaria. Frankfurt-Rhine-Main industrial zones host multi-client inhaler assembly lines serving European generic sponsors.
India
CDSCO streamlined approval pathways for inhaled generics attract facility investments to serve domestic and export markets, particularly in Maharashtra and Gujarat. Contract manufacturers in Hyderabad and Ahmedabad expand isolator-based filling capacity for nasal spray and dry powder platforms. Indian providers compete on cost for analytical services while building particle engineering expertise.
Switzerland
Swissmedic oversight of complex drug-device combinations sustains demand for high-continuity manufacturing partnerships among precision respiratory specialists. Basel-region CDMOs leverage proximity to major pharmaceutical sponsors for integrated development-to-commercial platforms. Geneva-area facilities specialize in sterile aqueous nasal formulations for migraine therapeutics.
United Kingdom
Quotient Sciences operates rapid integrated formulation and clinical testing cycles from Nottingham and Reading facilities, compressing timelines for first-in-human respiratory studies. MHRA alignment with FDA bioequivalence guidance facilitates parallel submission strategies for generic inhaler sponsors. Southeast England analytical laboratories invest in next-generation cascade impactor infrastructure.
Inhaled and Intranasal Products Contract Service Providers Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue gene therapy pulmonary delivery and continuous manufacturing niches. The market structures around three tiers: integrated platform providers spanning preformulation through commercial supply, specialized particle engineering boutiques, and regional scale manufacturers competing on cost. Strategic archetypes include full-service respiratory CDMOs, sterile respiratory specialists, and device-agnostic formulation developers. Dominant competitive moves involve preferred provider agreement consolidation by large pharmaceutical sponsors and capacity expansion into India to capture CDSCO pathway advantages.
Within the integrated platform tier, Catalent, Inc. and Recipharm AB exemplify archetypes of development-to-commercial bundling and sterile respiratory specialization respectively. Quotient Sciences occupies a position emphasizing rapid cycle integration between formulation and clinical testing. These three anchors represent distinct strategic postures: captive regulatory accountability, multi-continental sterile manufacturing scale, and compressed timeline service models.
| Leading Market Players |
|---|
| Recipharm AB |
| Quotient Sciences |
| Catalent, Inc. |
| Colep Healthcare |
| Beximco Pharmaceuticals Ltd. |
| Lonza Group |
| Hovione |
| Aptar Pharma |
| Kindeva Drug Delivery |
| Others |
Cost & Logistics Intelligence
Captive integration into sterile respiratory manufacturing anchors supply positions for contract providers serving FDA-regulated sponsors, embedding pricing power through validated aseptic processing networks that generic inhaler developers cannot replicate without multi-year capital commitments. Large pharmaceutical sponsors exploit this concentration by consolidating preferred provider agreements around full-service platforms spanning particle engineering through commercial supply.
Pricing Analysis
High-volume manufacturing commands thinner margins than formulation development, where spray-drying and cascade impaction characterization for lung deposition optimization absorbs premium pricing from mid-cap biotech firms in the United States. Three-tier pricing structure across premium integrated platforms, standard manufacturing services, and economy analytical tiers reflects certification grade and vertical integration depth. Cost compression in standard manufacturing is intensifying because Indian CDMOs expand isolator-based filling capacity under CDSCO streamlined pathways. Biotech firms developing gene therapy pulmonary delivery show least price sensitivity, prioritizing timeline compression over unit economics.
Supply Chain Analysis
Proprietary inhaler platform technologies rest on European and North American licensors, concentrating device master file control with Aptar Pharma and Kindeva Drug Delivery. Hydrofluorocarbon propellants for pressurized metered-dose inhalers draw from specialty chemical producers facing EPA Significant New Alternatives Policy phase-out mandates and EU F-Gas Regulation quota restrictions. Single-source vulnerability permeates the device tier, where simultaneous updates to drug and device regulatory submissions create coordination friction. Distribution runs through sponsor-directed logistics chains with validated temperature controls for sterile respiratory products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dry powder inhaler platforms are displacing legacy pressurized metered-dose systems as EPA and EU F-Gas regulations force propellant chemistry transitions, creating restructuring imperatives across contract manufacturing networks.
For Market Incumbents: To counter Indian CDMO cost competition in sterile respiratory filling, Catalent and Recipharm should deepen backward integration into particle engineering equipment and secure exclusive device platform licensing from European technology holders. Capacity addition in Maharashtra and Gujarat serves domestic Indian demand while preserving premium pricing for FDA-validated North American and European facilities. Gene therapy pulmonary delivery partnerships for cystic fibrosis indications offer margin defense through technical complexity barriers. For New Entrants and Emerging Players: Mid-cap biotech firms in the Boston-Cambridge corridor represent the most penetrable buyer archetype, as these sponsors displace fragmented sourcing with single-accountability partnerships bundling device selection and regulatory strategy. Continuous manufacturing adoption with real-time release testing integration offers white-space positioning against batch-oriented incumbents. A go-to-market angle emphasizing compressed first-in-human timelines differentiates against established providers with slower cycle integration. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by large pharmaceutical sponsors consolidating preferred provider agreements around full-service respiratory platforms. Long-term viability hinges on regulatory validation depth rather than geographic cost arbitrage, as FDA bioequivalence standards for inhaled generics extend development timelines and concentrate procurement among proven providers. The signal to watch is CDSCO approval volume for inhaled generics, indicating whether Indian manufacturing expansion sustains export competitiveness or fragments into domestic-only capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Manufacturing Adoption | Real-time release testing integration compresses batch cycles for multi-client respiratory lines at Quotient Sciences facilities. |
| Propellant Transition Partnership | Reformulation collaborations with EPA-compliant hydrofluorocarbon alternatives secure MDI pipeline continuity for generic sponsors. |
| Gene Therapy Platform Development | Lipid nanoparticle expertise for cystic fibrosis pulmonary delivery opens high-margin partnerships with biotech sponsors. |
| Indian Manufacturing Expansion | Isolator-based filling investments in Hyderabad and Ahmedabad capture CDSCO pathway advantages for export markets. |
| Connected Health Integration | Sensor-embedded dry powder inhalers transform dosing adherence data into monetizable service layers for self-administration segments. |
Research Approach
Multi-period observation of FDA generic inhaler approval volumes, EPA propellant phase-out timelines, and CDSCO regulatory pathway evolution anchored the trend analysis, supplemented by interviews with drug development executives at mid-cap biotech firms, regulatory affairs leads managing drug-device master file alignments, and sterile manufacturing heads at European and North American CDMOs. Secondary validation drew from FDA Orange Book filings, EMA Good Manufacturing Practice Annex 1 updates, ClinicalTrials.gov respiratory delivery protocol registrations, and customs data tracking hydrofluorocarbon propellant trade flows. Bottom-up capacity assessments at individual contract manufacturing facilities triangulated against top-down sponsor pipeline expenditure estimates.
Input-output matrices mapped particle engineering service demand against biotech financing cycles and generic inhaler sponsor R&D commitments across the projection horizon. Segmentation dimensions modeled included service type intensity, device architecture complexity, and regional regulatory cluster stringency. CAGRs were derived from sponsor pipeline velocity analysis and capacity expansion announcements. Industry-specific forecast inputs incorporated EPA Significant New Alternatives Policy implementation pace and EU F-Gas Regulation quota tightening schedules.
Revisions become necessary when FDA bioequivalence guidance for complex drug-device combinations shifts materially, EPA propellant phase-out timelines accelerate, or CDSCO approval pathways for inhaled generics restrict export eligibility. Forecasts reflect assumptions about regulatory stability and sponsor outsourcing propensity that pandemic-era investments in mucosal vaccine delivery may have distorted. A small set of named triggers—generic substitution policy changes, propellant chemistry breakthroughs, and Indian regulatory reciprocity agreements—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Spa Services Market
Healthcare Services
US Healthcare Staffing Market
Healthcare Services
Canada Corporate Wellness Market
Healthcare Services
China Fertility Services Market
Healthcare Services
South Korea Healthcare Cold Chain Logistics Market
Healthcare Services
Vaccine Transport Carrier Market
Healthcare Services
US Primary Care Physicians Market
Healthcare Services
Michigan Urgent Care Center Market
Healthcare Services
Care Services Market
Healthcare Services
Global Healthcare Provider Network Management Market
Healthcare Services
Global Hospital Services Market
Healthcare Services
Regulatory Affairs Outsourcing Market
Healthcare Services
Global Ambulatory Services Market
Healthcare Services
US Value-Based Healthcare Service Market
Healthcare Services
Healthcare Patent Filing Outsourcing Market
Healthcare Services
Canada Senior Living Market