
 US Long-Acting Contraception Market | 2026-2036
US Long-Acting Contraception Market Size, Share, and Industry Trends Forecast 2026-2036
US Long-Acting Contraception Market Intelligence
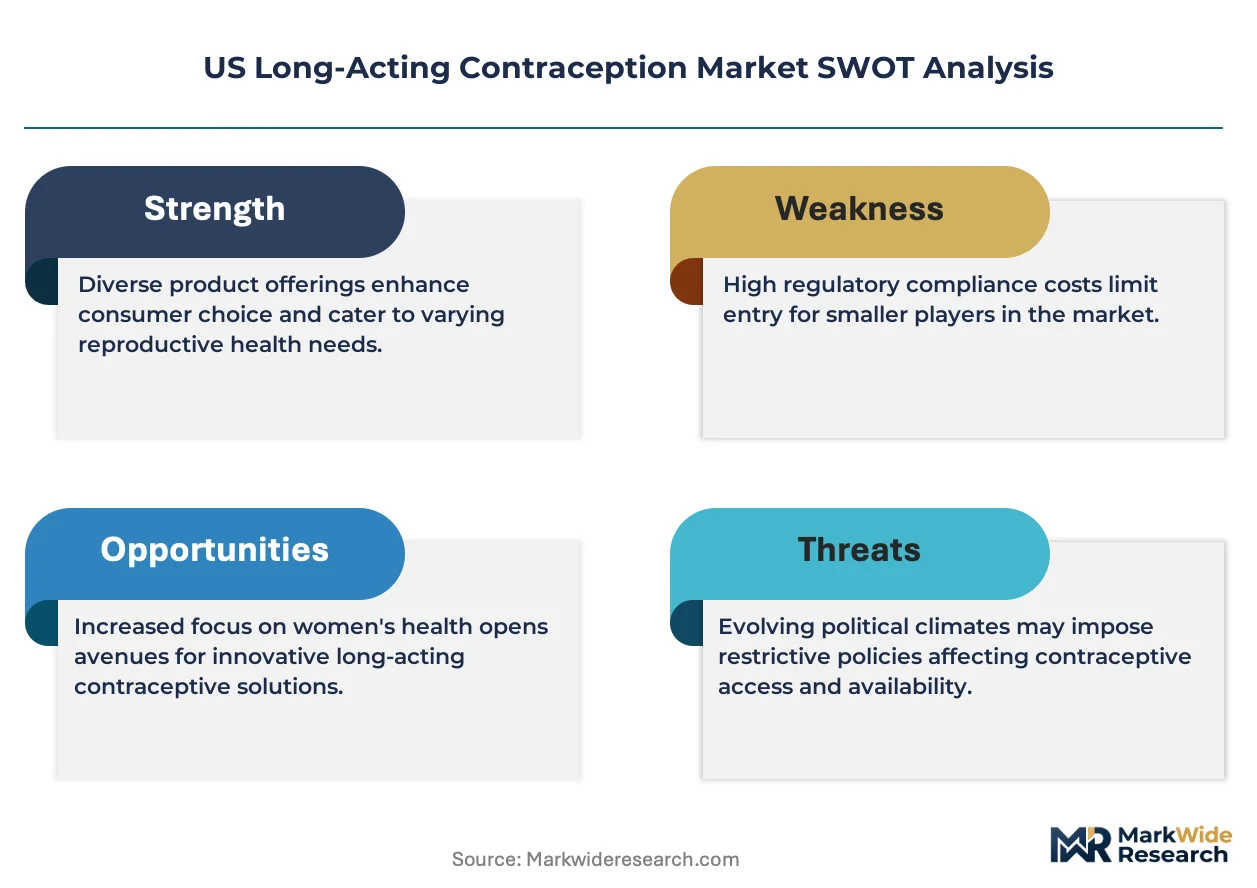
The divergence between premium and commodity tiers is hardening in the US Long-Acting Contraception Market, with copper intrauterine devices and branded hormonal systems commanding higher reimbursement rates than generic injectables. Bayer AG leverages its vertical integration in hormone synthesis to sustain manufacturing scale advantages across multiple delivery formats. CooperSurgical anchors its position through specialized distribution into hospital systems and ambulatory surgical centers.
Long-acting contraception encompasses reversible birth control methods engineered for extended duration, including levonorgestrel-releasing intrauterine systems with active ingredient loads calibrated for three to eight years of efficacy and etonogestrel implants designed for subcutaneous insertion with steady-state hormone release. These products serve the primary commercial purpose of reducing unintended pregnancy rates while minimizing user adherence requirements. Intrauterine devices occupy the dominant revenue position due to established clinician familiarity and broad insurance coverage, while implants represent the fastest-growing product type as postpartum placement protocols expand in hospital discharge workflows. The end user landscape tilts toward clinics as federally qualified health centers absorb volume from private practices facing reimbursement compression.
FDA premarket notification and premarket approval pathways govern device safety and efficacy standards, while CMS reimbursement rules shape provider economics through coding decisions for insertion and removal procedures. State-level Medicaid expansion decisions create geographic variation in access, with expansion states showing higher utilization rates among low-income populations. Stakeholders must monitor state abortion policy shifts and their downstream effects on contraceptive counseling intensity and method mix preferences.
Market Dynamics
Medicaid expansion across state lines is redrawing patient access maps for intrauterine devices and implants, concentrating volume in federally qualified health centers while private practices face reimbursement compression.
Growth Catalysts
- Medicaid Expansion:State-level coverage expansions are pulling low-income postpartum women into long-acting contraception protocols immediately following hospital discharge.
- Insertion Protocol Standardization:Same-day placement workflows are reducing loss-to-follow-up rates among ambulatory surgical centers and birthing hospitals.
- Copper IUD Demand:Hormone-free preferences among breastfeeding populations are sustaining copper intrauterine device volumes in community health settings.
Market Restraints
- Levonorgestrel API Concentration:Synthesis capabilities cluster among three European contract manufacturers, exposing supply continuity to single-source risks.
- FDA PMA Documentation Burden:Pre-market approval pathways for new hormonal implants require extended clinical follow-up periods that compress development timelines.
- Generic Depot Injectables:Three-month medroxyprogesterone acetate formulations compete on price for patients ineligible for intrauterine placement.
Strategic Opportunities
- Telehealth Counseling:Virtual pre-insertion consultations are extending reach into rural counties with OB-GYN shortages.
- Extended-Duration Systems:Eight-year levonorgestrel formulations are targeting replacement-cycle compression against five-year legacy products.
- Postpartum Protocol Integration:Hospital discharge bundles in expansion states are capturing patients during high-intent decision windows.
Industry Challenges
- Clinician Training Pipeline:Insertion competency requirements limit the pool of qualified providers in underserved markets.
- Prior Authorization Friction:Medicaid managed care plans impose variable documentation burdens that delay same-day placement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Long-Acting Contraception Market |
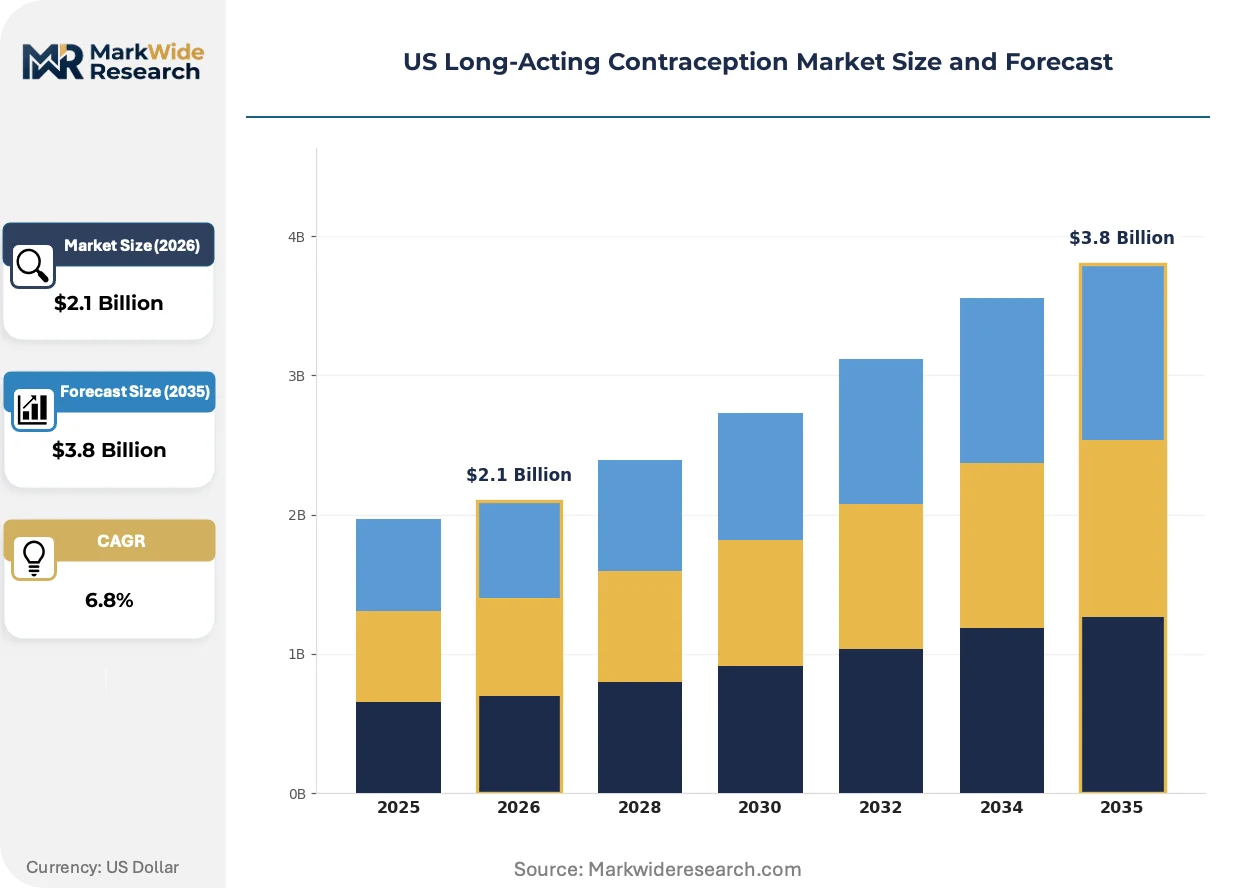
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intrauterine Devices, Implants, Injectables, Patch Delivery Mode: Subcutaneous, Intrauterine, Intramuscular, Transdermal End User: Clinics, Hospitals, Private Practices, Pharmacists Age Group: Adolescents, Young Adults, Adults, Postpartum Women |
| Companies Covered | Bayer AG, Merck & Co., Inc., CooperSurgical, Inc., Teva Pharmaceutical Industries Ltd., Allergan, Organon & Co., Pfizer Inc., Medicines360, Church & Dwight Co., Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Long-Acting Contraception Market Strategic Shifts & Innovations
Product development is pivoting toward longer-acting formulations and simplified insertion mechanisms, while reimbursement models are compressing decision timelines for patient counseling.
Biodegradable implant matrices are expanding into subcutaneous delivery systems that eliminate removal procedures. Federally qualified health centers are piloting these formats for adolescent populations seeking discrete, long-term options. The technology is expanding into Medicaid expansion states where removal access barriers historically limited implant uptake.
FDA premarket approval pathways are tightening safety documentation requirements for hormonal implants with novel release kinetics. Sponsors now face extended pediatric study mandates and post-approval surveillance commitments. Smaller developers are responding by partnering with established manufacturers possessing regulatory infrastructure.
Same-day insertion protocols are displacing traditional multi-visit counseling models in hospital discharge workflows. Postpartum units in expansion states are embedding contraceptive counseling into standard obstetric care, replacing standalone family planning referrals. This shift concentrates volume in integrated health systems with inpatient capabilities.
US Long-Acting Contraception Market Segmentation
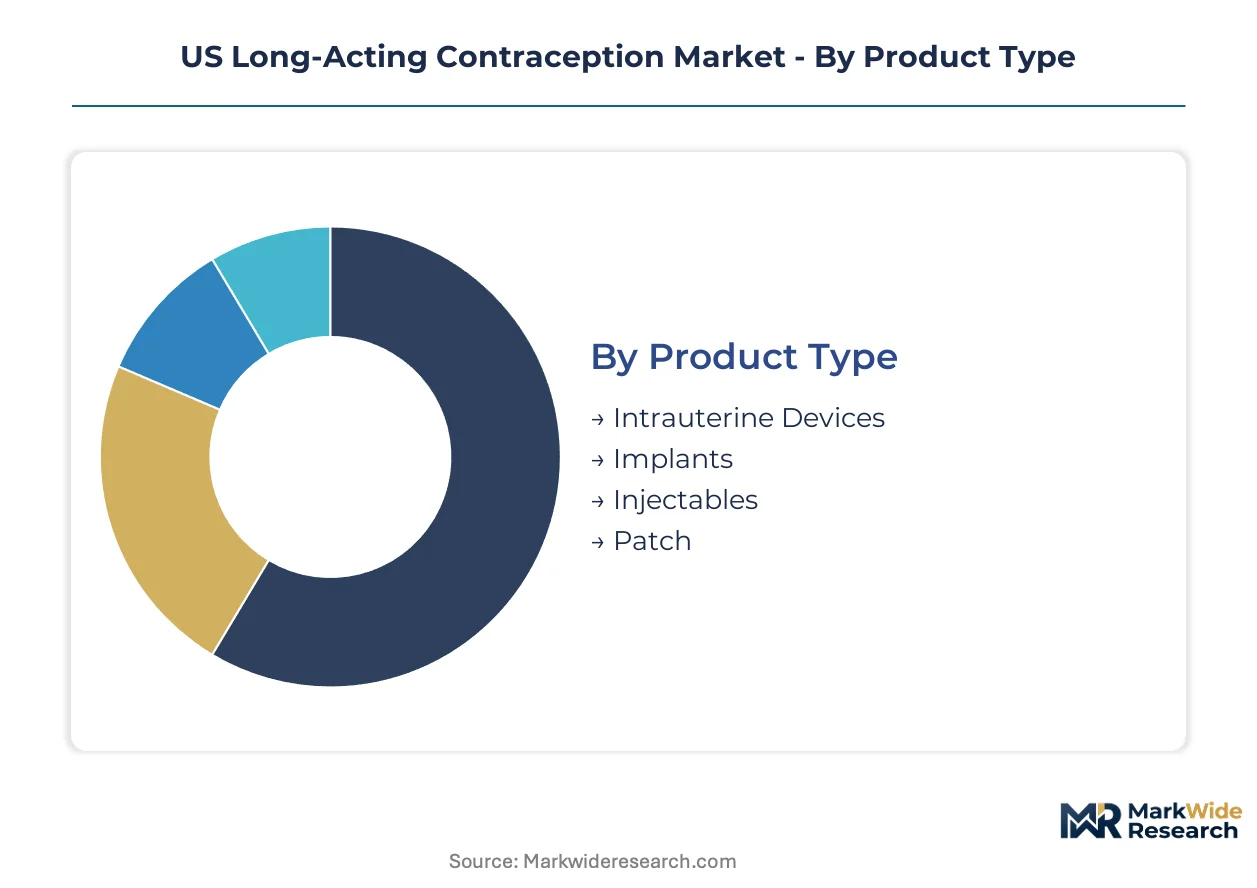
Long-acting contraception markets fragment across device formats, administration routes, and care settings. Each segmentation axis reveals distinct reimbursement patterns, regulatory pathways, and patient access barriers that shape commercial strategy.
Product Type:
Levonorgestrel-releasing intrauterine systems and etonogestrel implants anchor the technology portfolio, with copper devices and depot formulations occupying distinct market tiers.
- Intrauterine Devices:T-shaped systems deliver calibrated hormone loads or copper ion release for multi-year efficacy. Demand concentrates in Medicaid expansion states where postpartum placement protocols have embedded IUD counseling into standard obstetric discharge workflows.
- Implants:Flexible polymer rods enable subcutaneous etonogestrel release with steady-state pharmacokinetics over extended durations. Hospital systems in expansion states are absorbing volume as same-day insertion protocols displace multi-visit counseling models.
- Injectables:Medroxyprogesterone acetate formulations compete on price point for patients ineligible for intrauterine placement.
- Patch:Weekly transdermal systems occupy a narrower niche among patients seeking reversible alternatives without procedural insertion.
Intrauterine devices lead on scale; implants lead on momentum.
Delivery Mode:
Route of administration determines provider competency requirements, facility infrastructure needs, and reimbursement coding complexity.
- Intrauterine:Requires speculum examination and cervical instrumentation, limiting placement to clinicians with specialized training. Federally qualified health centers are expanding insertion capacity through dedicated family planning protocols.
- Subcutaneous:Upper arm insertion demands less specialized infrastructure, enabling broader provider pools in community health settings.
- Intramuscular:Quarterly depot injections rely on existing clinical nursing workflows without procedural complexity.
- Transdermal:Patient-administered application reduces clinical burden but requires adherence monitoring absent from long-acting alternatives.
Intrauterine delivery commands premium reimbursement; subcutaneous routes are expanding most quickly into underserved counties.
End User:
Site-of-care economics are restructuring as federally qualified health centers absorb volume from private practices facing reimbursement compression.
- Clinics:Title X-funded sites and community health centers anchor access for uninsured and Medicaid populations. Medicaid expansion has concentrated long-acting contraception volume in these settings.
- Hospitals:Inpatient obstetric units in expansion states are embedding same-day placement into postpartum discharge bundles, capturing patients during high-intent decision windows.
- Private Practices:Reimbursement compression and prior authorization friction are eroding procedural economics for independent OB-GYNs.
- Pharmacists:Scope-of-practice expansions in select states are enabling pharmacist-administered depot injections, though intrauterine and implant placement remains outside pharmacy practice authority.
Clinics lead on patient volume; hospitals lead on placement immediacy.
Age Group:
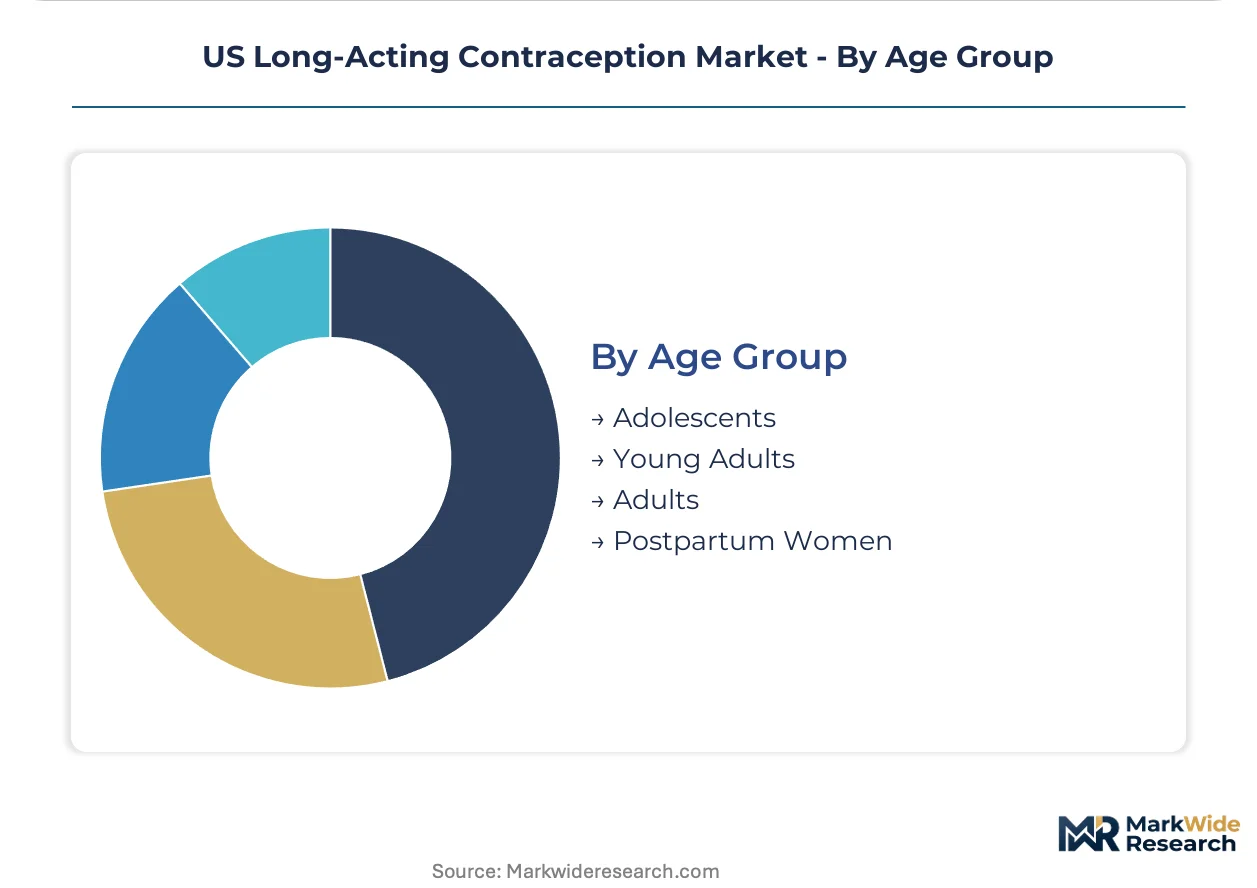
FDA labeling, state consent laws, and counseling intensity requirements segment demand across reproductive life stages.
- Postpartum Women:Immediate postpartum placement protocols in Medicaid expansion states are capturing patients during hospital discharge, eliminating the traditional six-week follow-up barrier.
- Adolescents:Pediatric study mandates and confidentiality concerns shape product selection, with biodegradable implant matrices piloting in federally qualified health centers for discrete long-term options.
- Young Adults:Insurance transitions and relationship instability drive demand for reversible extended-duration methods.
- Adults:Completed family planning drives uptake of longer-acting systems with replacement-cycle compression.
Postpartum women lead on placement velocity; adolescents represent the steepest expansion trajectory as pediatric labeling expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OB-GYN workforce density in Medicaid expansion states anchors geographic demand concentration for long-acting contraception placement. Hospital discharge protocols in these states embed same-day insertion into standard obstetric workflows. Federally qualified health centers absorb volume as private practices face reimbursement compression.
California
Postpartum placement protocols in Los Angeles County and Bay Area hospital systems capture patients during discharge windows. Medi-Cal expansion supports same-day IUD and implant insertion without prior authorization delays. San Diego and Sacramento federally qualified health centers train nurse practitioners to expand insertion capacity.
Texas
Non-expansion status limits Medicaid coverage for immediate postpartum placement, concentrating demand in Title X-funded clinics and self-pay segments. Houston and Dallas hospital systems rely on charity care programs for uninsured postpartum women. Austin and San Antonio community health centers absorb patients from surrounding rural counties with OB-GYN shortages.
New York
Medicaid expansion and state-level contraceptive equity laws eliminate cost-sharing for all long-acting methods. New York City Health + Hospitals embeds placement into prenatal and postpartum care across eleven acute care facilities. Buffalo and Rochester clinics serve cross-border patients from Pennsylvania and Ohio seeking expanded access.
Illinois
Chicago-area academic medical centers train residents in immediate postpartum IUD insertion, expanding qualified provider pools. Cook County Health integrates contraceptive counseling into maternal health workflows. Downstate federally qualified health centers in Peoria and Springfield address rural access gaps through mobile clinic deployment.
Florida
Non-expansion Medicaid limits coverage to pregnant women, creating a coverage cliff postpartum. Miami-Dade and Broward County hospital systems rely on 1115 waiver funding for limited postpartum extension programs. Orlando and Tampa federally qualified health centers serve uninsured populations through Title X and sliding-fee scales.
US Long-Acting Contraception Market Key Industry Players
Capital-heavy producers compete with asset-light designers across hormone synthesis, device manufacturing, and distribution infrastructure. The market structures around three tiers: integrated pharmaceutical conglomerates with captive API production, specialized women's health device manufacturers, and generic injectable suppliers competing on price. Strategic moves concentrate on vertical integration into hormone synthesis, hospital system contracting, and Medicaid managed care formulary positioning.
Within the integrated pharmaceutical tier, Bayer AG and Merck & Co., Inc. occupy positions defined by backward integration into levonorgestrel production and established hospital system relationships. CooperSurgical, Inc. exemplifies the specialized device manufacturer archetype, anchoring distribution through ambulatory surgical center networks. Organon & Co. represents the spin-off specialist model, inheriting legacy hormonal implant portfolios while rebuilding commercial infrastructure.
| Leading Market Players |
|---|
| Bayer AG |
| Merck & Co., Inc. |
| CooperSurgical, Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Allergan |
| Organon & Co. |
| Pfizer Inc. |
| Medicines360 |
| Church & Dwight Co., Inc. |
| Others |
Cost & Logistics Intelligence
Captive hormone synthesis operations at Bayer AG and Merck anchor both manufacturing scale and pricing power across levonorgestrel-releasing systems, enabling premium positioning against generic depot injectables while insulating against API cost volatility. This integration pattern concentrates margin control among integrated pharmaceutical conglomerates and shapes competitive responses from specialized device manufacturers lacking upstream chemical production.
Pricing Analysis
Bundled insertion-and-device reimbursement dominates hospital discharge workflows, while unbundled fee-for-service coding persists in federally qualified health centers. Price differentiation hinges on FDA PMA certification tier and clinician training infrastructure, with hormone-free copper systems commanding modest premiums over generic injectables. Cost compression in the injectable tier intensifies because Medicaid managed care plans drive formulary substitution toward medroxyprogesterone acetate. Uninsured patients in non-expansion states exhibit highest price sensitivity; integrated health systems with captive GPO contracts exhibit lowest.
Supply Chain Analysis
Workforce availability constraints in German and Swiss chemical manufacturing hubs limit expansion of levonorgestrel API synthesis capacity. Raw material dependencies center on progesterone precursor feedstocks, medical-grade silicone for implant matrices, and copper wire for intrauterine devices. Single-source vulnerability concentrates in European contract manufacturers serving multiple hormonal implant developers. Distribution runs through specialized medical device distributors into hospital systems and ambulatory surgical centers, with federally qualified health centers increasingly sourcing through 340B pharmacy networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US Long-Acting Contraception Market represents a late-cycle quality story as postpartum placement protocols shift demand toward extended-duration systems with higher reimbursement stability. Premium specifications—eight-year levonorgestrel formulations and biodegradable implant matrices—are displacing legacy five-year products in Medicaid expansion states.
For Market Incumbents: Anchor hospital system partnerships through same-day insertion protocol standardization, defending against CooperSurgical's ambulatory surgical center penetration. Deepen backward integration into hormone synthesis to offset European API concentration risk. Prioritize pediatric labeling investments to capture adolescent segment expansion as biodegradable matrices pilot in federally qualified health centers. For New Entrants and Emerging Players: The premium-to-economy price-point gap in hormonal implants opens white-space targeting for mid-tier etonogestrel formulations with simplified insertion mechanisms. Texas and Florida non-expansion markets offer penetrable volume through Title X clinic networks and self-pay cash models. Pursue telehealth counseling integration to bypass OB-GYN workforce shortages in rural counties. For Investors and Strategic Acquirers: Consolidation pressure builds where FDA PMA documentation burdens and extended pediatric study mandates favor acquirers with established regulatory infrastructure over standalone developers. Long-term viability favors asset-light designers with hospital system contracting relationships and Medicaid managed care formulary positioning. Watch state Medicaid expansion ballot initiatives as inflection indicators for geographic demand reallocation.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Captures postpartum placement volume through embedded discharge protocols in expansion states. |
| FDA Premarket Approval Pathway | Extends development timelines but secures premium reimbursement coding and competitive moats. |
| Backward Integration into API Synthesis | Insulates against European contract manufacturer concentration and supply continuity disruptions. |
| Telehealth Counseling Platform | Extends reach into rural counties with OB-GYN shortages and reduces loss-to-follow-up rates. |
| Extended-Duration Formulation Development | Targets replacement-cycle compression against legacy five-year products in commercial segments. |
Research Approach
Coverage spans US state-level Medicaid expansion clusters and non-expansion markets, with primary inputs from each. Interviews with OB-GYN department heads, federally qualified health center clinical directors, hospital purchasing committee members, and Medicaid managed care formulary managers combined with secondary validation from FDA PMA filings, CMS reimbursement coding decisions, state Medicaid expansion policy databases, and Title X funding allocation records. Bottom-up patient volume modeling and top-down pharmaceutical revenue triangulation anchored market sizing.
Granularity-level framing applied product type, delivery mode, end-user site of care, and age group segmentation with state-level geographic resolution. CAGRs derived from trend extrapolation of Medicaid expansion enrollment, postpartum placement protocol adoption curves, and clinician training pipeline expansion rates across the projection horizon. Forecast inputs included state-level abortion policy shift probabilities and their downstream effects on contraceptive counseling intensity.
Caveats apply where FDA pediatric study mandate revisions or state Medicaid expansion reversals could materially shift the outlook. Forecasts reflect assumptions about sustained federal Title X funding levels and stable European API supply continuity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Reproductive Health
Fertility Treatments Market
Reproductive Health
Germany in Vitro Fertilization (IVF) Market
Reproductive Health
Doula and Birth Coaching Services Market
Reproductive Health
Global Male Infertility Market
Reproductive Health
Asia-Pacific in Vitro Fertilization (IVF) Market
Reproductive Health
Gamete Preservation Market
Reproductive Health
Cervical Dysplasia Treatment Market
Reproductive Health
Vaginal Exam Specula Market
Reproductive Health
UK in Vitro Fertilization (IVF) Market
Reproductive Health
Global Genital Herpes Treatment Market
Reproductive Health
Assisted Reproductive Technology (ART) Market
Reproductive Health
Egg Freezing and Embryo Banking Market
Reproductive Health
Hormonal Contraception Market
Reproductive Health
Europe in Vitro Fertilization (IVF) Market
Reproductive Health
IVF Services Market
Reproductive Health
Smart Fertility Tracker Market