
 UK in Vitro Fertilization (IVF) Market | 2026-2036
UK in Vitro Fertilization (IVF) Market Size, Share, and Industry Trends Forecast 2026-2036
UK in Vitro Fertilization (IVF) Market Insights
The direct-to-clinic supply channel for culture media and cryopreservation kits is narrowing as national procurement frameworks consolidate purchasing power across NHS-affiliated fertility networks. CooperSurgical Inc. leverages its embryology portfolio to sustain long-term contracts with multi-site clinic groups. Vitrolife anchors the high-end segment through time-lapse incubator technology that commands premium positioning. Merck KGaA competes aggressively on gonadotropin formulations, extending its reach into both private and public treatment pathways.
In vitro fertilization encompasses laboratory-based fertilization of oocytes by sperm outside the body, typically performed in controlled incubation at 37 degrees Celsius with 5-6% carbon dioxide atmosphere and pH 7.2-7.4, yielding embryos for uterine transfer or cryogenic storage. Fresh IVF cycles still generate the largest procedure volume, though frozen cycles are expanding fastest as vitrification protocols improve post-thaw survival rates. Preimplantation genetic testing commands disproportionate margin pools due to sequencing costs and specialized embryologist labor, while intracytoplasmic sperm injection remains the dominant fertilization technology for male factor infertility cases.
The Human Fertilisation and Embryology Authority regulates all UK IVF clinics through licensing, inspection, and mandatory reporting of outcomes, directly shaping clinic operational standards and permissible research boundaries. The Care Quality Commission overlays additional facility inspections that influence capital investment decisions for laboratory air handling and contamination control. Stakeholders must monitor proposed amendments to statutory storage limits for frozen embryos, as these policy shifts would immediately alter cryopreservation capacity planning and revenue recognition across clinic networks.
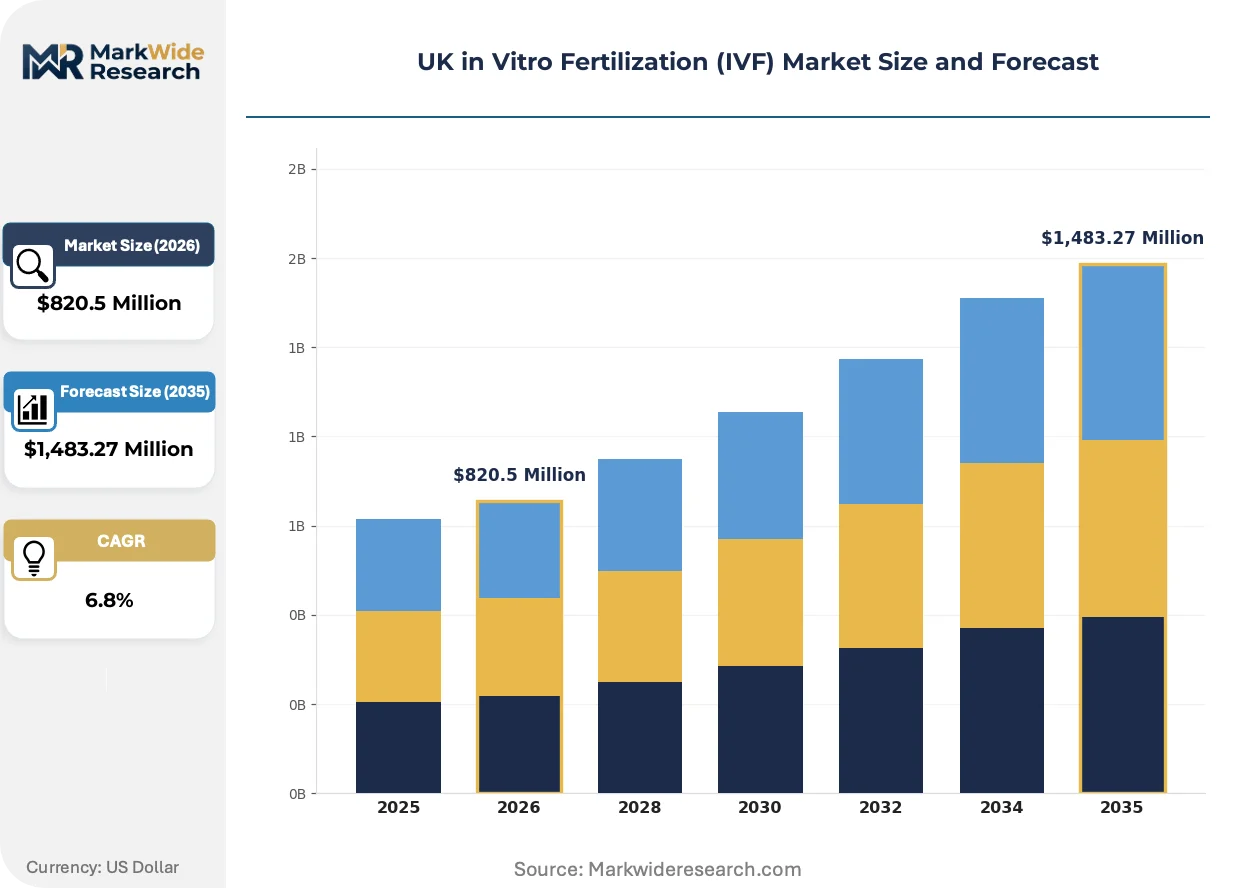
Market Dynamics
The Human Fertilisation and Embryology Authority's updated consent protocols are compressing decision timelines for embryo storage while simultaneously expanding eligible patient pathways, forcing clinics to reconfigure cryopreservation infrastructure and revenue models within compressed regulatory windows.
Growth Catalysts
- Vitrification Protocol Advancement:Post-thaw survival rates above 90% for blastocyst-stage embryos are converting fresh-cycle patients to frozen-cycle pathways, expanding addressable procedure volume across NHS and private networks.
- Greater London Demand Concentration:Fertility clinics in the capital and South East corridor are scaling laboratory capacity to serve women aged 35-40, the fastest-expanding patient demographic seeking first-cycle treatment.
- HFEA Licensing Framework:Mandatory outcome reporting and inspection standards are driving consolidation toward multi-site clinic groups capable of absorbing compliance overhead, concentrating market activity in accredited networks.
Market Restraints
- Gonadotropin Cost Volatility:Recombinant follicle-stimulating hormone formulations constitute 25-35% of medication costs per stimulated cycle, exposing private payers and NHS commissioners to biologics pricing fluctuations without generic substitution pathways.
- Embryologist Labor Scarcity:The Association of Clinical Embryologists certifies fewer than 400 new practitioners annually against clinic expansion rates, constraining laboratory throughput regardless of physical incubator capacity.
- Statutory Storage Limits:Current HFEA-mandated maximum storage durations for frozen embryos create forced disposition events that interrupt patient continuity and compress recurring storage revenue recognition.
Strategic Opportunities
- Preimplantation Genetic Testing Expansion:Next-generation sequencing integration with time-lapse morphokinetic analysis is opening high-margin service lines for aneuploidy screening and monogenic disorder detection in targeted patient subgroups.
- North England Undersupply:Clinic density in Yorkshire, North West, and North East regions remains 40-60% below London per-capita benchmarks, presenting acquisition and greenfield development white space for scaled operators.
- NHS Long-Term Plan Fertility Access:Proposed expansion of publicly funded IVF cycles to three full cycles per eligible patient would redirect volume toward NHS-affiliated networks and reshape private clinic referral patterns.
Industry Challenges
- Air Handling Compliance Capex:Care Quality Commission laboratory inspection standards for particulate control and pressure differentials require HVAC replacement cycles of 7-10 years, straining smaller independent clinic capital reserves.
- Time-Lapse Incubator Integration Complexity:EmbryoScope and comparable platforms demand specialized IT infrastructure and data archiving protocols that conflict with legacy laboratory information management systems, extending implementation timelines.
- Cross-Border Gamete Transport Logistics:Brexit-related customs friction for donor sperm and oocyte shipments from Danish and Spanish cryobanks is introducing temperature excursion risks and documentation delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK in Vitro Fertilization (IVF) Market |
| Market Size in 2026 | $820.5 Million |
| Market Size in 2035 | $1,483.27 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh IVF Cycle, Frozen IVF Cycle, Donor Eggs, Embryo Adoption End User: Fertility Clinics, Hospitals, Research Institutions, Home Users Technology: Intracytoplasmic Sperm Injection, Preimplantation Genetic Testing, Cryopreservation, Surrogacy Age Group: Under 35, 35-40, 41-45, Above 45 |
| Companies Covered | Vitrolife, CooperSurgical Inc., Merck KGaA, Ferring Pharmaceuticals Ltd, IBSA Pharma Ltd, Cook Medical Inc., Thermo Fisher Scientific Inc., Bayer AG, Hamilton Thorne, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK in Vitro Fertilization (IVF) Market Trends and Innovations
Time-lapse incubation systems are converging with artificial intelligence-based embryo selection algorithms to reshape laboratory workflow economics and competitive differentiation across UK fertility networks.
Vitrification media formulations are hybridizing with synthetic macromolecular cryoprotectants to reduce osmotic stress during ultra-rapid cooling protocols. Private fertility clinics in Greater London are adopting these next-generation kits at replacement pace as standard glycerol-based solutions face survival rate ceilings. The technology is compressing pricing power for incumbent cryopreservation suppliers while enabling premium positioning for integrated media-instrument bundles.
HFEA consultation on extending statutory embryo storage limits beyond the current ten-year standard is forcing clinics to model capacity scenarios and patient communication strategies. The policy uncertainty is accelerating investment in modular cryogenic storage infrastructure with scalable nitrogen supply systems. Multi-site clinic groups in England's urban corridors are most exposed, as they hold 60-70% of national frozen embryo inventory.
Direct-to-clinic procurement consolidation is displacing distributor-mediated supply relationships for culture media and disposable consumables. NHS-affiliated fertility networks are aggregating purchasing volume through national procurement frameworks, extracting price concessions from manufacturers. The channel shift is most visible in the South East and Midlands, where integrated care systems are standardizing laboratory supply contracts across constituent clinics.
UK in Vitro Fertilization (IVF) Market Segmentation
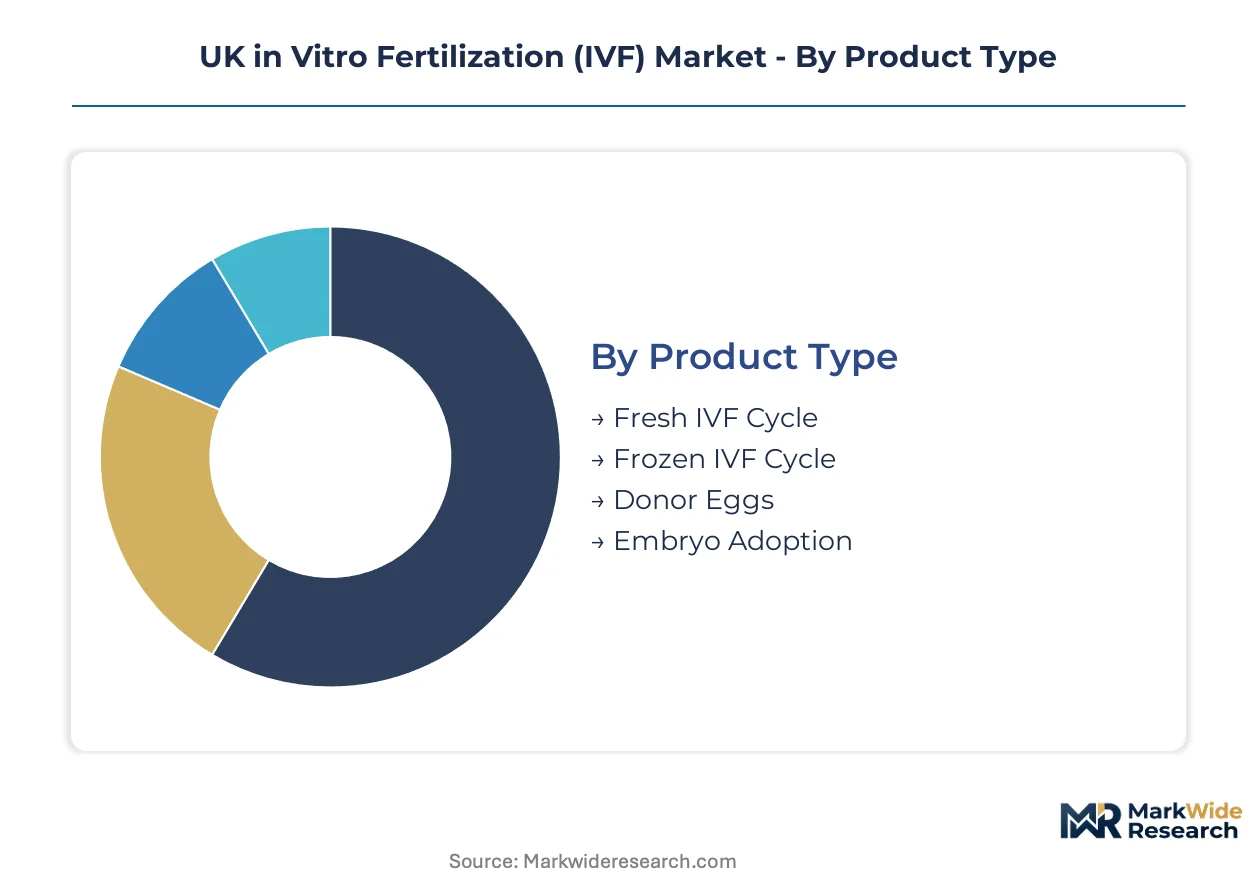
IVF market segmentation reveals divergent margin profiles and capacity constraints across treatment modalities. Cycle economics vary dramatically between fresh and frozen pathways, while patient demographics and technology choices reshape clinic investment priorities.
Product Type:
Fresh IVF cycles turn over fastest with single-stimulation timelines, while frozen cycles stretch revenue recognition across months or years of storage fees.
- Fresh IVF Cycle:Ovarian stimulation, retrieval, fertilization, and embryo transfer occur within 4-6 weeks. Greater London clinics process the highest fresh-cycle volumes for women aged 35-40 seeking immediate conception pathways.
- Frozen IVF Cycle:Vitrified embryos enable deferred transfer, extending patient relationships through annual storage renewals. Post-thaw survival rates above 90% are converting fresh-cycle patients toward frozen pathways across NHS and private networks.
- Donor Eggs:Oocyte donation addresses diminished ovarian reserve, with cycles relying on cryobank supply chains from Danish and Spanish donors.
- Embryo Adoption:Transfer of surplus embryos from completed families offers lower-cost alternatives for specific patient subgroups.
Fresh IVF Cycle anchors the volume base while Frozen IVF Cycle gains share at the steepest rate.
End User:
Cost tiers separate capital-intensive laboratory operators from lower-infrastructure settings, with compliance burdens scaling directly with procedural complexity.
- Fertility Clinics:Standalone reproductive medicine centers house full embryology laboratories with time-lapse incubators and cryogenic storage. Multi-site groups in England's urban corridors concentrate 60-70% of national frozen embryo inventory.
- Hospitals:Acute care settings integrate fertility services within broader women's health departments, often under NHS commissioning frameworks.
- Research Institutions:Academic medical centers pursue HFEA-licensed research using surplus embryos, operating under stricter consent and destruction protocols.
- Home Users:At-home ovulation monitoring and hormone testing support treatment timing, though fertilization procedures remain clinic-bound.
Fertility Clinics dominate revenue concentration while Hospitals expand most quickly under NHS Long-Term Plan access proposals.
Technology:
Application focus distinguishes diagnostic precision tools from procedural interventions, with genetic screening commanding premium positioning.
- Intracytoplasmic Sperm Injection:Micromanipulation technique injects single sperm directly into ooplasm, addressing male factor infertility. The procedure remains the dominant fertilization technology across UK clinic networks.
- Preimplantation Genetic Testing:Next-generation sequencing of blastocyst biopsies enables aneuploidy screening and monogenic disorder detection. Integration with time-lapse morphokinetic analysis opens high-margin service lines.
- Cryopreservation:Vitrification protocols using synthetic macromolecular cryoprotectants reduce osmotic stress during ultra-rapid cooling.
- Surrogacy:Gestational carrier arrangements require separate legal frameworks and HFEA-compliant embryo transfer procedures.
Intracytoplasmic Sperm Injection anchors procedural volume while Preimplantation Genetic Testing climbs fastest on margin expansion.
Age Group:
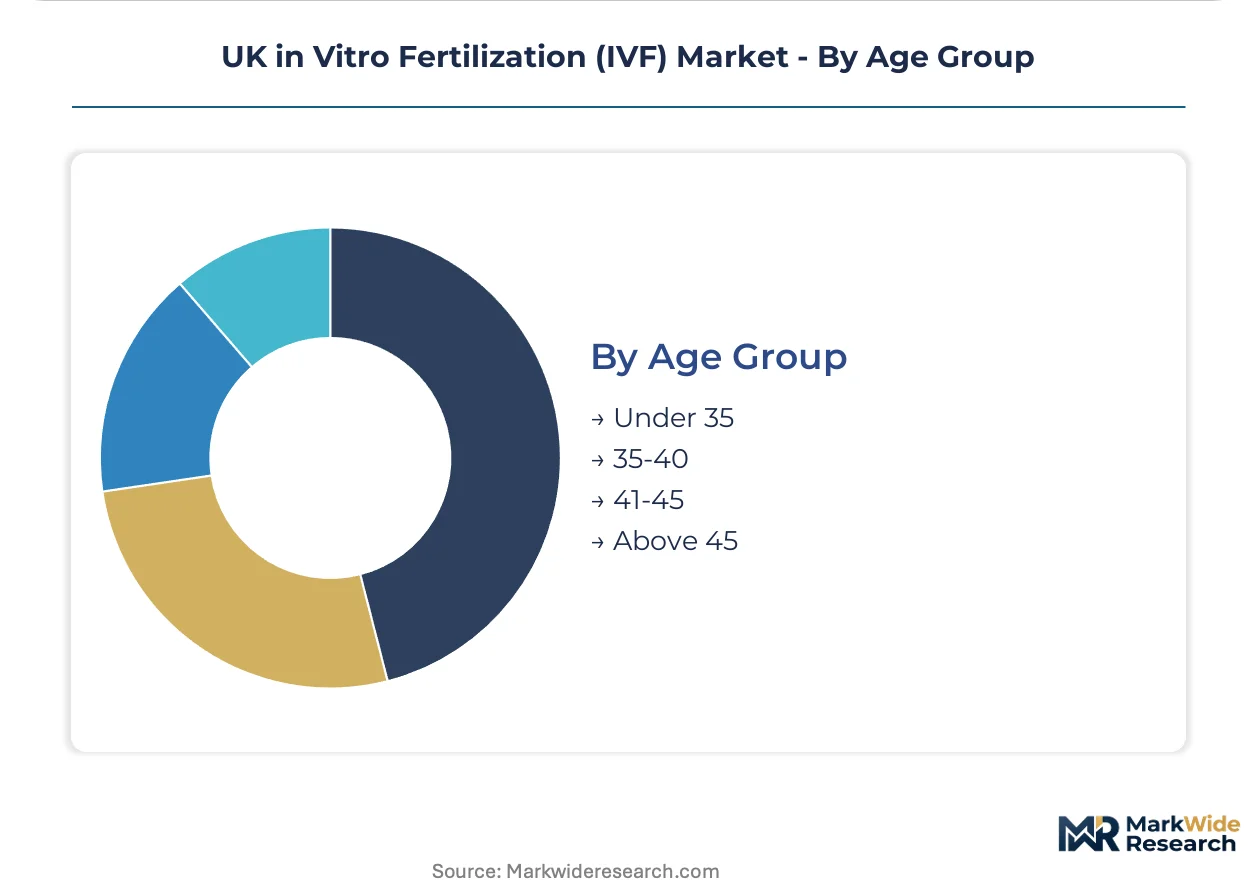
Patient maturity segments correlate directly with treatment intensity and success probability, reshaping clinic capacity planning.
- Under 35:Peak ovarian reserve yields highest live birth rates per cycle, often requiring fewer stimulation attempts.
- 35-40:Fertility clinics in Greater London and the South East are scaling laboratory capacity specifically for this fastest-expanding demographic seeking first-cycle treatment.
- 41-45:Diminished ovarian reserve shifts treatment toward donor eggs and higher gonadotropin dosing protocols.
- Above 45:Very low autologous success rates concentrate demand on donor oocyte pathways and gestational surrogacy arrangements.
The 35-40 segment anchors volume growth while Above 45 expands most quickly on donor-dependent service lines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Human Fertilisation and Embryology Authority regulates all UK IVF activity through licensing, inspection, and mandatory outcome reporting, anchoring national market structure. Clinic concentration varies sharply across England's regions, with capacity expansion and procurement consolidation reshaping local competitive dynamics.
Greater London and South East
Fertility clinics in this corridor process the highest fresh-cycle volumes nationally, scaling laboratory capacity specifically for women aged 35-40. The Care Quality Commission overlays facility inspections that drive capital investment in air handling and contamination control. Multi-site clinic groups here hold 60-70% of national frozen embryo inventory, forcing modular cryogenic storage upgrades.
Midlands
NHS-affiliated fertility networks in this region are consolidating purchasing volume through national procurement frameworks, extracting price concessions from manufacturers. Integrated care systems standardize laboratory supply contracts across constituent clinics, displacing distributor-mediated relationships. Birmingham and Leicester clusters anchor regional capacity, though density remains below London benchmarks.
North England
Clinic density in Yorkshire, North West, and North East regions runs 40-60% below London per-capita levels, presenting acquisition and greenfield development white space. Manchester and Leeds house the primary laboratory infrastructure, with embryologist labor scarcity constraining throughput expansion regardless of physical incubator capacity. The NHS Long-Term Plan fertility access proposals would redirect volume toward NHS-affiliated networks here.
Scotland
Scottish IVF provision operates under distinct NHS commissioning frameworks with separate funding allocations from England. Edinburgh and Glasgow concentrate laboratory capacity, with regulatory alignment to HFEA standards ensuring cross-border operational consistency. Cryopreservation service lines face similar statutory storage limit pressures as English clinics.
Wales
Welsh fertility services integrate within NHS Wales commissioning structures, with Cardiff anchoring regional laboratory infrastructure. HFEA licensing applies uniformly, though patient pathways differ in funding eligibility criteria. Clinic networks here remain smaller-scale, with less procurement leverage than English multi-site groups.
UK in Vitro Fertilization (IVF) Market Competitive Landscape
Specialized embryology suppliers and diversified pharmaceutical manufacturers split the market between premium technology bundles and high-volume medication formulations. The vendor base concentrates around three strategic archetypes: integrated media-instrument platforms, gonadotropin-focused pharmaceutical houses, and time-lapse incubator specialists. Consolidation toward multi-site clinic groups favors suppliers capable of absorbing compliance overhead and anchoring long-term contracts. Competitive moves center on portfolio diversification into genetic testing integration and geographic expansion into undersupplied northern regions.
Within the integrated platform tier, Vitrolife exemplifies premium positioning through embryology portfolio depth, while CooperSurgical Inc. anchors long-term contract relationships with multi-site clinic groups. Merck KGaA occupies a position exemplifying pharmaceutical-scale competition on gonadotropin formulations, extending reach across both private and public treatment pathways.
| Leading Market Players |
|---|
| Vitrolife |
| CooperSurgical Inc. |
| Merck KGaA |
| Ferring Pharmaceuticals Ltd |
| IBSA Pharma Ltd |
| Cook Medical Inc. |
| Thermo Fisher Scientific Inc. |
| Bayer AG |
| Hamilton Thorne |
| Others |
Pricing and Supply Chain Analysis
Laboratory capacity underutilization in North England is compressing procurement leverage for standalone clinics while concentrating negotiating power with multi-site groups in Greater London and the South East. This utilization gap forces suppliers to tier pricing structures geographically and pushes independent operators toward group purchasing frameworks to recover margin.
Pricing Analysis
Greater London clinics command 15-20% price premiums over Yorkshire and North East counterparts for equivalent fresh IVF cycles, reflecting laboratory density and embryologist labor scarcity. Three-tier pricing structure across premium time-lapse incubator protocols, standard culture media bundles, and economy gonadotropin formulations separates high-complexity fertility networks from NHS-affiliated hospitals. Pricing pressure stems from national procurement framework consolidation extracting volume discounts from manufacturers. NHS commissioners exhibit highest price sensitivity due to fixed reimbursement bands, while private payers in London tolerate premium positioning for genetic testing integration.
Supply Chain Analysis
Upstream media formulations and cryoprotectant chemistries draw from pharmaceutical manufacturing clusters in Germany, Switzerland, and the United States, with gonadotropin active pharmaceutical ingredients anchored in Italian and Danish biologics facilities. Recombinant follicle-stimulating hormone, synthetic macromolecular cryoprotectants, and time-lapse incubator optical components constitute critical input dependencies. Single-source vulnerability concentrates in Danish and Spanish cryobank supply for donor gametes, exposing clinics to Brexit-related customs friction. Distribution runs through direct-to-clinic channels for multi-site groups, while independent operators rely on distributor-mediated relationships with extended lead times.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK IVF market rewards organizations that control scarce embryology talent and modular cryogenic infrastructure, with laboratory headcount constraints proving more binding than physical capacity expansion.
For Market Incumbents: Harden contractual lock-in with NHS-affiliated networks through long-term culture media supply agreements and embedded embryologist training programs. Deepen backward integration into cryopreservation kit manufacturing to offset gonadotropin cost volatility, while acquiring independent clinics in Yorkshire and North East to capture undersupplied patient flow. For New Entrants and Emerging Players: North England clinic density running 40-60% below London benchmarks offers the most penetrable white space for greenfield laboratory development. Target NHS Long-Term Plan commissioning expansion in Manchester and Leeds corridors, positioning for publicly funded cycle volume growth. Differentiate through time-lapse incubator partnerships with AI embryo selection platforms rather than competing on gonadotropin pricing. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across cryogenic storage infrastructure as HFEA storage limit consultations force modular nitrogen system upgrades. Prioritize multi-site clinic groups with existing frozen embryo inventory concentration and scalable laboratory information management systems. Monitor HFEA statutory storage limit amendments as the critical inflection signal for revenue model durability.| Strategic Initiative | Industry Significance |
|---|---|
| Embryologist Training Academy Development | Addresses Association of Clinical Embryologists certification bottleneck constraining national laboratory throughput expansion. |
| Modular Cryogenic Storage Deployment | Enables scalable nitrogen supply systems responding to HFEA storage limit policy uncertainty. |
| AI Embryo Selection Platform Integration | Converges time-lapse morphokinetic analysis with next-generation sequencing for premium service line positioning. |
| North England Greenfield Laboratory Network | Captures 40-60% clinic density gap against London benchmarks in fastest-expanding NHS commissioning regions. |
| Direct-to-Clinic Procurement Consolidation | Displaces distributor relationships through national framework participation with integrated care systems. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with fertility clinic laboratory directors, HFEA compliance officers, NHS commissioning leads, and embryology supply chain managers; and secondary validation against HFEA licensing databases, Care Quality Commission inspection reports, NHS Digital procurement frameworks, and pharmaceutical customs records. Bottom-up cycle volume modeling triangulated against top-down market sizing from gonadotropin shipment data and cryopreservation kit import declarations.
Forecast inputs considered treatment modality splits, patient age demographic shifts, technology adoption curves for time-lapse incubation, and regulatory scenario modeling for storage limit extensions. Segmentation dimensions included fresh versus frozen cycle pathways, private versus NHS funding routes, and geographic clinic density differentials. CAGRs were derived from procedure volume elasticity to funding access expansion and embryologist labor supply constraints across the projection horizon.
Practitioners should monitor HFEA consultation outcomes on statutory storage limits and NHS Long-Term Plan fertility access implementation for early signals requiring forecast revision. Cross-checking against HFEA mandatory outcome reporting databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Reproductive Health
Donor Egg IVF (in-Vitro Fertilization) Market
Reproductive Health
Surrogacy Market
Reproductive Health
US Sexual and Reproductive Health Clinics Market
Reproductive Health
Global Male Infertility Market
Reproductive Health
Global Genital Herpes Treatment Market
Reproductive Health
US Birth Centers Market
Reproductive Health
Asia-Pacific in Vitro Fertilization (IVF) Market
Reproductive Health
Assisted Reproductive Technology (ART) Market
Reproductive Health
Egg Freezing and Embryo Banking Market
Reproductive Health
IVF Services Market
Reproductive Health
Contraceptives Market
Reproductive Health
Egg Donation Market
Reproductive Health
Global Gynecology Drugs Market
Reproductive Health
Cervical Dysplasia Treatment Market
Reproductive Health
Fertility Services Market
Reproductive Health
Hormonal Contraception Market