
 IVF Services Market | 2026-2036
IVF Services Market Size, Share, and Industry Trends Forecast 2026-2036
IVF Services Market Intelligence
Referral networks between obstetrics practices and specialized fertility centers are reshaping patient flow patterns in the IVF services landscape. Vitrolife AB leverages its embryo culture media portfolio to sustain leadership in laboratory consumables. CooperSurgical Inc. anchors North American distribution through its integrated device and media offerings. Monash IVF Group dominates Asia-Pacific service delivery with clinic networks across Australia and Southeast Asia.
IVF services encompass clinical procedures, laboratory processing, and cryopreservation workflows that facilitate conception outside the human body, typically involving controlled ovarian stimulation, oocyte retrieval, fertilization in specialized incubators maintaining temperature at 37 degrees Celsius with 5% carbon dioxide, and embryo transfer or vitrification for storage. The primary commercial purpose centers on treating infertility pathologies while generating recurring revenue through multiple cycle attempts and adjunct genetic screening. Intracytoplasmic sperm injection commands premium positioning within service type segmentation due to its applicability in severe male factor cases. Package pricing models capture margin pools by bundling medications, procedures, and cryostorage into predictable patient commitments. Fertility clinics represent the most consolidated end-user channel, with independent women's health centers facing pressure to affiliate with larger reproductive networks.
FDA oversight of assisted reproductive technology devices under 21 CFR Part 1271 governs tissue handling standards in the United States, while the EU Tissue and Cells Directive mandates traceability requirements across European member states. China's National Medical Products Administration imposes Good Tissue Practice standards on imported cryopreservation media and culture systems. Stakeholders must monitor evolving preimplantation genetic testing regulations and reimbursement policy shifts that will determine accessible patient volumes and service mix priorities.
Market Dynamics
Regulatory fragmentation across tissue-handling jurisdictions is forcing service providers to maintain parallel quality systems while cross-border patient flows concentrate treatment volumes in regulatory-friendly clusters.
Growth Catalysts
- EU Tissue and Cells Directive:Mandatory traceability requirements accelerate laboratory digitization and create competitive moats for compliant operators across European member states.
- Intracytoplasmic sperm injection:Male-factor infertility protocols expand addressable patient populations beyond traditional IVF candidacy criteria.
- Spain:Liberal donor anonymity laws and specialized reproductive medicine clusters attract cross-border fertility tourism from restrictive jurisdictions.
Market Restraints
- Culture media supply:Three manufacturers control global embryo culture media production, creating input concentration risk for independent clinics.
- FDA 21 CFR Part 1271:Tissue-handling compliance costs disproportionately burden smaller fertility networks versus consolidated chains.
- Ovarian stimulation pharmaceuticals:Recombinant gonadotropin pricing volatility compresses margin predictability on medication-inclusive packages.
Strategic Opportunities
- Preimplantation genetic testing:Regulatory clarity on embryo screening protocols opens premium service tiers in jurisdictions with favorable genetic counseling frameworks.
- Vitrification technology:Cryopreservation workflow automation converges with AI-assisted embryo grading to reduce embryologist labor intensity.
- Telemedicine-enabled consultations:Remote patient monitoring expands geographic catchment areas for established clinic networks.
Industry Challenges
- Embryologist certification:Specialized laboratory training pipelines fail to match clinic expansion rates, constraining service scalability.
- Laboratory information management system integration:Legacy patient record architectures resist seamless connectivity with modern cryostorage tracking platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IVF Services Market |
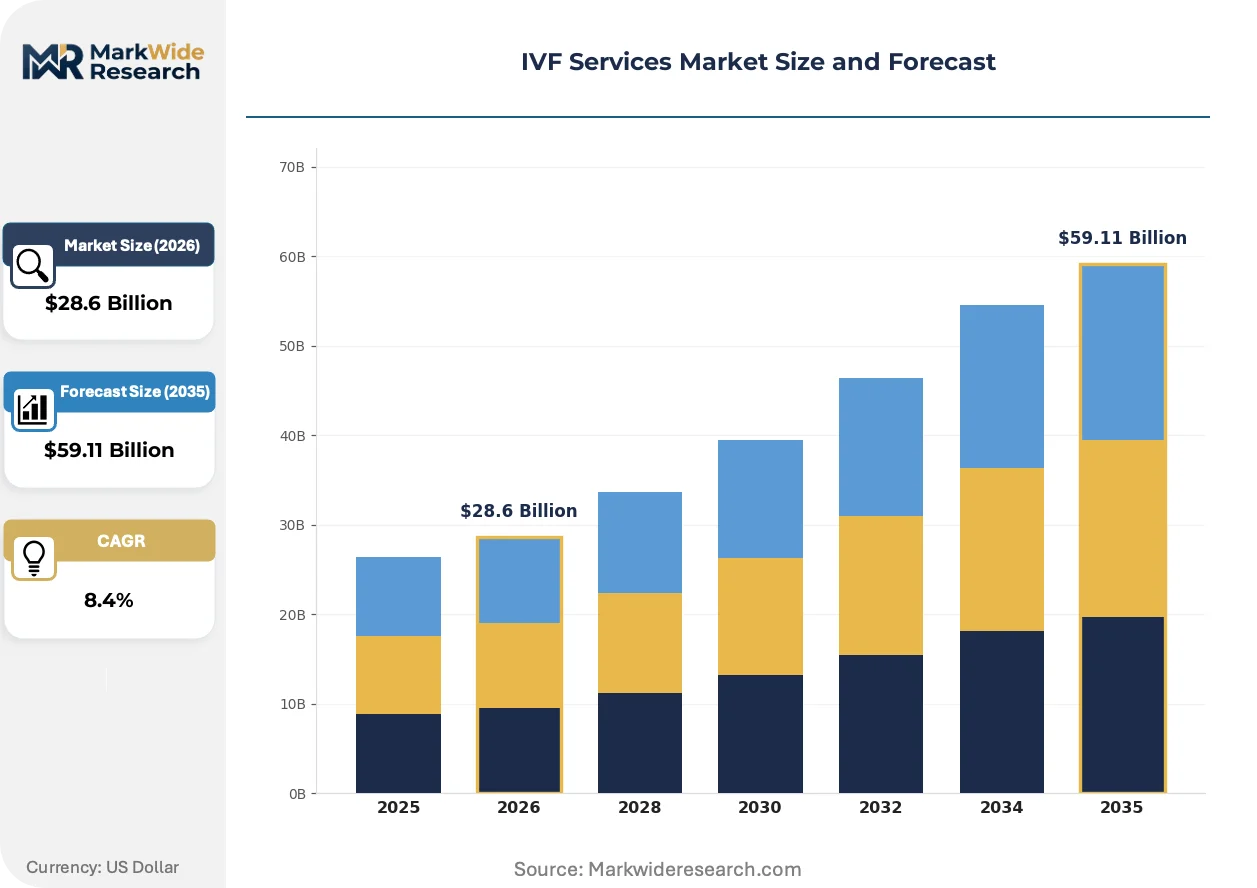
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $59.11 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: In Vitro Fertilization, Intracytoplasmic Sperm Injection, Egg Donation, Embryo Freezing End User: Fertility Clinics, Women’s Health Centers, Reproductive Specialists, Assisted Reproduction Units Application: Male Infertility, Female Infertility, Genetic Disorders Screening, Unexplained Infertility Pricing Model: Package Pricing, Pay Per Cycle, Subscription Plans, Consultation Fees |
| Companies Covered | Vitrolife AB, Merck KGaA, CooperSurgical Inc., Thermo Fisher Scientific Inc., CARE Fertility, Monash IVF Group, CCRM Fertility, Kindbody, IVF Australia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IVF Services Market Strategic Shifts & Innovations
Automation and algorithmic decision-support are compressing traditional embryology workflows while regulatory technology investments reshape compliance economics across multi-site operators.
Time-lapse incubation systems with integrated morphokinetic analysis are collapsing the historical reliance on static embryo observation protocols. Fertility networks with high cycle volumes deploy these platforms to reduce manual assessment labor and standardize selection criteria. The technology is collapsing variability in embryo grading consistency that previously required senior embryologist oversight.
China's National Medical Products Administration Good Tissue Practice standards impose batch-release documentation on imported cryopreservation media. Domestic manufacturers gain procurement preference as foreign suppliers navigate extended customs clearance protocols. European media exporters face margin compression from accelerated local certification investments.
Subscription-based fertility preservation packages disperse upfront cryostorage costs across extended payment horizons. Younger patient segments in metropolitan United States markets favor this structure over traditional lump-sum embryo banking. Employer-sponsored fertility benefits increasingly specify these arrangements in covered service catalogs.
IVF Services Market Segmentation
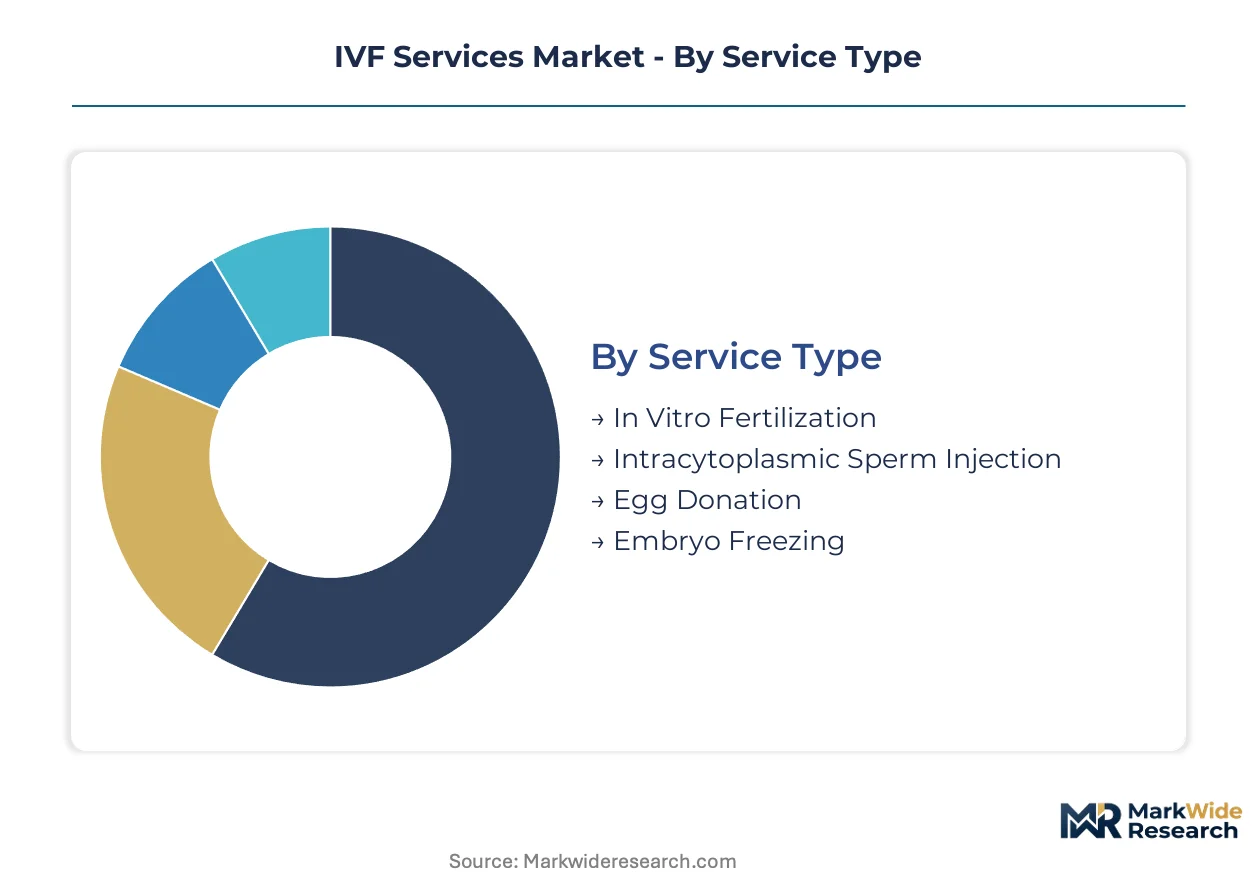
IVF services fragment across four distinct taxonomies that govern how providers structure revenue, deploy laboratory capacity, and target patient populations. Each segmentation layer reveals divergent margin profiles and operational intensity requirements.
Service Type:
Cycle velocity varies dramatically across service modalities, with some protocols completing in weeks while others span months of donor matching and cryostorage.
- In Vitro Fertilization:Standard IVF combines controlled ovarian stimulation with conventional fertilization in laboratory incubators. Demand concentrates in Spain and the United States where regulatory clarity supports high-throughput clinic operations.
- Intracytoplasmic Sperm Injection:ICSI involves direct sperm injection into oocytes using micromanipulation equipment, commanding premium positioning for severe male factor cases. United States fertility networks report ICSI penetration exceeding 70% of fresh cycles as embryologists favor its fertilization certainty over conventional methods.
- Egg Donation:Third-party oocyte procurement with donor screening and synchronization protocols.
- Embryo Freezing:Vitrification workflows for fertility preservation and surplus embryo banking.
Standard IVF anchors the volume base while ICSI gains share at the steepest rate.
End User:
Customer concentration shapes procurement patterns, with consolidated networks extracting supplier discounts unavailable to fragmented independent operators.
- Fertility Clinics:Dedicated reproductive medicine facilities with integrated laboratories and embryology staff. Spain's Barcelona and Madrid clusters attract cross-border patients seeking donor anonymity protections unavailable in home jurisdictions.
- Women’s Health Centers:General obstetrics practices with limited ART capabilities. China's tier-one cities host expanding networks as NMPA Good Tissue Practice standards drive affiliation with larger groups for compliance cost sharing.
- Reproductive Specialists:Individual physician practices referring complex cases to full-service laboratories.
- Assisted Reproduction Units:Hospital-embedded departments with academic research mandates.
Fertility clinics capture the dominant revenue share while women's health centers expand most quickly through network affiliation.
Application:
Clinical indication determines laboratory workflow complexity and pharmaceutical intensity, with genetic screening applications requiring extended embryology labor.
- Male Infertility:Azoospermia and severe oligospermia cases requiring surgical sperm retrieval. United States urology-reproductive medicine referral channels concentrate these patients in ICSI-capable centers.
- Female Infertility:Tubal factor, endometriosis, and diminished ovarian reserve presentations. China's urban fertility networks report rising patient volumes as delayed childbearing extends treatment candidacy windows.
- Genetic Disorders Screening:Preimplantation genetic testing for monogenic conditions and chromosomal abnormalities.
- Unexplained Infertility:Diagnostic categories where standard workup reveals no identifiable pathology.
Female infertility indications dominate cycle volume while genetic screening climbs fastest on regulatory clarity in permissive jurisdictions.
Pricing Model:
Revenue predictability separates models, with subscription structures smoothing cash flow against the lumpiness of pay-per-cycle arrangements.
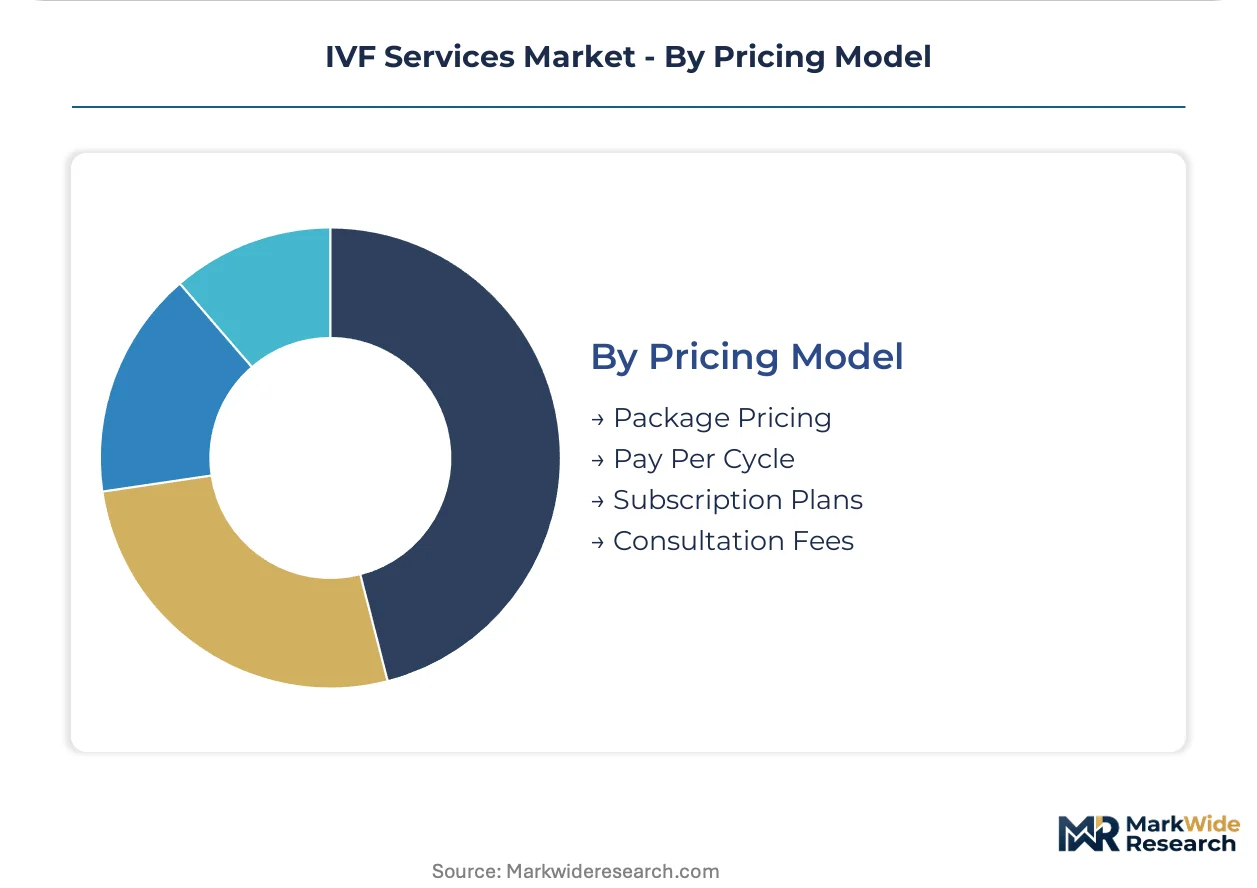
- Package Pricing:Bundled medications, procedures, and cryostorage into single-commitment contracts. United States employer benefit administrators increasingly specify these arrangements to cap exposure on fertility coverage.
- Pay Per Cycle:Itemized billing for discrete treatment attempts. Spain's fertility tourism segment favors this transparency for cross-border patients comparing jurisdictional cost structures.
- Subscription Plans:Extended payment horizons for fertility preservation services.
- Consultation Fees:Standalone diagnostic and counseling revenue separate from treatment.
Package pricing holds the volume base while subscription plans expand most quickly among younger metropolitan patient segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reimbursement policy shifts and donor anonymity frameworks are redirecting patient flows toward jurisdictions with favorable regulatory environments. Spain's liberal tissue donation laws attract cross-border fertility tourism from restrictive European markets. China's NMPA Good Tissue Practice standards are accelerating domestic laboratory certification investments.
United States
Employer-sponsored fertility benefits now cover over 40% of large corporate plans, driving insured patient volumes into specialized networks. FDA 21 CFR Part 1271 mandates tissue-handling documentation that favors consolidated clinic chains over independent operators. Boston and San Francisco host the densest concentrations of academic-affiliated reproductive medicine centers.
Spain
Anonymous donor oocyte availability supports cycle volumes exceeding domestic demand by threefold. The EU Tissue and Cells Directive traceability requirements have digitized Barcelona's laboratory workflows ahead of Mediterranean competitors. Madrid clinics capture premium positioning through English-language patient coordination services.
China
Delayed childbearing in tier-one cities extends treatment candidacy windows beyond age 35. NMPA batch-release documentation for imported culture media creates procurement preference for domestic suppliers. Shanghai and Beijing fertility networks are absorbing compliance costs that pressure smaller provincial operators.
Australia
Medicare reimbursement caps limit out-of-pocket exposure for standard IVF cycles. TGA oversight of assisted reproductive technology devices aligns with ISO 13485 quality management expectations. Sydney and Melbourne clinic clusters dominate national cycle volume through metropolitan patient density.
United Kingdom
NHS funding rationing pushes one-third of patients toward private pay options. HFEA licensing requirements for embryology staffing ratios constrain clinic expansion rates. London's Harley Street corridor maintains premium positioning through consultant-led service models.
IVF Services Market Key Industry Players
On the supply side, the industry is bifurcated between integrated service networks and specialized consumables manufacturers. Laboratory media production concentrates among three global suppliers while fertility clinic operations fragment across regional and national chains. Strategic archetypes include: vertically integrated device-and-service conglomerates, pure-play laboratory consumables specialists, and multi-site clinic operators with captive patient bases. Dominant competitive moves encompass geographic network expansion through clinic acquisitions and backward integration into cryopreservation media manufacturing.
Within the consumables tier, Vitrolife AB and Merck KGaA exemplify European-headquartered suppliers with embryo culture media portfolios. Among North American service operators, CooperSurgical Inc. occupies a position spanning both device distribution and laboratory supplies. Monash IVF Group represents the Asia-Pacific clinic network archetype with multi-country service delivery capabilities.
| Leading Market Players |
|---|
| Vitrolife AB |
| Merck KGaA |
| CooperSurgical Inc. |
| Thermo Fisher Scientific Inc. |
| CARE Fertility |
| Monash IVF Group |
| CCRM Fertility |
| Kindbody |
| IVF Australia |
| Others |
Cost & Logistics Intelligence
Three manufacturers controlling global embryo culture media production concentrate upstream supply in Sweden, Germany, and the United States, directing margin capture toward integrated fertility networks that negotiate volume discounts unavailable to independent clinics.
Pricing Analysis
Volume-discount tiering structures separate consolidated clinic chains from independent operators across medication-inclusive package contracts. Price differentiation hinges on ICSI capability certification and geographic proximity to reproductive medicine clusters. Pricing pressure stems from recombinant gonadotropin cost volatility compressing predictability on bundled offerings. Employer-sponsored benefit administrators demonstrate lowest price sensitivity; self-pay fertility tourism patients exhibit highest.
Supply Chain Analysis
Upstream feedstock for embryo culture media draws from pharmaceutical-grade chemical synthesis concentrated in Germany, Sweden, and Switzerland. Critical inputs encompass recombinant proteins, synthetic hormones, and medical-grade polymers. Single-source vulnerability runs through the trio of media suppliers dominating laboratory consumables. Distribution runs through direct procurement contracts between manufacturers and consolidated clinic networks, bypassing traditional medical device distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
IVF services are approaching a platform-economics inflection as telemedicine-enabled consultations and AI-assisted embryo grading create interoperability standards that favor networks with integrated data architectures over fragmented independent operators.
For Market Incumbents: Insulate laboratory margins through backward integration into cryopreservation media manufacturing, countering input concentration risk from the three dominant suppliers. Secure embryologist certification pipelines through academic partnerships, addressing the capability scarcity constraining clinic expansion rates.
For New Entrants and Emerging Players: Establish a beachhead in employer-sponsored fertility benefits administration, the fastest-expanding reimbursement channel. Target metropolitan markets with subscription-based fertility preservation packages, leveraging payment-horizon flexibility to differentiate from lump-sum competitors.
For Investors and Strategic Acquirers: Capital is best deployed toward multi-site clinic operators with captive patient bases and demonstrated compliance with FDA 21 CFR Part 1271 or EU Tissue and Cells Directive standards. Watch for regulatory clarity on preimplantation genetic testing protocols as the signal indicating premium service tier viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Laboratory Information Management System Integration | Seamless connectivity with cryostorage tracking platforms reduces embryologist labor intensity across high-volume networks. |
| Time-Lapse Incubation Platform Deployment | Morphokinetic analysis standardizes embryo selection criteria previously requiring senior embryologist oversight. |
| Telemedicine-Enabled Consultation Expansion | Remote patient monitoring extends geographic catchment areas for established clinic networks beyond metropolitan cores. |
| Preimplantation Genetic Testing Service Launch | Regulatory clarity on embryo screening protocols opens premium tiers in jurisdictions with favorable genetic counseling frameworks. |
| Vitrification Technology Automation | Cryopreservation workflow convergence with AI-assisted grading compresses traditional embryology labor requirements. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with reproductive endocrinologists, embryology laboratory directors, fertility clinic procurement managers, and employer benefits administrators; and secondary validation against FDA 510(k) filings, EUDAMED device registrations, hospital procurement databases, and GPO contract repositories. Bottom-up cycle volume estimates triangulated against top-down service revenue benchmarks.
Forecast inputs span service type segmentation, end-user channel concentration, application indication mix, and pricing model adoption patterns across the projection horizon. CAGRs derive from regression analysis against historical cycle velocity, reimbursement policy trajectories, and regulatory approval timelines for preimplantation genetic testing protocols.
Stress conditions across gonadotropin pricing volatility, embryologist certification pipeline constraints, and cross-border patient flow restrictions were modeled; outcomes outside those bands fall beyond the analytical envelope. Cross-checking against national fertility registry data and employer benefit administrator coverage disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Reproductive Health
Hormonal Contraception Market
Reproductive Health
Donor Egg IVF (in-Vitro Fertilization) Market
Reproductive Health
Cervical Dysplasia Treatment Market
Reproductive Health
Assisted Reproductive Technology (ART) Market
Reproductive Health
Ovum Egg Banking Market
Reproductive Health
In Vitro Fertilization (IVF) Market
Reproductive Health
Fertility Services Market
Reproductive Health
Global Male Infertility Market
Reproductive Health
Egg Freezing and Embryo Banking Market
Reproductive Health
US Contraceptive Market
Reproductive Health
Donor Egg IVF Services Market
Reproductive Health
Doula and Birth Coaching Services Market
Reproductive Health
Contraceptives Market
Reproductive Health
Intrauterine Insemination (IUI) Treatment Market
Reproductive Health
Europe in Vitro Fertilization (IVF) Market
Reproductive Health
Global Genital Herpes Treatment Market