
 Doula and Birth Coaching Services Market | 2026-2036
Doula and Birth Coaching Services Market Size, Share, and Industry Trends Forecast 2026-2036
Doula and Birth Coaching Services Market Foresight
Certified birth worker availability is bifurcating the competitive landscape between credentialed training networks and informal community practitioners. DONA International sustains the largest certification footprint across North America. ProDoula differentiates through business mentorship bundled with doula credentials. Mama Glow anchors premium urban markets with culturally centered training programs.
Doula and birth coaching services encompass continuous physical, emotional, and informational support during pregnancy, labor, and the postpartum period, typically delivered through 12-40 hour engagement models that include prenatal visits, birth attendance, and lactation guidance. The primary commercial purpose is reducing cesarean rates, shortening labor duration, and improving patient satisfaction scores for payers and health systems. In-person support commands the highest fee structures and deepest provider relationships, while virtual coaching scales fastest among rural and underinsured populations. Package deals dominate pricing architecture as clients prefer bundled prenatal-through-postpartum commitments over hourly billing.
Medicaid reimbursement policies in the US, the EU's cross-border healthcare directive, and ISO standards for perinatal education collectively shape market access and service legitimacy. State-level Medicaid expansion in the US directly determines addressable demand for certified doulas in low-income communities. Stakeholders must monitor regulatory harmonization between private insurance codes and public reimbursement frameworks to capture sustainable revenue pools.
Market Dynamics
Medicaid reimbursement expansion across US states is restructuring how doula services reach low-income birthing populations, converting cash-pay community practitioners into credentialed providers within formal healthcare billing systems.
Growth Catalysts
- Medicaid Billing Codes:State-level Medicaid programs in Minnesota, Oregon, and New Jersey now reimburse certified doula services under dedicated CPT codes, expanding addressable demand among previously uninsured populations.
- Hospital System Integration:Maternal care pathways at urban birth centers in California and Texas now embed doula support as standard protocol, creating institutional procurement channels.
- Telehealth Infrastructure:HIPAA-compliant video platforms enable rural and underinsured clients to access virtual birth coaching, extending service reach beyond metropolitan service areas.
Market Restraints
- Certification Cost Barriers:DONA International and ProDoula credentialing programs require $800-$1,200 in training fees, excluding community-based practitioners from Medicaid reimbursement eligibility.
- Reimbursement Rate Compression:State Medicaid programs cap doula reimbursement at $300-$900 per birth, below market rates for comprehensive prenatal-through-postpartum packages.
- Supply Concentration in Urban Corridors:Certified birth workers cluster in Los Angeles, New York City, and Houston metropolitan areas, leaving rural counties with practitioner shortages exceeding 70% of demand.
Strategic Opportunities
- Community Health Worker Convergence:Integration of doula services with federally qualified health center programs creates reimbursement pathways through HRSA funding streams.
- Employer Benefit Expansion:Large self-insured employers in technology and finance sectors add doula coverage as fertility and maternal health benefits, bypassing traditional insurance intermediaries.
- Postpartum Medicaid Extension:The American Rescue Plan Act's 12-month postpartum coverage option in 35 states extends reimbursable service windows for lactation and mental health support.
Industry Challenges
- Credentialing Timeline Friction:DONA certification requires 15 hours of documented birth attendance, creating 12-18 month entry barriers for aspiring practitioners.
- Interoperability with EHR Systems:Doula documentation lacks standardized data fields in Epic and Cerner platforms, complicating care coordination with obstetric teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Doula and Birth Coaching Services Market |
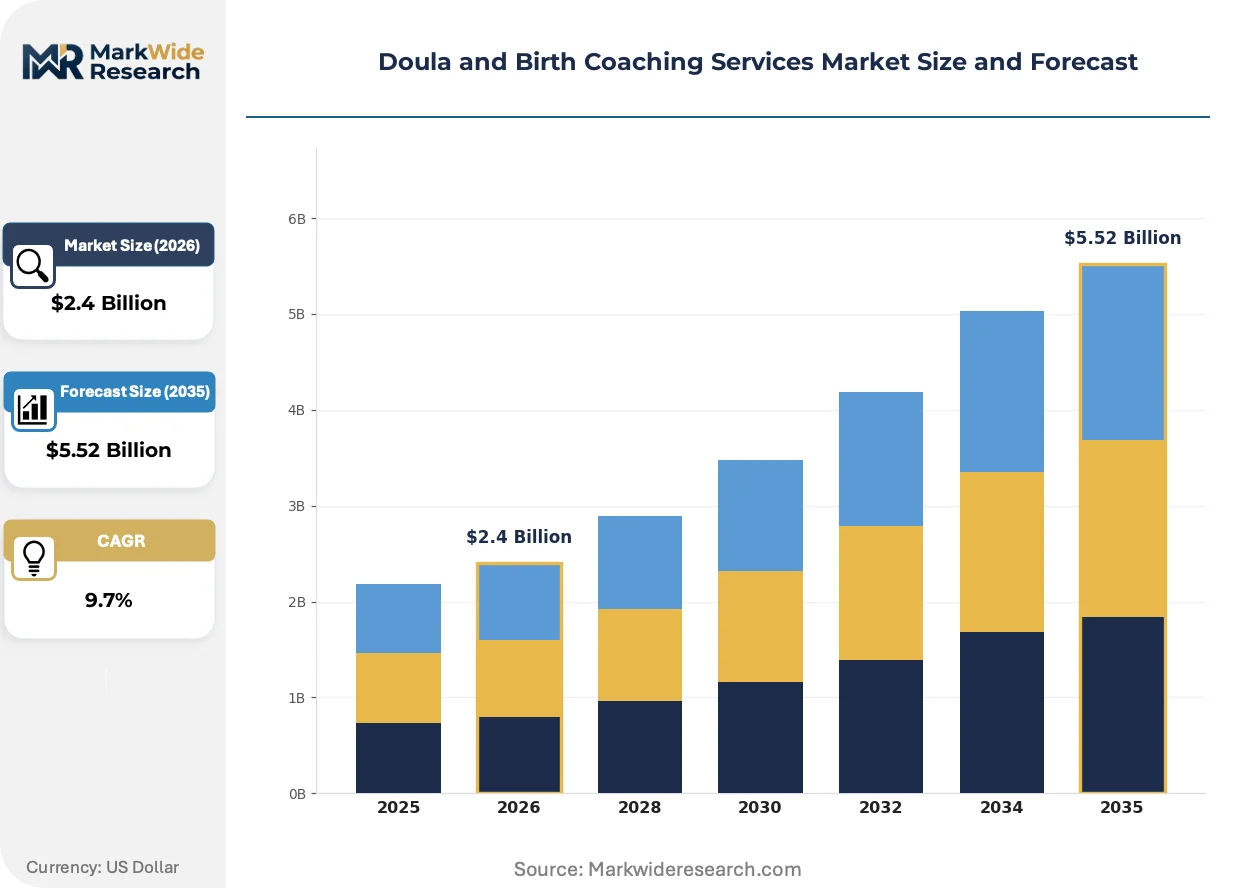
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.52 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: In-Person Support, Virtual Coaching, Group Classes, Postpartum Support Client Type: Expecting Mothers, Couples, Single Parents, Healthcare Providers Delivery Model: One-on-One Sessions, Workshops, Online Courses, Community Programs Pricing Model: Hourly Rate, Package Deals, Subscription Plans, Gift Certificates |
| Companies Covered | Birth Coach Method, The Childbirth and Postpartum Professional Association (CAPPA), DONA International, MaternityWise International, ProDoula, BEST Doula Training, Childbirth Professionals International, SMC Full Circle Doula Birth Companions, Mama Glow, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Doula and Birth Coaching Services Market Shifts & Advancements
Technology and policy are converging to transform how birth support is delivered, reimbursed, and integrated into clinical workflows. Three developments are reshaping competitive positioning.
Virtual birth coaching platforms are supplanting traditional in-person-only service models. These HIPAA-compliant telehealth systems enable real-time labor support via video and messaging. Rural health networks in Montana and North Dakota deploy these tools to serve dispersed populations. The technology is compressing geographic barriers that previously limited practitioner market reach.
The EU's cross-border healthcare directive and ISO standards for perinatal education are harmonizing credential recognition across member states. This regulatory convergence enables certified doulas trained in France or Germany to practice in neighboring jurisdictions without re-certification. Mobile practitioners and digital health platforms are responding by building cross-border service networks.
Subscription-based maternity support packages are displacing traditional hourly billing. Expectant parents in metropolitan markets prefer fixed-fee commitments covering prenatal education, birth attendance, and six-week postpartum follow-up. This consumption-pattern shift pressures independent practitioners to formalize service bundles or affiliate with platform intermediaries that standardize pricing and scheduling.
Doula and Birth Coaching Services Market Segmentation
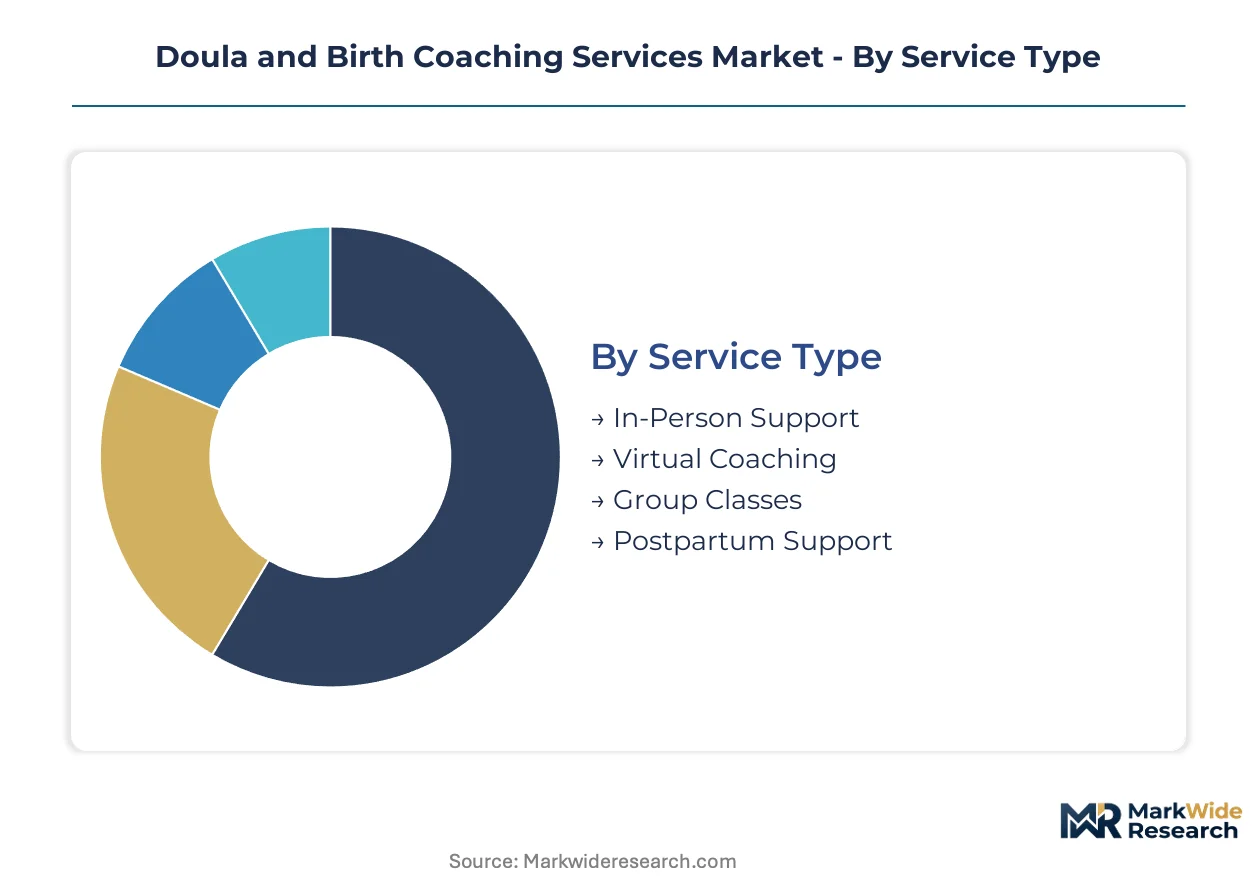
Service differentiation in the Doula and Birth Coaching Services Market determines reimbursement eligibility, client acquisition costs, and practitioner income stability. Segmentation reveals which delivery formats capture Medicaid dollars versus private-pay premiums, and which client categories drive volume versus margin.
Service Type:
Virtual coaching platforms exert substitution pressure on traditional in-person support as telehealth infrastructure matures and rural access gaps persist.
- In-Person Support:Continuous physical presence during labor and delivery with hands-on comfort measures and real-time advocacy. Hospital systems in California and Texas embed this service into maternal care pathways as standard protocol, though supply concentration in urban corridors limits rural availability.
- Virtual Coaching:HIPAA-compliant video and messaging platforms delivering real-time labor guidance and prenatal education. Montana and North Dakota health networks deploy these tools to serve dispersed populations where certified practitioner density falls below operational thresholds.
- Group Classes:Cohort-based prenatal education covering childbirth preparation and newborn care fundamentals. Federally qualified health centers bundle these into HRSA-funded community health worker programs.
- Postpartum Support:Lactation consulting and mental health check-ins during the 12-month coverage window extended under the American Rescue Plan Act in 35 states.
In-Person Support retains volume leadership; Virtual Coaching holds the steepest expansion curve.
Client Type:
Cost tier stratification separates Medicaid-eligible populations from employer-sponsored benefit recipients and private-pay clients seeking premium concierge services.
- Expecting Mothers:Individual clients purchasing direct-to-consumer packages or accessing services through insurance benefits. Self-insured employers in technology and finance sectors add doula coverage as fertility and maternal health perks, creating a high-margin channel distinct from public reimbursement.
- Couples:Partners seeking joint prenatal education and coordinated birth planning. Urban birth centers in New York and Houston metropolitan areas report this segment commands premium package pricing above Medicaid reimbursement caps.
- Single Parents:Clients requiring enhanced logistical and emotional support structures. Community-based practitioners in low-income neighborhoods serve this population through informal sliding-scale arrangements outside credentialed billing systems.
- Healthcare Providers:Obstetric practices and hospital systems contracting doula services to improve patient satisfaction scores and reduce cesarean rates. Procurement decisions hinge on EHR interoperability and standardized documentation protocols.
Expecting Mothers dominate addressable demand; Healthcare Providers deliver the most stable recurring revenue contracts.
Delivery Model:
Supply concentration among certified practitioners shapes which delivery models achieve scale versus remaining artisanal services.
- One-on-One Sessions:Personalized prenatal visits, birth attendance, and postpartum follow-up delivered through 12-40 hour engagement models. DONA International certification requirements of 15 documented births create 12-18 month entry barriers that constrain supply expansion.
- Workshops:Intensive weekend or multi-week group formats covering childbirth education and newborn care. Birth centers in California package these with facility-based delivery services to differentiate from hospital competitors.
- Online Courses:Self-paced modules accessible asynchronously through subscription platforms. These scale fastest among rural and underinsured populations beyond metropolitan service areas.
- Community Programs:Peer-based support networks operating through faith organizations and neighborhood collectives. Informal practitioners in these channels face exclusion from Medicaid reimbursement due to certification cost barriers of $800-$1,200.
One-on-One Sessions command the highest fee structures; Online Courses achieve the broadest geographic penetration.
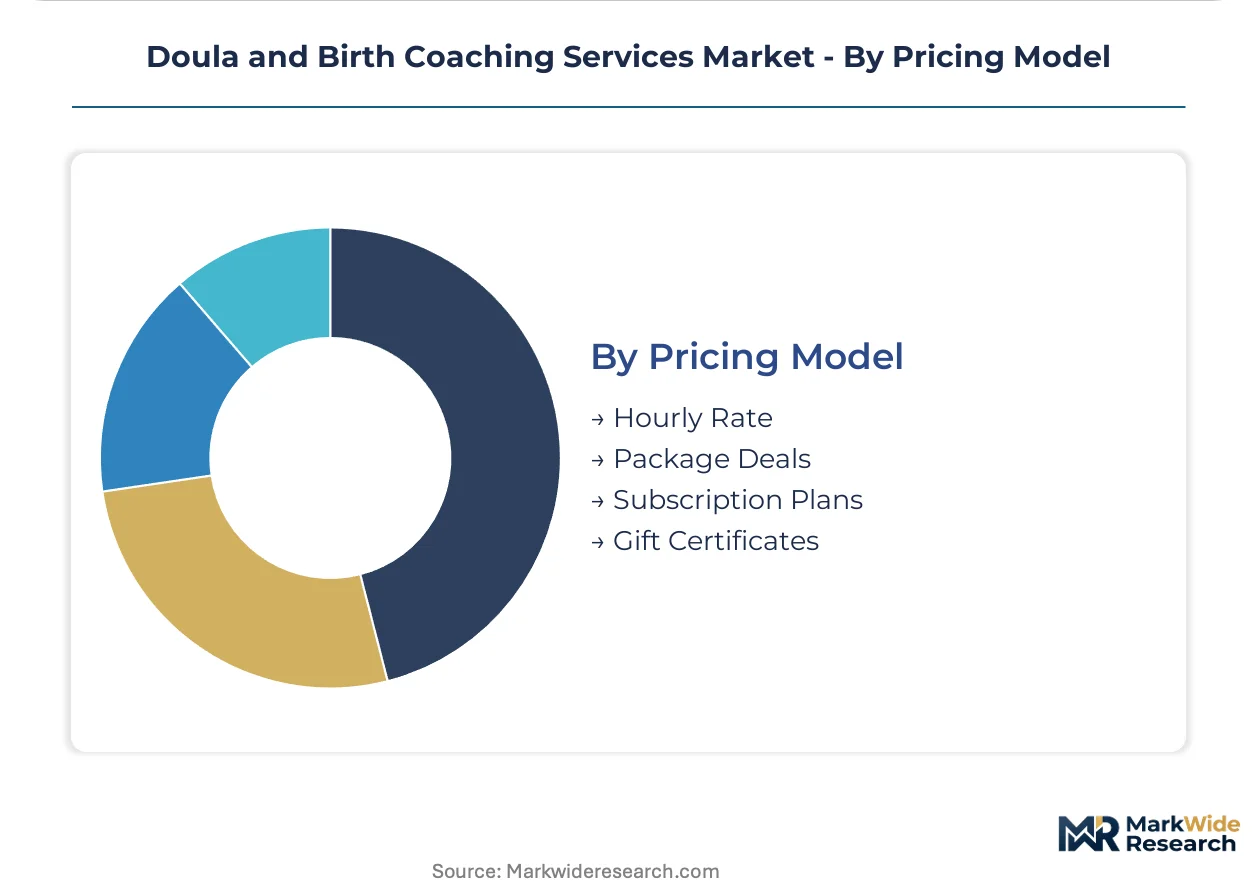
Pricing Model:
Margin structure varies dramatically across billing approaches, with subscription and package formats capturing client lifetime value more effectively than transactional hourly rates.
- Hourly Rate:Time-based billing for discrete consultations or labor support hours. State Medicaid programs cap reimbursement at $300-$900 per birth, compressing margins below market rates for comprehensive service.
- Package Deals:Bundled prenatal-through-postpartum commitments covering education, birth attendance, and lactation guidance. Metropolitan clients prefer this fixed-fee certainty over unpredictable hourly billing.
- Subscription Plans:Recurring monthly access to coaching calls, educational content, and community forums. Platform intermediaries standardize these offerings to reduce scheduling friction for independent practitioners.
- Gift Certificates:Prepaid service credits purchased by family members or employers as maternity benefits. Technology sector employers deploy these as fertility and wellness program components.
Package Deals dominate private-pay transaction volume; Subscription Plans are climbing the fastest as platform intermediaries consolidate practitioner networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
HIPAA compliance requirements anchor the United States as the dominant geography, with state-level Medicaid expansion creating divergent regulatory environments across sub-national markets. Certification recognition and reimbursement frameworks vary substantially, shaping where certified birth workers concentrate versus where informal practitioners operate.
United States
California, New York, and Texas concentrate certified practitioner supply as hospital systems embed doula support into maternal care pathways. Minnesota, Oregon, and New Jersey Medicaid programs now reimburse certified doula services under dedicated CPT codes. Urban birth centers in Los Angeles and Houston metropolitan areas actively contract certified birth coaches for institutional procurement channels.
Canada
Provincial health authorities in British Columbia and Ontario integrate doula services into publicly funded maternity care bundles. Health Canada guidelines recognize DONA International and CAPPA certifications for provincial reimbursement eligibility. Toronto and Vancouver metropolitan clusters sustain the highest practitioner density, with community health centers in Montreal expanding francophone birth support programs.
United Kingdom
NHS maternity transformation programs pilot doula integration in Greater London and Manchester health systems. The Care Quality Commission monitors perinatal education standards without mandating specific certification bodies. Private birth centers in Bristol and Edinburgh metropolitan areas command premium pricing for comprehensive prenatal-through-postpartum packages outside NHS reimbursement.
Germany
Statutory health insurance funds in Bavaria and North Rhine-Westphalia reimburse Hebamme-midwife services, creating competitive pressure on doula positioning. The Federal Joint Committee evaluates supplemental birth support for inclusion in standard care catalogs. Berlin and Hamburg urban corridors sustain independent practitioner networks serving expatriate and private-pay client segments.
Australia
Medicare reimbursement excludes doula services, concentrating demand in private health insurance channels and direct-to-consumer payment. The Therapeutic Goods Administration regulates perinatal education materials without certifying practitioner training programs. Sydney and Melbourne metropolitan areas host the largest certified practitioner populations, with telehealth platforms extending virtual coaching to Queensland and Western Australia rural zones.
Doula and Birth Coaching Services Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with DONA International sustaining the largest certification footprint across North America. ProDoula differentiates through business mentorship bundled with doula credentials, while Mama Glow anchors premium urban markets with culturally centered training programs. The competitive terrain separates credentialing bodies from service delivery platforms, with technology intermediaries emerging to consolidate practitioner scheduling and client acquisition. Strategic moves concentrate on Medicaid billing code navigation and hospital system partnership formation.
Within the credentialing archetype tier, DONA International and ProDoula exemplify divergent positioning strategies—DONA through volume certification reach, ProDoula through entrepreneur support bundling. Mama Glow occupies a position in the premium-tier vector with celebrity-affiliated urban programming. These three entities represent the dominant competitive anchors without exhaustively mapping the fragmented long tail of regional training collectives and informal community practitioners.
| Leading Market Players |
|---|
| Birth Coach Method |
| The Childbirth and Postpartum Professional Association (CAPPA) |
| DONA International |
| MaternityWise International |
| ProDoula |
| BEST Doula Training |
| Childbirth Professionals International |
| SMC Full Circle Doula Birth Companions |
| Mama Glow |
| Others |
Supply & Pricing Matrix
Virtual coaching platforms replacing in-person support as the default service modality simultaneously redistributes practitioner supply from urban corridors to rural catchment areas and compresses fee structures from premium package rates toward Medicaid reimbursement ceilings. This substitution dynamic fragments pricing power across delivery formats while extending addressable geography beyond metropolitan certification clusters.
Pricing Analysis
Metropolitan California commands package rates exceeding rural Medicaid caps by multiples, while Texas and New York corridors sustain premium pricing for hospital-embedded services. Three-tier pricing structure across DONA-certified premium providers, ProDoula-affiliated standard practitioners, and informal community economy tiers segments buyer access. Cost compression in Medicaid-reimbursed births intensifies because state programs cap payments below comprehensive service costs. Employer-sponsored benefit recipients exhibit least price sensitivity; uninsured rural populations face greatest affordability constraints.
Supply Chain Analysis
Practitioner certification costs create inbound barriers equivalent to logistics friction, with DONA and ProDoula training programs concentrated in United States, Canada, and United Kingdom metropolitan hubs. Training curricula, continuing education modules, and credentialing examinations draw from standardized DONA, CAPPA, and ISO perinatal education frameworks. Single-source vulnerability concentrates in DONA International's certification dominance across North American reimbursement eligibility. Distribution runs through hospital procurement channels, employer benefit administrators, and direct-to-consumer platform intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Medicaid reimbursement expansion constitutes a regulatory inflection converting informal community practice into credentialed healthcare billing, disrupting traditional cash-pay service models and formalizing supply-side entry barriers.
For Market Incumbents: Shield certification premium through accelerated DONA or ProDoula credentialing investments before Medicaid eligibility requirements harden. Vertical integration into hospital system EHR interoperability and standardized documentation protocols defends position against platform intermediaries consolidating scheduling and client acquisition.
For New Entrants and Emerging Players: Rural telehealth service gaps where certified practitioner density falls below operational thresholds offer white-space expansion beyond urban supply concentration. Montana and North Dakota health networks present most penetrable geography for HIPAA-compliant virtual coaching deployment. Go-to-market through federally qualified health center HRSA funding streams bypasses direct Medicaid billing complexity.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed telehealth platforms consolidating independent practitioner networks under subscription-based maternity support packages. Long-term viability hinges on regulatory harmonization between private insurance codes and public reimbursement frameworks. Watch state-level Medicaid expansion momentum as inflection indicator for addressable demand scaling.
| Strategic Initiative | Industry Significance |
|---|---|
| Medicaid Billing Code Navigation | Secures reimbursement eligibility under Minnesota, Oregon, and New Jersey CPT frameworks. |
| Hospital System Partnership Formation | Embeds services into California and Texas maternal care pathways as standard protocol. |
| Telehealth Platform Integration | Extends reach through HIPAA-compliant video infrastructure to rural Montana and North Dakota. |
| Certification Investment Acceleration | Meets DONA's 15-documented-birth requirement for Medicaid eligibility before barriers rise. |
| EHR Interoperability Development | Resolves documentation friction with Epic and Cerner platforms for care coordination. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with DONA-certified doulas, ProDoula-affiliated trainers, hospital maternal care pathway administrators, Medicaid program officers in Minnesota and Oregon, and employer benefits managers at self-insured technology firms. Secondary validation drew from CMS Medicaid reimbursement databases, state health department policy filings, DONA International certification records, hospital procurement contract registries, and ISO perinatal education standards. Bottom-up practitioner supply estimates triangulated against top-down payer expenditure data.
Across the analysis window, projections model service type segmentation between in-person and virtual delivery, client type stratification across Medicaid-eligible and employer-sponsored populations, and pricing model evolution from hourly toward subscription structures. CAGRs derive from Medicaid expansion adoption curves, hospital system integration timelines, and telehealth platform penetration rates in designated rural health professional shortage areas.
Forecasts assume regulatory continuity in US state Medicaid programs and EU cross-border healthcare directive harmonization; material policy shifts would require re-modeling. Certification requirement changes, reimbursement rate compression beyond current caps, or EHR interoperability standardization delays represent specific revision triggers. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Reproductive Health
Vaginal Exam Specula Market
Reproductive Health
Smart Fertility Tracker Market
Reproductive Health
Assisted Reproductive Technology (ART) Market
Reproductive Health
Intrauterine Insemination (IUI) Treatment Market
Reproductive Health
US Contraceptive Market
Reproductive Health
Pregnancy Care Products Market
Reproductive Health
Cervical Dysplasia Treatment Market
Reproductive Health
Global Cervical Dysplasia Market
Reproductive Health
Global Male Infertility Market
Reproductive Health
Contraceptives Market
Reproductive Health
Gamete Preservation Market
Reproductive Health
Fertility Treatments Market
Reproductive Health
Fertility Services Market
Reproductive Health
UK in Vitro Fertilization (IVF) Market
Reproductive Health
Surrogacy Market
Reproductive Health
Cryopreservation for in-Vitro Fertilization (IVF) Market