
 Smart Fertility Tracker Market | 2026-2036
Smart Fertility Tracker Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Fertility Tracker Market Outlook
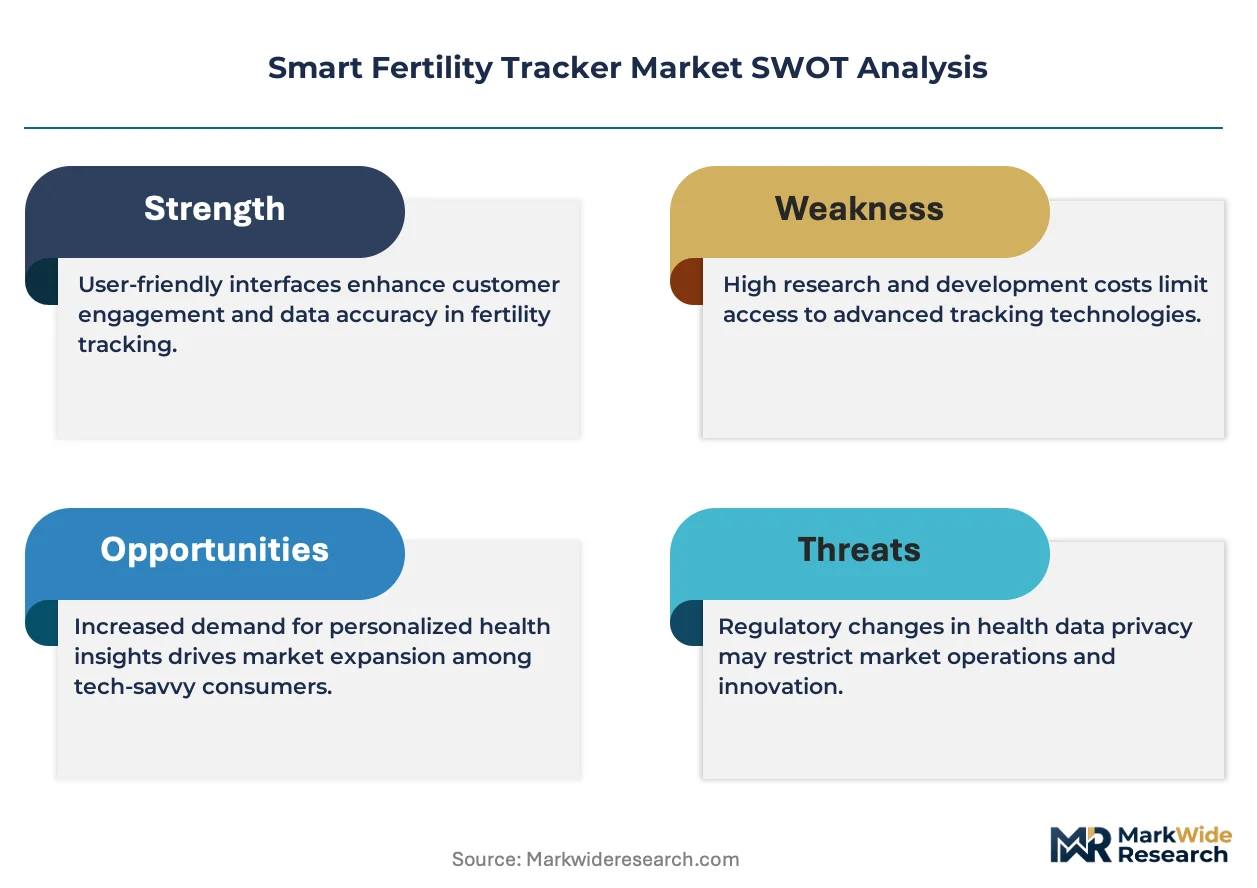
Shortage of clinical data scientists fluent in reproductive endocrinology is collapsing development timelines for algorithm training across the sector. Ava AG leverages its Zurich-based research team to sustain European regulatory credibility through BSI-notified body engagement. Tempdrop anchors its position via proprietary axillary temperature sensing hardware that controls manufacturing quality in-house. Natural Cycles competes on the strength of its FDA-cleared algorithm, occupying a distinctive regulatory tier that positions the brand in provider-channel discussions.
Smart fertility trackers comprise wearable, app-based, and sensor-integrated systems that measure basal body temperature, luteinizing hormone, or progesterone metabolites to predict ovulation windows with quantified precision. These devices serve both individual family-planning decisions and clinical fertility treatment protocols by reducing cycle uncertainty through continuous biomarker capture. Wearable devices and biometric sensors lead current revenue contribution due to hardware margins and replacement purchase cycles, while artificial intelligence and data analytics segments represent the fastest-expanding margin pools as subscription-based algorithm refinement commands recurring revenue. Mobile apps remain structurally constrained by platform-store fee structures and privacy compliance costs that compress net margins relative to integrated hardware-software bundles.
FDA Software as a Medical Device frameworks, EU MDR Class IIa requirements, and HIPAA data governance standards collectively shape product architecture, forcing developers to segregate health records from analytics pipelines or risk market access denial. GDPR and state-level US privacy statutes add jurisdictional fragmentation that increases compliance expenditure for cross-border deployment. Stakeholders must monitor evolving regulatory distinctions between wellness and medical device classifications, as reclassification rulings could abruptly alter competitive moats and channel economics for algorithm-dependent offerings.
Market Dynamics
Algorithmic fertility prediction is decomposing the traditional diagnostic hierarchy, forcing hardware manufacturers to defend margin through sensor precision while software-only entrants capture recurring revenue from clinical-grade analytics.
Growth Catalysts
- FDA Software as a Medical Device pathway:The FDA's SaMD framework accelerates commercial entry for algorithm developers by separating software validation from hardware certification timelines.
- Employer-sponsored fertility benefits:Large US employers expanding reproductive health coverage normalize device reimbursement and reduce out-of-pocket price sensitivity among target consumers.
- Continuous biomarker sensing:Wearable temperature and hormone sensors replace discrete testing with passive data streams that improve prediction accuracy through longitudinal pattern recognition.
Market Restraints
- EU MDR Class IIa compliance costs:European notified body backlogs and clinical evidence requirements extend certification timelines to 18-24 months for algorithm-dependent devices.
- Silicon sensor supply concentration:Discrete temperature and optical sensor fabrication concentrates in Taiwan and South Korea, exposing hardware manufacturers to single-source disruption risk.
- HIPAA-GDPR jurisdictional friction:Cross-border data transfer restrictions force redundant infrastructure deployment and fragment analytics training datasets across regulatory boundaries.
Strategic Opportunities
- Underpenetrated fertility clinic integration:US reproductive endocrinology practices lack standardized remote monitoring protocols, creating first-mover advantage for platform vendors with EHR interoperability.
- Progesterone metabolite sensing convergence:Combination of microfluidic sampling with smartphone-read colorimetric assays enables at-home luteal phase confirmation without laboratory processing.
- Direct-to-consumer channel expansion:Specialty pharmacy and telehealth platforms bypass traditional retail markup and capture patient relationship data for algorithm refinement.
Industry Challenges
- Reproductive endocrinology data science scarcity:Clinical validation of fertility algorithms requires rare hybrid expertise in hormonal physiology and machine learning pipeline architecture.
- Legacy EHR integration complexity:Fertility clinic management systems lack standardized APIs, forcing custom integration projects that consume implementation resources and delay revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Fertility Tracker Market |
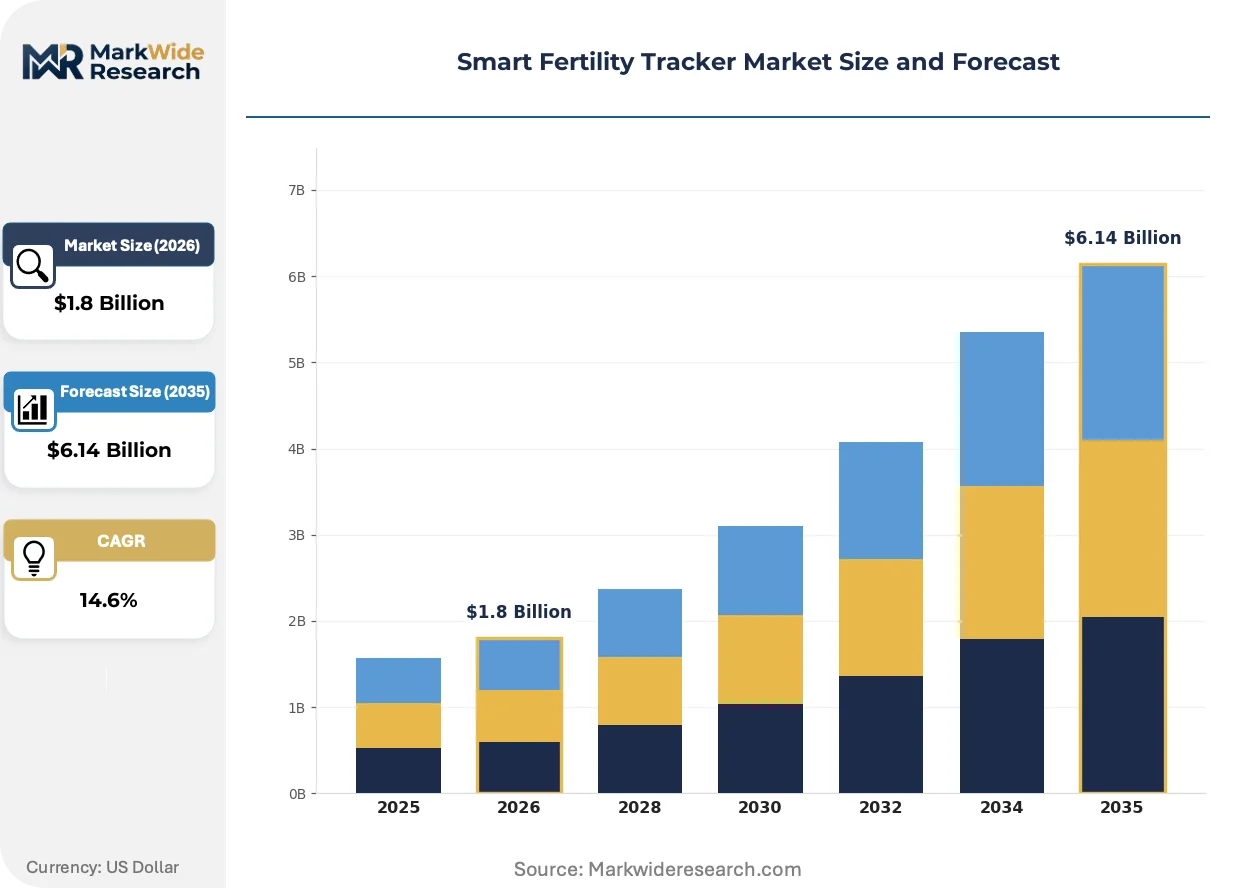
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Mobile Apps, Diagnostic Tools, Biometric Sensors Technology: Bluetooth, Artificial Intelligence, Data Analytics, Cloud Computing End User: Single Women, Couples, Healthcare Providers, Fertility Clinics Application: Cycle Tracking, Ovulation Prediction, Hormone Monitoring, Fertility Awareness |
| Companies Covered | Ava AG, Tempdrop, Natural Cycles, Clearblue, Mira, OvuSense, Kindara, Premom, Inito, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Fertility Tracker Market Strategic Shifts
Continuous biomarker capture is displacing episodic diagnostic testing across family planning and fertility treatment protocols, compressing the interval between physiological change and clinical response.
Multi-sensor fusion architectures are decomposing the standalone thermometer market by integrating skin conductance, heart rate variability, and accelerometry into unified ovulation prediction engines. Fertility clinics in the United States are adopting these platforms for remote cycle monitoring during ovarian stimulation protocols. The structural consequence is margin compression for single-modality hardware vendors unable to license complementary algorithm stacks.
EU MDR Class IIa requirements for clinical evidence are reshaping competitive positioning by elevating regulatory affairs capability above pure engineering speed. Manufacturers must now maintain post-market surveillance systems and periodic safety update reports that smaller entrants cannot resource. The algorithm-centric product category faces the steepest compliance burden as software updates trigger re-evaluation cycles.
Subscription-based algorithm access is displacing perpetual-license hardware sales in the direct-to-consumer channel, unbundling device purchase from ongoing fertility insight delivery. Telehealth platforms and employer benefit administrators favor this model for predictable cost structures and aggregated population analytics. This shift concentrates most visibly in the United States where fertility benefit managers negotiate enterprise pricing for covered employee populations.
Smart Fertility Tracker Market Segmentation
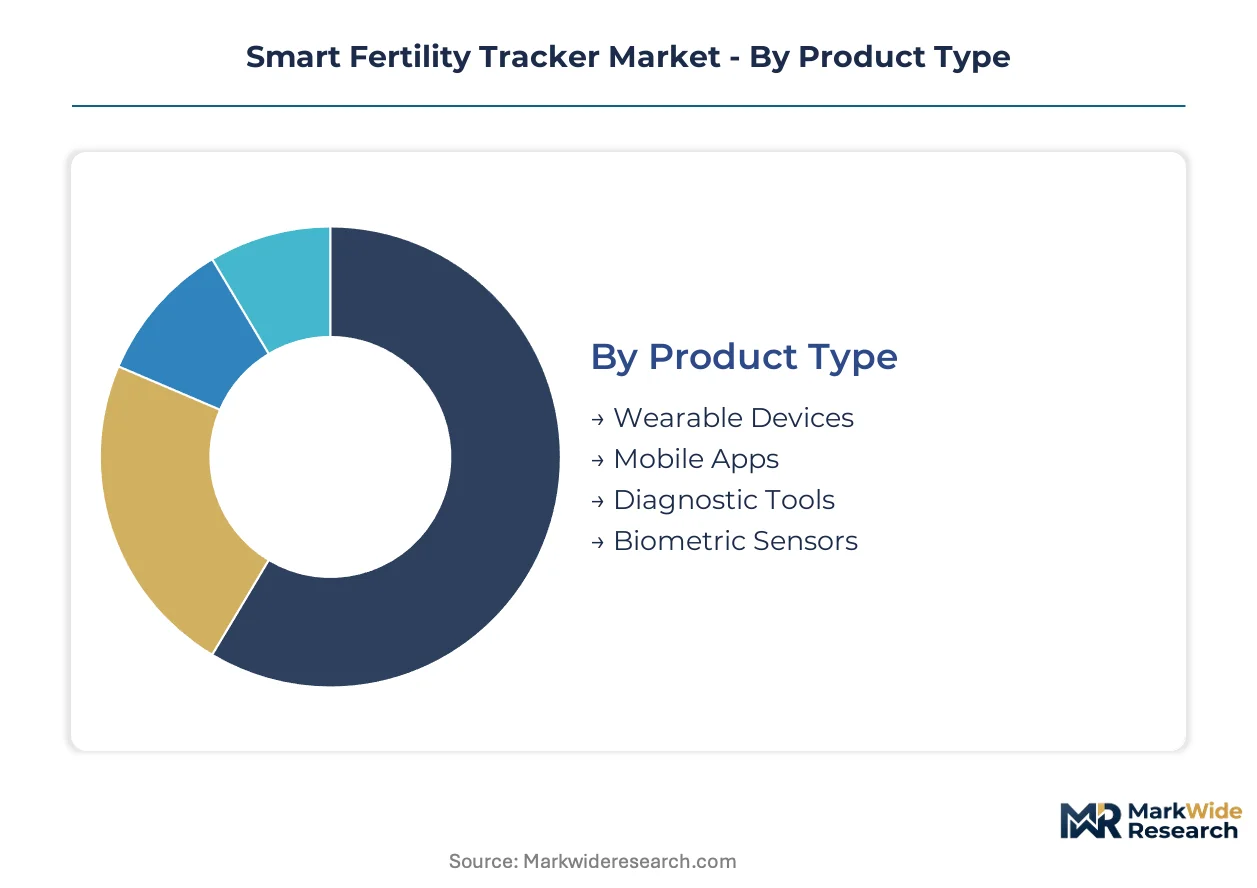
Segmentation in the Smart Fertility Tracker Market reveals how hardware margins, algorithmic differentiation, and clinical channel access create divergent competitive positions. Product architecture choices lock vendors into distinct regulatory pathways and recurring revenue models that reshape capital allocation priorities.
Product Type:
Wearable devices and biometric sensors concentrate manufacturing in Taiwan and South Korea, while mobile apps and diagnostic tools distribute development across software hubs in the United States and Europe.
- Wearable Devices:Continuous skin temperature and accelerometry sensors capture longitudinal physiological data streams. Demand clusters in the United States where employer-sponsored fertility benefits subsidize hardware acquisition for covered employees.
- Mobile Apps:Algorithm-only platforms deliver ovulation predictions through smartphone interfaces without dedicated hardware. These products face margin compression from app store fees and fragmented HIPAA-GDPR compliance costs that force redundant infrastructure deployment.
- Diagnostic Tools:Microfluidic luteinizing hormone and progesterone metabolite assays enable at-home luteal phase confirmation.
- Biometric Sensors:Discrete optical and temperature sensing modules supply componentry to integrated device manufacturers.
Wearable devices hold the largest share; momentum sits with biometric sensors as multi-sensor fusion architectures displace single-modality hardware.
Technology:
Cost tier separation runs deep: Bluetooth and cloud computing represent mature, commoditized infrastructure layers, while artificial intelligence and data analytics command premium pricing through clinical-grade algorithm subscriptions.
- Bluetooth:Low-energy wireless protocols enable seamless data transmission from wearable sensors to paired smartphones. This technology saturates the mid-market as hardware manufacturers compete on connection reliability rather than protocol differentiation.
- Artificial Intelligence:Machine learning pipelines process longitudinal biomarker patterns to refine ovulation window predictions with quantified precision. FDA SaMD clearance pathways accelerate commercial entry for algorithm developers by separating software validation from hardware certification timelines.
- Data Analytics:Population-level cycle pattern aggregation supports fertility clinic protocol optimization and employer benefit population health management.
- Cloud Computing:Distributed infrastructure hosts encrypted health records and analytics pipelines under HIPAA and GDPR jurisdictional constraints.
Bluetooth underpins volume deployment; artificial intelligence captures the steepest expansion trajectory as subscription models displace perpetual hardware licenses.
End User:
Customer type determines channel economics and pricing power: direct-to-consumer segments face out-of-pocket price sensitivity, while healthcare providers and fertility clinics negotiate enterprise contracts with embedded algorithm access fees.
- Single Women:Individual family-planning decisions drive demand for discreet, app-first solutions with minimal hardware investment. This segment concentrates purchasing through direct-to-consumer channels and telehealth platforms that bypass traditional retail markup.
- Couples:Shared cycle monitoring requirements favor multi-user app subscriptions and dual-device hardware bundles. United States fertility benefit administrators negotiate enterprise pricing for covered employee populations, reducing price sensitivity.
- Healthcare Providers:Primary care and OB-GYN practices seek EHR-integrated remote monitoring solutions for patient management protocol enhancement.
- Fertility Clinics:Reproductive endocrinology practices adopt connected diagnostic tools for ovarian stimulation cycle monitoring and treatment optimization.
Fertility clinics hold the largest share; momentum sits with healthcare providers as EHR interoperability gaps create first-mover advantage for platform vendors.
Application:
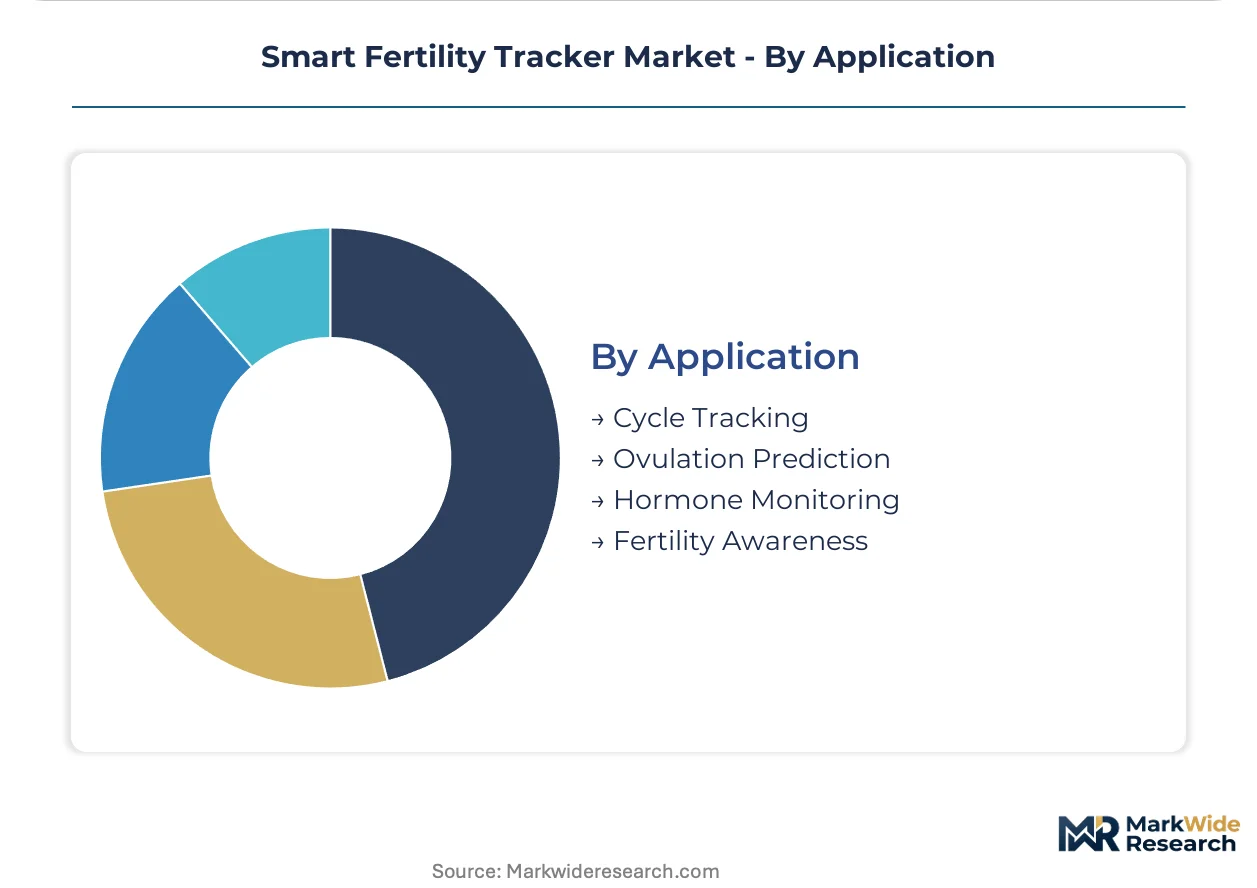
Application maturity varies sharply: cycle tracking and fertility awareness represent established use cases with saturated algorithm performance, while ovulation prediction and hormone monitoring attract R&D investment for clinical-grade accuracy improvements.
- Cycle Tracking:Basal body temperature logging and menstrual calendar interfaces form the foundational functionality across consumer-facing platforms. This application dominates direct-to-consumer channels in the United States where wellness-classification devices avoid FDA medical device scrutiny.
- Ovulation Prediction:Multi-biomarker fusion algorithms integrate temperature, heart rate variability, and luteinizing hormone data to narrow fertile window estimates. EU MDR Class IIa requirements elevate regulatory affairs capability above pure engineering speed, extending certification timelines to 18-24 months.
- Hormone Monitoring:Progesterone metabolite and estrogen quantification enable luteal phase defect detection without laboratory processing.
- Fertility Awareness:Education-focused interfaces support natural family planning method adherence and contraceptive decision-making.
Cycle tracking holds the largest share; hormone monitoring gains share fastest as microfluidic smartphone-read assays converge with wearable continuous sensing platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA Software as a Medical Device pathways anchor commercial legitimacy in the United States, while EU MDR Class IIa requirements and notified body backlogs reshape European market entry timelines. Demand concentrates where employer-sponsored fertility benefits and direct-to-consumer health spending create favorable reimbursement dynamics.
United States
Employer-sponsored fertility benefits from large technology and financial services firms normalize device reimbursement for covered employees. FDA SaMD frameworks accelerate algorithm commercial entry by separating software validation from hardware certification timelines. Boston and San Francisco Bay Area fertility clinic networks integrate connected diagnostic tools into ovarian stimulation protocols.
Germany
Reproductive endocrinology practices in Berlin and Munich adopt remote monitoring platforms for standardized patient management. EU MDR notified body engagement through BSI and TÜV SÜD extends certification timelines to 18-24 months for algorithm-dependent devices. The Rhine-Ruhr industrial corridor concentrates sensor component distribution for European hardware manufacturers.
United Kingdom
NHS fertility treatment waiting lists drive private clinic adoption of connected diagnostic tools for cycle optimization. MHRA recognition of FDA-cleared algorithms streamlines market entry for software-focused entrants. London and Manchester reproductive health networks pilot EHR-integrated remote monitoring during ovarian stimulation.
Switzerland
Zurich-based research teams sustain European regulatory credibility through Swissmedic and BSI-notified body engagement. Basel pharmaceutical corridor partnerships enable clinical validation studies for algorithm training datasets. Geneva fertility clinics serve cross-border French and Italian patients seeking premium reproductive health services.
Sweden
Stockholm digital health clusters develop subscription-based algorithm access models for employer benefit administrators. The Swedish Medical Products Agency enforces GDPR-HIPAA jurisdictional compliance for cross-border data transfer infrastructure. Gothenburg wearable sensor manufacturers supply componentry to integrated device vendors across Northern Europe.
Smart Fertility Tracker Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in the Smart Fertility Tracker Market. Hardware-software bundles command premium pricing through sensor precision and recurring algorithm subscriptions, while software-only entrants capture margin through clinical-grade analytics without manufacturing overhead. Three archetypes dominate: wearable sensor manufacturers with in-house algorithm development, FDA-cleared software platforms licensing to hardware partners, and fertility clinic-focused platform vendors with EHR integration capabilities. Competitive moves concentrate on strategic partnerships for algorithm licensing and geographic expansion through notified body engagement in Europe.
Within the integrated hardware-software tier, Ava AG and Tempdrop exemplify divergent manufacturing strategies. Ava AG leverages Zurich-based research capabilities for European regulatory credibility, while Tempdrop anchors position through proprietary axillary temperature sensing hardware with in-house production control. Natural Cycles occupies a distinctive regulatory tier through FDA-cleared algorithm status that positions the brand in provider-channel discussions alongside direct-to-consumer distribution.
| Leading Market Players |
|---|
| Ava AG |
| Tempdrop |
| Natural Cycles |
| Clearblue |
| Mira |
| OvuSense |
| Kindara |
| Premom |
| Inito |
| Others |
Value Chain & Pricing Dynamics
Eighteen-to-twenty-four month EU MDR certification timelines compress inventory planning horizons for algorithm-dependent device manufacturers, concentrating pricing power with notified body-approved vendors while forcing hardware makers to absorb component pre-positioning costs ahead of regulatory clearance.
Pricing Analysis
United States list prices for FDA-cleared fertility trackers command 40-60% premiums over uncertified wellness-classified alternatives in European direct-to-consumer channels. Subscription-based algorithm access models now dominate, separating hardware purchase from recurring fertility insight delivery. Price differentiation rests on FDA SaMD clearance tier and multi-sensor fusion capability rather than single-modality hardware specifications. Cost compression in the wellness-classified tier intensifies as platform-store fees and privacy compliance expenditures erode net margins for software-only entrants.
Supply Chain Analysis
Taiwan Strait transit exposure concentrates risk for discrete temperature and optical sensor supplies that fertility hardware manufacturers source from Taiwanese and South Korean fabrication facilities. Silicon wafer processing and MEMS sensor production draw from concentrated East Asian capacity, while microfluidic assay componentry feeds from German and Swiss precision manufacturing clusters. Single-source vulnerability in Bluetooth low-energy module supply creates disruption exposure for mid-market wearable vendors. Distribution runs through specialty pharmacy and telehealth platforms that bypass traditional retail markup and capture patient relationship data.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Algorithm subscription revenue layers expand faster than hardware replacement cycles, transforming capital allocation priorities toward software validation pipelines and post-market surveillance infrastructure.
For Market Incumbents: Secure FDA SaMD clearance for algorithm updates ahead of software-triggered re-evaluation cycles that EU MDR Class IIa requirements impose. Deepen captive production control over axillary temperature sensing modules to defend margin against discrete sensor supply concentration in Taiwan and South Korea. Channel control through fertility clinic EHR integration represents the priority defensive lever against telehealth platform disintermediation. For New Entrants and Emerging Players: Differentiate on progesterone metabolite sensing convergence with smartphone-read colorimetric assays, a white-space target where microfluidic sampling meets wearable continuous sensing. Underpenetrated fertility clinic integration in United States reproductive endocrinology practices offers the most penetrable segment for platform vendors with remote monitoring protocol development capability. Direct-to-consumer channel expansion through employer benefit administrators provides the clearest go-to-market angle for subscription-based algorithm access models. For Investors and Strategic Acquirers: Carve-out targets emerge from pharmaceutical corridor partnerships where Basel and Boston-based clinical validation studies have generated algorithm training datasets without scaled commercial infrastructure. Long-term viability over the next decade hinges on regulatory affairs capability elevation above pure engineering speed as EU MDR notified body backlogs persist. Watch FDA reclassification rulings between wellness and medical device categories as the critical inflection signal for algorithm-dependent offering valuations.| Strategic Initiative | Industry Significance |
|---|---|
| FDA SaMD Clearance Pathway | Accelerates commercial entry by separating software validation from hardware certification timelines for algorithm developers. |
| EU MDR Notified Body Engagement | BSI and TÜV SÜD certification through Zurich or Berlin offices sustains European market access for device manufacturers. |
| Fertility Clinic EHR Integration | First-mover advantage accrues to platform vendors resolving legacy reproductive endocrinology system API fragmentation. |
| Employer Benefit Administrator Partnership | Enterprise pricing negotiations with United States fertility benefit managers normalize device reimbursement for covered populations. |
| Multi-Sensor Fusion Architecture Development | Integration of skin conductance, heart rate variability, and accelerometry displaces standalone thermometer market share. |
Study Parameters
Cross-validation between primary interviews with reproductive endocrinologists, fertility clinic operations directors, biomedical engineers, and employer benefits administrators and secondary validation through FDA 510(k) filings, EU MDR notified body registration databases, and hospital procurement contract records anchors the qualitative findings. Bottom-up demand modeling from wearable device shipment data and algorithm subscription activations triangulates against top-down fertility clinic capital expenditure surveys and employer benefit plan document analysis.
Sensitivity analysis across regulatory approval timeline scenarios, sensor supply disruption assumptions, and reimbursement policy shifts informs the analytical framework over the projection horizon. Segmentation dimensions modeled include product architecture, technology layer, end-user type, and application maturity, with cross-cutting analysis of FDA SaMD versus EU MDR Class IIa regulatory pathway adoption. CAGRs derive from fitted growth curves against historical fertility tracker shipment data and algorithmic fertility prediction accuracy improvement trajectories.
The analysis sits within stated boundaries; outcomes outside sustained employer-sponsored fertility benefit expansion or FDA-EU regulatory harmonization progress would require recalibration. Forecasts reflect assumptions regarding notified body capacity resolution and silicon sensor supply diversification that algorithm-dependent device manufacturers pursue. Practitioners should keep alternative scenarios live as HIPAA-GDPR jurisdictional friction and reproductive endocrinology data science scarcity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Reproductive Health
Global Cervical Dysplasia Market
Reproductive Health
Ovum Egg Banking Market
Reproductive Health
US Long-Acting Contraception Market
Reproductive Health
Gamete Preservation Market
Reproductive Health
US Sexual and Reproductive Health Clinics Market
Reproductive Health
Egg Freezing and Embryo Banking Market
Reproductive Health
Fertility Services Market
Reproductive Health
Doula and Birth Coaching Services Market
Reproductive Health
Intrauterine Insemination (IUI) Treatment Market
Reproductive Health
In Vitro Fertilization (IVF) Market
Reproductive Health
Cervical Dysplasia Treatment Market
Reproductive Health
Cryopreservation for in-Vitro Fertilization (IVF) Market
Reproductive Health
Egg Donation Market
Reproductive Health
Germany in Vitro Fertilization (IVF) Market
Reproductive Health
UK in Vitro Fertilization (IVF) Market
Reproductive Health
Europe in Vitro Fertilization (IVF) Market