
 Veterinary Progesterone Testing Market | 2026-2036
Veterinary Progesterone Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Veterinary Progesterone Testing Market Analytics
Companion animal breeding facilities is broadening as a revenue channel for progesterone testing suppliers. IDEXX Laboratories sustains technology leadership through integrated diagnostic platforms that span in-clinic chemistry and immunoassay workflows. Zoetis anchors its position with a deep veterinary channel presence and reproductive health portfolio breadth. Thermo Fisher Scientific leverages analytical instrument expertise to serve reference laboratories with high-sensitivity hormone quantification methods.
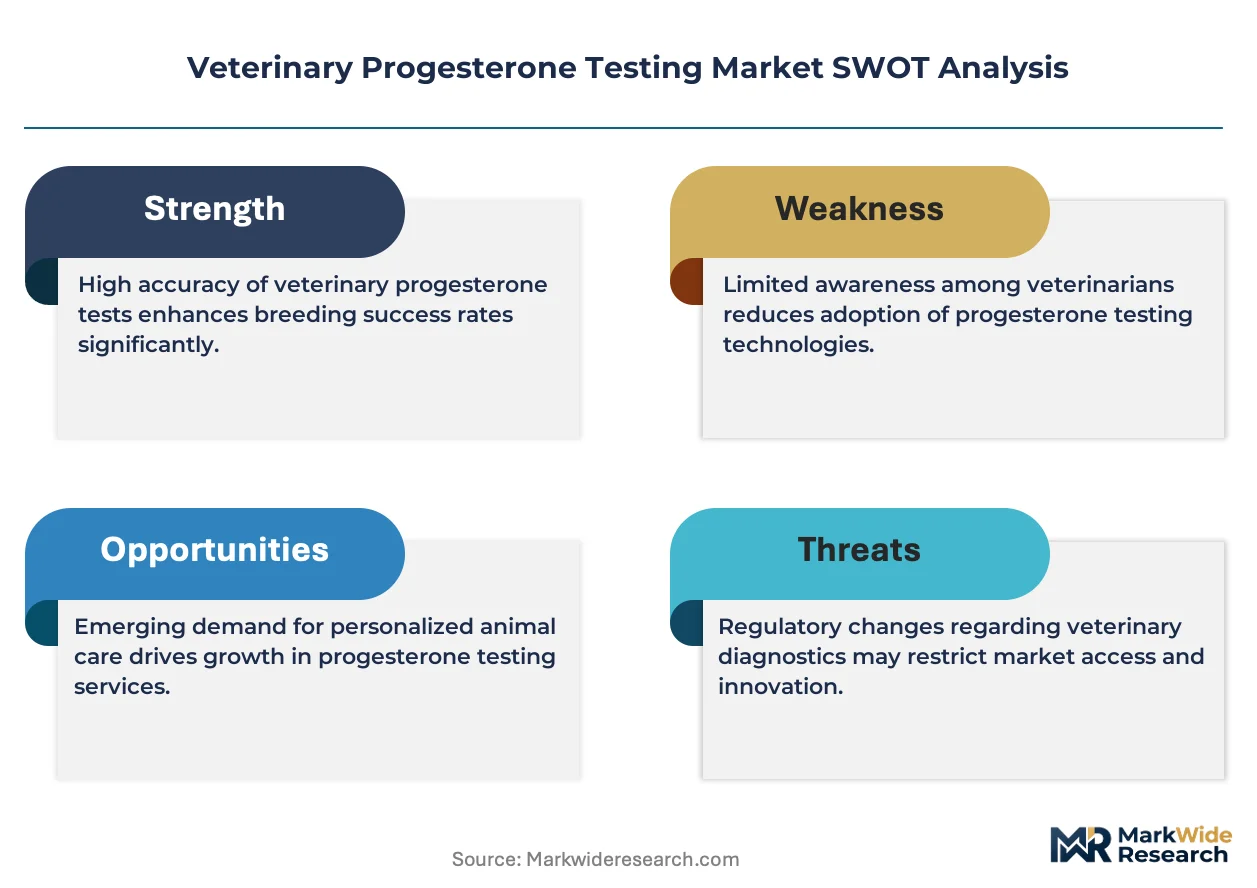
Veterinary progesterone testing encompasses quantitative and semi-quantitative analytical methods that measure circulating progesterone in canine, feline, and equine serum or plasma samples, typically employing enzyme-linked immunosorbent assay chemistry with detection thresholds reaching 0.1 ng/mL for precise ovulation timing. These assays serve commercial breeders and veterinary practitioners who require objective hormonal data to optimize artificial insemination windows and reduce failed conception rates. ELISA Kits command the largest installed base among product formats due to lower capital requirements and established workflow familiarity in private practice settings. Mass Spectrometry represents the fastest-expanding technology segment as reference laboratories adopt liquid chromatography-tandem mass spectrometry for superior specificity in multi-hormone panels.
FDA Center for Veterinary Medicine oversight of diagnostic test kits, combined with USDA Animal and Plant Health Inspection Service guidelines for breeding facility health protocols, elevates compliance burdens for manufacturers entering the US market. ISO 17025 accreditation requirements for veterinary reference laboratories in Europe further shape product development priorities for assay standardization and traceability. Stakeholders must monitor evolving regulatory harmonization between human diagnostic standards and veterinary-specific pathways, as convergence pressures could reshape competitive barriers for emerging assay formats.
Market Dynamics
Quantitative immunoassay platforms are compressing turnaround times for ovulation timing decisions, forcing reference laboratories and in-clinic operators to recalibrate service models around same-day result delivery.
Growth Catalysts
- USDA Breeding Facility Protocols:Mandatory health screening requirements for commercial canine operations are expanding routine hormone monitoring volumes across licensed kennels.
- Liquid Chromatography-Tandem Mass Spectrometry:Multi-analyte panels with superior specificity are capturing share from single-parameter ELISA workflows in high-throughput reference settings.
- Artificial Insemination Services:Specialty reproductive veterinary practices are bundling progesterone testing with semen collection and surgical insemination to improve conception success rates.
Market Restraints
- Capital Intensity of LC-MS/MS:Liquid chromatography-tandem mass spectrometry systems require substantial upfront investment, limiting adoption to high-volume reference laboratories.
- Reagent Supply Concentration:Specialized antibody and conjugate manufacturing concentrates among a limited supplier base, creating vulnerability to batch variability and lead time extension.
- ELISA Specificity Limitations:Cross-reactivity with structurally similar steroids in canine samples can produce ambiguous results during critical pre-ovulation windows.
Strategic Opportunities
- Point-of-Care Connectivity:Cloud-integrated handheld analyzers enabling real-time breeder decision support represent untapped penetration potential in mobile veterinary services.
- Equine Reproductive Medicine:Broodmare management programs are adopting quantitative progesterone protocols for early pregnancy monitoring and luteal insufficiency detection.
- FDA Streamlined Pathway Alignment:Convergence between human diagnostic quality systems and veterinary assay requirements is lowering regulatory friction for ISO 13485-certified manufacturers entering the companion animal segment.
Industry Challenges
- Specialized Veterinary Endocrinology Expertise:Interpretation of dynamic progesterone curves requires trained personnel, creating bottlenecks in general practice settings without dedicated reproductive staff.
- Legacy Analyzer Integration:New assay formats must interface with installed chemistry platforms, constraining design flexibility and extending validation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Veterinary Progesterone Testing Market |
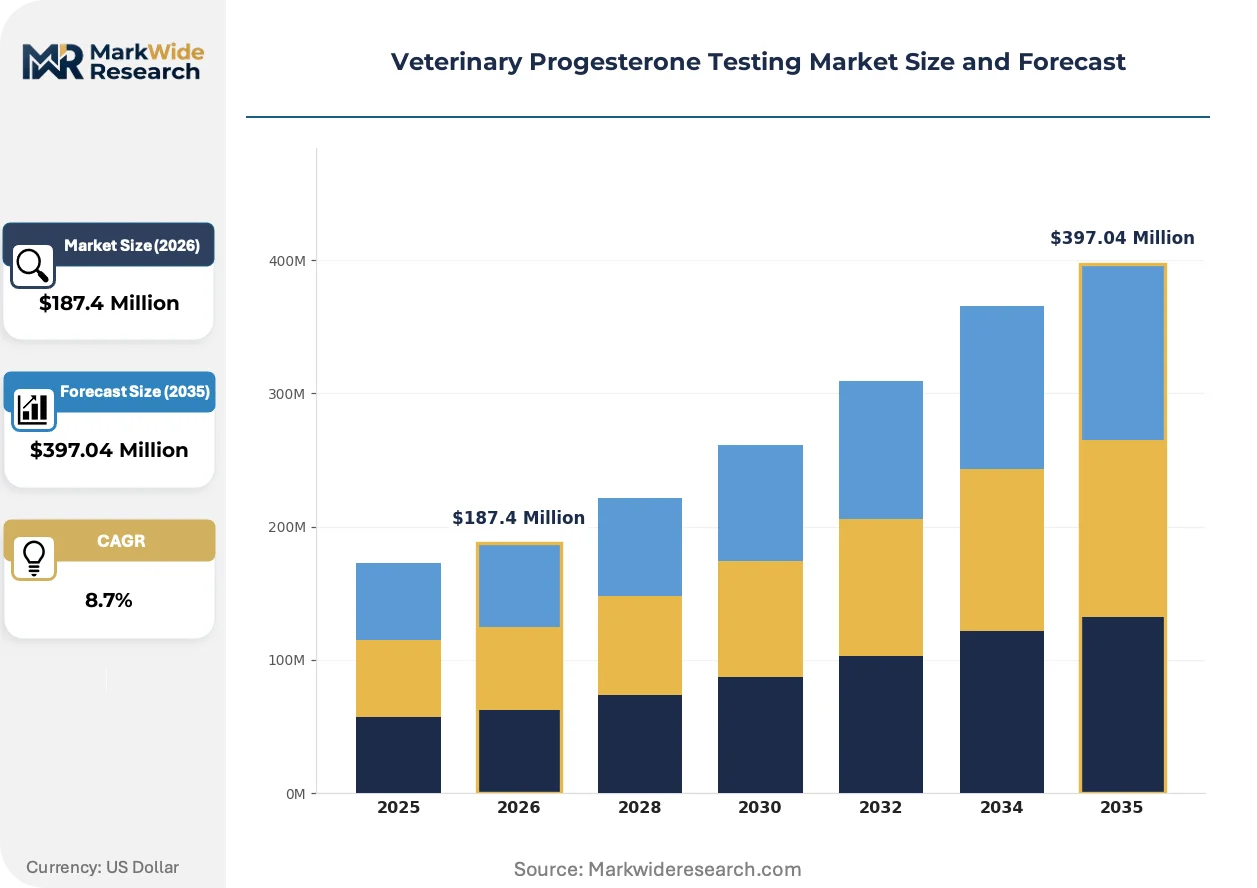
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ELISA Kits, Immunoassays, Reagents, Analyzers End User: Veterinary Clinics, Research Laboratories, Animal Hospitals, Breeding Facilities Technology: Chromatography, Fluorescent Methods, Radioimmunoassays, Mass Spectrometry Application: Reproductive Health, Pregnancy Diagnosis, Estrus Detection, Hormonal Therapy |
| Companies Covered | bioMérieux SA, BioNote Inc., IDEXX Laboratories, Inc., Heska Corporation, Zoetis Inc., Randox Laboratories Ltd., PerkinElmer Inc., Demeditec Diagnostics GmbH, Thermo Fisher Scientific Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Veterinary Progesterone Testing Market Evolving Landscape
Automation and connectivity are redefining how hormonal data moves from sample to decision, collapsing the latency between collection and actionable breeding recommendations.
Fluorescence-based immunoassay cartridges with onboard calibration are rewriting the economics of in-clinic progesterone quantification. Mid-size breeding operations with weekly testing volumes are adopting these systems to eliminate reference laboratory shipping delays. The technology is compressing the competitive window for centralized testing services in suburban and exurban markets.
ISO 17025 accreditation mandates for European veterinary reference laboratories are elevating traceability requirements for hormone assays. Manufacturers must now document metrological chains from primary reference materials through to patient reports. Small and mid-size reference laboratories in Germany and France are consolidating or outsourcing to accredited networks to meet compliance costs.
Breeders are unbundling testing from full-service reproductive packages, procuring standalone progesterone panels through direct-to-consumer veterinary platforms. Specialty telemedicine channels are capturing this demand by offering result interpretation without physical consultation. This pattern is most pronounced in Texas, Florida, and California, where large commercial kennel density supports dedicated service models.
Veterinary Progesterone Testing Market Segmentation
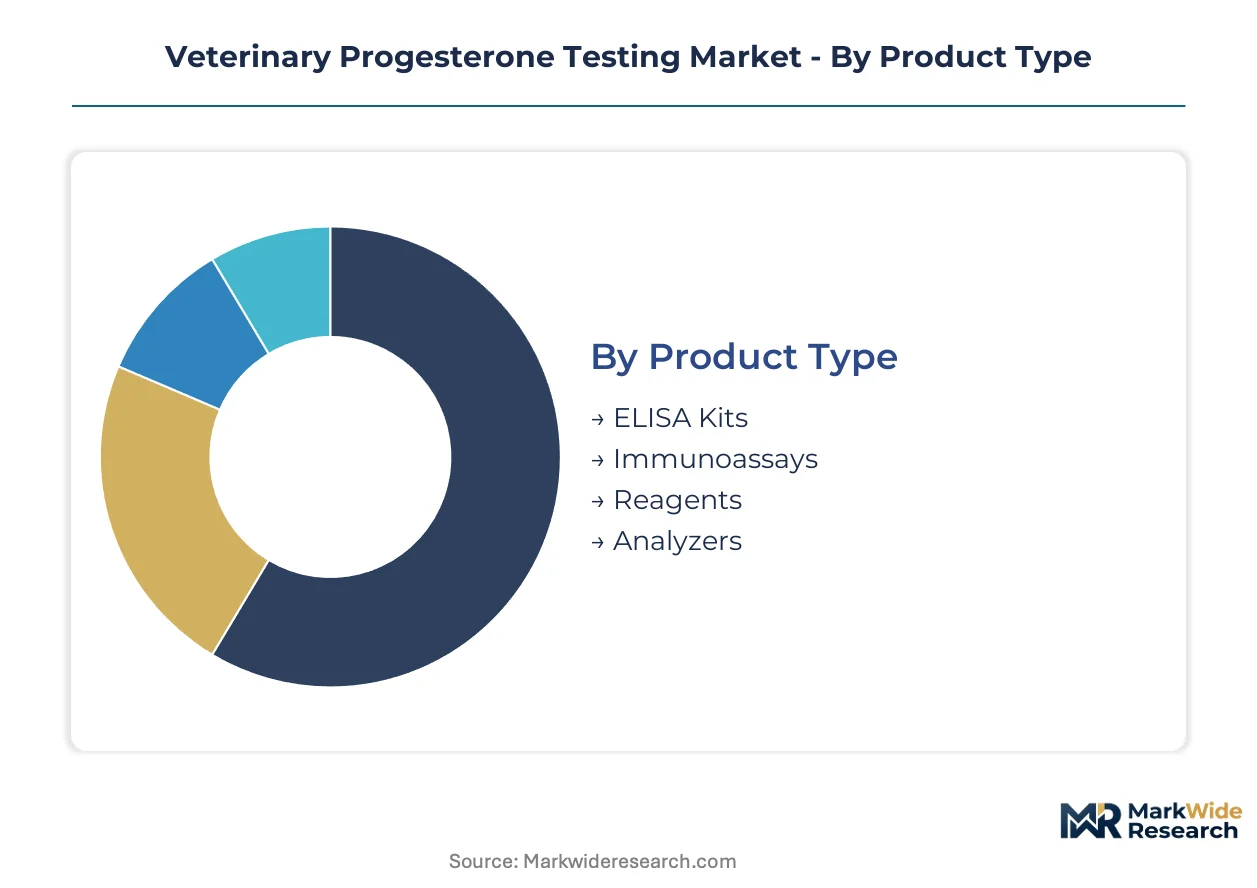
Veterinary progesterone testing segments reflect divergent buyer priorities across cost sensitivity, throughput requirements, and clinical integration depth. Equipment selection, technology adoption, and service bundling vary substantially between high-volume breeding operations and general veterinary practices.
Product Type:
Purchase decisions center on capital availability versus per-test economics, with smaller practices prioritizing low-entry formats and reference laboratories favoring integrated systems.
- ELISA Kits:Enzyme-linked immunosorbent assay kits employ colorimetric detection with microplate readers, requiring minimal instrument investment. Breeding facilities in Texas and Florida concentrate procurement here, driven by batch processing flexibility and established protocol familiarity.
- Immunoassays:Automated chemiluminescent and fluorescent immunoassay platforms deliver quantitative results within 30-60 minutes. Veterinary clinics in California and New York are migrating toward these systems, constrained by reagent contract lock-in and platform-specific consumable requirements.
- Reagents:Antibody conjugates, calibrators, and substrate solutions for in-house assay development. Academic veterinary hospitals and research consortia represent primary demand clusters.
- Analyzers:Dedicated benchtop instruments with onboard sample handling and result reporting. High-throughput reference laboratories in Illinois and Massachusetts anchor adoption.
ELISA Kits lead on scale; Immunoassays lead on momentum.
End User:
Service model differentiation separates transaction-focused testing from integrated reproductive management programs.
- Veterinary Clinics:General and specialty practices offering progesterone testing as ancillary reproductive services. Point-of-care instrument placement is climbing fastest here, eliminating reference laboratory shipping delays.
- Research Laboratories:Academic and commercial research facilities conducting endocrine studies and assay validation work. Funding cycles and publication timelines shape procurement patterns.
- Animal Hospitals:Multi-specialty tertiary centers with dedicated theriogenology departments. These facilities command premium pricing for complex cases requiring serial hormone monitoring.
- Breeding Facilities:Commercial canine kennels and equine breeding operations with weekly testing volumes. USDA licensing requirements for licensed operations mandate health screening protocols that include hormonal monitoring.
Breeding Facilities dominate transaction volume; Veterinary Clinics show the steepest expansion trajectory.
Technology:
Specificity requirements and capital deployment horizons determine technology selection across end-user segments.
- Chromatography:High-performance liquid chromatography methods separate progesterone from interfering steroids prior to detection. Reference laboratories in Germany and Switzerland maintain installed bases for multi-hormone panels.
- Fluorescent Methods:Fluorescence polarization and time-resolved fluorescence immunoassays enable rapid quantification with reduced sample volumes. Portable analyzer adoption is gaining share fastest in mobile veterinary services.
- Radioimmunoassays:Traditional competitive binding assays using radioactive tracers. Declining demand reflects regulatory burden of isotope handling and waste disposal.
- Mass Spectrometry:Liquid chromatography-tandem mass spectrometry delivers definitive identification with structural specificity. Academic medical centers and contract research organizations anchor demand.
Chromatography maintains installed base leadership; Mass Spectrometry captures premium positioning.
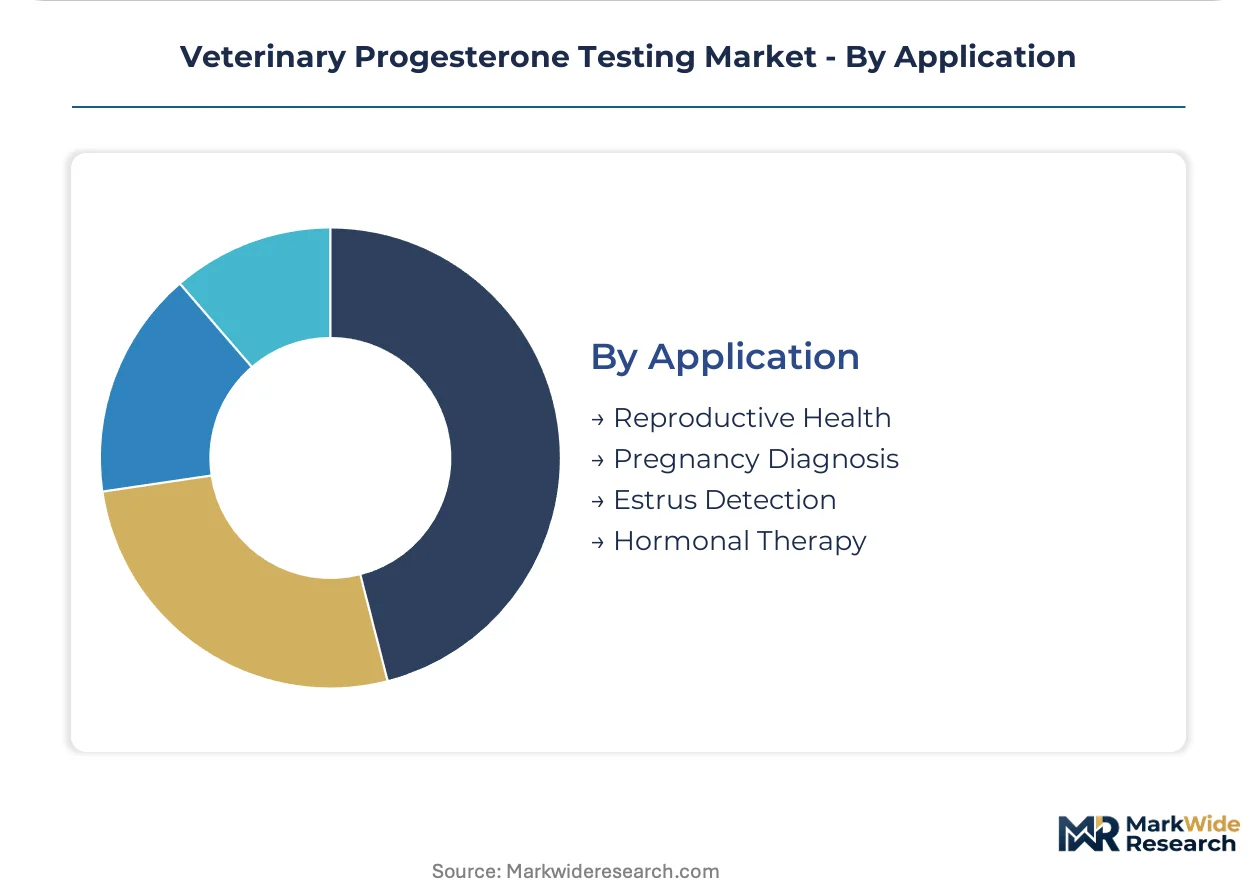
Application:
Clinical utility depth varies from single-parameter timing decisions to longitudinal therapeutic monitoring protocols.
- Reproductive Health:Comprehensive ovulation timing, fertility assessment, and breeding soundness evaluation. Commercial canine operations in the southeastern United States concentrate demand here.
- Pregnancy Diagnosis:Progesterone decline monitoring for early pregnancy maintenance and abortion risk assessment. Equine broodmare management programs are expanding adoption.
- Estrus Detection:Baseline progesterone measurement to confirm anestrus or cycling status. Dairy and beef cattle operations utilize this application segment.
- Hormonal Therapy:Therapeutic monitoring for luteal insufficiency, induced ovulation protocols, and medical pregnancy termination. Specialty reproductive practices command premium service fees.
Reproductive Health anchors revenue concentration; Pregnancy Diagnosis shows emerging clinical adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States breeding corridor concentration shapes veterinary progesterone testing demand geography. Commercial canine operations across Texas, Florida, and California generate weekly testing volumes that sustain specialized service models. Regulatory frameworks and veterinary infrastructure density separate mature markets from emerging adoption zones.
United States
USDA-licensed commercial kennels in Texas and Florida mandate hormonal screening protocols under federal breeding facility regulations. FDA Center for Veterinary Medicine oversight of diagnostic test kits elevates quality compliance burdens for assay manufacturers. The Dallas-Fort Worth metroplex anchors high-throughput reference laboratory networks serving suburban breeding operations.
Germany
ISO 17025 accreditation requirements for veterinary reference laboratories reshape hormone assay standardization priorities. EFSA guidelines on veterinary medicinal products influence diagnostic quality system convergence with human laboratory standards. Bavaria's academic veterinary hospitals consolidate multi-hormone panel testing for equine broodmare management programs.
United Kingdom
Specialty reproductive veterinary practices in Greater London bundle progesterone testing with artificial insemination services. The Veterinary Medicines Directorate maintains oversight of diagnostic kit performance claims. Cambridge-area research consortia drive assay validation work for novel fluorescence-based detection methods.
France
ANSM regulatory alignment with EU veterinary diagnostic frameworks shapes market entry pathways for assay suppliers. Normandy's equine breeding region adopts quantitative progesterone protocols for early pregnancy monitoring. Paris-region reference laboratories consolidate accreditation compliance to meet CSRD-aligned traceability mandates.
Japan
PMDA oversight of veterinary diagnostics creates structured approval pathways for imported hormone assay platforms. METI industrial policy supports domestic analytical instrument manufacturing for multi-species applications. Osaka-based veterinary chains deploy point-of-care analyzers for same-day ovulation timing decisions.
Veterinary Progesterone Testing Market Competitive Landscape
Strategic partnerships dominate the current landscape as manufacturers seek distribution depth and technology access. The vendor base stratifies across integrated diagnostic conglomerates, specialized veterinary assay developers, and analytical instrument suppliers. Three archetypes anchor competitive positioning: platform-integrated majors with chemistry and immunoassay workflows, reference laboratory-focused precision instrument specialists, and regional reagent manufacturers serving batch-processing breeding operations. Portfolio diversification and geographic expansion constitute the primary competitive moves, with players extending reproductive health assay menus and penetrating USDA-licensed kennel networks.
Within the platform-integrated tier, IDEXX Laboratories and Zoetis exemplify archetypes combining diagnostic infrastructure with veterinary channel presence. Thermo Fisher Scientific occupies a position among analytical instrument specialists leveraging mass spectrometry expertise for high-sensitivity hormone quantification. bioMérieux SA represents the European diagnostic conglomerate archetype with regulatory compliance capabilities spanning multiple veterinary markets.
| Leading Market Players |
|---|
| bioMérieux SA |
| BioNote Inc. |
| IDEXX Laboratories, Inc. |
| Heska Corporation |
| Zoetis Inc. |
| Randox Laboratories Ltd. |
| PerkinElmer Inc. |
| Demeditec Diagnostics GmbH |
| Thermo Fisher Scientific Inc. |
| Others |
Value Network & Pricing Analysis
ISO 17025 accreditation mandates gate qualified supply access for European veterinary reference laboratories while simultaneously anchoring premium-tier pricing for manufacturers with documented metrological traceability chains. Buyers without certified suppliers face exclusion from regulated testing networks, compressing procurement options and elevating cost structures for compliant assay formats.
Pricing Analysis
Distributor margin layers absorb 15-25 points between manufacturer and end-user pricing in fragmented breeding facility markets. Three-tier pricing structure across premium, standard, and economy levels separates LC-MS/MS reference laboratory services from automated immunoassay platforms and batch-processed ELISA kits. Cost compression in economy-tier ELISA consumables is intensifying because antibody conjugate suppliers concentrate manufacturing among limited qualified sources. Commercial breeding facilities in Texas and Florida exhibit highest price sensitivity, while academic veterinary hospitals command least negotiation leverage due to grant-funded procurement flexibility.
Supply Chain Analysis
Dual-sourcing requirements from USDA-licensed kennels mandate qualified backup suppliers for critical reagent components, extending vendor qualification timelines. Antibody production concentrates in the United States, Germany, and China, while specialized substrate chemistries draw from Japanese and Swiss chemical manufacturers. Supply chain risk centers on single-source vulnerability for high-affinity progesterone monoclonal antibodies, where batch-to-batch variability disrupts assay calibration stability. Distribution runs through veterinary distribution consortia and direct manufacturer relationships with high-volume reference laboratory networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion trajectories in veterinary progesterone testing rest on fluorescence-based platform cost-down curves and unbundled telemedicine service premiums. Automated cartridge systems are displacing reference laboratory shipping models, capturing value previously lost to logistics intermediaries.
For Market Incumbents: Anticipate displacement pressure from cloud-integrated handheld analyzers by accelerating point-of-care instrument refresh cycles and locking in breeding facility reagent contracts. Defensive consolidation through captive supply of antibody conjugates neutralizes batch variability risks from third-party reagent suppliers. Channel control investments in USDA-licensed kennel direct sales forces preserve volume access against emerging telemedicine platforms. For New Entrants and Emerging Players: Enter via equine broodmare management programs in Normandy and Kentucky, where quantitative progesterone adoption lags canine breeding sophistication and incumbent platform lock-in remains shallow. Target mobile veterinary services with portable fluorescence analyzer placements, exploiting service territory fragmentation that resists centralized reference laboratory capture. Go-to-market leverage through specialty telemedicine channels bypasses capital-intensive field sales infrastructure. For Investors and Strategic Acquirers: Valuations sit cheapest among regional reagent manufacturers with ISO 13485 certification gaps blocking US market entry. Long-term viability framing favors precision instrument specialists with mass spectrometry expertise transferable across human and veterinary diagnostic segments. Acquisition target archetype: European reference laboratory networks consolidating to meet CSRD-aligned traceability mandates. Signal to watch: FDA streamlined pathway alignment announcements lowering regulatory friction for ISO 13485-certified manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Point-of-Care Instrument Launch | Cloud-integrated handheld analyzers collapse reference laboratory shipping delays for mobile veterinary services. |
| Reagent Contract Lock-In | Long-term consumable agreements with USDA-licensed kennels defend volume against unbundled telemedicine competitors. |
| ISO 17025 Accreditation Investment | Metrological traceability documentation opens European reference laboratory procurement to qualified suppliers. |
| Equine Application Expansion | Broodmare management protocol development captures underpenetrated premium segment in Kentucky and Normandy. |
| Strategic Partnership with Telemedicine Platforms | Direct-to-consumer result interpretation channels bypass traditional veterinary clinic distribution gatekeepers. |
Research Methodology
Coverage spans the United States, Germany, United Kingdom, France, and Japan, with primary inputs from each market cluster combined with secondary validation. Interviews with veterinary diagnostic platform engineers, USDA-licensed kennel operations managers, reference laboratory accreditation officers, and reproductive veterinary specialists informed demand-side assumptions. Secondary sources included FDA Center for Veterinary Medicine guidance documents, EFSA veterinary medicinal product guidelines, ISO 17025 accreditation registries, and customs data on diagnostic reagent trade flows. Bottom-up instrument placement estimates triangulated against top-down breeding facility testing volume models.
Rate-of-change decomposition separated technology substitution effects from end-user segment expansion and regulatory compliance cost pass-through. Segmentation dimensions modeled encompassed product type, technology platform, end-user archetype, and application depth across the projection horizon. CAGRs derived from fitted adoption curves for fluorescence-based systems and reference laboratory LC-MS/MS panel growth, cross-checked against USDA breeding facility licensing trajectory data and specialty veterinary practice reproductive service revenue disclosures.
Inputs from regulatory filing databases and veterinary industry association membership directories were available through the study window; gaps in private breeding facility testing volume records introduce uncertainty bands around commercial kennel segment estimates. Forecasts reflect assumptions regarding FDA streamlined pathway implementation timing and European accreditation harmonization progress. Deviation in USDA breeding facility inspection enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Veterinary Lasers Market
Veterinary
Veterinary Faecal Filters Market
Veterinary
Canine Flu Therapeutics Market
Veterinary
Global Animal Antimicrobials and Antibiotics Market
Veterinary
Veterinary Consumables Market
Veterinary
Global Veterinary Monitoring Equipment Market
Veterinary
Veterinary Healthcare Market
Veterinary
United Kingdom Veterinary Healthcare Market
Veterinary
Veterinary Intravenous (IV) Solutions Market
Veterinary
Veterinary Anesthesia Drugs Market
Veterinary
Veterinary Respiratory Disease Treatment Market
Veterinary
Veterinary Contract Development and Manufacturing Organizations (CDMO) Market
Veterinary
Australia Veterinary Healthcare Market
Veterinary
Animal Antibiotics Market
Veterinary
Global Animal Sedative Market
Veterinary
Global Equine Supplement Products Market