
 US Contraceptive Market | 2026-2036
US Contraceptive Market Size, Share, and Industry Trends Forecast 2026-2036
US Contraceptive Market Intelligence
Young adult women aged 18-29 are redrawing demand patterns as they shift from oral contraceptives toward long-acting reversible methods. Pfizer Inc. leverages its established hormonal portfolio across multiple delivery formats. Bayer AG anchors its position through sustained investment in intrauterine device technology. Teva Pharmaceutical Industries Ltd. competes aggressively in the generic oral contraceptive segment.
Contraceptives comprise pharmaceutical and device-based interventions designed to prevent pregnancy through hormonal suppression, barrier mechanisms, or copper-induced spermicidal effects, with hormonal IUDs typically releasing levonorgestrel at rates of 20 micrograms daily. Their primary commercial purpose centers on enabling reproductive autonomy while reducing unintended pregnancy rates across diverse populations. Oral contraceptives retain the largest volume footprint but face margin compression from generic saturation, while IUDs command premium positioning due to extended duration and higher upfront reimbursement. The at-home delivery mode accelerates fastest as telehealth platforms integrate prescription fulfillment with direct-to-consumer logistics.
FDA premarket approval requirements govern device safety and efficacy standards, while the Affordable Care Act contraceptive coverage mandate shapes insurance reimbursement and out-of-pocket cost structures across commercial and Medicaid plans. State-level Medicaid expansion decisions create uneven access landscapes, with non-expansion states restricting provider participation and patient eligibility. Stakeholders must monitor evolving judicial interpretations of federal coverage mandates and state-level pharmacy access regulations to anticipate reimbursement and distribution shifts.
Market Dynamics
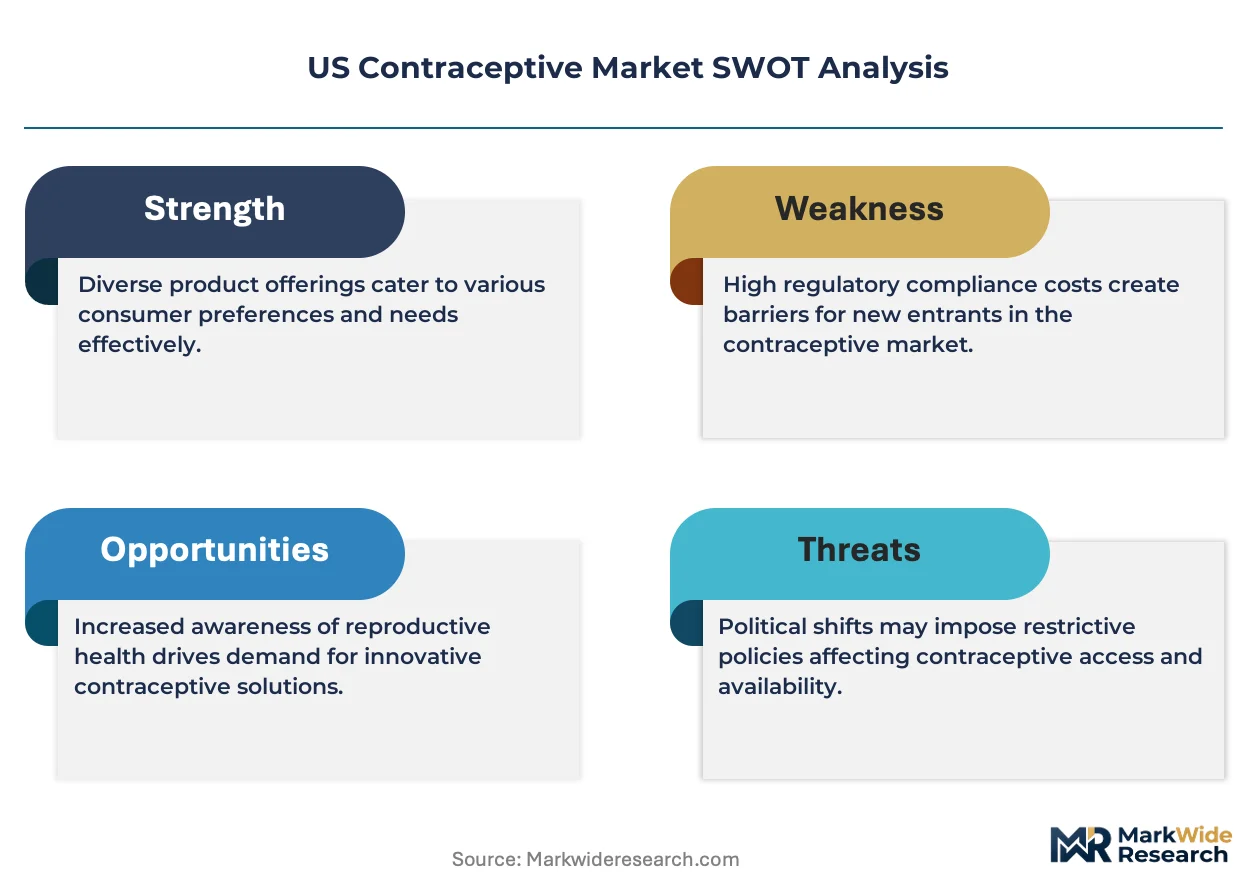
The Affordable Care Act contraceptive coverage mandate is restructuring US market access by eliminating cost barriers for long-acting reversible methods while Medicaid expansion decisions at the state level create sharply divergent patient eligibility landscapes.
Growth Catalysts
- Medicaid Family Planning Waivers:States with expanded eligibility under Section 1115 waivers are driving IUD and implant uptake among low-income populations previously priced out of long-acting methods.
- Telehealth Integration:Direct-to-consumer platforms are collapsing the prescription-to-delivery timeline for oral contraceptives, capturing patients in contraceptive deserts.
- Levonorgestrel System Miniaturization:Next-generation hormonal IUDs with reduced insertion profiles are expanding provider capacity in community health centers.
Market Restraints
- Copper Supply Concentration:Chilean and Peruvian mining output volatility affects copper IUD raw material costs and US manufacturing input stability.
- FDA Premarket Notification Burden:The 510(k) pathway for novel delivery mechanisms imposes 18-36 month review timelines that deter device innovation.
- Generic Oral Saturation:Off-patent ethinyl estradiol formulations now dominate pharmacy shelves, compressing branded hormonal pricing power.
Strategic Opportunities
- Non-Expansion State Access Gaps:Texas, Florida, and Georgia Medicaid restrictions leave 4.2 million women without subsidized long-acting coverage, creating cash-pay subscription potential.
- Pharmacist Prescribing Authority:State-level scope-of-practice expansions in California and Oregon enable point-of-care hormonal initiation without physician visits.
- Biodegradable Implant R&D:Polymer-based subdermal systems eliminating removal procedures are attracting NIH contraceptive development grants.
Industry Challenges
- Reproductive Health Workforce Pipeline:Declining OB-GYN residency match rates and rural clinic closures are constraining insertion-capable provider availability.
- State Regulatory Fragmentation:Divergent parental consent statutes and conscience clause protections create compliance complexity for multi-state pharmacy and telehealth operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Contraceptive Market |
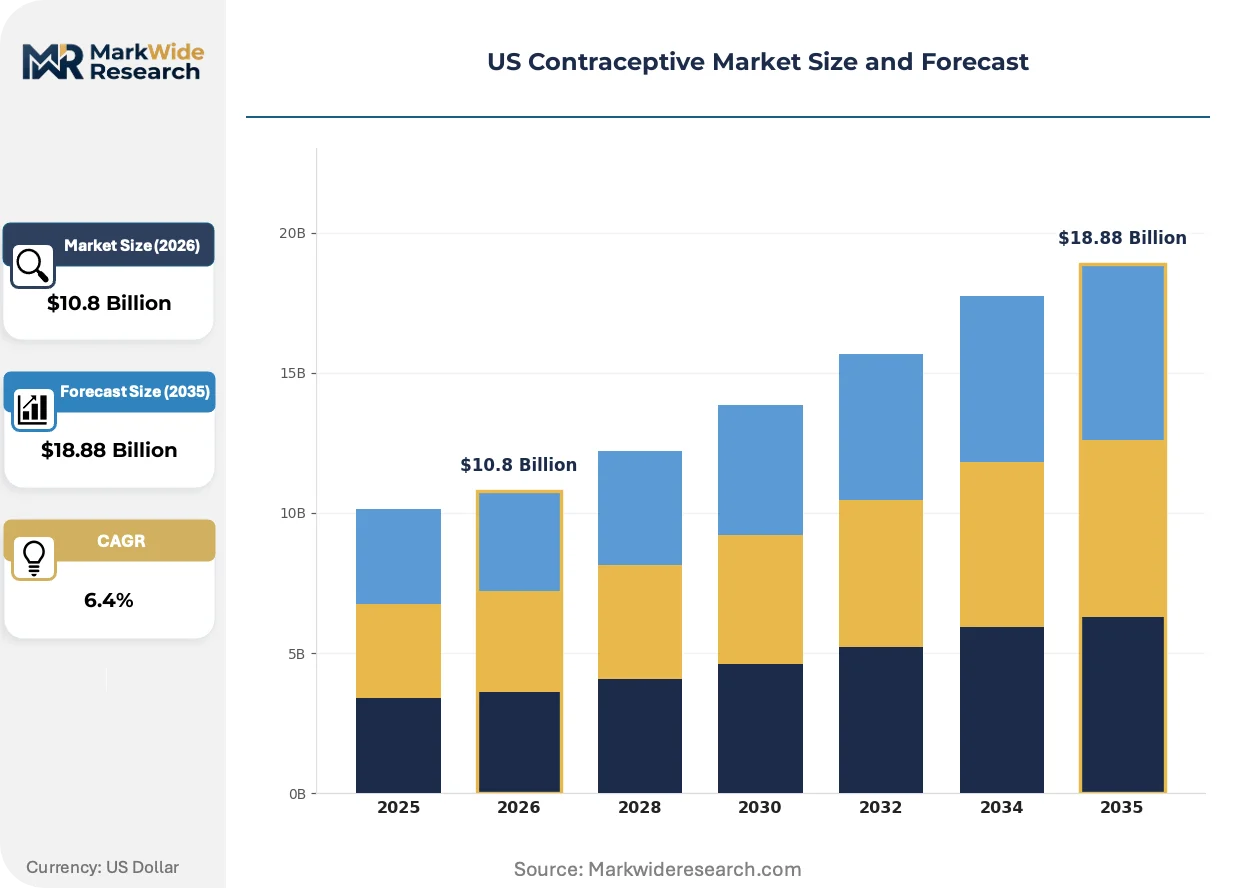
| Market Size in 2026 | $10.8 Billion |
| Market Size in 2035 | $18.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oral Contraceptives, IUDs, Condoms, Implants End User: Women, Teens, Couples, Healthcare Providers Delivery Mode: In-Clinic, At-Home, Pharmacies, Online Pricing Model: Insurance Coverage, Out-of-Pocket, Subscription, Free |
| Companies Covered | Pfizer Inc., Bayer AG, Merck & Co. Inc., AbbVie Inc., Teva Pharmaceutical Industries Ltd., Church & Dwight Co. Inc., Reckitt Benckiser Group Plc, The Cooper Companies Inc., Organon Group of Companies, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Contraceptive Market Strategic Shifts & Innovations
Digital health infrastructure is rewiring how contraceptive counseling, prescription authorization, and product fulfillment connect, collapsing traditional primary care gatekeeping while raising new questions about clinical oversight.
Long-acting reversible contraceptive technology is fragmenting the historical oral-dominant market structure. Hormonal IUDs and subdermal implants now capture preference share among nulliparous women aged 18-29 who previously cycled through pill discontinuation. This shift is compressing pharmacy volume for monthly oral refills while expanding office-based procedural revenue for insertion and removal services.
FDA guidance on real-world evidence for contraceptive effectiveness is accelerating post-market surveillance requirements for new hormonal delivery systems. Manufacturers must now maintain active pregnancy registry databases as a condition of approval extension. Device sponsors with existing levonorgestrel portfolios are absorbing these compliance costs into lifecycle management budgets, while novel entrants face higher barriers to market entry.
Subscription-based contraceptive delivery is displacing traditional pharmacy pickup patterns among urban millennials and Gen Z patients. Telehealth platforms in New York and California bundle asynchronous provider consultation with automated 90-day supply shipments. This channel shift is most visible in oral contraceptive categories where generic substitution rules allow pharmacy benefit managers to steer toward lowest-net-cost formulations.
US Contraceptive Market Segmentation
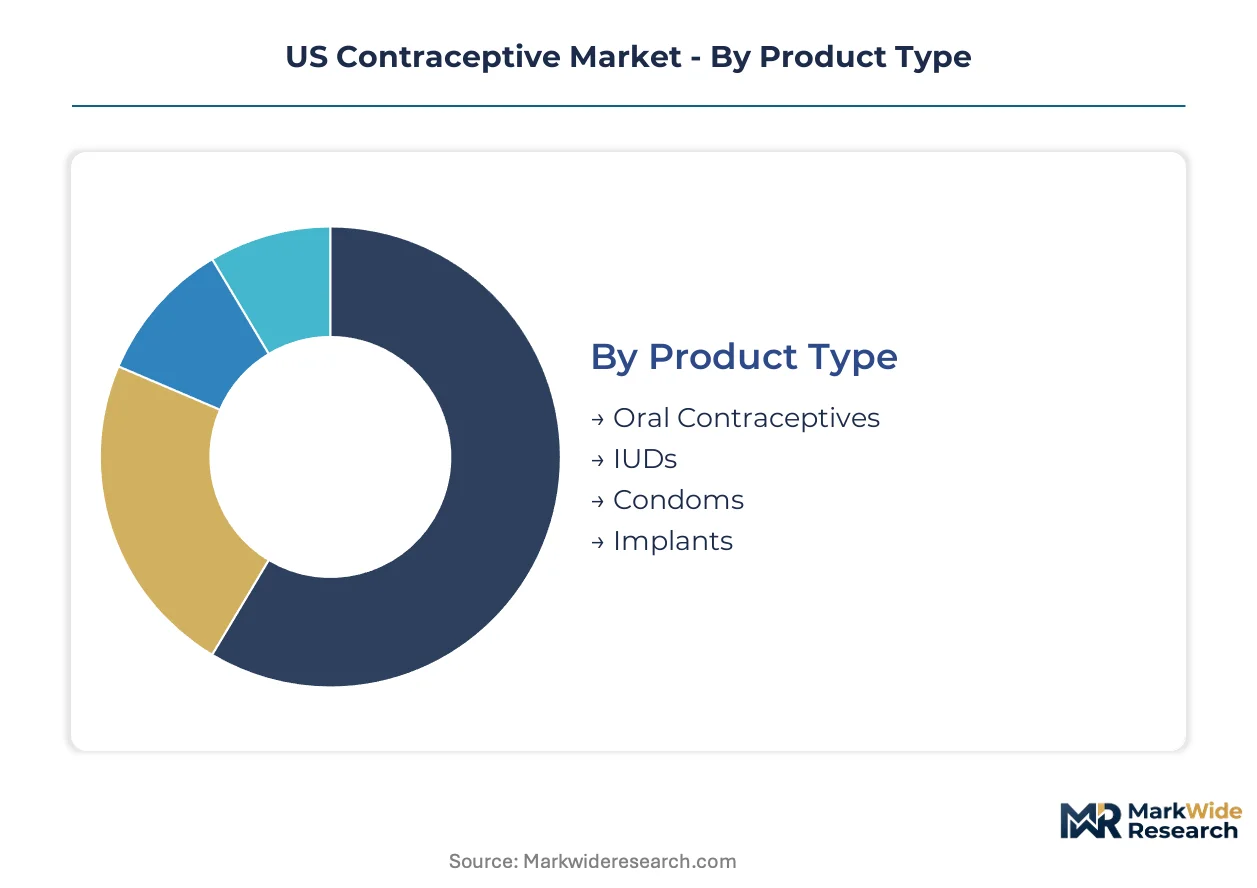
US contraceptive demand fragments across product formats, user demographics, and access channels. Each segment carries distinct margin profiles and regulatory exposure that shape manufacturer strategy and provider investment priorities.
Product Type:
Margin pools concentrate in long-acting reversible devices where upfront reimbursement and extended duration offset higher manufacturing complexity.
- IUDs:Hormonal and copper intrauterine devices release levonorgestrel or generate spermicidal copper ion concentrations. Demand clusters in California and New York Medicaid expansion states where ACA preventive coverage eliminates cost barriers for low-income patients.
- Implants:Etonogestrel-releasing subdermal rods provide three-year protection through single insertion. Young adult women aged 18-29 in urban markets are driving uptake as they abandon oral discontinuation cycles.
- Oral Contraceptives:Daily ethinyl estradiol-progestin combinations retain volume leadership but face margin erosion from generic saturation.
- Condoms:Barrier methods serve dual pregnancy and STI prevention functions with over-the-counter accessibility.
IUDs hold installed capacity. Implants are rotating up the share rankings.
End User:
Volume concentration varies sharply by reimbursement pathway and clinical oversight requirements.
- Women:Adult women aged 18-44 constitute the core addressable population across all product categories. California and New York family planning clinics report highest IUD and implant insertion volumes under expanded Medicaid eligibility.
- Teens:Adolescents aged 15-19 face access fragmentation from state-level parental consent statutes. Confidential services in expansion states contrast with restricted clinic participation in Texas and Florida.
- Couples:Partner-involved decision-making drives condom selection and shared cost responsibility for subscription oral deliveries.
- Healthcare Providers:OB-GYNs, family medicine physicians, and nurse practitioners control insertion capacity for device-based methods.
Women anchor volume throughput. Teens represent the steepest expansion trajectory where regulatory barriers ease.
Delivery Mode:
Channel economics diverge between procedural reimbursement and product margin capture.
- In-Clinic:Office-based insertion and counseling services bill procedural codes with higher reimbursement rates. Community health centers in expansion states are expanding IUD and implant capacity through HRSA funding.
- At-Home:Direct-to-consumer platforms collapse prescription-to-delivery timelines for oral contraceptives. Telehealth-integrated logistics capture patients in contraceptive deserts across rural Texas and Georgia.
- Pharmacies:Retail and independent pharmacies dispense oral generics under PBM substitution rules.
- Online:Subscription platforms bundle asynchronous consultation with automated 90-day shipments.
In-Clinic commands premium positioning. At-Home is climbing the fastest as telehealth infrastructure matures.
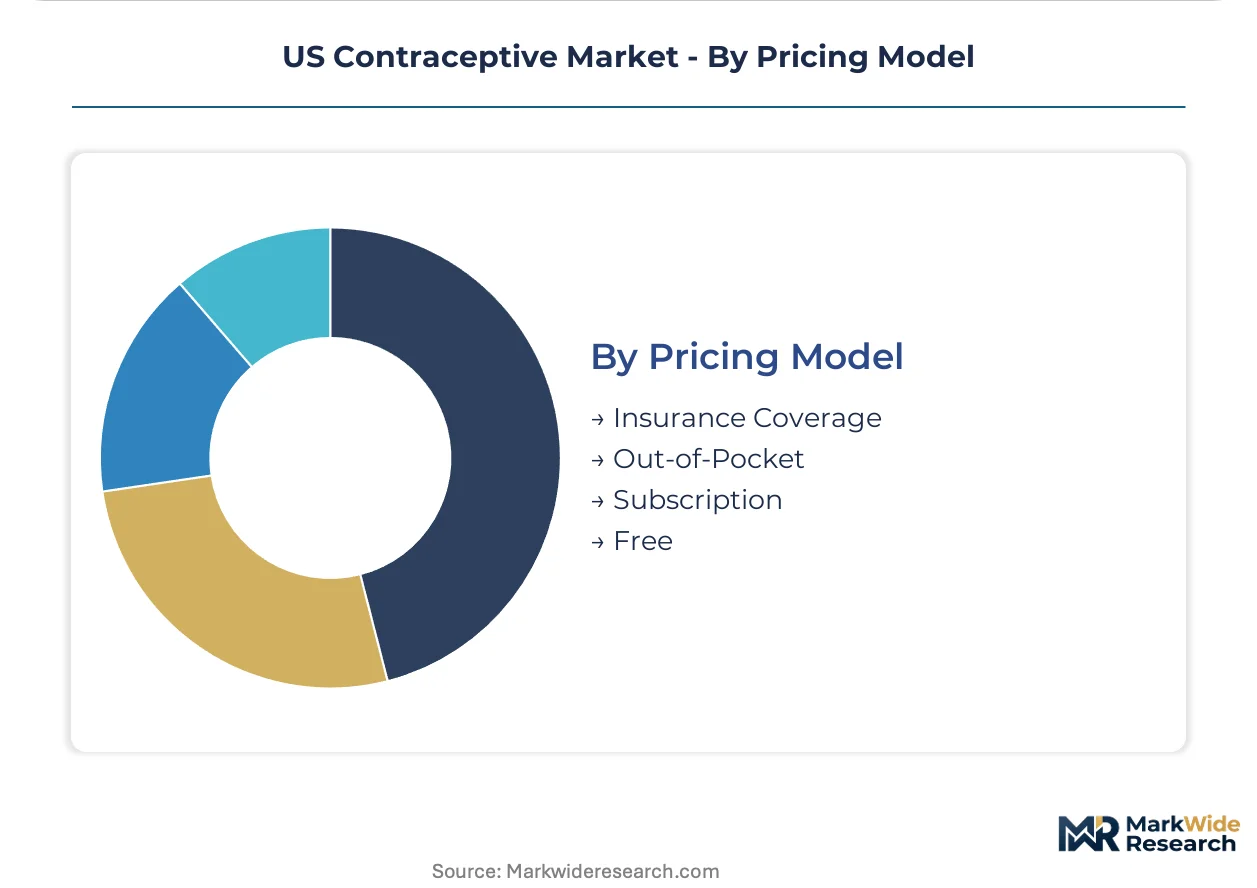
Pricing Model:
Revenue realization depends on payer mix and state Medicaid configuration.
- Insurance Coverage:ACA preventive services mandate eliminates cost-sharing for FDA-approved methods in commercial and expansion Medicaid plans. This pathway captures IUD and implant demand in California, New York, and Illinois.
- Out-of-Pocket:Cash-pay transactions dominate in Texas, Florida, and Georgia where Medicaid restrictions leave 4.2 million women without subsidized access.
- Subscription:Monthly or quarterly billing models align with oral contraceptive adherence patterns and telehealth platform economics.
- Free:Title X-funded clinics and safety-net providers distribute methods without charge to qualifying low-income patients.
Insurance Coverage holds installed capacity. Subscription is gaining share fastest among urban millennial and Gen Z cohorts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Interstate 95 corridor and major freight rail networks linking Boston to Washington anchor contraceptive distribution infrastructure across the US Northeast, while the Port of Long Beach handles inbound pharmaceutical raw materials for West Coast manufacturing clusters.
California
Medicaid expansion under Section 1115 waivers drives IUD and implant insertion volumes at Los Angeles County family planning clinics. FDA premarket notification requirements govern device safety standards for manufacturers supplying the San Francisco Bay Area biotech corridor. The Oakland-Alameda health system cluster reports highest long-acting reversible contraceptive uptake rates among publicly insured patients.
New York
Expanded Medicaid eligibility eliminates cost barriers for hormonal IUDs across New York City boroughs and upstate metropolitan areas. The Affordable Care Act preventive coverage mandate shapes commercial insurance reimbursement structures statewide. Buffalo-Rochester-Syracuse corridor health centers concentrate provider capacity for subdermal implant services.
Texas
Medicaid family planning restrictions leave 1.8 million women without subsidized long-acting coverage, creating cash-pay demand concentration in Houston and Dallas-Fort Worth metro areas. State-level pharmacy access regulations limit telehealth platform expansion. The Texas Medical Center in Houston anchors private-pay contraceptive counseling volume.
Illinois
ACA-compliant commercial plans and expanded Medicaid drive dual reimbursement pathway complexity for Chicago-area providers. FDA 510(k) review timelines affect device innovation pipelines serving the Midwest manufacturing belt. Cook County health system clinics report elevated implant removal procedure volumes correlating with initial insertion demand cycles.
Florida
Non-expansion Medicaid status restricts subsidized access for 1.4 million women, channeling demand toward retail pharmacy oral contraceptive purchases in Miami-Dade and Orange County markets. State parental consent statutes fragment adolescent access patterns. Jacksonville-Tampa corridor telehealth platforms capture subscription oral deliveries despite regulatory friction.
US Contraceptive Market Key Industry Players
Concentration sits with diversified pharmaceutical conglomerates holding hormonal portfolio depth across multiple delivery formats. Three strategic archetypes define competitive positioning: established hormonal innovators with IUD and implant device capabilities, generic oral manufacturers competing on pharmacy benefit manager substitution economics, and consumer health specialists with over-the-counter barrier method distribution. Dominant competitive moves include portfolio diversification across prescription and non-prescription channels, and strategic partnerships with telehealth platforms for direct-to-consumer fulfillment.
Within the diversified pharmaceutical tier, Pfizer Inc. and Bayer AG exemplify archetypes with established hormonal portfolios spanning multiple delivery mechanisms. Teva Pharmaceutical Industries Ltd. occupies a position representing generic oral contraceptive competition dynamics. Among device-focused specialists, The Cooper Companies Inc. and Organon Group of Companies anchor the long-acting reversible contraceptive segment structure.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Bayer AG |
| Merck & Co. Inc. |
| AbbVie Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Church & Dwight Co. Inc. |
| Reckitt Benckiser Group Plc |
| The Cooper Companies Inc. |
| Organon Group of Companies |
| Others |
Cost & Logistics Intelligence
Generic ethinyl estradiol substitution for branded oral formulations is redrawing procurement geography toward Indian and Chinese API manufacturers while compressing pharmacy reimbursement rates for legacy hormonal portfolios. This input shift simultaneously erodes margin capture at branded manufacturers and concentrates pricing power with pharmacy benefit managers steering toward lowest-net-cost alternatives.
Pricing Analysis
Volume-discount tiering structures dominate procurement negotiations, with three-tier pricing separating premium branded IUDs from standard hormonal implants and economy generic orals. Price differentiation rests on FDA certification tier and vertical integration depth, as manufacturers with captive levonorgestrel synthesis command wider spreads. Cost compression in the generic oral tier is intensifying because pharmacy benefit manager substitution rules narrow formulary positioning. Safety-net clinics and Title X providers exhibit highest price sensitivity, while private OB-GYN practices show lowest sensitivity due to procedural reimbursement bundling.
Supply Chain Analysis
Port congestion at Long Beach and container availability fluctuations on the transpacific lane elevate inbound logistics costs for copper IUD raw materials sourced from Chilean mining operations. Manufacturing concentration spans China for API synthesis, Germany for precision polymer extrusion, and the United States for final device assembly. Supply chain risk centers on single-source vulnerability for etonorgestrel implant cores. Distribution runs through specialty pharmaceutical wholesalers serving hospital systems and direct-to-consumer telehealth platforms bypassing traditional pharmacy networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Device removal and replacement services are expanding faster than initial insertion hardware, creating a recurring-revenue layer that outpaces one-time product sales. This service-attach dynamic rewards platforms bundling procedural access with longitudinal patient management.
For Market Incumbents: Secure insertion-capable provider networks against telehealth platform encroachment by expanding training partnerships with nurse practitioner programs in Texas and Florida. Acquire subdermal implant manufacturing capacity to offset generic oral saturation pressure. Defensive consolidation around procedural service revenue protects against direct-to-consumer disintermediation.
For New Entrants and Emerging Players: Cash-pay subscription gaps in non-expansion states represent the most penetrable white-space, where 4.2 million women lack subsidized long-acting access. Target pharmacist prescribing authority expansions in California and Oregon for point-of-care hormonal initiation without physician gatekeeping. A telehealth-integrated logistics model capturing rural contraceptive deserts offers the clearest go-to-market angle.
For Investors and Strategic Acquirers: FDA real-world evidence requirements for contraceptive effectiveness reshapes the acquisition landscape toward sponsors with established pregnancy registry infrastructure. Long-term viability across the next decade favors device-focused specialists with biodegradable implant pipelines over saturated generic oral manufacturers. Watch state Medicaid expansion decisions as the primary inflection signal for addressable market expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pathway Optimization | Accelerated premarket notification timelines reduce 18-36 month review burdens for novel delivery mechanisms. |
| Telehealth Platform Integration | Asynchronous provider consultation with automated 90-day shipments captures contraceptive desert populations. |
| Biodegradable Implant R&D | NIH contraceptive development grants attract polymer-based subdermal systems eliminating removal procedures. |
| Pharmacist Prescribing Expansion | State-level scope-of-practice liberalization enables point-of-care hormonal initiation without physician visits. |
| Medicaid Waver Navigation | Section 1115 waiver expertise unlocks IUD and implant uptake among previously priced-out low-income populations. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with device manufacturers, formulary directors at pharmacy benefit managers, and family planning clinic administrators; and secondary validation against FDA 510(k) filings, CMS Medicaid enrollment statistics, and state-level pharmacy access regulations. Bottom-up demand modeling from insertion procedure volumes and top-down market sizing from manufacturer revenue disclosures were triangulated for convergence.
Across the analysis window, the forecasting framework modeled product type segmentation alongside end-user demographics, delivery mode channel economics, and state-level Medicaid configuration. CAGRs were derived from trend extrapolation of long-acting reversible uptake rates and oral contraceptive volume erosion patterns. Key inputs included HRSA-funded clinic capacity expansion trajectories and telehealth platform prescription fulfillment growth curves.
Material uncertainties — judicial reinterpretations of ACA contraceptive coverage mandates, state Medicaid expansion reversals, and copper supply disruptions from Andean mining volatility — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory stability and reimbursement continuity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Reproductive Health
Europe in Vitro Fertilization (IVF) Market
Reproductive Health
Asia-Pacific in Vitro Fertilization (IVF) Market
Reproductive Health
Global Gynecology Drugs Market
Reproductive Health
Hormonal Contraception Market
Reproductive Health
Global Male Infertility Market
Reproductive Health
Surrogacy Market
Reproductive Health
Pregnancy Care Products Market
Reproductive Health
Doula and Birth Coaching Services Market
Reproductive Health
Donor Egg IVF (in-Vitro Fertilization) Market
Reproductive Health
Egg Donation Market
Reproductive Health
Germany in Vitro Fertilization (IVF) Market
Reproductive Health
US Sexual and Reproductive Health Clinics Market
Reproductive Health
Smart Fertility Tracker Market
Reproductive Health
Cryopreservation for in-Vitro Fertilization (IVF) Market
Reproductive Health
US Birth Centers Market
Reproductive Health
Egg Freezing and Embryo Banking Market