
 Global Male Infertility Market | 2026-2036
Global Male Infertility Market Size, Share, and Industry Trends Forecast 2026-2036
Global Male Infertility Market Intelligence
Demand from large, multi-site fertility clinics is bifurcating the customer base away from smaller, independent urology centers. CooperSurgical leverages its comprehensive portfolio of assisted reproductive technology (ART) solutions to serve these large clinical networks. Merck KGaA sustains its market position through its established hormone therapy and fertility drug pipeline. Vitrolife specializes in high-tech lab equipment and media, targeting premium fertility centers with advanced capabilities.
Male infertility is a reproductive system disease characterized by the inability to achieve pregnancy after one year of unprotected intercourse, often linked to parameters like low sperm concentration or poor motility. The market's solutions aim to diagnose underlying causes and provide treatments to improve conception chances. Diagnostic devices, including advanced sperm analyzers, form the foundational segment for treatment planning. Concurrently, fertility drugs for treating conditions such as oligospermia constitute a major portion of therapeutic interventions delivered through fertility clinics.
Regulatory frameworks established by the US FDA and the European Medicines Agency (EMA) dictate the stringent clinical trial requirements for new fertility drugs. In parallel, approvals from bodies like China's NMPA control market access for both novel therapeutics and advanced diagnostic instruments. Stakeholders must now decide how to balance investments in next-generation genetic screening technologies against the cost-containment pressures within public and private healthcare systems.
Market Dynamics
The central dynamic shaping the male infertility market is the push-pull between rapid technological advancements in genetic and molecular diagnostics and the countervailing pressure for cost containment from public and private healthcare payers, which often limits reimbursement and patient access.
Growth Catalysts
- Pro-Natalist Policies:Government initiatives in countries like China aimed at increasing birth rates are directly stimulating demand for fertility services and related diagnostic and therapeutic products.
- Diagnostic Innovation:The development of more precise diagnostic methods, such as sperm DNA fragmentation analysis, enhances the accuracy of diagnoses, leading to better-tailored and more effective treatment plans within fertility clinics.
- Rising Health Awareness:Increasing public discourse and destigmatization surrounding male factor infertility in developed nations encourage more men to seek medical evaluation, expanding the patient pool for diagnostic and treatment providers.
Market Restraints
- High Treatment Costs:The substantial out-of-pocket expense for advanced assisted reproductive technologies and fertility drugs remains a significant barrier to access for a large portion of the population without comprehensive insurance coverage.
- Regulatory Hurdles:Stringent clinical evidence requirements mandated by regulatory bodies like the US FDA and EMA for new fertility drugs create long and expensive development timelines, slowing the introduction of novel therapies.
- Cultural and Social Barriers:In many regions, persistent social stigma and a lack of education about male infertility prevent individuals from seeking timely diagnosis and treatment, suppressing market potential.
Strategic Opportunities
- At-Home Diagnostics:Developing direct-to-consumer, FDA-cleared or CE-marked male fertility testing kits offers a path to reach a broader audience by providing a private, accessible, and less intimidating entry point for fertility assessment.
- Geographic Expansion:Untapped markets in Latin America and Southeast Asia present significant growth opportunities as rising disposable incomes and improving healthcare infrastructure increase access to fertility care.
- Telehealth Integration:Integrating male fertility consultations and follow-ups into telehealth platforms can improve patient convenience, reduce travel burdens, and expand the reach of specialized andrology expertise beyond major urban centers.
Industry Challenges
- Specialized Talent Shortage:A deficit of highly trained embryologists and andrologists proficient in complex procedures like ICSI and preimplantation genetic testing creates operational bottlenecks for fertility clinics.
- Data Standardization Gaps:The absence of uniform data reporting standards across global fertility clinics hinders the ability to conduct large-scale, multi-center studies and accurately benchmark treatment outcomes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Male Infertility Market |
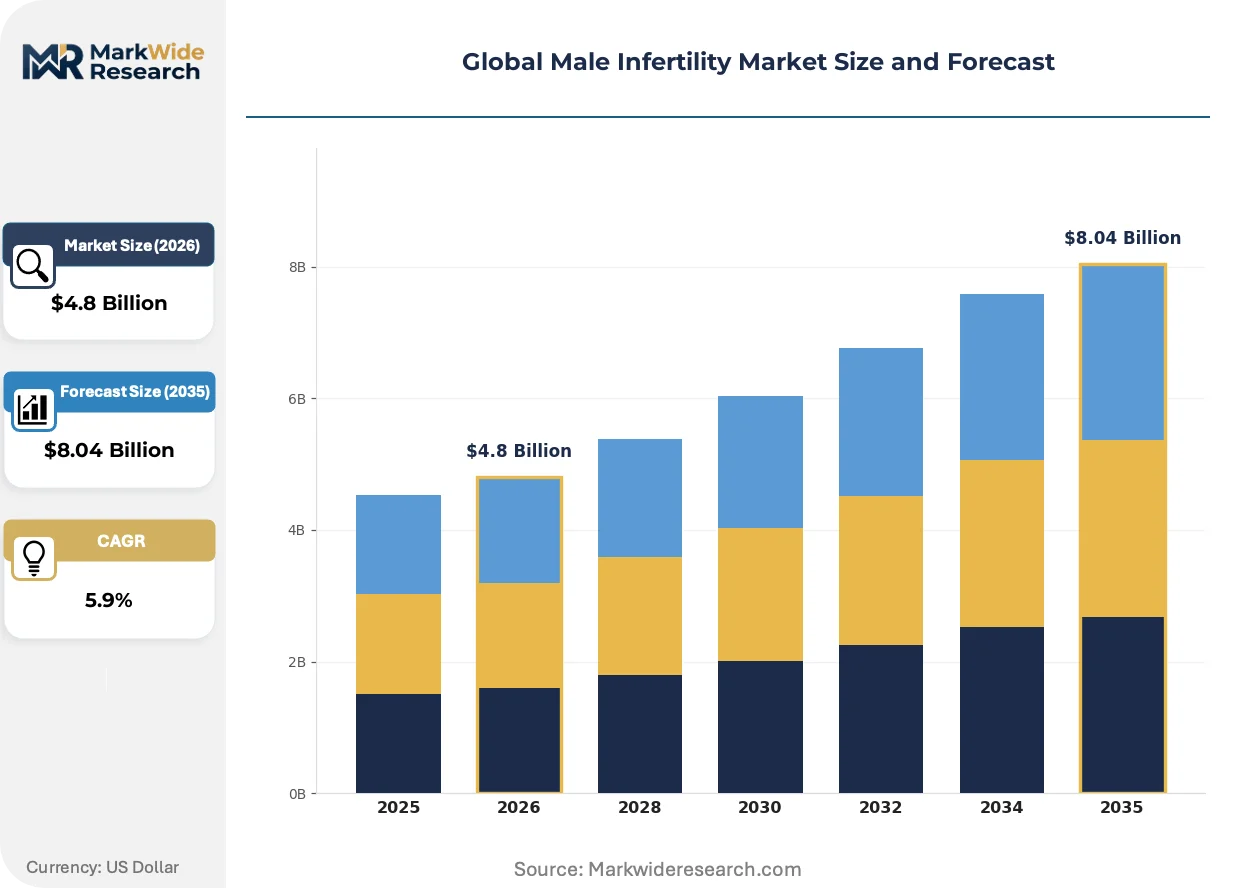
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.04 Billion |
| CAGR (2026 – 2036) | 5.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Devices, Fertility Drugs, Hormone Therapy, Surgical Instruments Therapy Area: Oligospermia, Azoospermia, Asthenospermia, Teratospermia End User: Fertility Clinics, Andrology Labs, Urology Centers, Research Institutions Distribution Channel: Hospital Pharmacies, Retail Pharmacies, Online Pharmacies, Wholesalers |
| Companies Covered | Merck KGaA, Vitrolife, CooperSurgical, Ferring International, Halotech DNA, Bayer AG, Andrology Solutions, Endo International plc, SCSA Diagnostics, Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Male Infertility Market Strategic Shifts & Innovations
The convergence of microfluidics, artificial intelligence, and genetic screening is transforming male infertility care. This shift moves the market away from generalized approaches toward highly personalized diagnostic and therapeutic strategies tailored to the individual's specific biological profile.
Microfluidic sperm sorting chips are a key innovation that leverages precise fluid control to isolate sperm with the highest motility and best morphology. High-volume fertility clinics are adopting these devices to enhance the quality of samples used in ART procedures like IVF and ICSI. This technology is miniaturizing the traditionally complex and time-consuming sperm preparation process into a standardized, disposable format, improving consistency and reducing labor.
Regulatory frameworks are evolving to address the complexity of new technologies. China's NMPA, for instance, has implemented more rigorous review processes for novel medical devices, including advanced genetic testing kits and AI-powered diagnostic software. This forces manufacturers to provide more extensive clinical validation data to gain market access. Consequently, companies targeting the Chinese market are allocating greater resources to clinical trials and regulatory affairs.
A notable behavioral shift involves large fertility clinic networks centralizing procurement for capital equipment and high-volume consumables. This consolidated purchasing model is displacing the previous pattern of fragmented buying by individual physicians or smaller independent practices. The trend is most prominent in the United States and parts of Europe, where private equity investment is driving clinic consolidation and professionalizing supply chain management.
Global Male Infertility Market Segmentation
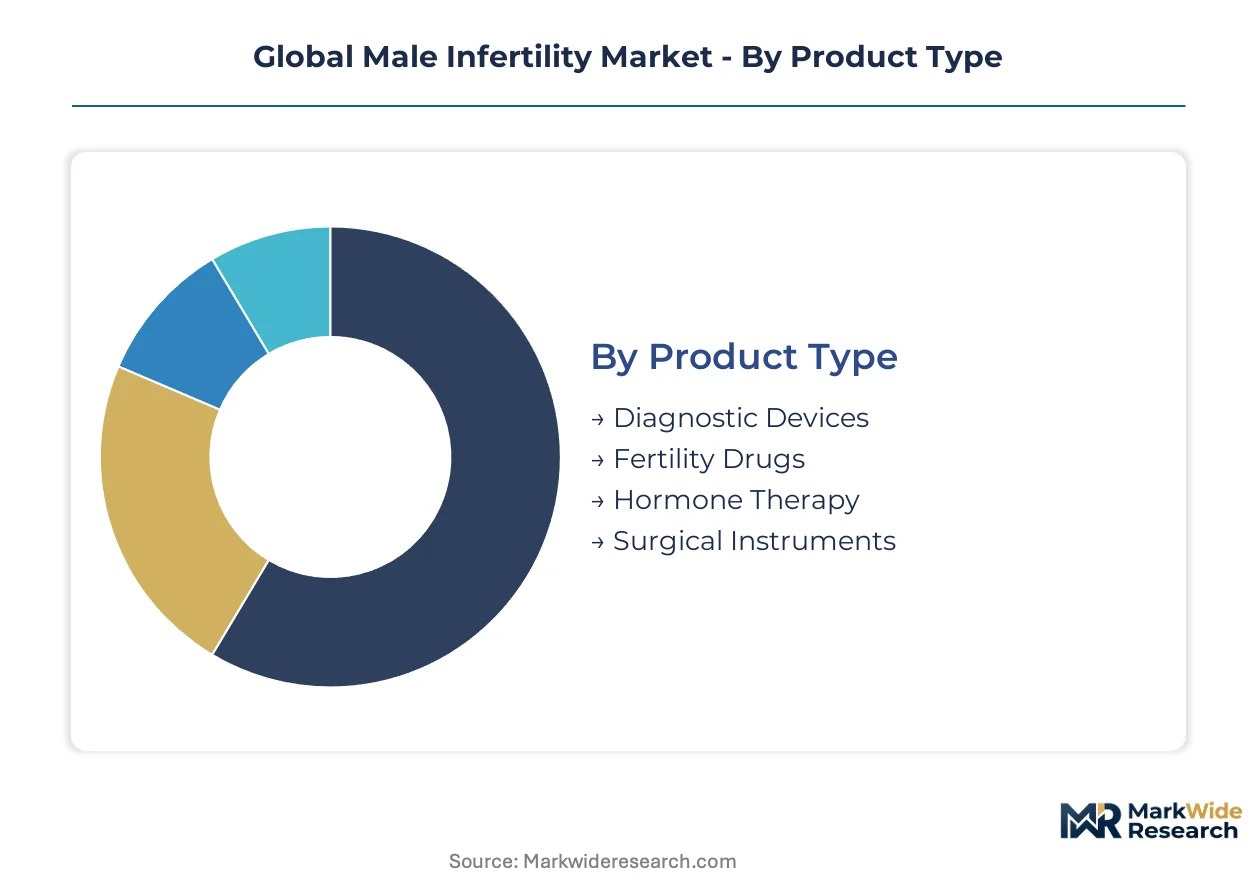
The male infertility market's segmentation provides a detailed framework for understanding specific demand patterns and supply chain dynamics. Analyzing these segments reveals how different product types and therapeutic approaches address the diverse needs of affected individuals. This granular view assists stakeholders in identifying key growth areas and operational efficiencies across the care continuum.
Product Type:
Regulatory bodies like the US FDA and China's NMPA impose distinct approval pathways for devices versus drugs, influencing market entry and development timelines for product types.
- Diagnostic Devices:These instruments include advanced sperm analyzers, microfluidic sperm sorting chips, and genetic testing kits designed to identify underlying causes of male infertility. Demand for these sophisticated tools is concentrating in large fertility clinics, driven by the need for enhanced diagnostic accuracy and personalized treatment planning.
- Fertility Drugs:This segment encompasses pharmaceuticals such as gonadotropins, anti-estrogens, and antioxidants aimed at improving sperm production, motility, or hormonal balance. Consumption of these therapeutic interventions forms a major portion of treatment protocols delivered through fertility clinics, particularly for conditions like oligospermia.
- Hormone Therapy:This involves administering exogenous hormones or hormone-regulating agents to correct endocrine imbalances affecting male reproductive function.
- Surgical Instruments:This category includes specialized tools used in procedures like varicocelectomy, vasectomy reversal, or sperm retrieval techniques such as TESE and PESA.
Established volume favors Fertility Drugs; emerging adoption favors Diagnostic Devices.
Therapy Area:
The application of specific diagnostic and therapeutic interventions varies significantly based on the underlying physiological condition causing male infertility.
- Oligospermia:Characterized by a low sperm concentration, this condition often responds to fertility drugs and lifestyle modifications aimed at increasing sperm production. Treatment planning for oligospermia is a primary focus within fertility clinics, where patient-specific drug regimens are common.
- Azoospermia:Defined by the complete absence of sperm in ejaculate, this severe condition necessitates advanced diagnostic techniques to determine its obstructive or non-obstructive nature. Surgical sperm retrieval procedures are frequently employed for individuals with azoospermia, particularly in specialized andrology labs.
- Asthenospermia:This diagnosis indicates reduced sperm motility, impacting the sperm's ability to reach and fertilize an egg.
- Teratospermia:Characterized by an abnormally high percentage of sperm with irregular morphology, this condition often influences the success rates of assisted reproductive technologies.
Specific diagnostic precision drives demand for Azoospermia treatments, while broader therapeutic needs sustain Oligospermia interventions.
End User:
Customer type differentiation dictates the scale of equipment procurement and the specialization of services required for male infertility management.
- Fertility Clinics:These multi-site networks and independent centers represent the largest end-user segment, providing comprehensive diagnostic, therapeutic, and ART services. Demand from these clinics for advanced diagnostic tools and high-volume consumables is concentrating, driven by patient volume and the integration of diverse treatment modalities.
- Andrology Labs:Specialized laboratories focus on sperm analysis, cryopreservation, and advanced sperm preparation techniques essential for assisted reproduction. These labs often serve as referral centers, demanding high-precision equipment and specialized reagents for detailed male factor assessment.
- Urology Centers:These medical facilities primarily address the anatomical and physiological issues contributing to male infertility, often performing surgical corrections.
- Research Institutions:Academic and private research entities conduct studies on male reproductive health, requiring specialized reagents, diagnostic kits, and laboratory equipment for experimental protocols.
Specialized service offerings define Fertility Clinics, with general access points provided by Urology Centers.
Distribution Channel:
Supply concentration within the pharmaceutical and medical device supply chain influences the accessibility and pricing of male infertility products.
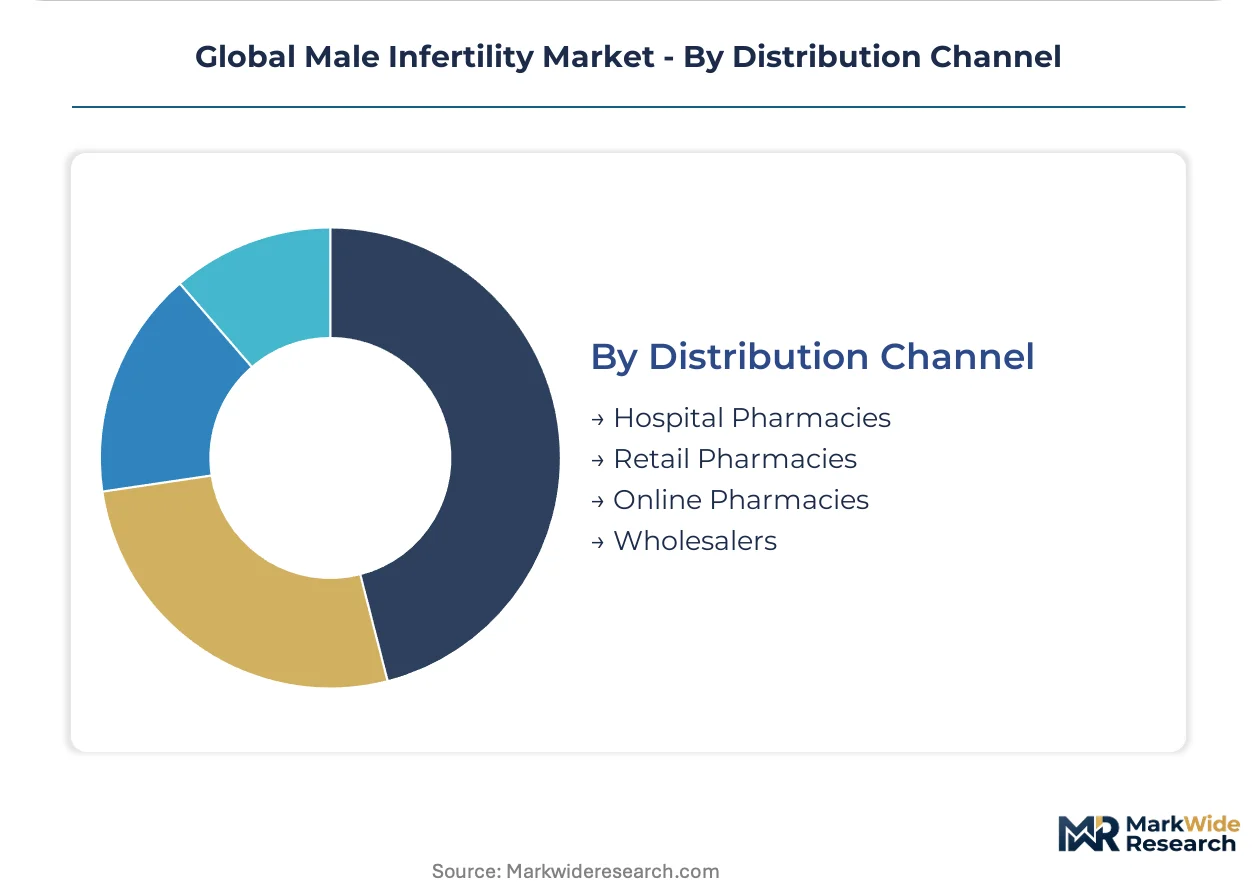
- Hospital Pharmacies:These pharmacies dispense fertility drugs and related medical supplies directly within hospital settings, often for inpatient or specialized outpatient treatments. They manage bulk procurement and maintain strict inventory control for high-value medications and devices.
- Retail Pharmacies:Community-based retail pharmacies offer convenient access to prescription fertility medications and over-the-counter supplements for male reproductive health. They cater to a broad patient base, fulfilling prescriptions issued by fertility specialists and urologists.
- Online Pharmacies:Digital platforms provide a discreet and convenient channel for purchasing fertility-related medications and diagnostic kits, particularly appealing to patients seeking privacy.
- Wholesalers:These entities serve as intermediaries, distributing large volumes of pharmaceutical products and medical devices from manufacturers to various healthcare providers and pharmacies.
Immediate patient access relies on Retail Pharmacies, while bulk procurement channels support Wholesalers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The trade corridor from European pharmaceutical hubs to Asian markets significantly influences the global male infertility landscape. Advanced diagnostic tools and therapeutic interventions developed in Western nations are increasingly finding demand in populous Eastern economies. This dynamic drives investment in both R&D and market access strategies.
United States
High adoption of advanced diagnostic devices, driven by patient demand for personalized treatments, is observed across the United States. The US FDA's stringent clinical trial requirements shape new drug development timelines for novel therapies. Major biotech clusters in Boston and San Francisco actively research next-generation genetic screening technologies.
Germany
Demand for fertility drugs and hormone therapies remains strong in Germany, supported by an advanced healthcare infrastructure. The European Medicines Agency (EMA) sets high standards for drug approval across the region, impacting market entry. Munich and Berlin are centers for medical technology innovation, fostering new diagnostic instrument development.
China
Pro-natalist policies are directly stimulating demand for fertility services and related products in China, especially in urban centers. China's NMPA has implemented rigorous review processes for novel medical devices and genetic testing kits. Shanghai and Beijing's large fertility clinics are rapidly integrating advanced ART procedures.
India
Rising health awareness and increasing disposable incomes are expanding the patient pool for male infertility diagnostics and treatments in India. The Central Drugs Standard Control Organization (CDSCO) regulates pharmaceutical and medical device approvals, influencing market accessibility. Major metropolitan areas like Mumbai and Bangalore see growing numbers of specialized fertility clinics.
United Kingdom
Patient awareness regarding male factor infertility is growing across the United Kingdom, leading more men to seek medical evaluation. The EMA's regulatory framework, even post-Brexit, still influences product availability and clinical trial standards. London's medical research institutions contribute significantly to advancements in reproductive medicine.
Global Male Infertility Market Key Industry Players
Listed leaders compete with private specialists across portfolio breadth and geographic reach within the male infertility market. The competitive landscape exhibits a tiered structure, with established pharmaceutical giants alongside specialized medical device manufacturers. Strategic archetypes include integrated solution providers, niche diagnostic innovators, and therapeutic drug developers. Companies primarily engage in strategic partnerships to expand technology access and pursue targeted acquisitions for portfolio diversification.
Within the integrated solutions archetype, Germany-based Merck KGaA represents a strong presence through its established hormone therapy and fertility drug pipeline. Sweden-based Vitrolife exemplifies specialization in high-tech lab equipment and media, targeting advanced fertility centers. CooperSurgical, an American company, occupies a position as a comprehensive assisted reproductive technology (ART) solutions provider, serving large clinical networks. These entities anchor distinct segments of the market, reflecting varied approaches to product development and market penetration.
| Leading Market Players |
|---|
| Merck KGaA |
| Vitrolife |
| CooperSurgical |
| Ferring International |
| Halotech DNA |
| Bayer AG |
| Andrology Solutions |
| Endo International plc |
| SCSA Diagnostics, Inc |
| Others |
Cost & Logistics Intelligence
Specialized manufacturing processes for advanced diagnostic devices and complex pharmaceutical compounds necessitate significant capital investment, establishing high barriers to entry and shaping price floors across the market.
Pricing Analysis
The technology-generation pricing gap is evident between established fertility drugs and novel genetic screening technologies. Value-based pricing dominates for advanced diagnostic tools, reflecting their enhanced accuracy and personalized treatment planning capabilities. Price differentiation stems from regulatory approvals like US FDA or EMA certification and the level of after-sales service offered to large fertility clinics. Pricing pressure intensifies on high-volume consumables due to cost-containment efforts from public healthcare systems. Public healthcare payers represent the most price-sensitive segment, while private fertility clinics with premium offerings demonstrate less sensitivity.
Supply Chain Analysis
Inbound logistics costs for specialized reagents and microfluidic chips, often originating from European pharmaceutical hubs and US biotech clusters, impact supply chain stability. Geographic supply concentration for active pharmaceutical ingredients (APIs) primarily resides in China and India, with high-tech device components sourced from Germany and the United States. The supply chain relies on specialized reagents and advanced microfluidic chips as critical raw material dependencies. Single-source vulnerability for proprietary diagnostic components represents a structural risk. Distribution runs through a hybrid model, combining direct sales to large clinic networks and wholesalers serving smaller practices and hospital pharmacies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The male infertility market faces a significant capability scarcity, particularly in highly trained embryologists and andrologists proficient in complex assisted reproductive technologies.
For Market Incumbents: Compound existing strengths in comprehensive ART solutions by acquiring niche diagnostic innovators focused on genetic screening technologies. This move defends against emerging entrants offering next-generation diagnostics and mitigates cost containment pressures from public payers. Leverage established channel control through large clinic networks to integrate new offerings. Invest R&D resources into AI-powered diagnostic software to maintain a competitive edge.
For New Entrants and Emerging Players: Differentiate on accessibility and convenience, targeting the underpenetrated direct-to-consumer segment with at-home diagnostic kits. Focus on geographic white-space opportunities in Southeast Asia, where rising disposable incomes expand the patient pool. A primary go-to-market angle involves strategic partnerships with telehealth platforms to provide remote consultations and follow-ups, reducing travel burdens for patients.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated ART solution providers and specialized diagnostic firms offering subscription-based software or consumables. Long-term viability hinges on companies that can demonstrate robust clinical validation for novel therapies and diagnostic tools. Target acquisition profiles include firms developing AI-driven sperm analysis platforms or genetic screening technologies. The signal to watch is expanding reimbursement coverage for advanced male infertility diagnostics in key markets like the United States and Germany.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Accelerates regulatory approval for novel fertility drugs and advanced diagnostic devices, expanding market access. |
| Platform Integration | Enhances interoperability between diagnostic instruments and treatment planning software within fertility clinics. |
| Geographic Expansion | Captures demand in high-growth regions like Latin America and Southeast Asia, diversifying revenue streams. |
| Acquisition of Specialist Firm | Adds specialized genetic screening capabilities or microfluidic technologies to an existing ART portfolio. |
| Channel Control Enhancement | Secures procurement relationships with large multi-site fertility clinic networks, stabilizing demand for consumables. |
Research Approach
Cross-validation between primary interviews with industry stakeholders and extensive secondary research anchors the qualitative findings of this study. This approach involved engaging fertility specialists, urologists, regulatory affairs managers, and clinic network executives to gather firsthand insights. Secondary validation drew from regulatory filings with the US FDA and EMA, scientific publications, and corporate financial reports, ensuring a robust data foundation.
Sensitivity analysis informs the quantitative projections across the analysis window, accounting for varying market conditions. The analytical framework models key segmentation dimensions, including product type, therapy area, end user, distribution channel, and regional regulatory approval status. Compound annual growth rates (CAGRs) were derived using historical data trends and projected market dynamics. Key industry-specific inputs, such as evolving pro-natalist policies and R&D investment in assisted reproductive technologies, influenced the forecast.
Forecasts assume regulatory continuity in regimes like the US, Europe, and China; material policy shifts would require re-modeling. The study acknowledges that unforeseen changes in healthcare reimbursement policies or significant new pro-natalist incentives could alter market trajectories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Reproductive Health
Germany in Vitro Fertilization (IVF) Market
Reproductive Health
Fertility Treatments Market
Reproductive Health
Doula and Birth Coaching Services Market
Reproductive Health
US Sexual and Reproductive Health Clinics Market
Reproductive Health
UK in Vitro Fertilization (IVF) Market
Reproductive Health
Pregnancy Care Products Market
Reproductive Health
Contraceptives Market
Reproductive Health
Ovum Egg Banking Market
Reproductive Health
US Contraceptive Market
Reproductive Health
Donor Egg IVF (in-Vitro Fertilization) Market
Reproductive Health
Hormonal Contraception Market
Reproductive Health
Surrogacy Market
Reproductive Health
Global Gynecology Drugs Market
Reproductive Health
Vaginal Exam Specula Market
Reproductive Health
Asia-Pacific in Vitro Fertilization (IVF) Market
Reproductive Health
Global Genital Herpes Treatment Market