
 Hormonal Contraception Market | 2026-2036
Hormonal Contraception Market Size, Share, and Industry Trends Forecast 2026-2036
Hormonal Contraception Market Foresight
India is fragmenting as domestic pharmaceutical capacity expands for hormonal contraceptive APIs. Bayer AG sustains long-standing manufacturing scale across European and Asian facilities. Pfizer Inc. competes through R&D intensity in next-generation progestin delivery systems. Merck & Co., Inc. anchors its position with established implant technology and healthcare provider channel control.
Hormonal contraception comprises synthetic estrogen and progestin compounds formulated to suppress ovulation through systemic hormone regulation, manufactured via steroid synthesis and micronization processes for oral, transdermal, injectable, and implantable administration. The primary commercial purpose centers on reversible fertility management across diverse patient populations and clinical settings. Oral pills retain the largest volume share among product types, though implants capture expanding margin pools through extended-duration efficacy and reduced adherence burden. Self-administered delivery modes dominate convenience-oriented segments, while long-acting formulations concentrate value growth in clinic-directed channels where provider administration ensures proper placement and monitoring.
FDA premarket review under 21 CFR 310.502 governs prescription status and labeling for hormonal contraceptives in the United States, while EMA centralized procedures coordinate market authorization across European member states with divergent reimbursement policies. India's CDSCO regulates import and domestic manufacture through the Drugs and Cosmetics Act, with BIS standards affecting API quality specifications for export-oriented production. Stakeholders must monitor evolving state-level pharmacy access legislation and payer coverage determinations that directly shape channel economics and patient out-of-pocket exposure across key markets.
Market Dynamics
Adolescent demand for menstrual regulation is redirecting volume toward clinic-based channels while state-level pharmacy access laws fragment distribution economics across the United States. This structural tension between convenience-seeking and provider-supervised administration is reshaping channel investment priorities.
Growth Catalysts
- Insurer coverage mandates:United States state-level mandates reduce patient out-of-pocket exposure and expand addressable population for prescription formulations.
- Extended-duration progestin delivery:Implant technology reduces adherence burden and shifts patient preference toward long-acting reversible contraception.
- India:Domestic API manufacturing capacity expansion under CDSCO oversight lowers input costs for export-oriented production.
Market Restraints
- Steroid synthesis input volatility:Precursor chemical costs fluctuate with pharmaceutical-grade solvent availability and energy pricing.
- FDA premarket review timelines:21 CFR 310.502 prescription status requirements extend development-to-commercialization cycles for novel formulations.
- Generic oral pill substitution:Patent-expired small-molecule alternatives compress margin pools in volume-dominant segments.
Strategic Opportunities
- Self-administered transdermal systems:Patch technology convergence with smartphone adherence tracking creates convenience-premium positioning.
- EMA centralized procedure harmonization:Streamlined multi-country authorization reduces regulatory fragmentation for European market entry.
- Sub-Saharan Africa:Underpenetrated clinic infrastructure presents volume expansion potential for injectable and implantable formats.
Industry Challenges
- Progestin formulation expertise scarcity:Specialized steroid chemistry and micronization process engineering talent concentrates in limited geographic clusters.
- CDSCO-BIS dual compliance:India's domestic quality standards and export certification requirements impose parallel documentation burdens on API manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hormonal Contraception Market |
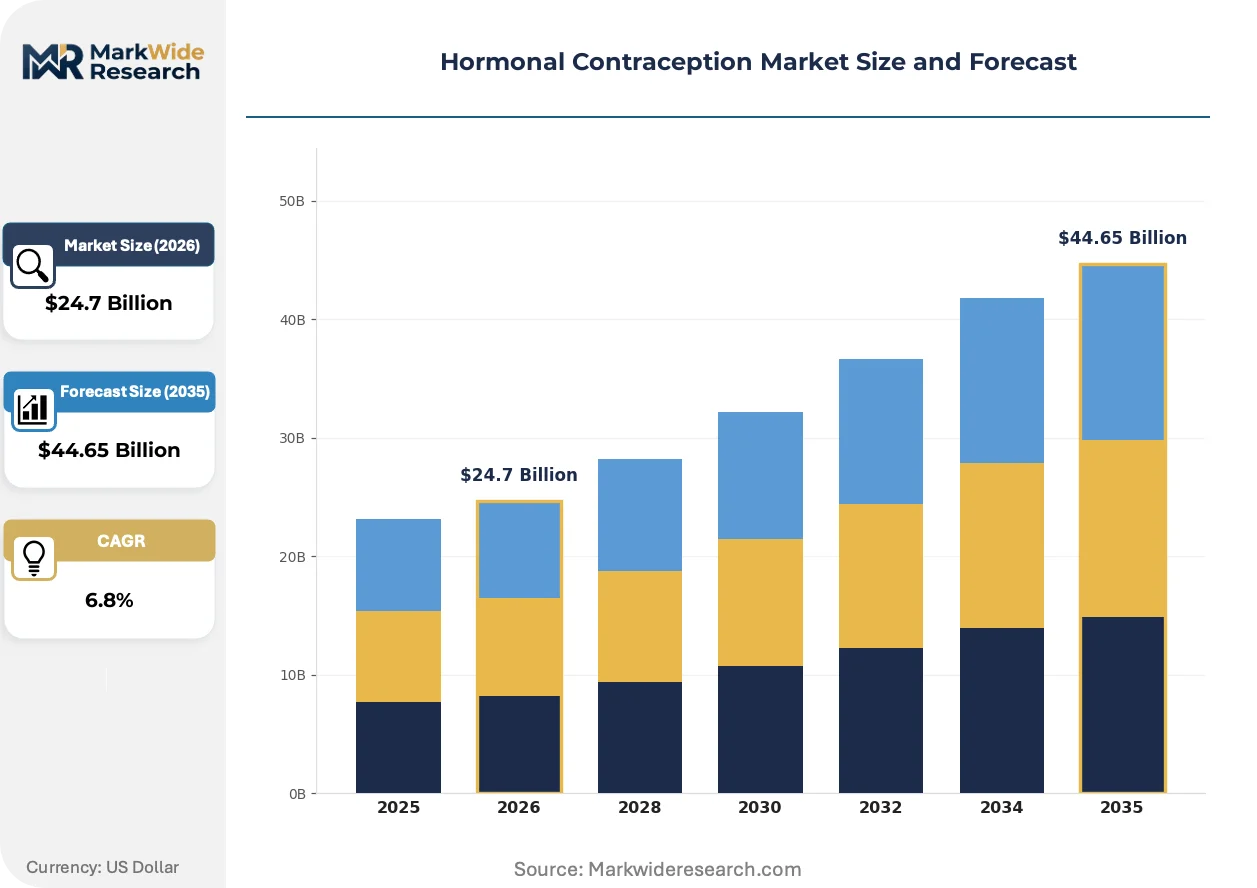
| Market Size in 2026 | $24.7 Billion |
| Market Size in 2035 | $44.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oral Pills, Patches, Injections, Implants Delivery Mode: Self-Administered, Healthcare Provider, Long-Acting, Immediate Release End User: Women, Adolescents, Couples, Clinics Application: Family Planning, Menstrual Regulation, Acne Treatment, Hormonal Therapy |
| Companies Covered | Merck & Co., Inc., Bayer AG, Pfizer Inc., Teva Pharmaceutical Industries, Johnson & Johnson, AbbVie Inc., Janssen Pharmaceuticals Inc., Lupin Pharmaceuticals Inc., Agile Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hormonal Contraception Market Shifts & Advancements
Delivery system engineering and regulatory pathway optimization are converging to compress development cycles while expanding patient self-administration options. These forces are redistributing value capture between pharmaceutical developers and point-of-care providers.
Biodegradable implant materials are hybridizing conventional polymer-based delivery with tunable erosion kinetics. Women's health clinics in Nordic markets are piloting these systems for personalized hormone release profiles. This technology is hybridizing the historical trade-off between duration and reversibility, enabling manufacturers to command premium positioning in provider-administered channels.
EMA's evolving environmental risk assessment requirements for pharmaceutical APIs are extending authorization timelines for estrogen-containing formulations. Manufacturers must now submit fate-and-transport studies alongside traditional efficacy data. Injectable and implantable categories face the most significant documentation expansion, with several sponsors delaying European filing strategies pending guidance clarification.
Subscription-based contraception delivery is displacing traditional pharmacy fulfillment for oral pill patients in direct-to-consumer channels. Telehealth platforms in the United States are bundling consultation, prescription, and home delivery under flat monthly fees. This model concentrates most visibly among urban millennials seeking discretion and schedule flexibility away from brick-and-counter pickup.
Hormonal Contraception Market Segmentation
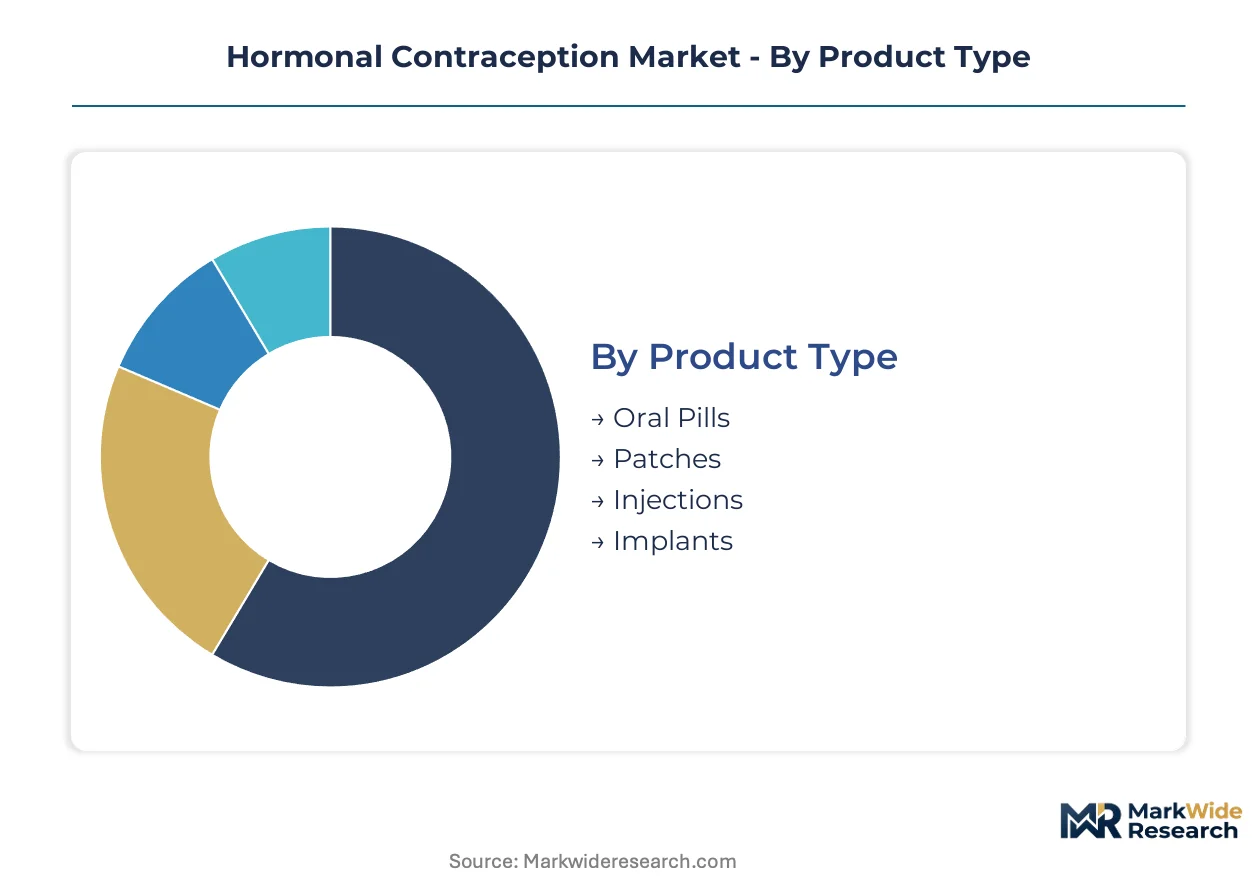
Hormonal contraception segments diverge sharply between convenience-driven self-administration and clinic-mediated long-acting formats. Product formulation, delivery mechanism, and patient lifecycle stage each create distinct margin profiles and regulatory exposure for manufacturers.
Product Type:
The use-case spectrum spans from daily adherence-dependent tablets to multi-year implantable reservoirs, with each format commanding different patient commitment levels and provider involvement intensity.
- Oral Pills:Synthetic estrogen-progestin combinations in tablet form requiring daily ingestion. Volume concentrates in retail pharmacy channels across the United States, where state-level insurance mandates reduce out-of-pocket exposure and sustain prescription refill frequency.
- Implants:Subdermal progestin-eluting rods providing multi-year efficacy through controlled-release polymer matrices. Nordic women's health clinics are piloting next-generation biodegradable variants, with demand accelerating among adolescents seeking menstrual regulation without daily compliance burden.
- Patches:Transdermal estrogen-progestin delivery via weekly adhesive application. Convenience positioning targets schedule-flexible urban demographics.
- Injections:Depot medroxyprogesterone formulations administered quarterly. Clinic-dependent delivery sustains provider channel control.
The dominant share belongs to Oral Pills, while Implants are closing the gap fastest.
Delivery Mode:
Patient autonomy versus clinical supervision defines cost tier differentiation, with self-directed formats capturing convenience premiums and provider-administered systems securing reimbursement reliability.
- Self-Administered:Oral tablets, patches, and vaginal rings under direct patient control. Telehealth subscription models in the United States are displacing traditional pharmacy fulfillment for this cohort.
- Healthcare Provider:Injections and implant insertions requiring trained administration. CDSCO-regulated clinics in India anchor volume for injectable formats.
- Long-Acting:Multi-year implants and intrauterine systems minimizing adherence failure. EMA environmental risk assessments are extending authorization timelines for estrogen-containing variants.
- Immediate Release:Emergency contraception tablets for post-coital use. Pharmacy access laws vary by United States state, fragmenting distribution economics.
Self-Administered formats retain volume leadership, though Long-Acting systems are expanding share most rapidly.
End User:
Demographic targeting shifts from fertility-focused adults to menstrual health-motivated younger patients, redirecting channel investment toward clinic-based adolescent services.
- Women:Primary reproductive-age demographic driving established family planning demand. United States insurer coverage mandates sustain prescription volume.
- Adolescents:Menstrual regulation and acne management applications expanding beyond contraceptive intent. Clinic-based channels capture this growth segment through provider-supervised initiation protocols.
- Couples:Shared decision-making contexts favoring discreet, cohabitation-compatible formats. Patch and ring systems align with this preference profile.
- Clinics:Institutional procurement for public health programs and fee-for-service administration. Sub-Saharan African infrastructure expansion targets this channel for injectable and implantable volume.
Women constitute the established base, while Adolescents are gaining share fastest.
Application:
Therapeutic scope extends beyond fertility suppression to dermatological and endocrine indications, broadening prescriber base and reimbursement coding complexity.
- Family Planning:Core fertility management indication with mature regulatory pathways. FDA 21 CFR 310.502 prescription status governs United States market access.
- Menstrual Regulation:Cycle control and dysmenorrhea management driving adolescent uptake. Nordic pilot programs for biodegradable implants target this application specifically.
- Acne Treatment:Anti-androgenic progestin formulations prescribed by dermatologists. Expands prescriber base beyond traditional gynecology.
- Hormonal Therapy:Menopausal symptom management and endocrine disorder treatment. EMA centralized procedures coordinate multi-country authorization.
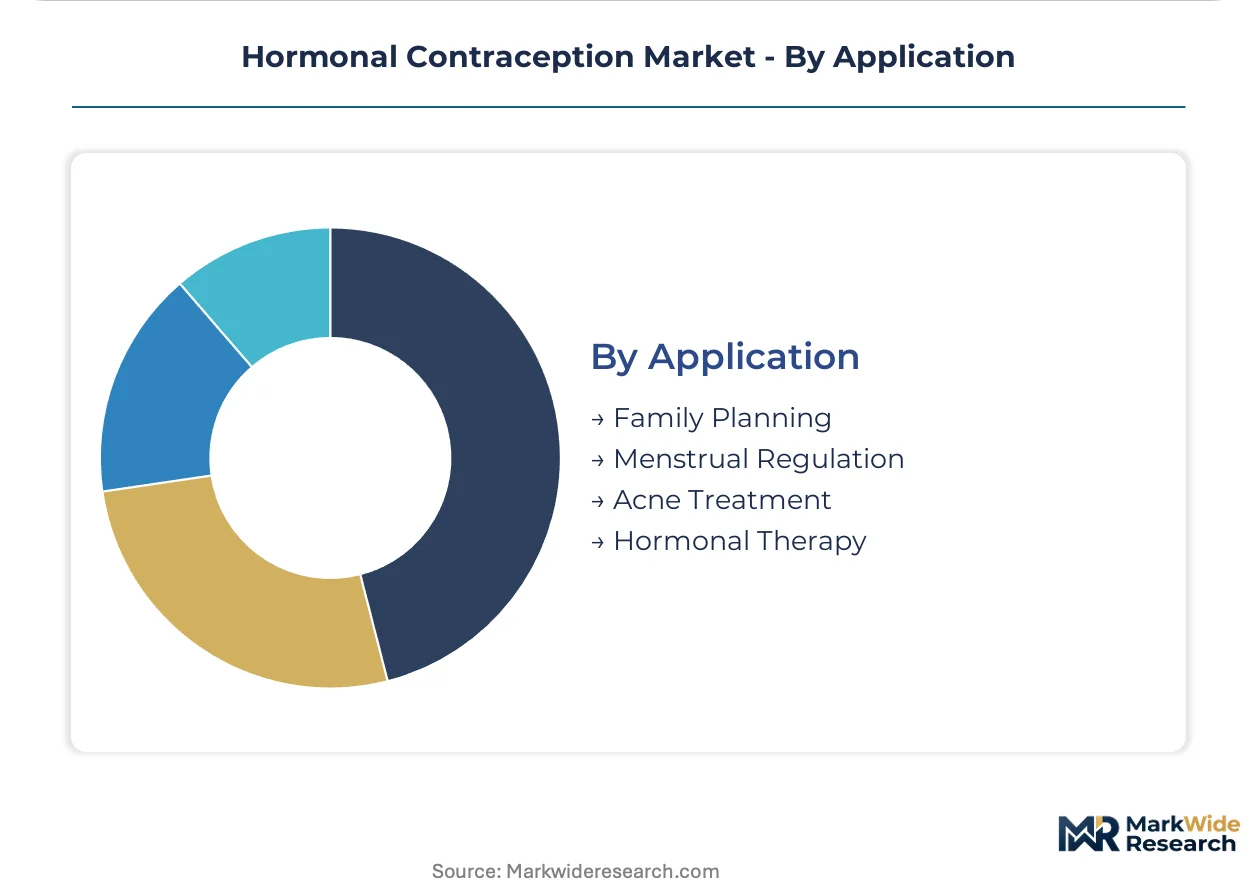
Family Planning anchors volume, while Menstrual Regulation is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Steroid synthesis capacity clusters in Germany, India, and the United States, with API manufacturing gravitating toward cost-optimized jurisdictions while formulation finishing concentrates in regulated markets with direct distribution access.
United States
Adolescent demand for menstrual regulation and acne management is redirecting volume toward clinic-based channels in Texas and California. FDA premarket review under 21 CFR 310.502 governs prescription status and labeling requirements. Boston and San Francisco anchor telehealth subscription models that bundle consultation, prescription, and home delivery under flat monthly fees.
Germany
Extended-duration implant technology and biodegradable polymer research command premium positioning among provider-administered formats. EMA centralized procedures coordinate multi-country authorization while REACH compliance shapes environmental risk assessment documentation. The Rhine-Ruhr pharmaceutical corridor sustains Bayer AG's manufacturing scale for progestin-eluting systems.
India
Domestic API manufacturing expansion under CDSCO oversight is lowering input costs for export-oriented steroid production. BIS quality specifications and DGFT export certification requirements impose parallel documentation burdens on manufacturers in Maharashtra and Gujarat. The Hyderabad-Visakhapatnam corridor concentrates micronization process engineering talent for pharmaceutical-grade hormone synthesis.
United Kingdom
Self-administered transdermal patches and vaginal rings capture convenience premiums among urban millennials seeking schedule flexibility. MHRA operates under EMA-aligned frameworks post-Brexit, with divergent reimbursement policies across NHS England, Scotland, and Wales. The London-Oxford-Cambridge golden triangle anchors women's health clinic networks piloting next-generation biodegradable implants.
Brazil
Injectable depot formulations sustain clinic-dependent delivery in public health program procurement through SUS, the national health system. ANVISA regulates import and domestic manufacture with extended timelines for novel progestin formulations. São Paulo and Rio de Janeiro concentrate private healthcare provider channels where quarterly administration ensures proper monitoring and adherence.
Hormonal Contraception Market Competitive Landscape
Research-intensive multinationals and established pharmaceutical conglomerates split the market between next-generation delivery innovation and manufacturing scale efficiency. The competitive structure tilts toward consolidation at the formulation level while API supply fragments across specialized chemical manufacturers. Three archetypes dominate: integrated pharma conglomerates with vertical control over steroid synthesis, specialist women's health companies with concentrated provider channel relationships, and generic manufacturers competing on cost in oral pill segments. Capacity expansion in Indian API production and strategic partnerships for biodegradable polymer sourcing represent the dominant competitive moves.
Among research-intensive multinationals, Bayer AG and Pfizer Inc. exemplify the integrated archetype with sustained manufacturing presence across European and Asian facilities. Merck & Co., Inc. anchors the specialist tier through established implant technology and healthcare provider channel control. These three companies represent the competitive spectrum from API synthesis through finished formulation distribution.
| Leading Market Players |
|---|
| Merck & Co., Inc. |
| Bayer AG |
| Pfizer Inc. |
| Teva Pharmaceutical Industries |
| Johnson & Johnson |
| AbbVie Inc. |
| Janssen Pharmaceuticals Inc. |
| Lupin Pharmaceuticals Inc. |
| Agile Therapeutics |
| Others |
Supply & Pricing Matrix
The Rotterdam-Antwerp pharmaceutical freight corridor carries steroid precursor shipments from Indian API manufacturers to European formulation facilities, with freight cost volatility feeding directly into margin compression for oral pill generics and premium positioning for biodegradable implant systems.
Pricing Analysis
FDA 21 CFR 310.502 prescription status requirements dictate the pricing tier structure across the United States market, separating clinic-administered implant formats from self-administered oral and transdermal alternatives. Three-tier pricing structure across premium biodegradable systems, standard polymer implants, and economy oral generics tracks certification complexity and provider involvement intensity. Cost compression in oral pill segments is intensifying because generic substitution has eroded brand premiums, while adolescent demand for menstrual regulation sustains price resilience in provider-supervised channels. Public health procurement programs exhibit highest price sensitivity, whereas private clinic networks serving urban millennials demonstrate lowest sensitivity due to convenience-premium acceptance.
Supply Chain Analysis
Export certification requirements under India's DGFT and BIS standards restrict API flow velocity to regulated markets, creating documentation bottlenecks that extend lead times for European and North American formulation sites. Manufacturing concentrates in India for steroid synthesis and micronization, Germany for polymer-based implant engineering, and the United States for finished formulation packaging. Progestin API production draws from pharmaceutical-grade diosgenin and soy sterol precursors, with polymer matrix materials for implants sourced from specialized chemical suppliers. Single-source vulnerability concentrates in micronization process engineering talent clustered around Hyderabad. Distribution runs through CDSCO-regulated wholesale channels in India, EMA-authorized depot systems in Europe, and state-level pharmacy networks across the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized steroid chemistry expertise and micronization process engineering talent anchor competitive differentiation, with concentration in limited geographic clusters creating acquisition premiums and partnership bottlenecks for expansion-minded players.
For Market Incumbents: Build regulatory data moats through expanded FDA 21 CFR 310.502 submission experience and EMA environmental risk assessment documentation capabilities. Deepen backward integration into steroid precursor synthesis to offset input cost volatility from pharmaceutical-grade solvent markets. Channel control through women's health clinic networks defends against telehealth subscription displacement in oral pill segments. For New Entrants and Emerging Players: Build out biodegradable implant manufacturing partnerships with Nordic pilot clinic networks before EMA authorization timelines harden competitive barriers. Sub-Saharan Africa's underpenetrated clinic infrastructure offers the most penetrable geography for injectable and implantable volume expansion. Direct procurement relationships with national health systems bypass established distributor markups. For Investors and Strategic Acquirers: Carve-out targets emerge from pharmaceutical conglomerates divesting women's health portfolios amid strategic repositioning toward oncology and immunology. Five-to-ten year viability favors specialists with captive API supply and established provider channel relationships over pure-play formulation marketers. Watch FDA premarket review timeline extensions for novel progestin formulations as inflection indicator for competitive entry windows.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Implant Material Development | Nordic clinic pilots validate tunable erosion kinetics for personalized hormone release profiles. |
| CDSCO-BIS Dual Compliance Investment | Parallel documentation capabilities unlock Indian API export access to regulated markets. |
| Telehealth Subscription Platform Launch | Flat-fee bundling of consultation, prescription, and delivery displaces traditional pharmacy fulfillment. |
| EMA Centralized Procedure Harmonization | Streamlined multi-country authorization reduces regulatory fragmentation for European market entry. |
| Sub-Saharan African Clinic Infrastructure Partnership | National health system procurement channels anchor volume for injectable and implantable formats. |
Research Methodology
Desk research of FDA 21 CFR 310.502 filings, EMA centralized procedure documentation, CDSCO manufacturing licenses, and clinical trial registries preceded structured interviews with regulatory affairs leads, women's health clinic administrators, pharmaceutical procurement managers, and API manufacturing executives. Bottom-up volume estimates from national prescription databases and top-down value triangulation from customs trade data were cross-validated against formulary coverage determinations and payer reimbursement schedules.
Fixed assumptions held regulatory pathway timelines, insurer coverage mandate expansion, and adolescent demand growth rates constant across the projection horizon, while steroid precursor input costs and environmental risk assessment requirements were varied parametrically. Segmentation modeling spanned product type, delivery mode, end user demographic, and application indication. CAGRs were derived from logistic diffusion curves fitted to historical adoption patterns and adjusted for channel shift dynamics.
Stress conditions across FDA premarket review duration, EMA environmental documentation expansion, and Indian API export certification delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and scenario bounds. Material shifts in state-level pharmacy access legislation or insurer coverage mandate rescission would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Reproductive Health
Assisted Reproductive Technology (ART) Market
Reproductive Health
IVF Services Market
Reproductive Health
US Birth Centers Market
Reproductive Health
Gamete Preservation Market
Reproductive Health
Fertility Treatments Market
Reproductive Health
In Vitro Fertilization (IVF) Market
Reproductive Health
Europe in Vitro Fertilization (IVF) Market
Reproductive Health
Smart Fertility Tracker Market
Reproductive Health
Fertility Services Market
Reproductive Health
Ovum Egg Banking Market
Reproductive Health
Germany in Vitro Fertilization (IVF) Market
Reproductive Health
Global Gynecology Drugs Market
Reproductive Health
UK in Vitro Fertilization (IVF) Market
Reproductive Health
Cryopreservation for in-Vitro Fertilization (IVF) Market
Reproductive Health
Intrauterine Insemination (IUI) Treatment Market
Reproductive Health
Pregnancy Care Products Market