
 Vaginal Exam Specula Market | 2026-2036
Vaginal Exam Specula Market Size, Share, and Industry Trends Forecast 2026-2036
Vaginal Exam Specula Market Analytics
Hospital purchasing is shifting toward disposable vaginal specula as infection prevention protocols harden across developed health systems. CooperSurgical Inc specializes in obstetric-gynecologic instrument portfolios that anchor its position in North American hospital supply chains. Medline Industries Inc leverages distribution scale to control channel access for mid-tier clinics seeking polymer-based disposables. Becton Dickinson and Co. differentiates through R&D intensity in sterile single-use designs that compete on compliance rather than price.
Vaginal exam specula are hinged medical instruments, typically manufactured from medical-grade stainless steel or polymer resins such as polystyrene or polypropylene, designed to dilate the vaginal canal for visual examination of the cervix and vaginal walls. The instrument consists of two blades, a handle, and a locking mechanism that maintains aperture width during procedures. Disposable polymer specula now lead volume in hospital settings where cross-contamination protocols have eliminated reusable metal reprocessing in many wards, while metal instruments sustain margin pools in gynecologic surgical suites where durability and heat sterilization compatibility remain essential. Medium and large sizes dominate procurement as standard adult examination fixtures, though small specula represent the fastest-growing dimension driven by pediatric and adolescent gynecology service expansion.
FDA 510(k) clearance requirements and EMA Medical Device Regulation (MDR) conformity assessments shape product entry barriers and ongoing compliance costs for manufacturers serving Western markets. The EPA regulates polymer resin emissions from injection molding facilities producing plastic specula, while ISO 13485 quality management standards govern production documentation for international shipment. Stakeholders must monitor evolving single-use plastic bans in European jurisdictions and assess bio-based polymer substitutions that preserve sterility performance without triggering environmental compliance penalties.
Market Dynamics
Hospital infection control protocols are eliminating reusable metal specula from routine examination wards, forcing procurement departments to rebuild supply chains around single-use polymer alternatives and their associated sterilization documentation burdens.
Growth Catalysts
- FDA 510(k) Clearance Pathway:Streamlined premarket notification for polymer specula variants accelerates product line extensions, allowing manufacturers to capture ward-level conversions faster than full PMA devices.
- Ambulatory Surgical Center Expansion:United States outpatient facility construction creates dedicated procurement channels for disposable instrument bundles, displacing traditional hospital central supply models.
- Heat-Sterilization Incompatibility:Polymer resin formulations that withstand gamma irradiation but degrade in autoclaves lock metal specula into surgical suites while pushing examination-grade volume toward single-use alternatives.
Market Restraints
- Medical-Grade Polymer Feedstock Concentration:Polystyrene and polypropylene resin supply for healthcare applications clusters among Gulf Coast petrochemical producers, exposing molders to hurricane-season disruption and force majeure pricing.
- EMA MDR Technical Documentation Burden:Extended conformity assessment timelines for Class I reusable instruments delay metal specula recertification, freezing product portfolios and compressing R&D budgets.
- Single-Use Plastic Bans:France, Italy, and Belgium have enacted healthcare-specific disposable restrictions that threaten polymer specula shelf access without viable bio-based substitutions at equivalent sterility assurance levels.
Strategic Opportunities
- Indian Maternal Health Screening Programs:National Rural Health Mission expansion into village-level gynecologic services creates demand for ultra-low-cost disposable specula without established supplier relationships.
- Integrated Delivery Network Purchasing Consortia:United States hospital system aggregation into multi-state buying groups favors distributors with logistics scale over manufacturers with direct sales forces.
- Bio-Based Polymer Certification:ISO 17088-compliant compostable resins that maintain tensile strength and sterilization compatibility offer first-mover positioning ahead of EU Green Deal packaging mandates.
Industry Challenges
- Injection Molding Tooling Lead Times:Medical-grade cavity production for specula blade geometries requires 16-20 week delivery windows from specialized German and Japanese toolmakers, constraining demand surge response.
- Gamma Sterilization Facility Capacity:Contract irradiation providers face cobalt-60 source replenishment delays and facility backlogs, extending finished goods quarantine periods and working capital cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vaginal Exam Specula Market |
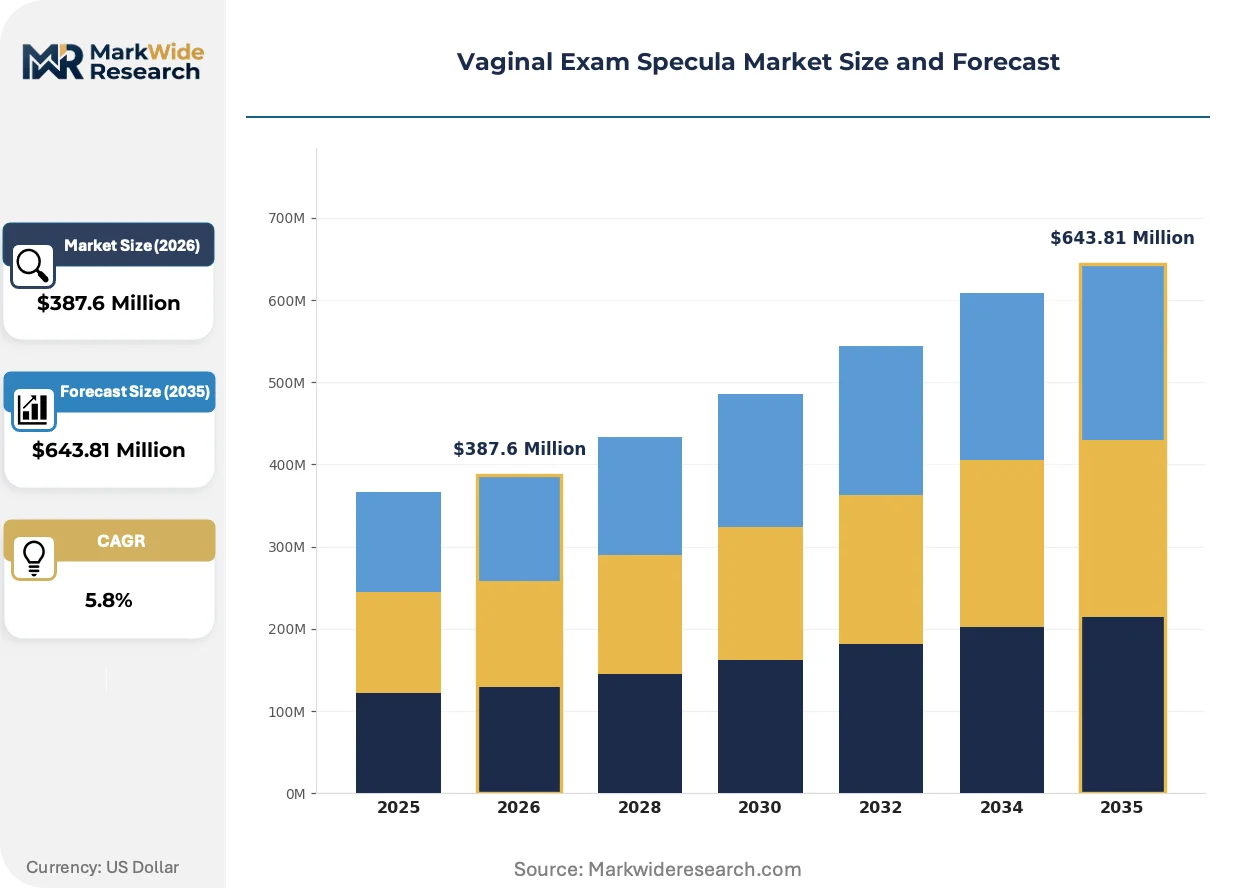
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $643.81 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable, Reusable, Plastic, Metal End User: Hospitals, Clinics, Gynecologists, Maternity Centers Size: Small, Medium, Large, Extra Large Application: Routine Check-ups, Diagnostics, Educational Purposes, Research |
| Companies Covered | Teleflex Inc., Integra Lifesciences Holdings Corp., CooperSurgical Inc, STERIS Plc, B. Braun SE, Becton Dickinson and Co., MedGyn Products Inc., Vernacare, Medline Industries Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vaginal Exam Specula Market Evolving Landscape
Speculum design is converging with disposable instrument ecosystem integration and automated sterilization tracking, compressing the traditional boundary between product manufacturing and hospital supply chain software.
LED-integrated polymer specula with built-in illumination circuits are rewriting the competitive landscape for examination room equipment. Gynecology clinics in Germany and the United States are adopting these devices to eliminate external light source positioning and reduce nurse staffing per procedure. The technology is compressing capital equipment budgets into disposable per-procedure costs while raising the barrier for metal instrument suppliers without electronics integration capabilities.
EMA Medical Device Regulation (MDR) economic operator requirements are restructuring European distribution networks. Manufacturers must now maintain authorized representatives with liability coverage in each member state, forcing smaller molders to abandon direct export and consolidate through regional distributors. German hospital purchasing departments are responding by consolidating supplier panels to reduce due diligence burden, favoring incumbents with established MDR technical files.
Direct-to-clinic e-commerce platforms are fragmenting traditional medical distributor relationships. United States independent gynecology practices now procure polymer specula through Amazon Business and specialized healthcare marketplaces, bypassing the local dealer networks that previously controlled territory access. This channel shift is most visible in Texas and Florida metropolitan areas where practice management software integrates punchout catalog connectivity, eroding distributor margin pools and forcing manufacturers to manage pricing parity across conflicting channels.
Vaginal Exam Specula Market Segmentation
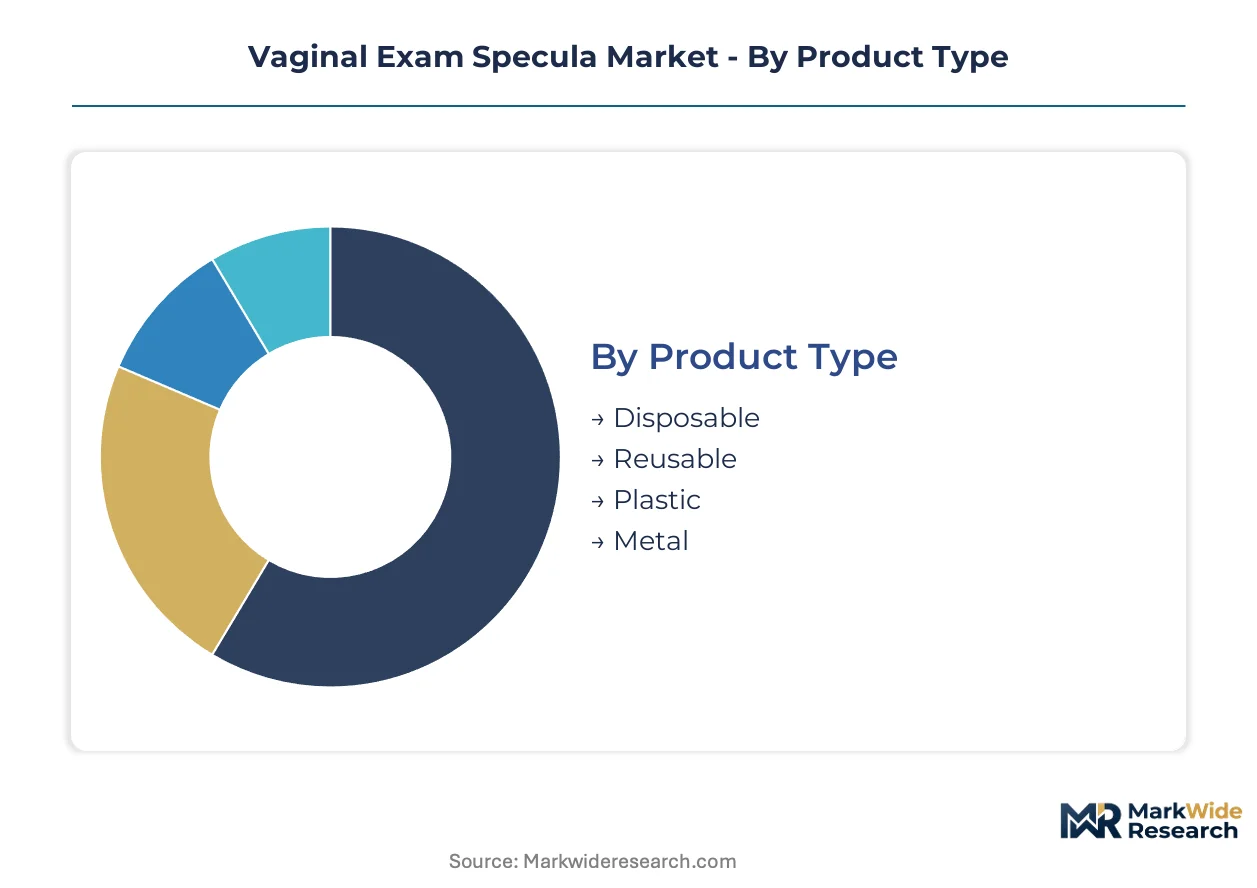
Segmentation in the vaginal exam specula market reveals how procurement decisions bifurcate between infection control mandates and capital preservation strategies. Material composition and end-use setting determine pricing architecture, while sizing configurations reflect patient demographic shifts in clinical practice.
Product Type:
Standardization dominates disposable polymer lines, yet reusable metal instruments retain customization through surgical-grade finishing and handle ergonomics.
- Disposable:Single-use polymer specula manufactured from medical-grade polystyrene or polypropylene eliminate reprocessing documentation burdens. Hospital infection control protocols in the United States and Germany now mandate these for routine examination wards, displacing metal alternatives through gamma sterilization compatibility rather than unit cost.
- Reusable:Medical-grade stainless steel instruments withstand autoclave cycles and sustain margin pools in gynecologic surgical suites. Heat sterilization compatibility locks these into operating theater procurement, though extended EMA MDR conformity timelines freeze product portfolio refresh.
- Plastic:Injection-molded polymer variants prioritize disposability with lower per-unit weight and reduced shipping costs. Gulf Coast petrochemical supply concentration exposes molders to force majeure disruption during hurricane season.
- Metal:Surgical stainless steel and chrome-plated brass instruments serve specialty practices requiring instrument longevity. Durability specifications align with ISO 13485 quality documentation for international shipment.
Leading the category by volume: Disposable. Expanding most quickly: Plastic variants for ambulatory surgical center bundles.
End User:
Procurement authority concentrates in consolidated hospital systems, while fragmented clinic networks create channel complexity for distributor margin capture.
- Hospitals:Central supply departments negotiate multi-year contracts for disposable specula bundles under infection prevention protocols. Integrated Delivery Network purchasing consortia in Texas and Florida favor distributors with logistics scale over manufacturer direct sales.
- Clinics:Independent gynecology practices procure through Amazon Business and specialized healthcare marketplaces, bypassing traditional dealer networks. Practice management software punchout catalog connectivity erodes distributor territory control.
- Gynecologists:Specialty practitioners balance patient comfort preferences against sterilization throughput requirements. LED-integrated polymer designs command premium positioning in metropolitan German and United States markets.
- Maternity Centers:Obstetric-focused facilities prioritize rapid instrument turnover for high-volume maternal health screening. Indian National Rural Health Mission village-level expansion creates demand for ultra-low-cost disposable configurations.
Capturing the largest procurement volume: Hospitals. Gaining share fastest: Clinics through direct-to-practice e-commerce channels.
Size:
Dimensional standardization yields to patient-specific fitting requirements across pediatric, adult, and bariatric service lines.
- Small:Pediatric and adolescent gynecology applications drive demand acceleration as specialty service lines expand in academic medical centers. Patient comfort specifications override cost minimization in these segments.
- Medium:Standard adult examination fixture across routine check-up protocols. Procurement volume concentrates in hospital ward replacement cycles under FDA 510(k) cleared polymer designs.
- Large:Adult patient populations with anatomical variation requirements. Gynecologic surgical suites specify these for operative procedures requiring extended visualization.
- Extra Large:Bariatric patient accommodation and specialized diagnostic applications. Niche positioning limits supplier competition and sustains margin premiums.
Dominating procurement volume: Medium. Climbing the fastest: Small specula for pediatric service expansion.
Application:
Clinical utility separates high-frequency screening workflows from capital-intensive diagnostic and research instrumentation.
- Routine Check-ups:High-volume cervical cancer screening and preventive care visits consume disposable polymer specula at accelerated replacement rates. Maternal health programs in India and China drive bulk procurement without established supplier relationships.
- Diagnostics:Colposcopy and biopsy procedures require specula with superior light transmission and tissue visualization. LED-integrated polymer designs from German manufacturers command positioning in premium diagnostic settings.
- Educational Purposes:Medical school and nursing program training kits prioritize cost minimization over clinical performance specifications. Bulk purchasing through academic supply contracts favors standardized disposable configurations.
- Research:Clinical trial and device validation studies require traceable sterilization documentation and lot consistency. ISO 13485-certified production governs acceptable supplier qualification.
Generating highest shipment volume: Routine Check-ups. Steepest expansion trajectory: Diagnostics through LED-integrated instrument adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polymer resin production clusters along the Gulf Coast of the United States, while consumption concentrates in hospital systems across Germany, China, and India where maternal health screening expansion drives procurement volume.
United States
Ambulatory surgical center construction in Texas and Florida creates dedicated procurement channels for disposable instrument bundles. FDA 510(k) clearance pathways streamline premarket notification for polymer specula variants. Houston petrochemical corridors supply medical-grade polystyrene resin to domestic molders facing hurricane-season disruption risks.
Germany
EMA MDR conformity assessments reshape distribution networks as manufacturers maintain authorized representatives with liability coverage in each member state. LED-integrated polymer specula command premium positioning in metropolitan clinic networks. Baden-Württemberg industrial clusters host specialized injection molding toolmakers serving medical device producers.
China
National maternal health screening programs drive bulk procurement of ultra-low-cost disposable configurations without established supplier relationships. NMPA medical device registration governs product entry for domestic and imported specula. Yangtze River Delta manufacturing hubs concentrate polymer injection capacity for export-oriented producers.
India
National Rural Health Mission expansion into village-level gynecologic services creates demand for cost-optimized disposable specula. CDSCO medical device rules establish registration requirements for imported and domestic instruments. Maharashtra pharmaceutical and medical device manufacturing corridors attract contract molders serving public health procurement tenders.
France
Healthcare-specific single-use plastic restrictions threaten polymer specula shelf access without viable bio-based substitutions. ANSM market surveillance enforces post-market vigilance for Class I reusable instruments. Île-de-France hospital purchasing departments consolidate supplier panels to reduce MDR due diligence burden.
Vaginal Exam Specula Market Competitive Landscape
Top-tier vendors anchor hospital supply chains and integrated delivery networks, while mid-scale distributors and regional molders compete on logistics scale and cost minimization for clinic procurement. The market structure favors incumbents with established regulatory technical files over new entrants facing extended conformity timelines. Two strategic archetypes dominate: sterile single-use specialists competing on compliance documentation, and diversified medical device conglomerates leveraging cross-portfolio bundling. Competitive moves concentrate on M&A to capture ambulatory surgical center channels and backward integration into polymer resin sourcing to hedge feedstock volatility.
Within the premium sterile disposable tier, CooperSurgical Inc and Becton Dickinson and Co. exemplify archetypes anchored in North American hospital supply chains, while Medline Industries Inc occupies a position representing distribution-scale channel control for mid-tier clinic networks. These three entities collectively illustrate how compliance intensity, logistics scale, and portfolio breadth define competitive positioning across divergent procurement authority concentrations.
| Leading Market Players |
|---|
| Teleflex Inc. |
| Integra Lifesciences Holdings Corp. |
| CooperSurgical Inc |
| STERIS Plc |
| B. Braun SE |
| Becton Dickinson and Co. |
| MedGyn Products Inc. |
| Vernacare |
| Medline Industries Inc. |
| Others |
Value Network & Pricing Analysis
Integrated Delivery Network purchasing consortia in the United States concentrate procurement authority into multi-state buying groups, forcing three-tier pricing structure across premium, standard, and economy levels where gamma-sterilized polymer specula command position against unbranded alternatives.
Pricing Analysis
Margin tightening in standard-tier disposable specula reflects Gulf Coast petrochemical feedstock volatility and force majeure pricing during hurricane season. Price differentiation hinges on FDA 510(k) clearance tier and gamma sterilization certification grade, with hospital systems least sensitive to unit cost and independent clinics most responsive to per-procedure economics. Cost-down pressure on economy-tier imports accelerates because CDSCO-registered Indian manufacturers compete without established brand premiums.
Supply Chain Analysis
Returns and refurbishment flows for reusable metal specula concentrate in German surgical instrument reprocessing centers, creating reverse logistics complexity that polymer disposables eliminate entirely. Manufacturing draws from United States Gulf Coast polystyrene resin, German precision tooling, and Chinese injection molding capacity. Single-source vulnerability clusters around cobalt-60 gamma sterilization facilities facing source replenishment delays. Distribution runs through regional medical distributors losing share to Amazon Business and healthcare marketplace direct channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
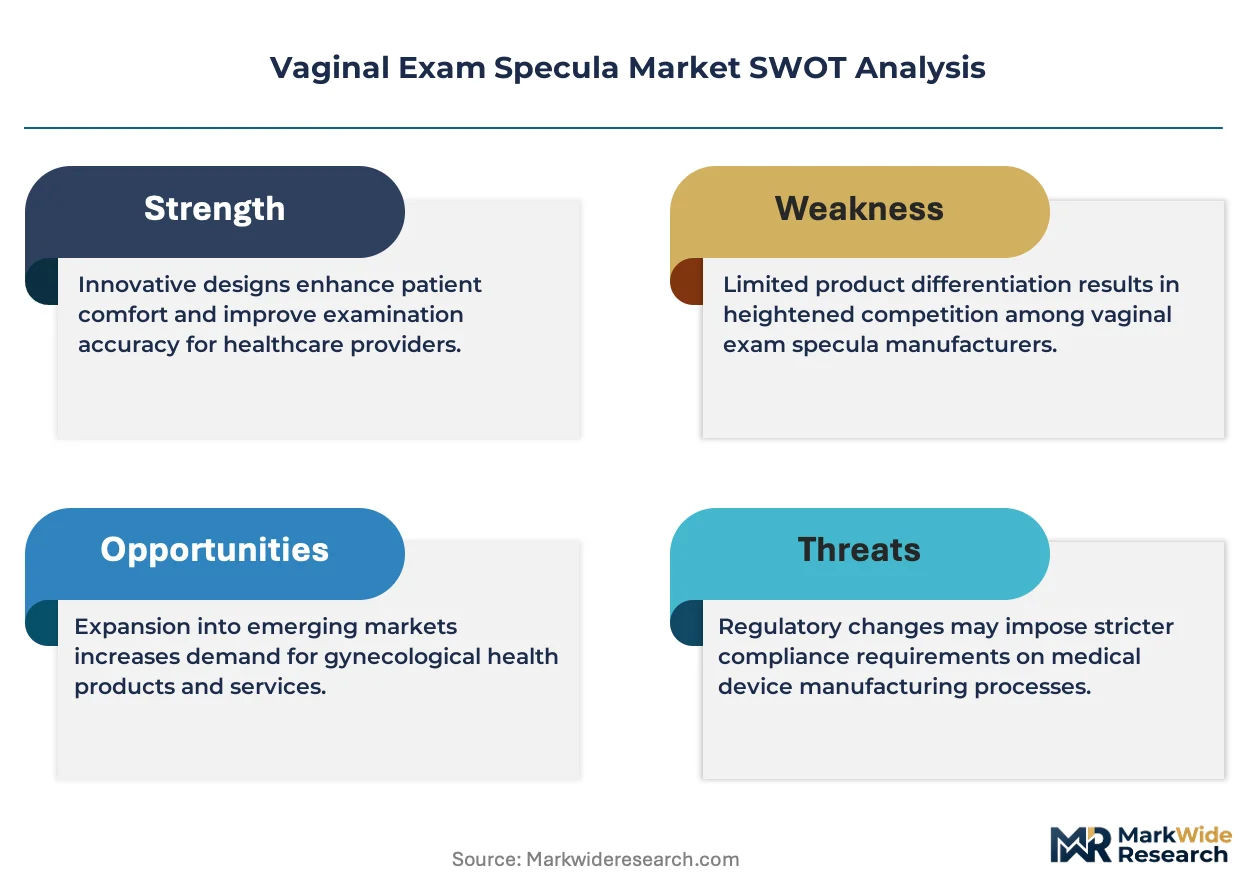
The vaginal exam specula market functions as a cost-of-compliance story where EMA MDR technical documentation burdens erect barrier-to-entry moats favoring incumbents with established conformity assessment files.
For Market Incumbents: Lock in hospital system partnerships through multi-year disposable specula bundles that embed sterilization documentation services. Deepen backward integration into medical-grade polymer resin sourcing to hedge Gulf Coast hurricane exposure. Capture ambulatory surgical center construction in Texas and Florida before distributor relationships solidify. For New Entrants and Emerging Players: FDA 510(k) clearance pathway streamlines in the United States opens a window for polymer specula variants targeting independent gynecology practices through direct-to-clinic e-commerce. India's National Rural Health Mission village-level expansion presents the most penetrable geography for ultra-low-cost disposable configurations. Pursue GPO contracts manager relationships rather than hospital central supply direct sales. For Investors and Strategic Acquirers: The window for entry favors sterile single-use specialists with existing gamma sterilization facility relationships and ISO 13485-certified production documentation. Mid-scale regional molders in Maharashtra and Yangtze River Delta manufacturing hubs represent acquisition targets with cost-optimized capacity. Monitor EMA MDR authorized representative liability coverage consolidation as inflection signal for European distribution network restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Accelerates polymer specula line extensions for ward-level conversions faster than PMA devices. |
| CE Marking Pathway | MDR conformity assessments freeze metal specula portfolios, favoring sterile disposable specialists. |
| Hospital System Partnership | Integrated Delivery Network purchasing consortia favor distributors with logistics scale over manufacturer direct sales. |
| Software Companion Development | Practice management software punchout catalog connectivity erodes traditional distributor territory control. |
| Reimbursement Strategy | Maternal health screening program eligibility determines bulk procurement access in India and China. |
Research Methodology
Multi-period observation of hospital infection control protocol adoptions and ambulatory surgical center construction permits anchored the trend analysis, supplemented by interviews with hospital purchasing committee members, GPO contracts managers, biomedical engineers, and regulatory affairs leads at polymer specula manufacturers. Secondary validation drew from FDA 510(k) clearance databases, EMA MDR technical documentation filings, hospital procurement databases, and customs trade records. Bottom-up demand modeling triangulated against top-down market sizing across the analysis window.
Segment-weighting applied product type, end user procurement authority concentration, sizing configuration, and application intensity dimensions throughout the forecast period. CAGRs derived from procedure volume elasticity to maternal health screening program expansion and replacement cycle dynamics. Industry-specific inputs included gamma sterilization facility capacity utilization and injection molding tooling lead time trajectories from German and Japanese specialized suppliers.
Caveats apply where EMA MDR conformity assessment timeline extensions or single-use plastic ban enforcement in France and Italy could materially shift the outlook. Practitioners should monitor cobalt-60 source replenishment schedules and bio-based polymer ISO 17088 certification progress for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Reproductive Health
UK in Vitro Fertilization (IVF) Market
Reproductive Health
Global Male Infertility Market
Reproductive Health
Global Gynecology Drugs Market
Reproductive Health
Cervical Dysplasia Treatment Market
Reproductive Health
Ovum Egg Banking Market
Reproductive Health
Fertility Treatments Market
Reproductive Health
Global Cervical Dysplasia Market
Reproductive Health
In Vitro Fertilization (IVF) Market
Reproductive Health
Egg Donation Market
Reproductive Health
Surrogacy Market
Reproductive Health
US Birth Centers Market
Reproductive Health
Global Genital Herpes Treatment Market
Reproductive Health
US Contraceptive Market
Reproductive Health
Pregnancy Care Products Market
Reproductive Health
Cryopreservation for in-Vitro Fertilization (IVF) Market
Reproductive Health
Europe in Vitro Fertilization (IVF) Market