
 Europe in Vitro Fertilization (IVF) Market | 2026-2036
Europe in Vitro Fertilization (IVF) Market Size, Share, and Industry Trends Forecast 2026-2036
Europe in Vitro Fertilization (IVF) Market Analytics
Aftermarket service revenue for embryology systems is tilting toward long-term maintenance contracts and remote monitoring platforms. Vitrolife AB leverages its cryopreservation portfolio to sustain recurring instrument service income across Nordic clinics. Cooper Surgical anchors its position through specialized media formulations that dominate European fertility laboratory supply chains. Merck KGaA differentiates via integrated hormone-to-culture-media workflows that reduce protocol variability for end users.
In vitro fertilization encompasses laboratory-based fertilization of oocytes with sperm outside the body, requiring controlled incubation at 37 degrees Celsius with 5-6% carbon dioxide and humidity exceeding 95% to maintain embryo viability. The procedure serves as the cornerstone of assisted reproductive technology for treating tubal factor infertility, severe male factor cases, and unexplained fertility failures. ICSI technology commands premium positioning due to its indispensability for severe male infertility cases where conventional fertilization fails. Fertility clinics represent the dominant end-user channel, though hospital-affiliated centers are gaining structural ground where public reimbursement frameworks apply. Preimplantation genetic testing is emerging as the fastest-expanding technology segment as aneuploidy screening becomes standard in premium treatment protocols.
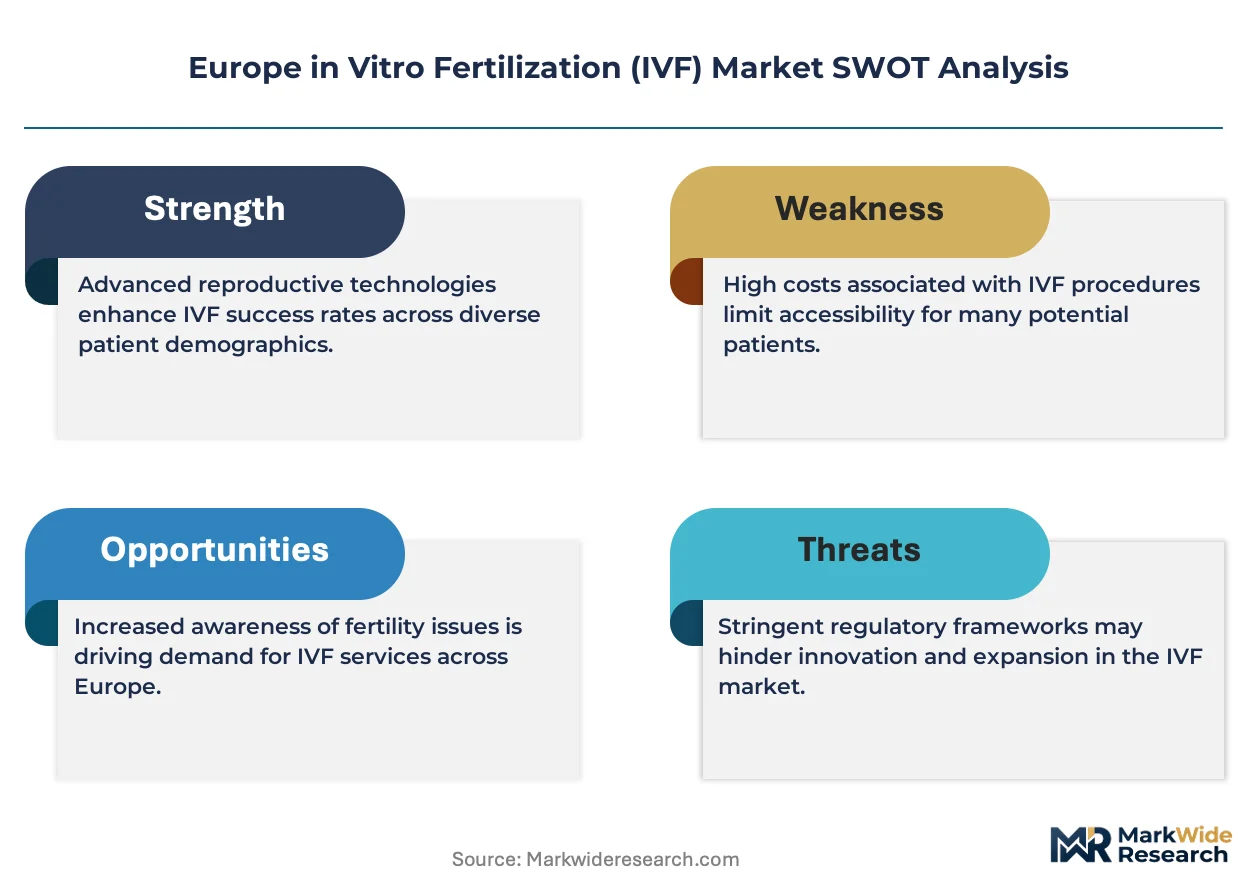
EMA oversight of culture media as medical devices, combined with the EU MDR's stricter clinical evidence requirements for embryo handling equipment, is elevating compliance costs for manufacturers seeking CE marking renewal. REACH chemical safety protocols and the F-Gas Regulation constrain refrigerant choices for cryopreservation systems, pushing equipment makers toward alternative cooling architectures. Stakeholders must monitor how national reimbursement decisions in France, Italy, and the Netherlands reshape patient access and clinic investment cycles.
Market Dynamics
The EU MDR's stricter clinical evidence requirements for embryo handling equipment is compressing manufacturer margins while simultaneously elevating barriers to CE marking renewal across European fertility laboratory supply chains.
Growth Catalysts
- Preimplantation genetic testing:Aneuploidy screening protocols are becoming standard in premium IVF treatment workflows, expanding laboratory service menus and per-cycle revenue capture.
- Public reimbursement frameworks:Hospital-affiliated IVF centers in France, Italy, and the Netherlands are gaining structural ground where national coverage decisions expand patient access pools.
- ICSI technology:Intracytoplasmic sperm injection maintains indispensable positioning for severe male infertility cases, securing premium pricing tiers within fertilization procedure portfolios.
Market Restraints
- REACH chemical safety protocols:Embryo culture media formulations face escalating compliance documentation burdens and restricted substance candidate screening timelines.
- F-Gas Regulation constraints:Cryopreservation equipment manufacturers must abandon conventional refrigerant architectures, forcing costly redesign cycles for cooling systems.
- Specialized embryology talent scarcity:Nordic and German fertility clinics report extended recruitment cycles for certified laboratory personnel with advanced micromanipulation competencies.
Strategic Opportunities
- Eastern European clinic networks:Poland, Czech Republic, and Hungary fertility centers remain underpenetrated by integrated hormone-to-media workflow suppliers.
- Remote monitoring platforms:Long-term embryology system maintenance contracts are displacing transactional service calls, generating recurring revenue streams for equipment vendors.
- EU Green Deal alignment:Alternative cooling architectures for cryopreservation systems qualify for sustainability-linked procurement preferences in publicly funded hospital networks.
Industry Challenges
- CE marking renewal timelines:EMA oversight of culture media as medical devices extends certification cycles, freezing product portfolio refreshes for 18-24 month windows.
- Legacy incubator integration:New remote monitoring sensors face protocol incompatibility with installed base equipment across Spanish and Italian clinic chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe in Vitro Fertilization (IVF) Market |
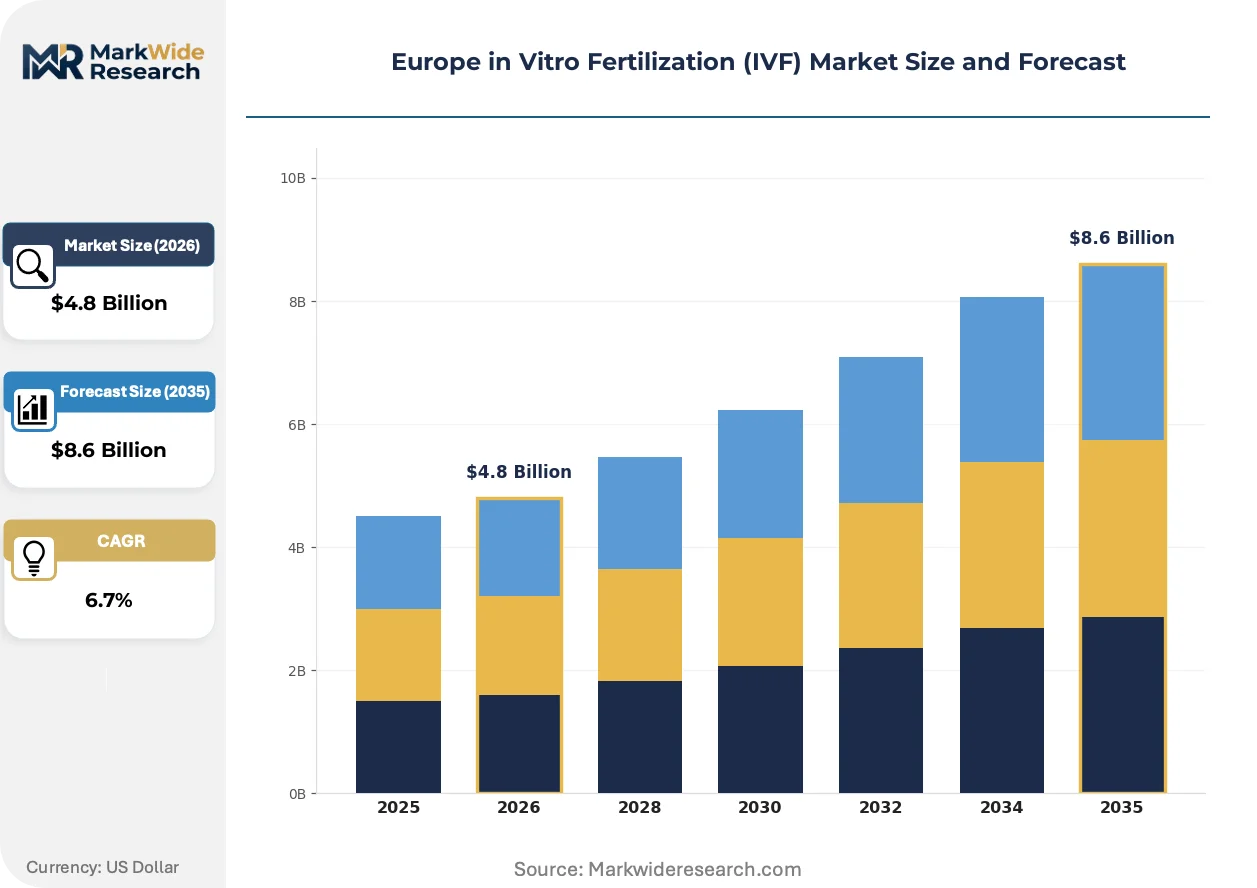
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hormones, Cryopreservation Equipment, IVF Culture Media, Embryology Systems Technology: ICSI, IVF, Preimplantation Genetic Testing, Oocyte Preservation End User: Fertility Clinics, Hospitals, Research Laboratories, Academic Institutions Application: Male Infertility, Female Infertility, Genetic Disorders, Fertility Preservation |
| Companies Covered | Vitrolife AB, Cooper Surgical, Merck KGaA, Cook Medical, Irvine Scientific, Thermo Fisher Scientific, EMD Serono, IVI-RMA Global, Ferring B.V., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe in Vitro Fertilization (IVF) Market Evolving Landscape
Time-lapse embryo imaging systems are collapsing conventional morphological assessment workflows, while regulatory pressure on refrigerant chemistry and procurement centralization reshape competitive positioning across European fertility markets.
Time-lapse incubators equipped with continuous embryo monitoring cameras are collapsing the interval between fertilization and transfer decision points. Private fertility chains in Spain and the United Kingdom are adopting these systems at accelerated replacement cycles. The technology is collapsing reliance on static daily observations, compressing laboratory staffing models and standardizing grading protocols across multi-site clinic networks.
The EU MDR's intensified clinical evidence requirements for embryo handling equipment are extending CE marking renewal timelines. Manufacturers must submit expanded biocompatibility and performance validation data for cryopreservation devices and culture media containment systems. German and French notified bodies are processing submissions at reduced throughput, forcing suppliers to maintain dual inventory streams during transition periods.
Aftermarket service contracts are unbundling from equipment sale packages across Nordic fertility networks. Private clinic buyers in Denmark and Sweden now specify multi-year remote monitoring and predictive maintenance agreements as separate procurement line items. This shift is most visible in Stockholm and Copenhagen metropolitan clusters where laboratory directors prioritize uptime guarantees over capital expenditure minimization.
Europe in Vitro Fertilization (IVF) Market Segmentation
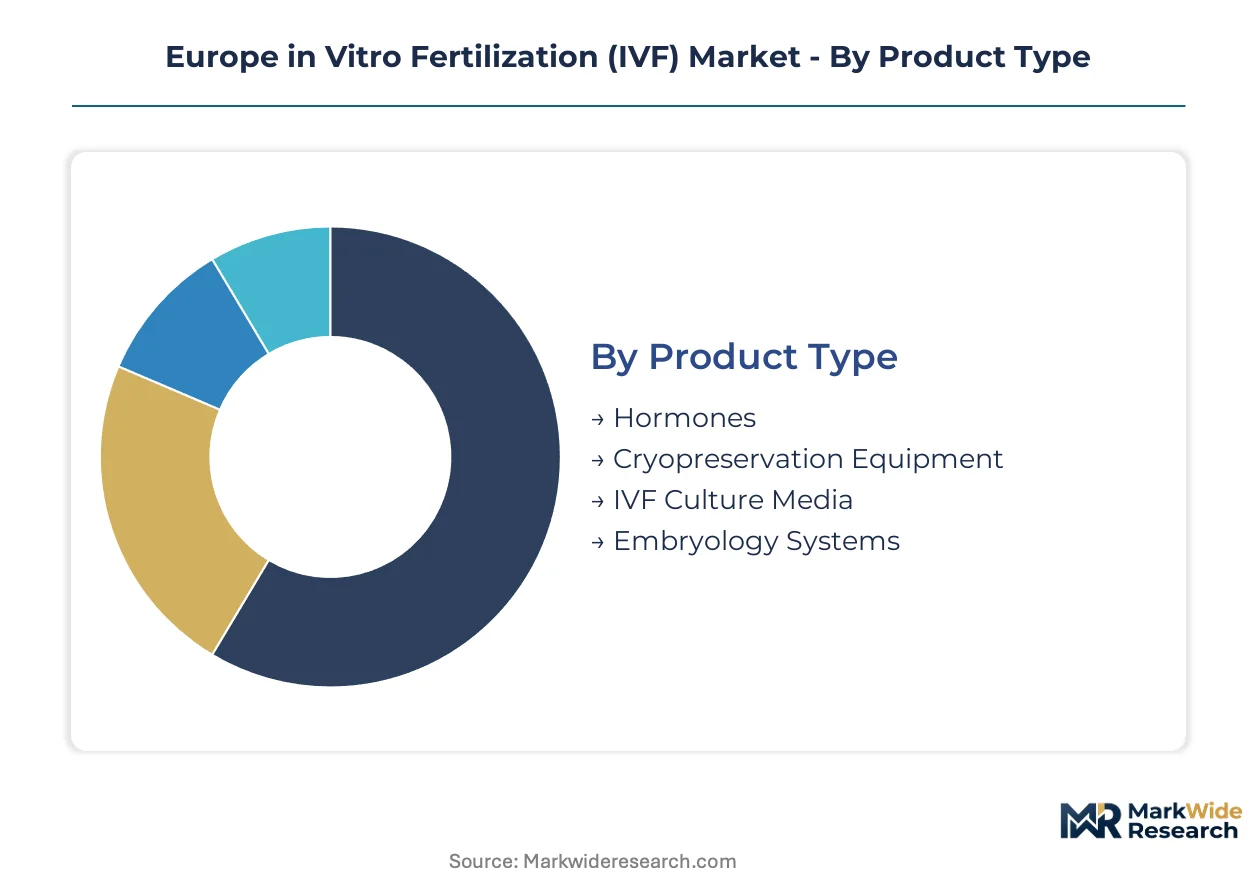
IVF market segmentation reveals how clinical workflows, regulatory pathways, and reimbursement structures fragment procurement decisions across European fertility networks. Each dimension carries distinct margin profiles and compliance burdens that reshape vendor prioritization.
Product Type:
Mature consumable categories dominate transaction volumes while emerging equipment segments capture capital investment cycles.
- Hormones:Gonadotropin and GnRH analog formulations drive protocol standardization across multi-site clinic chains. German and French fertility centers concentrate procurement through centralized pharmacy tenders, compressing unit economics for non-integrated suppliers.
- Cryopreservation Equipment:Programmable freezers and liquid nitrogen storage systems face forced redesign under F-Gas Regulation constraints. Nordic clinic networks prioritize alternative cooling architectures that qualify for EU Green Deal procurement preferences in publicly funded hospital systems.
- IVF Culture Media:Protein-supplemented and chemically defined formulations fall under EMA medical device oversight with extended CE marking renewal timelines.
- Embryology Systems:Integrated incubator-microscope platforms command premium positioning through remote monitoring capabilities and predictive maintenance contracts.
Hormones retain volume leadership; cryopreservation equipment holds the steepest expansion curve as refrigerant transitions accelerate replacement demand.
Technology:
Application intensity varies sharply by infertility etiology, with severe male factor cases commanding premium intervention protocols.
- ICSI:Micromanipulation-based sperm injection maintains indispensable positioning where conventional fertilization fails. Spanish and Italian fertility clinics report ICSI utilization exceeding standard IVF in severe male factor caseloads, securing sustained pricing power for specialized pipette and micromanipulator suppliers.
- IVF:Conventional insemination protocols concentrate in public reimbursement frameworks where cost containment limits technology adoption.
- Preimplantation Genetic Testing:Aneuploidy screening is expanding most quickly across UK and Dutch premium treatment workflows. Private fertility chains in London and Amsterdam metropolitan clusters now bundle PGT-A with standard cycles, elevating laboratory service menus and per-patient revenue capture.
- Oocyte Preservation:Elective fertility preservation protocols are gaining structural ground among urban professional demographics in Scandinavian markets.
ICSI retains procedural dominance in male factor cases; preimplantation genetic testing gains share fastest as screening standardization spreads.
End User:
Channel configuration splits sharply between reimbursement-dependent hospital networks and privately capitalized clinic chains.
- Fertility Clinics:Private chains in Spain, the United Kingdom, and the Czech Republic drive technology adoption through centralized laboratory standardization. These buyers prioritize multi-year service contracts and remote monitoring platforms over capital expenditure minimization.
- Hospitals:Publicly affiliated centers in France, Italy, and the Netherlands expand patient access pools where national coverage decisions apply. Procurement centralization through regional health authorities constrains vendor selection to pre-qualified suppliers with established CE marking documentation.
- Research Laboratories:Academic medical centers in Germany and Belgium concentrate demand for experimental culture media formulations and time-lapse imaging systems.
- Academic Institutions:University-affiliated fertility units in Nordic markets prioritize training-compatible equipment configurations for embryology certification programs.
Fertility clinics retain volume leadership; hospitals hold the steepest expansion curve as reimbursement frameworks broaden access pools.
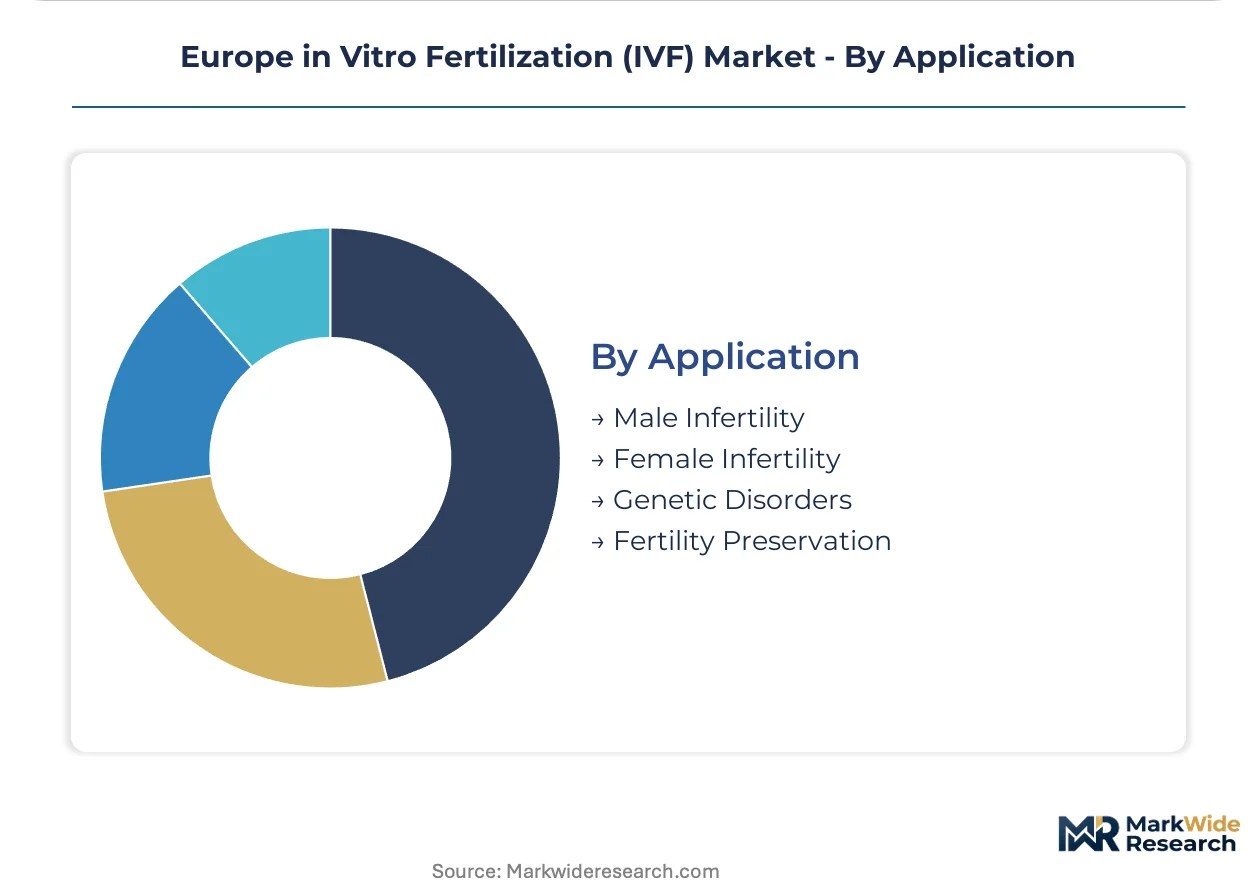
Application:
Clinical indication severity determines technology intensity and pricing tier access across European treatment protocols.
- Male Infertility:Severe oligospermia and azoospermia cases command ICSI-based intervention with surgical sperm retrieval. UK and Spanish clinics report extended treatment cycles for this indication, elevating cumulative per-patient revenue.
- Female Infertility:Tubal factor and endometriosis-related cases concentrate demand for conventional IVF protocols with shorter laboratory processing windows.
- Genetic Disorders:Monogenic disease screening drives preimplantation genetic testing adoption in Dutch and Belgian centers with specialized genetic counseling capabilities.
- Fertility Preservation:Oncofertility and elective oocyte freezing protocols are climbing the fastest in Stockholm, Copenhagen, and London metropolitan clusters.
Female infertility retains volume leadership; fertility preservation holds the steepest expansion curve as elective protocols normalize among urban demographics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German fertility clinics emphasize protocol standardization through centralized pharmacy procurement, while Spanish and UK chains prioritize technology refresh cycles and multi-site laboratory integration.
Germany
Hospital-affiliated IVF centers in Bavaria and North Rhine-Westphalia dominate patient volumes through statutory health insurance reimbursement frameworks. The EU MDR's extended CE marking timelines force German notified bodies to process embryo handling equipment submissions at reduced throughput. Berlin-Brandenburg laboratory networks now require dual inventory streams during regulatory transition periods.
United Kingdom
Private fertility chains in London metropolitan clusters bundle preimplantation genetic testing with standard treatment cycles to elevate per-patient revenue capture. The Human Fertilisation and Embryology Authority maintains stringent licensing requirements for embryology laboratory personnel. Manchester and Birmingham clinic networks are accelerating time-lapse incubator replacement cycles to compress staffing models.
Spain
Barcelona and Madrid fertility networks drive centralized laboratory standardization across multi-site private chains serving international patient flows. Spanish regulatory authorities align with EMA oversight timelines for culture media medical device classification. Valencia and Andalusia clinics report ICSI utilization exceeding conventional IVF in severe male factor caseloads.
France
Public reimbursement expansion through regional health authorities is broadening patient access pools in Île-de-France and Auvergne-Rhône-Alpes. ANSM oversight of assisted reproductive technology products complements EU MDR requirements for embryo culture media. Lyon and Marseille hospital-affiliated centers constrain vendor selection to pre-qualified suppliers with established CE marking documentation.
Netherlands
Amsterdam metropolitan fertility clinics standardize aneuploidy screening protocols across premium treatment workflows. Dutch healthcare procurement centralization through regional purchasing cooperatives limits supplier diversity in embryology consumables. Rotterdam and Utrecht laboratory directors prioritize multi-year remote monitoring contracts over capital expenditure minimization.
Europe in Vitro Fertilization (IVF) Market Competitive Landscape
Capability concentration sits with specialized embryology consumable formulators; scale advantage sits with diversified life science conglomerates. The vendor base separates into three functional tiers: integrated hormone-to-media workflow suppliers, standalone cryopreservation equipment specialists, and multi-product laboratory platform providers. Dominant competitive moves include strategic partnerships with fertility clinic chains for long-term service contracts and portfolio diversification into remote monitoring platforms.
Among Nordic-based specialists, Vitrolife AB exemplifies the cryopreservation-focused archetype through recurring instrument service income capture. Cooper Surgical and Merck KGaA represent contrasting integration strategies: the former anchors position through specialized media formulation dominance, while the latter occupies workflow integration territory spanning hormone stimulation through embryo culture protocols. These three entities collectively illustrate how European fertility laboratory supply chains fragment between point-solution depth and protocol-spanning breadth.
| Leading Market Players |
|---|
| Vitrolife AB |
| Cooper Surgical |
| Merck KGaA |
| Cook Medical |
| Irvine Scientific |
| Thermo Fisher Scientific |
| EMD Serono |
| IVI-RMA Global |
| Ferring B.V. |
| Others |
Value Network & Pricing Analysis
Stockholm's Nordic fertility laboratory cluster anchors cryopreservation equipment manufacturing, translating concentrated specialized production into sustained pricing power for alternative cooling architectures that satisfy EU Green Deal procurement preferences. This geographic concentration of embryology system assembly feeds downstream margin structures across German and French hospital-affiliated IVF centers.
Pricing Analysis
Long-term service contracts now dominate embryology system procurement, displacing spot transactional purchases across Nordic and UK clinic networks. Three-tier pricing structure across premium, standard, and economy levels differentiates by remote monitoring capability and predictive maintenance bundling. Cost compression in standard-tier consumables is intensifying because REACH documentation burdens escalate formulation compliance expenses. Public hospital networks in France and Italy exhibit highest price sensitivity, while private Spanish fertility chains prioritize uptime guarantees over capital expenditure minimization.
Supply Chain Analysis
Export control regimes on specialized refrigerants and cryogenic cooling technologies constrain equipment component flows into European manufacturing facilities. Germany, Sweden, and Denmark concentrate embryology system assembly, drawing from Japanese precision optics, US sensor components, and domestic stainless steel fabrication. Single-source vulnerability sits with liquid nitrogen storage vessel suppliers facing extended CE marking renewal timelines under EU MDR. Distribution runs through centralized pharmacy tenders in German hospital networks and direct procurement relationships with private clinic chains in Spain and the United Kingdom.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in Eastern European fertility networks where integrated hormone-to-media workflow suppliers remain underpenetrated, as Polish and Czech clinic expansion outpaces vendor coverage.
For Market Incumbents: Harden defensible positions through backward integration into protein-supplemented culture media formulation capacity, securing supply continuity against REACH chemical safety protocol disruptions. Anchor multi-year remote monitoring contracts with Nordic clinic networks to lock in recurring revenue streams. Prioritize CE marking renewal acceleration for cryopreservation portfolios before German and French notified body backlogs extend further. For New Entrants and Emerging Players: Pursue white-space capture in Hungary and Romania fertility center networks where centralized laboratory standardization creates procurement consolidation opportunities. Elective fertility preservation protocols in Scandinavian urban clusters offer fastest penetration trajectory. Lead with EU Green Deal-aligned alternative cooling architectures to qualify for sustainability-linked procurement preferences in publicly funded hospital systems. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized embryology consumable formulators with established regulatory documentation libraries and clinic network relationships. Long-term viability hinges on MDR compliance infrastructure depth and remote monitoring platform development. Watch CE marking renewal throughput at German notified bodies as inflection indicator for equipment vendor margin compression timelines.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Acceleration | Shortens regulatory transition periods for cryopreservation equipment portfolios at German notified bodies. |
| Hospital System Partnership | Secures preferred vendor status in French regional health authority centralized procurement frameworks. |
| Software Companion Development | Enables remote embryo monitoring capabilities that Stockholm clinic networks now specify as mandatory. |
| Backward Integration into Media Formulation | Reduces REACH compliance cost exposure for hormone-to-culture workflow suppliers. |
| Reimbursement Strategy | Aligns preimplantation genetic testing bundling with Dutch and UK premium treatment coverage expansion. |
Research Methodology
Desk research of EMA medical device registration databases, EU MDR technical documentation repositories, and national reimbursement authority filings preceded structured interviews with embryology laboratory directors, fertility clinic procurement officers, biomedical equipment service managers, and reproductive endocrinology practice administrators. Primary fieldwork across German, Spanish, UK, and Nordic clinic networks combined with secondary validation against hospital procurement databases and GPO contracts. Bottom-up segment sizing triangulated against top-down macroeconomic healthcare expenditure frameworks.
Assumption sets held regulatory transition timelines and REACH substance restriction schedules fixed while varying national reimbursement expansion scenarios and private clinic capital expenditure cycles across the projection horizon. Segmentation modeling incorporated product type, technology intensity, end-user channel configuration, and application indication severity dimensions. CAGRs derived from weighted average of historical procedure volume trajectories and equipment replacement cycle compression rates, with fertility preservation protocol adoption curves and ICSI utilization patterns as key forecast inputs.
Sensitivities concentrate around CE marking renewal throughput at notified bodies, REACH candidate list substance designations affecting culture media formulations, and French national reimbursement expansion timing. Forecasts reflect documented assumptions regarding MDR implementation pace and F-Gas Regulation refrigerant phase-out schedules. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Reproductive Health
Smart Fertility Tracker Market
Reproductive Health
Gamete Preservation Market
Reproductive Health
Donor Egg IVF (in-Vitro Fertilization) Market
Reproductive Health
Ovum Egg Banking Market
Reproductive Health
US Contraceptive Market
Reproductive Health
Doula and Birth Coaching Services Market
Reproductive Health
US Sexual and Reproductive Health Clinics Market
Reproductive Health
In Vitro Fertilization (IVF) Market
Reproductive Health
Egg Freezing and Embryo Banking Market
Reproductive Health
Assisted Reproductive Technology (ART) Market
Reproductive Health
Global Male Infertility Market
Reproductive Health
US Long-Acting Contraception Market
Reproductive Health
IVF Services Market
Reproductive Health
Germany in Vitro Fertilization (IVF) Market
Reproductive Health
Donor Egg IVF Services Market
Reproductive Health
Contraceptives Market