
 Assisted Reproductive Technology (ART) Market | 2026-2036
Assisted Reproductive Technology (ART) Market Size, Share, and Industry Trends Forecast 2026-2036
Assisted Reproductive Technology (ART) Market Analysis
Subscription-based cryostorage and remote embryo monitoring is recalibrating what fertility networks sell beyond procedural fees. CooperSurgical Inc. leverages its integrated media and device portfolio to anchor clinic supply relationships across North America. Vitrolife AB dominates time-lapse incubator technology, while Genea Biomedx competes on software-driven embryo assessment tools.
Assisted Reproductive Technology encompasses laboratory and clinical procedures that handle human gametes and embryos outside the body, requiring temperature-controlled incubation at 37 degrees Celsius with 5% carbon dioxide and pH-stable culture media to maintain viability. Its primary commercial purpose is to treat infertility through controlled fertilization and embryo development for uterine transfer. In Vitro Fertilization occupies the largest revenue pool given its procedural complexity and repeat cycle economics, while Preimplantation Genetic Testing commands premium pricing due to specialized embryology expertise. Fertility Clinics represent the dominant end-user channel, though Research Institutions are expanding as cryopreservation protocols advance.
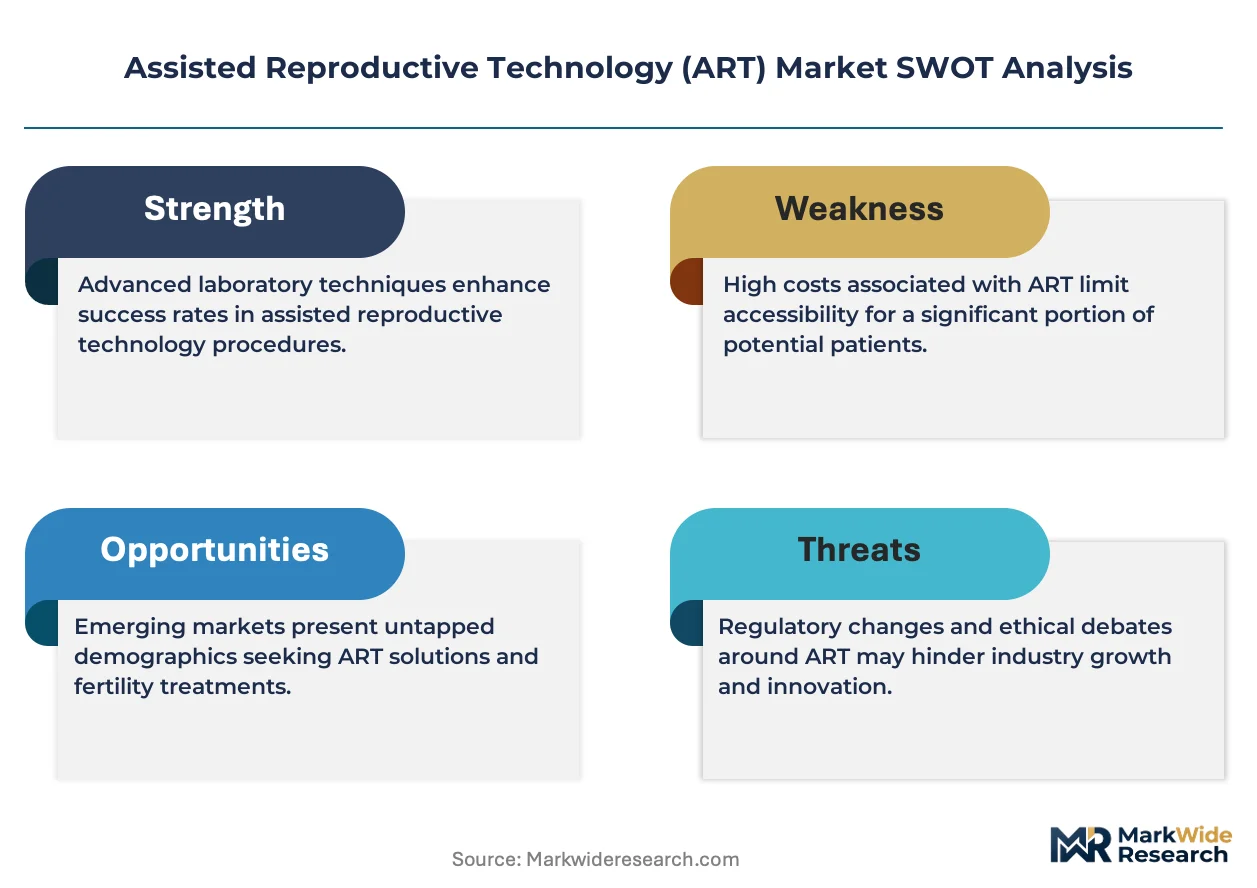
The FDA regulates ART devices and genetic testing platforms under medical device and laboratory-developed test frameworks, shaping validation requirements and market entry timelines. EMA oversight through the In Vitro Diagnostic Medical Devices Regulation affects product certification across European fertility networks. India's CDSCO and the national assisted reproduction bill impose facility standards that constrain unaccredited clinic expansion. Stakeholders must weigh regulatory compliance investments against the margin compression from standardized reimbursement frameworks.
Market Dynamics
Subscription-based cryostorage and remote embryo monitoring are recalibrating what fertility networks sell beyond procedural fees, compressing traditional revenue models while opening recurring service streams. This structural shift toward service bundling is forcing device manufacturers to integrate hardware with cloud-based analytics platforms.
Growth Catalysts
- Delayed Childbearing Demographics:Urban professional populations in Brazil and India are pursuing first pregnancies at later ages, expanding the addressable patient base for fertility preservation and intervention services.
- Preimplantation Genetic Testing Expansion:The FDA's oversight framework for laboratory-developed tests is clarifying validation pathways, accelerating commercial deployment of expanded carrier screening panels.
- Time-Lapse Incubator Adoption:Fertility clinics are replacing conventional incubation systems with continuous embryo monitoring platforms to improve selection accuracy and reduce multiple gestation risks.
Market Restraints
- Culture Media Supply Concentration:Three manufacturers control the majority of pH-stable media formulations, creating vulnerability to batch variability or supply interruption.
- Embryologist Training Bottlenecks:Specialized micromanipulation certification requires 12-24 months of supervised practice, constraining clinic expansion velocity regardless of capital availability.
- Reimbursement Compression:Standardized insurance frameworks in the United States cap cycle coverage at fixed rates, squeezing margins on high-complexity cases requiring extended culture.
Strategic Opportunities
- Secondary City Penetration:India's tier-2 metropolitan clusters lack accredited ART facilities despite rising demand, creating first-mover positioning for quality-certified networks.
- AI-Assisted Embryo Grading:Machine vision algorithms trained on time-lapse image sequences are converging with morphokinetic scoring to reduce subjective assessment variation.
- Oocyte Cryopreservation Elective Demand:Employer-sponsored fertility benefits are normalizing egg freezing as a workforce retention tool among technology and financial services firms.
Industry Challenges
- Cross-Border Reproductive Tourism Complexity:Patients traveling from restrictive jurisdictions to permissive regulatory environments create liability fragmentation and informed consent documentation gaps.
- Laboratory Information System Integration:Legacy clinic management platforms resist seamless data exchange with modern embryo monitoring devices, requiring costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Assisted Reproductive Technology (ART) Market |
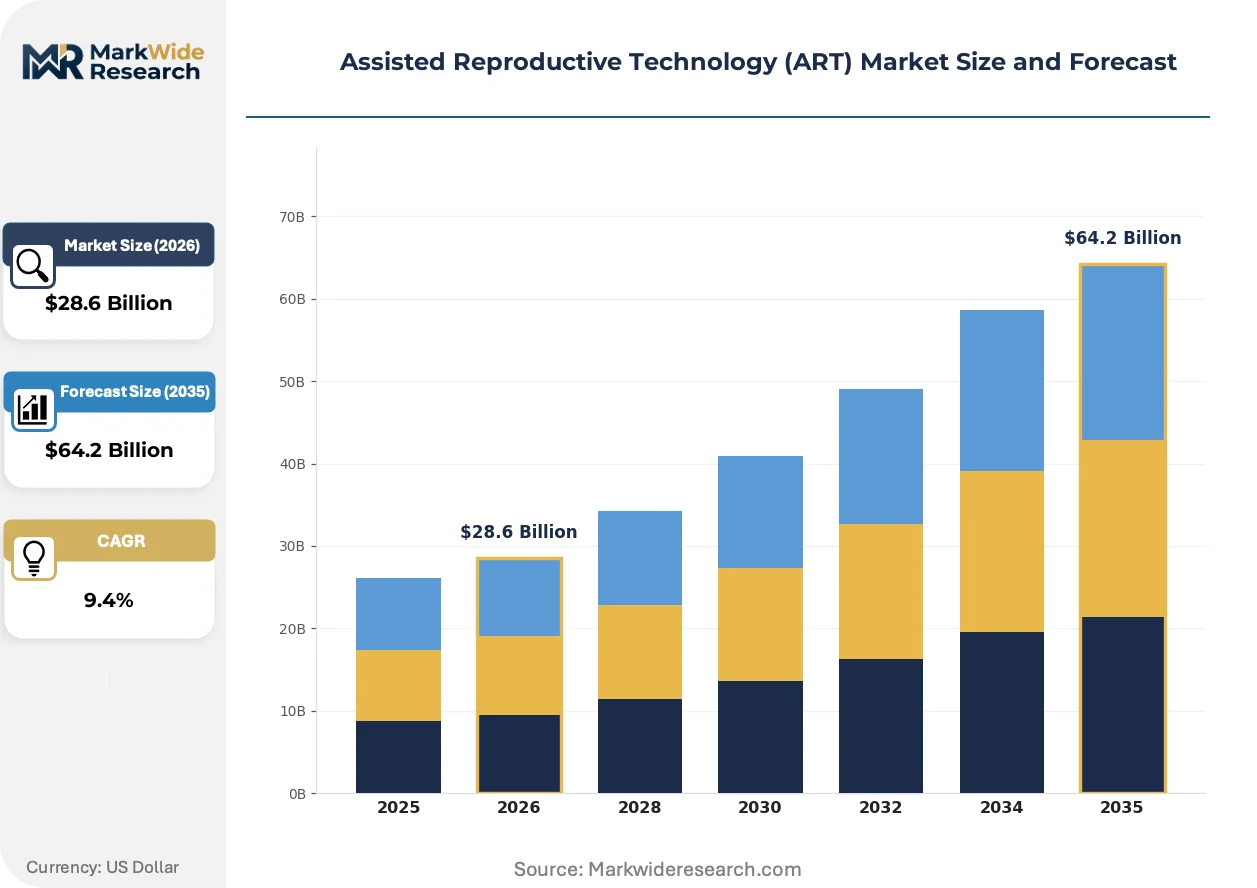
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $64.2 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: In Vitro Fertilization, Artificial Insemination, Egg Donation, Surrogacy End User: Fertility Clinics, Hospitals, Research Institutions, Home Use Technology: Intracytoplasmic Sperm Injection, Preimplantation Genetic Testing, Cryopreservation, Embryo Culture Service Type: Counseling, Diagnostic Testing, Hormonal Treatments, Embryo Transfer |
| Companies Covered | CooperSurgical Inc., FUJIFILM Irvine Scientific, Vitrolife AB, Merck KGaA, California Cryobank, Cook Medical Inc., Thermo Fisher Scientific Inc., Hamilton Thorne, Genea Biomedx, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Assisted Reproductive Technology (ART) Market Emerging Trajectories
Artificial intelligence is penetrating embryology workflows at the point of highest clinical uncertainty: embryo viability prediction. This computational shift is compressing the traditional reliance on subjective morphological grading while raising new questions about algorithmic transparency and liability allocation.
Time-lapse incubation combined with deep learning-based image analysis is unifying the previously separate functions of environmental control and developmental assessment. Fertility networks in Spain and Denmark are deploying these integrated platforms at scale, replacing standalone conventional incubators and manual microscope evaluations. The technology is unifying hardware and software procurement decisions, favoring vendors with captive AI development capabilities over pure device manufacturers.
The European Union's In Vitro Diagnostic Medical Devices Regulation is tightening clinical evidence requirements for genetic screening platforms used in embryo biopsy analysis. Manufacturers must now submit prospective validation studies rather than retrospective analytical performance data, extending certification timelines by 18-30 months. Preimplantation genetic testing providers are responding by consolidating laboratory operations to concentrate regulatory expertise and reduce compliance overhead across multiple member states.
Large employers in the United States are unbundling fertility benefits from traditional health insurance and contracting directly with specialized networks for managed care carve-outs. This purchasing behavior is concentrating patient volume among a smaller set of high-volume clinics capable of meeting reporting and outcome transparency requirements. The shift is most visible in technology sector headquarters locations where talent competition justifies premium benefit investment.
Assisted Reproductive Technology (ART) Market Segmentation
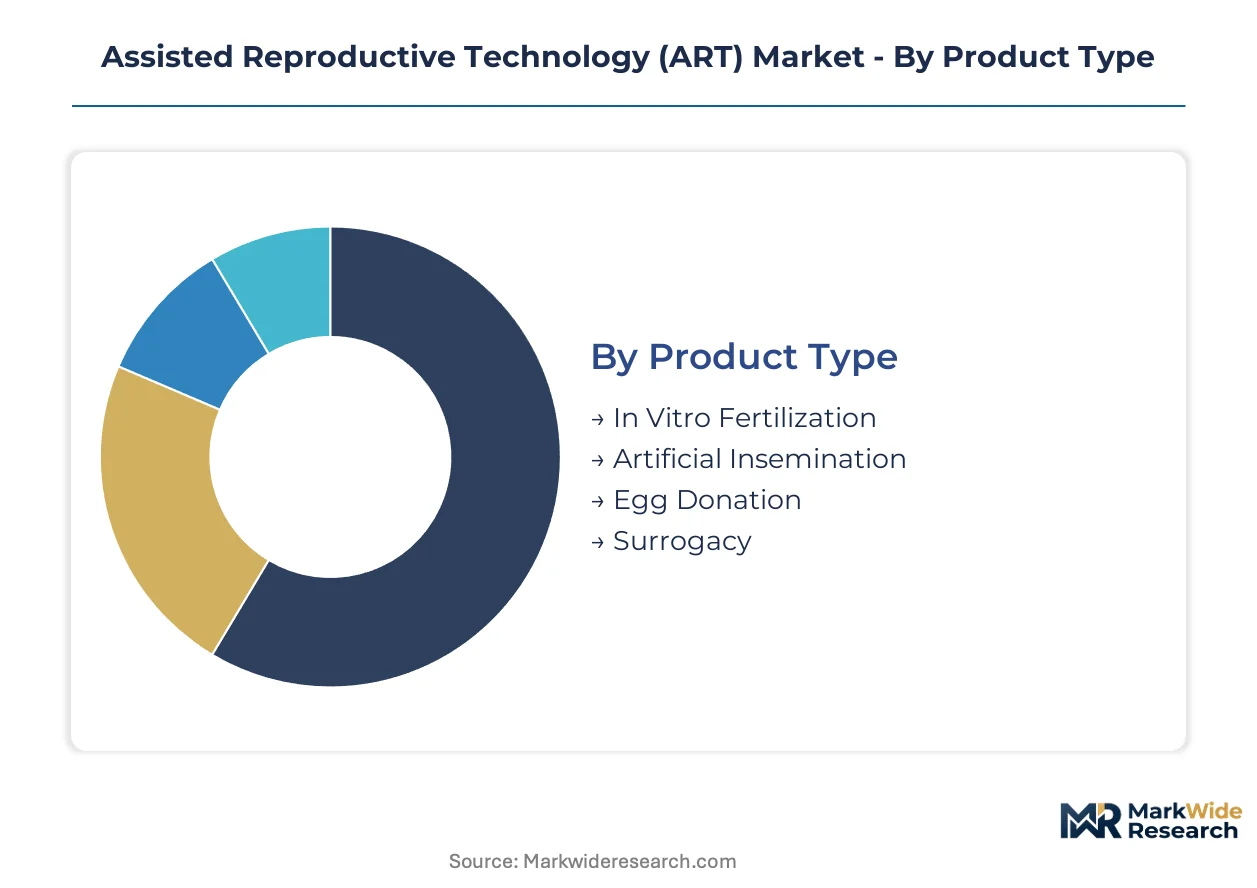
ART market segmentation reveals distinct procurement patterns across clinical and research channels. Product complexity, regulatory burden, and reimbursement frameworks create divergent margin profiles within each category.
Product Type:
Customization intensity spans from standardized gamete handling to highly personalized third-party reproductive arrangements.
- In Vitro Fertilization:Laboratory-based fertilization outside the body requires temperature-controlled incubation at 37 degrees Celsius with pH-stable culture media. Demand concentrates in metropolitan hospital clusters across India and Brazil, driven by delayed childbearing demographics among urban professionals. Fertility clinics in the United States are expanding service capacity to meet rising patient volumes for this core procedure.
- Artificial Insemination:Less invasive gamete placement technique utilizing processed semen specimens with lower laboratory infrastructure requirements. Home use segments in permissive regulatory jurisdictions are gaining traction, though clinical oversight remains preferred for complex infertility cases.
- Egg Donation:Third-party oocyte procurement with extensive genetic screening and donor matching protocols.
- Surrogacy:Gestational carrier arrangements involving legal, medical, and psychological coordination across multiple parties.
Leading the category by volume: In Vitro Fertilization. Expanding most quickly: Egg Donation.
End User:
Channel concentration reflects capital requirements, regulatory accreditation, and patient access patterns.
- Fertility Clinics:Dedicated reproductive medicine facilities with embryology laboratories and specialized micromanipulation suites. These clinics represent the dominant end-user channel, capturing procedural complexity and repeat cycle economics through subscription-based cryostorage and remote embryo monitoring services.
- Hospitals:Integrated health systems offering ART as part of broader women's health portfolios. Metropolitan hospital clusters across India and Brazil concentrate demand, leveraging existing infrastructure for high-complexity cases requiring extended culture.
- Research Institutions:Academic and commercial laboratories advancing cryopreservation protocols and embryonic stem cell applications. These institutions are expanding as cryopreservation protocols advance, particularly in Spain and Denmark where time-lapse incubator platforms deploy at scale.
- Home Use:Direct-to-consumer fertility tracking and intracervical insemination kits for low-intervention conception support.
Fertility clinics dominate revenue capture. Research institutions are climbing the fastest as cryopreservation technology matures.
Technology:
Technology tiers separate hardware-intensive environmental control from software-driven analytical platforms.
- Intracytoplasmic Sperm Injection:Micromanipulation technique delivering single sperm directly into oocyte cytoplasm, requiring 12-24 months of specialized embryologist certification. Vitrolife AB dominates time-lapse incubator technology that integrates with ICSI workflows, while Genea Biomedx competes on software-driven embryo assessment tools.
- Preimplantation Genetic Testing:Embryo biopsy analysis for chromosomal and monogenic conditions, commanding premium pricing due to specialized embryology expertise. The FDA's oversight of preimplantation genetic testing devices shapes product development pathways, while the EMA's In Vitro Diagnostic Medical Devices Regulation extends certification timelines by 18-30 months.
- Cryopreservation:Vitrification and slow-freeze protocols for gamete and embryo banking.
- Embryo Culture:Extended in vitro development to blastocyst stage for improved selection accuracy.
Intracytoplasmic Sperm Injection leads procedure volume. Preimplantation Genetic Testing shows the steepest expansion trajectory.
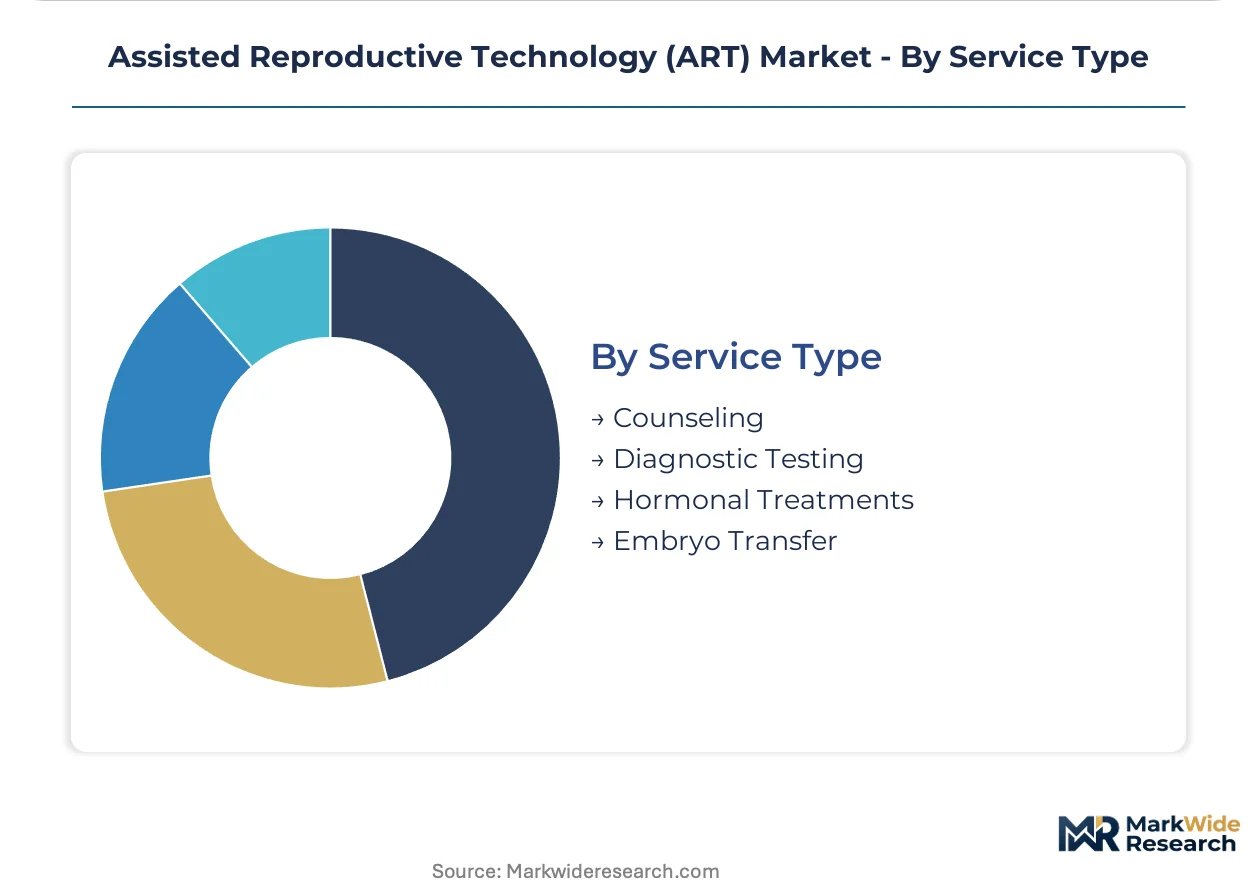
Service Type:
Service bundling shifts revenue from discrete procedures to recurring care relationships.
- Counseling:Psychological and reproductive planning support throughout treatment cycles.
- Diagnostic Testing:Hormonal assays, imaging, and semen analysis for fertility assessment.
- Hormonal Treatments:Ovarian stimulation protocols using gonadotropin medications to produce multiple oocytes.
- Embryo Transfer:Final clinical procedure placing developed embryos into uterine cavity, with time-lapse incubator adoption reducing multiple gestation risks through improved selection accuracy.
Diagnostic testing anchors initial patient intake. Embryo transfer services are gaining share fastest through technology integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mumbai's metropolitan hospital clusters concentrate India's highest ART procedural volumes, with fertility networks expanding into tier-2 cities to capture underserved demand from delayed childbearing professionals.
United States
Employer-sponsored fertility benefits at technology and financial services firms are normalizing elective oocyte cryopreservation as a workforce retention tool. The FDA's oversight of preimplantation genetic testing devices shapes product development pathways for domestic manufacturers. Fertility clinics in California and the Northeast Corridor are expanding service capacity to meet rising patient volumes.
India
Urban professionals in Maharashtra and Gujarat are pursuing first pregnancies at later ages, expanding demand for fertility preservation services. The CDSCO and national assisted reproduction bill impose facility standards that constrain unaccredited clinic expansion. Tier-2 metropolitan clusters across Karnataka and Tamil Nadu lack accredited ART facilities despite rising demand.
Brazil
Delayed childbearing demographics among São Paulo's urban professional populations are driving procedural growth in metropolitan hospital clusters. ANVISA regulates device certification for imported incubation and cryopreservation equipment. Fertility networks in Rio de Janeiro and Minas Gerais are deploying time-lapse monitoring platforms to improve embryo selection accuracy.
Spain
Fertility networks in Madrid and Catalonia are deploying integrated time-lapse incubation and deep learning-based image analysis at scale. The EMA's In Vitro Diagnostic Medical Devices Regulation extends certification timelines for genetic screening platforms by 18-30 months. Barcelona's reproductive medicine clusters are consolidating laboratory operations to concentrate regulatory expertise.
Denmark
Research institutions in Copenhagen are advancing cryopreservation protocols using time-lapse incubator platforms. EMA oversight through the MDR framework affects product certification across Scandinavian fertility networks. Academic-commercial partnerships in the Øresund Region are unifying hardware and software procurement decisions for embryology workflows.
Assisted Reproductive Technology (ART) Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the ART device landscape, with integrated media and device portfolios anchoring supply relationships against specialized component vendors. The market structure shows moderate consolidation at the platform level alongside fragmentation in consumables and diagnostics. Two strategic archetypes dominate: full-stack laboratory solution providers and point-technology specialists focused on single workflow steps. Competitive moves center on M&A to capture AI development capabilities and strategic partnerships to embed cloud-based analytics into legacy clinic management platforms.
Among integrated solution providers, CooperSurgical Inc. and Vitrolife AB occupy positions representing contrasting approaches to clinic supply relationships, while Genea Biomedx exemplifies the software-driven assessment tool archetype competing on algorithmic embryo grading capabilities.
| Leading Market Players |
|---|
| CooperSurgical Inc. |
| FUJIFILM Irvine Scientific |
| Vitrolife AB |
| Merck KGaA |
| California Cryobank |
| Cook Medical Inc. |
| Thermo Fisher Scientific Inc. |
| Hamilton Thorne |
| Genea Biomedx |
| Others |
Supply Flow & Price Mechanics
Culture media formulations, the pH-stable liquids maintaining embryo viability at 37 degrees Celsius, flow from concentrated European and North American manufacturing through three-tier pricing structures that separate GMP-certified premium grades from research-use formulations. These specialized inputs anchor downstream device bundling strategies, with incubation hardware vendors absorbing media cost volatility into long-term service contracts.
Pricing Analysis
Outcome-linked pricing tied to live birth rates per initiated cycle anchors contract negotiations between fertility networks and device vendors. Three-tier pricing structure across premium, standard, and economy levels separates time-lapse incubator platforms with integrated AI assessment from conventional incubation systems and refurbished equipment tiers. Cost compression in standard-tier hardware is intensifying because Chinese manufacturers are entering cryopreservation device assembly. Price sensitivity concentrates among independent fertility clinics in India's tier-2 cities, while integrated hospital systems in São Paulo and Madrid prioritize throughput guarantees over per-unit procurement costs.
Supply Chain Analysis
ISO 13485 and FDA Quality System Regulation certifications gate entry for culture media suppliers, with manufacturing concentrated in Sweden, the United States, and Japan. pH-buffered media formulations, disposable micromanipulation pipettes, and liquid nitrogen storage dewars constitute critical input dependencies. Single-source vulnerability runs through vitrification media supply, where two Swedish manufacturers control proprietary cryoprotectant formulations. Distribution runs through direct sales forces for high-complexity incubation platforms, while consumables flow through regional medical device distributors with cold-chain capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around integrated platform providers, with EMA's In Vitro Diagnostic Medical Devices Regulation forcing sub-scale genetic testing laboratories to exit or sell.
For Market Incumbents: Cement clinic supply relationships by bundling time-lapse incubation hardware with captive AI embryo grading software, neutralizing Genea Biomedx's algorithmic threat. Acquire distressed genetic testing laboratories in Spain and Denmark to concentrate regulatory expertise and reduce per-facility compliance overhead. Backward integration into pH-stable culture media production insulates margin pressure from the three-manufacturer supply concentration. For New Entrants and Emerging Players: CDSCO facility standardization in India opens a window for quality-certified networks to capture first-mover positioning in Karnataka and Tamil Nadu tier-2 clusters before incumbent chains deploy. Target employer-sponsored fertility benefits carve-outs in United States technology sector headquarters, where reporting transparency requirements filter out sub-scale competitors. Lead with remote embryo monitoring SaaS subscriptions to bypass capital-intensive laboratory buildouts. For Investors and Strategic Acquirers: Consolidation of Barcelona and Madrid laboratory operations is the leading indicator that European genetic testing margins are compressing toward sustainable levels for platform rollups. Acquire embryology laboratory networks with captive AI development capabilities rather than pure device manufacturers, as hardware-software unification determines procurement decisions. Watch for FDA expanded carrier screening panel approvals as inflection signals for United States market expansion velocity.| Strategic Initiative | Industry Significance |
|---|---|
| AI Embryo Grading Platform Integration | Machine vision algorithms trained on time-lapse sequences reduce subjective assessment variation in Madrid and Copenhagen networks. |
| Cryostorage Subscription Service Launch | Recurring revenue streams recalibrate fertility network economics beyond procedural fees in United States employer benefit contracts. |
| Secondary City Accreditation Expansion | CDSCO facility certification in India's tier-2 metropolitan clusters captures underserved delayed childbearing demand. |
| Genetic Testing Laboratory Consolidation | Concentrated regulatory expertise reduces EMA MDR compliance overhead across multiple European member states. |
| Time-Lapse Incubator Platform Deployment | Continuous embryo monitoring improves selection accuracy and reduces multiple gestation risks in São Paulo and Rio de Janeiro clinics. |
Methodological Framework
Multi-period observation of FDA premarket notification filings, EMA MDR certification timelines, and fertility clinic expansion announcements anchored the trend analysis, supplemented by interviews with embryology laboratory directors, reproductive endocrinologists, hospital purchasing committee members, and medical device distribution channel managers. Secondary validation drew from CDSCO facility accreditation databases, ANVISA device import records, SEC 10-K filings of listed manufacturers, and European fertility network outcome registries. Bottom-up procedure volume estimates triangulated against top-down market size assessments across the analysis window.
Segment-weighting approaches modeled technology adoption curves separately for time-lapse incubation, preimplantation genetic testing, and cryopreservation protocols across product type, end user channel, and geographic regulatory cluster dimensions. CAGRs were derived from fitted growth curves incorporating delayed childbearing demographic projections, employer benefit penetration rates, and regulatory approval velocity assumptions. Forecast inputs included embryologist training pipeline constraints, culture media manufacturing capacity, and AI algorithm validation study timelines.
The model assumes a particular technology adoption path; alternative pathways for deep learning-based embryo assessment would alter the outlook if regulatory validation timelines extend beyond current EMA and FDA frameworks. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Reproductive Health
Smart Fertility Tracker Market
Reproductive Health
Doula and Birth Coaching Services Market
Reproductive Health
Gamete Preservation Market
Reproductive Health
Contraceptives Market
Reproductive Health
Hormonal Contraception Market
Reproductive Health
Europe in Vitro Fertilization (IVF) Market
Reproductive Health
Cervical Dysplasia Treatment Market
Reproductive Health
US Birth Centers Market
Reproductive Health
Pregnancy Care Products Market
Reproductive Health
Vaginal Exam Specula Market
Reproductive Health
UK in Vitro Fertilization (IVF) Market
Reproductive Health
Egg Freezing and Embryo Banking Market
Reproductive Health
Global Male Infertility Market
Reproductive Health
Surrogacy Market
Reproductive Health
Asia-Pacific in Vitro Fertilization (IVF) Market
Reproductive Health
Global Gynecology Drugs Market