
 Asia-Pacific in Vitro Fertilization (IVF) Market | 2026-2036
Asia-Pacific in Vitro Fertilization (IVF) Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific in Vitro Fertilization (IVF) Market Foresight
Next-generation sequencing integration with embryology workflows is narrowing the gap between diagnostic precision and clinical outcomes. Virtus Health leverages its multi-site network across Australia to sustain consistent laboratory standards. Max Healthcare anchors its competitive position through high-volume IVF centers in Delhi and Mumbai. Bloom Fertility Center differentiates via specialized endocrinology protocols for complex infertility cases.
In vitro fertilization encompasses laboratory-based fertilization of oocytes with sperm outside the body, followed by embryo culture for two to six days before uterine transfer, with success rates critically dependent on controlled incubator environments maintaining 37°C, 5% CO2, and 20% O2. The technology serves primarily to overcome tubal factor infertility, male factor infertility, and unexplained reproductive failure. ICSI technology leads the technology segment due to its established efficacy in severe male factor cases, while artificial intelligence applications in embryo selection represent the fastest-growing margin pool as clinics seek to reduce multiple pregnancy rates and improve single embryo transfer outcomes. Fertility clinics dominate the end user landscape, though hospital-affiliated IVF programs in Thailand and South Korea are capturing complex cases requiring multidisciplinary care.
CDSCO in India and Australia's TGA regulate IVF media and device classifications, with India's 2021 Assisted Reproductive Technology Regulation Act mandating clinic registration and standardizing treatment protocols. Japan's PMDA oversees preimplantation genetic testing frameworks, creating compliance thresholds that favor accredited laboratory networks. South Korea's MFDS maintains stringent cryopreservation equipment standards that shape import dynamics for European and American manufacturers. Stakeholders must monitor evolving genetic testing regulations across jurisdictions, as policy divergence on embryo editing and PGT-A reimbursement will determine where capital deployment for laboratory expansion generates sustainable returns.
Market Dynamics
Next-generation sequencing integration with embryology workflows is compressing diagnostic-to-treatment timelines across fertility networks, while CDSCO and TGA regulatory modernization simultaneously accelerates device approval pathways and intensifies compliance scrutiny for laboratory accreditation.
Growth Catalysts
- ICSI technology refinement:Microinjection protocols for severe male factor infertility now achieve standardized success rates across high-volume fertility clinics in India and Australia, expanding addressable patient populations.
- India's 2021 Assisted Reproductive Technology Regulation Act:Mandatory clinic registration and protocol standardization by CDSCO is professionalizing service delivery and consolidating fragmented provider networks into accredited chains.
- Metropolitan fertility corridor concentration:Patient volumes are concentrating in Mumbai, Delhi, and Bangalore, enabling scale economies in laboratory infrastructure and embryologist staffing.
Market Restraints
- Specialized culture media supply concentration:European and American manufacturers dominate IVF media formulation, exposing clinics to import cost volatility and currency fluctuation risk.
- Cryopreservation equipment certification delays:South Korea's MFDS maintains stringent equipment validation timelines that extend deployment cycles for vitrification systems.
- Embryo storage cost structure:Long-term cryostorage facilities require continuous liquid nitrogen supply and redundant power systems, creating fixed cost burdens for smaller clinic operators.
Strategic Opportunities
- Artificial intelligence embryo selection:Machine learning algorithms analyzing time-lapse imaging data are virtualizing morphological assessment, reducing multiple pregnancy rates and improving single embryo transfer outcomes.
- Southeast Asia service expansion:Thailand and Vietnam present underpenetrated demand for fertility preservation among elective egg-freezing patients and oncology referrals.
- Preimplantation genetic testing reimbursement:Japan's PMDA framework evolution on PGT-A coverage creates pathway for test volume expansion in chromosomal screening applications.
Industry Challenges
- Embryologist training pipeline constraints:Specialized micromanipulation and culture expertise requires multi-year apprenticeship, creating talent scarcity as clinic networks expand capacity.
- Laboratory quality management system integration:ISO 15189 medical laboratory accreditation demands documentation infrastructure that legacy fertility centers struggle to implement without operational disruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific in Vitro Fertilization (IVF) Market |
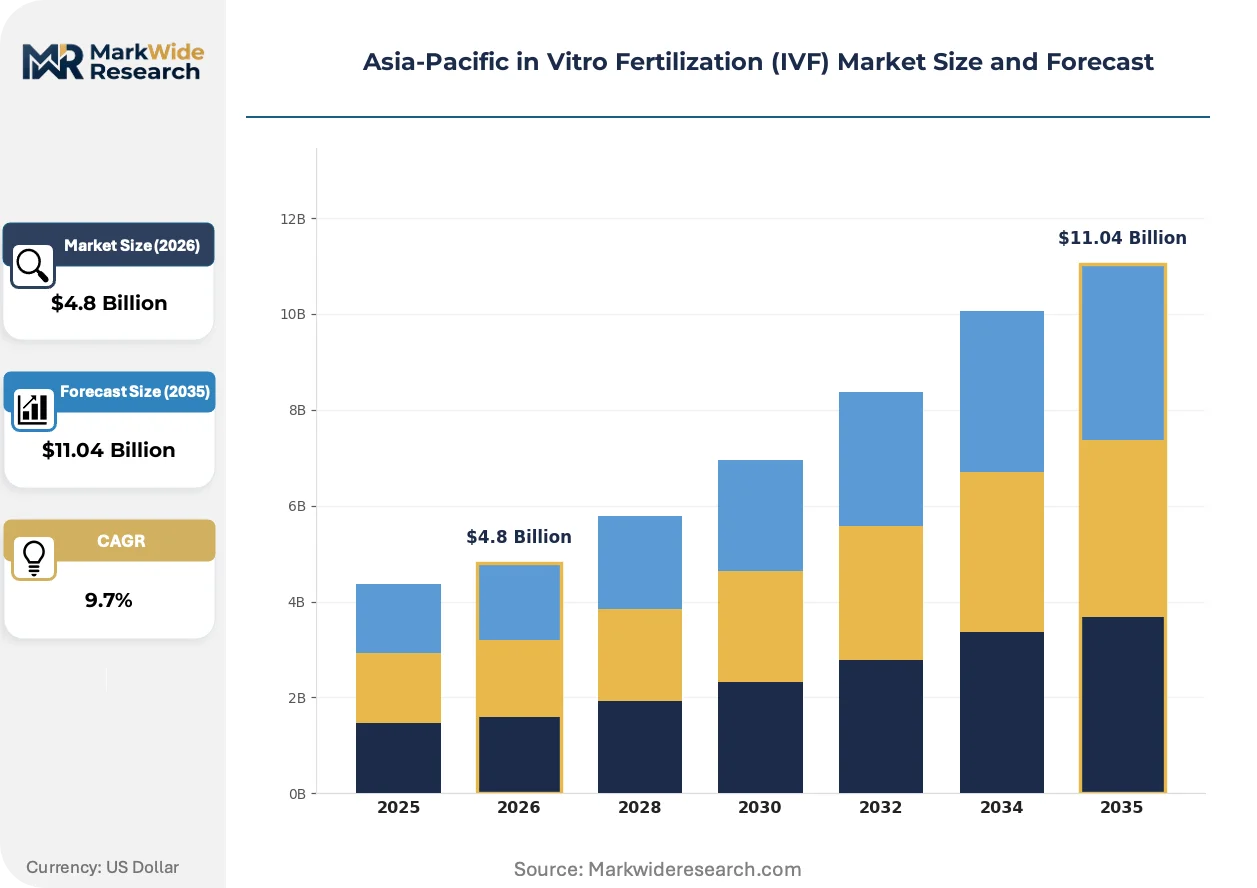
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Embryo Transfer, Oocyte Retrieval, IVF Media, Cryopreservation Equipment Technology: ICSI, Preimplantation Genetic Testing, Artificial Intelligence, Laser-Assisted Hatching End User: Hospitals, Fertility Clinics, Research Institutes, IVF Centers Service Type: Consultation Services, Laboratory Services, Treatment Services, Support Services |
| Companies Covered | Virtus Health, Max Healthcare, Bourn Hall Fertility Center, Manipal Fertility, Bloom Fertility Center, Cloudnine Fertility, Chennai Fertility Center, IVF Australia, Singapore General Hospital, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific in Vitro Fertilization (IVF) Market Shifts & Advancements
Artificial intelligence applications and time-lapse incubation systems are restructuring embryology workflows, while regulatory divergence on genetic testing reimbursement is fragmenting investment priorities across national markets.
Time-lapse morphokinetic analysis is virtualizing traditional static embryo grading. Fertility clinics in Australia and South Korea are deploying incubator-integrated imaging platforms that capture developmental sequences without culture disturbance. This technology is virtualizing manual assessment protocols and enabling algorithmic ranking of embryo viability.
Japan's PMDA is revising preimplantation genetic testing notification requirements, creating clearer pathways for expanded chromosomal and monogenic disorder screening. The regulatory shift permits accredited laboratory networks to offer PGT-A and PGT-M as standard service components rather than exceptional procedures. Australian fertility networks are responding by pursuing TGA alignment with Japanese frameworks to maintain regional competitiveness.
Patient acquisition patterns are rotating toward direct-to-consumer digital channels and employer-sponsored fertility benefits. Large corporate health programs in India and Singapore are contracting directly with fertility networks for managed care bundles, bypassing traditional referral pathways through obstetrician-gynecologists. This channel shift concentrates patient volume with network-affiliated clinics capable of standardized reporting and outcome transparency.
Asia-Pacific in Vitro Fertilization (IVF) Market Segmentation
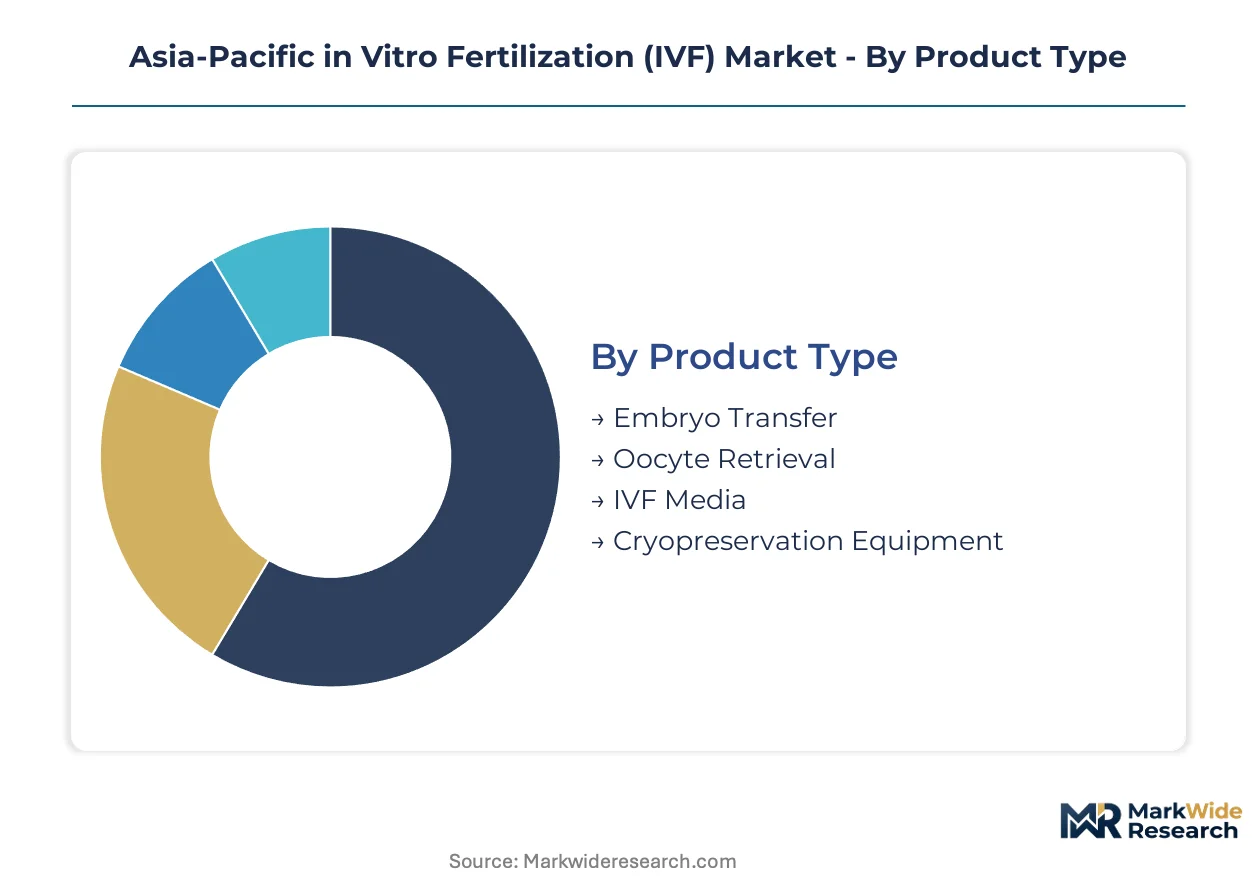
IVF market segmentation reveals how capital allocation, regulatory compliance, and clinical workflow specialization concentrate value across distinct product, technology, and service categories. Understanding these partitions enables stakeholders to identify where margin accretion aligns with volume expansion versus where infrastructure investment yields defensive positioning.
Product Type:
Cost tier stratification across IVF consumables and equipment exposes divergent margin structures between single-use media formulations and capital-intensive cryopreservation systems.
- Embryo Transfer:Catheter systems and transfer media kits designed for minimally invasive uterine delivery of cultured embryos. Demand concentrates in high-volume fertility corridors across Mumbai, Delhi, and Bangalore where procedure standardization enables bulk procurement negotiations with CDSCO-registered suppliers.
- Oocyte Retrieval:Aspiration needles, ultrasound-guided retrieval systems, and follicular flushing media for transvaginal oocyte collection. Australia's TGA-regulated clinics drive specification requirements that propagate through regional supply chains, favoring manufacturers with multi-jurisdiction certification.
- IVF Media:Culture media formulations supporting gamete and embryo development outside physiological conditions.
- Cryopreservation Equipment:Vitrification systems and liquid nitrogen storage infrastructure for long-term embryo and gamete banking.
Embryo Transfer holds installed capacity. Cryopreservation Equipment is rotating up the share rankings.
Technology:
Application maturity spans from established micromanipulation protocols to algorithmic embryo assessment tools that remain in early commercial deployment.
- ICSI:Intracytoplasmic sperm injection technology enabling fertilization in severe male factor cases through direct sperm deposition into ooplasm. India's metropolitan fertility networks have standardized ICSI protocols across Delhi and Mumbai centers, with CDSCO oversight ensuring consistent training certification for embryologists performing microinjection.
- Preimplantation Genetic Testing:Chromosomal and monogenic screening of embryos prior to transfer, encompassing PGT-A and PGT-M methodologies. Japan's PMDA framework evolution is expanding reimbursable indications, concentrating demand growth in accredited laboratory networks capable of NGS integration.
- Artificial Intelligence:Machine learning algorithms applied to time-lapse morphokinetic data for embryo viability ranking.
- Laser-Assisted Hatching:Precision laser systems for zona pellucida thinning to facilitate embryo implantation.
ICSI holds installed capacity. Artificial Intelligence is climbing the fastest as clinics virtualize morphological assessment protocols.
End User:
Customer type differentiation reflects divergent capital intensity, regulatory burden, and patient complexity handling capabilities across institutional settings.
- Fertility Clinics:Dedicated reproductive medicine facilities with integrated laboratory and clinical services. Mumbai, Delhi, and Bangalore corridors concentrate India's highest-volume operators, where India's 2021 Assisted Reproductive Technology Regulation Act mandates CDSCO registration and standardized outcome reporting.
- Hospitals:Multidisciplinary medical centers with IVF programs embedded within broader obstetric and oncology services. Thailand and South Korea hospital networks capture complex cases requiring coordinated fertility preservation for oncology patients, leveraging MFDS and domestic health ministry accreditation.
- IVF Centers:Specialized facilities focused exclusively on assisted reproduction without full hospital infrastructure.
- Research Institutes:Academic and institutional laboratories conducting reproductive biology research and clinical trials.
Fertility Clinics hold installed capacity. Hospitals are gaining share fastest through multidisciplinary case capture.
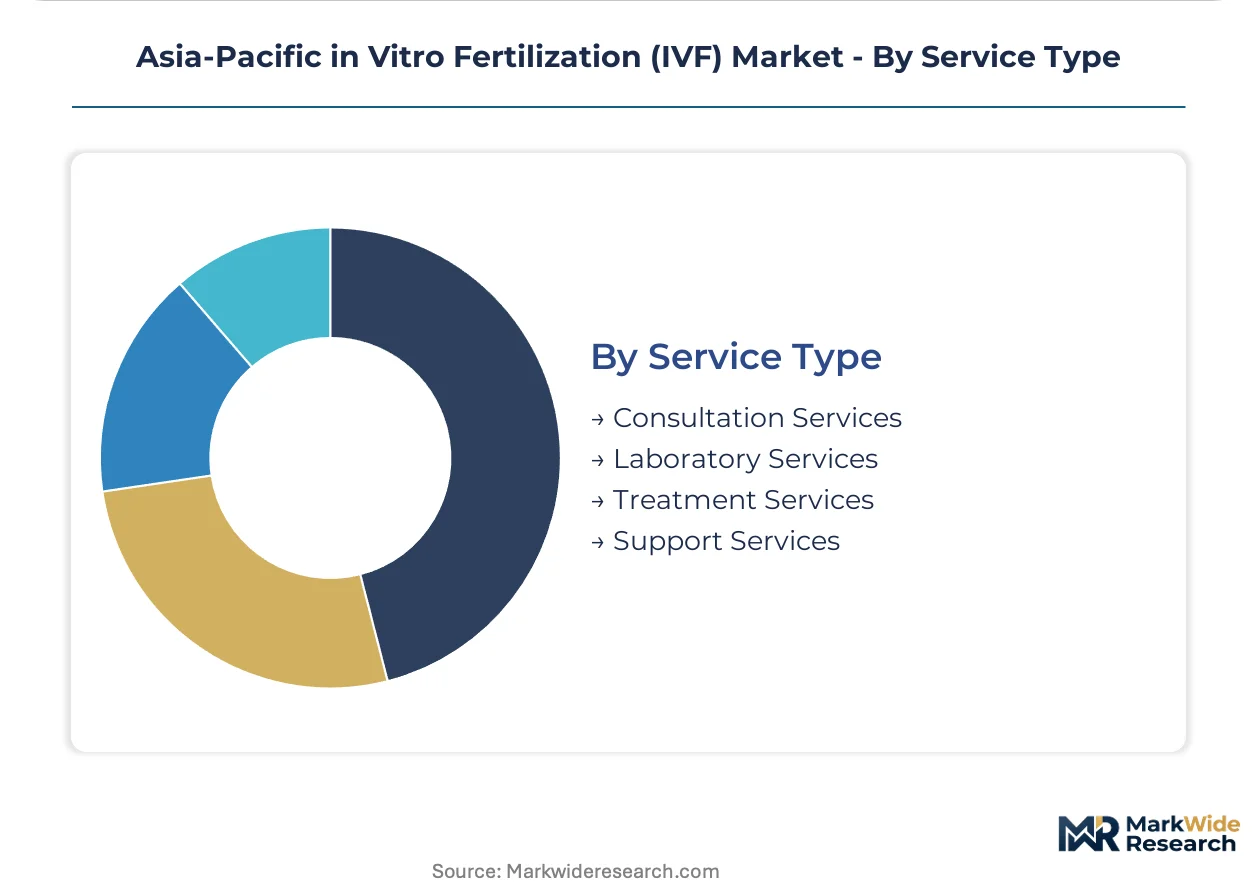
Service Type:
Margin concentration varies across professional consultation, technical laboratory execution, clinical treatment delivery, and ongoing patient support functions.
- Laboratory Services:Embryology operations including oocyte handling, sperm preparation, fertilization, culture, and cryopreservation. Australia's TGA-accredited networks maintain consistent standards across Virtus Health's multi-site operations, with ISO 15189 accreditation serving as a competitive filter.
- Treatment Services:Clinical procedures spanning ovarian stimulation monitoring, oocyte retrieval, embryo transfer, and pregnancy management. Max Healthcare's Delhi and Mumbai centers achieve scale economies through high-volume treatment protocols standardized under CDSCO oversight.
- Consultation Services:Initial fertility assessment, diagnostic workup, and treatment planning.
- Support Services:Counseling, nutritional guidance, and administrative coordination.
Laboratory Services hold installed capacity. Treatment Services are expanding most quickly as patient volumes concentrate in accredited high-volume centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Patient acquisition concentrates across metropolitan fertility corridors where CDSCO-registered clinics achieve scale economies through high-volume laboratory operations. India's 2021 Assisted Reproductive Technology Regulation Act is consolidating fragmented provider networks into accredited chains.
India
Mumbai, Delhi, and Bangalore corridors anchor demand concentration for IVF services as Max Healthcare and Bloom Fertility Center expand laboratory capacity. CDSCO mandates clinic registration and standardized outcome reporting under the 2021 ART Regulation Act. Delhi-NCR fertility networks achieve procurement scale for single-use media formulations through multi-site consolidation.
Australia
Virtus Health sustains consistent laboratory standards across its multi-site network through TGA-accredited quality management systems. Australia's Therapeutic Goods Administration streamlines approval pathways for advanced reproductive technologies while intensifying ISO 15189 accreditation requirements. Sydney and Melbourne fertility corridors capture complex cases requiring multidisciplinary oncology-fertility coordination.
Japan
Preimplantation genetic testing demand accelerates as PMDA revises notification requirements for PGT-A and PGT-M reimbursement. Japan's Pharmaceuticals and Medical Devices Agency framework evolution permits accredited laboratory networks to offer chromosomal screening as standard service. Tokyo and Osaka metropolitan clusters concentrate NGS-integrated embryology workflows.
South Korea
Hospital-affiliated IVF programs capture oncology fertility preservation referrals through MFDS-accredited cryopreservation infrastructure. South Korea's Ministry of Food and Drug Safety maintains stringent equipment validation timelines for vitrification systems. Seoul Capital Area fertility networks deploy time-lapse incubation platforms for algorithmic embryo assessment.
Thailand
Elective egg-freezing and medical fertility preservation drive service expansion in Bangkok and Phuket medical tourism corridors. Thailand's health ministry accreditation standards shape import dynamics for European and American culture media manufacturers. Hospital-based IVF programs differentiate through multidisciplinary care coordination for complex infertility cases.
Asia-Pacific in Vitro Fertilization (IVF) Market Competitive Landscape
Channel-controlling players compete with product-specialist players across accreditation-tiered market tiers. CDSCO and TGA regulatory modernization favors accredited laboratory networks with documented quality management infrastructure. Three archetypes dominate: multi-site fertility networks with standardized protocols, high-volume metropolitan clinic operators, and hospital-embedded programs with multidisciplinary capabilities. Competitive moves concentrate on geographic expansion into underpenetrated corridors and technology licensing for AI-integrated embryo selection platforms.
Within the multi-site network tier, Virtus Health and Max Healthcare exemplify channel-controlling archetypes through multi-jurisdiction laboratory standardization. Bloom Fertility Center occupies a specialist position focused on complex endocrinology protocols. These three entities anchor competitive dynamics as CDSCO and TGA accreditation requirements filter smaller operators from high-volume corridors.
| Leading Market Players |
|---|
| Virtus Health |
| Max Healthcare |
| Bourn Hall Fertility Center |
| Manipal Fertility |
| Bloom Fertility Center |
| Cloudnine Fertility |
| Chennai Fertility Center |
| IVF Australia |
| Singapore General Hospital |
| Others |
Supply & Pricing Matrix
European and American IVF media manufacturers anchor upstream supply concentration, directing margin capture toward clinics with volume-scale procurement leverage and multi-site consolidation in India's metropolitan fertility corridors.
Pricing Analysis
Cost-plus contracts with currency indexation dominate IVF media procurement between Indian fertility networks and European suppliers. Three-tier pricing structure across premium CDSCO-registered imports, standard TGA-aligned formulations, and economy unbranded alternatives stratifies the market. Pricing pressure stems from rupee volatility against euro-denominated supply agreements, compressing margins for standalone clinics lacking bulk negotiation scale. Hospital-affiliated IVF programs exhibit lowest price sensitivity due to captive procurement infrastructure, while independent fertility centers face acute cost exposure.
Supply Chain Analysis
Export-control regimes on advanced embryo imaging technologies limit flows of time-lapse incubation platforms from European manufacturers to Asia-Pacific markets. Supply concentrates in Germany, Denmark, and Japan for culture media formulations, vitrification systems, and NGS-integrated diagnostic platforms respectively. Cryopreservation equipment draws from single-source validation dependencies under South Korea's MFDS and Australia's TGA frameworks. Tariff exposure on liquid nitrogen storage infrastructure creates supply risk for clinic expansion timelines. Distribution runs through authorized distributor networks with CDSCO import licensing rather than direct manufacturer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
IVF incumbents must navigate substitution pressure from employer-sponsored fertility benefits redirecting patient volume toward managed care bundles and direct-to-consumer digital channels.
For Market Incumbents: Harden laboratory quality infrastructure through ISO 15189 accreditation investment, creating compliance barriers against unregistered competitors. Pursue backward integration into cryopreservation equipment servicing capabilities to reduce dependency on European manufacturer maintenance contracts. Channel control through employer benefit network contracts represents the critical defensive lever against digital-native entrants capturing patient acquisition.
For New Entrants and Emerging Players: Elective egg-freezing corridors in Vietnam and secondary Thai cities represent the most penetrable entry point for volume build before CDSCO registration mandates intensify. Oncology fertility preservation referrals within hospital networks offer embedded patient flow without standalone marketing expenditure. Go-to-market execution should prioritize MFDS-aligned equipment partnerships enabling immediate operational credibility.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed multi-site fertility networks approaching portfolio consolidation thresholds. Five-to-ten year viability hinges on PGT-A reimbursement expansion across Japanese and Australian regulatory frameworks. The signal to watch is CDSCO enforcement intensity against unregistered standalone clinics, which would accelerate accredited chain valuation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| AI Embryo Selection Platform Licensing | Machine learning integration with time-lapse imaging virtualizes morphological assessment, reducing multiple pregnancy liability. |
| CDSCO Registration Compliance Investment | India's 2021 ART Regulation Act mandates clinic registration, filtering fragmented providers from high-volume corridors. |
| Employer Benefit Network Contracting | Corporate health programs in India and Singapore concentrate patient volume through direct fertility network partnerships. |
| PGT-A Reimbursement Strategy | Japan's PMDA framework evolution on chromosomal screening coverage determines test volume expansion feasibility. |
| Cryopreservation Equipment Validation | MFDS and TGA accreditation for vitrification systems enables capture of oncology fertility preservation referrals. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of CDSCO registration databases, TGA device approval records, and hospital procurement contract disclosures across the Asia-Pacific region. Primary interviews engaged embryology laboratory directors, fertility clinic operations managers, reproductive endocrinologists, and medical device import distributors. Secondary validation drew from regulatory filings with India's CDSCO, Australia's TGA, Japan's PMDA, and South Korea's MFDS, supplemented by ISO 15189 accreditation registries and GPO contract databases. Bottom-up clinic capacity modeling triangulated against top-down media consumption estimates.
Forecast inputs span technology adoption curves for AI-integrated embryo selection, regulatory approval timelines for PGT-A expansion, and patient volume concentration in metropolitan fertility corridors. Segmentation dimensions include product type stratification, technology maturity tiers, end-user institutional categories, and service delivery models. CAGRs derive from installed base growth rates cross-referenced against procedure volume elasticity and pricing trajectory assumptions across the projection horizon. Cryopreservation infrastructure deployment cycles and embryologist training pipeline constraints shape capacity-bound growth modeling.
Macroeconomic conditions sit as an overlay; deviation in rupee-euro exchange rates, liquid nitrogen supply costs, or cross-border medical tourism flows would shift the trajectory. Forecasts reflect documented assumptions on regulatory enforcement intensity and reimbursement policy evolution. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Reproductive Health
Intrauterine Insemination (IUI) Treatment Market
Reproductive Health
Gamete Preservation Market
Reproductive Health
Global Male Infertility Market
Reproductive Health
Global Genital Herpes Treatment Market
Reproductive Health
US Sexual and Reproductive Health Clinics Market
Reproductive Health
Donor Egg IVF (in-Vitro Fertilization) Market
Reproductive Health
US Contraceptive Market
Reproductive Health
Doula and Birth Coaching Services Market
Reproductive Health
Europe in Vitro Fertilization (IVF) Market
Reproductive Health
Surrogacy Market
Reproductive Health
UK in Vitro Fertilization (IVF) Market
Reproductive Health
Hormonal Contraception Market
Reproductive Health
Smart Fertility Tracker Market
Reproductive Health
Global Cervical Dysplasia Market
Reproductive Health
US Long-Acting Contraception Market
Reproductive Health
Global Gynecology Drugs Market