
 Egg Freezing and Embryo Banking Market | 2026-2036
Egg Freezing and Embryo Banking Market Size, Share, and Industry Trends Forecast 2026-2036
Egg Freezing and Embryo Banking Market Analytics
North American fertility clinic networks are expanding storage capacity to meet rising patient volumes. Cryos International leverages its pan-European donor gamete logistics to sustain cross-border banking operations. ReproTech LLC anchors long-term cryostorage services for regional clinic partnerships. Kindbody competes through employer-sponsored fertility benefit channels that streamline patient access.
Egg freezing and embryo banking encompasses the cryopreservation of oocytes and embryos at sub-zero temperatures using vitrification or slow freezing protocols, typically involving cryoprotectant equilibration and liquid nitrogen storage at minus 196 degrees Celsius to preserve cellular viability for future fertilization or gestation. The practice serves fertility preservation for oncology patients, elective deferral of parenthood, and IVF cycle optimization. Vitrification dominates clinical workflows due to superior post-thaw survival rates compared to slow freezing methods. Fertility clinics represent the primary service delivery channel where margin pools concentrate around bundled retrieval-storage-thaw packages. Donor egg banking is gaining structural importance as cross-border reproductive care normalizes.
FDA regulates cryopreservation media as medical devices while CMS reimbursement policies shape patient out-of-pocket exposure for fertility services. HIPAA governs genetic data portability across state lines, complicating multi-site embryo transfers. EMA oversight of cryoprotectant biocompatibility affects European clinic procurement standards. Stakeholders must monitor evolving insurance mandates and storage term liability frameworks as patient cohorts age into utilization windows.
Market Dynamics
Vitrification protocols have displaced slow freezing as the clinical standard, compressing post-thaw survival variance and concentrating margin capture around high-throughput fertility hubs with liquid nitrogen infrastructure scale.
Growth Catalysts
- Delayed childbearing patterns:Single women in the United States are pursuing elective fertility preservation at expanding volumes, pulling clinic capacity expansion in metropolitan fertility corridors.
- Cross-border reproductive care normalization:Spain, the Czech Republic, and Denmark have established regulatory frameworks that attract international patients seeking donor gamete banking services.
- HIPAA portability requirements:Genetic data transfer mandates across state lines are forcing multi-site clinic networks to standardize cryostorage documentation protocols, improving patient mobility between facilities.
Market Restraints
- Liquid nitrogen supply concentration:Cryogenic infrastructure depends on regional industrial gas suppliers, creating vulnerability in storage continuity for remote clinic locations.
- FDA device classification overhead:Cryopreservation media regulation as medical devices imposes validation timelines and documentation burdens that constrain new market entrants.
- Long-duration storage liability:Extended cryostorage contracts expose clinics to decades of operational continuity risk without corresponding revenue recognition timing.
Strategic Opportunities
- Employer-sponsored benefit channels:Large corporations are integrating fertility preservation into health benefit packages, creating direct-to-patient access routes that bypass traditional referral networks.
- Oncology patient capture:Pre-chemotherapy fertility preservation represents an underpenetrated indication with established clinical pathways and reimbursement precedent in select markets.
- AI-assisted embryo grading convergence:Machine vision algorithms paired with time-lapse incubation systems are enabling automated viability assessment that reduces embryologist labor intensity.
Industry Challenges
- Embryologist talent scarcity:Specialized micromanipulation skills require years of training, constraining clinic expansion velocity in secondary markets.
- Storage facility capex intensity:Liquid nitrogen infrastructure and 24/7 monitoring systems demand substantial capital deployment with extended depreciation horizons.
- Multi-jurisdiction compliance complexity:Cross-border embryo transfer requires navigation of divergent genetic data governance frameworks and informed consent standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egg Freezing and Embryo Banking Market |
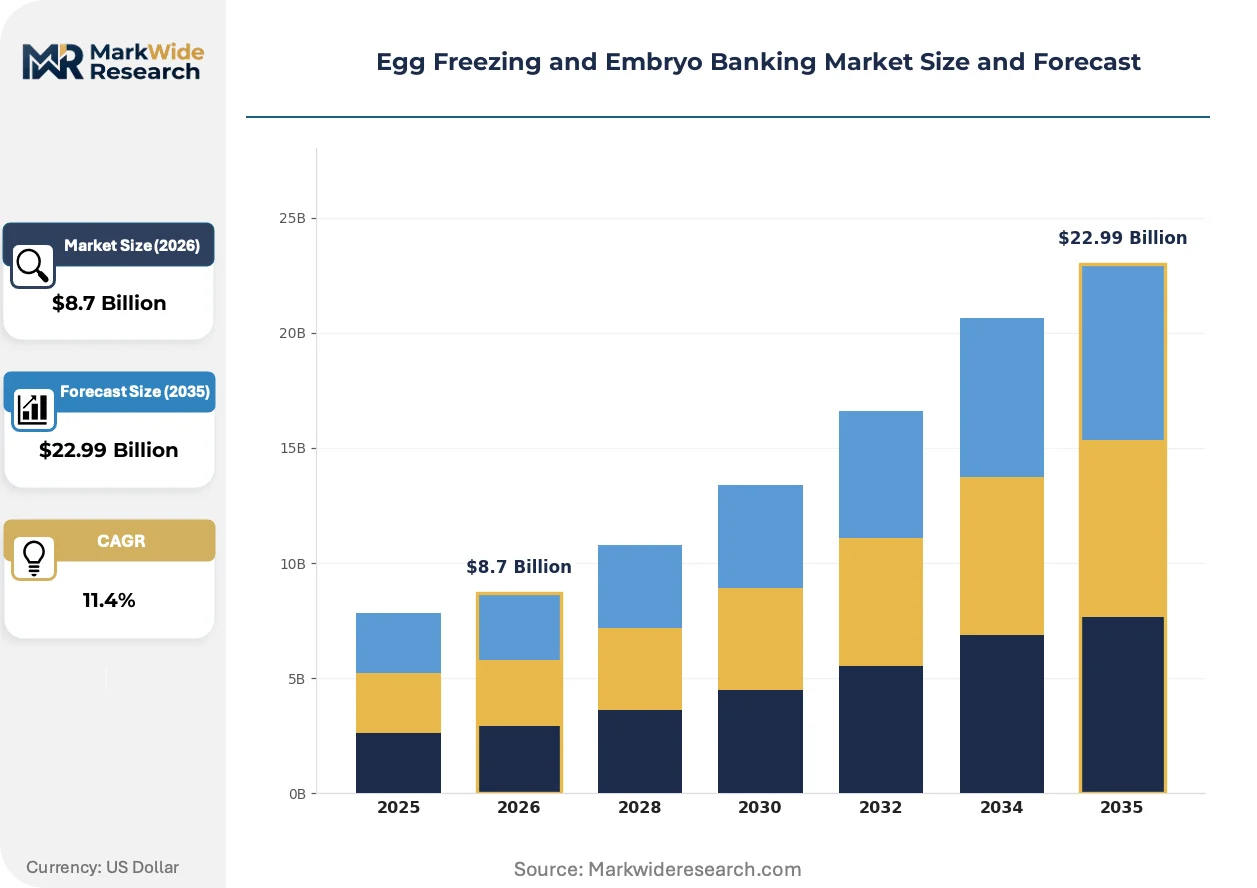
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Vitrification, Slow Freezing, Intracytoplasmic Sperm Injection, Cryopreservation Application: Fertility Preservation, IVF Treatment, Donor Egg Banking, Gender Selection End User: Fertility Clinics, Hospitals, Research Institutions, Private Laboratories Customer Type: Individuals, Couples, Same-Sex Couples, Single Women |
| Companies Covered | ReproTech LLC, Cryos International, CCRM Fertility, RMA Network, Carrot Fertility, WINFertility, Shady Grove Fertility, Kindbody, Extend Fertility, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egg Freezing and Embryo Banking Market Evolving Landscape
Automation and algorithmic decision support are penetrating embryology workflows, altering labor economics and quality standardization across fertility clinic operations.
Vitrification is absorbing the residual slow freezing volume in oocyte preservation workflows. High-volume fertility centers in the United States and Spain have completed protocol transitions, while smaller regional clinics are accelerating adoption to maintain competitive viability benchmarks. This technology shift is compressing the survival rate dispersion between elite and mid-tier facilities, eroding differentiation based on historical protocol expertise alone.
EMA oversight of cryoprotectant biocompatibility is tightening procurement specifications for European fertility clinics. The regulatory scrutiny is elevating documentation requirements for media composition and endotoxin testing, favoring suppliers with established quality management systems. German and Danish clinic networks are responding by consolidating vendor relationships around manufacturers with MDR-compliant technical files.
Direct employer contracting is displacing traditional insurance reimbursement pathways for fertility preservation services. Large technology and financial services employers in the United States are negotiating bundled rates with clinic networks, bypassing payer intermediaries. This channel shift is most visible in California and New York metropolitan corridors where employer density supports dedicated account management structures.
Egg Freezing and Embryo Banking Market Segmentation
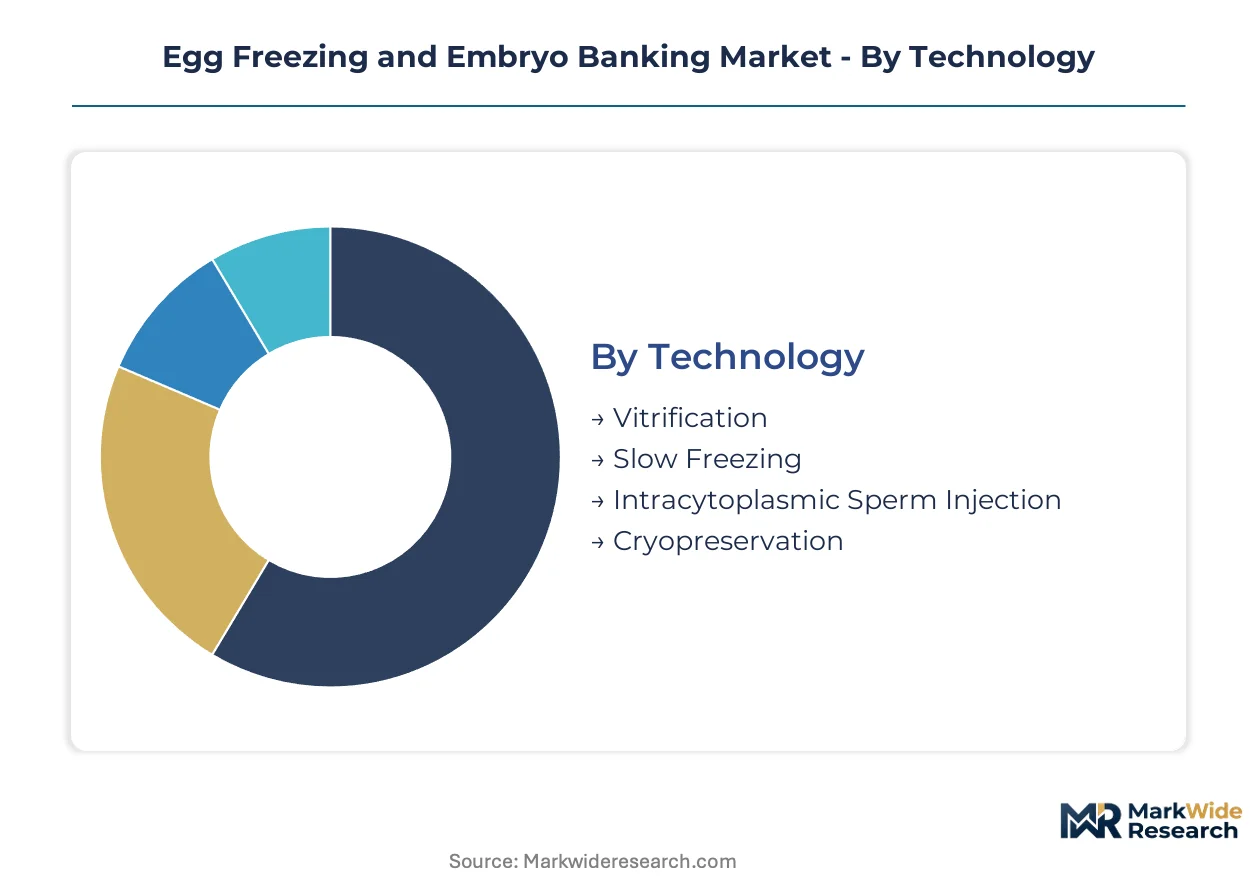
Segmentation in egg freezing and embryo banking reveals how capital deployment, regulatory exposure, and patient demographics concentrate margin pools across distinct service configurations. Understanding these partitions clarifies where infrastructure investments yield sustainable returns versus commoditized competition.
Technology:
Capital intensity varies sharply across preservation protocols, with infrastructure requirements dictating which segments attract scaled investment from multi-site clinic networks.
- Vitrification:Ultra-rapid cooling using high-concentration cryoprotectants eliminates ice crystal formation, achieving post-thaw survival rates above 90% for oocytes. Demand concentrates in high-throughput fertility hubs across Spain and the Czech Republic where liquid nitrogen infrastructure amortizes across large patient volumes. FDA oversight of cryoprotectant formulations as medical devices elevates compliance costs for new entrants.
- Slow Freezing:Controlled-rate cooling with permeating cryoprotectants remains relevant for embryo preservation in legacy clinic systems. Deployment persists in regional US clinics where equipment depreciation cycles have not yet triggered protocol conversion, though patient demand is shifting toward vitrification-based service bundles.
- Intracytoplasmic Sperm Injection:Micromanipulation technique for direct sperm delivery into oocytes prior to cryopreservation or immediate fertilization.
- Cryopreservation:General term encompassing all sub-zero temperature storage protocols using liquid nitrogen systems at minus 196 degrees Celsius.
Vitrification absorbs the bulk of installed capacity; slow freezing is contracting most rapidly as clinic networks consolidate around standardized protocols.
Application:
Revenue recognition timing diverges across indication types, with oncology-linked fertility preservation commanding premium pricing against elective deferral services.
- Fertility Preservation:Pre-chemotherapy or pre-radiation gamete banking for oncology patients represents a medically necessary indication with established reimbursement pathways in select US markets. Demand clusters around academic medical centers with integrated oncofertility programs, particularly in California and New York metropolitan corridors where employer-sponsored benefit density supports patient access.
- IVF Treatment:Embryo banking to optimize IVF cycle efficiency through batch fertilization and elective single embryo transfer. Concentration in Denmark and Spain reflects cross-border patient mobility seeking donor gamete compatibility with cryostorage continuity.
- Donor Egg Banking:Cryopreserved donor oocyte inventory enabling asynchronous recipient matching and reduced treatment coordination friction.
- Gender Selection:Preimplantation genetic testing combined with embryo banking for family balancing purposes, restricted to jurisdictions permitting non-medical sex selection.
IVF treatment captures the largest revenue share; fertility preservation is climbing the fastest as oncology clinic integration deepens.
End User:
Facility type determines regulatory burden intensity and patient volume scalability, with fertility clinics operating under specialized laboratory certification requirements distinct from hospital accreditation frameworks.
- Fertility Clinics:Dedicated reproductive medicine facilities with embryology laboratories, retrieval suites, and cryostorage infrastructure. Margin pools concentrate here around bundled retrieval-storage-thaw service packages.
- Hospitals:Academic medical centers and community hospital systems with obstetrics-gynecology departments offering fertility preservation alongside oncology services.
- Research Institutions:University-affiliated laboratories conducting gamete biology research and protocol development under institutional review board oversight.
- Private Laboratories:Independent reference laboratories providing cryostorage services without direct patient care responsibilities.
Fertility clinics command dominant patient volume; hospitals are expanding service lines fastest through oncofertility program integration.
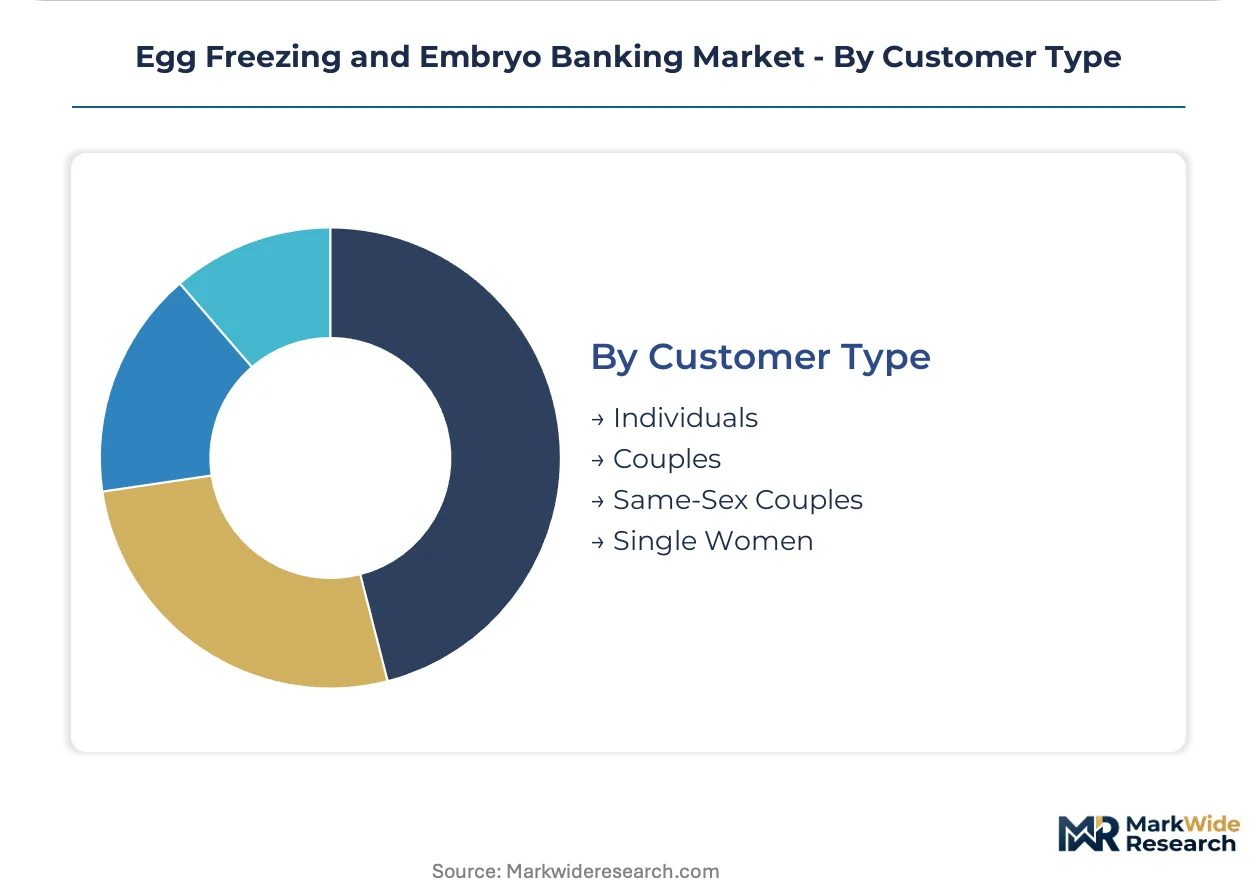
Customer Type:
Patient demographic composition shapes marketing expenditure allocation and service bundling architecture across direct-to-consumer and employer-sponsored channels.
- Individuals:Single patients pursuing fertility preservation without partner coordination requirements, typically electing oocyte banking over embryo creation.
- Couples:Heterosexual partnerships utilizing embryo banking for IVF cycle optimization or future family planning flexibility.
- Same-Sex Couples:Male couples requiring donor oocytes with surrogacy coordination; female couples accessing reciprocal IVF with dual genetic contribution options.
- Single Women:Demographic segment driving elective fertility preservation volume expansion in US metropolitan markets, particularly among technology and financial services professionals with employer-sponsored benefit access.
Single women represent the steepest expansion trajectory; couples retain the largest absolute patient base across established clinic networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Liquid nitrogen supply corridors from industrial gas producers in the US Gulf Coast and North Sea anchor cryogenic infrastructure deployment for fertility preservation services.
United States
Single women in technology and financial services sectors drive elective egg freezing volumes in California and New York metropolitan corridors. FDA oversight of cryopreservation media as medical devices elevates compliance costs for new clinic entrants. Boston's academic medical centers integrate oncofertility programs with established chemotherapy coordination pathways.
Spain
Cross-border reproductive care patients from across Europe seek donor gamete banking services in Barcelona and Madrid fertility hubs. EMA oversight of cryoprotectant biocompatibility shapes procurement specifications for Spanish clinic networks. Andalusian fertility centers leverage cost advantages to attract international patients seeking asynchronous donor matching.
Czech Republic
Prague-based fertility clinics capture Central European demand for affordable vitrification services with English-language patient coordination. The country's national pharmaceutical regulator enforces cryostorage facility licensing standards that exceed neighboring jurisdictions. Brno's emerging clinic clusters benefit from lower operational costs while maintaining EU MDR-compliant quality systems.
Denmark
Copenhagen fertility centers specialize in donor sperm and oocyte banking with progressive regulatory frameworks enabling open-identity donor programs. GDPR genetic data governance requirements complicate cross-border embryo transfers from Danish storage facilities. Aarhus university hospitals conduct clinical research on vitrification protocol optimization for oncology patient populations.
United Kingdom
London fertility clinics face storage capacity constraints as ten-year legal limits on embryo retention pressure demand for extension legislative reform. The Human Fertilisation and Embryology Authority licenses cryostorage facilities with inspection regimes that influence clinic network expansion decisions. Manchester and Birmingham regional centers develop satellite retrieval capabilities to reduce patient travel burdens.
Egg Freezing and Embryo Banking Market Competitive Landscape
Global majors compete with regional champions across cryogenic logistics and clinic service delivery, producing a tiered structure where scale-driven storage operators coexist with metropolitan fertility specialists. The vendor base organizes around three archetypes: pan-European donor gamete logistics platforms, employer-sponsored benefit channel intermediaries, and regional long-term cryostorage specialists. Dominant competitive moves include fertility clinic network consolidation through acquisition and direct employer contracting arrangements that bypass traditional insurance reimbursement pathways.
Among US-based fertility service providers, Kindbody and Extend Fertility exemplify employer-sponsored benefit channel strategies, while ReproTech LLC anchors the long-term cryostorage specialist archetype with regional clinic partnership models. Cryos International occupies a position representing pan-European donor gamete logistics scale, leveraging cross-border reproductive care normalization to sustain banking operations across multiple jurisdictions.
| Leading Market Players |
|---|
| ReproTech LLC |
| Cryos International |
| CCRM Fertility |
| RMA Network |
| Carrot Fertility |
| WINFertility |
| Shady Grove Fertility |
| Kindbody |
| Extend Fertility |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up fertility clinic specialists have consolidated metropolitan networks across the United States, compressing vendor negotiation leverage while standardizing bundled retrieval-storage-thaw pricing across acquired assets. This ownership concentration feeds directly into supply procurement discipline and service-tier unbundling strategies that shape patient out-of-pocket exposure.
Pricing Analysis
Warranty and long-term storage service bundling separates premium fertility hubs from mid-tier competitors, with elite clinics incorporating decade-long cryostorage guarantees into upfront package pricing while regional players unbundle storage renewals. Three-tier pricing structure across premium, standard, and economy levels reflects embryologist experience tiers and facility accreditation status rather than protocol differences. Cost compression in the economy tier is intensifying because liquid nitrogen infrastructure amortization favors high-volume operators. Employer-sponsored benefit channels exhibit lowest price sensitivity due to direct contracting arrangements, whereas self-pay single women in secondary metropolitan markets demonstrate highest sensitivity to unbundled storage fees.
Supply Chain Analysis
Regional distribution centers for cryoprotectant media operate through hub-and-spoke patterns anchored in industrial gas corridors from the US Gulf Coast and North Sea production clusters. Manufacturing concentration for vitrification media rests in Germany, the United States, and Japan, with MDR-compliant and FDA-registered facilities commanding procurement preference from clinic networks. Liquid nitrogen supply draws from regional industrial gas suppliers with single-source vulnerability in remote clinic locations. Distribution runs through specialized cold-chain logistics providers with 24-hour temperature monitoring requirements. Tariff exposure on cryoprotectant chemical precursors from China creates input cost volatility for European formulation facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market sits in active protocol transition as vitrification displaces residual slow freezing capacity, creating asymmetric returns for operators with completed infrastructure conversion versus legacy-dependent competitors.
For Market Incumbents: Deploy embryologist training pipelines as the primary lever to constrain expansion velocity by mid-tier competitors facing talent scarcity. Consolidate vendor relationships around MDR-compliant cryoprotectant manufacturers to preempt EMA documentation requirements. Defend against AI-assisted embryo grading entrants by embedding time-lapse incubation systems into standard service bundles before algorithmic pricing erodes embryologist labor premiums. For New Entrants and Emerging Players: Employer benefits administrators represent the most penetrable channel partner type for bypassing traditional insurance reimbursement friction. Target oncology patient capture at academic medical centers with underdeveloped oncofertility coordination pathways. Geographic white space exists in secondary US metropolitan markets where liquid nitrogen infrastructure gaps have stalled incumbent expansion. Pursue direct-to-employer contracting models that mirror Kindbody's benefit channel architecture. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional cryostorage specialists with established liquid nitrogen infrastructure and underutilized capacity in fertility hub adjacencies. Long-term viability hinges on 5-10 year storage contract liability management and utilization rate trajectories as deferred-parenthood cohorts age into thaw windows. Monitor FDA device classification enforcement intensity as inflection indicator for new entrant cost barriers and incumbent margin protection.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Assisted Embryo Grading Integration | Machine vision algorithms from Israeli and US developers reduce embryologist labor intensity in high-throughput Spanish and Czech clinics. |
| Direct Employer Benefit Channel Expansion | Technology and financial services employers in California and New York metropolitan corridors bypass payer intermediaries through bundled rate negotiations. |
| Cryostorage Infrastructure Consolidation | Liquid nitrogen facility scale economies favor acquisition of regional specialists by multi-site networks seeking depreciation leverage. |
| Oncofertility Program Integration | Academic medical centers in Boston and Aarhus deepen chemotherapy coordination pathways for pre-radiation gamete banking capture. |
| Cross-Border Regulatory Compliance Investment | German and Danish clinic networks consolidate around MDR-compliant cryoprotectant suppliers to preempt EMA biocompatibility enforcement. |
Research Methodology
Independent corroboration across fertility clinic operations executives, embryology laboratory directors, employer benefits administrators, and cryogenic logistics specialists underwrites the qualitative findings in this study. Primary interviews with these stakeholders combined with secondary validation from FDA 510(k) device filings, EMA MDR technical documentation, CMS reimbursement policy bulletins, and fertility clinic network SEC disclosures establish demand-side and supply-side triangulation. Bottom-up patient volume modeling and top-down market sizing approaches converge on segment-level estimates.
Rate-of-change decomposition across the analysis window separates volume expansion from pricing trajectory and mix-shift effects. Segmentation dimensions modeled include preservation protocol technology, clinical application indication, facility type certification tier, and patient demographic composition. CAGRs derive from logistic adoption curves for vitrification protocol penetration and cohort-based utilization assumptions for deferred-parenthood populations. Industry-specific forecast inputs incorporate liquid nitrogen infrastructure deployment timelines and employer-sponsored benefit adoption rates.
Caveats apply where FDA device reclassification, EMA MDR enforcement intensity shifts, or liquid nitrogen supply disruptions could materially shift the outlook. Forecasts reflect documented assumptions regarding protocol transition velocity and cross-border patient mobility patterns. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Reproductive Health
Donor Egg IVF (in-Vitro Fertilization) Market
Reproductive Health
Germany in Vitro Fertilization (IVF) Market
Reproductive Health
Smart Fertility Tracker Market
Reproductive Health
Cryopreservation for in-Vitro Fertilization (IVF) Market
Reproductive Health
Gamete Preservation Market
Reproductive Health
US Contraceptive Market
Reproductive Health
Egg Donation Market
Reproductive Health
In Vitro Fertilization (IVF) Market
Reproductive Health
IVF Services Market
Reproductive Health
Assisted Reproductive Technology (ART) Market
Reproductive Health
Global Male Infertility Market
Reproductive Health
Asia-Pacific in Vitro Fertilization (IVF) Market
Reproductive Health
Pregnancy Care Products Market
Reproductive Health
Contraceptives Market
Reproductive Health
US Long-Acting Contraception Market
Reproductive Health
Global Genital Herpes Treatment Market