
 Germany in Vitro Fertilization (IVF) Market | 2026-2036
Germany in Vitro Fertilization (IVF) Market Size, Share, and Industry Trends Forecast 2026-2036
Germany in Vitro Fertilization (IVF) Market Insights
Buyer concentration among fertility clinics is repositioning as hospital-affiliated centers absorb independent practices and consolidate referral networks. VivaNeo leverages its multi-site clinic platform to sustain geographic coverage across German metropolitan regions. EMD Serono anchors pharmaceutical supply for ovarian stimulation protocols through dedicated gonadotropin portfolios. Heidelberg University Hospital competes on integrated research-to-treatment pathways that differentiate academic fertility programs from commercial operators.
In vitro fertilization encompasses laboratory-based fertilization of oocytes with sperm outside the body, followed by embryo culture for two to six days before uterine transfer, with success rates critically dependent on maternal age and embryo grading systems. The procedure serves primarily to overcome tubal factor infertility, male factor infertility, and unexplained infertility where conventional treatments fail. Frozen embryo transfer now leads product type segments due to improved cryopreservation viability and reduced ovarian hyperstimulation risks, while ICSI dominates technology utilization for male factor indications. Telehealth delivery mode segments show fastest structural expansion as remote monitoring reduces clinic visit burdens for rural patients.
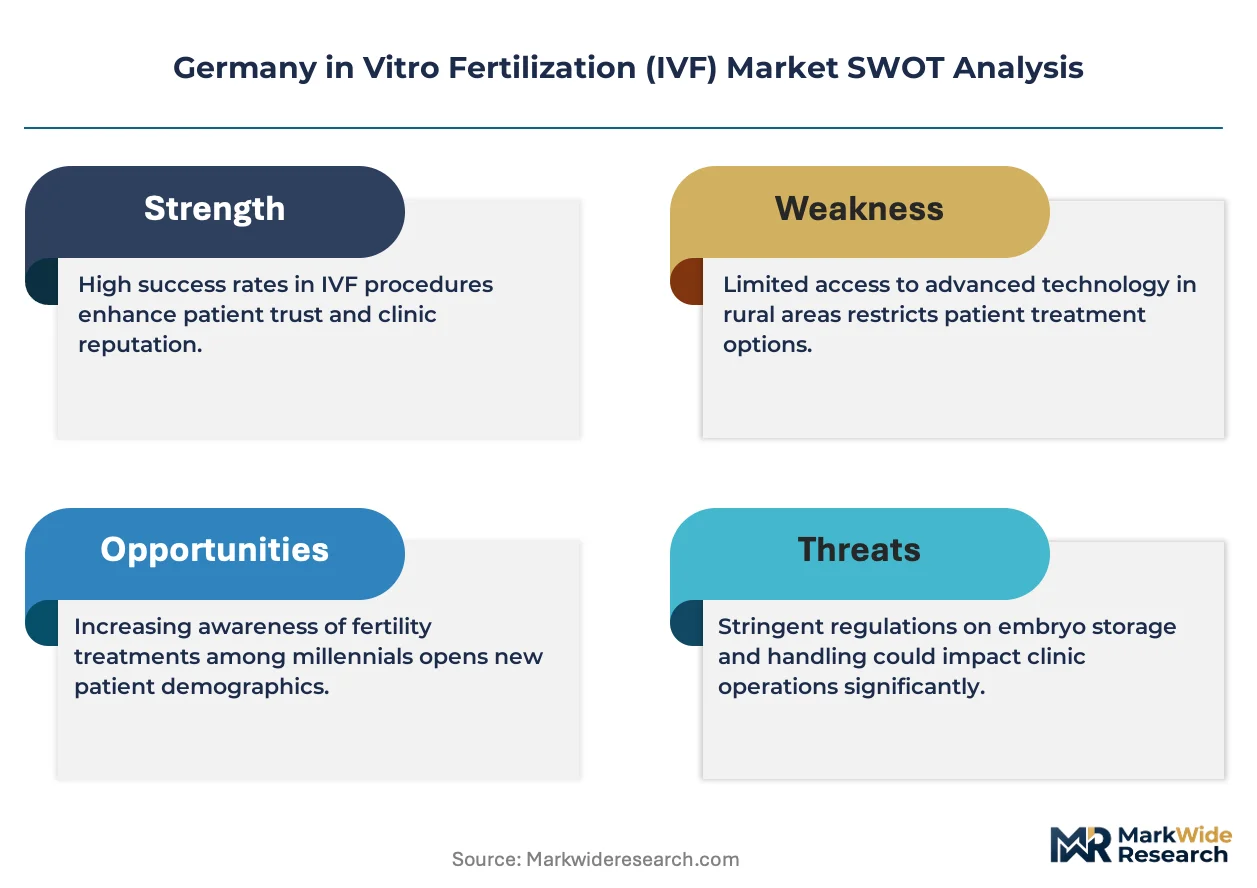
German IVF practice operates under the Embryonenschutzgesetz, which restricts embryo selection and preimplantation genetic testing to specific diagnostic indications, while the German Medical Association maintains quality standards through its directive on assisted reproduction. The Federal Joint Committee (G-BA) determines reimbursement scope for statutory health insurance, directly shaping patient access and clinic revenue stability. Stakeholders must monitor whether regulatory liberalization of embryo testing or expanded insurance coverage emerges as the more probable demand catalyst.
Market Dynamics
Hospital-affiliated fertility centers in Berlin and Munich are absorbing independent practices, consolidating referral networks and reshaping competitive positioning across German metropolitan regions.
Growth Catalysts
- Expanded Patient Demographics:Single women and same-sex couples now represent the fastest-growing patient segment seeking assisted reproductive services in German fertility clinics.
- Telehealth Integration:Remote monitoring protocols are reducing clinic visit burdens for rural patients, expanding geographic access beyond traditional metropolitan clusters.
- Cryopreservation Advances:Improved embryo freezing viability has elevated frozen embryo transfer to the dominant product type, lowering ovarian hyperstimulation risks.
Market Restraints
- Embryonenschutzgesetz Restrictions:The German Embryo Protection Act limits embryo selection and preimplantation genetic testing to narrow diagnostic indications, constraining clinical flexibility.
- G-BA Reimbursement Control:The Federal Joint Committee determines statutory health insurance coverage scope, creating revenue instability for clinic operators.
- Specialist Concentration:Fertility expertise clusters near academic medical complexes in Berlin and Munich, leaving secondary cities underserved.
Strategic Opportunities
- ICSI Technology Expansion:Intracytoplasmic sperm injection dominates male factor infertility treatment, with room for protocol refinement and outcome optimization.
- Eastern Germany Penetration:Cities like Leipzig and Dresden show rising demand but limited specialized center density.
- Research-to-Treatment Pathways:Academic fertility programs can differentiate through integrated clinical trial access and experimental protocol offerings.
Industry Challenges
- Embryologist Talent Pipeline:Specialized laboratory training programs struggle to produce sufficient certified embryologists for expanding clinic networks.
- Regulatory Compliance Burden:The German Medical Association's directive on assisted reproduction requires continuous quality documentation, stretching administrative resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany in Vitro Fertilization (IVF) Market |
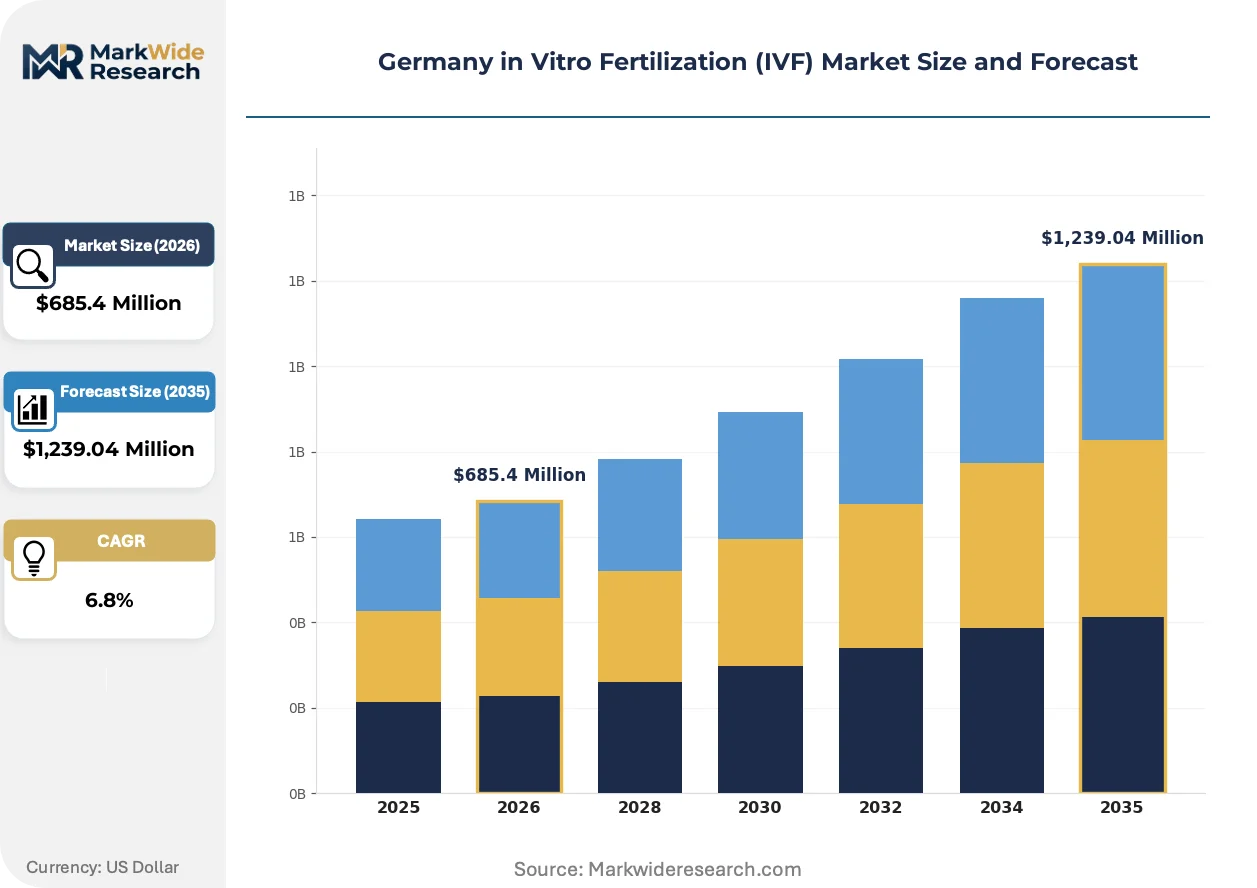
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh Embryo Transfer, Frozen Embryo Transfer, Egg Donation, Sperm Donation Technology: ICSI, IVF, Preimplantation Genetic Testing, Cryopreservation End User: Fertility Clinics, Hospitals, Research Institutions, Home Care Delivery Mode: In-Person, Telehealth, Mobile Applications, Traditional Clinics |
| Companies Covered | Bayer AG, VivaNeo, EMD Serono, Cook Medical, Ferring, Thermo Fisher Scientific, Vitrolife, Heidelberg University Hospital, University Medical Center Freiburg, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany in Vitro Fertilization (IVF) Market Trends and Innovations
Automation and remote care delivery are compressing traditional clinic-based workflows, while regulatory pressure on embryo handling protocols intensifies scrutiny of laboratory practices.
Time-lapse embryo imaging is automating morphokinetic assessment, replacing manual daily embryo checks. Fertility centers in Hamburg and Cologne are adopting these systems to standardize grading consistency. The technology is automating labor-intensive laboratory steps, freeing embryologists for complex micromanipulation procedures.
The Embryonenschutzgesetz shapes how German clinics approach embryo culture and transfer decisions. Restrictions on embryo selection limit competitive differentiation through genetic screening services. Academic medical centers respond by emphasizing non-selective embryo quality optimization through culture medium innovations.
Patients increasingly initiate fertility consultations through digital health platforms before physical clinic visits. Telehealth channels are disrupting traditional referral pathways from gynecology practices. This pattern concentrates in Bavaria and Baden-Württemberg, where rural patient populations face significant travel distances to specialized centers.
Germany in Vitro Fertilization (IVF) Market Segmentation
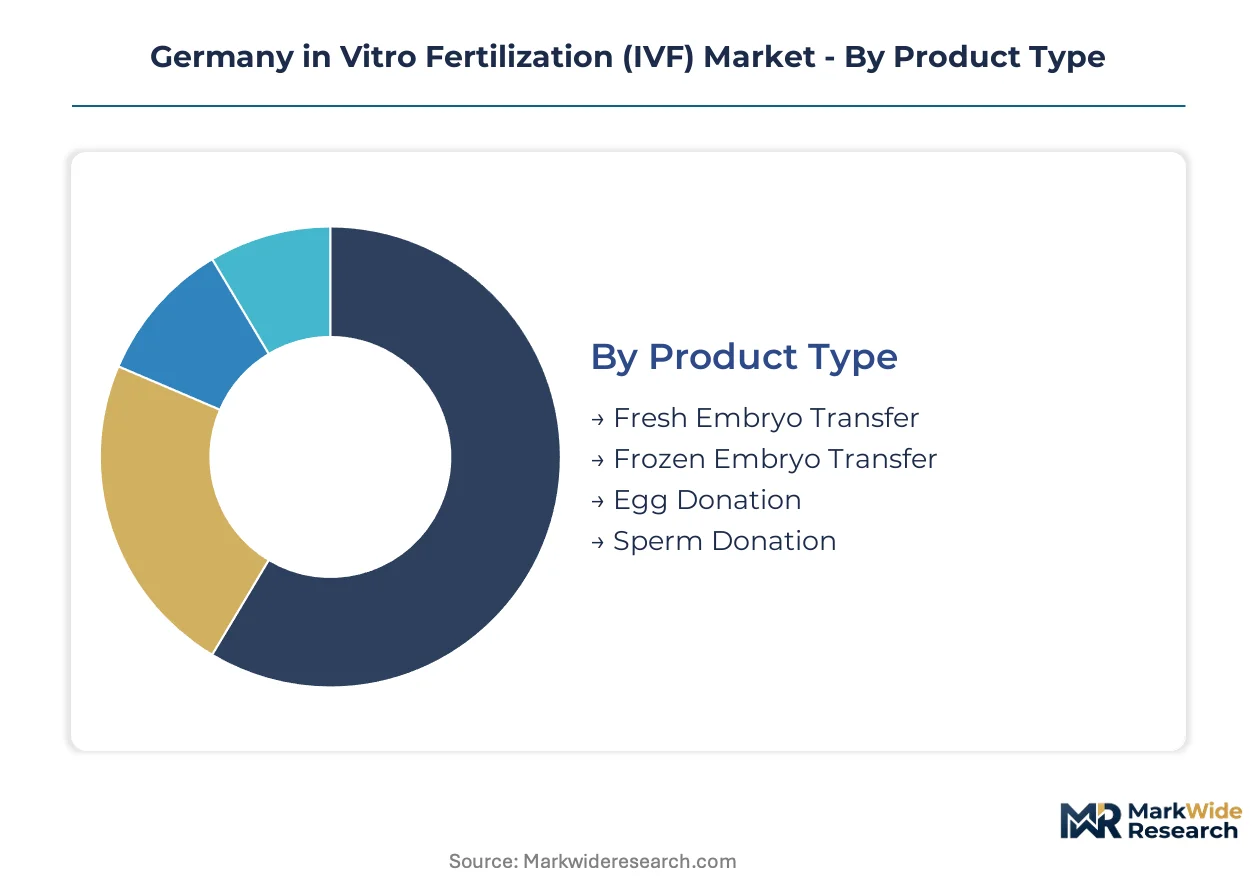
German IVF market segmentation reveals how clinical practice splits between established hospital-based protocols and emerging decentralized care models. Understanding these divisions exposes where reimbursement policy, regulatory constraints, and patient demographics concentrate commercial opportunity.
Product Type:
Supply concentration among metropolitan fertility centers in Berlin and Munich drives differential adoption rates across embryo handling protocols.
- Frozen Embryo Transfer:Vitrification-based cryopreservation preserves embryos at ultra-low temperatures for deferred uterine transfer. Bavarian fertility networks report highest utilization rates as ovarian hyperstimulation syndrome avoidance gains clinical priority. The Embryonenschutzgesetz permits extended culture monitoring before transfer decisions.
- Fresh Embryo Transfer:Immediate post-fertilization embryo placement within the same ovarian stimulation cycle. Rhineland-Palatinate and Hesse clinics maintain significant fresh transfer volumes for younger patient cohorts with robust ovarian response profiles.
- Egg Donation:Third-party oocyte procurement for patients with diminished ovarian reserve. German regulatory framework restricts commercial compensation, limiting donor pool expansion.
- Sperm Donation:Cryopreserved donor insemination for single women and same-sex couples. Hamburg and Frankfurt sperm banks coordinate national distribution networks.
Today's leader: Frozen Embryo Transfer. Tomorrow's challenger: Egg Donation.
Technology:
Cost tier differentiation separates premium micromanipulation platforms from standard fertilization protocols across German clinic networks.
- ICSI:Single sperm microinjection directly into ooplasm for severe male factor infertility. Academic medical centers in Heidelberg and Tübingen refine injection pipette angles and piezo-assisted techniques.
- Preimplantation Genetic Testing:Embryo biopsy with chromosomal or monogenic disorder screening. The Embryonenschutzgesetz restricts testing to explicit diagnostic indications, compressing addressable patient volume.
- IVF:Conventional insemination placing sperm and oocytes in shared culture medium. Standard protocol for tubal factor and unexplained infertility across statutory-insured patient base.
- Cryopreservation:Gamete and embryo freezing infrastructure supporting deferred fertility preservation. Berlin oncology centers coordinate fertility preservation for cancer patients prior to gonadotoxic therapy.
ICSI commands current procedural volume. Preimplantation Genetic Testing faces steepest expansion trajectory if regulatory liberalization emerges.
End User:
Application concentration determines where pharmaceutical stimulation protocols and laboratory disposables generate recurring revenue streams.
- Fertility Clinics:Specialized reproductive medicine centers performing complete IVF cycles from ovarian stimulation through embryo transfer. North Rhine-Westphalia hosts densest clinic concentration outside Berlin-Munich axis.
- Hospitals:Academic medical center fertility departments integrating research protocols with clinical service. University Hospital Cologne and Charité Berlin compete on experimental treatment access.
- Research Institutions:Basic science and clinical trial infrastructure advancing embryo culture medium formulations and non-invasive viability assessment.
- Home Care:Patient-administered gonadotropin injections and telehealth-monitored stimulation protocols reducing clinic visit frequency.
Fertility Clinics anchor current procedure economics. Home Care represents the fastest-climbing engagement model as remote monitoring technology matures.
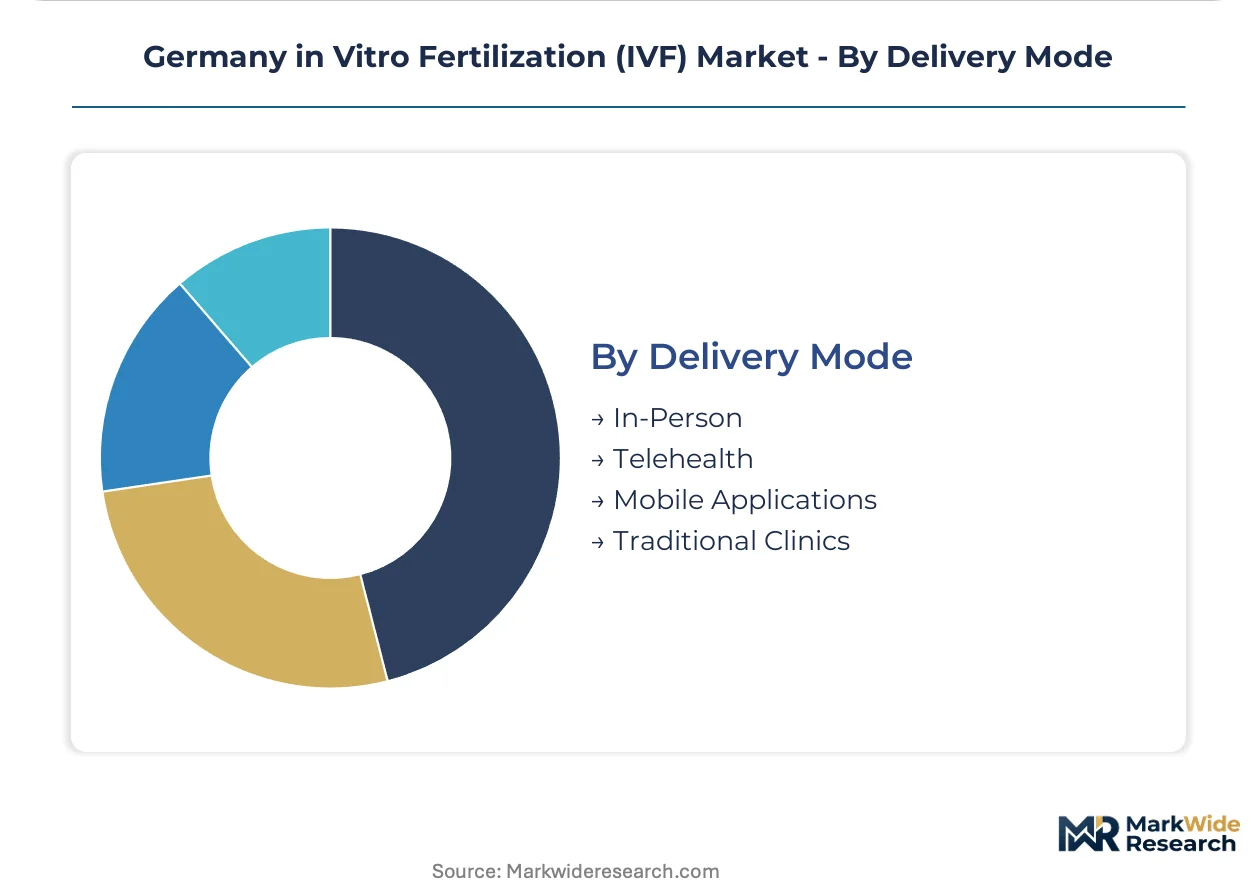
Delivery Mode:
Geographic reach constraints shape how rural patient populations access specialized reproductive services beyond metropolitan clusters.
- Telehealth:Remote consultation, stimulation monitoring, and pregnancy surveillance via secure video platforms. Baden-Württemberg rural districts show highest adoption as travel distances to Stuttgart and Freiburg centers exceed 150 kilometers.
- In-Person:Traditional clinic-based consultation and procedure delivery requiring physical presence for ultrasound monitoring and embryo transfer.
- Mobile Applications:Patient-facing software for medication adherence tracking, symptom reporting, and cycle calendar management.
- Traditional Clinics:Established brick-and-mortar fertility centers with full embryology laboratory and surgical suite infrastructure.
In-Person delivery retains procedural dominance. Telehealth gains share fastest where G-BA reimbursement clarity stabilizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized embryologists and reproductive endocrinologists concentrate in German metropolitan medical clusters, creating uneven geographic access to fertility services across the federal republic.
Bavaria
Munich anchors the densest fertility center concentration outside Berlin, with university-affiliated hospitals absorbing independent practices into consolidated referral networks. The Embryonenschutzgesetz shapes clinical protocols at Ludwig Maximilian University Hospital, where time-lapse imaging systems standardize embryo grading. Bavarian fertility networks report highest frozen embryo transfer utilization rates as ovarian hyperstimulation avoidance gains priority.
North Rhine-Westphalia
Cologne and Düsseldorf host significant clinic density serving the Rhine-Ruhr population corridor, with University Hospital Cologne competing on experimental treatment access. The Federal Joint Committee's reimbursement determinations directly shape patient access across statutory-insured populations in this industrial heartland. Telehealth adoption accelerates in rural districts where travel distances to specialized centers exceed 100 kilometers.
Baden-Württemberg
Heidelberg and Tübingen academic medical centers refine ICSI micromanipulation techniques, attracting male factor infertility referrals from across southern Germany. The German Medical Association's quality documentation requirements stretch administrative resources at mid-sized Stuttgart clinics. Rural districts show highest telehealth consultation rates as patients initiate fertility journeys through digital platforms before physical visits.
Berlin-Brandenburg
Charité Berlin integrates research protocols with clinical fertility services, differentiating through clinical trial access unavailable at commercial operators. Single women and same-sex couples represent the fastest-growing patient demographic seeking assisted reproductive services in the capital region. Fertility preservation coordination with oncology centers serves cancer patients prior to gonadotoxic therapy.
Hamburg
Sperm bank networks coordinate national distribution from Hamburg facilities, serving single women and same-sex couples across northern Germany. The city's fertility centers balance research integration with commercial service delivery. Harbor logistics infrastructure supports cryopreserved gamete import logistics for donor programs operating under restrictive German compensation regulations.
Germany in Vitro Fertilization (IVF) Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across pharmaceutical supply, laboratory equipment, and clinical service delivery. Hospital-affiliated centers absorb independent practices, consolidating referral networks and compressing margins for standalone operators. Three archetypes dominate: multinational pharmaceutical suppliers, multi-site clinic platforms, and academic medical center programs. M&A activity concentrates among metropolitan fertility networks, while technology licensing agreements proliferate for cryopreservation and embryo imaging systems.
Within the pharmaceutical supply tier, Bayer AG and EMD Serono anchor gonadotropin and stimulation protocol portfolios. VivaNeo occupies a position as the multi-site clinic platform exemplar, sustaining geographic coverage across German metropolitan regions through distributed center networks. Heidelberg University Hospital represents the academic medical center archetype, competing on integrated research-to-treatment pathways that differentiate university fertility programs from commercial operators.
| Leading Market Players |
|---|
| Bayer AG |
| VivaNeo |
| EMD Serono |
| Cook Medical |
| Ferring |
| Thermo Fisher Scientific |
| Vitrolife |
| Heidelberg University Hospital |
| University Medical Center Freiburg |
| Others |
Pricing and Supply Chain Analysis
Gonadotropin pharmaceutical costs cascade from EMD Serono and Ferring manufacturing facilities through hospital-affiliated fertility centers to statutory-insured patients, with the Federal Joint Committee's reimbursement determinations compressing margins at each pricing tier downstream.
Pricing Analysis
The bundled-versus-unbundled service split distinguishes academic medical center pricing from commercial clinic structures. Three-tier pricing structure across premium, standard, and economy levels separates research-integrated programs from high-volume operators and basic statutory-covered cycles. Price differentiation hinges on embryologist certification grade and geographic delivery cost to rural districts. Cost compression in the economy tier is intensifying because G-BA reimbursement ceilings constrain clinic operators. Single women and same-sex couples demonstrate highest price sensitivity, while oncology fertility preservation patients show lowest sensitivity due to time-critical decision frameworks.
Supply Chain Analysis
Single-source vulnerability sits with Danish and Swiss pharmaceutical manufacturers dominating gonadotropin active ingredient supply. Laboratory equipment draws from Germany, Japan, and the United States, while culture media formulations rest on Swedish and Australian specialty chemical producers. Raw material dependencies include recombinant FSH proteins, vitrification cryoprotectants, and micromanipulation pipettes. Tariff exposure on Chinese-manufactured imaging sensors creates procurement risk for time-lapse embryo monitoring systems. Distribution runs through hospital procurement consortia and direct clinic contracts with limited wholesale intermediary presence.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The German IVF market functions as a regulatory compounder where Embryonenschutzgesetz restrictions on embryo selection and preimplantation genetic testing create pent-up demand that would accelerate rapidly under any liberalization milestone.
For Market Incumbents: Anticipate telehealth reimbursement clarity from the Federal Joint Committee as the decisive margin inflection point. Defensive consolidation moves should prioritize absorbing independent practices in Leipzig and Dresden before hospital networks capture eastern Germany referral pathways. Backward integration into cryopreservation logistics infrastructure secures supply chain control against single-source vulnerabilities in vitrification technology. For New Entrants and Emerging Players: Remote patient monitoring platforms offer a technology-first wedge into Baden-Württemberg rural districts where travel distances exceed 150 kilometers to Stuttgart and Freiburg centers. White-space targets include home care stimulation protocols and digital fertility preservation counseling for oncology networks. The most penetrable segment spans single women and same-sex couples seeking sperm bank coordination through telehealth channels. A go-to-market angle emphasizing G-BA reimbursement navigation support differentiates against established clinic operators. For Investors and Strategic Acquirers: Consolidation pressure builds where hospital-affiliated centers absorb independent practices and compress standalone operator margins across metropolitan clusters. Long-term viability over a multi-year horizon favors platforms with integrated research-to-treatment pathways and geographic diversification beyond Berlin-Munich concentration. Acquisition target archetypes include mid-sized clinics with embryologist talent pipelines and established G-BA reimbursement contracts. The signal to watch as inflection indicator is any Federal Joint Committee movement toward telehealth service reimbursement expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Telehealth Reimbursement Strategy | G-BA coverage expansion would unlock rural patient access beyond metropolitan clusters. |
| Embryologist Training Pipeline Investment | Certified laboratory talent scarcity constrains clinic network expansion capacity. |
| Research-to-Treatment Pathway Integration | Academic medical centers differentiate through clinical trial access unavailable commercially. |
| Cryopreservation Logistics Infrastructure | In-house vitrification capabilities reduce single-source dependency on Danish suppliers. |
| Eastern Germany Geographic Expansion | Leipzig and Dresden show rising demand with limited specialized center density. |
Research Methodology
Bottom-up fertility clinic procedure modeling reconciled against top-down pharmaceutical supply tracking forms the analytical core of this study. Primary interviews with reproductive endocrinologists, embryology laboratory directors, hospital procurement managers, and G-BA reimbursement specialists combined with secondary validation from German Medical Association directives, Federal Joint Committee coverage determinations, and statutory health insurance claims databases. Triangulation between demand-side patient flow analysis and supply-side gonadotropin shipment tracking ensures cross-verified volume estimates.
Input-output matrices map ovarian stimulation protocol costs through embryo transfer completion rates across the projection horizon. Segmentation dimensions modeled include product type, technology utilization, end-user facility category, and delivery mode, with regional regulatory clusters capturing Embryonenschutzgesetz interpretation variance across federal states. CAGRs were derived from trend extrapolation of historical procedure volumes adjusted for demographic shift projections and reimbursement policy scenarios. Forecast inputs incorporate maternal age distribution shifts and cryopreservation viability improvement curves.
The model holds under stable Embryonenschutzgesetz interpretation and G-BA reimbursement scope; deviation in regulatory liberalization or statutory coverage expansion would shift demand trajectories substantially. Forecasts reflect documented assumptions regarding telehealth adoption curves and pharmaceutical pricing stability. Specific risk factors include embryologist training pipeline constraints and potential G-BA reimbursement compression. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Reproductive Health
Global Male Infertility Market
Reproductive Health
Surrogacy Market
Reproductive Health
Contraceptives Market
Reproductive Health
Europe in Vitro Fertilization (IVF) Market
Reproductive Health
Gamete Preservation Market
Reproductive Health
US Birth Centers Market
Reproductive Health
Doula and Birth Coaching Services Market
Reproductive Health
Egg Freezing and Embryo Banking Market
Reproductive Health
Donor Egg IVF Services Market
Reproductive Health
In Vitro Fertilization (IVF) Market
Reproductive Health
IVF Services Market
Reproductive Health
Smart Fertility Tracker Market
Reproductive Health
Asia-Pacific in Vitro Fertilization (IVF) Market
Reproductive Health
US Sexual and Reproductive Health Clinics Market
Reproductive Health
Pregnancy Care Products Market
Reproductive Health
Ovum Egg Banking Market