
 Gamete Preservation Market | 2026-2036
Gamete Preservation Market Size, Share, and Industry Trends Forecast 2026-2036
Gamete Preservation Market Analysis
Asset-light leasing models for cryogenic storage infrastructure are rewriting competitive economics in gamete preservation. CooperSurgical leverages its broad distribution network to sustain clinical partnerships across North America. Vitrolife AB anchors its position through specialized media formulations for embryo culture. Thermo Fisher Scientific competes by extending its life sciences portfolio into assisted reproductive technology consumables.
Gamete preservation encompasses the cryogenic storage of sperm, oocytes, and embryos at temperatures below minus 196 degrees Celsius using cryoprotectant media to maintain cellular viability for future fertilization procedures. The process serves fertility treatment deferral, oncology patient fertility preservation, and donor gamete banking for third-party reproduction. Cryopreservation dominates the method landscape due to established protocols and regulatory familiarity, while vitrification captures the fastest growth trajectory as clinics adopt ultra-rapid freezing to reduce ice crystal formation. Oocytes and sperm represent the most actively banked product types, with embryo preservation generating premium margins where legal frameworks permit extended storage.
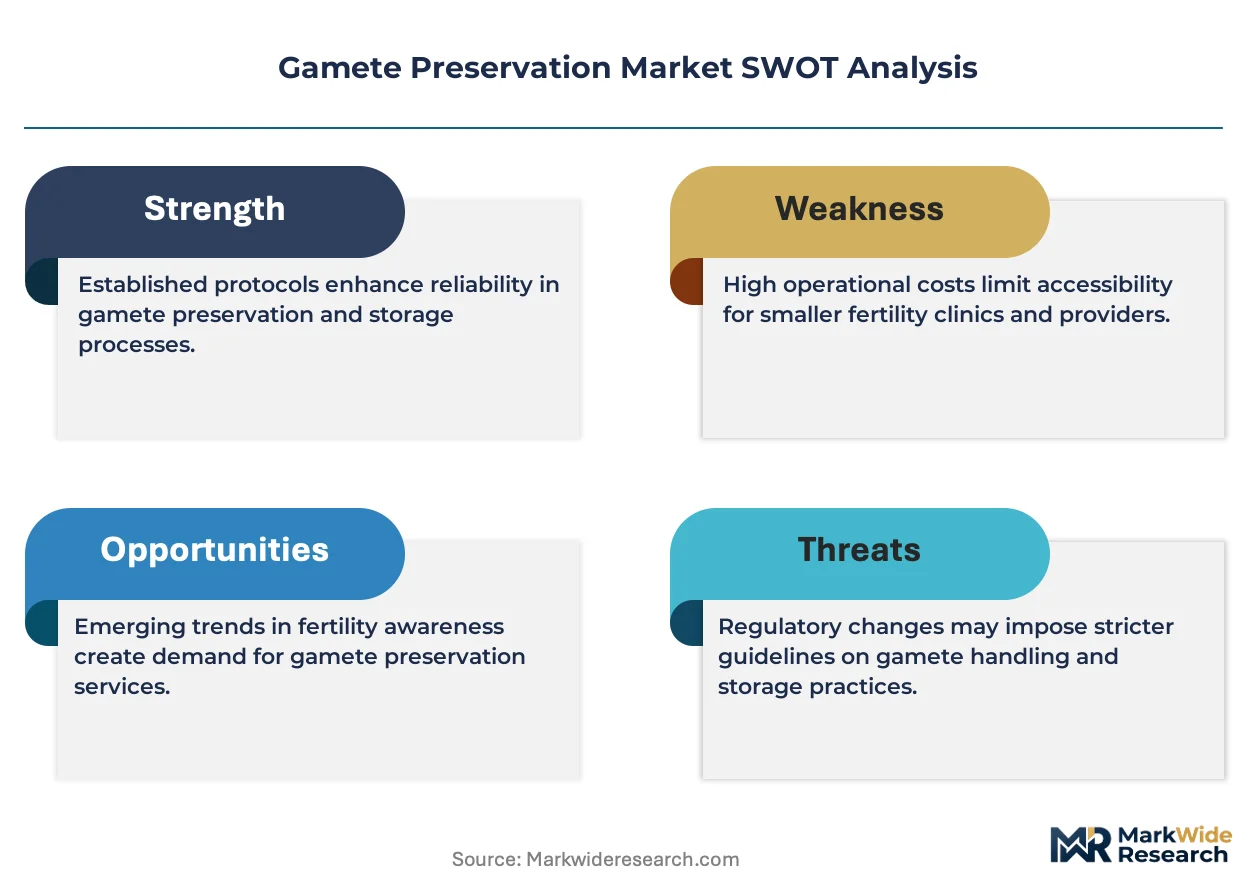
The FDA's human cells, tissues, and cellular and tissue-based products regulations govern donor screening and infectious disease testing in the United States, while the EMA and national competent authorities enforce the EU Tissues and Cells Directive across European member states. These frameworks elevate compliance costs but also create barriers that favor accredited laboratories and licensed cryobanks over informal operators. Stakeholders must monitor evolving storage duration limits and genetic testing requirements as jurisdictions reassess the ethical and legal boundaries of long-term gamete and embryo holding.
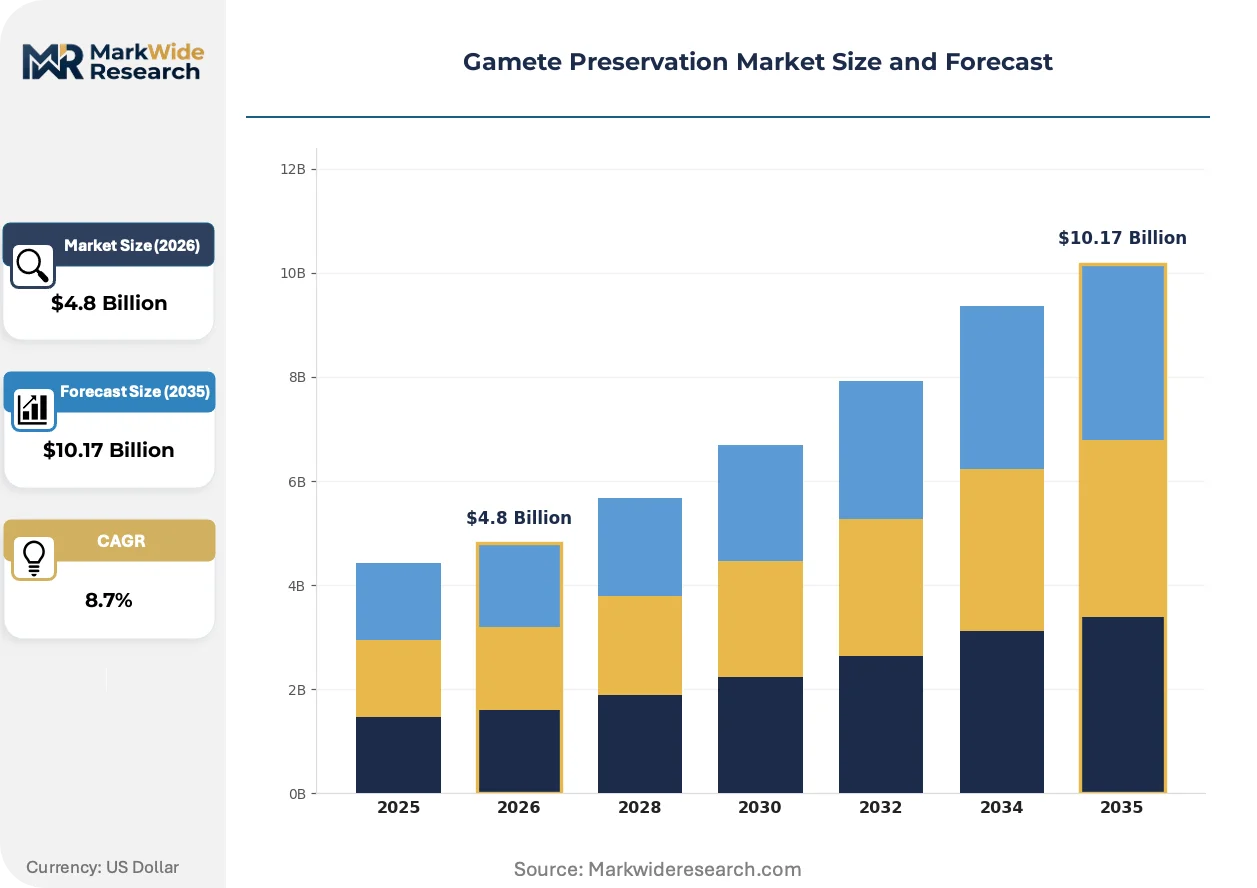
Market Dynamics
The transition from slow-freeze cryopreservation to vitrification protocols is compressing protocol development cycles and forcing cryobanks to requalify storage infrastructure. This technological inflection point is reshaping capital allocation across the preservation services value chain.
Growth Catalysts
- Oncology patient protocols:Fertility preservation counseling is now standard-of-care before gonadotoxic cancer therapy, creating baseline demand for oocyte and sperm banking services.
- Delayed parenthood demographics:Elective egg freezing among professionals in their early thirties is expanding addressable market beyond medical necessity into lifestyle segments.
- EU Tissues and Cells Directive harmonization:Cross-border recognition of accredited cryobank certifications is reducing friction for patients seeking treatment in neighboring member states.
Market Restraints
- Liquid nitrogen supply concentration:Industrial gas production clusters in Germany and the United States create vulnerability for cryobanks dependent on continuous cryogen replenishment.
- FDA donor screening burden:Infectious disease testing requirements for anonymous sperm donors elevate compliance costs and extend qualification timelines for new donor programs.
- Embryo storage duration caps:Legal limits on maximum holding periods in several jurisdictions force premature disposal cycles and compress recurring revenue streams.
Strategic Opportunities
- Home collection kits:At-home sperm preservation sampling with courier transport to processing labs is opening geographic access beyond clinic catchment areas.
- ART tourism corridors:Patients from jurisdictions with restrictive embryo research laws are traveling to Spain and the Czech Republic for extended storage and research-linked disposal options.
- AI-assisted embryo grading:Machine vision algorithms for morphokinetic assessment are converging with time-lapse incubation systems to improve selection efficiency.
Industry Challenges
- Embryologist certification bottlenecks:Specialized training programs for vitrification technique mastery are scarce, constraining clinic expansion capacity.
- Legacy inventory migration:Cryobanks holding slow-frozen gametes from prior decades face technical and ethical complexity in converting storage formats or contacting dormant clients.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gamete Preservation Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Method: Cryopreservation, Vitrification, Fresh Collection, Slow Freezing Application: Fertility Treatments, Gender Selection, Research Purposes, Egg Donation End User: Hospitals, Fertility Clinics, Research Laboratories, Universities Product Type: Oocytes, Sperm, Embryos, Others |
| Companies Covered | Vitrolife AB, CooperSurgical, Cook Medical, Fairfax Cryobank, Cryos International, California Cryobank, Genea Biomedx, FUJIFILM Irvine Scientific, Thermo Fisher Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gamete Preservation Market Emerging Trajectories
Vitrification is displacing established slow-freeze protocols across fertility networks, while regulatory frameworks tighten traceability requirements and patient self-service models erode traditional clinic gatekeeping.
Closed vitrification devices with pre-filled cryoprotectant media are migrating from boutique research clinics toward high-volume commercial laboratories. Large cryobank networks in the United States and Spain are adopting these systems to standardize technician-independence and reduce variability in post-thaw survival rates. The technology is migrating from premium positioning toward operational baseline, compressing margins on conventional open-system consumables.
The EU's revised Tissues and Cells Directive implementation is mandating unique donor identification codes and centralized traceability registries across member states. Cryobanks must now maintain interoperable data systems for cross-border gamete movement. Spanish and Danish fertility centers with established international patient flows are investing in compliance infrastructure ahead of enforcement deadlines.
Direct-to-consumer subscription models for long-term embryo and oocyte storage are fragmenting the traditional clinic-cryobank relationship. Patients in California and New York are increasingly contracting preservation services independently of their treating fertility center, then transporting gametes between facilities based on pricing and storage terms. This disintermediation pressures clinic-affiliated cryobanks to unbundle storage from treatment cycles.
Gamete Preservation Market Segmentation
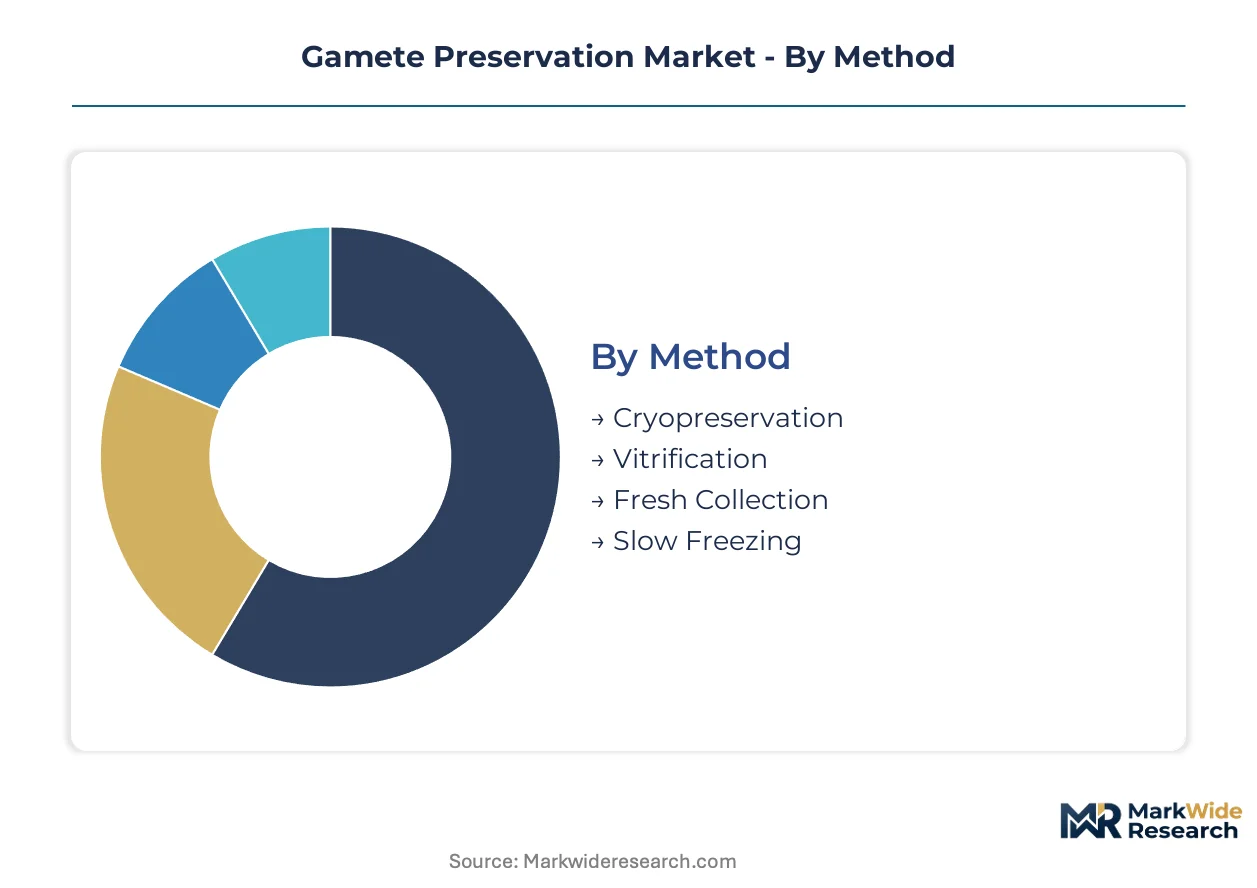
Segmentation in gamete preservation reveals distinct operational rhythms across preservation methods, clinical applications, and institutional buyers. Each dimension carries implications for capital deployment, regulatory exposure, and margin structure that shape competitive positioning.
Method:
Cryopreservation cycles span years while vitrification protocols turn over monthly as clinics requalify technicians and validate new device formats.
- Cryopreservation:Controlled-rate freezing with cryoprotectant permeation remains the dominant infrastructure base across established cryobank networks. Demand concentrates in legacy donor sperm repositories and oncology preservation programs where protocol familiarity reduces training burden.
- Vitrification:Ultra-rapid cooling eliminates ice crystal formation through high-concentration cryoprotectant exposure and direct liquid nitrogen immersion. Spanish and Czech fertility centers are adopting closed-system devices fastest, driven by cross-border patient flows seeking higher post-thaw survival rates.
- Fresh Collection:Immediate-use gamete retrieval without cryogenic holding serves same-cycle IVF procedures where transport logistics permit.
- Slow Freezing:Gradual temperature reduction protocols persist in resource-constrained settings with limited liquid nitrogen access.
Cryopreservation anchors the volume base while vitrification gains share at the steepest rate.
Application:
Cost tiers separate emergency oncology preservation from elective lifestyle banking, with research applications occupying a distinct funding structure.
- Fertility Treatments:IVF cycle support and deferred parenthood planning generate recurring cryostorage revenue streams across multi-year holding periods. United States fertility networks are consolidating storage contracts into subscription models.
- Gender Selection:Preimplantation genetic testing combined with embryo preservation serves family balancing demand in jurisdictions permitting non-medical sex selection.
- Research Purposes:Academic and commercial R&D access to de-identified gamete specimens operates under institutional review board oversight with distinct informed consent requirements.
- Egg Donation:Third-party oocyte banking for anonymous recipient matching requires extended donor screening protocols and traceability systems.
Fertility treatments anchor the volume base while gender selection gains share at the steepest rate where regulatory frameworks permit.
End User:
Customer type determines procurement sophistication, with hospitals integrating preservation into broader oncology service lines while standalone clinics optimize for cycle throughput.
- Fertility Clinics:Specialized reproductive medicine centers perform the majority of elective oocyte and embryo banking procedures. United States metropolitan markets show concentration of multi-site clinic networks competing on storage pricing.
- Hospitals:Academic medical centers anchor oncology fertility preservation through integrated oncofertility programs with mandatory pre-chemotherapy counseling protocols.
- Research Laboratories:Commercial and academic R&D facilities access gamete specimens under material transfer agreements with distinct chain-of-custody requirements.
- Universities:Institutional repositories support longitudinal reproductive biology studies with extended specimen holding needs.
Fertility clinics anchor the volume base while hospitals gain share at the steepest rate as oncofertility standard-of-care expands.
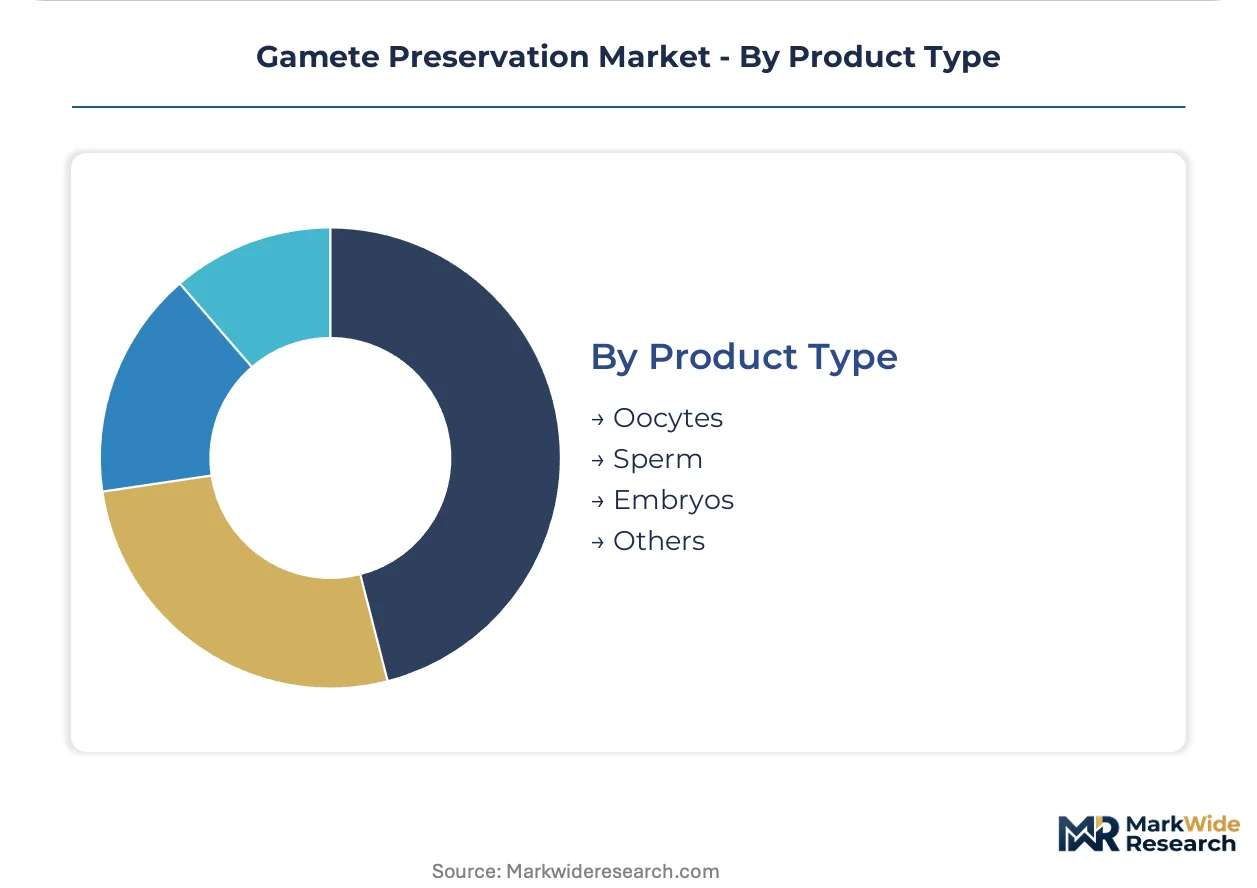
Product Type:
Margin structure varies sharply across cellular complexity, with oocyte preservation commanding premium pricing due to technical difficulty and lower post-thaw survival baselines.
- Oocytes:Immature and mature egg cryopreservation requires specialized vitrification expertise given membrane permeability challenges and spindle assembly sensitivity. Elective egg freezing demand from professionals in their early thirties is expanding addressable market beyond medical necessity.
- Embryos:Fertilized oocyte preservation generates premium storage revenue where legal frameworks permit extended holding, though duration caps in several jurisdictions force premature disposal cycles.
- Sperm:Male gamete banking benefits from established cryoprotectant protocols and higher post-thaw viability rates across both medical and donor indications.
- Others:Ovarian tissue and testicular tissue cryopreservation serves prepubertal oncology patients lacking mature gamete production.
Sperm anchors the volume base while oocytes gain share at the steepest rate as elective egg freezing normalizes among delayed parenthood demographics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reimbursement policy divergence is redrawing competitive maps in gamete preservation. Countries with fertility treatment coverage mandates generate volume concentration, while jurisdictions with restrictive embryo research laws push demand across borders.
United States
Large cryobank networks in California and New York dominate storage capacity for elective egg freezing. FDA tissue donation rules govern donor screening and infectious disease testing protocols. Boston and San Francisco metropolitan clusters anchor oncofertility program integration with academic medical centers.
Spain
Barcelona and Madrid fertility centers capture cross-border patient flows seeking extended embryo storage options. The EU Tissues and Cells Directive mandates unique donor identification codes and centralized traceability registries. Spanish clinics are investing in compliance infrastructure ahead of enforcement deadlines for cross-border gamete movement.
Denmark
Copenhagen-based cryobank operations serve international donor sperm demand with established logistics networks. National competent authorities enforce EU tissue directives with additional domestic quality standards. The Øresund Region concentration supports coordinated storage and distribution across Scandinavian markets.
United Kingdom
London clinic networks are consolidating storage contracts into subscription models independent of treatment cycles. Human Fertilisation and Embryology Authority regulations cap embryo storage durations and mandate licensed facility operations. Research corridors in Cambridge and Oxford maintain institutional repositories for longitudinal reproductive biology studies.
Czech Republic
Prague fertility centers attract patients from jurisdictions with restrictive embryo research laws for research-linked disposal options. National implementation of EU tissue directives proceeds with transitional periods for legacy inventory. Brno medical technology clusters support cryopreservation device manufacturing and protocol development.
Gamete Preservation Market Vendor Landscape
On the supply side, the industry is consolidating around multi-site cryobank networks and diversified life sciences conglomerates. Three strategic archetypes dominate: specialized reproductive media formulators, integrated fertility service platforms, and broad-based laboratory consumables suppliers. M&A activity targets geographic footprint expansion and cryogenic logistics capabilities. Technology licensing partnerships are proliferating for closed-system vitrification device formats.
Within the specialized media tier, Vitrolife AB and FUJIFILM Irvine Scientific exemplify formulators anchoring clinical partnerships through proprietary cryoprotectant compositions. CooperSurgical occupies a position bridging consumables manufacturing with direct clinical service delivery. Thermo Fisher Scientific represents the diversified conglomerate archetype, leveraging scale advantages in laboratory infrastructure to extend into assisted reproductive technology segments.
| Leading Market Players |
|---|
| Vitrolife AB |
| CooperSurgical |
| Cook Medical |
| Fairfax Cryobank |
| Cryos International |
| California Cryobank |
| Genea Biomedx |
| FUJIFILM Irvine Scientific |
| Thermo Fisher Scientific |
| Others |
Supply Flow & Price Mechanics
Liquid nitrogen production clusters in Germany and the United States concentrate cryogen supply for cryobanks, anchoring margin pools in cryogenic logistics and storage infrastructure ownership rather than in clinical service delivery. This upstream concentration forces downstream operators to absorb transport cost volatility or invest in captive liquefaction capacity.
Pricing Analysis
Certification level creates the primary spread across storage tiers, with FDA-registered and EU-accredited facilities commanding premium rates over unlicensed operators. Three-tier pricing structure separates premium vitrification services from standard slow-freeze protocols and economy-grade donor sperm repositories. Cost compression in economy tiers is intensifying as direct-to-consumer subscription models force clinic-affiliated cryobanks to unbundle storage from treatment cycles. Fertility clinics show highest price sensitivity due to reimbursement pressure, while elective egg freezing patients demonstrate lowest sensitivity to annual storage fees.
Supply Chain Analysis
Export-control restrictions on cryoprotectant formulations and closed-system vitrification devices limit technology flows between the United States, European Union, and China. Manufacturing concentrates in Germany, the United States, and Japan for precision cryogenic equipment and specialized media formulations. Raw material dependencies include liquid nitrogen, dimethyl sulfoxide cryoprotectants, and medical-grade aluminum storage canisters. Single-source vulnerability runs through industrial gas production sites in Germany and the US Gulf Coast. Distribution runs through cryobank network hubs with regional satellite storage facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vitrification technique mastery represents a binding constraint on clinic expansion capacity, with embryologist certification programs failing to keep pace with protocol adoption curves. This skill scarcity rewards early movers who secure training partnerships and technician pipelines.
For Market Incumbents: Build regulatory moats through pre-positioned compliance infrastructure for EU Tissues and Cells Directive traceability requirements. Cryobank networks should secure dual-sourcing agreements for liquid nitrogen supply before industrial gas production disruptions materialize. Incumbent laboratories must invest in closed-system vitrification device qualification to defend against open-system commoditization. For New Entrants and Emerging Players: Geographic underpenetration in Central and Eastern European fertility markets offers expansion corridors with limited established cryobank presence. Home collection kits for sperm preservation represent the most penetrable segment, bypassing clinic gatekeeping through direct-to-consumer logistics. New entrants should pursue courier-network partnerships with existing diagnostic laboratory infrastructure rather than building de novo cold chain capabilities. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed multi-site clinic platforms seeking geographic roll-up opportunities. Long-term viability hinges on regulatory consolidation favoring accredited operators over informal preservation services. Acquisition targets should demonstrate established cross-border patient flows and compliant traceability systems. The signal to watch is enforcement action against unlicensed cryobank operators in major metropolitan markets.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-System Vitrification Device Adoption | Standardizes technician-independent protocols across high-volume commercial laboratories in Spain and Czech Republic. |
| EU Tissues and Cells Directive Compliance Investment | Enables cross-border gamete movement through interoperable data systems and unique donor identification codes. |
| Home Collection Kit Launch | Expands geographic access beyond clinic catchment areas through courier transport to processing labs. |
| Liquid Nitrogen Supply Dual-Sourcing | Mitigates vulnerability from industrial gas production concentration in Germany and United States. |
| AI-Assisted Embryo Grading Integration | Converges machine vision algorithms with time-lapse incubation systems for improved selection efficiency. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured interviews with fertility clinic medical directors, cryobank operations managers, embryology laboratory supervisors, and reproductive endocrinologists. Secondary validation drew from FDA tissue donation guidance documents, EU Tissues and Cells Directive implementation reports, hospital procurement databases for oncofertility services, and GPO contracts for assisted reproductive technology consumables. Bottom-up and top-down triangulation reconciled procedure volume estimates with cryogenic storage capacity data.
Calibration anchored forward projections to observed protocol transition rates from slow-freeze to vitrification across major fertility networks. The analytical framework modeled segmentation dimensions including preservation method, product type, end-user institution, and regional regulatory cluster. CAGRs were derived from fitted growth curves applied to baseline procedure volumes. Industry-specific forecast inputs incorporated delayed parenthood demographic trends and oncology patient fertility preservation protocol penetration rates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by diversified life sciences conglomerates into cryogenic logistics would shift outcomes. Material shifts in embryo storage duration regulations or liquid nitrogen supply disruptions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Reproductive Health
US Long-Acting Contraception Market
Reproductive Health
Ovum Egg Banking Market
Reproductive Health
Europe in Vitro Fertilization (IVF) Market
Reproductive Health
Global Male Infertility Market
Reproductive Health
Germany in Vitro Fertilization (IVF) Market
Reproductive Health
Intrauterine Insemination (IUI) Treatment Market
Reproductive Health
Donor Egg IVF Services Market
Reproductive Health
Hormonal Contraception Market
Reproductive Health
Global Gynecology Drugs Market
Reproductive Health
Pregnancy Care Products Market
Reproductive Health
UK in Vitro Fertilization (IVF) Market
Reproductive Health
Donor Egg IVF (in-Vitro Fertilization) Market
Reproductive Health
IVF Services Market
Reproductive Health
US Contraceptive Market
Reproductive Health
In Vitro Fertilization (IVF) Market
Reproductive Health
Cervical Dysplasia Treatment Market