
 Cervical Dysplasia Treatment Market | 2026-2036
Cervical Dysplasia Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Cervical Dysplasia Treatment Market Analysis
High-resolution colposcopy standards are redrawing competitive requirements for cervical dysplasia intervention systems. Hologic, Inc. leverages its integrated diagnostics-to-treatment platform across screening and ablation workflows. Merck & Co., Inc. anchors HPV therapeutic development that shapes downstream treatment protocols. GSK plc. competes through vaccine-adjacent education channels that influence patient presentation timing.
Cervical dysplasia treatment encompasses excisional and ablative modalities targeting premalignant cervical epithelial lesions, with loop electrosurgical excision procedure (LEEP) representing the dominant tissue-preserving technique using low-voltage alternating current through a thin wire loop. The primary purpose centers on eliminating high-grade squamous intraepithelial lesions while preserving fertility capacity and enabling histopathological confirmation. Cryotherapy occupies a mature cost-position in low-resource settings where equipment portability outweighs precision demands. Minimally invasive procedures capture margin concentration as ambulatory migration reduces facility overhead per case. Photodynamic therapy represents the fastest-growing technology segment amid photothermal ablation research expansion.
FDA clearance pathways govern device commercialization for electrosurgical and cryoablation platforms, while EMA MDR requirements impose post-market surveillance obligations on European suppliers. National cervical screening programs regulated by country-specific health technology assessment bodies determine reimbursement thresholds that directly shape provider procurement decisions. Stakeholders must monitor real-world evidence generation requirements that regulators are embedding into continued market access frameworks.
Market Dynamics
HPV vaccination policy expansion is redirecting patient flow toward earlier-stage interventions, compressing the addressable pool for high-grade lesion treatments while simultaneously elevating screening precision standards across developed health systems.
Growth Catalysts
- EMA MDR post-market surveillance:European suppliers face heightened evidence-generation obligations that favor established device manufacturers with robust clinical data infrastructure, consolidating procurement toward compliant vendors.
- Ambulatory surgical center throughput:Facility migration in the United States reduces per-case overhead and expands same-day procedure capacity, particularly for LEEP and cryotherapy modalities.
- Photothermal ablation research:Academic medical centers in Germany and Japan are accelerating photodynamic therapy validation protocols, creating new reimbursement pathways for tissue-sparing interventions.
Market Restraints
- Electrosurgical equipment supply concentration:Precision wire loop manufacturing for LEEP devices clusters among German and Japanese specialty metal suppliers, exposing procurement to input volatility.
- Cryogen logistics costs:Liquid nitrogen distribution for cryotherapy platforms faces cold-chain infrastructure gaps in rural United States markets, limiting portable device deployment.
- HPV therapeutic substitution:Merck's therapeutic vaccine pipeline threatens downstream ablation demand by intercepting lesion progression before intervention thresholds.
Strategic Opportunities
- India's national screening program:The country's health technology assessment body is evaluating portable thermal ablation devices for district-level deployment, creating first-mover positioning for cost-optimized platforms.
- AI-augmented colposcopy:Machine vision integration with high-resolution imaging systems is converging with cloud-based diagnostic workflows, enabling remote specialist consultation in underserved United States counties.
- Japan's PMDA fast-track pathway:The regulator's priority review designation for fertility-preserving interventions accelerates market entry timelines for novel ablation technologies targeting reproductive-age patients.
Industry Challenges
- Histopathology workflow integration:Excisional procedures require real-time specimen handling coordination between operating suites and pathology laboratories, creating staffing bottlenecks in high-volume United States ambulatory centers.
- LEEP certification timelines:Gynecologic surgeons must complete proctored training modules for electrosurgical competency, extending credentialing cycles and constraining provider supply in expansion markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cervical Dysplasia Treatment Market |
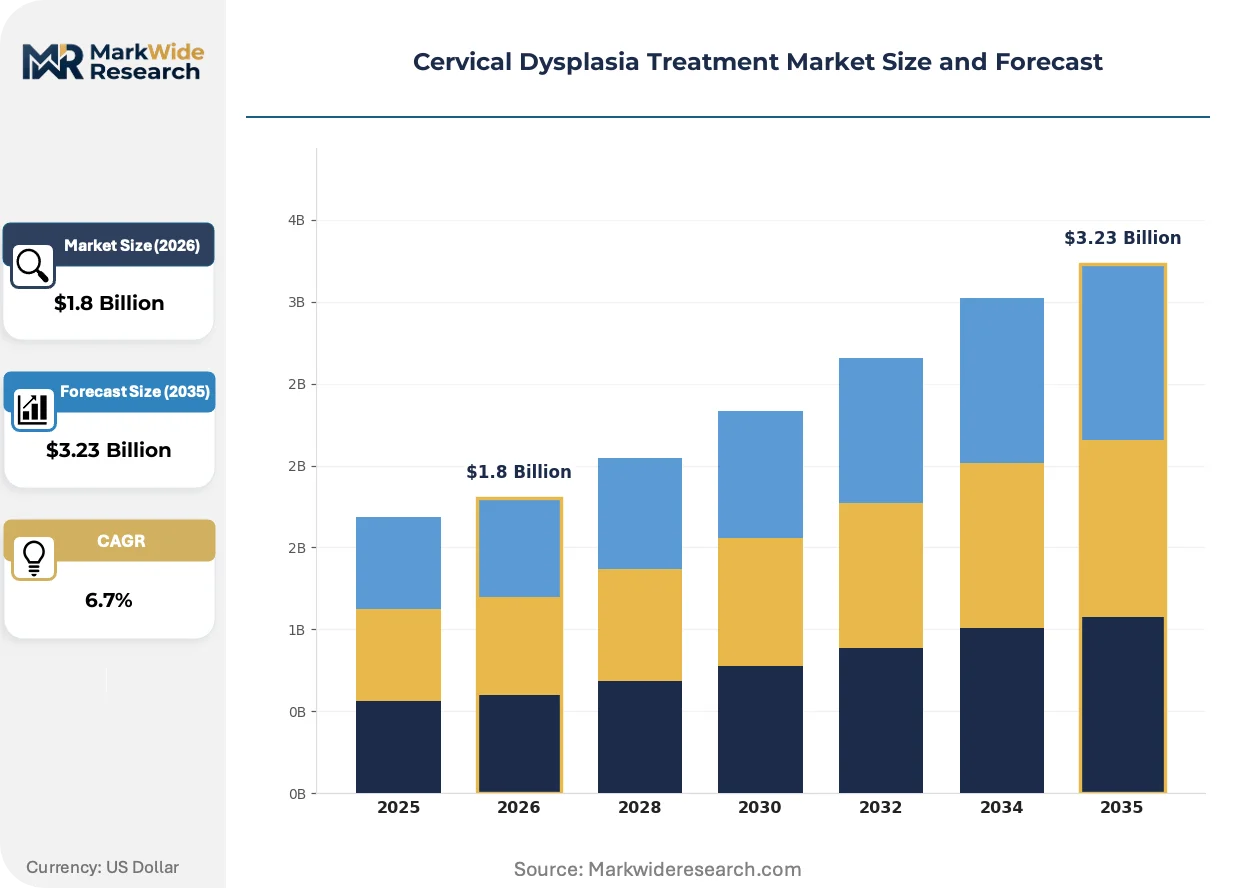
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cryotherapy, Laser Therapy, Loop Electrosurgical Excision Procedure, Cone Biopsy Technology: Cryosurgery, Electrosurgical Units, Photodynamic Therapy, Radiofrequency Ablation End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Laboratories Delivery Mode: Invasive Procedures, Non-invasive Procedures, Minimally Invasive Procedures, Home Care |
| Companies Covered | Hologic, Inc., Merck & Co., Inc., GSK plc., F. Hoffmann-La Roche Ltd, Pfizer Inc., AstraZeneca, Novartis AG, Bristol-Myers Squibb Company, AbbVie Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cervical Dysplasia Treatment Market Emerging Trajectories
Device miniaturization and diagnostic-treatment convergence are compressing procedural footprints while elevating precision requirements for cervical dysplasia interventions across ambulatory settings.
Thermal ablation platforms are miniaturizing through semiconductor-based heating element advances that eliminate cryogen dependency. Community health centers in Brazil and Mexico are piloting battery-operated devices that reduce facility infrastructure requirements. The technology is miniaturizing procedure suites from dedicated operating rooms to examination chairs, expanding access in resource-constrained settings.
FDA's 510(k) clearance pathway for electrosurgical devices now incorporates enhanced biocompatibility testing standards for cervical application-specific instruments. Manufacturers must submit expanded bench testing data on thermal spread characteristics. United States-based suppliers are responding by integrating real-time temperature monitoring into next-generation LEEP generators to preempt regulatory friction.
Point-of-care diagnostic integration is compressing the screening-to-treatment interval from weeks to single-visit protocols. United States federally qualified health centers are adopting colposcopy-LEEP combination workflows that disaggregate traditional referral-based care models. This behavioral shift is most visible in Texas and Florida Medicaid expansion counties where transportation barriers previously drove appointment attrition.
Cervical Dysplasia Treatment Market Segmentation
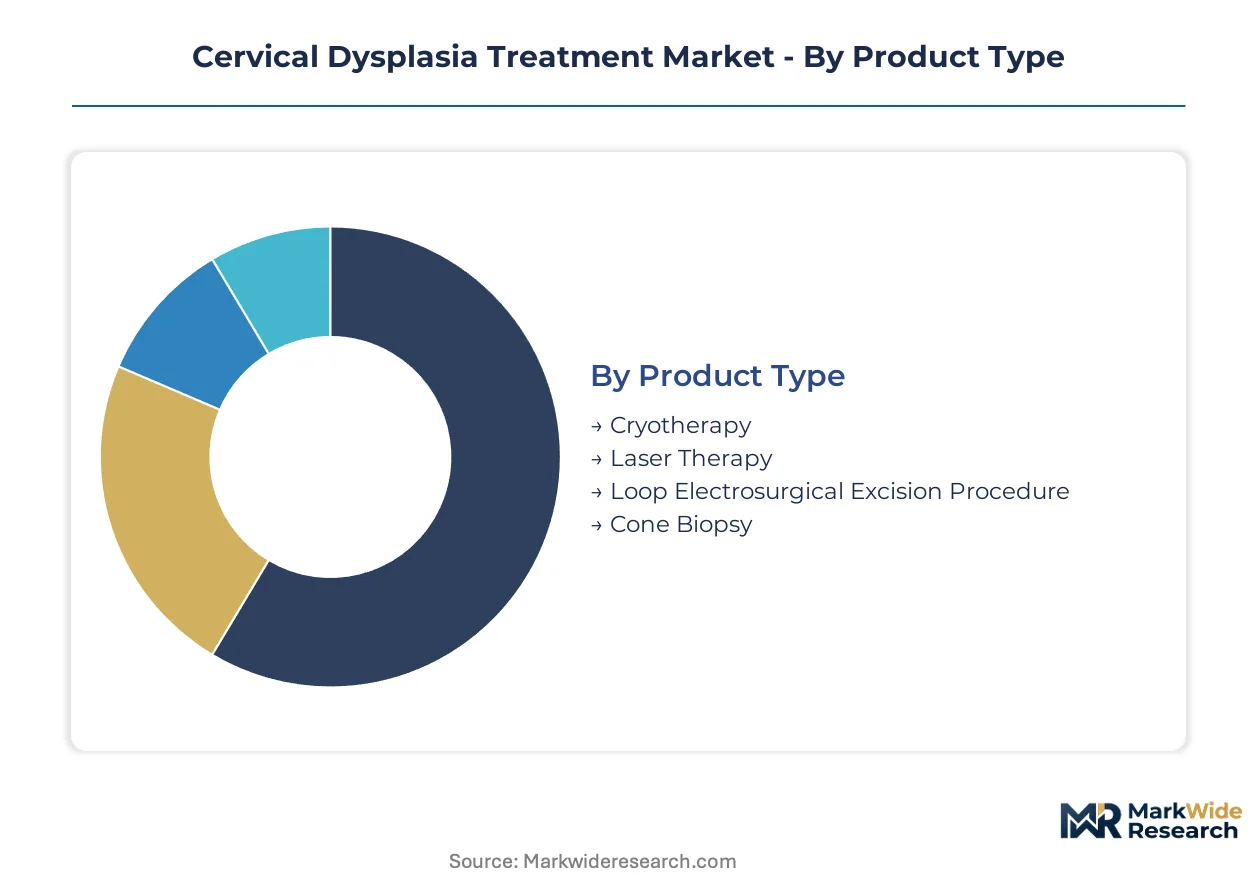
Cervical dysplasia treatment modalities span distinct procedural intensities and care settings, each commanding different reimbursement pathways and facility infrastructure requirements. Channel dynamics vary sharply between hospital-based excisional work and ambulatory ablation services.
Product Type:
Channel distribution splits between hospital-based excisional platforms and ambulatory ablation systems, with LEEP devices concentrating in same-day surgery centers while cryotherapy units penetrate community health networks.
- Loop Electrosurgical Excision Procedure:Low-voltage alternating current delivered through thin wire loops enables tissue-preserving excision with concurrent histopathological sampling. Demand concentrates in United States ambulatory surgical centers where same-day throughput maximizes facility utilization rates.
- Cryotherapy:Liquid nitrogen or compressed gas ablation destroys dysplastic epithelium through freeze-thaw cycles. Cost positioning drives adoption in Brazil and Mexico community health programs where equipment portability outweighs precision requirements.
- Laser Therapy:Carbon dioxide or Nd:YAG laser platforms deliver targeted thermal destruction with minimal collateral tissue damage.
- Cone Biopsy:Cold knife excision removes larger cervical specimens for definitive staging in suspected microinvasive disease.
By volume, LEEP leads. By growth pace, cryotherapy is ahead in resource-constrained markets.
Technology:
Cost tier stratification separates capital-intensive electrosurgical suites from disposable-dependent cryosurgical platforms, with reimbursement differentials shaping provider procurement priorities.
- Electrosurgical Units:Generator systems with integrated smoke evacuation and real-time impedance monitoring support precision tissue removal. United States outpatient facilities favor these platforms for their histopathology integration and favorable CPT reimbursement codes.
- Photodynamic Therapy:Photosensitizer-activated ablation using targeted light delivery spares surrounding healthy tissue. Academic medical centers in Germany and Japan are validating protocols for fertility-preserving applications in reproductive-age patients.
- Cryosurgery:Probe-based freezing systems require minimal operator training and no electrical infrastructure.
- Radiofrequency Ablation:Alternating current generates frictional heat for controlled tissue destruction without smoke production.
By installed base, electrosurgical units dominate. By expansion trajectory, photodynamic therapy is climbing the fastest amid tissue-sparing clinical validation.
End User:
Customer type fragmentation reflects divergent credentialing requirements, with hospital systems maintaining complex excisional capabilities while ambulatory centers optimize high-volume ablation workflows.
- Ambulatory Surgical Centers:Dedicated outpatient facilities achieve lower per-case overhead through streamlined LEEP and cryotherapy protocols. United States Medicare reimbursement differentials favor these settings for qualifying procedures, redirecting volume from hospital outpatient departments.
- Specialty Clinics:Gynecologic oncology and reproductive health practices combine diagnostic colposcopy with immediate treatment capability. Texas and Florida Medicaid expansion counties are adopting colposcopy-LEEP combination workflows to reduce appointment attrition from transportation barriers.
- Hospitals:Tertiary centers manage complex cases requiring cone biopsy or fertility-sparing radical excision.
- Research Laboratories:Academic institutions validate novel ablation technologies through clinical trial protocols.
By procedure volume, ambulatory surgical centers lead. By capability expansion, specialty clinics are gaining share fastest through diagnostic-treatment integration.
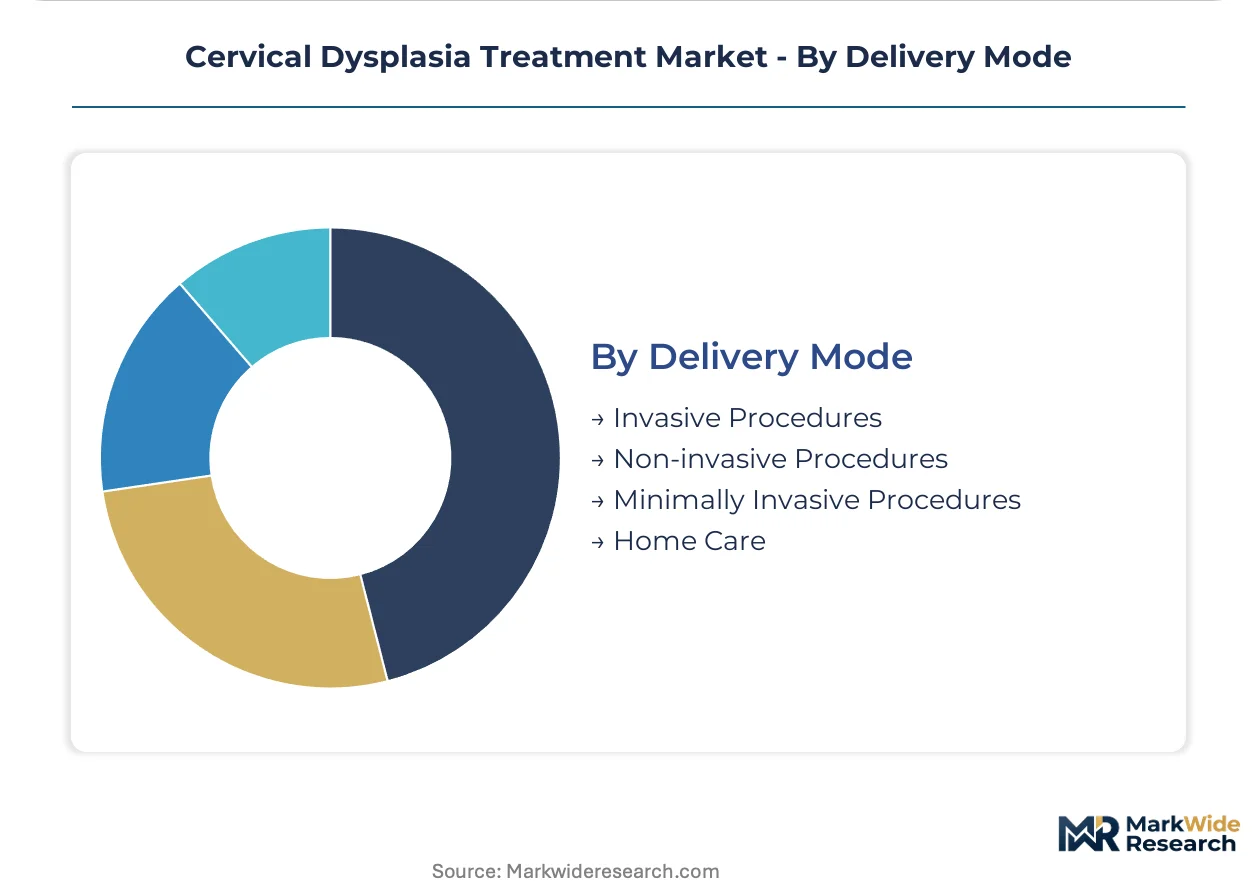
Delivery Mode:
Application intensity determines setting requirements, with invasive excisional procedures anchoring hospital revenue while minimally invasive modalities enable point-of-care migration.
- Minimally Invasive Procedures:LEEP and thermal ablation techniques preserve cervical architecture while eliminating dysplastic tissue. India's national screening program is evaluating portable thermal ablation devices for district-level deployment, creating access expansion in rural health networks.
- Non-invasive Procedures:Topical therapies and observation protocols manage low-grade lesions without tissue destruction. HPV vaccination policy expansion in developed health systems is compressing the addressable pool for these interventions by intercepting progression to treatable stages.
- Invasive Procedures:Cone biopsy and hysterectomy address high-grade disease or failed prior therapy.
- Home Care:Self-administered topical immunomodulators remain investigational for cervical application.
By current penetration, minimally invasive procedures lead. By protocol innovation, non-invasive approaches are expanding most quickly through vaccination-prevented disease reduction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity for cervical dysplasia treatment varies sharply across health systems. United States buyers prioritize reimbursement optimization and same-day throughput. Emerging markets emphasize equipment portability and cold-chain independence over precision metrics.
United States
Medicare reimbursement differentials favor ambulatory surgical centers for LEEP procedures, redirecting volume from hospital outpatient departments. FDA's enhanced biocompatibility testing standards for electrosurgical devices now require expanded bench data on thermal spread characteristics. Texas and Florida Medicaid expansion counties are adopting colposcopy-LEEP combination workflows to reduce appointment attrition from transportation barriers.
Germany
Academic medical centers are accelerating photodynamic therapy validation protocols for fertility-preserving applications. EMA MDR post-market surveillance obligations favor established device manufacturers with robust clinical data infrastructure. Heidelberg and Berlin clusters are generating real-world evidence for novel ablation technologies targeting reproductive-age patients.
India
The national screening program is evaluating portable thermal ablation devices for district-level deployment in rural health networks. The country's national pharmaceutical regulator and health technology assessment body are coordinating procurement standards for cost-optimized platforms. Maharashtra and Karnataka are piloting battery-operated devices that eliminate electrical infrastructure requirements in community health centers.
Japan
PMDA's priority review designation for fertility-preserving interventions accelerates market entry timelines for novel ablation technologies. METI standards for medical device manufacturing support domestic production of precision electrosurgical components. Tokyo and Osaka medical centers are validating semiconductor-based heating elements that eliminate cryogen dependency.
Brazil
Community health programs are deploying cryotherapy units where equipment portability outweighs precision requirements. ANVISA regulatory pathways for imported electrosurgical devices require localized safety testing. São Paulo and Minas Gerais are piloting procedure suite miniaturization that shifts interventions from operating rooms to examination chairs.
Cervical Dysplasia Treatment Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the cervical dysplasia treatment landscape. The market structure concentrates around integrated diagnostics-to-treatment platforms and vaccine-adjacent education channels. Three archetypes dominate: platform integrators spanning screening through ablation, therapeutic developers shaping downstream protocols, and point-of-care miniaturization specialists. Competitive moves center on diagnostic-treatment convergence and ambulatory workflow optimization.
Among platform integrators, Hologic, Inc. and F. Hoffmann-La Roche Ltd occupy positions representing the diagnostics-to-intervention continuum. Merck & Co., Inc. sits within the therapeutic development tier, anchoring HPV-related pipeline activity that influences patient presentation timing. These three exemplify how competitive positioning splits between hardware integration and biological intervention rather than converging on a single capability stack.
| Leading Market Players |
|---|
| Hologic, Inc. |
| Merck & Co., Inc. |
| GSK plc. |
| F. Hoffmann-La Roche Ltd |
| Pfizer Inc. |
| AstraZeneca |
| Novartis AG |
| Bristol-Myers Squibb Company |
| AbbVie Inc. |
| Others |
Supply Flow & Price Mechanics
Ambulatory surgical center throughput economics in the United States compress per-case overhead thresholds while simultaneously elevating precision requirements, concentrating procurement leverage among high-volume buyers and anchoring price floors to reimbursement ceilings set by Medicare CPT codes.
Pricing Analysis
FDA enhanced biocompatibility testing standards dictate the pricing tier structure for electrosurgical devices, separating premium platforms with real-time thermal monitoring from standard LEEP generators and economy cryotherapy units lacking histopathology integration. Price differentiation drivers center on FDA 510(k) clearance tier and ambulatory center volume scale, with reimbursement-optimized configurations commanding sustained premiums. Cost compression in economy cryotherapy tiers is intensifying because India's national screening program is driving procurement toward battery-operated portable devices. Community health centers exhibit highest price sensitivity; academic medical centers in Germany and Japan show lowest sensitivity amid fertility-preserving protocol investments.
Supply Chain Analysis
Specialty wire loop manufacturing for LEEP devices clusters among German and Japanese precision metal suppliers, creating single-source vulnerability for electrosurgical probe inputs. Raw material dependencies encompass tungsten-rhenium alloys for loop electrodes, semiconductor heating elements for thermal ablation platforms, and liquid nitrogen distribution infrastructure for cryogen-dependent systems. Supply chain risk centers on cold-chain logistics gaps in rural United States markets that constrain portable cryotherapy deployment. Distribution runs through hospital procurement committees and ambulatory surgical center GPO contracts, with direct manufacturer-to-facility relationships gaining share in high-volume United States outpatient networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
HPV therapeutic vaccine substitution threatens downstream ablation demand, forcing incumbents to defend procedural relevance against interception of lesion progression before intervention thresholds.
For Market Incumbents: Secure diagnostic-treatment platform integration through colposcopy-LEEP combination workflows that compress screening-to-treatment intervals from weeks to single-visit protocols. Anchor procurement relationships with United States federally qualified health centers in Medicaid expansion counties where transportation barriers previously drove appointment attrition. Counter therapeutic substitution threat by embedding real-time histopathology coordination into excisional procedure suites, creating workflow stickiness that vaccine-prevented disease reduction cannot replicate. For New Entrants and Emerging Players: Japan's PMDA priority review fast-track for fertility-preserving interventions opens regulatory acceleration pathways for novel ablation technologies targeting reproductive-age patients. Target India's district-level health networks where the national screening program is evaluating portable thermal ablation devices for rural deployment without electrical infrastructure requirements. Deploy battery-operated semiconductor heating platforms through Maharashtra and Karnataka pilot programs, leveraging cost-optimized positioning against cryogen-dependent legacy systems. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors point-of-care miniaturization specialists with diagnostic-treatment convergence capabilities over pure-play device manufacturers lacking software integration. Long-term viability rests on capturing ambulatory migration tailwinds as same-day procedure capacity expands across developed health systems. Acquisition target archetype: thermal ablation platform developers with validated photodynamic therapy protocols in German and Japanese academic medical centers. Signal to watch: reimbursement pathway establishment for tissue-sparing interventions in reproductive-age patient populations.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EMA MDR post-market surveillance obligations favor established manufacturers with clinical data infrastructure. |
| Hospital System Partnership | United States ambulatory surgical center alliances redirect volume from hospital outpatient departments. |
| Software Companion Development | AI-augmented colposcopy integration enables remote specialist consultation in underserved counties. |
| Reimbursement Strategy | Medicare CPT code optimization anchors procurement decisions for LEEP device configurations. |
| FDA Submission | Enhanced biocompatibility testing standards for thermal spread characteristics govern 510(k) clearance timelines. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with gynecologic surgeons, ambulatory surgical center administrators, biomedical engineers, and GPO contracts managers; and secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and EMA MDR surveillance reports. Bottom-up procedure volume estimates triangulated with top-down market sizing across electrosurgical, cryotherapy, and photodynamic therapy platform categories.
Across the analysis window, the forecasting framework modeled segmentation dimensions spanning product type, technology tier, end-user setting, and delivery mode intensity, with CAGRs derived from procedure volume trajectories and reimbursement pathway evolution. Inputs incorporated HPV vaccination policy penetration rates, ambulatory facility migration patterns, and regulatory clearance timeline differentials between FDA and PMDA pathways.
Decision-makers should treat outputs as directional under sustained Medicare reimbursement differentials favoring ambulatory settings; material deviation in HPV therapeutic vaccine efficacy would warrant model refresh. Practitioners should keep alternative scenarios live as photothermal ablation research validation and India's national screening program procurement decisions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Reproductive Health
Global Cervical Dysplasia Market
Reproductive Health
Global Gynecology Drugs Market
Reproductive Health
Doula and Birth Coaching Services Market
Reproductive Health
Contraceptives Market
Reproductive Health
Hormonal Contraception Market
Reproductive Health
In Vitro Fertilization (IVF) Market
Reproductive Health
Europe in Vitro Fertilization (IVF) Market
Reproductive Health
Donor Egg IVF (in-Vitro Fertilization) Market
Reproductive Health
UK in Vitro Fertilization (IVF) Market
Reproductive Health
Egg Donation Market
Reproductive Health
Fertility Treatments Market
Reproductive Health
Assisted Reproductive Technology (ART) Market
Reproductive Health
Surrogacy Market
Reproductive Health
Donor Egg IVF Services Market
Reproductive Health
IVF Services Market
Reproductive Health
Pregnancy Care Products Market