
 US Liquid Waste Management Market | 2026-2036
US Liquid Waste Management Market Size, Share, and Industry Trends Forecast 2026-2036
US Liquid Waste Management Market Intelligence
A capital-intensity divergence between incineration-capable networks and regional haulers is rotating competitive advantage toward integrated treatment platforms. Clean Harbors leverages its hazardous waste incineration footprint to command premium pricing on complex liquid streams. Republic Services sustains dense collection route economics across metropolitan markets through scale-driven logistics. Waste Management anchors national account relationships with bundled solid and liquid waste contracts.
US liquid waste management encompasses the collection, transportation, treatment, and disposal of non-hazardous and hazardous liquid byproducts from industrial, commercial, and municipal sources, typically governed by parameters such as pH, total dissolved solids, and toxicity characteristics under RCRA standards. The service generates recurring revenue through long-term contracts tied to waste generation volumes and regulatory compliance obligations. Collection and disposal services dominate revenue share due to their essential nature and regulatory mandate, while treatment—particularly chemical and biological processing—captures margin expansion as discharge standards tighten. Industrial facilities represent the fastest-growing end-user category as manufacturing reshoring intensifies wastewater output.
EPA enforcement of the Clean Water Act and RCRA hazardous waste provisions shapes facility-level investment in pretreatment systems and third-party management services. OSHA standards for worker exposure to chemical wastes further elevate operational compliance costs across the service chain. State-level variations in permitting timelines—particularly in California and Texas—create localized supply constraints that favor operators with established regulatory relationships. Stakeholders must monitor proposed PFAS effluent rules and their cascading impact on treatment technology selection and capital deployment priorities.
Market Dynamics
Capital deployment across the US liquid waste management sector is compressing toward integrated treatment platforms as EPA's updated Effluent Limitations Guidelines force manufacturing facilities into higher-cost compliance pathways. This regulatory ratchet is decomposing the economics of standalone collection networks.
Growth Catalysts
- RCRA hazardous waste provisions:EPA enforcement is mandating third-party management services for industrial facilities generating characteristic wastes, expanding addressable contract volume.
- PFAS effluent rulemaking:Proposed discharge standards are accelerating capital investment in advanced chemical treatment infrastructure across the Great Lakes industrial corridor.
- Manufacturing reshoring:Domestic production expansion in chemical processing and electronics fabrication is intensifying wastewater output requiring specialized handling.
Market Restraints
- Caustic soda and activated carbon input volatility:Chemical treatment operators face margin compression from commodity price swings in neutralization and adsorption media.
- Permitting timeline concentration in California:State-level regulatory bottlenecks create localized supply constraints that favor incumbent operators with established agency relationships.
- On-site zero-liquid-discharge systems:Capital-intensive industrial pretreatment installations threaten to displace third-party collection volumes for large-volume generators.
Strategic Opportunities
- Texas petrochemical corridor expansion:Gulf Coast facility construction is outpacing regional treatment capacity, creating greenfield development white space.
- OSHA worker exposure standards:Elevated compliance costs for in-house handling are pushing mid-size generators toward outsourced management contracts.
- Biological-chemical hybrid processing:Convergent treatment trains are opening margin expansion in high-BOD industrial streams previously routed to basic disposal.
Industry Challenges
- Licensed hazardous waste technician scarcity:Specialized operator certification requirements are constraining crew scaling in high-growth markets.
- Incineration asset retrofit timelines:Existing infrastructure requires extended downtime for air emissions compliance upgrades, disrupting service continuity.
- Legacy manifest system integration:Digital tracking mandates are forcing operational reconfiguration for haulers with paper-based documentation workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Liquid Waste Management Market |
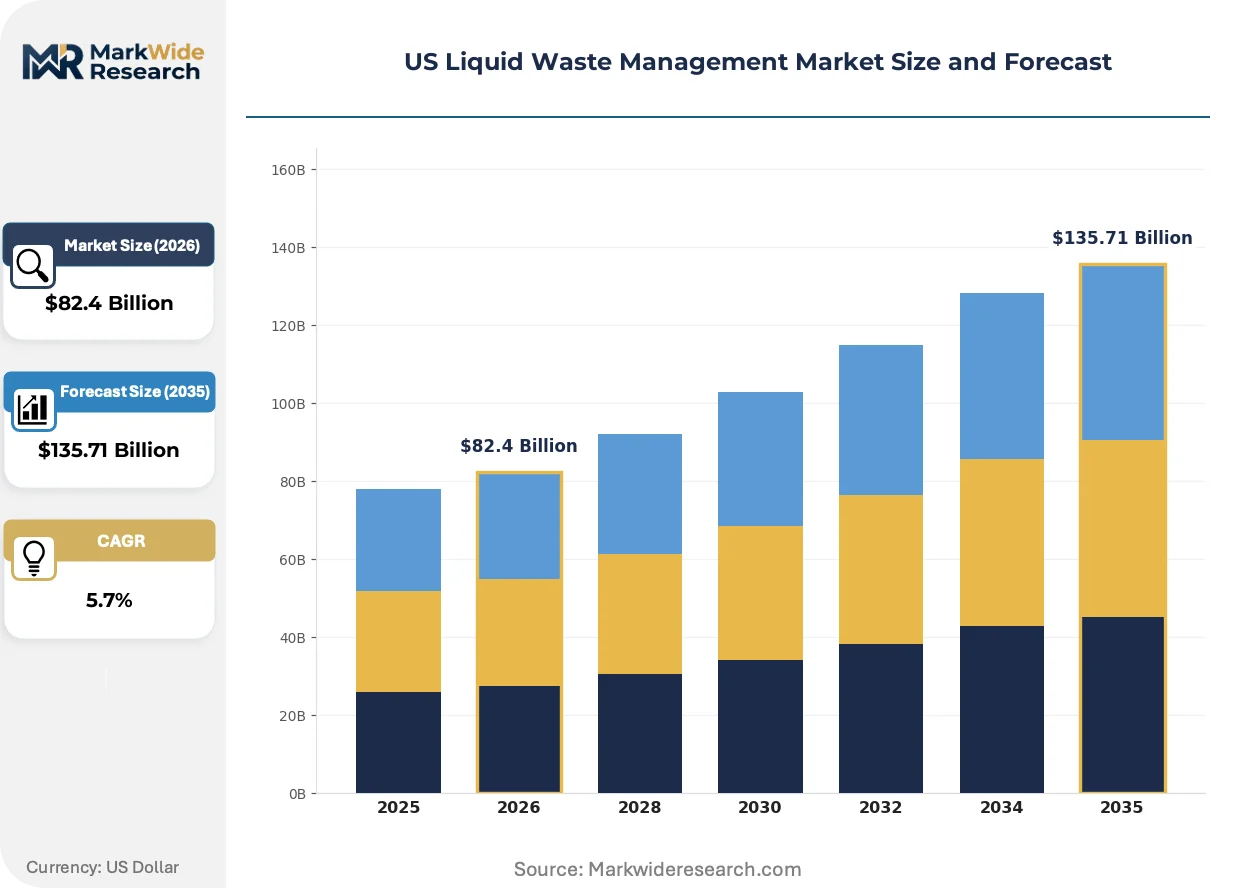
| Market Size in 2026 | $82.4 Billion |
| Market Size in 2035 | $135.71 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Collection, Treatment, Disposal, Recycling Industry Vertical: Construction, Manufacturing, Healthcare, Hospitality Technology: Biological, Chemical, Physical, Thermal End User: Municipalities, Industrial Facilities, Commercial Establishments, Households |
| Companies Covered | Republic Services, Hull’s Environmental Services, Clean Harbors, Liquid Environmental Solutions, Reworld, Veolia, GFL Environmental, Crystal Clean, Waste Management, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Liquid Waste Management Market Strategic Shifts & Innovations
Advanced oxidation processes are penetrating industrial pretreatment stages as discharge standards tighten, compressing the viable technology set toward higher-performance chemistry. This shift is redistributing value capture from transportation density toward treatment sophistication.
Supercritical water oxidation is decomposing recalcitrant organic compounds in pharmaceutical and chemical manufacturing effluent. Specialty chemical producers in New Jersey and Pennsylvania are piloting units at commercial scale. The technology is decomposing the traditional incineration premium for complex hazardous streams by enabling on-site destruction.
EPA's forthcoming PFAS effluent limitations are forcing manufacturing facilities into multimillion-dollar pretreatment investments. Metal finishing and electroplating operations face the steepest compliance ramps. Texas and California facilities are advancing engineering studies for granular activated carbon and ion exchange installations ahead of rule finalization.
Contract structures are migrating from per-gallon disposal rates toward total cost of compliance arrangements. Automotive and aerospace manufacturers are consolidating vendor relationships under multi-site performance guarantees. This bundling is most pronounced in the Midwest industrial belt where procurement teams prioritize regulatory risk transfer over unit cost minimization.
US Liquid Waste Management Market Segmentation
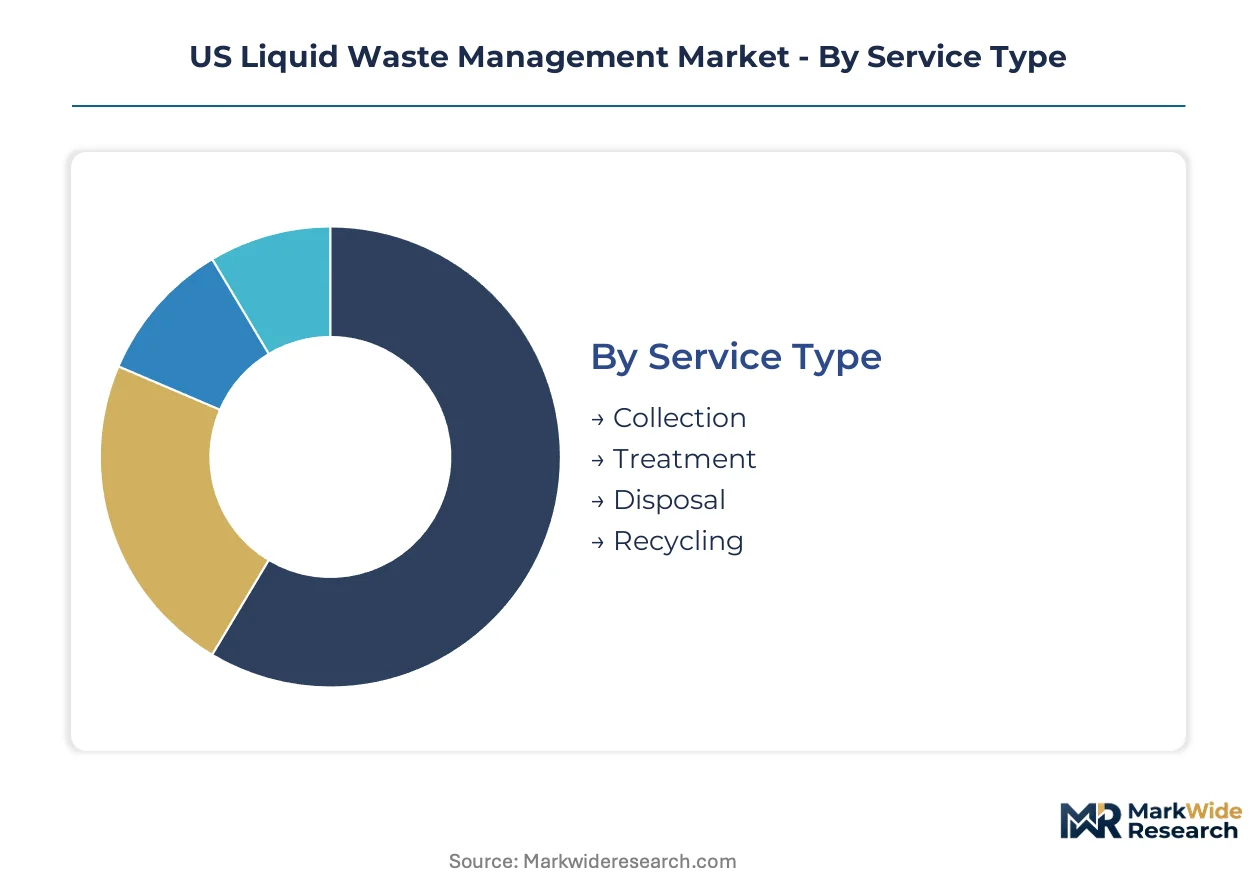
Liquid waste management operators configure service portfolios around regulatory complexity tiers. EPA discharge standards and RCRA hazardous waste classifications determine pricing power and capital requirements across segment boundaries.
Service Type:
EPA enforcement intensity separates compliance-mandated services from discretionary environmental programs.
- Collection:Route density economics dominate profitability for non-hazardous liquid haulers. Texas and California municipalities are expanding vacuum truck fleets for industrial effluent capture as manufacturing reshoring intensifies wastewater volumes.
- Treatment:Chemical and biological processing infrastructure commands margin expansion as discharge standards tighten. The Great Lakes industrial corridor is concentrating investment in advanced oxidation capacity for metal finishing and electroplating effluent.
- Disposal:Deep-well injection and hazardous waste landfill networks serve RCRA-regulated streams requiring secure containment.
- Recycling:Oil recovery and solvent reclamation programs reduce generator liability while capturing commodity value.
Established volume favors Collection; emerging adoption favors Treatment.
Industry Vertical:
Customer concentration and contract duration vary sharply across end-use sectors.
- Manufacturing:Chemical processing and electronics fabrication generate complex effluent streams requiring specialized handling. Reshoring production is expanding addressable contract volume across the Midwest and Gulf Coast.
- Healthcare:Medical liquid waste carries infectious and pharmaceutical contamination risks mandating strict chain-of-custody protocols.
- Construction:Dewatering and concrete washout services follow project-based demand cycles with lower recurring revenue predictability.
- Hospitality:Grease trap and kitchen effluent management operates on standardized service intervals with limited customization.
Contract stability anchors Manufacturing; service standardization dominates Hospitality.
Technology:
Capital intensity and operating sophistication stratify competitive positioning.
- Chemical:Neutralization, precipitation, and advanced oxidation processes address heavy metal and recalcitrant organic contamination. PFAS effluent rulemaking is accelerating granular activated carbon and ion exchange deployment.
- Biological:Activated sludge and anaerobic digestion systems treat high-BOD industrial streams. Hybrid biological-chemical trains are opening margin expansion in food and beverage processing.
- Physical:Sedimentation, filtration, and membrane separation handle suspended solids and oil-water separation.
- Thermal:Incineration and supercritical water oxidation destroy hazardous constituents requiring complete destruction.
Regulatory ratchet favors Chemical; cost efficiency sustains Physical.
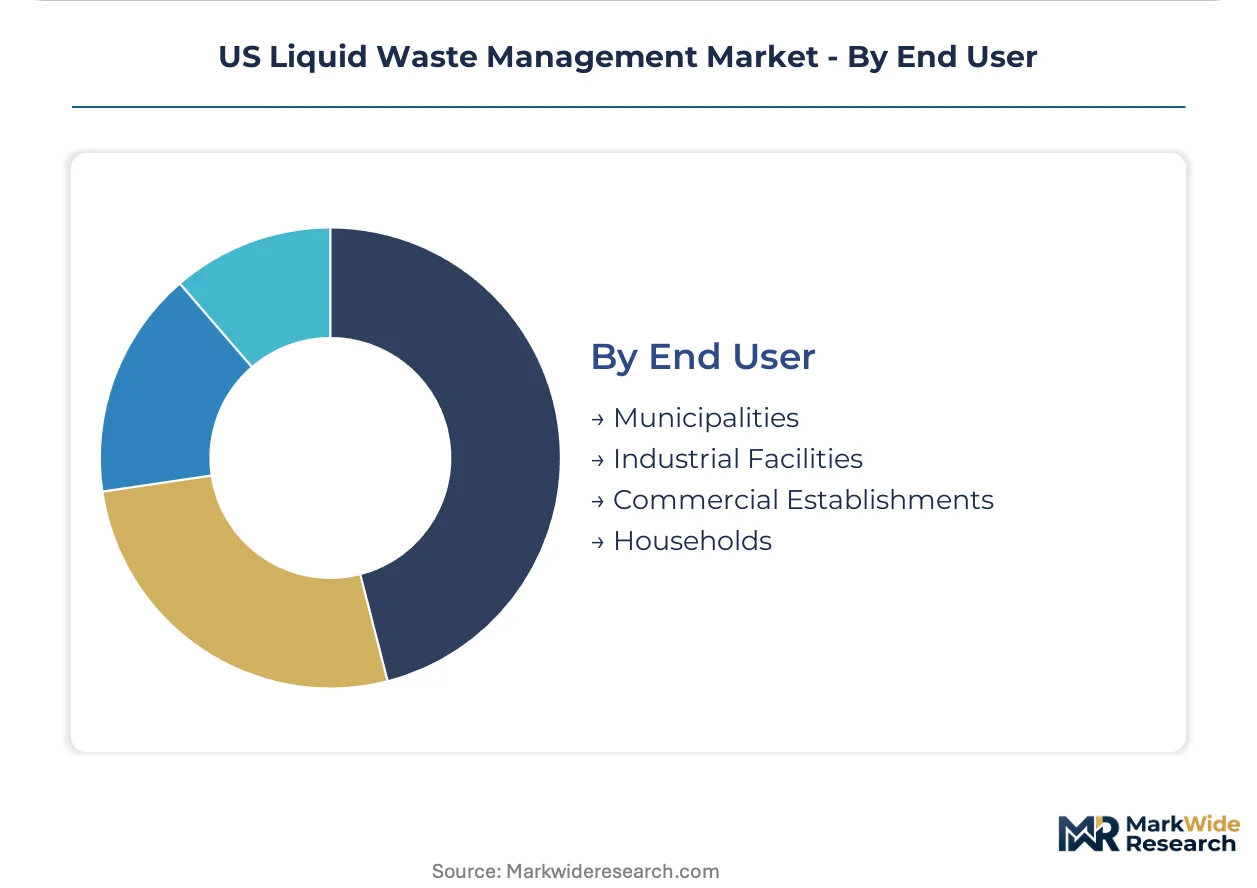
End User:
Procurement sophistication and compliance risk tolerance segment addressable demand.
- Industrial Facilities:Large-volume generators negotiate multi-site performance guarantees transferring regulatory liability. Automotive and aerospace manufacturers in the Midwest industrial belt prioritize risk transfer over unit cost.
- Municipalities:Public sector contracts emphasize route density and emergency response capability.
- Commercial Establishments:Mid-size generators face elevated OSHA compliance costs pushing outsourced management adoption.
- Households:Residential septic and grease trap services operate on localized subscription models with limited scale economies.
Contract value concentrates in Industrial Facilities; volume dispersion characterizes Households.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across US sub-regions, with coastal markets accepting compliance-driven premiums while Midwest buyers prioritize unit cost minimization in bundled contracts.
Texas Gulf Coast
Petrochemical facility construction is outpacing regional treatment capacity, creating acute demand for hazardous liquid handling services. EPA Region 6 maintains accelerated permitting timelines for RCRA-permitted facilities serving the corridor. Houston and Port Arthur industrial clusters are expanding vacuum truck fleets for refinery effluent capture as downstream chemical production intensifies.
California
Stringent state-level discharge standards are forcing manufacturing facilities into multimillion-dollar pretreatment investments. California's State Water Resources Control Board enforces basin-specific effluent limitations exceeding federal baselines. Los Angeles Basin and Bay Area metal finishing operations are advancing engineering studies for granular activated carbon installations ahead of anticipated PFAS rulemaking.
Great Lakes Industrial Corridor
Chemical treatment capacity is concentrating around metal finishing and automotive manufacturing effluent streams. EPA Region 5 coordinates with state environmental agencies on combined sewer overflow mitigation programs. Detroit, Cleveland, and Milwaukee metropolitan areas are deploying advanced oxidation infrastructure for electroplating wastewater as discharge standards tighten.
Southeast Manufacturing Belt
Reshoring of electronics and automotive production is expanding addressable contract volume for specialized liquid waste services. OSHA regional offices are elevating enforcement of worker exposure standards for chemical handling operations. Georgia and South Carolina Piedmont regions are attracting hazardous waste transfer stations to serve growing semiconductor fabrication clusters.
Midwest Agricultural Processing
Food and beverage manufacturing generates high-BOD effluent streams requiring biological-chemical hybrid treatment. EPA Region 7 administers concentrated animal feeding operation discharge permits affecting regional processing facilities. Iowa and Illinois corn belt processing centers are expanding anaerobic digestion capacity for ethanol production wastewater.
US Liquid Waste Management Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with national account bundling power separating scale operators from regional haulers. The upper tier commands premium pricing through RCRA-permitted incineration networks and multi-site compliance guarantees. Mid-cap specialists compete on route density in metropolitan markets and regulatory relationship depth in permit-constrained states. Dominant competitive moves include strategic acquisitions of regional treatment assets and capacity expansion in petrochemical corridor greenfield sites.
Among integrated national operators, Clean Harbors and Waste Management occupy positions defined by hazardous waste incineration footprints and bundled service contracts respectively. Republic Services exemplifies the scale-driven logistics archetype through dense metropolitan collection route economics. These three anchors illustrate the structural divergence between incineration-capable networks and regional haulers rotating competitive advantage toward treatment sophistication.
| Leading Market Players |
|---|
| Republic Services |
| Hull's Environmental Services |
| Clean Harbors |
| Liquid Environmental Solutions |
| Reworld |
| Veolia |
| GFL Environmental |
| Crystal Clean |
| Waste Management |
| Others |
Cost & Logistics Intelligence
Multi-year compliance contracts with take-or-pay minimums anchor pricing visibility for industrial generators across Texas and California, locking in treatment capacity access while insulating operators from caustic soda and activated carbon spot volatility. This structure concentrates procurement leverage with integrated platforms that bundle collection, treatment, and disposal under single-source accountability.
Pricing Analysis
After-sales service revenue from ongoing monitoring and compliance reporting drives lifetime contract value beyond initial treatment fees. Three-tier pricing structure across RCRA-permitted hazardous, non-hazardous industrial, and municipal collection services separates premium incineration-backed guarantees from standard biological processing and economy route-density haulage. Pricing pressure stems from on-site zero-liquid-discharge system adoption among large-volume automotive and aerospace manufacturers. Small and mid-size commercial generators exhibit highest price sensitivity due to limited compliance staff, while industrial facilities prioritize risk transfer over unit cost minimization.
Supply Chain Analysis
Inventory buffers for chemical treatment inputs stretch 60-90 days as operators hedge against caustic soda and granular activated carbon price swings. Domestic production of neutralization chemicals concentrates around Louisiana and Texas Gulf Coast petrochemical complexes, while specialty adsorption media draws from Chinese and Indian manufacturing. Single-source vulnerability runs through activated carbon supply chains subject to import tariff exposure. Distribution runs through RCRA-permitted transfer stations serving metropolitan industrial clusters, with final disposal routing to deep-well injection networks in Ohio and Texas or hazardous waste landfills in Utah and Alabama.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across EPA regions and state-level permitting timelines creates structural white space for specialized operators. PFAS effluent rulemaking is splintering demand into advanced treatment niches that favor technical specialists over volume haulers.
For Market Incumbents: Secure RCRA-permitted incineration capacity in the Texas Gulf Coast corridor ahead of petrochemical facility commissioning. Deepen backward integration into chemical treatment inputs to neutralize caustic soda price volatility threatening margin compression. Lock multi-site automotive and aerospace contracts under total-cost-of-compliance structures that transfer regulatory liability and deter competitive displacement. For New Entrants and Emerging Players: EPA Region 6 fast-track permitting for hazardous waste technicians offers regulatory arbitrage against California's 18-month approval timelines. Target vacuum truck collection density in Houston and Port Arthur industrial clusters where treatment capacity lags generator growth. Lead with PFAS-specific granular activated carbon and ion exchange capabilities to capture metal finishing and electroplating compliance spend ahead of rule finalization. For Investors and Strategic Acquirers: Regional treatment specialists with established Texas or California agency relationships represent priority acquisition targets given permitting bottlenecks that constrain new entrant supply. Long-term viability hinges on exposure to manufacturing reshoring corridors and advanced oxidation technology deployment. Monitor EPA PFAS effluent rulemaking publication as inflection signal for capital deployment into activated carbon infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| RCRA Permit Expansion | Accelerated EPA Region 6 approvals capture Texas petrochemical corridor demand before competitors. |
| Backward Integration into Chemical Inputs | Captive caustic soda supply neutralizes commodity volatility compressing treatment margins. |
| PFAS Treatment Technology Deployment | Granular activated carbon and ion exchange capacity positions operators for forthcoming EPA discharge rules. |
| Multi-Site Compliance Bundling | Automotive and aerospace manufacturer contracts transfer regulatory liability and entrench vendor relationships. |
| Licensed Technician Workforce Scaling | Hazardous waste operator certification programs alleviate crew constraints limiting growth in high-demand markets. |
Research Approach
Initial hypotheses were tested against primary input from treatment plant operators, industrial facility environmental compliance officers, RCRA permit consultants, and hazardous waste logistics coordinators and refined through secondary validation against EPA enforcement data, state water board discharge records, SEC 10-K filings of publicly traded waste operators, and American Chemistry Council industry surveys. Bottom-up volume estimates from generator facility counts and top-down market sizing from service revenue aggregation were triangulated to constrain forecast variance.
Variance decomposition across the projection horizon isolates volume growth from pricing mix shifts and regulatory-driven service tier migration. Segmentation dimensions modeled include service type, industry vertical, treatment technology, and end-user procurement sophistication. CAGRs were derived from regression against industrial production indices, manufacturing reshoring announcements, and EPA rulemaking timelines. Forecast inputs incorporate vacuum truck fleet expansion data and granular activated carbon installation engineering studies.
Decision-makers should treat outputs as directional under assumptions of sustained EPA enforcement intensity and PFAS rulemaking implementation; material deviation in regulatory timelines or industrial reshoring velocity would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
Produced Water Treatment Market
Water & Sludge Treatment
US Water and Wastewater Treatment Chemicals Market
Water & Sludge Treatment
Germany Water Treatment Chemicals Market
Water & Sludge Treatment
North America Membrane Water and Wastewater Treatment (WWT) Market
Water & Sludge Treatment
North America Water Treatment Chemicals Market
Water & Sludge Treatment
Middle-East and Africa Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
Fluid Waste Disposal Systems Market
Water & Sludge Treatment
Internal Boiler Treatment Chemicals Market
Water & Sludge Treatment
India Water and Wastewater Treatment (WWT) Technology Market
Water & Sludge Treatment
India Cooling Water Treatment Chemicals Market
Water & Sludge Treatment
Oil and Gas Water Treatment Chemicals Market
Water & Sludge Treatment
Hazardous Waste Treatment System Market
Water & Sludge Treatment
Global Sodium Hypochlorite Market
Water & Sludge Treatment
Pool and Spa Water Treatment Chemicals for Hotels and Clubs Market
Water & Sludge Treatment
Global Wet Waste Management Market
Water & Sludge Treatment
Water Treatment Market