
 Water Treatment Market | 2026-2036
Water Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Water Treatment Market Intelligence
A divergence in capital intensity for developing advanced treatment solutions is bifurcating the competitive landscape. Large, integrated service providers like Veolia leverage extensive global operations and R&D budgets to secure complex, multi-year contracts for municipal and industrial water systems. In contrast, specialists such as Xylem differentiate through a focus on high-tech monitoring, analytics, and smart water infrastructure components. This dynamic creates distinct strategic postures for companies based on their scale and technological specialization.
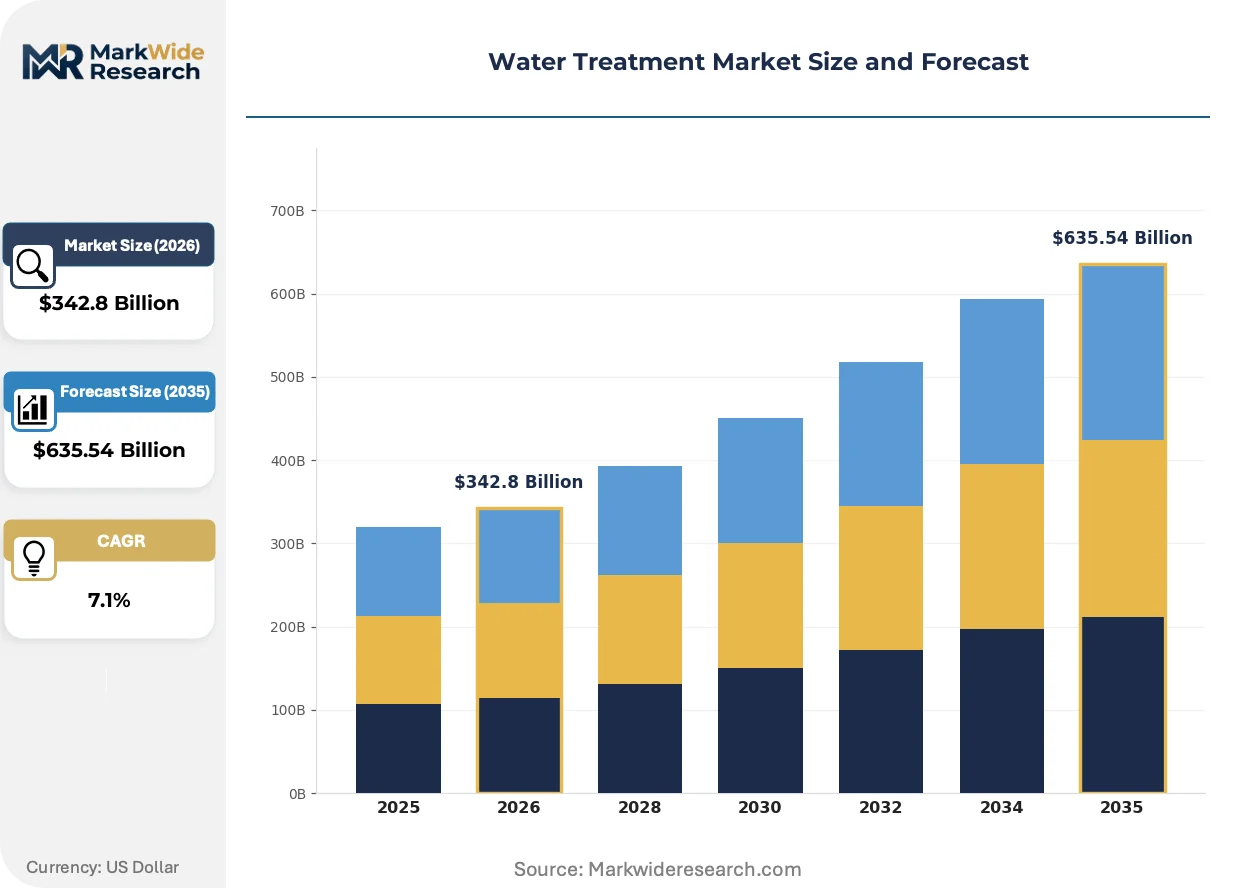
Water treatment encompasses the physical, chemical, and biological processes used to remove contaminants and improve water quality for a designated end-use. These systems are engineered to reduce impurities like pathogens, dissolved salts, and organic compounds to meet stringent quality targets, sometimes measured in parts-per-trillion. While the municipal water segment constitutes the largest volume, industrial applications often yield higher margins due to the need for ultra-pure process water. Membrane filtration and reverse osmosis technologies remain central to growth, especially in desalination and wastewater treatment applications.
Regulatory mandates are a primary market catalyst, with bodies like the US Environmental Protection Agency (EPA) and the European Chemicals Agency (ECHA) setting progressively stricter limits on contaminants. Concurrently, standards from organizations like the International Organization for Standardization (ISO) guide quality management for water utilities. In China, the Ministry of Ecology and Environment (MEE) enforces stringent discharge standards, pushing industries toward zero liquid discharge systems. Balancing the cost of compliance with the adoption of innovative treatment technologies remains the key strategic consideration for all stakeholders.
Market Dynamics
Heightened regulatory scrutiny over persistent contaminants, particularly per- and polyfluoroalkyl substances (PFAS), is the central force reshaping capital expenditure and technology selection. This pressure compels a move toward more advanced, and often more costly, separation and destruction technologies.
Growth Catalysts
- Industrial Purity Requirements:The semiconductor industry's demand for ultrapure water, free of even trace ionic and organic contaminants, necessitates the adoption of advanced ion exchange and membrane degassing systems, driving high-margin technology sales.
- Regulatory Mandates:New enforceable limits on PFAS in drinking water by the US Environmental Protection Agency (EPA) are compelling utilities to upgrade existing treatment trains with technologies like granular activated carbon or reverse osmosis.
- Water Scarcity:Nations like Saudi Arabia and India are heavily investing in large-scale desalination and wastewater reuse projects, creating sustained demand for membrane filtration and thermal distillation technologies to secure municipal and agricultural water supplies.
Market Restraints
- High Capital Intensity:The significant upfront investment required for constructing or upgrading treatment facilities, especially for advanced technologies like reverse osmosis or UV-AOP, acts as a major barrier for municipalities with constrained budgets.
- Brine Management Costs:Desalination and certain industrial wastewater treatment processes generate concentrated brine, the disposal of which is expensive and environmentally regulated, adding a significant operational cost that can limit project viability.
- Energy Consumption:Energy-intensive processes, notably reverse osmosis and thermal desalination, constitute a substantial portion of a treatment plant's operating expenses, making them vulnerable to electricity price volatility and hindering adoption in energy-poor regions.
Strategic Opportunities
- Decentralized Treatment Systems:Modular, containerized water and wastewater treatment units offer a scalable solution for remote communities, industrial sites, and disaster relief, opening a market segment underserved by large, centralized infrastructure projects. *Resource Recovery: Technologies that recover valuable resources such as phosphorus, nitrogen, and even metals from wastewater streams create new revenue opportunities for utilities and industrial operators, shifting treatment from a cost center to a value generator.
- Digital Twin Integration:The convergence of AI with physical asset data to create digital twins of treatment plants allows for predictive maintenance, process optimization, and operational simulation, offering a high-value service layer for technology providers.
Industry Challenges
- Skilled Workforce Scarcity:A shortage of qualified plant operators, process engineers, and data scientists capable of managing increasingly complex and automated smart water systems presents a significant operational bottleneck for utilities and service providers.
- Legacy Infrastructure Integration:Retrofitting aging municipal water infrastructure with modern sensors, controls, and advanced treatment modules is technically complex and can cause service disruptions, slowing the pace of technology adoption in established markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Treatment Market |
| Market Size in 2026 | $342.8 Billion |
| Market Size in 2035 | $635.54 Billion |
| CAGR (2026 – 2036) | 7.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Membrane Filtration, Reverse Osmosis, Ultraviolet, Ion Exchange Product Type: Chemical Treatment, Disinfection Equipment, Filtration Systems, Monitoring Solutions End User: Municipal Water, Industrial Applications, Residential Use, Commercial Establishments Application: Wastewater Treatment, Desalination, Drinking Water Purification, Process Water Treatment |
| Companies Covered | Ecolab, Evoqua Water Technologies, Veolia, Pentair, Aquatech International, SUEZ, Dow Water & Process Solutions, VA Tech Wabag, Xylem, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Treatment Market Strategic Shifts & Innovations
A fundamental shift toward data-driven process control and contaminant-specific solutions defines current market evolution. This transition moves the industry from broad-spectrum treatment to highly targeted, efficient water purification and reuse systems that address specific quality targets.
The resilience of advanced oxidation processes (AOPs) provides a powerful method for destroying persistent organic pollutants. These systems, which use reagents like ozone or hydrogen peroxide combined with UV light, are being adopted by municipal and industrial facilities to break down contaminants that conventional methods cannot remove. The effectiveness of AOPs against compounds like PFAS is fragmenting the market for contaminant destruction, creating a premium technology tier beyond simple filtration.
Regulatory frameworks are becoming more prescriptive regarding water reuse and resource recovery. The European Union's updated Urban Wastewater Treatment Directive, for example, sets targets for nutrient removal and energy neutrality in municipal plants. This directly impacts technology choices for utilities across the EU, requiring investment in advanced biological nutrient removal and sludge-to-energy systems to achieve compliance.
A clear behavioral change is emerging in how industrial facilities manage water, moving from a linear use-and-discharge model to a circular, onsite reuse approach. This disrupts the traditional reliance on municipal systems for both intake and discharge, with facilities investing in closed-loop systems. This trend is most pronounced in water-intensive sectors like data centers and food processing, particularly in water-stressed regions of the United States and Australia.
Water Treatment Market Segmentation
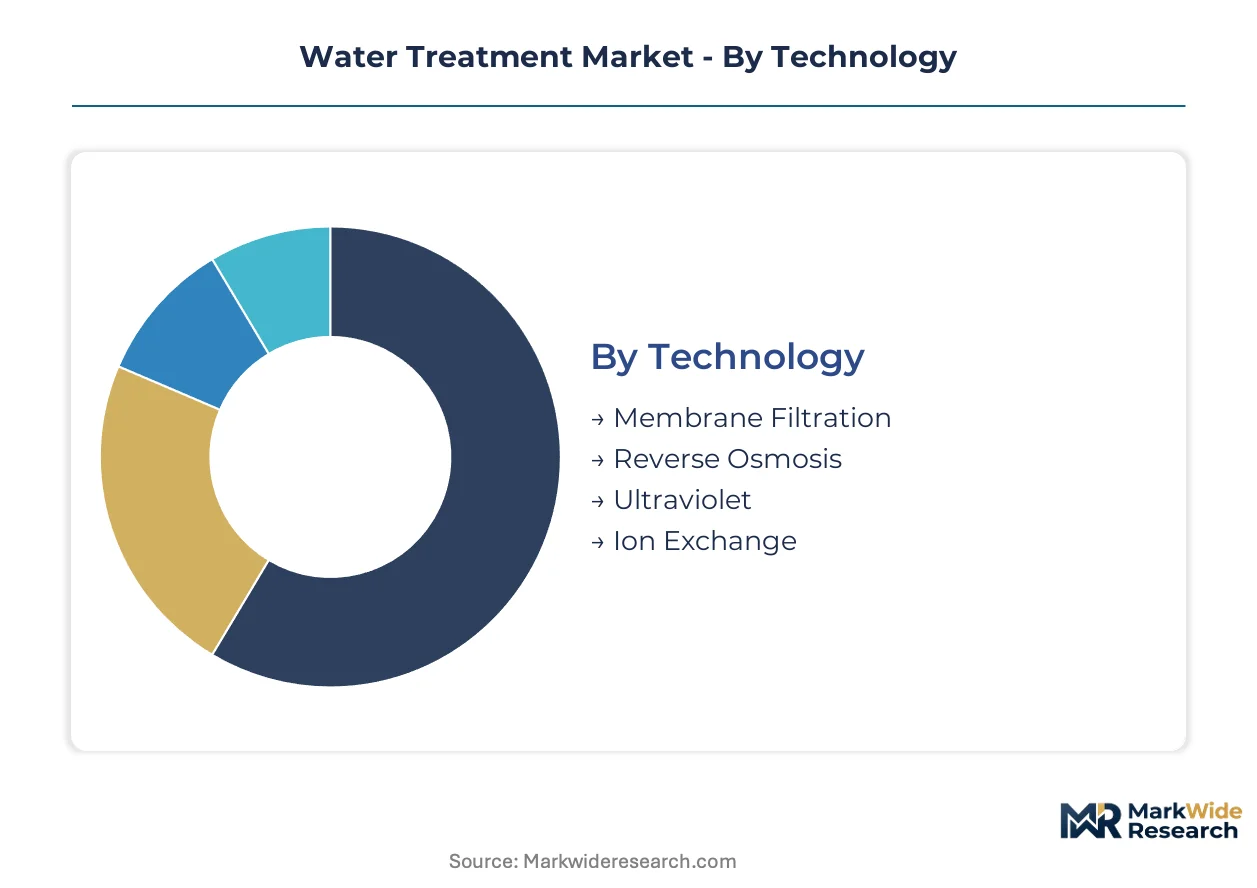
Market segmentation provides a granular view of the water treatment industry, revealing distinct demand drivers and technological preferences across various applications and end-users. Understanding these divisions helps stakeholders tailor solutions and optimize resource allocation within this complex and expanding sector.
Technology:
The water treatment technology landscape sees significant substitution pressure as advanced solutions challenge traditional methods, particularly for emerging contaminants.
- Membrane Filtration:This technology employs semi-permeable barriers to remove suspended solids, bacteria, and other particulates from water. Demand concentrates in wastewater reuse projects and industrial process water purification in nations like Singapore and Australia, driven by stringent discharge limits and water scarcity.
- Reverse Osmosis:Reverse osmosis utilizes high pressure to force water through a semi-permeable membrane, effectively rejecting dissolved salts and microscopic impurities. Large-scale desalination plants in Saudi Arabia and India are driving significant investment, securing potable water supplies for growing populations.
- Ultraviolet:Ultraviolet systems use UV-C light to disinfect water by deactivating microorganisms without chemical addition.
- Ion Exchange:Ion exchange resins remove specific dissolved ionic contaminants, including heavy metals and PFAS, from water streams.
Membrane Filtration anchors the volume base while Reverse Osmosis gains share at the steepest rate.
Product Type:
Cost tier differentiation significantly influences product type selection, with high-performance solutions commanding a premium due to their precision and efficacy.
- Filtration Systems:These systems encompass various physical barriers, including sand filters, cartridge filters, and media filters, designed to remove suspended solids and turbidity. Demand for robust filtration underpins municipal drinking water treatment in the United States and industrial pre-treatment processes globally, ensuring downstream system protection.
- Monitoring Solutions:This segment includes sensors, analytical instruments, and software platforms that track water quality parameters and system performance in real-time. Industrial facilities in Germany and municipal utilities in Japan seek these solutions for predictive maintenance and regulatory compliance, optimizing operational efficiency.
- Chemical Treatment:Chemical treatment involves the addition of coagulants, flocculants, and pH adjusters to purify water and manage scale or corrosion.
- Disinfection Equipment:This category includes technologies like chlorination systems, ozone generators, and UV disinfection units, vital for pathogen removal.
Filtration Systems contribute substantially to market volume, whereas Monitoring Solutions drive a disproportionate share of the value.
End User:
Application diversity shapes the end-user segment, with each sector presenting unique water quality requirements and operational scales.
- Industrial Applications:This segment includes diverse industries such as semiconductors, power generation, and food & beverage, requiring ultra-pure water for processes and compliant discharge. The semiconductor industry in Taiwan, for instance, demands exceptionally high purity water, driving advanced treatment technology adoption.
- Municipal Water:Municipalities manage drinking water supply and wastewater treatment for urban and rural populations, adhering to public health and environmental regulations. Cities across Europe are upgrading infrastructure to meet the European Union's Urban Wastewater Treatment Directive, affecting technology choices.
- Residential Use:Residential users employ point-of-use or point-of-entry systems for drinking water purification and general household water quality improvement.
- Commercial Establishments:This segment covers businesses like hotels, hospitals, and office buildings requiring water treatment for potable use, cooling, and hygiene.
Municipal Water users are heavily influenced by public health regulations, while Industrial Applications face stringent process-specific discharge standards.
Application:
Supply concentration for critical water resources directly influences the demand patterns across various water treatment applications.
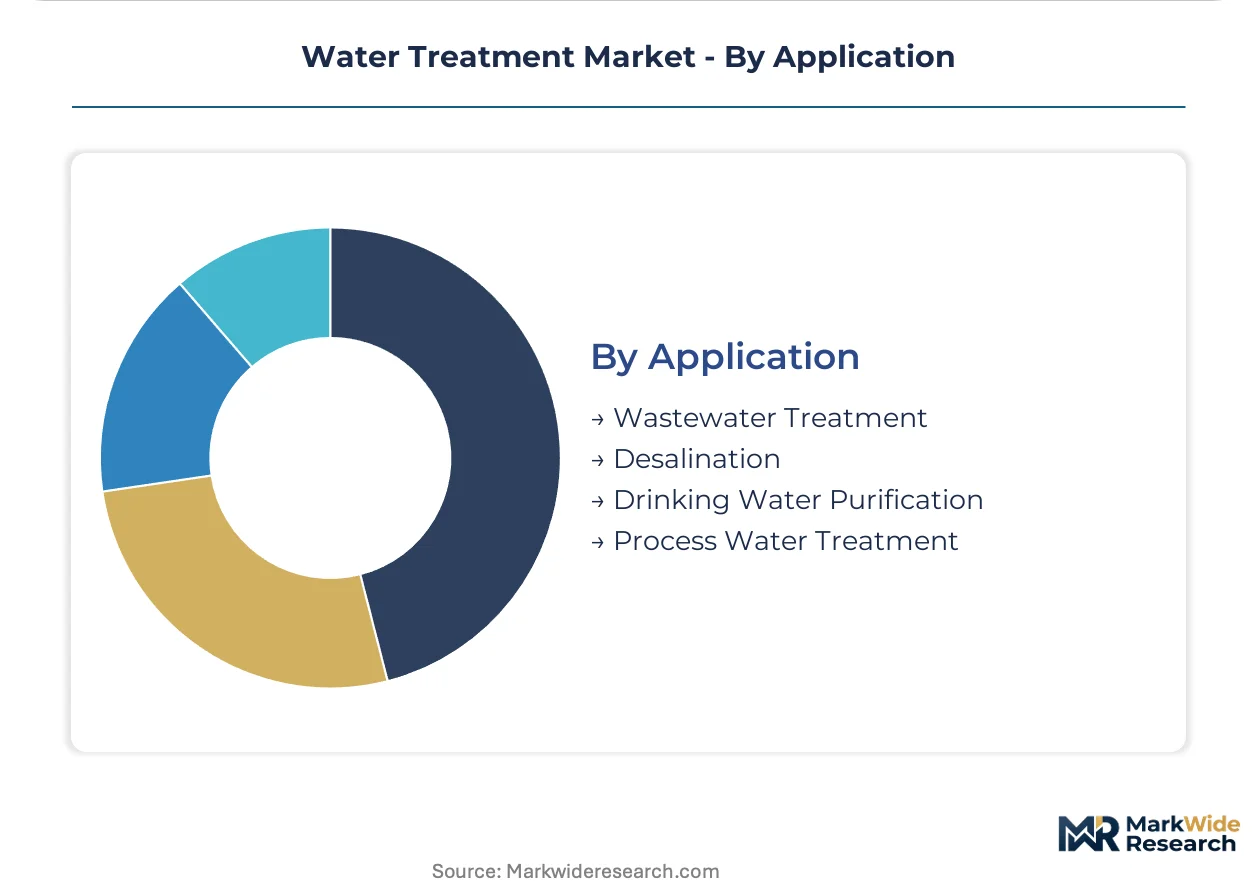
- Wastewater Treatment:This application involves treating domestic and industrial effluent to remove pollutants before discharge or reuse, meeting environmental protection agency standards. The Ministry of Ecology and Environment (MEE) in China drives significant investment in advanced wastewater treatment to achieve zero liquid discharge targets.
- Desalination:Desalination processes remove salt and other minerals from seawater or brackish water to produce fresh water, critical in arid regions. Nations like Saudi Arabia and the United Arab Emirates are investing heavily in large-scale desalination plants to address acute water scarcity.
- Drinking Water Purification:This segment focuses on treating raw water sources to meet potable water standards for human consumption.
- Process Water Treatment:Process water treatment purifies water for specific industrial uses, ensuring product quality and preventing equipment damage.
Wastewater Treatment requires a broad array of technologies, and Desalination projects demand highly specialized, energy-intensive solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The water treatment market exhibits a differential consumption mix across geographies, with some nations prioritizing municipal supply while others focus on industrial process water. This divergence shapes investment patterns in advanced technologies and infrastructure upgrades. Water scarcity and industrial demand serve as primary drivers.
United States
Demand for advanced treatment solutions in the United States stems from stringent regulatory mandates, particularly concerning emerging contaminants. The US Environmental Protection Agency (EPA) has established new enforceable limits on PFAS in drinking water, compelling utilities to upgrade existing infrastructure. Municipalities in California and New York are actively investing in granular activated carbon and reverse osmosis systems to ensure compliance.
India
India faces significant water scarcity issues, driving substantial investment in large-scale desalination and wastewater reuse projects. The government's initiatives to improve water security are creating sustained demand for membrane filtration and thermal distillation technologies. Cities like Chennai and Mumbai are expanding their water treatment capacities to meet the needs of growing urban populations.
Saudi Arabia
Saudi Arabia's arid climate necessitates heavy reliance on desalination to secure potable water supplies for its citizens and industries. The nation is investing billions in new and expanded desalination plants, often utilizing energy-intensive reverse osmosis and thermal distillation. Projects in the Eastern Province and NEOM are critical for economic development and urban expansion.
China
Chinese industries are compelled by the Ministry of Ecology and Environment (MEE) to meet stringent discharge standards, pushing toward zero liquid discharge systems. This regulatory pressure drives the adoption of advanced wastewater treatment technologies across various industrial sectors. The Yangtze River Delta region, with its dense industrial clusters, sees significant investment in process water treatment and reuse facilities.
Germany
German industrial facilities prioritize high-quality process water and efficient wastewater management, driven by strict environmental regulations and sustainability goals. The European Union's Urban Wastewater Treatment Directive guides investments in advanced biological nutrient removal and energy-neutral systems. Companies in industrial hubs like Bavaria and North Rhine-Westphalia are adopting monitoring solutions for predictive maintenance and operational optimization.
Water Treatment Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, defining the market's competitive structure. This tiered landscape includes global providers offering comprehensive solutions and niche players focusing on specific technologies or services. Portfolio diversification and strategic partnerships represent dominant competitive moves among market participants.
Within the integrated service provider archetype, Veolia exemplifies extensive global operations and R&D capabilities, securing complex, multi-year contracts for municipal and industrial water systems. Xylem occupies a position as a specialist, differentiating through high-tech monitoring, analytics, and smart water infrastructure components. Evoqua Water Technologies also sits within the specialized solutions segment, serving industrial and municipal clients with various treatment technologies.
| Leading Market Players |
|---|
| Ecolab |
| Evoqua Water Technologies |
| Veolia |
| Pentair |
| Aquatech International |
| SUEZ |
| Dow Water & Process Solutions |
| VA Tech Wabag |
| Xylem |
Cost & Logistics Intelligence
Long procurement lead times for specialized membrane modules directly shape the water treatment supply chain, influencing project scheduling and pricing power for integrated solution providers.
Pricing Analysis
Project-based contracts and long-term service agreements dominate the water treatment market's pricing model. Price differentiation stems from technology efficacy, such as advanced oxidation processes, and the comprehensive after-sales service packages offered. Pricing softness affects standard filtration components due to increased competition and commoditization. Municipal utilities, constrained by public budgets, exhibit the highest price sensitivity, often favoring lowest-cost compliant solutions, while industrial clients prioritize performance and reliability for critical processes.
Supply Chain Analysis
Strategic stockpiling of critical components, rather than just-in-time practices, characterizes the water treatment supply chain due to project-specific requirements and long lead times. Geographic supply concentration for advanced components centers in Germany for specialized instrumentation and China for many standard filtration media. Raw material dependencies include polymer resins for membranes and activated carbon for adsorption systems. Single-source vulnerability for highly specialized control systems presents a structural supply chain risk. Distribution runs through a network of engineering, procurement, and construction firms, alongside direct sales channels for large-scale industrial and municipal projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is positioned for a cyclical recovery, driven by the imperative for infrastructure upgrades to address aging systems and emerging contaminant threats.
For Market Incumbents: Consolidate market share through strategic acquisitions of niche technology providers, particularly those specializing in advanced oxidation processes or digital twin integration. Invest heavily in R&D for contaminant-specific solutions like PFAS destruction to counter the threat from agile, specialized firms. Leverage extensive global operational footprints to secure large-scale, multi-year municipal and industrial contracts, reinforcing a comprehensive service offering.
For New Entrants and Emerging Players: Differentiate on modular, decentralized treatment systems tailored for remote communities or specific industrial point-of-use applications. Target underserved industrial niches requiring ultra-pure water solutions, such as data centers or specialized manufacturing, as the most penetrable segment. A direct sales model, coupled with strong technical support and rapid deployment capabilities, offers a compelling go-to-market angle for these focused solutions.
For Investors and Strategic Acquirers: Long-term, this sits as a critical infrastructure upgrade play because of the increasing regulatory pressure and global water scarcity. Acquisition targets should focus on specialized technology providers with validated solutions for emerging contaminants or digital optimization platforms. The signal to watch for accelerated investment is the widespread implementation of new, enforceable regulatory limits on persistent pollutants by major economies.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for Membrane Production | Supports growing demand for desalination and wastewater reuse projects in water-stressed regions. |
| Investment in Advanced Oxidation Process R&D | Addresses the destruction of persistent organic pollutants like PFAS, expanding treatment capabilities. |
| Digital Twin Integration for Plant Optimization | Enhances operational efficiency and predictive maintenance for complex water treatment facilities. |
| Strategic Partnerships for Decentralized Solutions | Expands market reach into remote areas and specialized industrial applications with scalable units. |
| Acquisition of Water Quality Monitoring Firms | Strengthens real-time data analytics capabilities for regulatory compliance and process control. |
Research Approach
Operator-level perspectives from utility managers, process engineers, equipment manufacturers, and regulatory affairs specialists anchored the qualitative base for this study. This primary intelligence was rigorously combined with secondary validation from governmental environmental reports, industry association publications, and academic research. Bottom-up market sizing from specific projects and top-down validation against macroeconomic indicators ensured robust data integrity.
Sensitivity analysis framed the analytical framework, modeling market dynamics across the projection horizon. Segmentation dimensions modeled included technology, product type, end-user, application, and regional regulatory frameworks. Compound annual growth rates were derived through a proprietary regression model, incorporating industry-specific forecast inputs such as regulatory compliance timelines and regional water scarcity indices.
Material uncertainties — including geopolitical instability impacting energy prices or unforeseen technological breakthroughs — sit outside the modeled envelope. Forecasts reflect assumptions documented at the time of analysis. Revision becomes warranted when regulatory enforcement changes or major infrastructure funding shifts cross thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
Europe Water Treatment Chemicals Market
Water & Sludge Treatment
Global Mobile Water Treatment Market
Water & Sludge Treatment
Middle-East and Africa Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
Global Water Treatment Technology Market
Water & Sludge Treatment
South America Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
Asia-Pacific Water Free/ Waterless Urinals Market
Water & Sludge Treatment
India Water Treatment Market
Water & Sludge Treatment
Semiconductor Wastewater Treatment Market
Water & Sludge Treatment
Hypochlorous Acid Water Generator Market
Water & Sludge Treatment
North America Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
Nanotechnology in Water Treatment Market
Water & Sludge Treatment
Germany Water Treatment Chemicals Market
Water & Sludge Treatment
US Sludge Management and Dewatering Market
Water & Sludge Treatment
Water Purification Systems Market
Water & Sludge Treatment
Oil and Gas Water Treatment Chemicals Market
Water & Sludge Treatment
Industrial Water Treatment Chemicals Market