
 Global Sodium Hypochlorite Market | 2026-2036
Global Sodium Hypochlorite Market Size, Share, and Industry Trends Forecast 2026-2036
Global Sodium Hypochlorite Market Analysis
Maintenance contracts for on-site generation systems is decoupling equipment ownership from chemical supply in the sodium hypochlorite value chain. Vynova Group leverages its integrated chlor-alkali network to sustain cost-advantaged feedstock access across European production hubs. Olin Corporation anchors North American supply through its Gulf Coast manufacturing scale, while AkzoNobel differentiates via specialty formulations serving Nordic water utilities with stringent cold-climate performance requirements.
Sodium hypochlorite is an aqueous solution of sodium salt of hypochlorous acid, typically manufactured through the chlorination of caustic soda and commercially available in concentrations ranging from 5% to 15% available chlorine by weight; its primary industrial purpose centers on oxidation chemistry for pathogen inactivation, organic bleaching, and biofouling control. Industrial grade formulations dominate volume flows into municipal water treatment and pulp bleaching circuits where dosing precision and bulk logistics govern procurement economics. Household grade concentrates are gaining share through retail and distributor channels as consumer sanitation habits institutionalized during public health emergencies persist in developed markets.
The EPA regulates sodium hypochlorite under the Federal Insecticide, Fungicide, and Rodenticide Act for antimicrobial claims, while REACH in Europe mandates registration and hazard communication for chlorine-based disinfectants crossing threshold tonnages. India's Central Pollution Control Board enforces effluent standards that compel textile and paper mills to adopt hypochlorite-based bleaching sequences with controlled adsorbable organic halogen discharge limits. Stakeholders must monitor regulatory divergence between jurisdictions on byproduct formation limits and packaging waste rules to anticipate compliance-driven reformulation investments and regional sourcing reconfigurations.
Market Dynamics
Municipal procurement offices across developing economies are abandoning chlorine gas in favor of bulk hypochlorite systems, driven by safety liability concerns and infrastructure financing from multilateral development banks. This substitution cascade is compressing equipment lifecycles and rewiring chemical supply contracts toward service-based models.
Growth Catalysts
- EPA Stage 2 Disinfectants Rule:Drinking water utilities in the United States face mandated limits on disinfection byproducts, forcing upgrades from chlorine gas to hypochlorite dosing systems that generate fewer trihalomethanes.
- India urban water infrastructure:Smart Cities Mission funding and AMRUT scheme allocations are driving bulk hypochlorite procurement for new treatment plants in Tier-1 and Tier-2 cities.
- On-site generation technology:Electrochlorination systems using membrane cell technology are eliminating transportation hazards and degradation losses for coastal industrial users.
Market Restraints
- Caustic soda price volatility:Feedstock costs for sodium hypochlorite production fluctuate with chlorine-alkali capacity utilization and energy pricing, squeezing converter margins.
- Gulf Coast supply concentration:North American merchant hypochlorite supply clusters along hurricane-exposed chemical corridors, creating business continuity exposure.
- Peracetic acid substitution:Food and beverage processors are adopting peracetic acid for cold-chain sanitation where chlorine residuals conflict with organic certification requirements.
Strategic Opportunities
- Vietnam municipal water:Foreign investment in water treatment infrastructure under the country's environmental masterplan creates first-mover positioning for bulk chemical suppliers.
- EU Green Deal procurement criteria:Public tender scoring that rewards reduced carbon intensity in chemical supply chains advantages producers with renewable-powered chlor-alkali assets.
- Maintenance-as-a-service bundling:Remote monitoring platforms paired with predictive dosing algorithms are enabling annuity revenue streams that decouple supplier economics from commodity chlorine pricing.
Industry Challenges
- Electrochemical process engineering talent:On-site generation deployment requires scarce expertise in brine purification, electrode maintenance, and hydrogen handling protocols.
- REACH registration timelines:European chemical suppliers face extended dossier preparation periods for biocidal product authorization under the Biocidal Products Regulation.
- Legacy dosing system incompatibility:Retrofitting gas-based chlorination infrastructure for hypochlorite chemistry demands capital-intensive materials upgrades to resist accelerated corrosion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Sodium Hypochlorite Market |
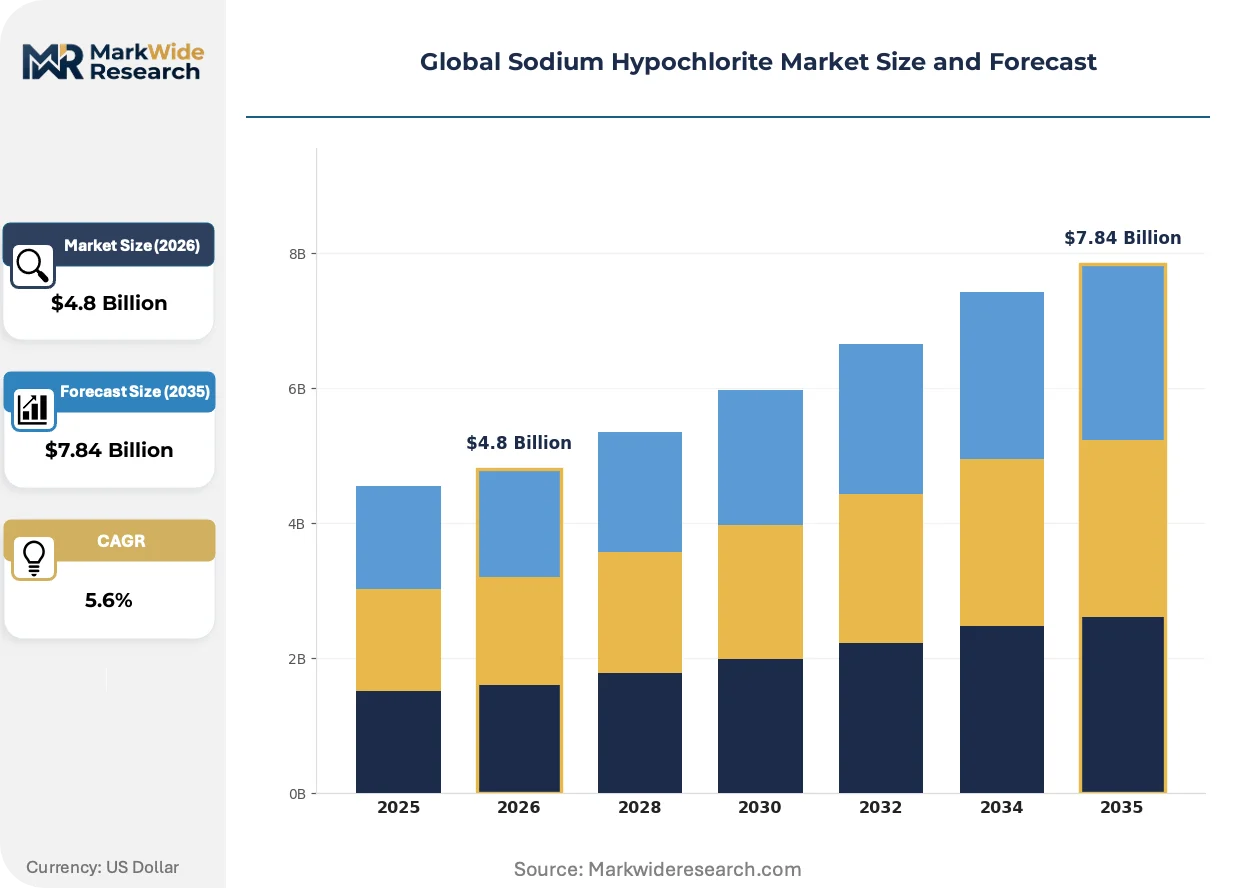
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.84 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Commercial Grade, Household Grade, Lab Grade Application: Water Treatment, Textile Manufacturing, Pulp & Paper, Bleaching Agent End User: Municipalities, Water Utilities, Food & Beverage Industry, Chemical Industry Distribution Channel: Direct Sales, Online Sales, Retail, Distributors |
| Companies Covered | Vynova Group, PPG Industries, OxyChem Corporation, Westlake Chemical Corporation, AkzoNobel, Olin Corporation, Hawkins, Inc., PCC Group, Tessenderlo Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Sodium Hypochlorite Market Emerging Trajectories
Electrochemical process intensification and digital dosing control are converging to displace conventional batch manufacturing and manual chemical handling. These shifts are compressing supply chains and redefining competitive advantage around service integration rather than commodity scale.
Membrane electrolysis for on-site sodium hypochlorite generation is overtaking delivered bulk chemical supply in coastal municipal and industrial installations. Desalination plants and offshore platforms are adopting skid-mounted electrochlorination units to eliminate hazardous material shipping. This technology is overtaking traditional merchant supply by collapsing logistics costs and removing degradation losses during storage.
REACH authorization requirements for chlorine-based biocides are tightening hazard communication and use-restriction protocols across European manufacturing and water treatment sectors. Downstream formulators must reclassify products and reformulate concentrations to maintain market access. Industrial laundries and food processors in Germany and France are accelerating substitution assessments to preempt regulatory discontinuity.
Bulk chemical procurement through integrated service contracts is displacing spot purchasing and equipment ownership for municipal water utilities. Brazilian and Indonesian cities are piloting performance-based contracts where chemical supply, dosing equipment, and compliance monitoring are bundled under single-source arrangements. This model concentrates vendor selection authority with procurement offices while transferring operational risk to chemical suppliers.
Global Sodium Hypochlorite Market Segmentation
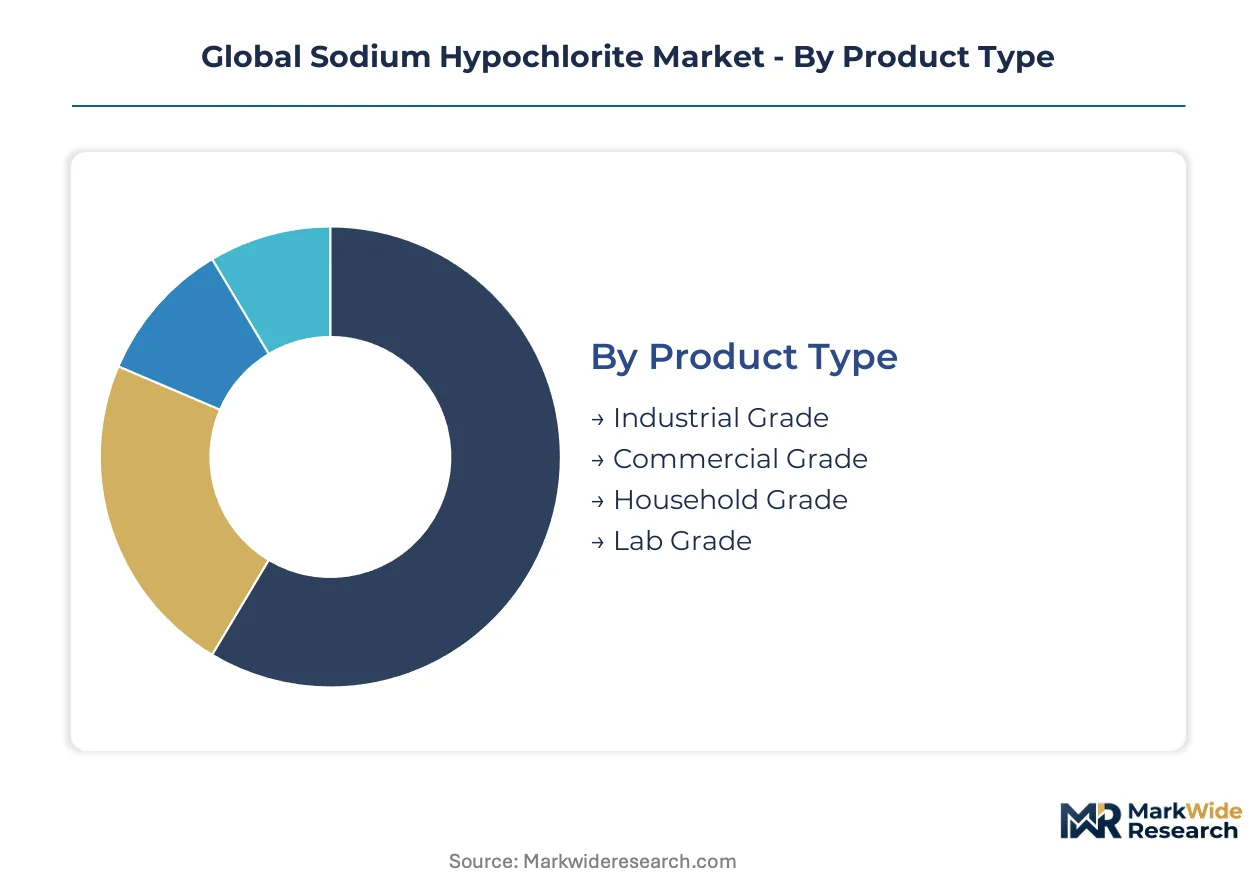
Sodium hypochlorite procurement economics vary sharply across concentration grades and delivery modes. Segment boundaries determine margin structures, regulatory exposure, and the feasibility of on-site generation versus merchant supply.
Product Type:
Industrial grade formulations operate as standalone commodities in bulk water treatment, while household and lab grades embed into packaged consumer goods and analytical workflows.
- Industrial Grade:Concentrations of 10-15% available chlorine serve municipal dosing systems and pulp bleaching circuits. Demand clusters in Indian urban water infrastructure upgrades and Gulf Coast chemical manufacturing corridors where bulk logistics dominate procurement.
- Commercial Grade:Intermediate concentrations of 6-10% available chlorine balance handling safety with oxidation efficacy for food processing sanitation. Brazilian meatpacking plants and Indonesian seafood processors are expanding procurement as cold-chain hygiene mandates tighten.
- Household Grade:3-6% solutions packaged for retail sanitation channels.
- Lab Grade:High-purity specifications for analytical chemistry and pharmaceutical quality control.
Volume placements concentrate in Industrial Grade; the faster expansion belongs to Commercial Grade.
Application:
Water treatment applications generate recurring bulk demand with long contract durations, while textile and bleaching agents face substitution pressure from peroxide-based alternatives.
- Water Treatment:Pathogen inactivation in drinking water and wastewater systems represents the anchor application. EPA Stage 2 compliance deadlines and India's AMRUT scheme allocations are accelerating hypochlorite system upgrades in US Midwest utilities and Maharashtra municipal corporations.
- Bleaching Agent:Organic oxidation in pulp processing and textile finishing maintains volume despite environmental scrutiny. Nordic paper mills are retrofitting dosing infrastructure to meet EU Green Deal procurement criteria for reduced carbon intensity.
- Textile Manufacturing:Cotton bleaching and dye house preparation in South Asian export zones.
- Pulp & Paper:Kraft pulp delignification and brightness enhancement.
Water Treatment commands the largest contract values; Bleaching Agent is climbing the fastest as mills phase out elemental chlorine.
End User:
Municipalities and water utilities operate on public procurement cycles with multi-year tenders, while food and chemical processors prioritize supply security over price optimization.
- Municipalities:City governments managing drinking water treatment for populations exceeding 100,000. Vietnamese provincial water authorities and Indonesian district utilities are piloting performance-based chemical service contracts.
- Water Utilities:Regional transmission and treatment operators with specialized engineering staff. German municipal utilities are bundling electrochlorination maintenance into long-term service agreements.
- Food & Beverage Industry:Dairy processors and beverage bottlers requiring chlorine residual control.
- Chemical Industry:Chlor-alkali derivatives manufacturing and intermediate synthesis.
Municipalities dominate tender volumes; Water Utilities show the steepest expansion trajectory as service contracts displace spot purchasing.
Distribution Channel:
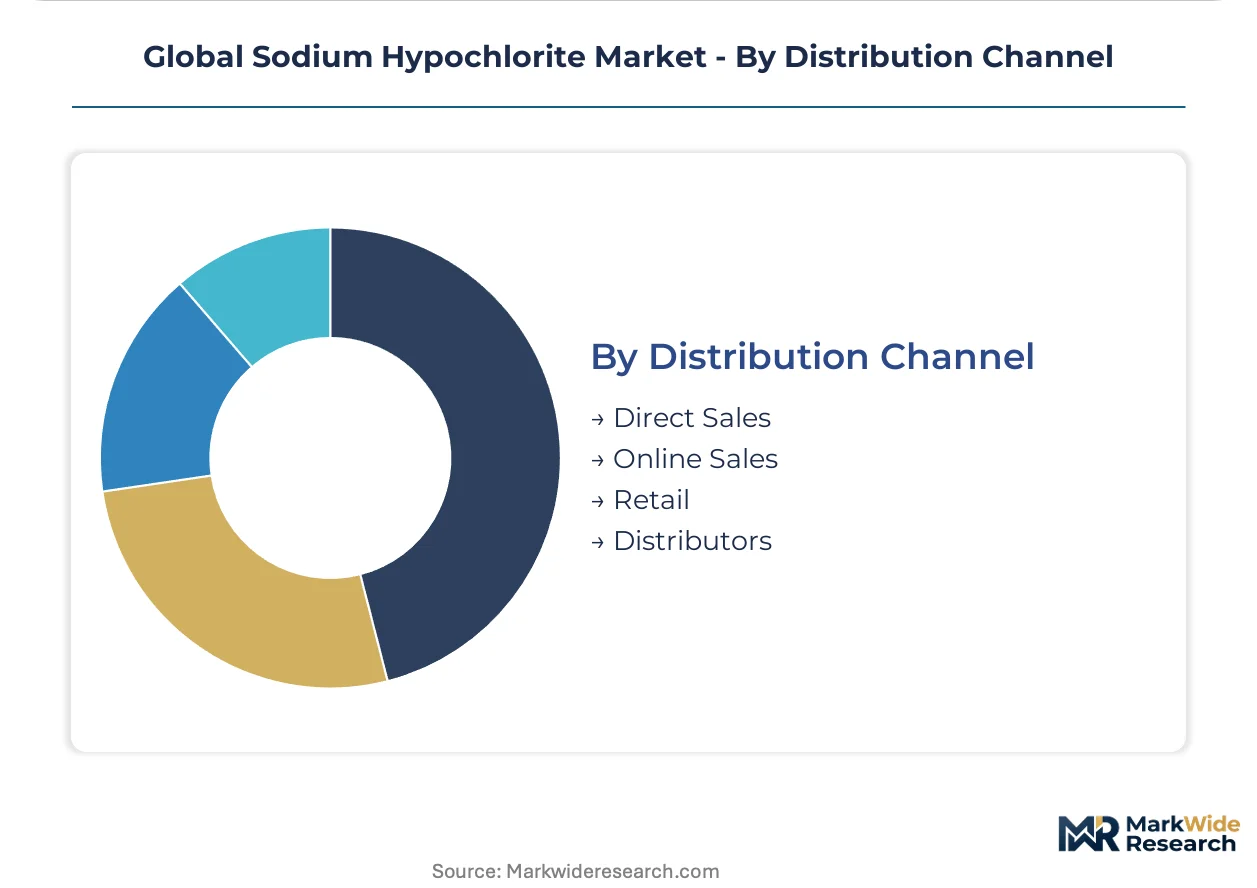
Direct sales relationships govern industrial bulk supply, while retail and online channels fragment household grade into low-margin commodity competition.
- Direct Sales:Producer-to-end-user contracts for tanker truck and railcar delivery of industrial grades. Olin Corporation and Vynova Group leverage integrated chlor-alkali networks to secure direct supply agreements with US and European water authorities.
- Distributors:Regional chemical wholesalers stocking multiple concentration grades for smaller municipal and commercial accounts. Indian distributor networks are consolidating to capture Smart Cities Mission procurement flows.
- Online Sales:E-commerce platforms for household grade and specialty formulations.
- Retail:Mass merchant and grocery channels for consumer sanitation products.
Direct Sales captures the heaviest volume tonnage; Distributors are gaining share fastest as mid-size utilities outsource procurement complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Merchant production clusters along the US Gulf Coast and northwestern Europe, while consumption gravity shifts toward Indian municipal water systems and Southeast Asian industrial zones. This geographic disconnect is rewiring trade flows and regional pricing structures.
United States
EPA Stage 2 compliance deadlines are forcing Midwest utilities to convert gas chlorination plants to hypochlorite dosing. The Federal Insecticide, Fungicide, and Rodenticide Act governs antimicrobial claims. Houston-Galveston corridor producers serve municipal contracts from Texas to the Great Lakes.
Germany
Nordic water utilities demand cold-climate formulations with extended stability windows. REACH and the Biocidal Products Regulation impose extended authorization timelines for chlorine-based disinfectants. Rhine-Ruhr chemical manufacturers supply municipal networks across northern Europe.
India
Smart Cities Mission funding and AMRUT scheme allocations are driving bulk procurement for Tier-1 and Tier-2 urban treatment plants. The Central Pollution Control Board enforces textile effluent standards that compel hypochlorite-based bleaching. Maharashtra municipal corporations represent the densest concentration of new plant commissioning.
Vietnam
Foreign investment in water treatment infrastructure under the national environmental masterplan is creating first-mover opportunities for bulk chemical suppliers. Provincial water authorities are piloting performance-based service contracts. Ho Chi Minh City and Hanoi metro systems anchor demand growth.
Brazil
Meatpacking plants and seafood processors are expanding commercial-grade procurement as cold-chain hygiene mandates tighten. ANVISA regulates sanitizer formulations for food contact surfaces. São Paulo state utilities are bundling electrochlorination maintenance into long-term agreements.
Global Sodium Hypochlorite Market Vendor Landscape
Capital-heavy chlor-alkali producers compete with asset-light regional blenders and on-site generation technology providers. The structure concentrates around integrated chemical majors with captive chlorine supply, mid-scale regional converters, and emerging electrochlorination specialists. Three archetypes dominate: backward-integrated commodity suppliers, regional distributors with logistics networks, and technology licensors selling skid-mounted generation systems. Capacity expansion along hurricane-exposed corridors and service-based contract restructuring represent the dominant competitive vectors.
Among European integrated producers, Vynova Group and AkzoNobel occupy positions defined by chlor-alkali network density and specialty formulation capabilities respectively. Olin Corporation anchors North American supply scale through Gulf Coast manufacturing positions. These three exemplify how feedstock access, geographic concentration, and regulatory compliance specialization determine competitive positioning in merchant hypochlorite markets.
| Leading Market Players |
|---|
| Vynova Group |
| PPG Industries |
| OxyChem Corporation |
| Westlake Chemical Corporation |
| AkzoNobel |
| Olin Corporation |
| Hawkins, Inc. |
| PCC Group |
| Tessenderlo Group |
| Others |
Supply Flow & Price Mechanics
Captive chlor-alkali integration across Gulf Coast and northwest European production hubs anchors both supply security and pricing leverage for merchant hypochlorite producers. This backward integration into caustic soda and chlorine feedstocks insulates integrated majors from spot raw material volatility while compressing margins for non-integrated regional blenders competing on delivered cost.
Pricing Analysis
Margin tightening in industrial grade bulk supply reflects caustic soda price volatility and energy cost pass-through pressures from European natural gas markets. Contract-based long-term offtake agreements dominate municipal procurement, with price differentiation resting on volume scale and geographic delivery cost rather than quality grade. Food processors demonstrate lowest price sensitivity due to chlorine residual compliance requirements, while mid-size commercial laundries face acute cost-down pressure from peracetic acid substitution threats.
Supply Chain Analysis
Electrochemical process engineering talent scarcity in coastal manufacturing zones constrains expansion of on-site generation capacity despite demand pull from desalination and offshore platforms. Merchant supply clusters in the United States, Germany, and India, with raw material dependencies on salt, caustic soda, and membrane cell technology. Single-source vulnerability haunts hurricane-exposed Gulf Coast corridors, while distribution runs through tanker truck and railcar direct sales for industrial grades and regional distributor networks for commercial accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where feedstock control and service contract bundling represent the decisive levers. Players are pursuing captive chlor-alkali capacity and predictive dosing platforms to escape commodity chlorine pricing cycles.
For Market Incumbents: Deploy predictive maintenance platforms to lock municipal utilities into annuity revenue streams that resist spot price erosion. Consolidate regional distributor networks in India to capture Smart Cities Mission procurement flows. Peracetic acid substitution in organic-certified food processing threatens volume retention in commercial grades. For New Entrants and Emerging Players: Mid-size Vietnamese provincial water authorities offer the most penetrable buyer archetype as foreign investment floods water infrastructure under the national environmental masterplan. Electrochlorination skid systems for coastal industrial users bypass merchant chemical logistics entirely. Partner with membrane cell technology licensors to shortcut electrochemical process engineering talent scarcity. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated chlor-alkali majors seeking geographic density in high-growth Asian municipal markets. Long-term viability hinges on service contract bundling rather than commodity scale. Watch electrochlorination penetration rates in Brazilian and Indonesian pilot cities as inflection indicator for merchant supply displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Caustic Soda | Captive feedstock access insulates margin compression from energy-linked chlorine-alkali volatility. |
| Electrochlorination Technology Licensing | Skid-mounted on-site generation eliminates hazardous material shipping for coastal desalination plants. |
| Performance-Based Service Contracting | Bundled chemical supply and compliance monitoring transfers operational risk from municipalities to suppliers. |
| Green Manufacturing Transition | Renewable-powered chlor-alkali assets score preferential tender treatment under EU Green Deal procurement criteria. |
| Joint Venture in Vietnam Water Infrastructure | Foreign investment partnerships under the environmental masterplan create first-mover positioning in untreated municipal markets. |
Methodological Framework
Document review covered customs and trade databases, chlor-alkali industry association reports, and EPA regulatory filings, complemented by interviews with municipal water treatment plant managers, chlor-alkali procurement leads at downstream OEMs, electrochlorination technology licensors, and distributor channel partners across India and Southeast Asia. Bottom-up volume estimates from plant-level capacity and utilization data were triangulated against top-down demand projections from water infrastructure investment disclosures.
Segment-level outputs across the analysis window reflect modeling of grade tier, end-use industry, regional production hub, and delivery mode dimensions. CAGRs were derived from regression analysis of historical capacity expansion patterns and forward projections of municipal procurement cycle timing. Forecast inputs incorporated AMRUT scheme allocation trajectories and REACH biocidal product authorization timeline assumptions.
Revisions become necessary when caustic soda price volatility exceeds historical bands, electrochlorination technology cost curves shift materially, or regulatory divergence on byproduct formation limits accelerates reformulation requirements. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
Asia-Pacific Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
Water Gel Market
Water & Sludge Treatment
Salt Water Softeners Market
Water & Sludge Treatment
Process Chemicals for Water Treatment Market
Water & Sludge Treatment
United States Water Treatment Chemicals Market
Water & Sludge Treatment
South America Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
Asia-Pacific Membrane Water and Wastewater Treatment (WWT) Market
Water & Sludge Treatment
Australia Water Treatment Chemicals Market
Water & Sludge Treatment
Liquid Waste Container Market
Water & Sludge Treatment
India Water and Wastewater Treatment (WWT) Technology Market
Water & Sludge Treatment
Internal Boiler Treatment Chemicals Market
Water & Sludge Treatment
Ultrapure Water Market
Water & Sludge Treatment
North America Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
Slurry Heaters Market
Water & Sludge Treatment
Asia-Pacific Water Treatment Chemicals Market
Water & Sludge Treatment
China Water Treatment Chemicals Market