
 India Water Treatment Market | 2026-2036
India Water Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
India Water Treatment Market Insights
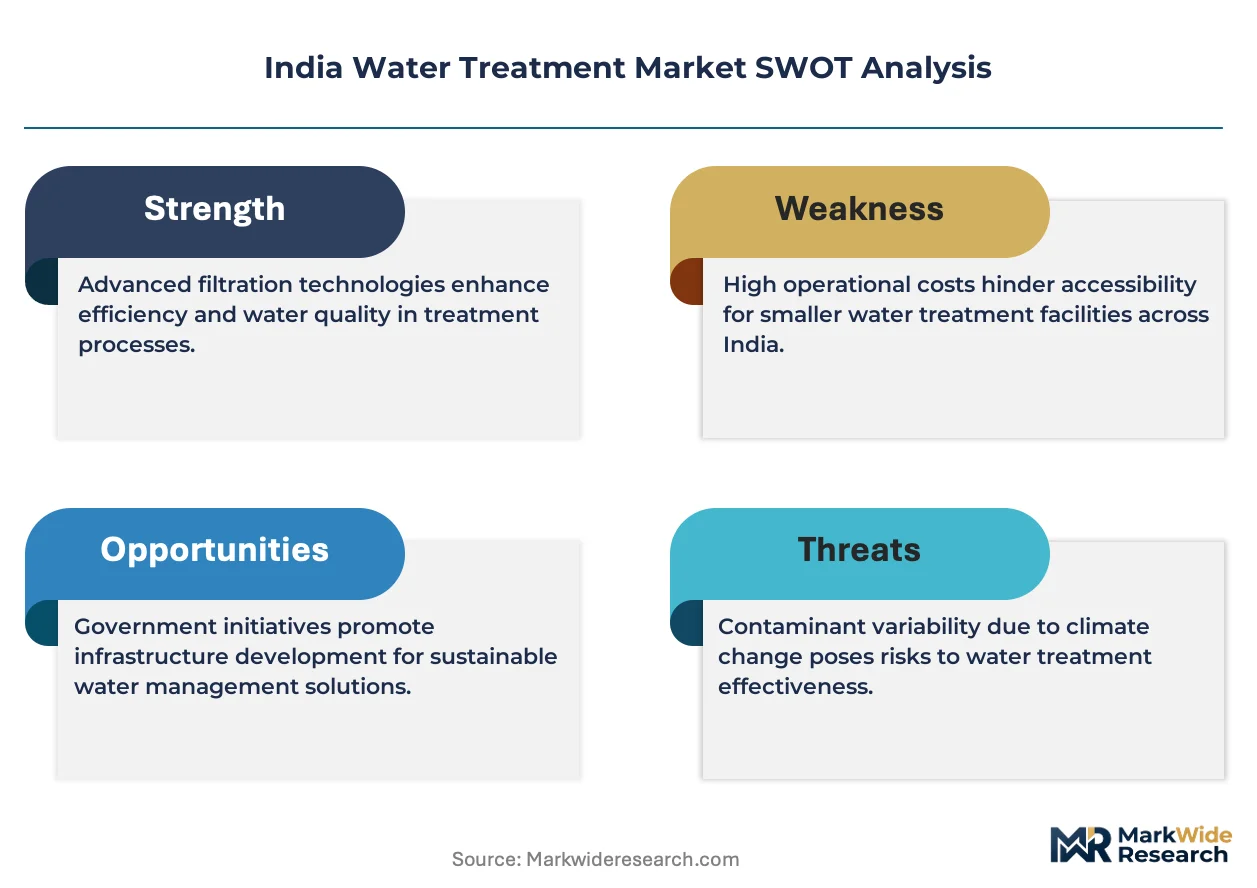
Gujarat's industrial effluent treatment capacity is realigning around zero-liquid-discharge mandates for textile and chemical parks. Thermax leverages its captive boiler-water expertise to cross-sell integrated treatment packages across the state's Special Economic Zones. VA Tech Wabag sustains its dominance in large-scale municipal desalination and sewage treatment through engineering-intensive project execution. Ion Exchange specializes in resin-based demineralization systems that anchor its position in India's power sector cooling-water segment.
Water treatment encompasses physical, chemical, and biological processes that remove suspended solids, dissolved contaminants, and microbial pathogens from raw water to render it suitable for specific end uses; reverse osmosis systems operate at transmembrane pressures of 10–80 bar to separate dissolved ions from brackish or seawater feed streams, while disinfection technologies deploy chlorine, ozone, or ultraviolet irradiation to achieve potable water microbiological standards. Reverse osmosis leads technology adoption where groundwater salinity exceeds BIS drinking-water limits, particularly in Rajasthan and coastal Tamil Nadu. Municipal supply applications command the largest project value pools, though industrial reuse systems for refineries and semiconductor fabrication plants represent the fastest-expanding application segment.
The Central Pollution Control Board enforces effluent discharge standards under the Water (Prevention and Control of Pollution) Act, compelling textile processors and tanneries to install tertiary treatment. BIS drinking-water specifications and the Jal Jeevan Mission's household tap-connection targets together reshape product certification requirements and procurement volumes for rural ultrafiltration units. Stakeholders must monitor state-level groundwater extraction regulations and the evolving Bureau of Indian Standards framework for recycled water quality, as these will determine which technology configurations qualify for public funding and industrial operating permits.
Market Dynamics
Zero-liquid-discharge mandates from the Central Pollution Control Board are forcing industrial clusters across Gujarat and Tamil Nadu to overhaul legacy effluent infrastructure, compressing project timelines and reshaping vendor qualification criteria.
Growth Catalysts
- Jal Jeevan Mission:The national rural tap-connection program is generating procurement volumes for decentralized ultrafiltration and reverse osmosis units in water-stressed districts of Maharashtra and Rajasthan.
- Textile cluster consolidation:Integrated processing parks in Surat and Tiruppur are mandating captive tertiary treatment, creating bundled demand for membrane bioreactors and evaporator systems.
- Groundwater salinity thresholds:BIS drinking-water specifications are accelerating brackish-water reverse osmosis deployment in coastal Tamil Nadu where aquifer intrusion exceeds permissible limits.
Market Restraints
- Membrane import dependence:Polyamide thin-film composite elements for high-pressure reverse osmosis remain concentrated among East Asian suppliers, exposing project EPCs to currency volatility and shipping delays.
- Power sector capex cycles:Thermal plant commissioning slowdowns are compressing demand for resin-based demineralization systems that anchor supplier order books.
- Skilled operator scarcity:Remote municipal plants in Bihar and Uttar Pradesh face sustained downtime due to inadequate training infrastructure for membrane cleaning and chemical dosing protocols.
Strategic Opportunities
- Semiconductor fabrication:Ultra-pure water systems for chip manufacturing are expanding in Karnataka and Telangana as PLI scheme incentives attract foundry investments.
- Industrial reuse certification:Evolving Bureau of Indian Standards frameworks for recycled water quality are creating first-mover advantages for vendors with proven tertiary treatment track records.
- IoT-enabled predictive maintenance:Sensor-integrated membrane monitoring is penetrating Gujarat's chemical parks where unplanned downtime carries penalty clauses.
Industry Challenges
- Legacy plant integration:Brownfield municipal sites in older Maharashtra cities face space constraints and civil foundation incompatibility with modular containerized treatment units.
- Operator certification timelines:State pollution control board licensing requirements for effluent plant managers are extending commissioning schedules by four to eight months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Water Treatment Market |
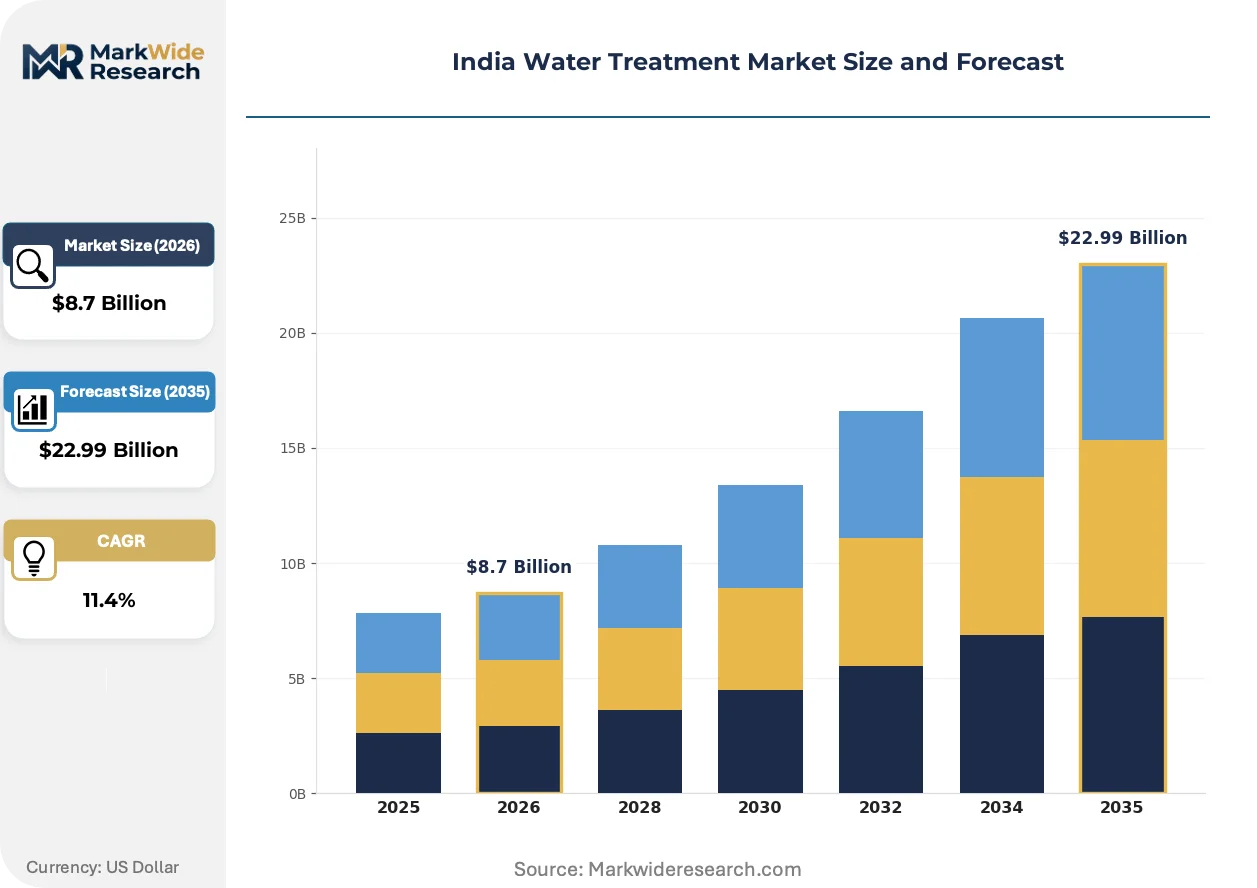
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Reverse Osmosis, Filtration, Disinfection, Ion Exchange Application: Industrial Use, Municipal Supply, Residential Use, Agricultural Use End User: Utilities, Commercial Buildings, Agriculture, Households Distribution Channel: Direct Sales, Retail Outlets, Online Sales, Distributors |
| Companies Covered | Thermax, Veolia, VA Tech Wabag, Voltas, Ecolab, Netsol Water, Siemens India, Hindustan Dorr-Oliver, Ion Exchange, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Water Treatment Market Trends and Innovations
Electrochemical advanced oxidation processes are gaining traction as textile processors seek alternatives to chemical-intensive tertiary treatment, while digital twin platforms are compressing commissioning cycles for complex membrane trains.
Membrane distillation systems are expanding into zero-liquid-discharge applications for high-salinity textile effluents where conventional reverse osmosis reaches osmotic limits. Chemical processors in Gujarat's Special Economic Zones are piloting these configurations to meet discharge mandates without evaporator energy penalties. The technology is expanding into modular skid formats that reduce civil works and accelerate site deployment.
The Central Pollution Control Board's 2023 amendments to effluent discharge norms under the Water Act are mandating real-time online monitoring for tanneries and dye houses. Plant operators must install continuous effluent quality transmitters linked to state regulatory portals. Tamil Nadu's leather cluster around Ambur is responding fastest, with processors retrofitting automated sampling and data transmission infrastructure to avoid permit suspensions.
Refinery operators are unbundling long-term service contracts and competitively rebidding membrane replacement and chemical supply separately from capital equipment. This disintermediation is compressing margins for integrated EPC vendors while creating openings for specialized membrane resellers and chemical dosing specialists. The pattern is most visible in Gujarat's Jamnagar and Vadinar complexes where procurement teams have adopted category management frameworks from parent international oil companies.
India Water Treatment Market Segmentation
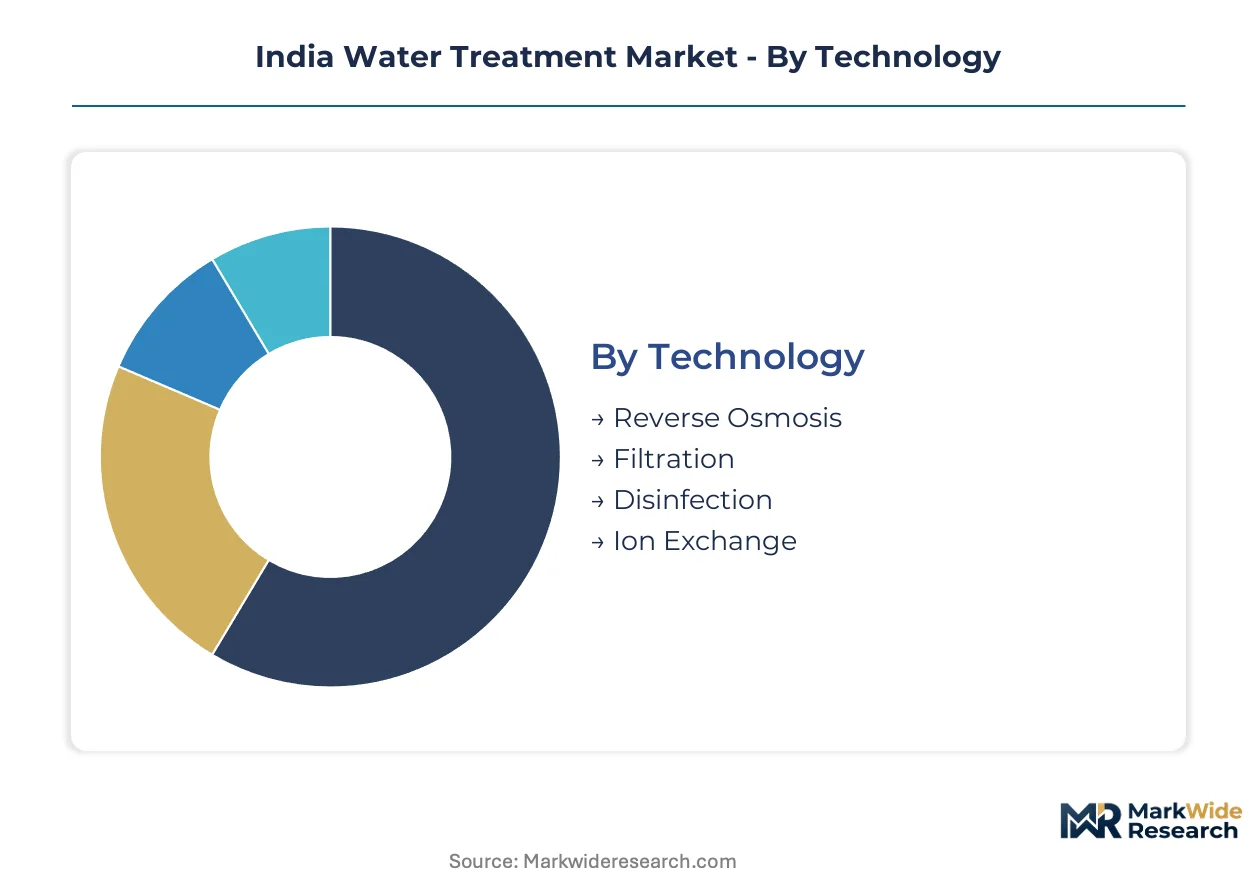
Technology configuration determines capital intensity and operating cost structures across India's water treatment landscape. Application context shapes regulatory compliance requirements and procurement decision-making timelines.
Technology:
Pressure-driven membrane separation and chemical substitution methods dominate installed capacity across industrial and municipal deployments.
- Reverse Osmosis:Semi-permeable polyamide thin-film composite membranes operate at 10–80 bar transmembrane pressure to reject dissolved ions from brackish groundwater and seawater. Deployment concentrates in coastal Tamil Nadu and Rajasthan where aquifer salinity exceeds BIS drinking-water limits, with textile processors in Tiruppur adopting tertiary RO for zero-liquid-discharge compliance.
- Filtration:Physical barrier separation using sand, activated carbon, or membrane media removes suspended solids and particulate matter. Municipal utilities in Maharashtra and Gujarat prioritize rapid gravity filtration for surface water treatment, while ultrafiltration skids serve Jal Jeevan Mission rural tap-connection targets in water-stressed districts.
- Disinfection:Chlorination, ozonation, and ultraviolet irradiation achieve microbiological compliance for potable water distribution networks.
- Ion Exchange:Synthetic resin beds selectively remove dissolved ions through reversible chemical substitution reactions.
Mature deployment sits with Filtration. Newer deployment is concentrated in Reverse Osmosis.
Application:
End-use context dictates scale economics, regulatory scrutiny intensity, and technology bundling requirements.
- Industrial Use:Captive treatment systems serve process water, cooling circuits, and effluent compliance for manufacturing facilities. Refineries in Gujarat's Jamnagar complex and semiconductor fabrication plants in Karnataka drive ultra-pure water demand, while textile parks in Surat mandate integrated tertiary treatment for zero-liquid-discharge adherence.
- Municipal Supply:Centralized treatment infrastructure serves urban distribution networks and rural tap-connection programs. The Jal Jeevan Mission generates procurement volumes for decentralized ultrafiltration and reverse osmosis units across Maharashtra and Rajasthan, with large-scale desalination projects addressing coastal city demand.
- Residential Use:Point-of-entry and point-of-use systems address household drinking-water quality concerns.
- Agricultural Use:Irrigation water treatment mitigates soil salinization and crop yield impacts from contaminated sources.
Volume concentration favors Municipal Supply. Margin expansion is steepest in Industrial Use.
End User:
Procurement sophistication and contract tenure vary sharply across institutional and dispersed customer bases.
- Utilities:State water boards and municipal corporations execute multi-year EPC contracts for centralized treatment infrastructure. Maharashtra and Gujarat utilities lead capacity expansion, with engineering-intensive project execution favoring vendors with proven commissioning track records.
- Commercial Buildings:Hotels, hospitals, and office complexes install captive treatment for operational reliability and brand protection.
- Agriculture:Cooperative and individual farming operations deploy filtration and disinfection for irrigation source management.
- Households:Individual consumers purchase point-of-use systems through retail and online channels.
Contract scale peaks with Utilities. Purchase frequency is highest among Households.
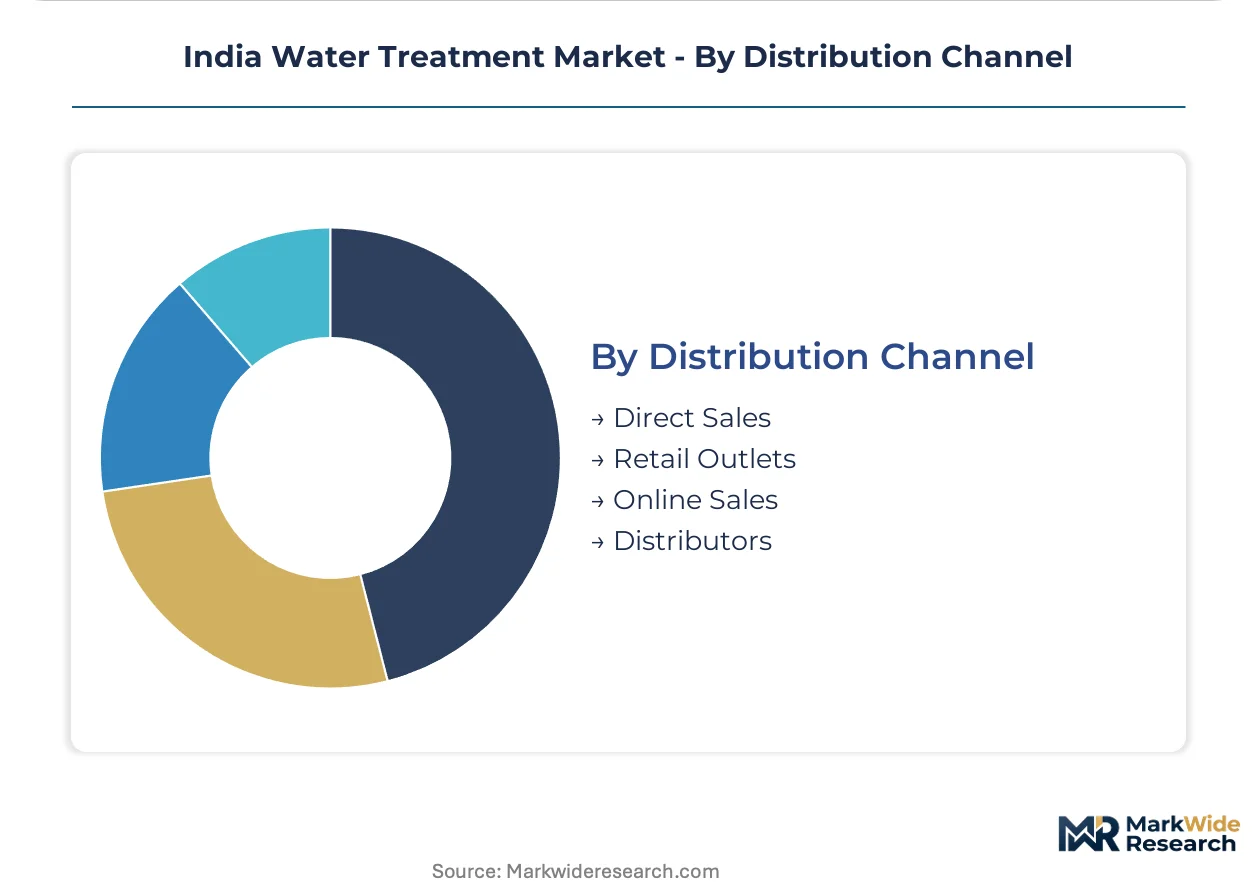
Distribution Channel:
Channel selection reflects equipment complexity, service attachment requirements, and buyer procurement maturity.
- Direct Sales:Manufacturer-led engagement for large-scale municipal and industrial EPC contracts. Thermax and VA Tech Wabag deploy dedicated project teams for Gujarat Special Economic Zones and Maharashtra urban utilities, with long-term service contracts bundled at inception.
- Distributors:Regional stockists and technical representatives serve mid-scale commercial and industrial accounts.
- Retail Outlets:Branded dealer networks and big-box stores reach residential and small commercial buyers.
- Online Sales:E-commerce platforms and direct-to-consumer digital channels penetrate tier-2 and tier-3 city markets.
Project value aggregates through Direct Sales. Volume throughput is expanding fastest in Online Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Groundwater basins across Gujarat, Tamil Nadu, and Maharashtra anchor treatment capacity expansion. The Narmada, Cauvery, and Godavari river systems face competing extraction pressures from agriculture, industry, and urban utilities.
Gujarat
Special Economic Zones in Ahmedabad and Vadodara drive captive effluent treatment demand for textile and chemical processors. The state's zero-liquid-discharge mandates under Central Pollution Control Board directives compress project timelines for membrane bioreactor installations. Surat's diamond polishing and synthetic textile clusters retrofit tertiary treatment to meet real-time discharge monitoring requirements.
Maharashtra
Mumbai's municipal corporation expands desalination capacity to reduce dependence on monsoon-fed reservoirs. The Jal Jeevan Mission generates procurement volumes for decentralized ultrafiltration units across Marathwada's water-stressed districts. Pune's automotive and semiconductor fabrication corridors drive ultra-pure water system specifications.
Tamil Nadu
Coastal aquifer salinity intrusion exceeds BIS drinking-water limits in Chennai's peripheral districts, accelerating brackish-water reverse osmosis deployment. Tiruppur's knitwear export cluster mandates integrated tertiary treatment for zero-liquid-discharge compliance. Ambur's leather processors retrofit automated effluent quality transmitters to avoid permit suspensions.
Karnataka
Bengaluru's electronics manufacturing cluster attracts semiconductor foundry investments under PLI scheme incentives, expanding ultra-pure water demand. The state's groundwater extraction regulations tighten permitting for commercial borewells in drought-prone districts. Mysuru's food processing parks install membrane-based reuse systems to reduce freshwater intake.
Rajasthan
Thar Desert groundwater salinity drives reverse osmosis adoption for rural Jal Jeevan Mission tap connections. Jaipur's pharmaceutical formulation units deploy resin-based demineralization for process water compliance. Jodhpur's textile dye houses pilot membrane distillation for high-salinity effluent concentration.
India Water Treatment Market Competitive Landscape
Global majors compete with regional champions across project execution capability and service network density. The vendor base stratifies between engineering-intensive EPC contractors and specialized component suppliers. Three archetypes dominate: integrated solution providers with captive manufacturing, membrane technology licensors with regional fabrication partnerships, and chemical dosing specialists with distribution networks. Competitive moves concentrate on long-term service contract unbundling and IoT-enabled predictive maintenance bundling.
Among India-based engineering contractors, VA Tech Wabag exemplifies the large-scale municipal project archetype, while Ion Exchange occupies a position within resin-based demineralization specialization. Thermax represents the cross-sector integrated solutions tier, leveraging boiler-water expertise into bundled treatment packages. These three anchors illustrate how vendor positioning aligns with state-level procurement sophistication and industrial cluster concentration.
| Leading Market Players |
|---|
| Thermax |
| Veolia |
| VA Tech Wabag |
| Voltas |
| Ecolab |
| Netsol Water |
| Siemens India |
| Hindustan Dorr-Oliver |
| Ion Exchange |
| Others |
Pricing and Supply Chain Analysis
Membrane distillation pilot deployments in Gujarat's chemical parks are compressing project economics while redrawing supplier qualification requirements around modular skid formats. This technology transition simultaneously elevates upfront capital commitments and fragments procurement across specialized component vendors.
Pricing Analysis
Long-term membrane replacement contracts are unbundling from initial EPC pricing as refinery operators in Jamnagar and Vadinar adopt category management frameworks. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and after-sales service bundling intensity. Cost compression in standard-tier municipal ultrafiltration is intensifying because Jal Jeevan Mission procurement favors lowest-compliant-bid award criteria. State water boards exhibit highest price sensitivity; semiconductor foundries in Karnataka demonstrate lowest sensitivity due to ultra-pure water quality non-negotiability.
Supply Chain Analysis
Dual-sourcing mandates from Maharashtra and Gujarat utilities require EPC contractors to qualify membrane element suppliers from Japan, South Korea, and the United States alongside domestic fabricators. Polyamide thin-film composites, activated carbon media, and synthetic ion-exchange resins constitute critical input dependencies. Single-source vulnerability concentrates in high-pressure reverse osmosis elements where East Asian suppliers dominate proprietary interfacial polymerization expertise. Distribution runs through direct manufacturer engagement for large municipal contracts, with regional distributors serving mid-scale industrial accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's water treatment sector is navigating a technology-transition phase where membrane bioreactors and electrochemical advanced oxidation are displacing conventional chemical-intensive tertiary treatment in textile clusters.
For Market Incumbents: Deepen backward integration into membrane element fabrication to offset import dependence exposure as currency volatility erodes project margins. Secure captive resin regeneration capacity in Maharashtra and Gujarat to defend service contract profitability against specialized chemical dosing entrants. Prioritize IoT-enabled predictive maintenance certification to meet real-time discharge monitoring mandates from the Central Pollution Control Board. For New Entrants and Emerging Players: Capture white-space demand in semiconductor ultra-pure water systems across Karnataka and Telangana where PLI scheme incentives are attracting foundry investments. Penetrate Rajasthan's Jal Jeevan Mission rural tap-connection deployments through decentralized reverse osmosis skid formats that minimize civil works. Lead with membrane distillation pilot-to-scale demonstration capabilities to differentiate from established reverse osmosis vendors. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by global water technology conglomerates seeking Indian engineering execution capabilities and regulatory relationships. Long-term viability hinges on positioning within zero-liquid-discharge compliance workflows as Central Pollution Control Board mandates tighten across Gujarat and Tamil Nadu industrial clusters. Monitor Bureau of Indian Standards recycled water quality framework finalization as inflection indicator for tertiary treatment certification premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Zero-Liquid-Discharge Technology Licensing | Textile parks in Surat and Tiruppur mandate evaporator-integrated membrane systems under CPCB directives. |
| IoT Predictive Maintenance Platform Launch | Gujarat chemical processors face penalty clauses for unplanned downtime, accelerating sensor adoption. |
| Backward Integration into Membrane Fabrication | Import dependence on East Asian polyamide elements exposes EPCs to shipping delays and currency risk. |
| Ultra-Pure Water System Partnership | Karnataka semiconductor foundries under PLI scheme require sub-ppb contamination specifications. |
| Resin Regeneration Service Expansion | Thermal plant commissioning slowdowns compress demand for Ion Exchange's core demineralization systems. |
Research Methodology
Independent corroboration across Central Pollution Control Board discharge compliance records, state pollution control board permitting databases, and Bureau of Indian Standards certification registries underwrites the qualitative findings. Primary interviews with municipal utility procurement officers, industrial plant engineers at Gujarat Special Economic Zones, membrane technology licensors, and EPC project managers combined with secondary validation from Jal Jeevan Mission implementation reports, customs import data for membrane elements, and state groundwater extraction notifications. Bottom-up project pipeline aggregation and top-down macroeconomic scaling were triangulated to reconcile volume estimates.
Comparable-period anchoring referenced historical capacity commissioning cycles from Maharashtra and Gujarat municipal corporations to calibrate deployment velocity assumptions across the projection horizon. Segmentation modeling incorporated technology configuration, application context, end-user procurement sophistication, and state-level regulatory enforcement intensity. CAGRs were derived from installed capacity growth trajectories and unit economics evolution rather than simple extrapolation. Forecast inputs included groundwater salinity intrusion monitoring data and PLI scheme incentive disbursement patterns for semiconductor manufacturing.
The model holds under sustained Central Pollution Control Board enforcement intensity and stable membrane import access; deviation in state-level groundwater extraction regulation tightening or East Asian supply chain disruption would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
Drinking Water Adsorbents Market
Water & Sludge Treatment
Slurry Homogenizer Tank Market
Water & Sludge Treatment
Aquarium Water Treatment Market
Water & Sludge Treatment
Industrial Wastewater Real-Time Toxicity Monitoring Test Systems Market
Water & Sludge Treatment
Global Liquid Waste Management Market
Water & Sludge Treatment
North America Membrane Water and Wastewater Treatment (WWT) Market
Water & Sludge Treatment
Water Dispersible Granules Market
Water & Sludge Treatment
Hazardous Waste Treatment System Market
Water & Sludge Treatment
Europe Water Treatment Chemicals Market
Water & Sludge Treatment
Feedwater Treatment Chemicals Market
Water & Sludge Treatment
Water and Wastewater Treatment Technologies Market
Water & Sludge Treatment
Global Wet Waste Management Market
Water & Sludge Treatment
Salt Water Softeners Market
Water & Sludge Treatment
Flocculants Market
Water & Sludge Treatment
Saudi Arabia Industrial Hazardous Waste Management Market
Water & Sludge Treatment
Nanotechnology in Water Treatment Market