
 Saudi Arabia Construction Chemicals Market | 2026-2036
Saudi Arabia Construction Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Construction Chemicals Market Insights
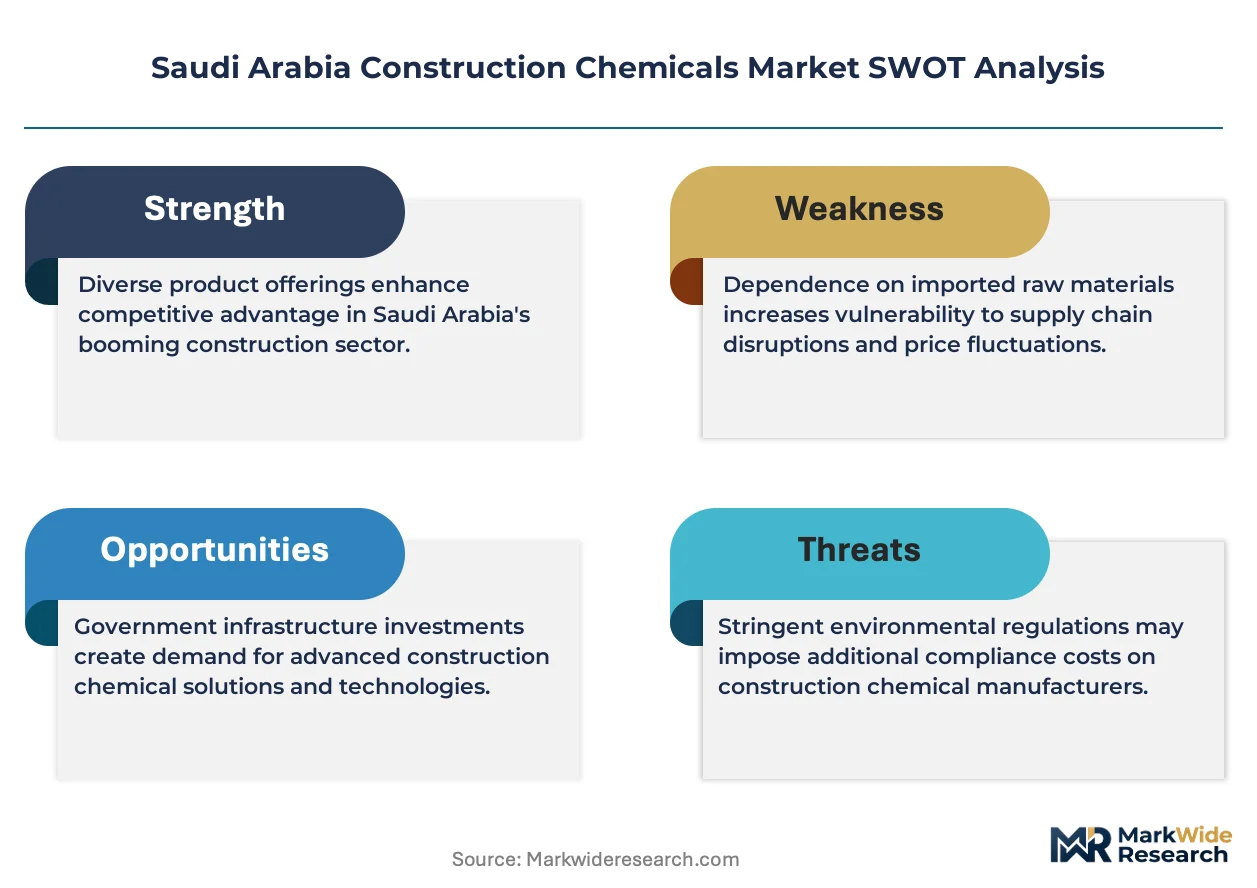
Polymer-modified cementitious systems is restructuring product economics across the Saudi Arabia construction chemicals sector, displacing conventional unmodified mortars in high-specification applications. Sika AG leverages its regional manufacturing footprint to supply waterproofing systems for coastal infrastructure exposed to chloride attack. BASF SE sustains R&D investment in polycarboxylate ether superplasticizers tailored for local aggregate profiles and extreme heat conditions. Fosroc International Ltd. anchors its position through technical service teams embedded at major contractor sites across the Kingdom.
Construction chemicals encompass formulated admixtures, grouts, waterproofing systems, and cement modifiers designed to enhance concrete workability, durability, and curing performance in harsh environments, typically containing active polymers, silica fume, or corrosion inhibitors at specified dosage rates. These formulations serve primarily to extend structural service life and reduce maintenance cycles in aggressive climates. Concrete admixtures command the largest volume share due to universal application across all project scales, while waterproofing chemicals generate superior margin pools driven by specification intensity in below-grade and marine structures. Performance grouts represent the fastest-expanding category as tunneling and ground-stabilization work accelerates beneath Riyadh's metro extensions and giga-project foundations.
SASO mandates product conformity assessment for all construction chemicals sold in the Kingdom, while the Saudi Building Code enforces performance-based specifications that elevate admixture quality thresholds. SFDA oversight of chemical imports adds a compliance layer affecting formulation registration timelines and raw material sourcing. Stakeholders must monitor evolving green building criteria under the Saudi Green Building Forum and assess how carbon-accounting requirements will reshape material selection protocols for state-backed developments.
Market Dynamics
NEOM and Red Sea Project mega-contractors are consolidating procurement of high-performance admixtures, compressing supplier margins while elevating technical service requirements across the Kingdom's construction chemicals value chain.
Growth Catalysts
- SASO conformity mandates:The Saudi Standards, Metrology and Quality Organization tightened product certification requirements, forcing out substandard imports and expanding addressable market share for compliant domestic and regional producers.
- Giga-project concentration:Riyadh and the Eastern Province host the bulk of state-backed developments, creating geographic demand density that justifies localized blending facilities and technical service investments.
- Polycarboxylate ether superplasticizers:Advanced admixture chemistry tailored for Saudi aggregate profiles and extreme heat curing conditions is displacing conventional naphthalene-based formulations in high-specification concrete.
Market Restraints
- Petrochemical feedstock volatility:Polymer-modified systems depend on ethylene and propylene derivatives, exposing margin structures to Saudi Aramco pricing adjustments and global olefin market swings.
- SFDA import registration timelines:The Saudi Food and Drug Authority's oversight of chemical raw materials extends formulation approval cycles by 4-8 months, delaying new product launches.
- Technical labor scarcity:Qualified concrete technologists and admixture application specialists remain concentrated with established multinationals, constraining local competitor scale-up.
Strategic Opportunities
- Red Sea coastal infrastructure:Chloride-resistant waterproofing systems for marine exposure represent an underpenetrated specification tier where specialized formulations command technical premiums.
- Saudi Green Building Forum criteria:Emerging carbon-accounting protocols for state-backed developments will reshape material selection, favoring low-carbon cementitious systems and recycled content admixtures.
- Embedded technical service models:On-site application support teams stationed at contractor batching plants create switching costs and capture specification influence before competitive bidding.
Industry Challenges
- Saudi Building Code performance testing:Third-party laboratory certification for admixture compatibility with local cements requires 12-18 month validation cycles that outpace project procurement windows.
- Legacy batching plant integration:Automated dosing systems for liquid superplasticizers demand capital upgrades at established ready-mix operations, slowing technology diffusion outside tier-one contractors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Construction Chemicals Market |
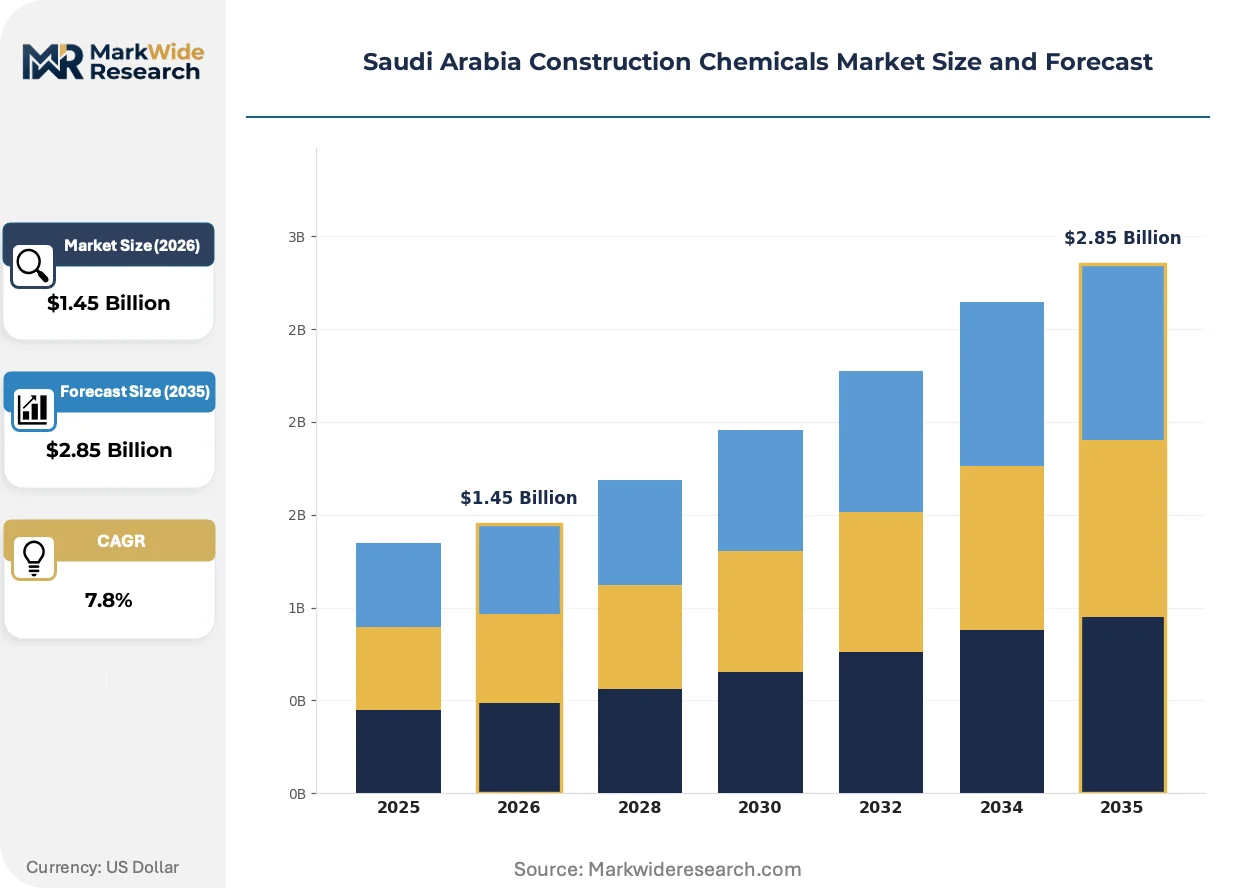
| Market Size in 2026 | $1.45 Billion |
| Market Size in 2035 | $2.85 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cement Additives, Performance Grouts, Concrete Admixtures, Waterproofing Chemicals Application: Residential, Commercial, Industrial, Infrastructure Form: Liquid, Powder, Granular, Paste End User: Contractors, Builders, Architects, Engineers |
| Companies Covered | Sika AG, BASF SE, RPM International Inc., Fosroc International Ltd., SABIC, MAPEI S.p.A., Arkema Group, 3M Company, Meister Co., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Construction Chemicals Market Trends and Innovations
Formulation chemistry and procurement protocols are converging to extend structural service life in aggressive Gulf climates while compressing project delivery schedules through accelerated curing technologies.
Silica fume and metakaolin supplementary cementitious materials are integrating into high-durability concrete specifications for below-grade and marine structures. NEOM contractors specify these systems for 100-year design life requirements. The technology is integrating quality assurance protocols that displace conventional cover-meter testing with embedded corrosion sensors.
SASO's 2024 technical regulations for construction chemicals introduced mandatory factory production control audits and traceability documentation. The Saudi Building Code now references these standards for all government-procured projects. Waterproofing and repair mortar categories face the steepest compliance ramp, with smaller importers exiting rather than absorbing certification costs.
Major contractors are consolidating admixture procurement under single-source technical partnership agreements rather than commodity spot purchasing. The Red Sea Project and Qiddiya developments anchor this shift, embedding supplier personnel at batching plants for real-time mix optimization. Riyadh's metro extensions demonstrate the model's execution, where performance guarantees replace traditional material supply contracts.
Saudi Arabia Construction Chemicals Market Segmentation
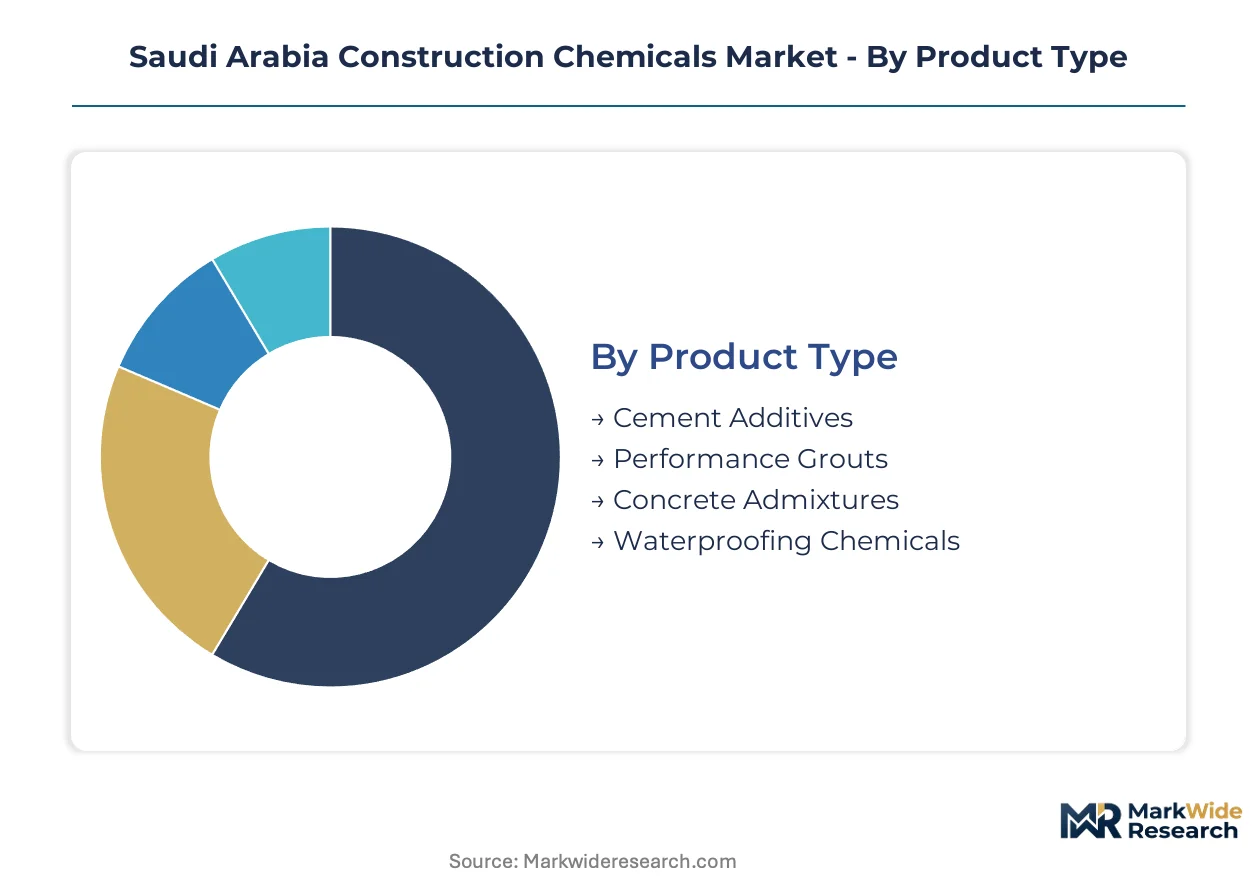
Segmentation reveals how procurement power concentrates across Saudi Arabia's construction chemicals value chain. Specification intensity varies sharply between giga-project infrastructure and standardized residential applications.
Product Type:
Formulation sophistication spans commodity-grade cement modifiers to engineered polymer systems with project-specific performance guarantees.
- Concrete Admixtures:Polycarboxylate ether and naphthalene-based superplasticizers dominate volume, with PCE formulations displacing legacy chemistry in NEOM and Red Sea Project specifications due to superior slump retention in extreme heat. Riyadh's metro extensions and Qiddiya foundations anchor demand for high-range water reducers with 8-12 hour workability windows.
- Waterproofing Chemicals:Crystalline, bituminous, and polyurethane membrane systems command technical premiums in below-grade marine exposure. Chloride-resistant formulations for Red Sea coastal infrastructure face SASO's steepest compliance ramp, filtering out smaller importers unable to absorb certification costs.
- Cement Additives:Grinding aids and performance enhancers optimize clinker substitution rates in local cement production.
- Performance Grouts:High-strength, non-shrink formulations for tunneling and ground stabilization work beneath Riyadh's urban core.
Most installed capacity flows through Concrete Admixtures. Expansion is steepest in Waterproofing Chemicals.
Application:
Project scale determines whether procurement flows through spot-market purchasing or embedded technical partnerships with real-time mix optimization.
- Infrastructure:Giga-projects anchor specification intensity, with 100-year design life requirements driving silica fume and metakaolin integration. NEOM contractors mandate embedded corrosion sensors and automated dosing systems that compress supplier margins while elevating service obligations.
- Commercial:Mixed-use developments in Riyadh and the Eastern Province balance cost control with accelerated curing demands to meet compressed delivery schedules.
- Industrial:Petrochemical facility construction in Jubail Industrial City specifies chemical-resistant flooring and containment systems.
- Residential:Standardized ready-mix procurement dominates volume, with limited penetration of advanced admixture chemistry outside tier-one developer portfolios.
Revenue concentrates in Infrastructure. Volume growth is fastest in Commercial.
Form:
Physical state dictates logistics economics and batching plant integration requirements across the Kingdom's contractor base.
- Liquid:Superplasticizers and curing compounds in bulk tanker delivery. Automated dosing systems demand capital upgrades at established ready-mix operations, slowing diffusion outside tier-one contractors with dedicated technical staff.
- Powder:Silica fume, metakaolin, and cementitious repair mortars in bulk silo storage. SFDA import registration timelines extend formulation approval cycles by 4-8 months for powder raw materials.
- Granular:Controlled-release admixtures for remote project sites with limited liquid storage infrastructure.
- Paste:Pre-measured grout cartridges for precision injection applications in tunneling and structural repair.
Liquid form commands the largest volume share. Powder form is gaining share fastest in high-durability specifications.
End User:
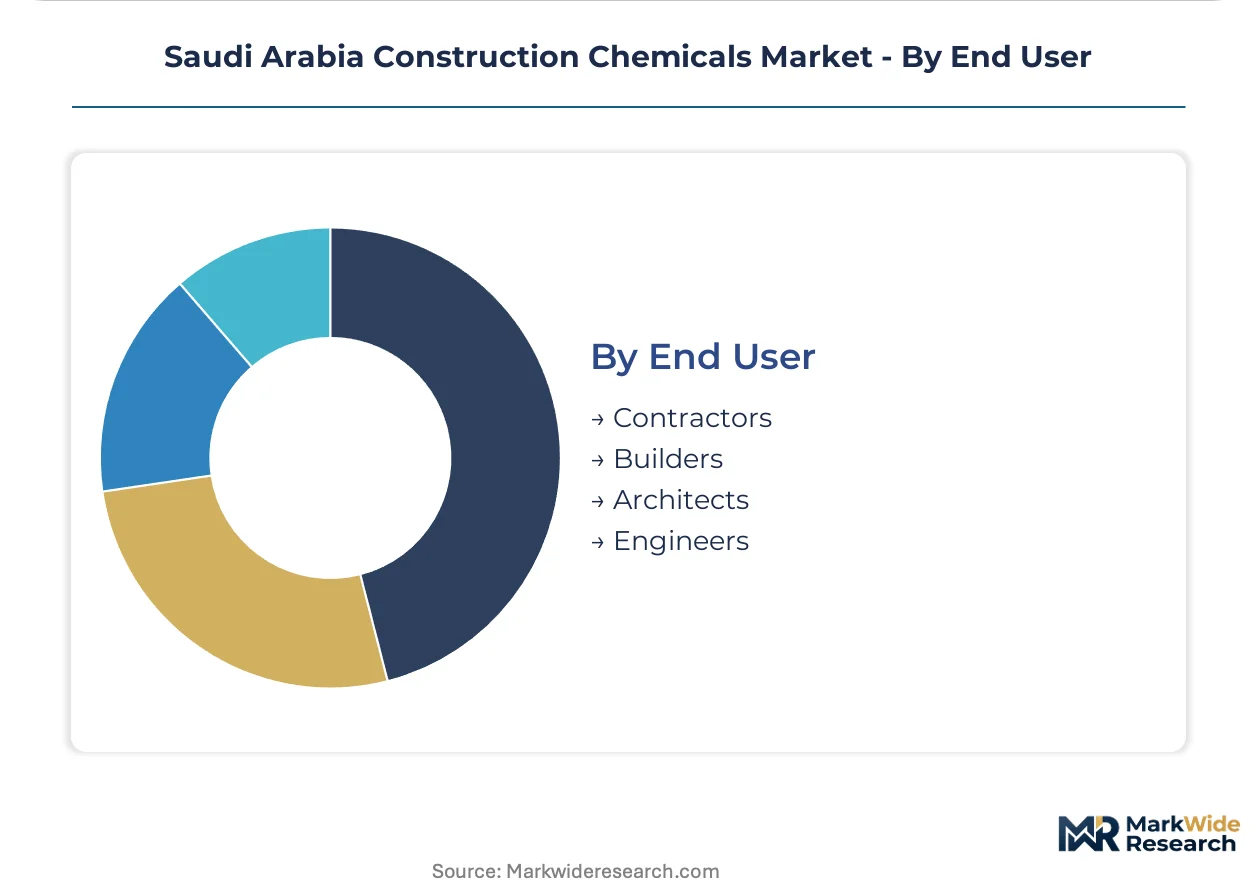
Technical capability gaps between specification authors and field applicators create friction in admixture selection and quality assurance.
- Contractors:Mega-project consolidators like those at the Red Sea Project and Qiddiya are shifting from commodity spot purchasing to single-source technical partnerships with performance guarantees replacing traditional material supply contracts.
- Builders:Mid-scale residential and commercial developers face legacy batching plant constraints and limited access to qualified concrete technologists.
- Architects:Specification influence concentrates in high-visibility developments where aesthetic concrete finishes and exposed structural elements demand specialized surface retarders and form release agents.
- Engineers:Structural design consultants increasingly mandate performance-based specifications referencing Saudi Building Code durability classes, forcing admixture suppliers into extended third-party laboratory certification cycles.
Procurement authority concentrates with Contractors. Technical specification influence is expanding fastest among Engineers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NEOM anchors construction chemicals procurement intensity across Saudi Arabia, with giga-project specifications cascading procurement standards through regional supply chains.
Riyadh
Metro extensions and Qiddiya foundations drive specification-grade admixture procurement. SASO conformity audits for concrete admixtures concentrate laboratory capacity in the capital. Riyadh's urban core hosts embedded technical service teams from multinational suppliers at contractor batching plants.
Eastern Province
Jubail Industrial City petrochemical construction mandates chemical-resistant flooring and containment systems. SFDA import registration timelines for powder raw materials extend formulation approvals through Dammam port facilities. Dhahran contractor clusters demonstrate automated dosing system adoption at tier-one ready-mix operations.
Western Region
Jeddah commercial developments balance cost control with accelerated curing demands for compressed delivery schedules. Saudi Building Code enforcement through municipal authorities elevates waterproofing specification thresholds. Makkah infrastructure corridors concentrate cementitious repair mortar applications for structural rehabilitation.
NEOM Northwest
The Line and Oxagon developments mandate 100-year design life concrete with silica fume and metakaolin integration. NEOM contractors enforce single-source technical partnerships replacing commodity spot purchasing. Trojena and Sindalah coastal zones specify chloride-resistant waterproofing systems for marine exposure.
Saudi Arabia Construction Chemicals Market Competitive Landscape
Capacity expansion dominates the current landscape as suppliers localize blending facilities to match giga-project geographic density. The market structure concentrates around multinational chemical conglomerates with regional manufacturing footprints, mid-sized regional specialists with technical service capabilities, and domestic distributors dependent on import relationships. Three archetypes define competitive positioning: integrated polymer producers with backward control over ethylene derivatives, formulation specialists with embedded application engineering teams, and commodity traders pivoting toward certification compliance. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with suppliers securing batching plant integration agreements ahead of project procurement windows.
Among Swiss-headquartered multinationals, Sika AG exemplifies the integrated formulation archetype with regional production assets. BASF SE, a German chemical conglomerate, occupies a position representing polymer science capabilities applied to local aggregate profiles. Fosroc International Ltd., a UK-based construction chemicals specialist, anchors the embedded technical service model through site-based engineering presence. These three entities collectively represent the spectrum from materials science depth to application engineering intensity that defines competitive differentiation in high-specification segments.
| Leading Market Players |
|---|
| Sika AG |
| BASF SE |
| RPM International Inc. |
| Fosroc International Ltd. |
| SABIC |
| MAPEI S.p.A. |
| Arkema Group |
| 3M Company |
| Meister Co. |
| Others |
Pricing and Supply Chain Analysis
Giga-project contractors at NEOM and the Red Sea Project are consolidating procurement under single-source technical partnerships, compressing supplier margins while elevating performance-guarantee pricing models that displace commodity spot purchasing.
Pricing Analysis
Ethylene and propylene derivative costs pass through directly to polymer-modified system pricing, exposing margin structures to Saudi Aramco pricing adjustments. Three-tier pricing structure across premium, standard, and economy levels separates SASO-certified formulations with embedded technical service from basic admixture supply. Pricing pressure stems from mega-contractor consolidation and compressed procurement windows at giga-projects. Mid-scale residential developers exhibit highest price sensitivity; NEOM-tier contractors prioritize performance guarantees over unit economics.
Supply Chain Analysis
SASO factory production control audits and SFDA import registration timelines gate supply chain participation, filtering out smaller importers unable to absorb certification costs. Raw material sourcing draws from Germany, Switzerland, and the UAE for specialized polymer intermediates and technical additives. Single-source vulnerability concentrates in polycarboxylate ether superplasticizer precursors. Distribution runs through regional blending facilities co-located with Riyadh and Eastern Province contractor clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Saudi Arabia construction chemicals market represents a late-cycle quality story as 100-year design life specifications at NEOM and Qiddiya displace commodity-grade procurement with performance-based material selection.
For Market Incumbents: Hedge petrochemical feedstock exposure through backward integration into ethylene derivative supply or long-term offtake agreements with Saudi Aramco. Anchor market position by embedding technical service teams at tier-one contractor batching plants before competitive bidding windows close, creating switching costs that resist margin compression.
For New Entrants and Emerging Players: Regional distributors with existing SASO certification infrastructure offer the fastest channel to market access without absorbing full compliance capital requirements. Target chloride-resistant waterproofing specifications at Red Sea coastal zones where specialized formulations command technical premiums absent entrenched multinational presence. Lead with application engineering support rather than price undercutting.
For Investors and Strategic Acquirers: Specialty chemical conglomerates with construction chemicals adjacencies represent the most active acquirer in this space, seeking regional formulation capabilities to complement polymer science depth. Five-to-ten year viability hinges on carbon-accounting protocol alignment under Saudi Green Building Forum criteria. Monitor embedded corrosion sensor adoption rates at NEOM as signal of specification intensity trajectory.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive ethylene derivative supply insulates margin structures from Aramco pricing volatility. |
| Embedded Technical Partnership | On-site application teams at contractor batching plants create specification influence before competitive bidding. |
| SASO Certification Investment | Factory production control audits filter out smaller importers, expanding addressable share for compliant producers. |
| Green Formulation Development | Low-carbon cementitious systems align with Saudi Green Building Forum criteria reshaping state-backed procurement. |
| Regional Blending Capacity | Localized facilities in Riyadh and Eastern Province match giga-project geographic density with compressed logistics economics. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with admixture procurement managers at mega-project contractors, technical directors at ready-mix operations, and regulatory affairs specialists navigating SASO conformity pathways with secondary validation through customs trade data, SEC filings of listed chemical conglomerates, and Saudi Building Code technical regulation updates. Bottom-up project pipeline aggregation and top-down sectoral spend analysis triangulated market sizing.
Segment-weighting across product type, application, and end-user dimensions anchored the analytical framework, with infrastructure-commercial-residential splits and contractor-builder-engineer procurement authority tiers modeled explicitly. CAGRs derived from project completion schedules and specification intensity trajectories across the projection horizon. Silica fume integration rates and automated dosing system adoption curves served as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Saudi Green Building Forum carbon-accounting protocol evolution and petrochemical feedstock pricing volatility. A model refresh is warranted upon material change in giga-project procurement consolidation patterns or SASO technical regulation amendments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Global Cysteine Market
Chemicals
N-Acetyl D-Neuraminic Acid Market
Chemicals
Mercury (I) Sulphate Market
Chemicals
Lime Sulfur Market
Chemicals
Calcium Carbide Market
Chemicals
Carbon Tetrabromide Market
Chemicals
Vinyl Acetate Market
Chemicals
Global Photoresist Chemicals Market
Chemicals
Superphosphoric Acid (SPA) Market
Chemicals
5 Dinitroaniline Market
Chemicals
Electroplating Chemicals Market
Chemicals
Azodicarbonamide (ADC) Market
Chemicals
Medical Grade Zinc Sulfate Market
Chemicals
Desalination Chemicals Market
Chemicals
Sodium Ethylate Market
Chemicals
Global Electronic Grade Phosphoric Acid Market