
 India Water and Wastewater Treatment (WWT) Technology Market | 2026-2036
India Water and Wastewater Treatment (WWT) Technology Market Size, Share, and Industry Trends Forecast 2026-2036
India Water and Wastewater Treatment (WWT) Technology Market Foresight
The capital-intensity divergence between engineering-procurement-construction specialists and component suppliers is unwinding as project bundling demands fuller capability stacks. VA Tech Wabag leverages its build-operate-transfer track record across municipal desalination contracts to sustain pricing power on large orders. Thermax Limited anchors its position through captive manufacturing of pressure vessels and ion-exchange resins, while Larsen & Toubro competes by integrating civil infrastructure with electromechanical packages.
Water and wastewater treatment technology encompasses physical, chemical, and biological processes engineered to remove contaminants from water sources or effluent streams, with membrane filtration systems typically operating at transmembrane pressures of 1–10 bar depending on pore classification. The primary purpose spans potable water production, industrial process water conditioning, and regulatory-compliant effluent discharge across manufacturing and utility networks. Membrane filtration leads value capture in high-salinity industrial applications where reverse osmosis trains command premium engineering margins, while activated sludge processes dominate municipal volumes with mature equipment supply chains. UV treatment segments are expanding fastest in pharmaceutical and food-processing end users where chemical-free disinfection supports product quality certifications.
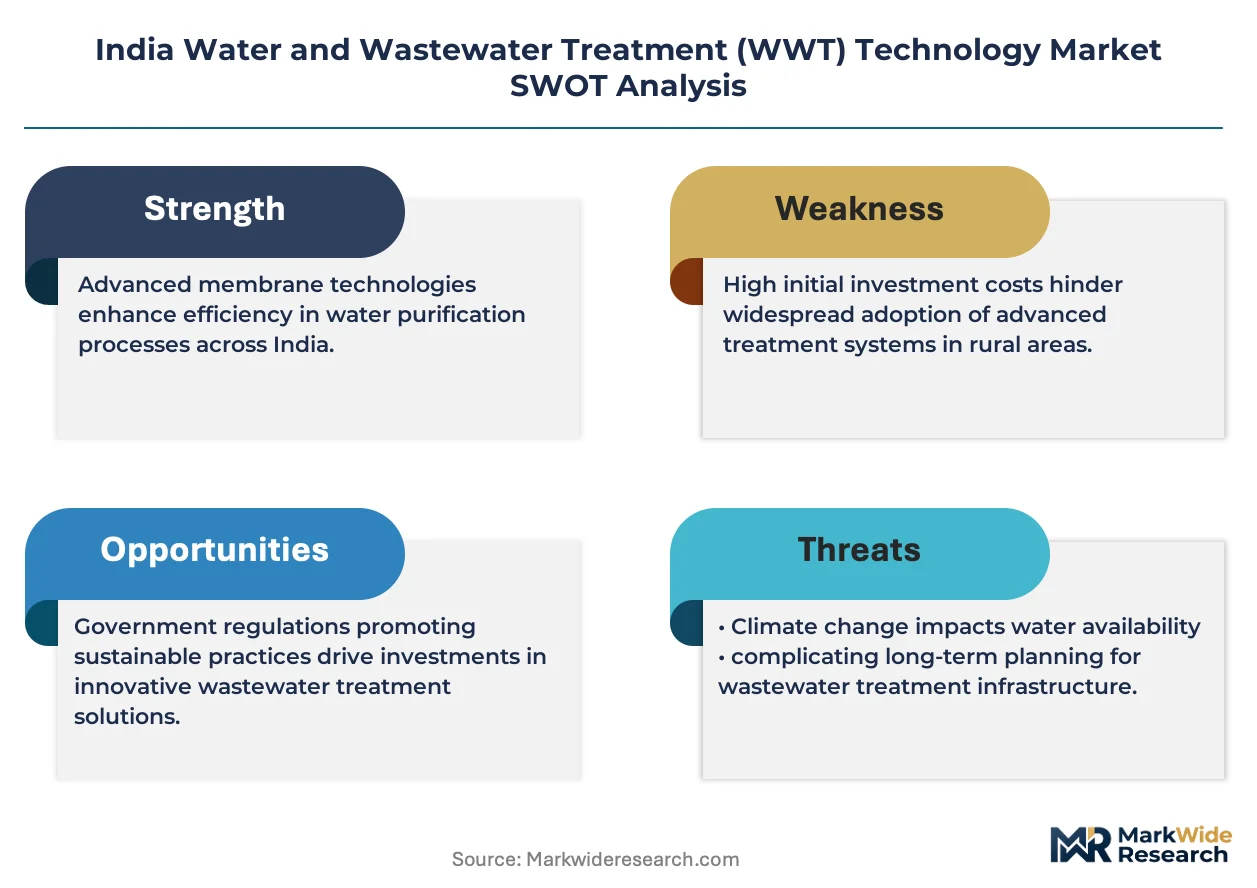
The Central Pollution Control Board enforces sector-specific effluent standards under the Water Prevention and Control of Pollution Act, compelling textile and tannery clusters in Tamil Nadu and Uttar Pradesh to upgrade biological treatment with advanced oxidation add-ons. BIS certification for drinking water treatment units and state-level Jal Jeevan Mission implementation protocols shape product approval timelines and market access conditions for technology vendors. Stakeholders must monitor how state pollution control boards interpret zero-liquid-discharge rules for distilleries and pulp mills, as enforcement variance will redirect capital deployment across regional industrial corridors.
Market Dynamics
The Jal Jeevan Mission's universal tap-water mandate is compressing replacement cycles for membrane filtration assets across state water boards, forcing technology vendors to reconfigure service networks for accelerated commissioning timelines.
Growth Catalysts
- Zero-Liquid-Discharge Mandates:The Central Pollution Control Board's enforcement in distilleries and pulp mills along the Delhi-Mumbai Industrial Corridor is forcing membrane-thermal hybrid retrofits.
- Maharashtra Municipal Expansion:Urban local bodies in Pune and Nagpur are bundling desalination with sewage recycling under integrated water management tenders.
- Textile Cluster Upgrades:Tamil Nadu's Tiruppur dyeing units are installing advanced oxidation processes ahead of state pollution control board consent renewals.
Market Restraints
- Import Concentration in Membranes:Thin-film composite reverse osmosis elements rely on Korean and Japanese suppliers, exposing project cash flows to yen and won volatility.
- Skilled Commissioning Bottleneck:Transmembrane pressure optimization and chemical cleaning protocol design require certified operators scarce outside Gujarat and Karnataka.
- Biological Treatment Margin Compression:Activated sludge package plants face price pressure from standardized MBBR skids manufactured in Rajasthan and Uttar Pradesh.
Strategic Opportunities
- Pharmaceutical UV Disinfection:CDSCO audit requirements for sterile water systems are expanding chemical-free disinfection deployments in Hyderabad and Bengaluru bulk drug parks.
- Jharkhand and Chhattisgarh Rural Pipelines:Jal Jeevan Mission allocations for arsenic- and fluoride-affected blocks favor ion-exchange and adsorption technology packages.
- Industrial IoT Convergence:Remote membrane fouling monitoring combined with predictive chemical dosing algorithms is opening performance-contracting revenue streams.
Industry Challenges
- BIS Certification Timelines:Drinking water treatment unit approvals under IS 10500 testing protocols stretch 14-18 months, delaying product launches for small and mid-cap equipment makers.
- Civil-Mechanical Interface Risk:Large EPC contracts require coordination between cast-in-place concrete basin construction and skid-mounted electromechanical delivery, with liquidated damages clauses penalizing schedule slippage.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Water and Wastewater Treatment (WWT) Technology Market |
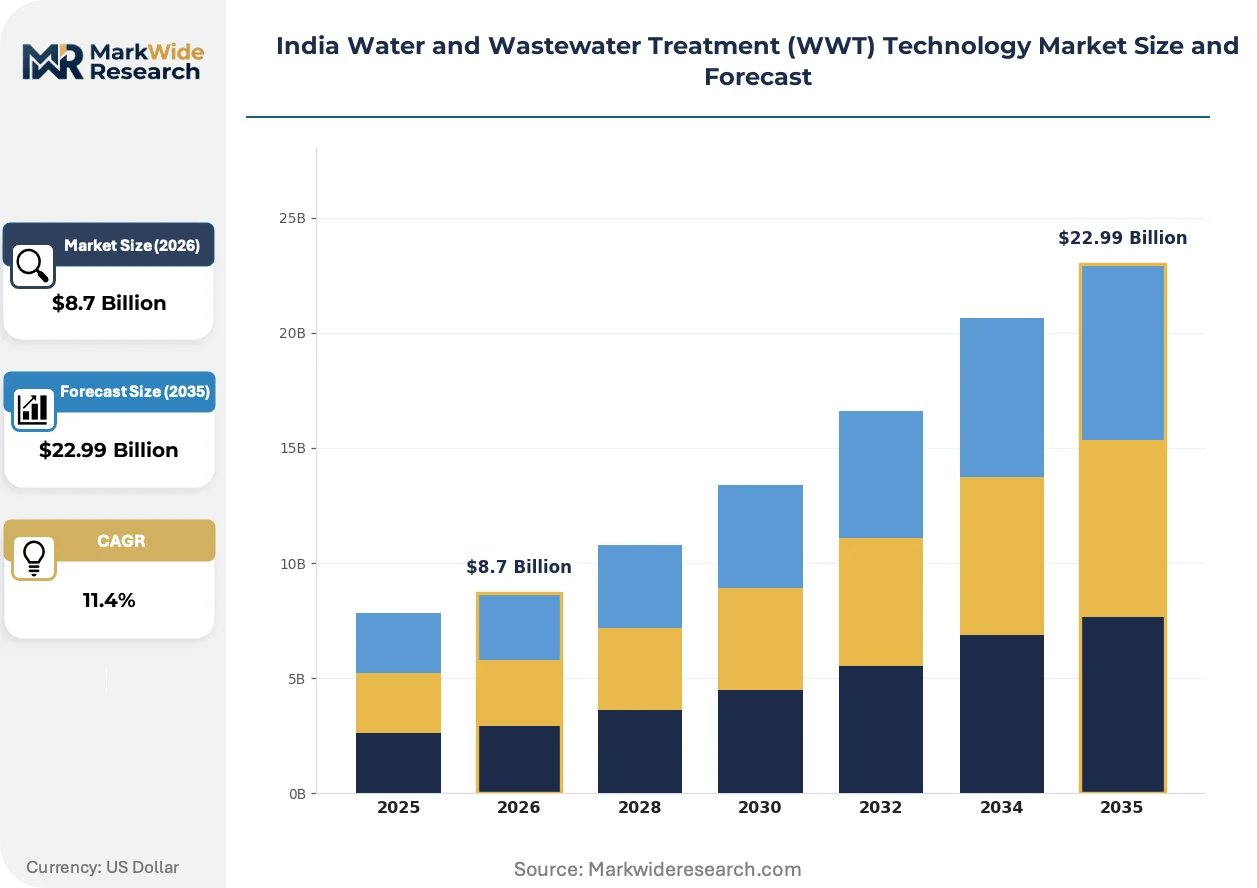
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Membrane Filtration, Activated Sludge, UV Treatment, Biofilm Reactor Application: Municipal, Industrial, Agricultural, Recycling Technology: Reverse Osmosis, Microfiltration, Electrodialysis, Advanced Oxidation End User: Manufacturing, Power Generation, Agriculture, Residential |
| Companies Covered | VA Tech Wabag, Thermax Limited, Ion Exchange India, Veolia, Aquatech, Larsen & Toubro, Xylem, DuPont, Ecolab, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Water and Wastewater Treatment (WWT) Technology Market Shifts & Advancements
Membrane technology maturation and regulatory tightening on industrial effluent are converging to reshape equipment specifications and vendor capability requirements across Indian water infrastructure.
Forward osmosis draw-solute regeneration systems are displacing conventional reverse osmosis in high-salinity textile effluent applications where energy recovery configurations struggle. Tiruppur and Surat dyeing houses are piloting these units to meet zero-liquid-discharge norms without thermal evaporator energy penalties. The technology is compressing operating expenditure structures for coastal plants with access to seawater draw solutions.
The Central Pollution Control Board's 2023 amendments to effluent standards for tanneries and pulp mills are mandating tertiary treatment trains that combine biological nutrient removal with advanced oxidation. Uttar Pradesh's Kanpur leather cluster and Tamil Nadu's Vellore tanneries face consent-to-operate suspensions without compliance upgrades. Equipment suppliers are bundling ozone-UV hybrid skids with extended biological aeration to meet chemical oxygen demand limits below 30 mg per liter.
Performance-based service contracts are replacing capital purchase models for municipal membrane plants in Gujarat and Maharashtra. Operators assume membrane replacement and chemical procurement risk while municipalities pay per kiloliter treated. The shift concentrates vendor selection criteria on historical uptime data rather than upfront equipment pricing, favoring contractors with captive membrane manufacturing or long-term supplier alliances.
India Water and Wastewater Treatment (WWT) Technology Market Segmentation
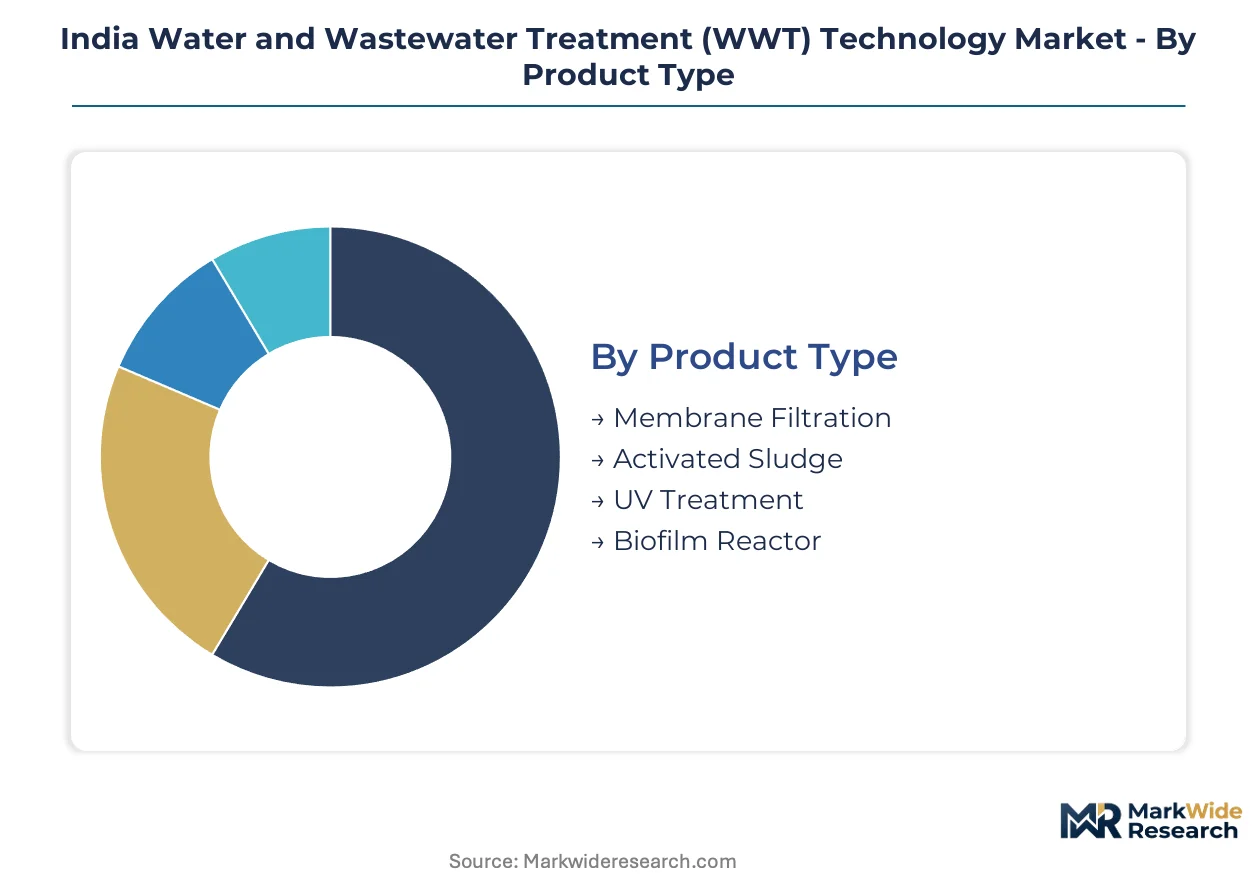
Technology selection in India's WWT market hinges on effluent chemistry, energy access, and regulatory enforcement intensity across state pollution control boards. Segmentation reveals how membrane systems command premium project values while biological processes absorb municipal volume.
Product Type:
BIS certification requirements under IS 10500 and state-level Jal Jeevan Mission protocols create divergent approval timelines that reshape vendor competitive position by product category.
- Membrane Filtration:Thin-film composite and ceramic configurations operate at transmembrane pressures of 1–10 bar depending on pore classification. Zero-liquid-discharge mandates along the Delhi-Mumbai Industrial Corridor are accelerating reverse osmosis train deployments in distilleries and textile dyeing houses.
- Activated Sludge:Conventional suspended-growth biological treatment dominates municipal sewage capacity expansion in Maharashtra and Gujarat. Extended aeration variants face margin compression from standardized MBBR skids manufactured in Rajasthan and Uttar Pradesh.
- UV Treatment:Low-pressure mercury and UV-C LED systems serve pharmaceutical sterile water requirements under CDSCO audit protocols.
- Biofilm Reactor:Moving bed biofilm reactor skids offer compact footprints for urban local bodies with land constraints.
Established volume favors activated sludge; emerging adoption favors membrane filtration.
Application:
Capital deployment patterns track enforcement variance across state pollution control boards and Jal Jeevan Mission allocation cycles.
- Municipal:State water boards in Maharashtra and Gujarat are bundling desalination with sewage recycling under integrated water management tenders. Pune and Nagpur urban local bodies specify membrane bioreactor trains for water-scarce catchments.
- Industrial:Tamil Nadu's Tiruppur dyeing units and Kanpur leather clusters face consent-to-operate suspensions without tertiary treatment upgrades. Advanced oxidation add-ons are becoming mandatory for chemical oxygen demand limits below 30 mg per liter.
- Agricultural:Fluoride and arsenic remediation in Jharkhand and Chharkhand rural blocks favors ion-exchange packages.
- Recycling:Performance-based service contracts are displacing capital purchase models in Gujarat municipal membrane plants.
Municipal contracts anchor supplier revenue stability; industrial retrofits deliver the steepest expansion trajectory.
Technology:
Energy intensity and draw-solute availability determine technology selection for high-salinity industrial effluent.
- Reverse Osmosis:Spiral-wound thin-film composite elements achieve 99.5% salt rejection for seawater and brackish feedwater. Import concentration from Korean and Japanese suppliers exposes project economics to yen and won exchange volatility.
- Microfiltration:Hollow-fiber polymeric membranes provide pretreatment protection for downstream reverse osmosis trains in coastal desalination plants.
- Electrodialysis:Ion-exchange membrane stacks suit selective salt recovery applications in chemical process industries.
- Advanced Oxidation:Ozone-UV hybrid skids address recalcitrant organics in tannery and pharmaceutical effluent.
Reverse osmosis captures the largest share of project value; forward osmosis pilots are gaining share fastest in Tiruppur and Surat dyeing houses.
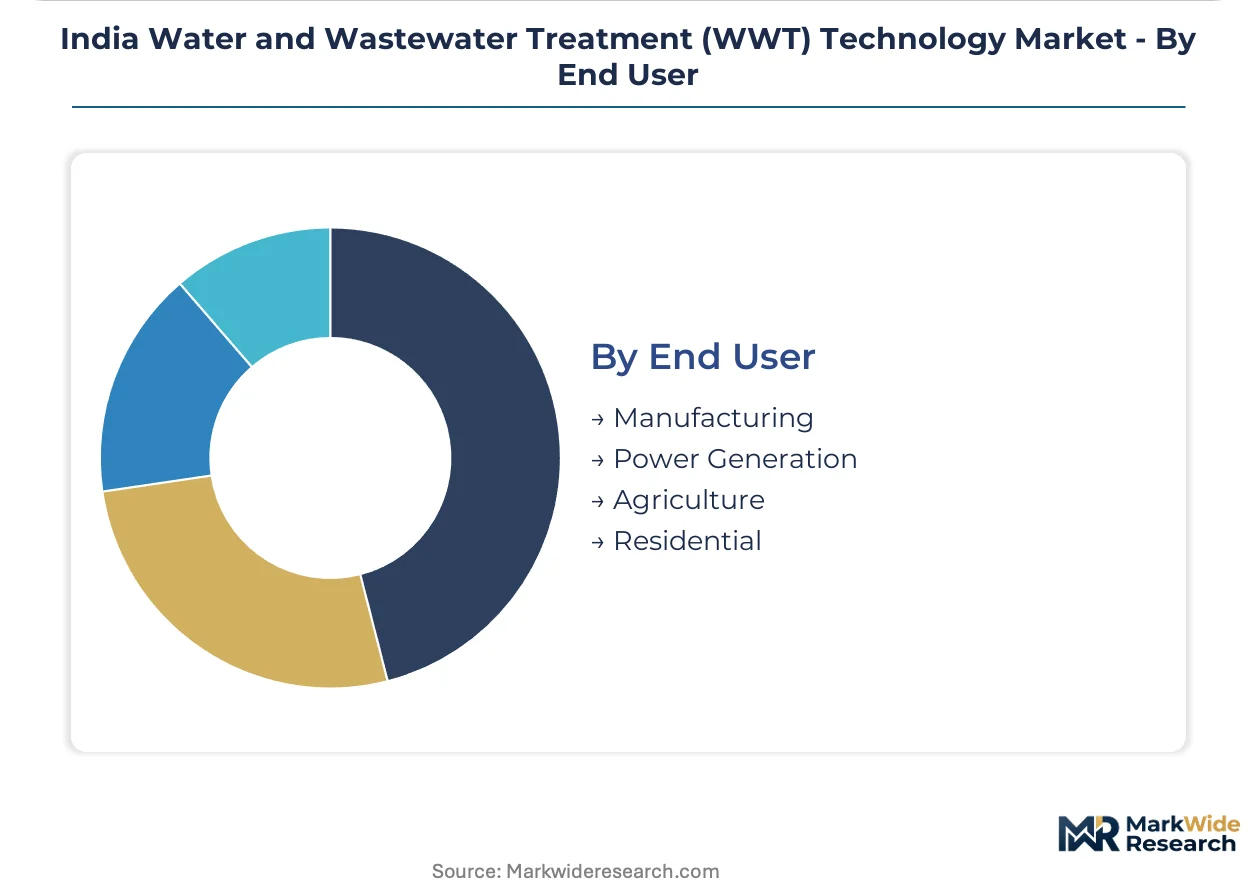
End User:
Water quality specifications and discharge liability exposure create distinct procurement behaviors across end-user categories.
- Manufacturing:Textile, tannery, and pharmaceutical facilities in Tamil Nadu, Uttar Pradesh, and Telangana face the tightest effluent standards. Zero-liquid-discharge compliance is reshaping capital allocation toward membrane-thermal hybrid systems.
- Power Generation:Thermal plants require boiler feedwater conditioning and cooling tower blowdown treatment.
- Agriculture:Drip irrigation expansion in water-stressed districts is driving demand for dissolved solids removal.
- Residential:Point-of-use UV and reverse osmosis units face 14-18 month BIS certification timelines.
Manufacturing commands premium technology specifications; residential point-of-use systems are expanding most quickly in arsenic-affected blocks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's water treatment technology trade deficit concentrates in membrane elements, with domestic engineering firms sourcing thin-film composites from East Asian suppliers while exporting packaged biological treatment skids to South Asian neighbors.
Maharashtra
Pune and Nagpur municipal corporations are bundling desalination with sewage recycling under integrated water management tenders. The state water board's Jal Jeevan Mission allocations prioritize membrane bioreactor trains for water-scarce catchments in Marathwada. Mumbai's industrial belt drives demand for zero-liquid-discharge retrofits in pharmaceuticals and textiles.
Gujarat
Performance-based service contracts are displacing capital purchase models for municipal membrane plants across Ahmedabad and Surat. The state's pollution control board enforces strict consent-to-operate norms for dyeing houses in the Surat cluster. Dahej and Mundra industrial corridors anchor membrane-thermal hybrid system deployments.
Tamil Nadu
Tiruppur's dyeing units face consent-to-operate suspensions without advanced oxidation process upgrades ahead of state pollution control board renewals. The leather cluster in Vellore is installing ozone-UV hybrid skids to meet chemical oxygen demand limits below 30 mg per liter. Chennai's municipal utility is expanding seawater reverse osmosis capacity.
Uttar Pradesh
Kanpur's tannery cluster is retrofitting extended biological aeration with tertiary treatment trains under Central Pollution Control Board's 2023 effluent standard amendments. The state's Jal Jeevan Mission allocations target arsenic-affected blocks in the Indo-Gangetic plain. Noida and Greater Noida industrial areas are upgrading common effluent treatment plants.
Telangana
Hyderabad's bulk drug parks are expanding UV disinfection deployments under CDSCO audit requirements for sterile water systems. The state's life sciences corridor is driving chemical-free disinfection technology adoption. Genome Valley pharmaceutical clusters are specifying advanced oxidation for recalcitrant pharmaceutical effluent.
India Water and Wastewater Treatment (WWT) Technology Market Competitive Landscape
Concentration sits with integrated engineering-procurement-construction specialists that bundle civil infrastructure with electromechanical packages. The vendor base spans three tiers: multinational technology licensors with membrane manufacturing alliances, domestic capital goods conglomerates with captive component production, and regional system integrators focused on standardized package plants. Strategic moves center on backward integration into membrane manufacturing and performance-contracting revenue models that shift risk from municipalities to operators.
Within the domestic integrated tier, VA Tech Wabag, Thermax Limited, and Larsen & Toubro occupy positions that exemplify divergent capability strategies. VA Tech Wabag represents the build-operate-transfer specialist archetype with municipal desalination track records. Thermax Limited anchors the captive manufacturing archetype through in-house production of pressure vessels and ion-exchange resins. Larsen & Toubro exemplifies the civil-mechanical bundling archetype, leveraging infrastructure execution scale for large order pricing power.
| Leading Market Players |
|---|
| VA Tech Wabag |
| Thermax Limited |
| Ion Exchange India |
| Veolia |
| Aquatech |
| Larsen & Toubro |
| Xylem |
| DuPont |
| Ecolab |
| Others |
Supply & Pricing Matrix
BIS certification timelines under IS 10500 protocols gate both supplier qualification and price differentiation, compressing margins for small-cap equipment makers while amplifying premiums for membrane vendors with captive manufacturing alliances.
Pricing Analysis
Configured-to-order pricing for membrane-thermal hybrid systems commands spreads of 40-60 percent above standardized MBBR skids. Project-based contracting dominates municipal tenders, with price differentiation anchored in certification grade and after-sales service bundling. Cost compression in biological treatment packages is intensifying because Rajasthan and Uttar Pradesh manufacturers are flooding urban local body procurement with interchangeable skids. State water boards exhibit highest price sensitivity; pharmaceutical sterile water systems show lowest sensitivity due to CDSCO audit compliance requirements.
Supply Chain Analysis
Inventory lead times for thin-film composite reverse osmosis elements stretch 16-24 weeks, tethering project cash flows to Korean and Japanese supplier schedules. Domestic engineering firms draw from East Asian membrane sources while sourcing pressure vessels and ion-exchange resins from captive Indian production. Single-source vulnerability concentrates in spiral-wound element supply, with yen and won volatility transmitting directly into project economics. Distribution runs through EPC contractors who bundle civil infrastructure with skid-mounted electromechanical packages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India WWT technology market is entering a cyclical recovery phase as Jal Jeevan Mission allocations accelerate replacement cycles for membrane filtration assets across state water boards.
For Market Incumbents: Compound pricing power by deepening backward integration into membrane manufacturing or securing long-term Korean and Japanese supplier alliances. Defend municipal order books through performance-contracting revenue models that shift membrane replacement risk from municipalities to operators. The threat of standardized MBBR skids from Rajasthan and Uttar Pradesh manufacturers demands differentiation through commissioning expertise and uptime guarantees. For New Entrants and Emerging Players: Lead with ion-exchange and adsorption technology packages targeting arsenic- and fluoride-affected rural blocks in Jharkhand and Chhattisgarh under Jal Jeevan Mission allocations. The most penetrable segment sits in pharmaceutical UV disinfection for Hyderabad and Bengaluru bulk drug parks where CDSCO audit requirements are expanding chemical-free disinfection deployments. A go-to-market angle anchored in remote membrane fouling monitoring combined with predictive chemical dosing algorithms opens performance-contracting revenue streams without heavy EPC balance sheet requirements. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across membrane-thermal hybrid system deployments as zero-liquid-discharge mandates force distillery and pulp mill retrofits along the Delhi-Mumbai Industrial Corridor. Long-term viability favors contractors with captive membrane manufacturing or enduring supplier alliances that can sustain pricing power through yen and won volatility. The acquisition target archetype is regional system integrators with standardized package plant expertise in biological treatment, positioned for bolt-on integration by integrated EPC specialists. The signal to watch is state pollution control board interpretation variance on zero-liquid-discharge rules, which will redirect capital deployment across regional industrial corridors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Membrane Manufacturing | Captive thin-film composite production insulates project margins from Korean and Japanese currency volatility. |
| Performance-Based Service Contracting | Municipalities in Gujarat and Maharashtra now pay per kiloliter treated, concentrating vendor selection on historical uptime data. |
| Remote Membrane Fouling Monitoring | Industrial IoT convergence with predictive chemical dosing algorithms creates recurring revenue streams beyond equipment sales. |
| Jharkhand and Chhattisgarh Rural Expansion | Jal Jeevan Mission allocations for arsenic- and fluoride-affected blocks favor ion-exchange technology packages. |
| Pharmaceutical UV Disinfection Specialization | CDSCO audit requirements for sterile water systems in Hyderabad and Bengaluru bulk drug parks expand chemical-free disinfection deployments. |
Research Methodology
The analysis maps membrane filtration, activated sludge, UV treatment, and biofilm reactor sub-sectors, each validated through municipal procurement officers, plant engineers at textile and tannery clusters, EPC project managers, and aftermarket service heads. Primary interviews with these stakeholders combined with secondary validation from Central Pollution Control Board effluent standard amendments, BIS certification protocols under IS 10500, state water board tender documents, and Jal Jeevan Mission allocation records. Bottom-up project pipeline aggregation and top-down regulatory enforcement intensity scoring were triangulated for consistency.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include technology type, application category, end-user industry, and regional enforcement intensity cluster. CAGRs were derived from project commissioning timelines and replacement cycle compression under regulatory tightening. Industry-specific forecast inputs incorporated membrane import lead times and certified operator scarcity outside Gujarat and Karnataka.
The analysis sits within stated boundaries; outcomes outside sustained Jal Jeevan Mission funding continuity or stable Korean and Japanese membrane supply would require recalibration. Forecasts reflect documented assumptions on state pollution control board enforcement variance and import substitution progress in thin-film composite manufacturing. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
Water Gel Market
Water & Sludge Treatment
Asia-Pacific Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
Pool and Spa Water Treatment Chemicals for Hotels and Clubs Market
Water & Sludge Treatment
Sludge Treatment and Disposal Equipment Market
Water & Sludge Treatment
North America Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
Slurry Valves Market
Water & Sludge Treatment
Germany Water Treatment Chemicals Market
Water & Sludge Treatment
Swimming Pool Treatment Chemicals Market
Water & Sludge Treatment
Industrial Wastewater Treatment Market
Water & Sludge Treatment
Liquid Waste Container Market
Water & Sludge Treatment
Africa Water Treatment Chemicals Market
Water & Sludge Treatment
South America Water Treatment Chemicals Market
Water & Sludge Treatment
Deionized Water Systems Market
Water & Sludge Treatment
Sludge Heater Market
Water & Sludge Treatment
Asia-Pacific Membrane Water and Wastewater Treatment (WWT) Market
Water & Sludge Treatment
Process Water Treatment Market