
 Internal Boiler Treatment Chemicals Market | 2026-2036
Internal Boiler Treatment Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Internal Boiler Treatment Chemicals Market Analytics
Aftermarket service revenue is tilting toward predictive water chemistry management and remote monitoring contracts. Ecolab Inc. leverages its global service network to anchor recurring revenue streams beyond chemical sales. Kurita Water Industries Ltd. specializes in membrane-based pre-treatment integration that sustains long-term boiler efficiency contracts. Solenis competes through digital dosing platforms that extend customer retention in industrial accounts.
Internal boiler treatment chemicals are specialty formulations comprising oxygen scavengers, alkalinity builders, and polymeric dispersants designed to prevent scale deposition and metallic corrosion in closed-loop steam systems operating at pressures from 15 to 3,200 psi. These chemicals maintain heat transfer efficiency and prevent tube failures in steam-generating equipment across industrial and commercial installations. Corrosion inhibitors command the largest product-type position due to their non-negotiable role in protecting carbon steel surfaces at elevated temperatures. Oxygen scavengers represent the fastest-expanding category as ultra-low dissolved oxygen targets become standard in high-pressure power generation boilers. Liquid formulations dominate procurement patterns because they permit automated feed systems and precise concentration control in continuous operations.
The EPA enforces Boiler Maximum Achievable Control Technology standards that compel facilities to document water treatment protocols and maintain stack emission limits. OSHA mandates workplace chemical exposure limits that shape product formulation choices and handling procedures for boiler treatment programs. ISO 9001 quality management certification has become a baseline market-access requirement for suppliers serving regulated industrial end users. Stakeholders must monitor evolving state-level water discharge regulations and assess whether green chemistry alternatives can meet performance thresholds without reformulation penalties.
Market Dynamics
Power generation facilities face mounting pressure to maintain ultra-low dissolved oxygen targets in high-pressure steam systems, forcing chemical suppliers to reformulate oxygen scavenger portfolios and embed predictive monitoring capabilities into service contracts.
Growth Catalysts
- Boiler MACT Standards:EPA emission mandates compel US industrial facilities to document water chemistry protocols and upgrade treatment programs, creating sustained chemical demand from compliance-driven retrofits.
- High-Pressure Boiler Expansion:China's manufacturing zones continue installing industrial boilers requiring specialized alkalinity builders and polymeric dispersants for scale control at elevated operating pressures.
- Membrane Pre-Treatment Integration:Combined reverse osmosis and boiler chemical programs extend equipment life cycles, anchoring long-term service contracts with measurable efficiency guarantees.
Market Restraints
- Phosphonate Raw Material Volatility:Sequestering agent formulations depend on phosphonate supply chains concentrated in Chinese manufacturing, exposing formulators to input cost swings and qualification delays.
- Green Chemistry Performance Gap:Bio-based dispersants struggle to match synthetic polymer efficacy in high-alkalinity, high-temperature conditions without reformulation penalties or dose rate increases.
- Specialized Technical Labor Scarcity:Water chemistry specialists capable of optimizing complex multi-product programs remain concentrated near established industrial clusters, limiting service expansion into emerging manufacturing regions.
Strategic Opportunities
- India Industrial Corridor Expansion:BIS certification requirements for boiler installations in Gujarat and Maharashtra chemical zones create entry points for suppliers offering integrated treatment and compliance documentation packages.
- Digital Dosing Platform Convergence:IoT-enabled chemical feed systems combined with cloud-based analytics enable remote optimization, shifting revenue from product sales to subscription-based performance contracts.
- EU Green Deal Chemistry Incentives:REACH-registered bio-scavenger formulations gain preferential procurement status in German and Dutch food-processing steam applications where discharge regulations are tightening.
Industry Challenges
- Legacy DCS Integration Complexity:Automated chemical feed systems must interface with decades-old distributed control architectures common in US power plants, extending commissioning timelines and requiring custom protocol bridges.
- ISO 9001 Certification Burden:Smaller regional formulators face documentation and audit costs that extend market-access timelines, consolidating procurement authority with certified multinational suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Internal Boiler Treatment Chemicals Market |
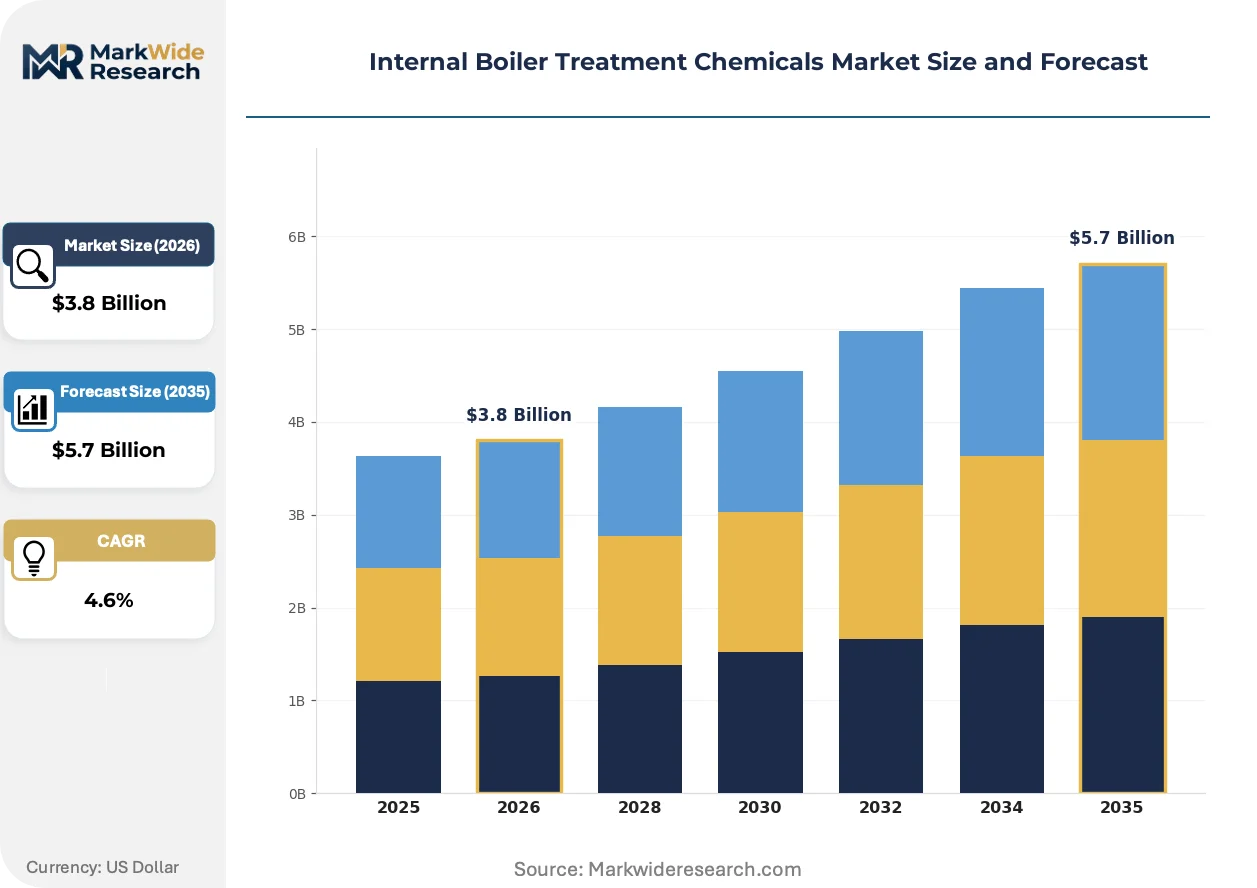
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corrosion Inhibitors, Oxygen Scavengers, pH Control Agents, Scale Inhibitors Application: Industrial Boilers, Commercial Boilers, Power Generation, Water Treatment Formulation: Liquid, Powder, Granular, Emulsion End User: Manufacturing, Pharmaceuticals, Energy, Food Processing |
| Companies Covered | Ecolab Inc., Solenis, Veolia Water Technologies, SUEZ Water Technologies & Solutions, Kurita Water Industries Ltd., ChemTreat, Inc., BASF SE, Akzo Nobel N.V., Buckman Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Internal Boiler Treatment Chemicals Market Evolving Landscape
Real-time water chemistry monitoring is compressing the feedback loop between boiler operation and chemical adjustment, enabling condition-based dosing that reduces chemical consumption while preventing tube failure events.
Smart sensor networks embedded in steam condensate return lines are digitizing corrosion rate tracking and scale deposition prediction. Power generation operators in the United States deploy these systems to maintain EPA Boiler MACT documentation automatically. The technology is digitizing traditional manual sampling programs into continuous compliance reporting, reducing laboratory staffing requirements while improving incident response speed.
REACH authorization timelines for traditional phosphonate-based scale inhibitors are accelerating formulation shifts across European industrial boiler installations. German chemical manufacturers face substance sunset dates that force reformulation investments or supply chain requalification. Food and beverage steam applications show the most visible response, with processors switching to polyacrylate alternatives ahead of regulatory deadlines to avoid production interruption risks.
Buying committees at multi-site manufacturing conglomerates are consolidating chemical procurement under corporate sustainability officers who prioritize suppliers with verified carbon footprint data and closed-loop packaging programs. Channel relationships with local distributors are giving way to direct master service agreements with annual performance guarantees. This pattern is most visible in Japanese automotive supplier networks where METI energy efficiency guidelines reward documented chemical optimization with tax incentives.
Internal Boiler Treatment Chemicals Market Segmentation
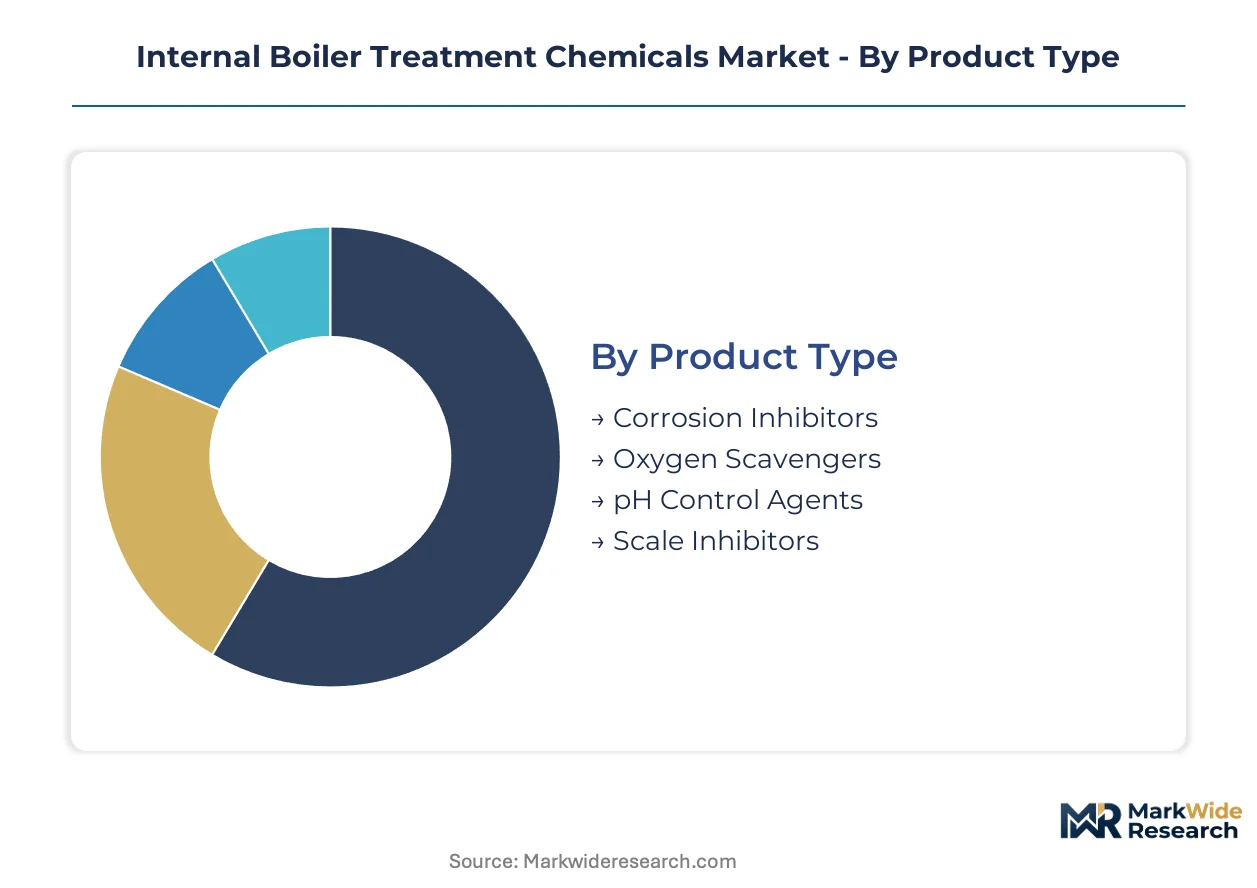
Internal boiler treatment chemicals serve distinct operational regimes across pressure classes, water chemistries, and compliance environments. Segment boundaries align with replacement cycles, formulation stability, and the technical sophistication of dosing infrastructure.
Product Type:
Oxygen scavengers turn over fastest due to continuous consumption in high-pressure systems, while scale inhibitors exhibit slower replacement cycles tied to seasonal blowdown schedules.
- Corrosion Inhibitors:Formulations combining filming amines and neutralizing amines protect carbon steel surfaces in condensate return systems. Demand concentrates in US power generation facilities facing EPA Boiler MACT documentation requirements for metallic corrosion prevention.
- Oxygen Scavengers:Catalyzed sulfite, hydrazine, and organic scavenger variants target dissolved oxygen levels below 5 ppb in ultra-high-pressure boilers. China's expanding manufacturing zones drive procurement volume as new industrial boiler installations multiply across chemical processing clusters.
- pH Control Agents:Alkalinity builders and pH buffers maintain 10.5-11.5 operating ranges in boiler water. Food processing steam applications in Germany and the Netherlands prioritize REACH-compliant formulations ahead of phosphonate sunset dates.
- Scale Inhibitors:Phosphonate and polyacrylate dispersants sequester calcium and magnesium hardness. Polyacrylate alternatives gain traction in European installations facing ECHA authorization timelines for traditional phosphonate chemistries.
Corrosion inhibitors dominate installed base. Oxygen scavengers are where expansion concentrates.
Application:
Power generation commands the highest formulation specification tiers, while commercial boilers operate on standardized treatment programs with lower technical service intensity.
- Industrial Boilers:High-pressure systems in chemical, petrochemical, and steel operations require customized multi-product programs. India's Gujarat and Maharashtra industrial corridors anchor near-term demand as BIS certification mandates expand.
- Power Generation:Utility and independent power producer boilers operate at 2,000+ psi with zero-tolerance tube failure protocols. US facilities deploy predictive monitoring to maintain EPA Boiler MACT compliance documentation automatically.
- Commercial Boilers:Healthcare, hospitality, and institutional heating systems prioritize automated liquid feed systems over manual powder handling. Japanese automotive supplier networks reward documented chemical optimization with METI energy efficiency tax incentives.
- Water Treatment:Pre-treatment and condensate polishing integration extends chemical program scope. Membrane-based RO-boiler combined programs anchor long-term service contracts with measurable efficiency guarantees.
Industrial boilers generate the highest chemical consumption per installation. Power generation delivers the steepest expansion trajectory for premium-formulation demand.
Formulation:
Liquid formulations support continuous feed automation, while powder and granular forms persist in legacy manual-dosing installations with lower capital investment profiles.
- Liquid:Ready-to-feed solutions enable precise concentration control through automated metering pumps. Manufacturing conglomerates consolidate procurement under corporate sustainability officers prioritizing closed-loop packaging programs.
- Powder:Concentrated dry blends reduce shipping costs and storage footprint for remote industrial sites. Specialized technical labor scarcity limits service expansion into emerging manufacturing regions lacking water chemistry specialists.
- Granular:Controlled-dissolution granules suit intermittent boiler operations with variable steam demand. Smaller regional formulators face ISO 9001 documentation burdens that consolidate procurement authority with certified multinational suppliers.
- Emulsion:Oil-in-water dispersions deliver hydrophobic active ingredients into high-alkalinity boiler water. Green chemistry performance gaps constrain bio-based emulsion adoption in high-temperature conditions without dose rate penalties.
Liquid formulations dominate procurement patterns. Emulsion technologies are gaining share fastest in specialized high-alkalinity applications.
End User:
Energy sector procurement cycles align with major turnaround schedules, while pharmaceutical and food processing demand exhibit tighter regulatory-driven reformulation timelines.
- Manufacturing:Chemical, textile, and general industrial boilers prioritize total cost of ownership over unit chemical pricing. Digital dosing platform convergence enables remote optimization shifting revenue to subscription-based performance contracts.
- Energy:Oil refineries and petrochemical complexes operate integrated steam-utility networks requiring 24/7 chemical program reliability. Legacy DCS integration complexity extends commissioning timelines for automated feed systems in decades-old plant architectures.
- Pharmaceuticals:cGMP-compliant steam for sterilization and process heating mandates validated water treatment protocols. FDA inspection readiness drives documented chemical optimization with audit trail capabilities.
- Food Processing:Direct and indirect food-contact steam applications face tightening discharge regulations across EU member states. EU Green Deal chemistry incentives accelerate bio-scavenger procurement in German and Dutch processing facilities.
Manufacturing anchors volume demand. Food processing is where regulatory-driven formulation shifts concentrate most intensely.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. US power generators prioritize predictive monitoring for EPA compliance, while Chinese manufacturers emphasize high-pressure system scale control. European food processors lead in bio-based formulation adoption ahead of regulatory deadlines.
United States
Utility-scale power plants drive demand for ultra-low dissolved oxygen scavengers and automated dosing infrastructure. EPA Boiler MACT standards mandate continuous water chemistry documentation and stack emission controls. Texas and Ohio industrial corridors anchor procurement volume for high-pressure boiler treatment programs.
China
Manufacturing zones across chemical and steel sectors require specialized alkalinity builders and polymeric dispersants for new boiler installations. MIIT industrial efficiency guidelines accelerate treatment program upgrades in state-owned enterprises. Yangtze River Delta chemical clusters concentrate procurement for membrane-integrated boiler systems.
Germany
Food and beverage steam applications prioritize REACH-compliant pH control agents ahead of phosphonate sunset dates. ECHA authorization timelines force reformulation investments across industrial boiler installations. Rhineland chemical processors switch to polyacrylate scale inhibitors to avoid production interruption risks.
India
BIS certification requirements for boiler installations in Gujarat and Maharashtra create entry points for integrated treatment suppliers. CEA efficiency mandates reward documented chemical optimization in thermal power stations. Western industrial corridors anchor near-term demand for multi-product treatment programs.
Japan
Automotive supplier networks consolidate procurement under corporate sustainability officers prioritizing closed-loop packaging. METI energy efficiency guidelines reward documented chemical optimization with tax incentives. Kanto and Kansai manufacturing belts concentrate demand for liquid formulation automated feed systems.
Internal Boiler Treatment Chemicals Market Competitive Landscape
Capability concentration sits with specialty chemical formulators possessing membrane integration expertise; scale advantage sits with diversified water treatment conglomerates with global service networks. The market structures around three tiers: multinational integrated suppliers, regional formulation specialists, and niche technology licensors. Consolidation pressure favors players with predictive monitoring platforms and long-term performance contracts. Geographic expansion and digital dosing platform development represent the dominant competitive vectors.
Among diversified water treatment conglomerates, Ecolab Inc., Solenis, and Kurita Water Industries Ltd. exemplify distinct strategic positions. Ecolab anchors the premium service tier through recurring revenue models extending beyond chemical sales. Solenis occupies a position emphasizing digital dosing convergence and remote optimization capabilities. Kurita represents the membrane integration specialist archetype, anchoring long-term efficiency contracts through pre-treatment system bundling.
| Leading Market Players |
|---|
| Ecolab Inc. |
| Solenis |
| Veolia Water Technologies |
| SUEZ Water Technologies & Solutions |
| Kurita Water Industries Ltd. |
| ChemTreat, Inc. |
| BASF SE |
| Akzo Nobel N.V. |
| Buckman Laboratories |
| Others |
Value Network & Pricing Analysis
Phosphonate manufacturing concentration in China directly determines margin distribution across formulators in North America and Europe, with raw material qualification delays and tariff exposure compressing returns for non-integrated suppliers dependent on Asian feedstock imports.
Pricing Analysis
Long-term performance contracts with annual efficiency guarantees dominate procurement for power generation and large industrial accounts, while spot purchasing persists for commercial boiler operators with lower technical service requirements. Price differentiation stems from ISO 9001 certification tier and membrane pre-treatment bundling intensity. Cost compression in standard-grade oxygen scavengers is intensifying because phosphonate raw material volatility exposes non-integrated formulators to input cost swings. Commercial boiler end users exhibit highest price sensitivity due to standardized treatment programs with limited customization, whereas power generation facilities prioritize documented EPA Boiler MACT compliance over unit pricing.
Supply Chain Analysis
Upstream feedstock production of phosphonate intermediates, catalyzed sulfite precursors, and polyacrylate monomers concentrates in China, Germany, and the United States. Formulation draws from these three input streams plus membrane module supply chains anchored in Japan and South Korea. Single-source vulnerability in Chinese phosphonate qualification creates supply chain risk for Western formulators facing ECHA authorization timelines. Distribution runs through authorized chemical distributors with technical service capabilities, though direct master service agreements are displacing channel relationships at multi-site manufacturing conglomerates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment and switching costs protect incumbents with validated EPA documentation protocols and embedded predictive monitoring infrastructure.
For Market Incumbents: Build switching-cost moats through predictive water chemistry platform integration that automates EPA Boiler MACT compliance documentation. Deepen membrane pre-treatment bundling to extend contract duration beyond chemical-only supply. Capacity addition in India's Gujarat and Maharashtra corridors captures BIS certification-driven demand before regional formulators achieve ISO 9001 compliance.
For New Entrants and Emerging Players: Establish a beachhead in India's western industrial corridors where BIS certification requirements and technical labor scarcity delay multinational service expansion. Target food processing steam applications in Germany and the Netherlands facing REACH phosphonate sunset dates with bio-scavenger formulations. Go-to-market through direct master service agreements with documented carbon footprint data to satisfy corporate sustainability officer procurement consolidation.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional formulators possessing ISO 9001 certification but lacking predictive monitoring platforms. Five-to-ten year viability hinges on digital dosing convergence and membrane integration capabilities. Watch for ECHA authorization timeline acceleration as inflection signal for polyacrylate scale inhibitor demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphonate Feedstock | Captive supply of sequestering agent precursors insulates margins from Chinese raw material volatility. |
| Predictive Monitoring Platform Deployment | IoT-enabled water chemistry analytics shift revenue from transactional chemical sales to subscription performance contracts. |
| Membrane Pre-Treatment System Bundling | Combined RO-boiler programs anchor long-term efficiency guarantees with measurable equipment life extension. |
| REACH-Compliant Bio-Scavenger Formulation | ECHA authorization timelines for traditional chemistries create preferential procurement status in EU food processing. |
| India Industrial Corridor Service Expansion | BIS certification mandates in Gujarat and Maharashtra create entry points for integrated treatment suppliers. |
Research Methodology
Cross-validation between primary interviews with plant engineers, water chemistry specialists, procurement leads at downstream OEMs, and distribution channel partners anchors the qualitative findings. Secondary validation draws from EPA enforcement documentation, ECHA authorization timelines, SEC 10-K filings of listed suppliers, and customs trade data for phosphonate intermediate flows. Bottom-up segmentation modeling triangulates against top-down macroeconomic calibration across the analysis window.
Calibration against historical replacement cycle patterns and regulatory compliance spending elasticity shapes the analytical framework. Segmentation dimensions include product type tier, end-use industry pressure class, formulation automation level, and regional regulatory cluster. CAGRs derive from installed base turnover rates and new boiler installation trajectories. Forecast inputs incorporate MIIT industrial efficiency guideline implementation pace and EPA Boiler MACT enforcement intensity.
Stress conditions across phosphonate supply disruption, ECHA authorization acceleration, and India BIS certification timeline compression were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement continuity and membrane technology adoption curves. Cross-checking against EIA power generation capacity additions and IEA industrial efficiency spending benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
Industrial Water Treatment Chemicals Market
Water & Sludge Treatment
India Water Treatment Market
Water & Sludge Treatment
CMP Slurry Blend and Delivery Systems Market
Water & Sludge Treatment
South America Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
Asia-Pacific Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
Europe Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
Semiconductor Wastewater Treatment Market
Water & Sludge Treatment
Global Industrial Sludge Treatment Chemicals Market
Water & Sludge Treatment
South America Water Treatment Chemicals Market
Water & Sludge Treatment
Slurry Valves Market
Water & Sludge Treatment
Drinking Water Adsorbents Market
Water & Sludge Treatment
Global Valves in Water and Wastewater Market
Water & Sludge Treatment
Ballast Water Treatment Market
Water & Sludge Treatment
China Water Treatment Chemicals Market
Water & Sludge Treatment
Global Electrodeionization Market
Water & Sludge Treatment
Hazardous Waste Treatment System Market