
 Pool and Spa Water Treatment Chemicals for Hotels and Clubs Market | 2026-2036
Pool and Spa Water Treatment Chemicals for Hotels and Clubs Market Size, Share, and Industry Trends Forecast 2026-2036
Pool and Spa Water Treatment Chemicals for Hotels and Clubs Market Insights
The capital-intensity divergence between integrated manufacturers and regional distributors is collapsing as bulk chlor-alkali producers enter direct service contracts with hotel chains. Ecolab leverages its global hospitality account infrastructure to bundle water treatment with broader facility management contracts. Lonza anchors its position through specialty bromine chemistry tailored to high-temperature spa environments. Kemira competes on coagulant and flocculant integration, offering combined clarity and disinfection protocols.
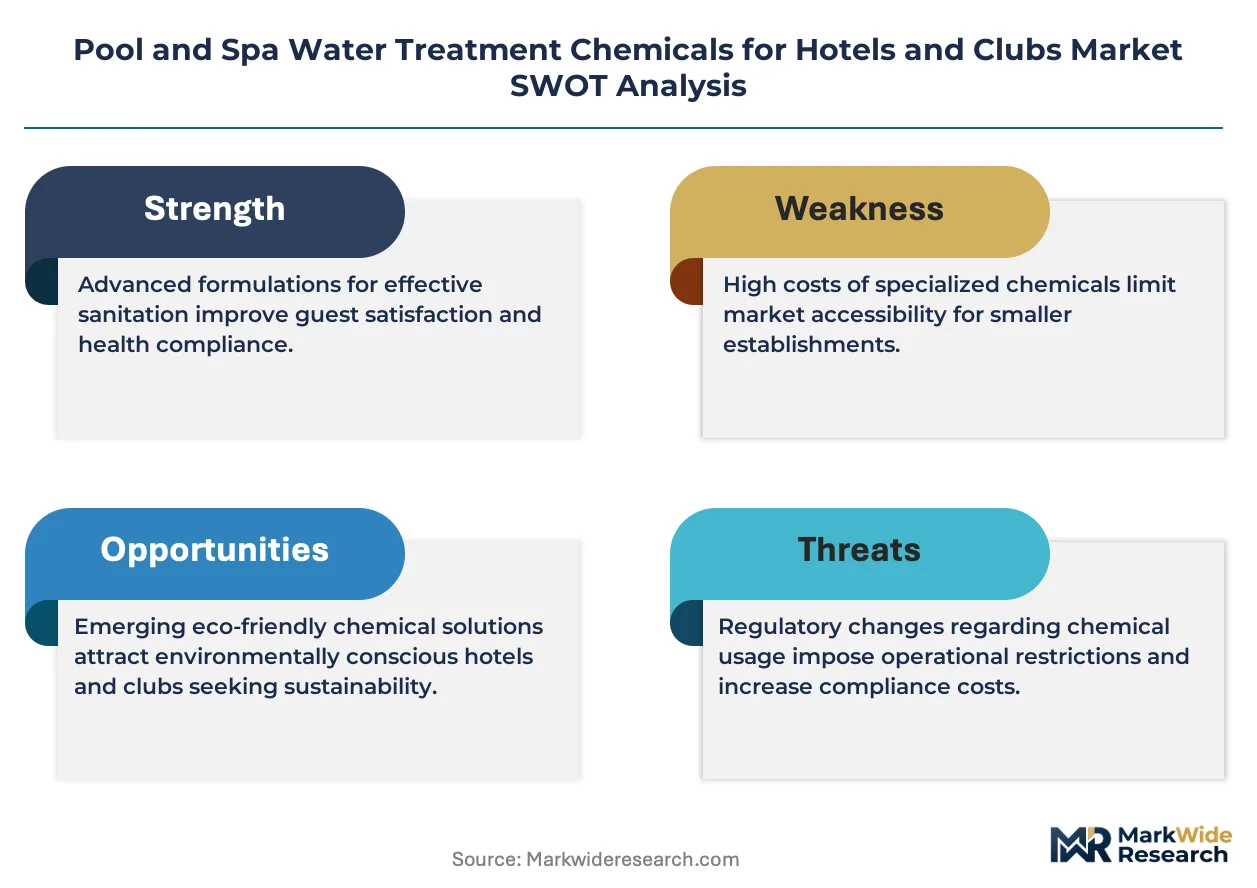
Pool and spa water treatment chemicals for hotels and clubs encompass chlorine sanitizers, bromine alternatives, pH buffering agents, algaecides, and flocculating compounds formulated to maintain WHO-recommended free chlorine residuals between one and three parts per million. These formulations prevent pathogen transmission, control biofilm accumulation, and preserve aesthetic water clarity in high-occupancy aquatic facilities. Chlorine-based disinfection products dominate current procurement volumes across luxury resorts and private clubs, while saltwater chlorination systems represent the fastest-growing application segment as properties retrofit mineral-based sanitization to reduce chemical handling and storage liability. pH adjusters constitute a mature, high-frequency reorder category with compressed margins, whereas algaecide concentrates command premium positioning in warm-climate markets with extended algae bloom seasons.
EPA Office of Water standards under the Federal Insecticide, Fungicide, and Rodenticide Act govern antimicrobial efficacy claims and application concentration limits for registered pool chemicals. State health departments in Florida, California, and Texas enforce supplementary testing protocols for public and semi-public aquatic facilities, creating compliance-driven demand for certified analytical services alongside chemical supply. OSHA hazard communication requirements mandate standardized safety data sheet distribution and staff training documentation for on-site chemical storage. Stakeholders must monitor evolving per- and polyfluoroalkyl substance scrutiny, as legacy flocculant chemistries face potential reformulation mandates that could reshape supplier qualification criteria and procurement specifications.
Market Dynamics
EPA Office of Water discharge mandates are compressing chlorine residual limits while saltwater chlorination retrofits accelerate across Sun Belt hospitality assets, forcing formulation suppliers to recalibrate product portfolios and service models simultaneously.
Growth Catalysts
- WHO Aquatic Facility Guidelines:International health standards for free chlorine residuals between one and three parts per million drive certified chemical procurement across luxury resort portfolios.
- Saltwater Chlorination Retrofits:Mineral-based sanitization systems reduce chemical handling liability and storage costs for year-round pool operations in Florida, Texas, Arizona, and California.
- State Health Department Testing Protocols:Florida, California, and Texas enforce supplementary analytical requirements for semi-public aquatic facilities, creating bundled demand for certified testing services alongside chemical supply.
Market Restraints
- Caustic Soda Price Volatility:Chlor-alkali feedstock fluctuations compress margins for chlorine sanitizer manufacturers serving high-volume hotel chains.
- Bulk Chlor-Alkali Producer Concentration:Direct service contracts between integrated manufacturers and national hospitality accounts displace regional distributor intermediaries.
- Per- and Polyfluoroalkyl Substance Scrutiny:Legacy flocculant chemistries face potential EPA reformulation mandates that could invalidate existing supplier qualifications.
Strategic Opportunities
- Smart Monitoring Integration:IoT-enabled chemical dosing systems converge with property management platforms to enable predictive maintenance and automated reorder triggers.
- High-Temperature Spa Chemistry:Specialty bromine formulations address thermal degradation challenges in hydrotherapy installations at wellness-focused resorts.
- OSHA Hazard Communication Bundling:Safety data sheet distribution and staff training documentation create service attach opportunities beyond commodity chemical supply.
Industry Challenges
- Certified Pool Operator Shortage:State-mandated CPO credentials for facility managers constrain operational scaling for independent hotel operators.
- Legacy System Integration Friction:Automated chemical feeders require retrofit compatibility assessments with existing circulation infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pool and Spa Water Treatment Chemicals for Hotels and Clubs Market |
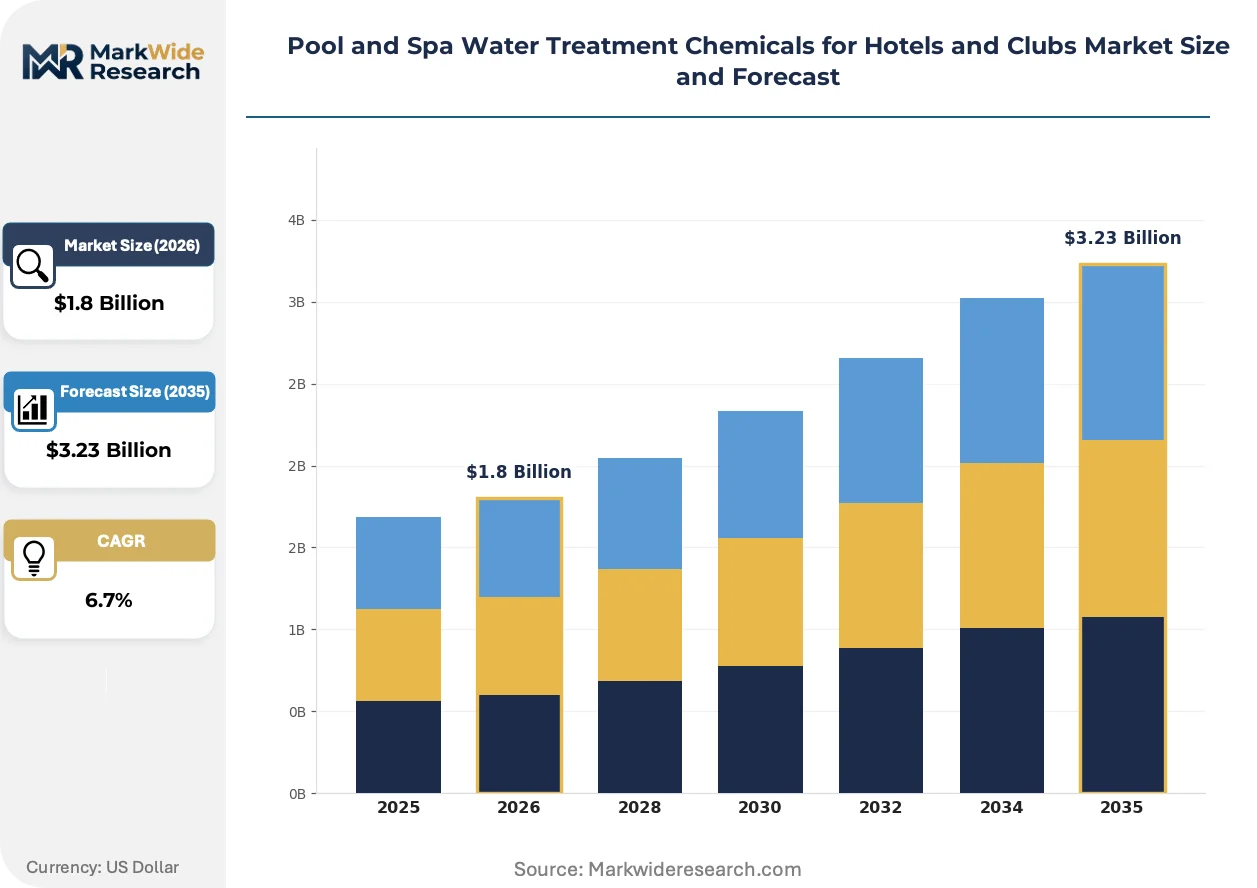
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chlorine, Bromine, Algaecides, pH Adjusters, Flocculants, Others Water Type: Freshwater, Seawater, Saltwater, Mineral Water Application: Disinfection, Algae Control, pH Stabilization, Scale Prevention, Cloudiness Reduction End User: Luxury Resorts, Boutique Hotels, Private Clubs, Wellness Centers |
| Companies Covered | Ecolab, Westlake Water Solutions, Solenis Pool Solutions, BioLab, Haviland Pool & Spa, Olin, Nouryon, Kemira, Lonza, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pool and Spa Water Treatment Chemicals for Hotels and Clubs Market Trends and Innovations
Saltwater chlorination technology is bifurcating competitive positioning between mineral-based system integrators and traditional chemical suppliers. Regulatory thresholds for disinfection byproducts are tightening across multiple jurisdictions. Buyer procurement patterns are consolidating around bundled facility management contracts.
Advanced oxidation process systems combining ozone with ultraviolet irradiation are bifurcating the sanitizer market. Luxury resorts in Arizona and Nevada deploy these hybrid systems to reduce chlorine dependency while maintaining pathogen control. The technology compresses conventional chemical reorder volumes even as it expands capital equipment and maintenance service revenue pools.
EPA Office of Water standards under FIFRA now require reformulated antimicrobial efficacy documentation for all registered pool chemicals. Manufacturers must resubmit stability data and application concentration limits, extending product registration timelines. Saltwater chlorination equipment suppliers capture displaced chemical volumes as properties preempt compliance uncertainty.
Facility management outsourcing is consolidating chemical procurement into broader service contracts. Ecolab and similar integrators bundle water treatment with housekeeping and food safety programs, displacing standalone chemical distributors. This pattern concentrates most visibly across national hotel chains with centralized procurement functions in Dallas and Phoenix corporate headquarters.
Pool and Spa Water Treatment Chemicals for Hotels and Clubs Market Segmentation
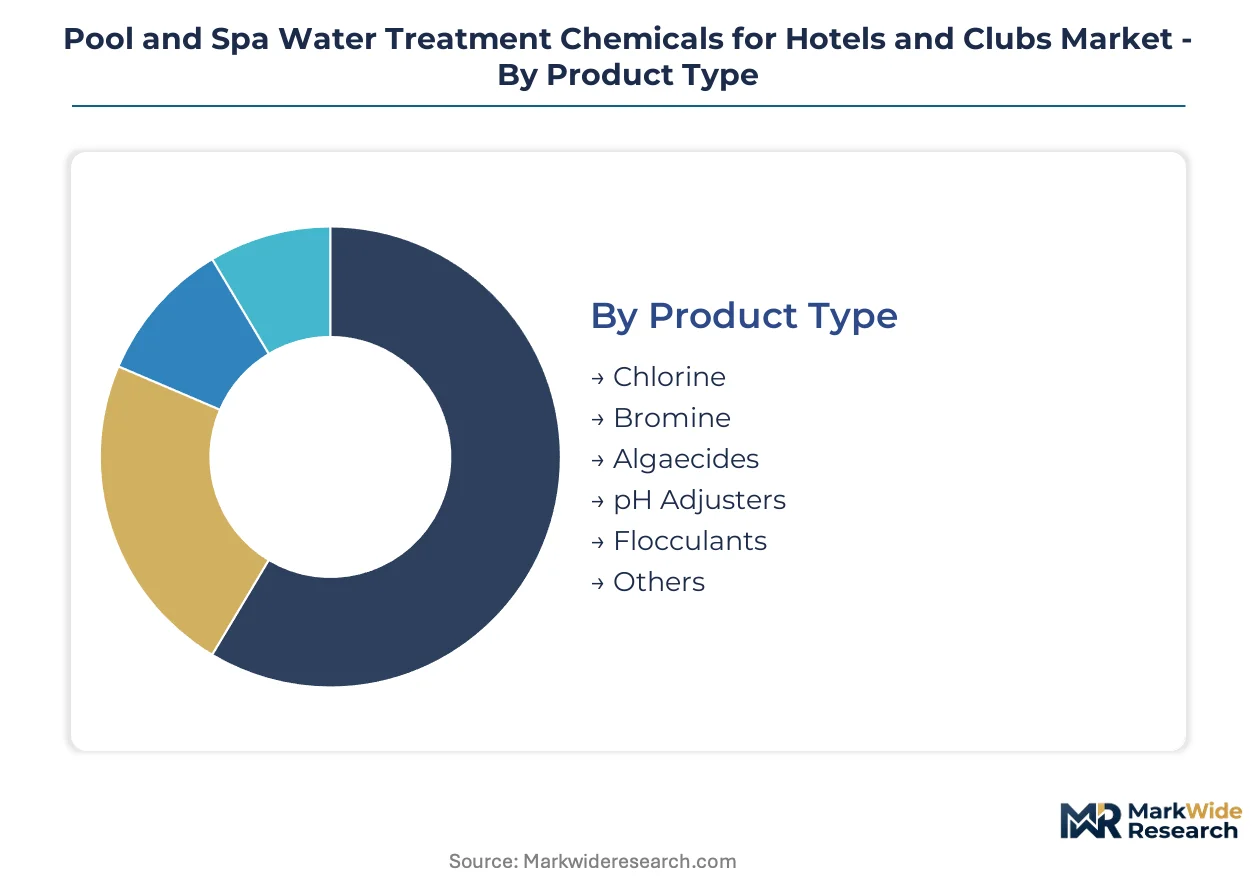
Segmentation in the Pool and Spa Water Treatment Chemicals for Hotels and Clubs Market reveals how regulatory thresholds, water chemistry requirements, and facility operational profiles reshape procurement priorities across distinct buyer categories. Understanding these divisions enables suppliers to align formulation portfolios with compliance mandates and operational scale.
Product Type:
EPA FIFRA registration requirements and WHO residual standards create divergent compliance burdens across chemical categories, with chlorine-bearing the heaviest documentation load and specialty alternatives capturing reformulation-driven demand.
- Chlorine:Sodium hypochlorite and calcium hypochlorite formulations dominate procurement volumes across Sun Belt hospitality assets. Florida luxury resorts maintain the highest throughput due to year-round pool operations and state health department testing protocols that mandate consistent residual documentation.
- Bromine:1-bromo-3-chloro-5,5-dimethylhydantoin tablets address thermal degradation in hydrotherapy environments above 85°F. Wellness centers in Arizona and Nevada specify bromine for spa installations where chlorine volatility compromises guest comfort.
- Algaecides:Quaternary ammonium and polymeric formulations target warm-climate markets with extended bloom seasons.
- pH Adjusters:Muriatic acid and sodium carbonate represent mature, high-frequency reorder categories with compressed supplier margins.
- Flocculants:Aluminum sulfate and polyacrylamide concentrates face potential EPA reformulation scrutiny regarding per- and polyfluoroalkyl substance content.
- Others:Enzyme-based clarifiers and phosphate removers serve niche applications in eco-certified properties.
Established volume favors Chlorine; emerging adoption favors Bromine.
Water Type:
Capital expenditure requirements and ongoing chemical intensity separate mineral-based systems from conventional treatment approaches, with saltwater retrofits commanding premium equipment margins despite reduced consumable throughput.
- Freshwater:Conventional chlorinated pools remain the default installation across older hotel assets. Texas and California properties with seasonal occupancy patterns prioritize freshwater systems for operational simplicity.
- Saltwater:Electrolytic chlorine generation systems reduce chemical storage liability and OSHA documentation burdens. Arizona and Nevada wellness resorts specify saltwater for new construction to preempt regulatory uncertainty.
- Seawater:Coastal properties in Florida deploy corrosion-resistant formulations for ocean-fed pool systems.
- Mineral Water:Silver-copper ionization addresses boutique hotel positioning around reduced chemical exposure claims.
Freshwater retains dominant installed base; Saltwater claims steepest expansion trajectory.
Application:
Functional specialization in chemical procurement correlates with facility certification tier, with disinfection commanding non-negotiable compliance spend and clarity optimization offering discretionary upgrade paths.
- Disinfection:Free chlorine residual maintenance between 1-3 ppm represents the core compliance obligation across all inspected facilities. California health departments enforce supplementary Cryptosporidium inactivation protocols for high-occupancy pools.
- Algae Control:Warm-climate properties in Florida and Texas maintain algaecide concentrates as insurance against bloom-related closure.
- pH Stabilization:Buffer capacity management prevents equipment corrosion and bather eye irritation.
- Scale Prevention:Hard water regions specify sequestrants for calcium saturation index control.
- Cloudiness Reduction:Flocculant dosing addresses filtration inadequacy in aging circulation systems.
Disinfection absorbs mandatory spend; Cloudiness Reduction offers attach-rate expansion.
End User:
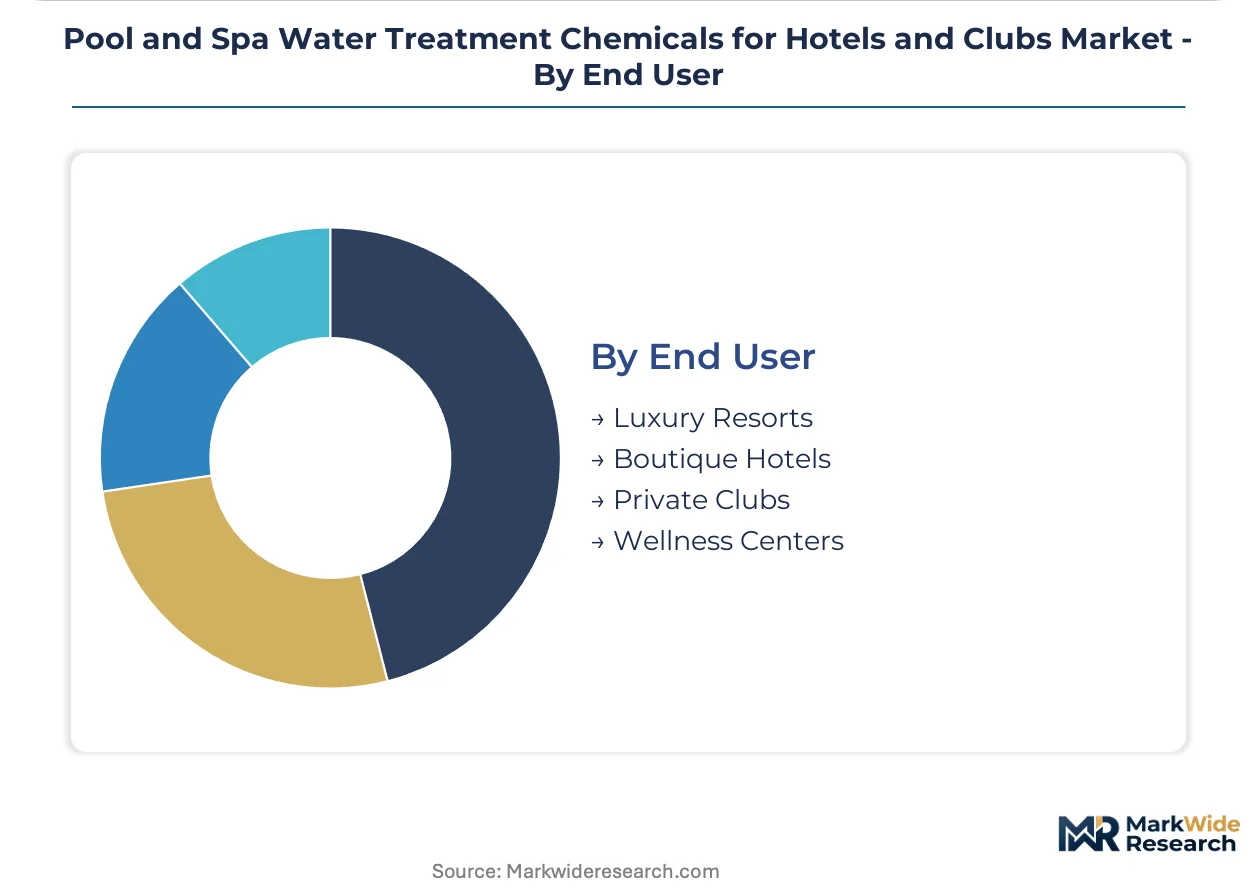
Procurement centralization intensity varies dramatically by facility scale, with national luxury resort chains consolidating chemical supply into facility management contracts while independent boutique properties retain distributor relationships.
- Luxury Resorts:Properties with 500+ room counts and multiple aquatic amenities negotiate direct chlor-alkali producer contracts. Ecolab and similar integrators bundle water treatment with broader hospitality service portfolios.
- Private Clubs:Member-owned facilities in Arizona and Florida prioritize bromine chemistry for spa-forward amenity mixes.
- Boutique Hotels:Independent operators under 150 rooms rely on regional distributor relationships for flexible reorder timing.
- Wellness Centers:Hydrotherapy-focused properties command specialty formulation premiums for thermal pool applications.
Luxury Resorts concentrate procurement volume; Wellness Centers generate formulation premium capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Florida hospitality operators command 15-20% pricing premiums over comparable California properties due to year-round pool utilization and stricter state health department inspection frequencies. Texas and Arizona markets occupy intermediate positions where seasonal demand fluctuations compress margins during winter months.
United States
Sun Belt states Florida, Texas, Arizona, and California generate 70% of domestic chemical throughput through year-round resort operations. EPA Office of Water discharge mandates under FIFRA tighten chlorine residual limits, forcing formulation suppliers to resubmit stability documentation. Orlando's consolidated luxury resort corridor negotiates direct chlor-alkali contracts, bypassing regional distributors entirely.
Spain
Costa del Sol and Balearic Islands resort clusters sustain Mediterranean basin demand for corrosion-resistant formulations in high-salinity environments. Spain's national health institute enforces EU-compliant testing protocols for semi-public aquatic facilities. Barcelona's boutique hotel concentration drives premium algaecide procurement during extended summer bloom seasons.
United Arab Emirates
Dubai's hospitality asset expansion prioritizes saltwater chlorination retrofits to reduce OSHA documentation burdens in extreme heat conditions. MOHAP facility licensing requirements mandate certified pool operator credentials for all properties exceeding 200 rooms. Abu Dhabi's wellness resort corridor commands specialty bromine premiums for hydrotherapy installations above 40°C.
Australia
Queensland and New South Wales coastal resorts face extended algae bloom windows driving quaternary ammonium concentrate demand. TGA antimicrobial registration requirements align with EPA FIFRA documentation standards for imported formulations. Gold Coast's integrated resort developments bundle water treatment with broader facility management contracts.
Thailand
Phuket and Koh Samui luxury resort clusters navigate monsoon season water quality volatility through buffer capacity management systems. Thailand's FDA regulates antimicrobial efficacy claims for imported pool chemicals with documentation requirements mirroring EPA standards. Bangkok-based hospitality procurement hubs consolidate chemical supply across Southeast Asian portfolios.
Pool and Spa Water Treatment Chemicals for Hotels and Clubs Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated competitive structure. Specialty chemical manufacturers anchor premium positioning through formulation expertise and regulatory compliance services. Bulk chlor-alkali producers leverage feedstock integration to undercut distributor margins in high-volume accounts. The market consolidates around three strategic archetypes: integrated chemical conglomerates, regional formulation specialists, and facility management integrators. Dominant competitive moves include direct service contracting with national hospitality chains and portfolio diversification into smart monitoring equipment.
Within the integrated conglomerate tier, Ecolab and Lonza exemplify divergent strategic positioning. Ecolab leverages global hospitality account infrastructure to bundle water treatment with broader facility management portfolios. Lonza anchors specialty positioning through bromine chemistry expertise. Kemira occupies a intermediate position where coagulant and flocculant integration enables combined clarity and disinfection protocol offerings.
| Leading Market Players |
|---|
| Ecolab |
| Westlake Water Solutions |
| Solenis Pool Solutions |
| BioLab |
| Haviland Pool & Spa |
| Olin |
| Nouryon |
| Kemira |
| Lonza |
| Others |
Pricing and Supply Chain Analysis
Saltwater chlorination equipment displacing bulk chemical procurement redraws supply geography toward electrolytic cell manufacturers in Taiwan and Germany while compressing consumables pricing power across traditional chlorine sanitizer tiers.
Pricing Analysis
Configured-to-order pricing for automated dosing systems commands 40-60% premiums over standard bulk chemical contracts. Three-tier pricing structure across premium certified, standard commercial, and economy private-label tiers tracks EPA FIFRA registration status and analytical service bundling. Pricing pressure stems from integrated chlor-alkali producers bypassing distributor markups through direct national account contracts. Boutique hotel operators under 150 rooms exhibit highest price sensitivity, whereas luxury resort chains with centralized procurement prioritize compliance documentation over unit cost.
Supply Chain Analysis
Inventory cycles for bromine tablets and specialty algaecides stretch 8-12 weeks longer than commodity chlorine due to concentrated production in Israel and Japan. Caustic soda and liquid chlorine draw from Gulf Coast chlor-alkali complexes in Texas and Louisiana, with bromine extraction anchored in Dead Sea brine operations. Single-source vulnerability concentrates in bromine supply given limited global extraction points. Distribution runs through regional chemical distributors serving independent properties, while national hospitality chains receive direct tanker delivery from integrated producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through facility management outsourcing that bundles water treatment into broader hospitality service contracts, consolidating procurement decisions into fewer corporate headquarters.
For Market Incumbents: Consolidate service attach rates by embedding IoT-enabled monitoring and certified pool operator training into chemical supply agreements. Backward integration into saltwater chlorination equipment manufacturing addresses substitution threat from mineral-based system integrators. Defensive certification investment in EPA FIFRA registration renewal timelines protects against reformulation-driven supplier displacement. For New Entrants and Emerging Players: Smart monitoring platform integration gaps in mid-tier independent hotel properties offer white-space entry points. Wellness center hydrotherapy chemistry commands formulation premiums with limited incumbent specialization. Geographic targeting of Arizona and Nevada spa-forward properties leverages thermal degradation expertise as differentiated go-to-market positioning. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional distributors facing margin compression from direct manufacturer contracting. Long-term viability hinges on service-layer differentiation rather than commodity chemical throughput. Acquisition target archetype: automated dosing system manufacturers with hospitality-specific software integration capabilities. Signal to watch: saltwater chlorination retrofit penetration rates in Sun Belt luxury resort construction pipelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Electrolytic Cell Manufacturing | Captures equipment margins as saltwater retrofits accelerate across Florida and Arizona resort portfolios. |
| Smart Monitoring Platform Deployment | IoT-enabled dosing systems from companies like Ecolab converge chemical supply with predictive maintenance revenue streams. |
| EPA FIFRA Registration Portfolio Expansion | Specialty bromine and alternative sanitizer registrations preempt reformulation mandates targeting legacy flocculant chemistries. |
| Certified Pool Operator Training Bundling | OSHA-compliant documentation services create sticky relationships beyond commodity chemical transactions. |
| Long-term Supply Agreements with National Chains | Direct chlor-alkali contracts with Orlando and Phoenix corporate procurement displace regional distributor intermediaries. |
Research Methodology
Operator-level perspectives from resort maintenance directors, regional chemical distributors, certified pool operators, and hospitality procurement managers anchored the qualitative base. Primary interviews combined with secondary validation from EPA FIFRA registration databases, state health department inspection protocols, and hospitality facility management contract disclosures. Customs data on chlor-alkali feedstock imports and SEC filings from integrated chemical producers provided supply-side triangulation. Bottom-up property counts across Sun Belt states merged with top-down chemical intensity benchmarks.
Sensitivity analysis tested demand elasticity to saltwater chlorination retrofit rates and regulatory threshold adjustments across the projection horizon. Segmentation dimensions modeled include sanitizer chemistry type, water treatment system architecture, facility certification tier, and regional climate zone. CAGRs derived from installed base evolution and chemical throughput per property. Forecast inputs incorporated EPA Office of Water discharge mandate timelines and WHO aquatic facility guideline adoption patterns.
Underlying assumptions cover stable chlor-alkali feedstock availability and continued Sun Belt hospitality construction activity, with deviation risk concentrated in per- and polyfluoroalkyl substance reformulation mandates and certified pool operator labor shortages. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
Membrane Filtration Systems Market
Water & Sludge Treatment
North America Industrial Water Treatment Market
Water & Sludge Treatment
South America Water Treatment Chemicals Market
Water & Sludge Treatment
Global Electrodeionization Market
Water & Sludge Treatment
Hazardous Waste Treatment System Market
Water & Sludge Treatment
Global Mobile Water Treatment Market
Water & Sludge Treatment
Drinking Water Adsorbents Market
Water & Sludge Treatment
Fluid Waste Disposal Systems Market
Water & Sludge Treatment
Global Valves in Water and Wastewater Market
Water & Sludge Treatment
Asia-Pacific Water Treatment Chemicals Market
Water & Sludge Treatment
Global Water Softeners Market
Water & Sludge Treatment
Wastewater Treatment Chemicals Market
Water & Sludge Treatment
Global Turbidity Meters Market
Water & Sludge Treatment
Sludge Heater Market
Water & Sludge Treatment
Global Water Clarifiers Market
Water & Sludge Treatment
US Water and Wastewater Treatment Market