
 Global Wet Waste Management Market | 2026-2036
Global Wet Waste Management Market Size, Share, and Industry Trends Forecast 2026-2036
Global Wet Waste Management Market Foresight
Modular service bundling is rebalancing how municipalities and food processors contract wet waste services, shifting from single-point collection to integrated collection-treatment-recovery packages. Veolia Environnement SA leverages its anaerobic digestion footprint across France and the United Kingdom to anchor long-term municipal concessions. Waste Management Inc. competes through vertical integration into landfill gas capture and organics processing in the United States. SUEZ SA specializes in mechanical separation technologies that extract value from mixed commercial wet waste streams.
Wet waste management encompasses the collection, transportation, treatment, and disposal of biodegradable waste with high moisture content, typically exceeding 60% water by weight, generated from food processing, agricultural residues, and municipal organic streams. The primary industrial purpose is to stabilize putrescible material, recover energy through biogas extraction, and produce soil amendments that displace synthetic fertilizers. Anaerobic digestion dominates capital deployment due to its dual revenue streams from biogas sales and digestate offtake, while composting occupies the low-cost tier for municipalities with limited energy infrastructure. Vermiculture is gaining traction in agricultural end-user segments where premium soil conditioner pricing offsets slower throughput rates.
The EPA's landfill methane regulations in the United States, the EU Green Deal's organic waste diversion targets, and India's SWM Rules under the Ministry of Environment, Forest and Climate Change collectively tighten disposal pathways and expand treatment capacity requirements. These frameworks shape demand by penalizing landfilling of organics while subsidizing biogas upgrading and compost certification. Stakeholders must monitor feedstock security agreements and digestate offtake contracts as the primary determinants of project bankability.
Market Dynamics
Anaerobic digestion technology maturation is compressing project payback periods and attracting infrastructure capital away from landfill-dependent models. Municipal procurement offices now prioritize integrated service contracts that bundle collection, treatment, and energy recovery under single concession agreements.
Growth Catalysts
- EU Green Deal landfill diversion mandates:The framework penalizes organic waste disposal while subsidizing biogas upgrading infrastructure, forcing municipalities across France, Germany, and Italy to accelerate anaerobic digestion procurement.
- Food processing sector consolidation:Large-scale slaughterhouses and dairy cooperatives in Brazil and Thailand are installing captive digestion systems to manage high-volume effluent streams and capture methane for captive thermal energy.
- Digestate certification standardization:The EU's revised Fertilizing Products Regulation creates tradable quality tiers for soil amendments, enabling premium pricing for certified outputs from municipal composting and anaerobic digestion facilities.
Market Restraints
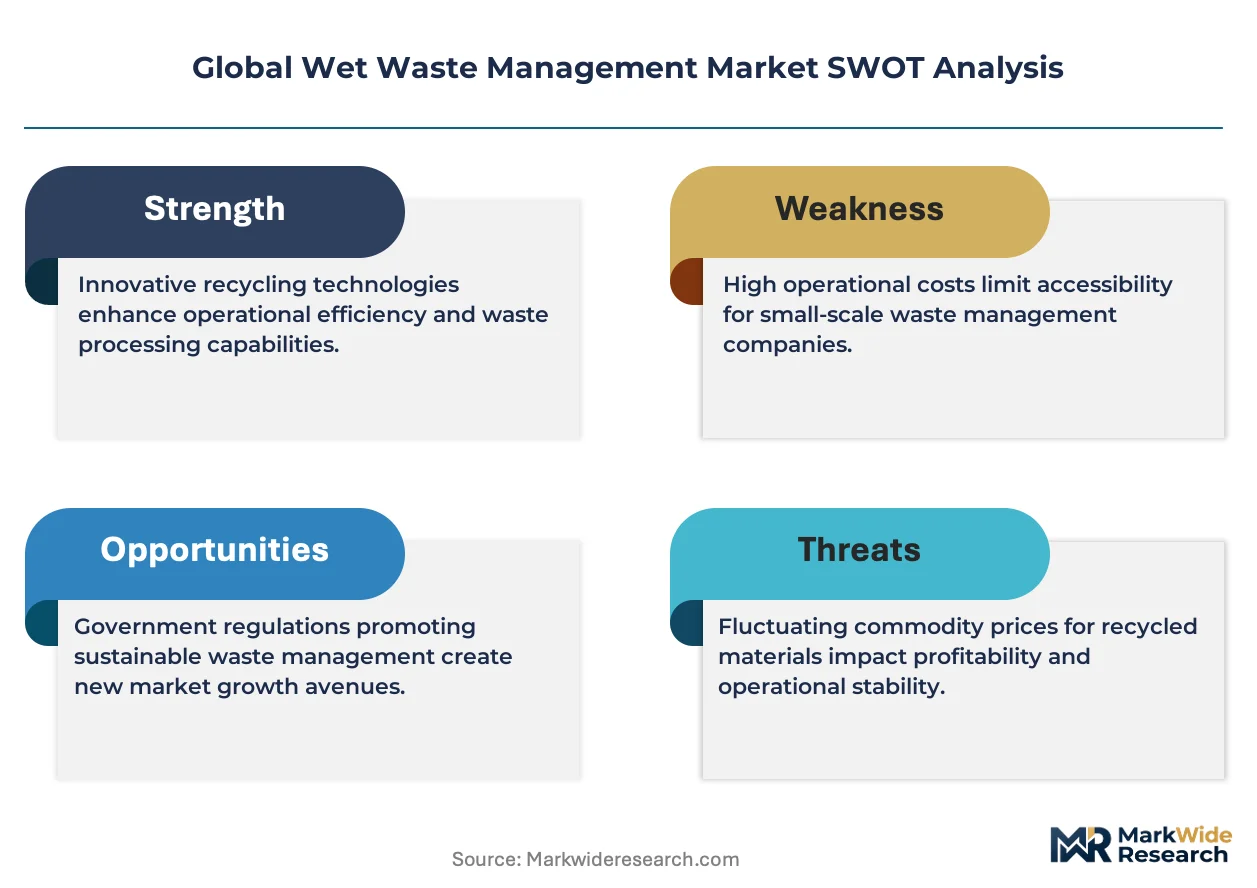
- Feedstock supply concentration risk:Single-source dependency on municipal collection contracts or agricultural cooperatives creates volume volatility that undermines project finance assumptions for independent biogas developers.
- Digestate offtake infrastructure gaps:Limited storage, transport, and distribution networks for processed organic fertilizers constrain revenue realization in regions lacking established agricultural buyer relationships.
- Natural gas price linkage:Biogas upgrading economics remain tethered to wholesale natural gas benchmarks, compressing margins when fossil fuel prices decline and renewable gas premiums narrow.
Strategic Opportunities
- India's Swachh Bharat Mission expansion:Centralized waste processing tenders in tier-2 and tier-3 cities are creating first-mover advantages for operators capable of delivering integrated collection-treatment systems at municipal scale.
- Biogas-to-hydrogen upgrading:Steam methane reforming of biogas for green hydrogen production is opening offtake contracts with industrial gas users and mobility fuel networks seeking Scope 1 emission reductions.
- Carbon credit monetization:Voluntary carbon markets and compliance mechanisms under the EU Emissions Trading System are generating incremental revenue streams for landfill gas capture and anaerobic digestion projects with verified methane destruction.
Industry Challenges
- Process engineering talent scarcity:Specialized expertise in anaerobic reactor design, biogas upgrading membrane selection, and digestate quality management remains concentrated among a limited pool of European and North American engineering consultancies.
- Legacy landfill asset stranding:Municipalities with long-term landfill concession contracts face contractual and political friction when accelerating closure timelines to shift organics toward digestion and composting infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Wet Waste Management Market |
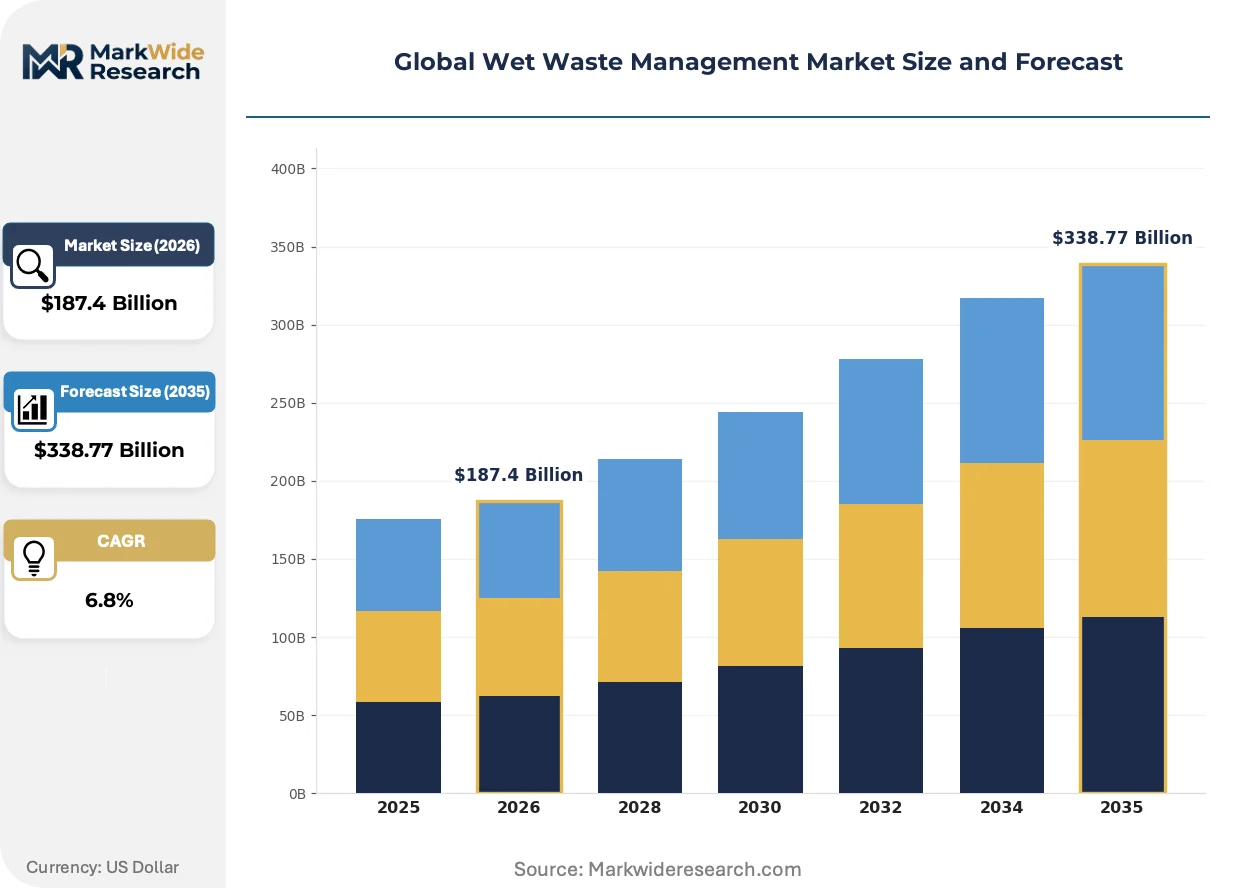
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $338.77 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Collection Method: Door-to-Door Pickup, Community Bins, Curbside Collection, Commercial Collection Processing Technology: Composting, Anaerobic Digestion, Vermiculture, Mechanical Separation End User: Food Processing Plants, Hospitality Sector, Agriculture, Municipalities Service Type: Waste Collection, Waste Treatment, Recycling, Transportation |
| Companies Covered | Veolia Environnement SA, Waste Management Inc., SUEZ SA, Republic Services Inc., Clean Harbors Inc., Remondis SE & Co. KG, Covanta Holding Corporation, Stericycle Inc., Progressive Waste Solutions Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Wet Waste Management Market Shifts & Advancements
Digital monitoring systems and advanced separation technologies are transforming operational economics across the wet waste value chain. Equipment suppliers and facility operators are embedding sensors and automation to reduce labor intensity and improve throughput consistency.
Near-infrared sorting technology is automating the separation of contaminants from organic waste streams at materials recovery facilities. Waste Management Inc. and SUEZ SA are deploying these systems at commercial and industrial receiving stations to reduce preprocessing costs and improve biogas yield. The technology is automating quality control functions that previously required manual labor, enabling higher throughput with smaller crews.
The EPA's landfill methane regulations are tightening emission monitoring and capture requirements for existing disposal sites. Facilities must install gas collection systems and flare or utilize captured methane, increasing operational costs for landfill-dependent operators. Municipalities in California, Texas, and Florida are responding by accelerating organics diversion programs and procuring anaerobic digestion capacity.
Integrated service contracting is displacing fragmented procurement models across municipal and industrial buyer segments. Single-vendor agreements covering collection, transport, preprocessing, and energy recovery are replacing discrete contracts with separate haulers and treatment operators. This consolidation is most visible in the United Kingdom and Netherlands, where Veolia Environnement SA and SUEZ SA have secured long-term concessions bundling entire value chains.
Global Wet Waste Management Market Segmentation
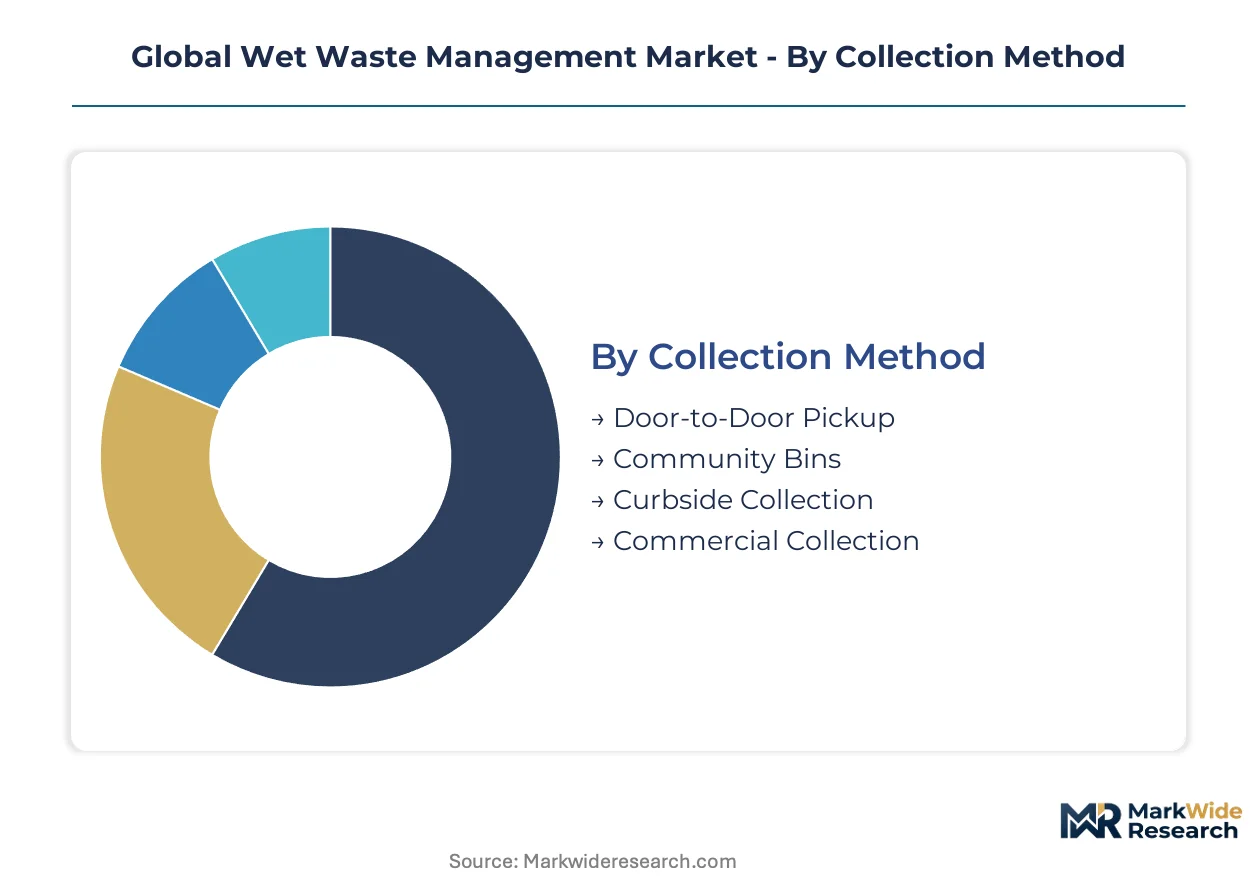
Wet waste management service providers configure their asset bases and contract structures around distinct operational segments. Collection density, processing technology selection, and end-user concentration determine capital allocation and margin profiles across the value chain.
Collection Method:
Supply concentration in collection infrastructure varies sharply by population density and regulatory enforcement intensity.
- Door-to-Door Pickup:Scheduled household collection using dedicated organic waste vehicles with sealed compartments to prevent leachate spillage. Demand clusters in Indian cities under Swachh Bharat Mission enforcement, where household segregation mandates create predictable feedstock streams for municipal digestion facilities.
- Community Bins:Centralized drop-off points in high-density residential zones with shared container systems and scheduled emptying protocols. Operators in Bangkok and Jakarta deploy these where narrow street widths restrict vehicle access, trading collection frequency for infrastructure cost reduction.
- Curbside Collection:Weekly or bi-weekly scheduled pickup from designated residential collection points using specialized trucks with compaction capability.
- Commercial Collection:Customized pickup schedules for restaurants, hotels, and food processors with variable container sizes and contamination monitoring.
Today's leader: Door-to-Door Pickup. Tomorrow's challenger: Commercial Collection.
Processing Technology:
Cost tier stratification separates mature low-capital options from energy-integrated systems requiring substantial upfront investment.
- Anaerobic Digestion:Oxygen-excluded biological decomposition producing biogas and stabilized digestate through mesophilic or thermophilic reactor operation. French and German municipalities prioritize this technology where EU Green Deal subsidies offset capital costs and natural gas grid injection creates dual revenue streams.
- Composting:Aerobic microbial decomposition of organic matter producing humus-rich soil amendments through windrow or in-vessel systems. Agricultural buyers in Brazil and Thailand favor these facilities for lower gate fees and faster permit approval timelines compared to energy recovery alternatives.
- Vermiculture:Earthworm-mediated decomposition generating premium castings for specialty crop applications.
- Mechanical Separation:Automated sorting and dewatering systems preprocessing mixed wet waste streams for downstream treatment.
Today's leader: Anaerobic Digestion. Tomorrow's challenger: Vermiculture.
End User:
Application-specific requirements drive divergent service specifications and pricing structures across buyer categories.
- Municipalities:Public sector entities managing residential organic waste streams through concession contracts or direct service provision. Procurement offices in tier-2 Indian cities bundle collection and treatment under integrated tenders that favor operators with existing digestion asset footprints.
- Food Processing Plants:Industrial facilities generating high-volume organic residues from slaughtering, dairy, and beverage operations. Brazilian beef processors install captive digestion systems to manage effluent compliance and capture methane for thermal process energy.
- Agriculture:Farm operations producing crop residues and livestock manure requiring stabilization or nutrient recovery.
- Hospitality Sector:Hotels and restaurants generating food scraps and prep waste with high contamination risk and irregular volume patterns.
Today's leader: Municipalities. Tomorrow's challenger: Food Processing Plants.
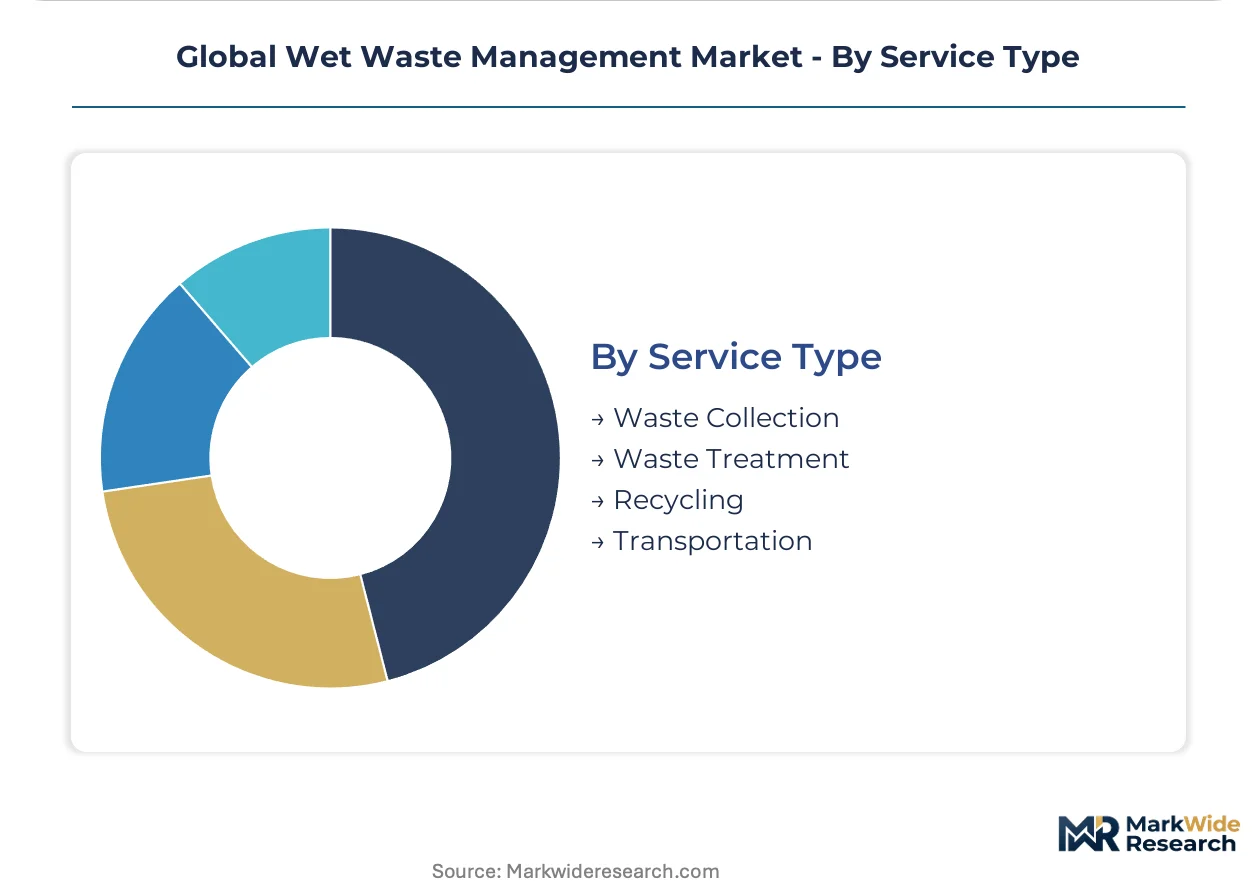
Service Type:
Customer type and contract duration preferences segment the market between discrete transactions and long-term concession arrangements.
- Waste Treatment:Processing services converting raw organic waste into stabilized outputs through biological or thermal methods. Dutch and UK operators secure 15-25 year concessions bundling treatment with energy recovery, locking in feedstock supply and digestate offtake certainty.
- Waste Collection:Scheduled pickup and transport from generation points to processing facilities using specialized fleet assets.
- Recycling:Recovery of organic matter for beneficial reuse as soil amendments, animal feed, or energy feedstock.
- Transportation:Logistical services moving processed or unprocessed materials between collection points, treatment facilities, and end markets.
Today's leader: Waste Treatment. Tomorrow's challenger: Recycling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wet waste management infrastructure first achieved industrial scale in Germany during the 1990s through the Duales System Deutschland packaging waste framework, which established the template for source-segregated collection and biological treatment now replicated across industrialized economies.
United States
California's SB 1383 mandates 75 percent organic waste diversion by 2025, compelling municipalities from Los Angeles to Sacramento to procure anaerobic digestion capacity. The EPA enforces landfill methane capture standards under the Clean Air Act, accelerating facility closures in Texas and Florida. Waste Management Inc. anchors collection infrastructure across the Sun Belt while independent developers finance digestion projects in the Northeast.
Germany
Bavarian and North Rhine-Westphalian municipalities operate Europe's densest network of agricultural co-digestion plants, processing manure alongside food waste under the Biowaste Ordinance. The EU Green Deal's landfill ban drives replacement of legacy composting with energy-integrated systems. E.ON and municipal utilities in Baden-Württemberg contract for biomethane grid injection, stabilizing revenue for facility operators.
India
The Swachh Bharat Mission 2.0 allocates centralized processing tenders for tier-2 cities including Indore, Surat, and Coimbatore, mandating door-to-door segregated collection. The Ministry of Environment's SWM Rules 2016 penalize untreated organic waste disposal, shifting procurement toward integrated operators. Maharashtra and Karnataka states lead concession awards, with Mumbai and Bengaluru municipalities bundling collection and treatment contracts.
France
Île-de-France and Auvergne-Rhône-Alpes regions enforce the Energy Transition for Green Growth Act, requiring large generators to source-separate organic waste or face landfill surcharges. Veolia Environnement SA leverages its historical concession footprint to secure 20-25 year service contracts around Paris and Lyon. The national biomethane injection tariff guarantees offtake pricing, de-risking capital deployment for independent project developers.
Brazil
São Paulo state's Environmental Company (CETESB) enforces effluent standards on slaughterhouses and dairy processors in the interior, driving captive anaerobic digestion adoption. The National Solid Waste Policy mandates organic waste diversion timelines, though enforcement concentrates in the Southeast region. JBS and Minerva Foods anchor industrial biogas demand, utilizing captured methane for thermal energy in beef processing facilities.
Global Wet Waste Management Market Competitive Landscape
The competitive structure tilts toward vertically integrated environmental service conglomerates with existing collection infrastructure and long-dated municipal concession relationships. Tier-one operators combine route density advantages with digestion asset ownership, while mid-scale specialists compete on technology differentiation or geographic focus. Two archetypes dominate: full-service concessionaires bundling collection through energy recovery, and technology-anchored players licensing preprocessing systems. Competitive moves concentrate on concession renewal timing and strategic partnerships for biogas offtake.
Within the full-service concessionaire tier, Veolia Environnement SA and Waste Management Inc. exemplify operators leveraging historical route density to anchor integrated contract structures. SUEZ SA occupies a position emphasizing mechanical separation and preprocessing technology. These three entities represent the dominant competitive anchors, with European-based limited companies and North American incorporated entities each commanding distinct regional strongholds through concession tenure and regulatory familiarity.
| Leading Market Players |
|---|
| Veolia Environnement SA |
| Waste Management Inc. |
| SUEZ SA |
| Republic Services Inc. |
| Clean Harbors Inc. |
| Remondis SE & Co. KG |
| Covanta Holding Corporation |
| Stericycle Inc. |
| Progressive Waste Solutions Ltd. |
| Others |
Supply & Pricing Matrix
Municipal procurement offices in France, Germany, and India anchor pricing power through integrated concession contracts that bundle collection, treatment, and energy recovery. Long-term offtake agreements for biogas and digestate create contract-based pricing stability, while spot-market exposure concentrates in commercial waste streams lacking municipal anchors.
Pricing Analysis
Three-tier pricing structure across premium certified digestate, standard compost output, and economy landfill diversion services dominates contract structures. Price differentiation rests on EU Fertilizing Products Regulation certification tiers and volume scale commitments from agricultural buyers. Cost compression in the standard tier is intensifying because independent developers compete for municipal feedstock security. Food processing plants demonstrate highest price sensitivity due to captive digestion alternatives, while municipalities with landfill diversion mandates show lowest sensitivity.
Supply Chain Analysis
Regional distribution centers for digestate offtake cluster around Paris, Munich, and São Paulo agricultural corridors. Equipment manufacturing concentrates in Germany, Italy, and China, with anaerobic reactor vessels and biogas upgrading membranes drawing from specialized engineering fabricators. Single-source vulnerability in membrane technology suppliers creates supply chain risk. Distribution runs through hub-and-spoke networks connecting digestion facilities to farm cooperatives via contracted haulage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Wet Waste Management Market operates as a stable compounder where regulatory landfill diversion mandates generate predictable procurement cycles across municipal and industrial buyer segments.
For Market Incumbents: Deploy concession renewal timing as the primary defensive lever. Secure early renewal of municipal contracts in France and the United Kingdom before EU Green Deal enforcement peaks. Invest in biogas upgrading certification to capture premium digestate pricing tiers and offset margin pressure from natural gas price linkage. For New Entrants and Emerging Players: Begin with tier-2 Indian cities under Swachh Bharat Mission 2.0 where integrated collection-treatment tenders remain underpenetrated. Target food processing clusters in Brazil's interior where CETESB enforcement creates captive digestion demand. Pursue technology licensing partnerships with European engineering consultancies to overcome process engineering talent scarcity. For Investors and Strategic Acquirers: Infrastructure funds with waste-to-energy mandates are the most active acquirer in this space. Target mid-scale anaerobic digestion operators with secured municipal feedstock agreements and digestate offtake contracts. Watch for inflection when India's centralized processing tender awards accelerate beyond current tier-2 city coverage.| Strategic Initiative | Industry Significance |
|---|---|
| Biogas Upgrading Certification | EU Fertilizing Products Regulation compliance unlocks premium digestate pricing tiers for agricultural buyers. |
| Integrated Service Concession | Veolia and SUEZ secure 20-25 year municipal contracts bundling collection through energy recovery in France. |
| Feedstock Security Agreement | Long-term municipal contracts de-risk capital deployment for independent biogas developers in Germany and India. |
| Digestate Distribution Partnership | Agricultural cooperative alliances close infrastructure gaps constraining revenue realization in Brazil and Southeast Asia. |
| Carbon Credit Monetization | EU Emissions Trading System compliance mechanisms generate incremental revenue streams for verified methane destruction projects. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary discussions engaged municipal procurement officers, anaerobic digestion plant operators, agricultural buyers, biogas upgrading equipment suppliers, and regulatory compliance consultants. Secondary validation drew from EPA enforcement databases, EU Green Deal implementation reports, Indian SWM Rules compliance filings, and FAO agricultural residue statistics. Bottom-up project pipeline analysis and top-down regulatory mandate sizing were triangulated against operator revenue disclosures.
Segment-weighting approaches modeled capacity deployment across processing technology tiers, collection method density, and end-user concentration. The analytical framework projected biogas yield coefficients, digestate offtake pricing trajectories, and concession contract renewal patterns across the projection horizon. CAGRs were derived from facility commissioning timelines and regulatory deadline enforcement schedules. Feedstock availability indices and natural gas benchmark correlations served as industry-specific forecast inputs.
Caveats apply where feedstock supply disruptions, digestate offtake infrastructure delays, or fossil fuel price volatility could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
Saudi Arabia Industrial Hazardous Waste Management Market
Water & Sludge Treatment
Asia-Pacific Membrane Water and Wastewater Treatment (WWT) Market
Water & Sludge Treatment
Asia-Pacific Water Treatment Chemicals Market
Water & Sludge Treatment
US Water and Wastewater Treatment Chemicals Market
Water & Sludge Treatment
Process Chemicals for Water Treatment Market
Water & Sludge Treatment
Low-Dosage Hydrate Inhibitors (Ldhis) Market
Water & Sludge Treatment
Middle-East and Africa Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
Nanotechnology in Water Treatment Market
Water & Sludge Treatment
Liquid Waste Container Market
Water & Sludge Treatment
Australia & New Zealand Water Treatment Chemicals Market
Water & Sludge Treatment
Ultrapure Water Market
Water & Sludge Treatment
Asia-Pacific Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
Hazardous Waste Treatment System Market
Water & Sludge Treatment
Asia-Pacific Water Free/ Waterless Urinals Market
Water & Sludge Treatment
Water Gel Market
Water & Sludge Treatment
India Water Treatment Chemicals Market