
 Fluid Waste Disposal Systems Market | 2026-2036
Fluid Waste Disposal Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Fluid Waste Disposal Systems Market Foresight
Closed-loop vacuum collection and automated segregation is rewriting how healthcare and industrial facilities handle infectious, chemical, and hydrocarbon-laden fluids. Clean Harbors, Inc. leverages its North American hazardous waste infrastructure to capture high-margin thermal treatment contracts. SUEZ anchors European municipal sludge processing through membrane-based dewatering installations. Veolia dominates integrated water-waste-energy service bundles across multiple geographies.
Fluid waste disposal systems encompass engineered equipment and processes for collecting, treating, and permanently removing liquid effluents containing biological, chemical, or radioactive contaminants, typically operating at flow rates from 10 to 10,000 liters per hour with sterilization thresholds reaching 6-log reduction. These systems serve to prevent environmental discharge violations and protect occupational health in settings generating pathogenic or toxic liquid streams. Membrane filtration leads system type demand where water recovery for reuse is mandated, while thermal treatment commands premium pricing for pharmaceutical and laboratory waste streams with high heat-content or prion contamination risk. Biological digestion is accelerating fastest among food processing units seeking to convert organic-laden wastewater into biogas feedstock.
The US EPA enforces effluent limitations under the Clean Water Act, compelling petrochemical and textile facilities to upgrade clarifier and separator technologies, while the EU Industrial Emissions Directive and REACH framework restrict hazardous substance release into wastewater streams. FDA cGMP guidelines for pharmaceutical manufacturing additionally specify validated fluid waste containment protocols. Stakeholders must monitor evolving PFAS destruction mandates, as emerging thermal and plasma-based treatment standards promise to reshape capital allocation across disposal method categories.
Market Dynamics
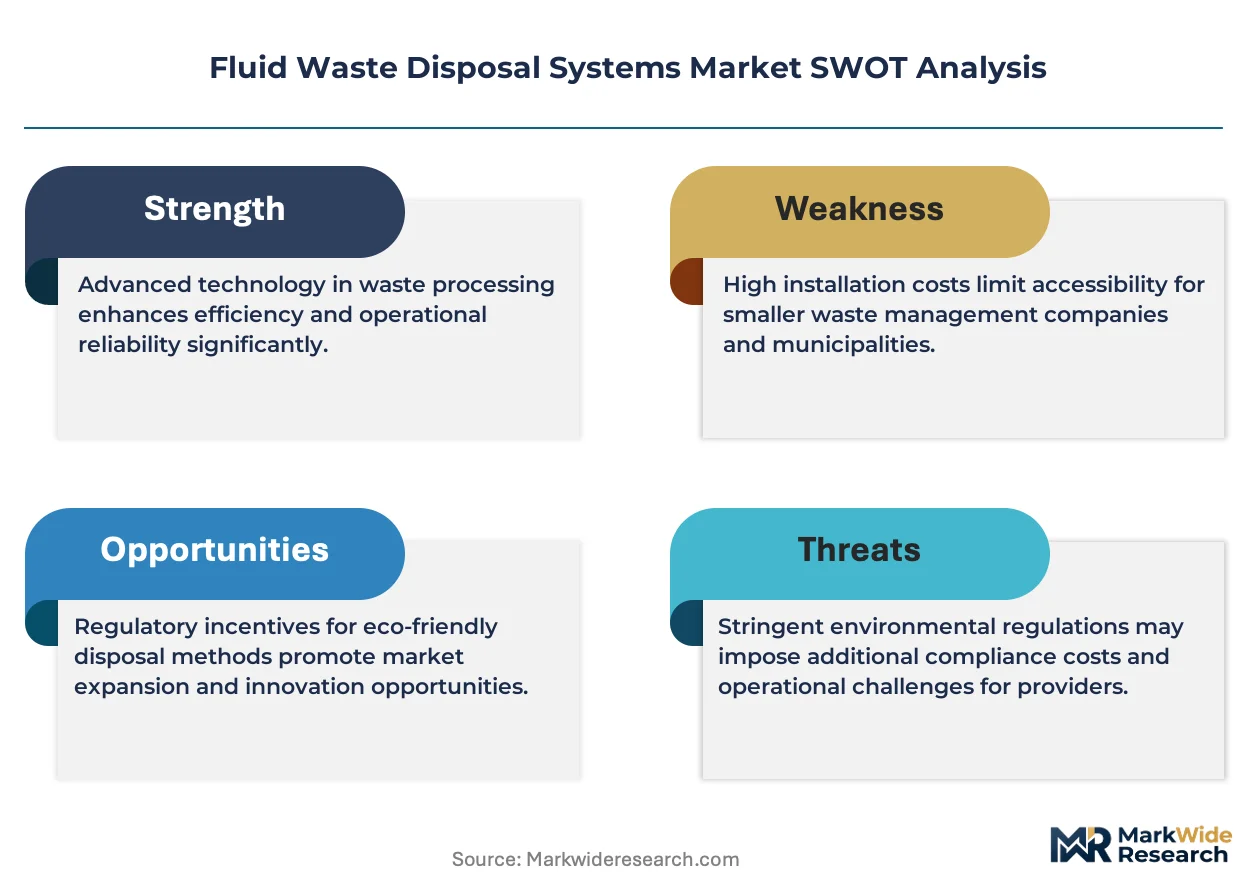
Closed-loop vacuum collection platforms are forcing wholesale replacement of open-bucket fluid handling in hospitals, while EPA effluent guidelines and EU Industrial Emissions Directive upgrades are mandating capital-intensive treatment infrastructure across petrochemical and pharmaceutical manufacturing.
Growth Catalysts
- US EPA Effluent Limitations Guidelines:Petrochemical and textile facilities must upgrade clarifier and separator technologies, creating immediate equipment replacement cycles.
- Membrane filtration systems:Water recovery mandates in water-stressed manufacturing regions are accelerating adoption of reverse osmosis and ultrafiltration skids for process wastewater.
- Germany's hazardous liquid processing density:REMONDIS and Veolia operate dense collection networks that normalize high-service-frequency contracts for industrial generators.
Market Restraints
- Stainless steel and specialty alloy input costs:Corrosion-resistant vessel fabrication depends on nickel and molybdenum prices that swing with mining supply disruptions.
- Plasma arc thermal treatment capex concentration:PFAS destruction systems require $15-50 million installations concentrated among three North American technology licensors.
- REACH authorization timelines:ECHA's substance-by-substance review creates 18-36 month certification delays for chemical waste treatment additives.
Strategic Opportunities
- India's pharmaceutical manufacturing expansion:CDSCO cGMP enforcement is creating first-time demand for validated fluid waste containment in active ingredient production.
- Biogas feedstock conversion:Anaerobic digestion of food processing wastewater pairs membrane concentration with biogas upgrading for circular energy models.
- Outcome-based service bundling:Integrated water-waste-energy contracts displace equipment-only sales in municipal and industrial accounts seeking transfer of operational risk.
Industry Challenges
- ASME pressure vessel certification timelines:State-by-state boiler and pressure vessel inspector backlogs delay commercial startup of thermal treatment units by 4-8 months.
- Legacy sewer connection permitting:Municipal pretreatment coordinators lack bandwidth to process industrial discharge permit modifications at the pace of equipment deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fluid Waste Disposal Systems Market |
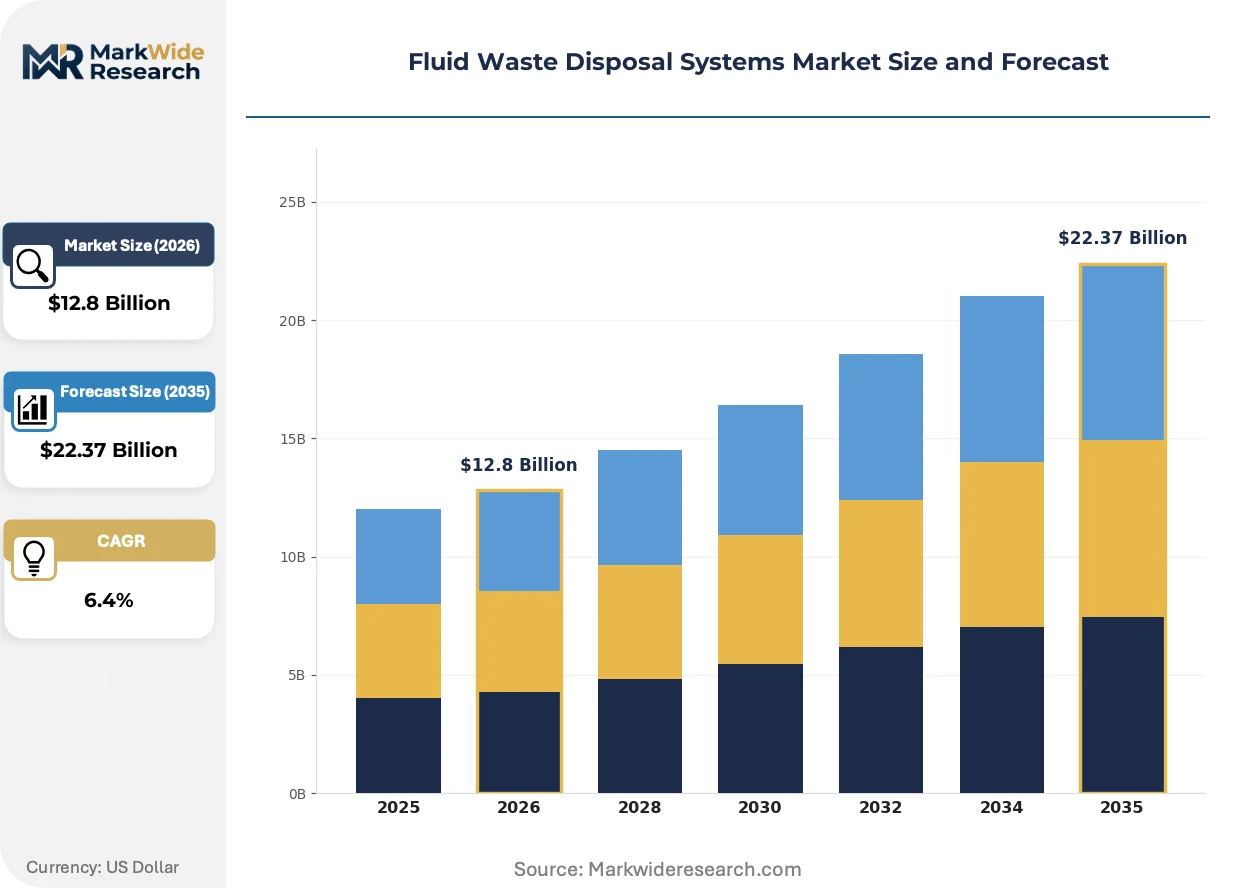
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.37 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
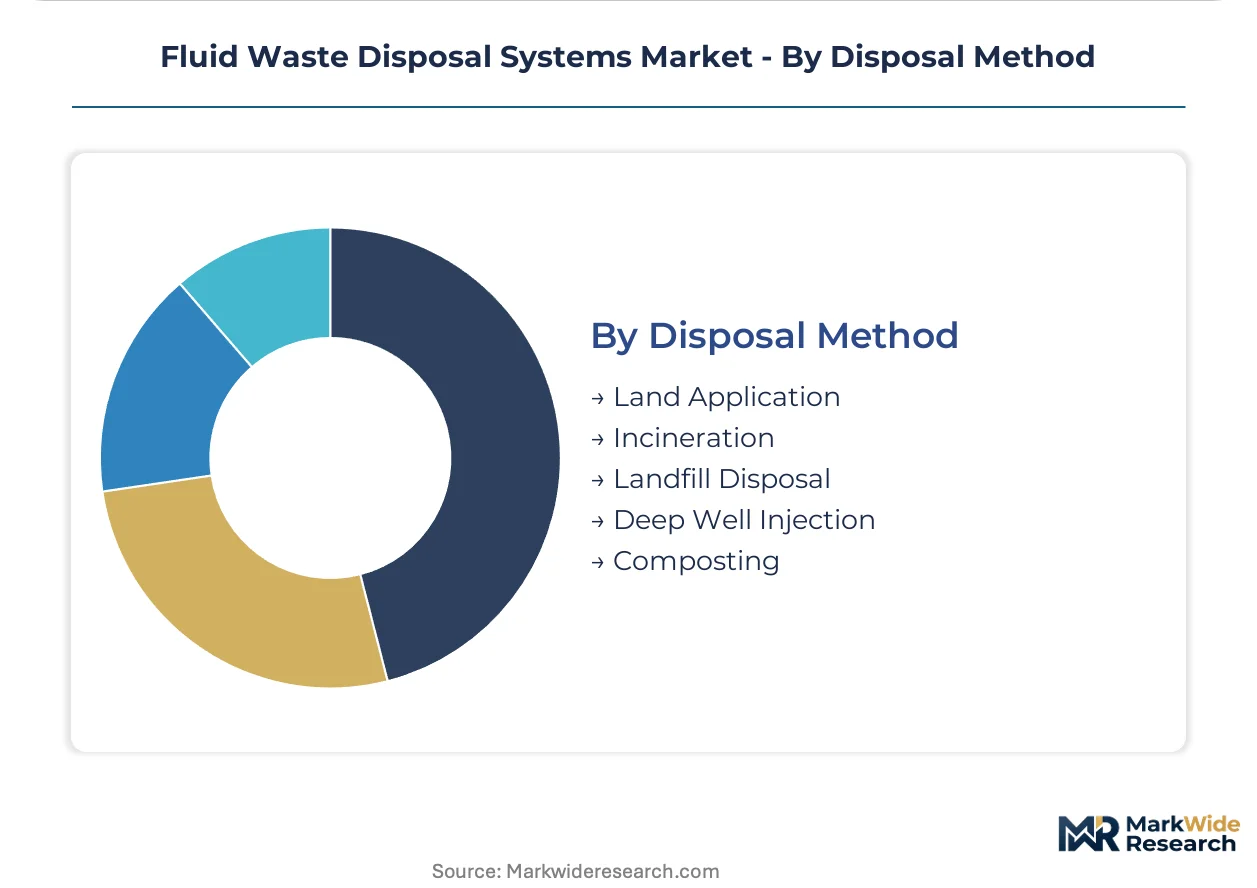
| Segmentation | System Type: Septic Tanks, Grease Traps, Oil-Water Separators, Industrial Clarifiers, Sludge Dewatering Units Technology: Membrane Filtration, Thermal Treatment, Chemical Precipitation, Biological Digestion, Adsorption Filtration End User: Municipal Authorities, Food Processing Units, Petrochemical Plants, Textile Manufacturers, Waste Management Companies Disposal Method: Land Application, Incineration, Landfill Disposal, Deep Well Injection, Composting |
| Companies Covered | Veolia, Clean Harbors, Inc., Waste Management, Inc., Republic Services, Inc., SUEZ, GFL Environmental Inc., REMONDIS SE & Co. KG, Covanta Holding Corp., H heritage Crystal Clean Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fluid Waste Disposal Systems Market Shifts & Advancements
Automation of fluid segregation and advances in destructive treatment chemistry are compressing the viable lifecycle of conventional open-collection methods across healthcare and heavy industry.
Plasma arc gasification for PFAS-laden aqueous film-forming foam is rendering obsolete legacy incineration and deep-well injection for fluorinated compound destruction. Defense and aviation sector buyers are specifying 99.99% destruction removal efficiency in new procurement. The technology is compressing addressable market share for thermal oxidizers lacking fluorine scrubbing capability.
The EU Industrial Emissions Directive's 2024 best available technique reference document revision tightens wastewater discharge limits for priority substances. Pharmaceutical manufacturers must retrofit biological treatment trains with powdered activated carbon polishing. German and Dutch facilities face the steepest compliance deadlines, driving membrane bioreactor upgrade contracts through 2027.
Hospital purchasing consortiums are consolidating fluid waste management under single-source service agreements that bundle equipment, consumables, and regulatory documentation. Group purchasing organizations negotiate three-to-five-year contracts that lock out point-of-sale equipment vendors. This concentration is most visible in US health systems exceeding 500 licensed beds, where standardization across facility networks overrides site-specific engineering preferences.
Fluid Waste Disposal Systems Market Segmentation
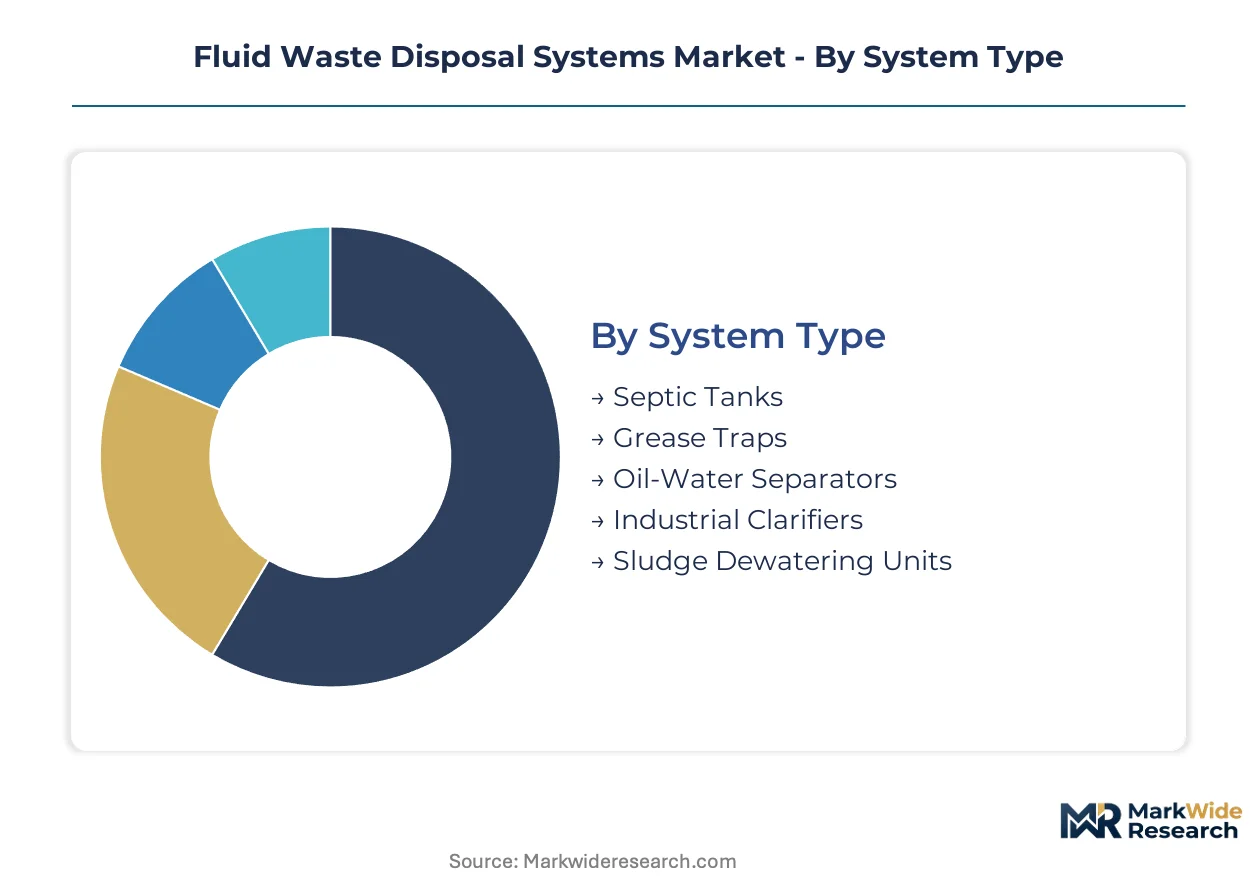
Equipment replacement cycles and regulatory compliance deadlines vary dramatically across fluid waste system categories. Understanding these temporal patterns reveals where capital deployment concentrates and which technologies face imminent obsolescence.
System Type:
Replacement cycles range from annual grease trap pumping to 25-year septic tank lifespans, creating divergent revenue recognition patterns across equipment categories.
- Septic Tanks:Underground concrete or fiberglass vessels with 1,000-5,000 gallon capacity serve rural and peri-urban properties lacking sewer connections. Municipalities in Germany and France subsidize decentralized wastewater infrastructure, sustaining steady replacement demand as aging concrete structures crack.
- Grease Traps:Steel or plastic interceptors with 20-50 gallon capacity capture fats, oils, and grease from commercial kitchen drains. US municipal pretreatment programs mandate quarterly pumping for restaurants, generating recurring service revenue concentrated in metropolitan clusters.
- Oil-Water Separators:Coalescing plate or centrifugal systems remove hydrocarbons from industrial runoff. EPA stormwater permits drive retrofit demand at automotive and machining facilities.
- Industrial Clarifiers:Circular or rectangular settling basins with 10-100 meter diameter separate suspended solids from process streams. Textile manufacturers in India upgrade clarifier trains to meet Zero Liquid Discharge mandates.
- Sludge Dewatering Units:Belt filter presses and centrifuges reduce biosolids volume by 80-95% prior to disposal. Membrane-based dewatering commands premium pricing where landfill tipping fees exceed $150 per ton.
Septic tanks dominate installed base across rural geographies. Sludge dewatering units are where expansion concentrates as landfill restrictions tighten.
Technology:
Capital intensity spans three orders of magnitude, from simple chemical dosing skids to $50 million plasma arc installations.
- Membrane Filtration:Reverse osmosis and ultrafiltration modules achieve 90-99% contaminant rejection for water reuse applications. Singapore's NEWater program and California's Title 22 regulations sustain demand for high-recovery membrane trains in municipal and industrial settings.
- Thermal Treatment:Rotary kilns, fluidized bed incinerators, and pyrolysis units destroy organic contaminants through 850-1,200°C oxidation. Pharmaceutical manufacturers in Switzerland and Germany specify thermal treatment for cytotoxic waste streams where biological methods fail.
- Chemical Precipitation:pH adjustment and coagulant dosing precipitate heavy metals as hydroxide or sulfide sludge. Electroplating facilities in China's Pearl River Delta deploy automated precipitation systems to meet MEE discharge standards.
- Biological Digestion:Anaerobic digesters and aerobic activated sludge processes convert organic load to biogas or biomass. Food processors in the Netherlands pair digestion with biogas upgrading to inject renewable natural gas into distribution networks.
- Adsorption Filtration:Activated carbon or ion exchange resins capture trace contaminants polishing effluent prior to discharge. PFAS remediation projects in Michigan and North Carolina specify granular activated carbon for groundwater treatment.
Membrane filtration leads capital deployment in water-stressed manufacturing regions. Biological digestion is climbing the fastest as carbon accounting values biogas capture.
End User:
Contract structures diverge sharply: municipal authorities favor 10-20 year design-build-operate agreements while industrial generators prefer 3-5 year equipment leases with service bundling.
- Municipal Authorities:Cities and wastewater utilities operate centralized treatment plants serving 10,000 to 10 million population equivalents. Australia's urban utilities consolidate biosolids processing through regional hubs, displacing small-scale anaerobic digesters.
- Food Processing Units:Meatpacking, dairy, and beverage plants generate high-BOD wastewater requiring pretreatment prior to sewer discharge. Brazil's JBS and BRF facilities deploy dissolved air flotation and anaerobic digestion to manage slaughterhouse effluent volumes.
- Petrochemical Plants:Refineries and chemical complexes produce process wastewater containing benzene, phenols, and sulfides. Saudi Aramco's Jubail complex operates one of the world's largest industrial wastewater reclamation facilities using membrane bioreactors.
- Textile Manufacturers:Dyeing and finishing operations discharge colored effluent with high salt and heavy metal content. Bangladesh's leather tanneries cluster around centralized effluent treatment plants in Hazaribagh and Savar.
- Waste Management Companies:Specialized contractors collect, transport, and treat hazardous liquid wastes from dispersed generators. Veolia's German network operates mobile treatment units for on-site processing of chemical industry waste streams.
Municipal authorities anchor long-term service revenue through concession contracts. Waste management companies are gaining share fastest through vertical integration of collection and treatment assets.
Disposal Method:
Regulatory tailwinds and liability exposure are reordering the hierarchy of permanent disposal routes, with thermal destruction gaining ground against land-based options.
- Land Application:Treated biosolids spread as agricultural fertilizer recycle nitrogen and phosphorus. Wisconsin and Minnesota restrict PFAS-laden sludge spreading on farmland, diverting volumes to incineration.
- Incineration:Multiple-hearth and fluidized bed furnaces achieve 99.9% volume reduction with energy recovery. Japan's sludge incineration rate exceeds 70% as landfill scarcity forces thermal disposal.
- Landfill Disposal:Monofills and hazardous waste cells receive dewatered sludge and solidified liquids. EU Waste Framework Directive hierarchy subordinates landfill to recovery and recycling, shrinking addressable volume.
- Deep Well Injection:Class I wells dispose treated effluent into confined saline aquifers 1,000-4,000 meters below surface. Texas and Louisiana host the majority of US injection capacity for oilfield and petrochemical waste.
- Composting:Aerobic decomposition of organic-laden waste produces soil amendments. California's SB 1383 organic waste mandates expand composting infrastructure for food processing residuals.
Landfill disposal retains the largest installed capacity base. Incineration is where capacity expansion concentrates as circular carbon policies valorize energy recovery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement consortiums and petrochemical facility clusters concentrate demand in specific national markets where regulatory enforcement and infrastructure investment align. The United States, Germany, China, India, and Japan each present distinct buyer archetypes and compliance frameworks.
United States
Defense aviation facilities and municipal utilities drive PFAS destruction demand. EPA effluent limitation guidelines compel textile and petrochemical plants to upgrade clarifier infrastructure. Michigan and North Carolina host concentrated groundwater remediation clusters requiring granular activated carbon and thermal treatment systems.
Germany
REMONDIS and Veolia operate dense hazardous liquid processing networks that normalize high-service-frequency contracts. The EU Industrial Emissions Directive's 2024 best available technique revision tightens pharmaceutical wastewater discharge limits. Facilities in North Rhine-Westphalia and Bavaria face steep compliance deadlines through 2027.
China
Electroplating facilities in the Pearl River Delta deploy automated chemical precipitation systems. MEE discharge standards enforce heavy metal removal from industrial effluent. The Yangtze River Delta concentrates membrane bioreactor installations for textile dyeing and finishing operations.
India
Pharmaceutical active ingredient manufacturers generate first-time demand for validated fluid waste containment. CDSCO cGMP enforcement creates compliance-driven equipment procurement. Textile clusters in Gujarat and Tamil Nadu upgrade clarifier trains to meet Zero Liquid Discharge mandates.
Japan
Sludge incineration exceeds 70 percent as landfill scarcity forces thermal disposal adoption. METI circular economy policies valorize energy recovery from biosolids processing. The Kanto and Kansai regions concentrate multiple-hearth furnace capacity for municipal wastewater treatment.
Fluid Waste Disposal Systems Market Competitive Landscape
Channel-controlling players compete with product-specialist players across equipment-only and integrated service contract segments. The market structure tiers between multinational environmental service conglomerates and regional fabrication specialists. Three archetypes dominate: full-service environmental contractors bundling water-waste-energy offerings, hazardous waste specialists capturing high-margin thermal treatment contracts, and municipal equipment fabricators supplying standardized clarifier and dewatering units. Competitive moves concentrate on geographic expansion through mobile treatment assets and outcome-based service bundling displacing capital equipment sales.
Within the full-service contractor tier, Veolia and SUEZ exemplify integrated platform operators spanning collection networks through permanent disposal infrastructure. Clean Harbors, Inc. occupies a position among North American hazardous waste specialists leveraging thermal treatment scale. These three entities anchor distinct competitive vectors—European municipal concession contracts, industrial hazardous waste destruction, and North American environmental services consolidation—without overlapping core market positioning.
| Leading Market Players |
|---|
| Veolia |
| Clean Harbors, Inc. |
| Waste Management, Inc. |
| Republic Services, Inc. |
| SUEZ |
| GFL Environmental Inc. |
| REMONDIS SE & Co. KG |
| Covanta Holding Corp. |
| Heritage Crystal Clean Inc. |
| Others |
Supply & Pricing Matrix
The Rhine-Main corridor freight networks impose diesel surcharges that cascade through stainless steel vessel fabrication, concentrating pricing power with German and Dutch fabricators while forcing North American buyers into premium expedited delivery tiers.
Pricing Analysis
Cost-plus contracts indexed to nickel and molybdenum LME benchmarks dominate thermal treatment equipment procurement. Three-tier pricing structure across premium, standard, and economy levels separates ASME-certified units from CE-marked European alternatives and non-certified Asian fabrication. Cost compression in standard-grade membrane skids is intensifying because Chinese manufacturers are flooding water-stressed markets with reverse osmosis trains. Municipal authorities exhibit highest price sensitivity due to bond financing constraints, while pharmaceutical manufacturers show least sensitivity given cGMP validation requirements.
Supply Chain Analysis
Extended payment terms from 60 to 120 days characterize supplier financing arrangements for specialty alloy procurement. Supply concentrates in Germany, China, and South Korea for corrosion-resistant vessel fabrication. Raw material flows draw from Indonesian nickel smelters, Chilean molybdenum mines, and Japanese specialty steel mills. Single-source vulnerability persists for plasma arc torch assemblies licensed through three North American technology holders. Distribution runs through regional environmental service contractors who bundle installation with regulatory compliance documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment creates asymmetric returns: permitting backlogs and certification timelines lock out fast followers once incumbents secure operating authority.
For Market Incumbents: Insulate thermal treatment margins by securing captive supply of specialty alloys through backward integration into European steel distribution networks. Expand mobile treatment fleets into India's pharmaceutical corridors before CDSCO enforcement hardens compliance requirements. Plasma arc PFAS destruction technology represents the critical substitution threat requiring R&D lock-in with defense aviation procurement channels. For New Entrants and Emerging Players: Mid-market food processing units in Southeast Asia represent the most penetrable entry point, as anaerobic digestion retrofits lag behind European adoption curves. Brazil's JBS and BRF facility clusters offer concentrated demand for dissolved air flotation and biogas upgrading packages. A equipment-as-a-service model with bundled regulatory documentation displaces capital-shy processors locked out of traditional equipment financing. For Investors and Strategic Acquirers: Regional membrane fabrication specialists with proprietary hollow-fiber spinning technology command scarcity premia as water reuse mandates proliferate. Long-term viability hinges on exposure to regulatory enforcement intensity rather than commodity cycle timing. The signal to watch is EPA effluent guideline revision pacing, which determines replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| PFAS Destruction Technology Licensing | Defense aviation facilities in Michigan and North Carolina mandate 99.99% destruction removal efficiency specifications. |
| Mobile Treatment Fleet Expansion | Veolia's German network demonstrates high-service-frequency contract capture through on-site processing capabilities. |
| Membrane Bioreactor Retrofit Contracts | EU Industrial Emissions Directive deadlines in North Rhine-Westphalia drive pharmaceutical wastewater upgrade demand. |
| Anaerobic Digestion Biogas Upgrading | Netherlands food processors inject renewable natural gas into distribution networks through membrane concentration pairing. |
| Outcome-Based Service Bundling | Integrated water-waste-energy contracts transfer operational risk from municipal authorities to environmental service operators. |
Research Methodology
Desk research of EPA effluent limitation guidelines, EU Industrial Emissions Directive amendments, and ASME boiler and pressure vessel codes preceded structured interviews with hospital procurement managers, petrochemical environmental compliance officers, membrane system design engineers, and hazardous waste logistics coordinators. Secondary validation drew from customs trade data for specialty alloy imports, SEC 10-K filings of publicly traded environmental service providers, and state-level pretreatment program enforcement records. Bottom-up equipment installation tracking triangulated against top-down regulatory mandate sizing.
Assumptions held fixed include current EPA and EU regulatory enforcement trajectories, while nickel and molybdenum price volatility and PFAS destruction technology cost curves were varied across sensitivity scenarios. Segmentation modeling spanned system type, treatment technology, end-user industry vertical, and disposal method route. CAGRs were derived from replacement cycle timing analysis overlaid with compliance deadline clustering. Industry-specific inputs incorporated membrane flux degradation rates and thermal treatment throughput capacity utilization benchmarks.
Macroeconomic conditions sit as an overlay; deviation in industrial capital expenditure cycles or municipal bond financing costs would shift the trajectory of equipment procurement timing. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and technology substitution pacing. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
North America Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
Water Gel Market
Water & Sludge Treatment
Pool and Spa Water Treatment Chemicals for Hotels and Clubs Market
Water & Sludge Treatment
India Cooling Water Treatment Chemicals Market
Water & Sludge Treatment
Sludge Treatment and Disposal Equipment Market
Water & Sludge Treatment
US Water and Wastewater Treatment Chemicals Market
Water & Sludge Treatment
Oil and Gas Water Treatment Chemicals Market
Water & Sludge Treatment
Global Flocculant and Coagulant Market
Water & Sludge Treatment
Feedwater Treatment Chemicals Market
Water & Sludge Treatment
Membrane Filtration Systems Market
Water & Sludge Treatment
Liquid Waste Container Market
Water & Sludge Treatment
Hypochlorous Acid Water Generator Market
Water & Sludge Treatment
US Water and Wastewater Treatment Market
Water & Sludge Treatment
Global Industrial Sludge Treatment Chemicals Market
Water & Sludge Treatment
Global Water Treatment Technology Market