
 North America Water Treatment Chemicals Market | 2026-2036
North America Water Treatment Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
North America Water Treatment Chemicals Market Analytics
The capability gap between integrated formulation houses and regional distributors is rotating toward on-site technical service density rather than raw material access alone. Ecolab leverages its captive field engineering network to sustain premium positioning across power and refining accounts. Kemira anchors Nordic pulp-and-paper technology into North American bleached board mills. Solenis competes through specialized deposit control chemistry for membrane-intensive desalination plants.
Water treatment chemicals encompass engineered formulations including polyaluminum chloride coagulants, quaternary ammonium disinfectants, and acrylic-based flocculants designed to remove suspended solids, control microbial growth, or adjust corrosivity in engineered water systems. These products function through charge neutralization, oxidation, or film-forming mechanisms to protect infrastructure and meet effluent quality thresholds. Coagulants and flocculants dominate value pools in mining and oil sands tailings, where solids-liquid separation intensity drives volume. Disinfectant demand accelerates fastest in recycled drinking water schemes, as California and Texas utilities advance direct potable reuse pilots. Cooling water treatment remains structurally mature, with margin compression from commodity phosphonate competition.
EPA effluent limitation guidelines under the Clean Water Act, Health Canada's PMRA re-evaluation of quaternary ammonium compounds, and NSF/ANSI Standard 60 certification requirements collectively shape product registration costs and reformulation timelines. The EPA's forthcoming PFAS discharge rules will force municipal and industrial end users to audit chemical supply chains for fluorinated precursors. Stakeholders must monitor state-level precursor notification laws, as Minnesota and Maine advance broader PFAS restrictions ahead of federal rulemaking.
Market Dynamics
Membrane-compatible polymer chemistry is supplanting legacy aluminum sulfate across high-purity process water loops, forcing municipal utilities and industrial operators to rebuild chemical dosing infrastructure around charge-neutralization efficiency rather than commodity cost alone.
Growth Catalysts
- EPA Effluent Limitation Guidelines:Municipal utilities across the United States are expanding chemical dosing capacity to meet stricter discharge standards under the Clean Water Act, accelerating coagulant and flocculant procurement cycles.
- Petrochemical Corridor Cooling Tower Regulations:Tightening blowdown rules along the US Gulf Coast are driving demand for advanced corrosion inhibitors and biocides in concentrated cooling water systems.
- Direct Potable Reuse Pilots:California and Texas utilities are advancing recycled drinking water schemes that require enhanced disinfection protocols, boosting quaternary ammonium compound consumption.
Market Restraints
- Alumina Feedstock Volatility:Polyaluminum chloride production depends on bauxite-derived alumina hydrate, exposing North American formulators to price swings tied to smelter output and Chinese export quotas.
- PFAS Supply Chain Auditing Burden:The EPA's forthcoming PFAS discharge rules will force end users to trace fluorinated precursors through chemical supply chains, extending procurement timelines and compliance costs.
- Phosphonate Commoditization:Cooling water treatment faces margin compression as commodity phosphonate producers flood the market with undifferentiated scale inhibitors.
Strategic Opportunities
- Oil Sands Tailings Chemistry:Canadian mining operations present underpenetrated demand for high-molecular-weight flocculants capable of accelerating solids-liquid separation in bitumen extraction tailings ponds.
- On-Site Technical Service Density:Integrated formulation houses can capture premium positioning by embedding field engineering networks directly at power and refining accounts, displacing regional distributors.
- Health Canada PMRA Re-Evaluation:Anticipated regulatory clarity on quaternary ammonium compound safety profiles will create first-mover advantage for suppliers with pre-validated alternative biocide platforms.
Industry Challenges
- NSF/ANSI Standard 60 Certification Timelines:Product registration costs and reformulation cycles extend commercialization timelines for novel coagulants seeking drinking water approval.
- Membrane-Compatibility Testing Capacity:Shortages of pilot-scale membrane test facilities delay validation of new polymer chemistries for desalination and high-purity process applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Water Treatment Chemicals Market |
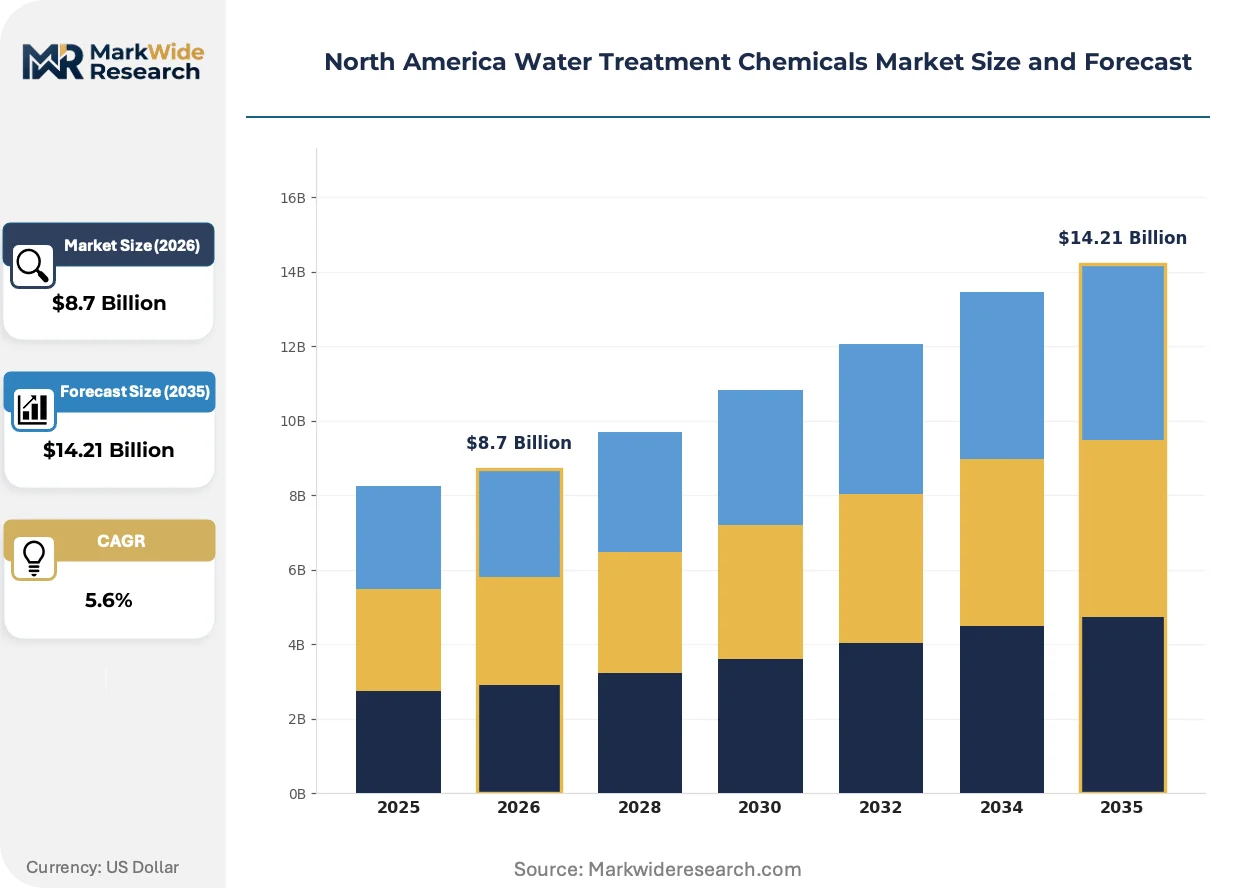
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coagulants, Disinfectants, pH Adjusters, Flocculants End User: Municipal, Industrial, Residential, Commercial Application: Wastewater Treatment, Drinking Water Treatment, Cooling Water Treatment, Process Water Treatment Form: Liquid, Powder, Granular, Tablet |
| Companies Covered | Ecolab, Kemira, SUEZ, Solenis, Kurita Water Industries Ltd., BASF SE, Dow, Veolia, ChemTreat Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Water Treatment Chemicals Market Evolving Landscape
Formulation chemistry is pivoting from commodity mineral salts to engineered polymers, while regulatory pressure on persistent contaminants forces simultaneous innovation in molecular design and supply chain transparency.
Acrylic-based flocculants with tailored charge density profiles are supplanting conventional polyacrylamide in membrane-intensive desalination plants. Saudi Arabia's SWCC and California's Poseidon Carlsbad facility have adopted these polymers for reduced fouling rates. The shift is compressing demand for legacy aluminum sulfate in high-purity loops while elevating technical service requirements.
Health Canada's PMRA re-evaluation of quaternary ammonium compounds is tightening biocide registration pathways across Canadian municipal and industrial markets. Formulators face accelerated reformulation timelines to secure renewed approvals. The bleached board mill segment is responding fastest, with Nordic-anchored suppliers advancing peracetic acid and chlorine dioxide alternatives.
Power utilities are unbundling chemical supply from bundled service contracts, forcing distributors to compete on transparent unit pricing rather than captive engineering relationships. Texas ERCOT-grid operators and Ontario nuclear facilities now run competitive chemical tenders separate from maintenance agreements. The disintermediation is most visible in cooling water treatment, where procurement teams centralize specification authority previously held by plant engineers.
North America Water Treatment Chemicals Market Segmentation
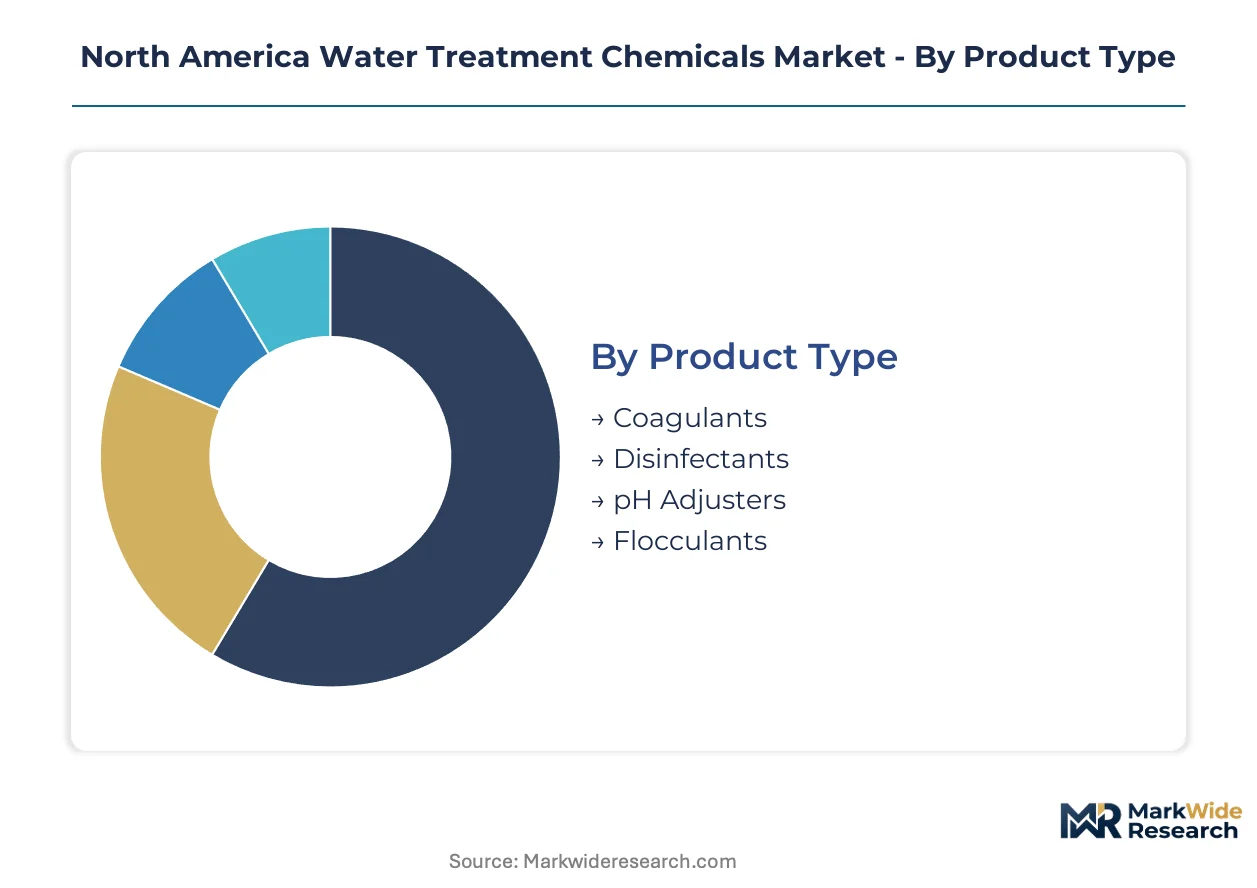
Water treatment chemical procurement channels vary sharply by segment. Municipal utilities run centralized tenders through engineering consultants, while industrial operators source through integrated service contracts. Form, concentration, and regulatory certification tier pricing and distribution access across every category.
Product Type:
Coagulants and flocculants move through bulk tanker and tote distribution to municipal utilities and mining operators. Disinfectants and pH adjusters fragment across specialized chemical distributors serving smaller-volume commercial and residential accounts.
- Coagulants:Polyaluminum chloride and ferric sulfate formulations neutralize suspended particle charge in raw water intakes. Demand concentrates in US Gulf Coast petrochemical complexes facing tighter EPA effluent guidelines for total suspended solids discharge.
- Flocculants:High-molecular-weight polyacrylamide and acrylic-based polymers bridge neutralized particles into settleable masses. Canadian oil sands tailings operations in Alberta present underpenetrated demand for anionic flocculants capable of accelerating bitumen extraction waste consolidation.
- Disinfectants:Quaternary ammonium compounds, chlorine dioxide, and peracetic acid formulations control microbial growth in distribution systems. Health Canada PMRA re-evaluation timelines are forcing reformulation cycles across bleached board mills and municipal utilities.
- pH Adjusters:Sulfuric acid, caustic soda, and sodium carbonate correct alkalinity in boiler feedwater and effluent neutralization. Industrial power plants in Texas ERCOT grid territory represent concentrated procurement volume.
Coagulants dominate installed base. Flocculants are where expansion concentrates.
End User:
Cost tier stratification separates specification-grade municipal procurement from price-sensitive residential retail. Industrial accounts occupy the premium service tier where technical density commands margin.
- Municipal:City and county water authorities operate continuous dosing systems for drinking water treatment and wastewater discharge compliance. California and Texas utilities advancing direct potable reuse pilots are driving enhanced disinfection protocol adoption.
- Industrial:Petrochemical refineries, pulp-and-paper mills, and power generation facilities require customized corrosion inhibition and deposit control. Cooling tower blowdown regulations along the US Gulf Coast are tightening procurement specifications for biocide and scale inhibitor bundles.
- Commercial:Hotels, hospitals, and office complexes maintain secondary disinfection in building plumbing systems. Legionella prevention protocols in healthcare facilities are expanding point-of-use chemical treatment installations.
- Residential:Homeowners purchase point-of-entry softeners and pitcher filtration cartridges through retail channels. Consumer education gaps suppress premium formulation uptake relative to commodity salt and carbon products.
Industrial accounts generate premium margin. Municipal represents the deepest volume pool.
Application:
Volume scale differentiates continuous-process industrial treatment from intermittent residential use. Membrane-intensive applications command the highest polymer specification grades.
- Wastewater Treatment:Secondary and tertiary biological processes require nutrient removal chemistry and final disinfection. EPA effluent limitation guidelines under the Clean Water Act are accelerating coagulant procurement cycles across US municipal utilities.
- Drinking Water Treatment:Surface water filtration plants dose coagulants, disinfectants, and corrosion inhibitors to meet Safe Drinking Water Act standards. NSF/ANSI Standard 60 certification requirements extend commercialization timelines for novel chemistry introductions.
- Cooling Water Treatment:Open recirculating systems demand scale inhibitors, corrosion inhibitors, and biocides to manage concentration cycles. Commodity phosphonate flooding is compressing margins in this structurally mature segment.
- Process Water Treatment:High-purity loops in semiconductor fabrication and pharmaceutical manufacturing require membrane-compatible polymers. Acrylic-based flocculants with tailored charge density profiles are displacing legacy aluminum sulfate in desalination pretreatment.
Wastewater treatment anchors volume. Process water treatment is climbing the fastest.
Form:
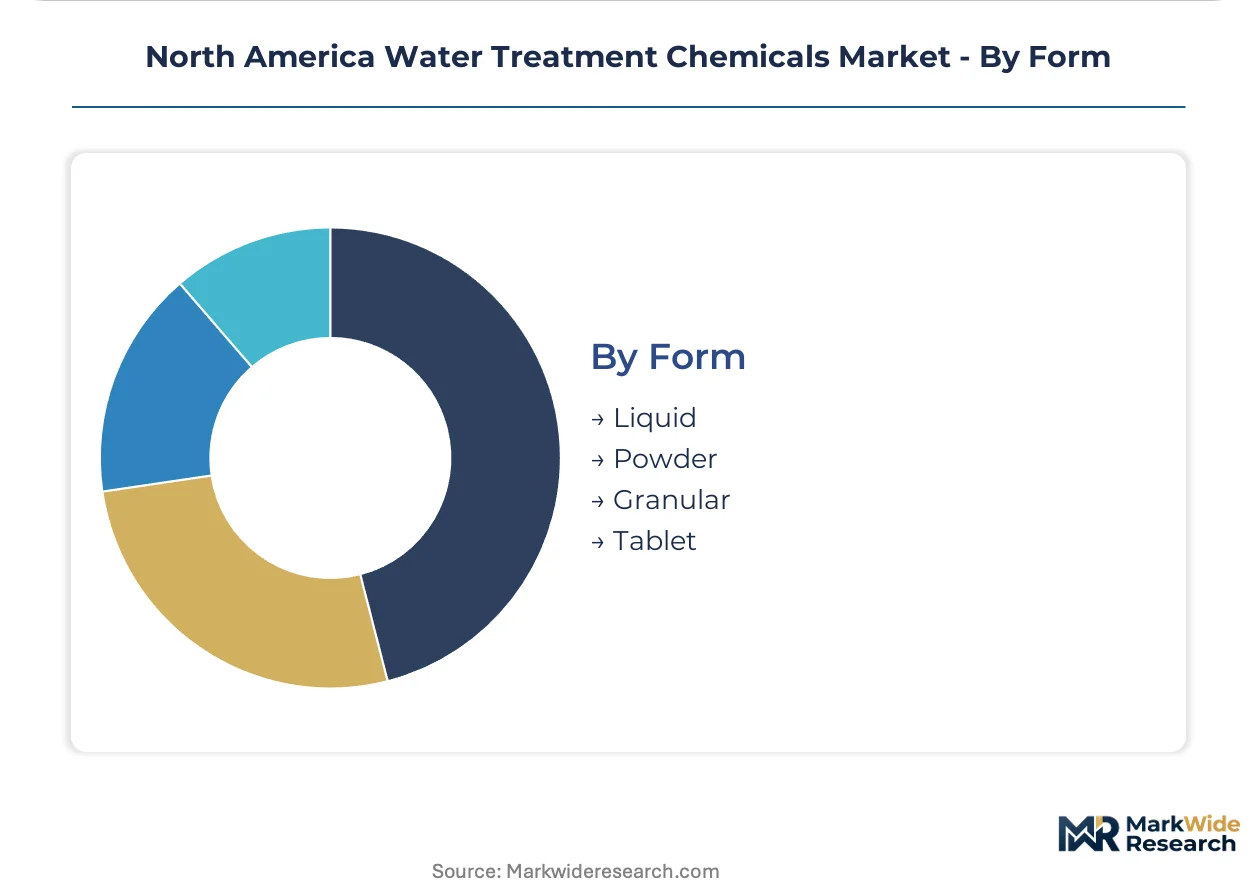
Supply concentration and logistics economics favor liquid formulations for high-volume industrial accounts. Solid forms capture residential and remote-site distribution where transport costs dominate.
- Liquid:Ready-to-feed solutions eliminate on-site dissolution equipment and reduce operator exposure. Bulk tanker deliveries serve continuous municipal and industrial dosing systems across the US Midwest and Southeast.
- Powder:Concentrated active ingredients reduce freight costs for remote mining camps and small utilities. Canadian oil sands operations in northern Alberta rely on powder flocculants where liquid transport infrastructure is limited.
- Granular:Controlled-release formulations extend service intervals in residential softeners and commercial cooling towers. Big-box retail distribution concentrates in suburban markets surrounding major metropolitan areas.
- Tablet:Pre-measured doses simplify application in seasonal recreational water and emergency disinfection scenarios. Campground and marine vessel markets represent niche but stable demand pockets.
Liquid formulations dominate installed base. Powder is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial buyers in the US Gulf Coast petrochemical corridor show the lowest price elasticity, absorbing premium formulations to meet tightening discharge rules. Canadian mining operators exhibit moderate sensitivity, balancing freight costs against flocculant performance. Mexican municipal utilities face the highest budget constraints, driving demand for commodity-grade coagulants.
United States
California utilities advancing direct potable reuse pilots are driving enhanced disinfection protocol adoption. EPA effluent limitation guidelines under the Clean Water Act are accelerating coagulant procurement cycles nationwide. Texas ERCOT-grid power operators and Gulf Coast refineries concentrate demand for cooling water biocides and corrosion inhibitors.
Canada
Alberta oil sands tailings operations present underpenetrated demand for high-molecular-weight anionic flocculants. Health Canada PMRA re-evaluation of quaternary ammonium compounds is forcing reformulation timelines across bleached board mills. Ontario municipal utilities anchor eastern procurement volume for membrane-compatible polymer chemistry.
Mexico
Northern border state maquiladoras require process water treatment for semiconductor and automotive manufacturing. Mexican environmental regulators are aligning discharge standards with US EPA frameworks, elevating compliance investment. Mexico City metropolitan utilities represent the deepest municipal volume pool for bulk liquid coagulant deliveries.
North America Water Treatment Chemicals Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the North American water treatment chemicals market. Integrated formulation houses with captive field engineering networks command premium positioning at power and refining accounts. Regional distributors compete on logistics density and undifferentiated commodity supply. The dominant competitive moves are embedding technical service teams directly at industrial sites and securing pre-validated alternative biocide platforms ahead of regulatory deadlines.
Within the integrated formulation tier, Ecolab exemplifies the field-engineering-intensive archetype through its captive technical service density. Kemira occupies a position bridging Nordic pulp-and-paper technology transfer into North American bleached board applications. Solenis represents the specialized chemistry vector, anchoring deposit control expertise for membrane-intensive desalination facilities. These three players illustrate how competitive positioning rotates toward on-site technical capability rather than raw material access alone.
| Leading Market Players |
|---|
| Ecolab |
| Kemira |
| SUEZ |
| Solenis |
| Kurita Water Industries Ltd. |
| BASF SE |
| Dow |
| Veolia |
| ChemTreat Inc. |
| Others |
Value Network & Pricing Analysis
NSF/ANSI Standard 60 certification gates both supplier qualification and price differentiation simultaneously, forcing municipal procurement teams to pay premiums for pre-validated coagulants while excluding uncertified commodity alternatives from drinking water tenders.
Pricing Analysis
Technical service contracts and extended field engineering engagements drive lifetime value more than chemical unit sales alone. Pricing stratifies across premium, standard, and economy tiers based on certification grade and on-site service density. Cost compression in commodity phosphonate scale inhibitors is intensifying because Chinese producers flood spot markets with undifferentiated supply. Industrial power and refining accounts show the lowest price sensitivity, while Mexican municipal utilities absorb the highest budget constraints.
Supply Chain Analysis
China and Jamaica anchor bauxite-derived alumina hydrate supply for polyaluminum chloride production across North American formulation plants. Domestic production draws from sulfuric acid and caustic soda feedstocks concentrated along the US Gulf Coast petrochemical corridor. Single-source vulnerability in alumina supply exposes formulators to Chinese export quota volatility. Distribution runs through bulk tanker networks serving continuous municipal dosing systems, with powder formulations reaching remote Canadian mining camps via rail and intermodal.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Water treatment chemicals represent a service-attach opportunity where technical field engineering contracts expand faster than commodity chemical volumes, rewarding suppliers who embed on-site capability ahead of hardware-only competitors.
For Market Incumbents: Fortify captive field engineering density at power and refining accounts to defend against unbundling trends separating chemical supply from maintenance contracts. Deepen backward integration into membrane-compatible polymer R&D to offset commodity phosphonate margin erosion. Prioritize pre-validation of alternative biocide platforms ahead of Health Canada PMRA re-evaluation deadlines.
For New Entrants and Emerging Players: Anchor in Canadian oil sands tailings chemistry where high-molecular-weight anionic flocculant demand remains underpenetrated by integrated formulation houses. Target Alberta bitumen extraction operators with powder-form logistics solutions bypassing limited liquid transport infrastructure. Lead with pilot-scale membrane compatibility testing as a differentiated entry wedge.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across membrane-compatible polymer sub-segments as pilot-scale validation infrastructure achieves scale economies. Long-term viability favors vertically integrated specialists with captive bauxite sourcing or sulfuric acid backward integration. Monitor EPA PFAS discharge rule finalization as the signal to watch for supply chain auditing burden inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alumina Supply | Secures bauxite-derived feedstock against Chinese export quota volatility. |
| Membrane Compatibility Certification | Unlocks premium positioning in desalination and semiconductor process water loops. |
| Field Engineering Network Expansion | Captures recurring service revenue at power utilities unbundling chemical procurement. |
| Alternative Biocide Platform Development | Positions ahead of Health Canada PMRA quaternary ammonium re-evaluation outcomes. |
| Oil Sands Tailings Chemistry Partnership | Accesses underpenetrated Alberta demand for high-molecular-weight flocculants. |
Research Methodology
The analysis maps coagulant, flocculant, disinfectant, and pH adjuster sub-sectors, each validated through technical sales directors at integrated formulation houses, municipal procurement managers, and plant engineers at petrochemical refineries. Primary interview intelligence triangulates against secondary sources including EPA effluent limitation guideline filings, Health Canada PMRA re-evaluation dockets, ACC chemical industry reports, and SEC 10-K disclosures from listed suppliers. Bottom-up volume builds from end-use consumption patterns cross-check against top-down market sizing across the analysis window.
Consistency checks validate volume and value outputs against external benchmarks including customs trade data for bauxite-derived alumina hydrate imports and utility capital expenditure disclosures for chemical dosing infrastructure. The forecast framework segments by product type, end-use industry, application intensity, and form factor, with CAGRs derived from regression analysis of historical procurement cycles and regulatory implementation timelines. Modeled inputs include EPA rulemaking schedules, membrane installation growth curves, and direct potable reuse pilot expansion rates.
Decision-makers should treat outputs as directional under stable regulatory implementation assumptions; material acceleration or delay in EPA PFAS discharge rules would warrant model refresh. Recalibration cycles align with material shifts in Clean Water Act enforcement intensity, Health Canada PMRA re-evaluation outcomes, and membrane technology adoption curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
Germany Water Treatment Chemicals Market
Water & Sludge Treatment
Global Liquid Waste Management Market
Water & Sludge Treatment
Water Treatment Polymers Market
Water & Sludge Treatment
South America Membrane Water and Wastewater (WWT) Treatment Market
Water & Sludge Treatment
Wastewater Treatment Chemicals Market
Water & Sludge Treatment
Global Industrial Sludge Treatment Chemicals Market
Water & Sludge Treatment
Global Boiler Water Treatment Chemicals Market
Water & Sludge Treatment
Mexico Water Treatment Chemicals Market
Water & Sludge Treatment
Swimming Pool Treatment Chemicals Market
Water & Sludge Treatment
Hypochlorous Acid Water Generator Market
Water & Sludge Treatment
Enzymes for Water Treatment Market
Water & Sludge Treatment
Cooling Water Treatment Chemicals Market
Water & Sludge Treatment
Industrial Water Treatment Chemicals Market
Water & Sludge Treatment
Water Treatment Market
Water & Sludge Treatment
Europe Membrane Water and Wastewater Treatment (WWT) Market
Water & Sludge Treatment
India Water and Wastewater Treatment (WWT) Technology Market