
 Germany Water Treatment Chemicals Market | 2026-2036
Germany Water Treatment Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Water Treatment Chemicals Market Foresight
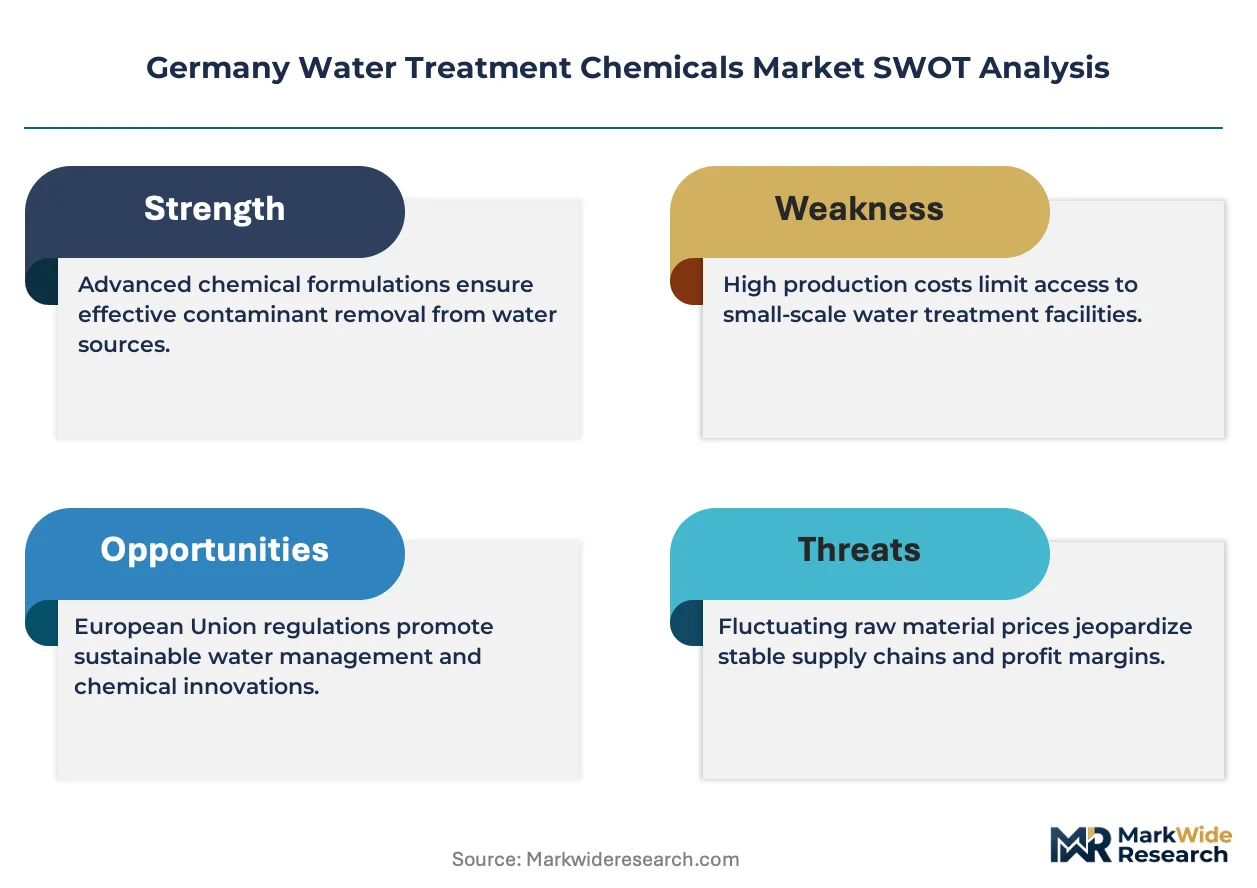
Chemical engineering talent scarcity is bifurcating the competitive landscape between integrated multinationals and specialized regional formulators. BASF SE leverages its Ludwigshafen manufacturing complex to sustain captive production of polyacrylamide flocculants and phosphonate scale inhibitors. Kemira Oyj anchors its position through R&D intensity in bio-based coagulant chemistry, while Solenis specializes in application-specific dosing systems for pulp and paper effluent streams.
Germany water treatment chemicals encompass functional formulations including aluminum sulfate coagulants, chlorine dioxide disinfectants, and phosphonate-based scale inhibitors designed to modify water chemistry across industrial and municipal systems. These chemicals operate within precise pH windows and dosage parameters to prevent biofouling, mineral scaling, and corrosion in circulating water infrastructure. Coagulants and flocculants dominate volume consumption given their indispensable role in solids-liquid separation across municipal treatment plants, while biocides command premium margins due to stringent approval pathways under Germany's Biocidal Products Regulation. Application demand from power generation cooling towers represents the fastest-expanding segment as utilities retrofit once-through systems with closed-loop chemistries to comply with thermal discharge limits.
The Federal Environment Agency (UBA) enforces Drinking Water Ordinance (TrinkwV) standards that mandate maximum contaminant levels for disinfection byproducts, directly shaping product substitution timelines for chlorine-based chemistries. REACH registration requirements and EU Biocidal Products Regulation (BPR) authorization processes create multi-year market access barriers that favor incumbent suppliers with established dossier portfolios. Stakeholders must monitor the interplay between UBA's anticipated tightening of phosphate discharge limits and the readiness of polymeric alternatives to achieve equivalent scale inhibition performance without eutrophication risk.
Market Dynamics
Germany's water treatment chemicals sector faces structural compression from the Federal Environment Agency's anticipated phosphate discharge limits, which are forcing formulators to rebuild scale inhibitor chemistries around polymeric alternatives before 2027 implementation deadlines.
Growth Catalysts
- Rhine-Ruhr industrial corridor expansion:Chemical processing and power generation clusters in North Rhine-Westphalia drive concentrated bulk procurement of coagulants and corrosion inhibitors for cooling tower infrastructure.
- TrinkwV amendment compliance:Tightened residual limits under Germany's Drinking Water Ordinance accelerate substitution toward bio-based formulations across municipal utilities.
- Closed-loop cooling retrofits:Thermal discharge regulations under the Federal Immission Control Act push utilities to replace once-through systems, expanding demand for biocide and scale control chemistries.
Market Restraints
- REACH registration barriers:Multi-year dossier requirements and substance evaluation timelines create market access friction for new entrants without established regulatory portfolios.
- Acrylamide monomer cost volatility:Polyacrylamide flocculant production remains exposed to petrochemical feedstock price swings that compress formulator margins.
- Biocidal Products Regulation authorization:BPR's tiered approval process for active substances extends commercialization timelines for novel disinfectant chemistries by 24-36 months.
Strategic Opportunities
- Bavarian municipal utility modernization:Aging treatment infrastructure in southern Germany creates retrofit demand for automated dosing systems and advanced oxidation chemistries.
- EU Green Deal alignment:Circular economy action plan incentives favor bio-based coagulant development using agricultural waste streams as feedstock alternatives.
- Digital twin integration:Convergence of real-time sensor networks with predictive chemical dosing algorithms opens service-contract revenue models for equipment-chemical bundling.
Industry Challenges
- Process engineering talent scarcity:Specialized expertise in chemical dosing optimization and membrane compatibility testing concentrates among aging workforce cohorts, constraining regional formulator expansion.
- Legacy SCADA integration complexity:Municipal utilities operate decades-old control systems that resist seamless interface with modern automated chemical feed systems, extending deployment timelines.
- Biocide resistance management:Microbial adaptation to conventional oxidizing chemistries demands continuous formulation rotation protocols that strain operator training resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Water Treatment Chemicals Market |
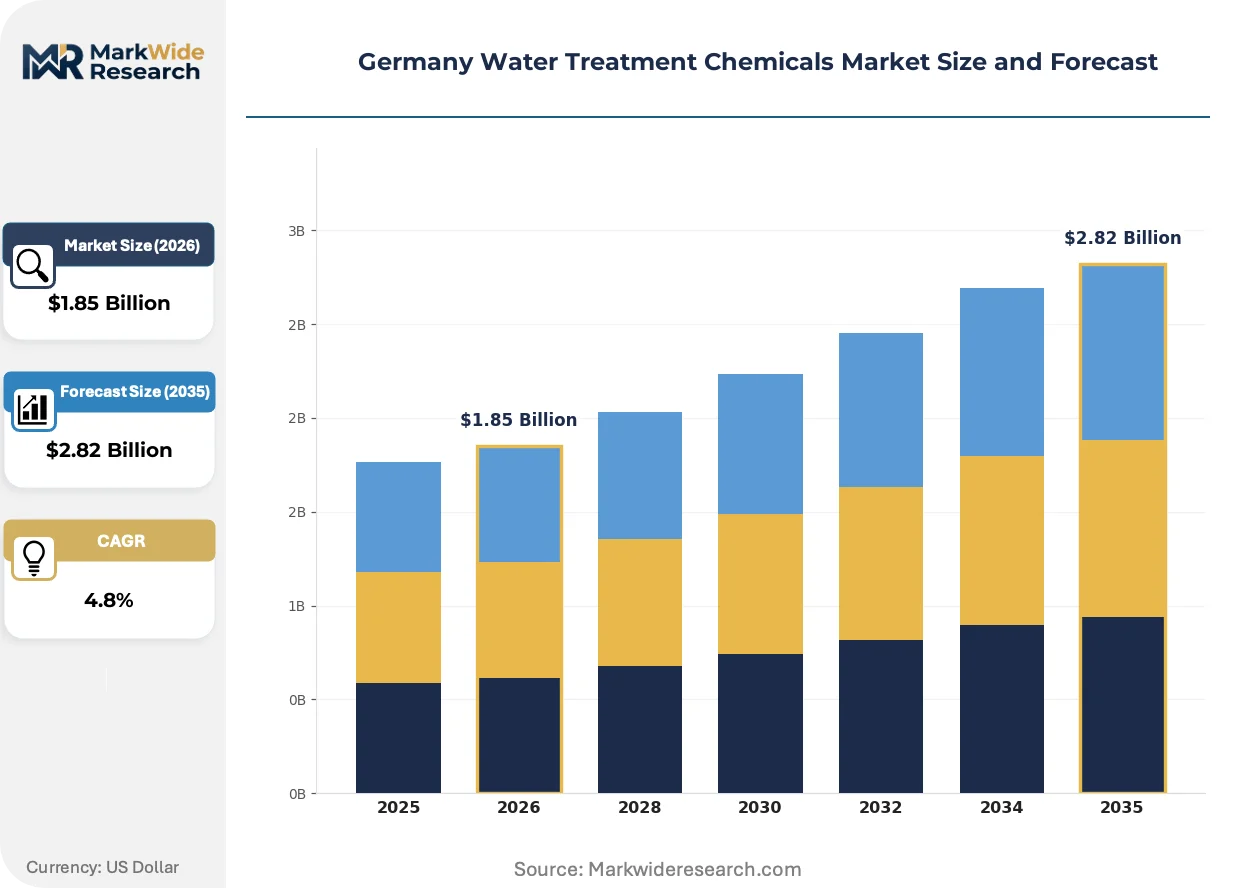
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.82 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coagulants, Disinfectants, Scale Inhibitors, Corrosion Inhibitors, Flocculants, Biocides Application: Industrial Process Water, Municipal Water Supply, Wastewater Treatment, Cooling Towers, Swimming Pools, Desalination Plants End User: Power Generation Plants, Food & Beverage Manufacturers, Chemical Processing Units, Pharmaceutical Companies, Textile Producers Form: Liquid, Powder, Granular, Tablet, Emulsion |
| Companies Covered | BASF SE, Ecolab Inc., Kemira Oyj, Solenis LLC, Nouryon, Dow Inc., SUEZ, Solvay, Kurita Water Industries Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Water Treatment Chemicals Market Shifts & Advancements
Formulation chemistry and delivery mechanisms are undergoing parallel transformation as regulatory pressure and operational efficiency targets converge on precision dosing and bio-based alternatives.
Polymeric scale inhibitors are decomposing the historical dominance of phosphonate chemistries in German power generation cooling systems. Operators in the Rhine-Ruhr corridor are piloting polycarboxylate and maleic acid copolymer alternatives at 15-20% dosage premiums to preempt phosphate discharge restrictions. This substitution is decomposing incumbent supplier margins while opening technical service contracts for polymer compatibility testing.
REACH authorization timelines are compressing product lifecycle planning for biocide manufacturers serving German municipal markets. The European Chemicals Agency's 2024-2026 substance evaluation roadmap targets several chlorinated disinfectant actives for restriction, forcing utilities to validate peracetic acid and chlorine dioxide alternatives. Small-to-mid-sized municipal operators in Saxony and Thuringia face the steepest compliance costs given limited technical staffing.
Performance-based chemical supply agreements are displacing traditional volume contracts among industrial water treatment buyers in Baden-Württemberg. Automotive and electronics manufacturers now specify guaranteed heat transfer efficiency outcomes rather than fixed chemical tonnage, transferring dosage optimization risk to formulator partners. This model concentrates procurement authority with integrated multinationals capable of underwriting performance guarantees.
Germany Water Treatment Chemicals Market Segmentation
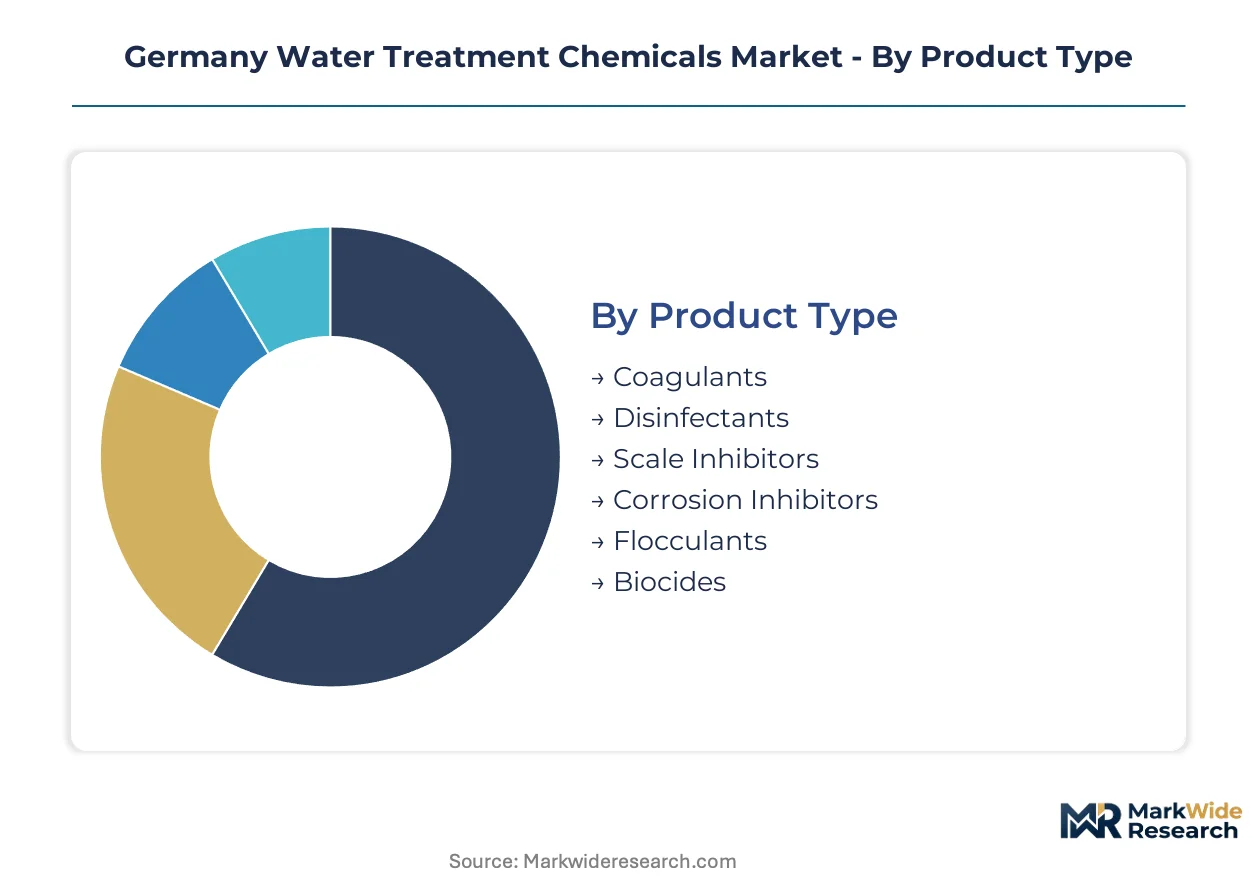
Product differentiation in German water treatment chemicals follows regulatory pressure vectors and end-use performance requirements. Each segment category maps to distinct procurement patterns across municipal utilities and industrial clusters.
Product Type:
Domestic consumption dominates coagulant and flocculant procurement, while disinfectant and biocide production serves both local municipal markets and export demand into neighboring EU member states.
- Coagulants:Aluminum sulfate and ferric chloride formulations precipitate suspended solids in municipal clarification basins. Rhine-Ruhr utilities consume bulk volumes for surface water treatment, though tightening TrinkwV residual limits are accelerating ferric-based substitution.
- Scale Inhibitors:Phosphonate and emerging polycarboxylate chemistries prevent mineral deposition in circulating cooling systems. Power generation facilities in North Rhine-Westphalia represent the concentrated demand node as operators retrofit once-through infrastructure.
- Disinfectants:Chlorine dioxide and peracetic acid alternatives displace legacy chlorination at municipal plants.
- Corrosion Inhibitors:Orthophosphate and zinc-based formulations protect distribution network metallurgy.
- Flocculants:Polyacrylamide polymers bridge coagulated particles for enhanced sedimentation.
- Biocides:Oxidizing and non-oxidizing microbiological control agents face BPR authorization bottlenecks.
Coagulants command the established base. The steepest expansion runs through scale inhibitors as phosphate discharge limits force chemistry transitions.
Application:
Volume concentration varies sharply between capital-intensive industrial installations and fragmented municipal procurement.
- Municipal Water Supply:Drinking water treatment plants deploy coagulants, disinfectants, and pH adjusters across multi-stage filtration trains. Bavarian and Baden-Württemberg utilities are modernizing aging infrastructure with automated dosing systems.
- Industrial Process Water:Manufacturing facilities demand high-purity conditioning chemistries for boiler feed and rinse applications. Chemical processing clusters along the Rhine corridor specify customized formulation packages.
- Wastewater Treatment:Biological nutrient removal drives polymer demand for sludge dewatering.
- Cooling Towers:Closed-loop retrofits expand biocide and scale inhibitor consumption.
- Swimming Pools:Recreational water treatment uses stabilized chlorine and alternative oxidizers.
- Desalination Plants:Reverse osmosis pretreatment requires antiscalant chemistries at limited German coastal installations.
Municipal water supply anchors volume procurement. Industrial process water is climbing the fastest as manufacturing quality standards tighten.
End User:
Procurement sophistication diverges between regulated utilities and private industrial operators with divergent technical staffing levels.
- Power Generation Plants:Cooling water chemistry dominates chemical spend as utilities balance thermal efficiency against discharge compliance. Lignite and combined-cycle facilities in the Lusatian and Rhine mining districts drive bulk inhibitor procurement.
- Chemical Processing Units:Integrated petrochemical complexes require specialized scale and corrosion control for high-temperature process streams. BASF's Ludwigshafen complex exemplifies captive formulation production at scale.
- Food & Beverage Manufacturers:Brewery and dairy processors demand food-grade chemistries with documented purity certifications.
- Pharmaceutical Companies:USP-grade water systems require validated chemical additives with full supply chain documentation.
- Textile Producers:Dyehouse effluent treatment uses coagulants for color removal.
Power generation commands the established base. Pharmaceutical companies represent the steepest expansion trajectory given validation complexity and premium pricing tolerance.
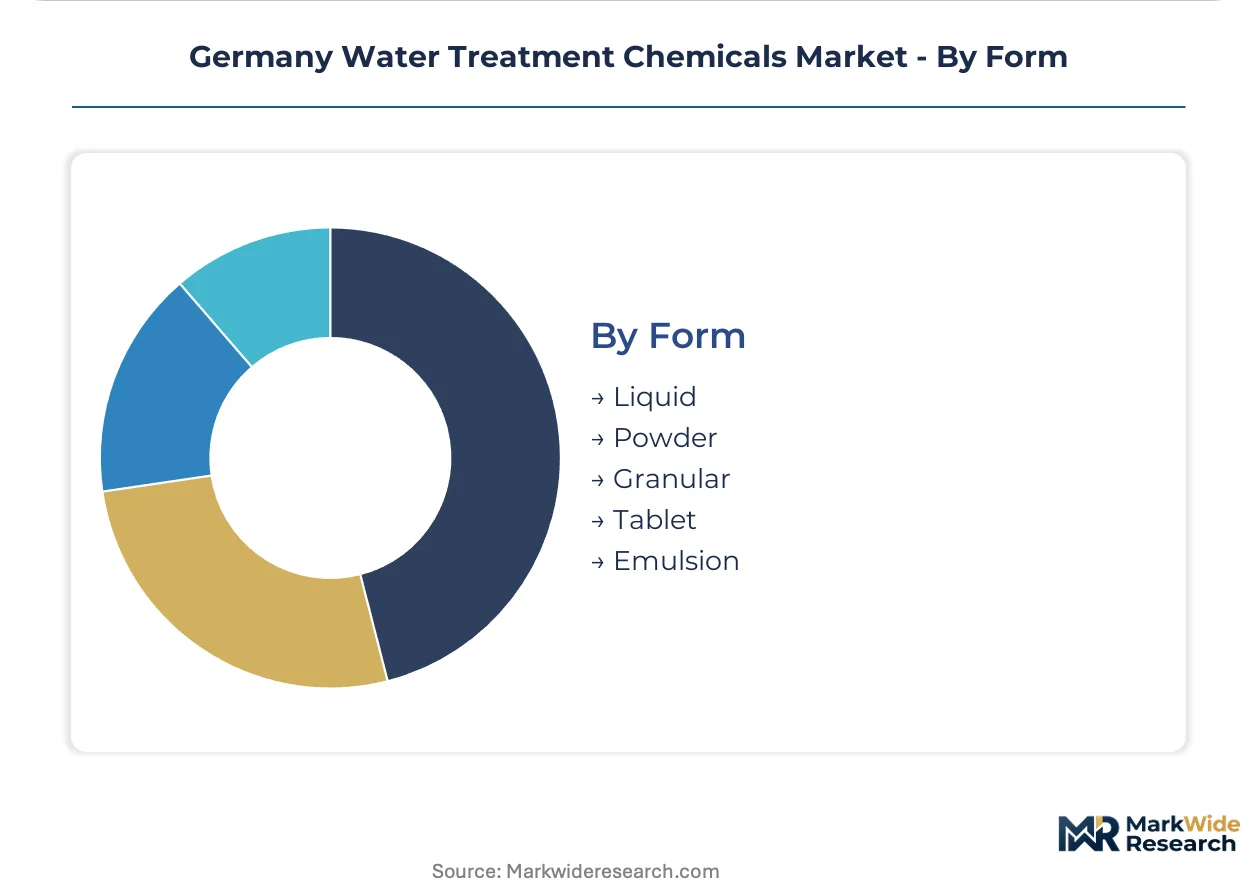
Form:
Physical formulation determines logistics economics and dosing system compatibility across customer segments.
- Liquid:Pump-ready solutions dominate industrial installations with automated feed systems. Ready-to-dose convenience offsets higher transport costs for Rhine-Ruhr chemical processors.
- Powder:Concentrated dry forms reduce freight expenditure for high-volume municipal procurement. Saxony and Thuringia utilities favor bulk powder delivery with on-site dissolution.
- Granular:Controlled-release formulations suit remote or low-technical-capability installations.
- Tablet:Pre-measured dosing simplifies small-scale swimming pool and secondary disinfection applications.
- Emulsion:Specialized polymer delivery systems enhance mixing efficiency in high-turbidity raw water.
Liquid formulations command the established base. Powder alternatives are gaining share fastest as freight cost optimization pressures intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Federal Environment Agency anchors Germany's water treatment chemicals demand through TrinkwV enforcement and phosphate discharge limits. State-level infrastructure investment varies across industrial corridors and municipal modernization cycles.
North Rhine-Westphalia
Chemical processing and power generation clusters drive concentrated bulk procurement of coagulants and scale inhibitors. The Federal Immission Control Act thermal discharge regulations push utilities toward closed-loop cooling retrofits. The Rhine-Ruhr corridor sustains captive formulation production at Ludwigshafen-scale complexes while municipal utilities modernize aging surface water treatment plants.
Bavaria
Aging treatment infrastructure in southern Germany creates retrofit demand for automated dosing systems and advanced oxidation chemistries. State environmental agencies enforce stricter residual limits than federal baselines, accelerating bio-based formulation adoption. Munich and Nuremberg metropolitan utilities pilot digital twin integration for predictive chemical dosing optimization.
Baden-Württemberg
Automotive and electronics manufacturers specify performance-based chemical supply agreements with guaranteed heat transfer efficiency outcomes. The state's industrial water treatment buyers transfer dosage optimization risk to formulator partners through outcome-based contracting. Stuttgart-region manufacturing clusters concentrate procurement authority with integrated multinationals capable of underwriting technical guarantees.
Lower Saxony
Lignite power facilities in the Lusatian mining district drive bulk inhibitor procurement for cooling water chemistry compliance. State-level mining and energy regulators coordinate thermal discharge limits with federal BImSchG implementation timelines. Wolfsburg-area automotive manufacturing integrates high-purity process water conditioning into supplier quality certification requirements.
Hesse
Frankfurt-Rhine-Main financial and logistics centers sustain commercial building cooling tower demand for biocide and corrosion inhibitor chemistries. The state's central location positions chemical distributors for nationwide supply chain optimization. Darmstadt-region technical universities supply process engineering talent to regional formulator R&D operations.
Germany Water Treatment Chemicals Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes within Germany's water treatment chemicals sector. Integrated petrochemical multinationals leverage captive raw material access and Ludwigshafen-scale manufacturing complexes against specialized regional formulators competing on application-specific technical service. The competitive structure stratifies across three strategic archetypes: integrated chemical conglomerates with backward integration into monomer production, mid-sized European specialists concentrating on bio-based formulation R&D, and application-focused service providers bundling equipment with chemical supply. Dominant competitive moves include performance-based contracting that transfers operational risk from industrial buyers to chemical suppliers, and regulatory dossier portfolio expansion to secure BPR authorization timelines.
Among integrated chemical conglomerates, BASF SE anchors the scale-driven tier through its Ludwigshafen manufacturing complex and captive polyacrylamide production. Kemira Oyj occupies a position within the European specialist tier, representing bio-based coagulant chemistry development. Solenis LLC exemplifies the application-focused service archetype, sitting within the equipment-chemical bundling segment for industrial effluent treatment. These three companies represent distinct competitive positioning vectors rather than direct substitutability.
| Leading Market Players |
|---|
| BASF SE |
| Ecolab Inc. |
| Kemira Oyj |
| Solenis LLC |
| Nouryon |
| Dow Inc. |
| SUEZ |
| Solvay |
| Kurita Water Industries Ltd. |
| Others |
Supply & Pricing Matrix
Ludwigshafen-scale manufacturing complexes anchor price floors through captive acrylamide monomer production, compressing regional formulator margins while elevating barriers for non-integrated entrants. Capacity utilization at Rhine-Ruhr chemical clusters shapes procurement leverage for bulk coagulant buyers, with municipal utilities facing asymmetric negotiating positions against backward-integrated suppliers.
Pricing Analysis
Rhine-Ruhr industrial buyers command 12-18% discounts versus Bavarian municipal utilities due to concentrated volume procurement and direct rail-tanker delivery infrastructure. Pricing stratifies across premium, standard, and economy tiers: pharmaceutical-grade biocides with full BPR dossier support capture 35-40% premiums over commodity chlorine alternatives, while generic ferric chloride faces relentless cost compression from Chinese import competition. Price erosion runs through polyacrylamide flocculants as petrochemical feedstock volatility transfers downstream. Small-to-mid-sized Saxony utilities exhibit highest price sensitivity due to limited technical staffing for performance-based contract evaluation.
Supply Chain Analysis
Port congestion at Rotterdam and Hamburg elevates inbound logistics costs for phosphonate intermediates sourced from Chinese manufacturers, extending lead times for German formulators. Raw material supply concentrates in China for phosphonate actives, the United States for specialty acrylamide monomers, and Belgium for bulk aluminum sulfate precursors. Feedstock dependency rests on ethylene oxide derivatives, acrylic acid esters, and phosphate rock concentrates. Single-source vulnerability persists for REACH-registered biocide actives with restricted supplier pools. Distribution runs through tank-truck networks serving Rhine-Ruhr chemical corridors, with rail-bulk delivery dominating municipal utility procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Germany's water treatment chemicals sector demands substitution defense against polymeric scale inhibitors displacing phosphonate incumbents before Federal Environment Agency phosphate limits take effect. Bio-based coagulant chemistry represents the critical pivot point where formulators must rebuild product portfolios or cede share to agricultural-waste-derived alternatives.
For Market Incumbents: Secure BPR authorization dossiers for chlorine dioxide and peracetic acid alternatives ahead of ECHA's substance evaluation roadmap deadlines. Deepen backward integration into bio-based feedstock supply chains through partnerships with Bavarian agricultural processors, insulating margin structures from petrochemical volatility while aligning with EU Green Deal circular economy incentives.
For New Entrants and Emerging Players: Technical service gaps in legacy SCADA integration for automated dosing systems present immediate white-space opportunity. Target Thuringia and Saxony municipal utilities with limited in-house process engineering capacity, offering bundled equipment-chemical contracts with guaranteed performance outcomes. Deploy digital twin pilot programs as differentiated entry mechanism against established volume suppliers.
For Investors and Strategic Acquirers: Regional formulators with established REACH registration portfolios and specialized membrane-compatibility testing capabilities offer compelling acquisition targets. Long-term viability hinges on regulatory dossier depth rather than manufacturing scale alone. Monitor ECHA substance evaluation announcements as inflection indicator for portfolio revaluation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Feedstocks | Partnerships with Bavarian agricultural processors secure circular economy alignment and margin insulation. |
| REACH Dossier Portfolio Expansion | Multi-year registration timelines for biocide actives create defensive moats against regulatory disruption. |
| Digital Twin Integration for Predictive Dosing | Munich and Nuremberg utilities pilot real-time sensor networks enabling service-contract revenue models. |
| Performance-Based Supply Agreements | Baden-Württemberg automotive manufacturers transfer dosage optimization risk to integrated multinationals. |
| Regional Formulator Acquisition | Specialized membrane-compatibility expertise concentrates among aging workforce cohorts in Darmstadt-region. |
Research Methodology
Cross-validation between primary interviews with municipal utility procurement directors, chemical plant managers, and ECHA regulatory affairs specialists anchors the qualitative findings against secondary validation from UBA enforcement guidance, REACH registration databases, and Bundesverband der Deutschen Industrie sector reports. Technical R&D directors at Rhine-Ruhr formulators and distribution channel partners provided downstream demand calibration. Bottom-up segment sizing triangulates with top-down macroeconomic indicators across the analysis window.
Sensitivity analysis around phosphate discharge limit implementation timelines and acrylamide monomer price volatility bounds the forecast confidence intervals. The analytical framework models product type, application end-use, physical form, and regional production hub dimensions throughout the projection horizon. CAGRs derive from segment-level demand elasticity estimates and substitution rate assumptions for bio-based alternatives. Industry-specific inputs include TrinkwV amendment compliance cost curves and BPR authorization pipeline status.
Forecasts assume regulatory continuity in Germany's Drinking Water Ordinance and EU Biocidal Products Regulation enforcement regimes; material policy shifts would require re-modeling. Specific risk factors include accelerated phosphate limit adoption, REACH substance restriction expansions, and petrochemical feedstock supply disruptions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
Water Treatment Chemicals Market
Water & Sludge Treatment
Global Sodium Hypochlorite Market
Water & Sludge Treatment
South America Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
Feedwater Treatment Chemicals Market
Water & Sludge Treatment
Oil and Gas Water Treatment Chemicals Market
Water & Sludge Treatment
Polish Water Treatment Chemicals Market
Water & Sludge Treatment
Slurry Heaters Market
Water & Sludge Treatment
Global Sludge Treatment Chemicals Market
Water & Sludge Treatment
Ultrapure Water Market
Water & Sludge Treatment
North America Water Treatment Chemicals Market
Water & Sludge Treatment
Global Water Softeners Market
Water & Sludge Treatment
Enzymes for Water Treatment Market
Water & Sludge Treatment
Sludge Heater Market
Water & Sludge Treatment
Europe Membrane Bioreactor (MBR) Market
Water & Sludge Treatment
CMP Slurry Blend and Delivery Systems Market
Water & Sludge Treatment
Pool and Spa Water Treatment Chemicals for Hotels and Clubs Market