
 North America Membrane Water and Wastewater Treatment (WWT) Market | 2026-2036
North America Membrane Water and Wastewater Treatment (WWT) Market Size, Share, and Industry Trends Forecast 2026-2036
North America Membrane Water and Wastewater Treatment (WWT) Market Analytics
North American membrane module production is consolidating around suppliers with captive polymer synthesis and hollow-fiber spinning capabilities. DuPont Water Solutions leverages its fluoropolymer expertise to dominate high-pressure reverse osmosis element supply for seawater desalination. Evoqua Water Technologies sustains a dense service network across U.S. industrial corridors, anchoring aftermarket revenue in ultrafiltration skids. Koch Separation Solutions specializes in crossflow systems for dairy and food processing, occupying a defensible niche in hygienic membrane design.
Membrane water and wastewater treatment employs semipermeable barriers with pore sizes ranging from 0.1 micrometers in microfiltration to sub-nanometer dimensions in reverse osmosis, typically fabricated from polyethersulfone, polyamide thin-film composites, or ceramic alumina to selectively exclude contaminants, salts, and pathogens under applied pressure or vacuum. Reverse osmosis leads product type revenue due to energy-intensive desalination and high-purity industrial water demand, while membrane bioreactors represent the fastest-expanding technology segment as utilities seek compact footprints and superior nutrient removal. Municipal application channels command the largest share of installed base, though pharmaceutical end users generate premium pricing for validated ultrafiltration systems with full extractables documentation.
The EPA enforces Clean Water Act discharge limits that compel municipal utilities toward advanced membrane-based tertiary treatment, while Health Canada and PMRA coordinate on drinking water quality guidelines affecting membrane selection across Canadian provinces. State-level regulations in California, Texas, and Florida independently mandate direct potable reuse feasibility studies, creating fragmented but demanding compliance landscapes. Stakeholders must monitor emerging PFAS maximum contaminant levels, as these compounds will force retrofit cycles across existing conventional plants and reshape membrane specification priorities.
Market Dynamics
EPA enforcement of emerging PFAS maximum contaminant levels is forcing municipal utilities across the United States to accelerate retrofit timelines for conventional treatment plants, compressing procurement cycles for advanced membrane systems and reshaping supplier qualification criteria.
Growth Catalysts
- California's direct potable reuse mandates:State legislation requires feasibility studies for membrane-based indirect potable reuse, creating immediate procurement pipelines for reverse osmosis trains in water-scarce districts.
- Membrane bioreactor technology:Compact footprint and superior nutrient removal performance are displacing conventional activated sludge in urban utilities facing land constraints.
- Central Valley agricultural groundwater replenishment:California's Sustainable Groundwater Management Act drives demand for reverse osmosis systems treating agricultural return flows for aquifer injection.
Market Restraints
- Fluoropolymer supply concentration:High-pressure reverse osmosis element production depends on captive fluoropolymer synthesis capabilities concentrated among a limited supplier base.
- Energy cost volatility:Reverse osmosis desalination and high-purity industrial applications face margin pressure from electricity input cost swings affecting operating expenditure calculations.
- Thin-film composite fouling sensitivity:Polyamide membrane vulnerability to oxidants and organics limits direct application in certain industrial wastewater streams without pretreatment capital.
Strategic Opportunities
- Texas municipal direct potable reuse:State-level feasibility study mandates create white space for membrane system integrators in rapidly growing metropolitan water districts.
- Pharmaceutical extractables documentation:Validated ultrafiltration systems with full qualification packages command premium positioning in biologics manufacturing.
- Ceramic membrane convergence with ozone:Advanced oxidation process integration with ceramic alumina systems opens industrial high-temperature applications inaccessible to polymeric alternatives.
Industry Challenges
- Membrane integrity testing certification:Utilities face compressed timelines for operator qualification on pressure decay testing and bubble point validation protocols under evolving state operator certification requirements.
- Legacy SCADA integration complexity:Brownfield membrane bioreactor retrofits require custom protocol bridging with existing distributed control systems in aging municipal infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Membrane Water and Wastewater Treatment (WWT) Market |
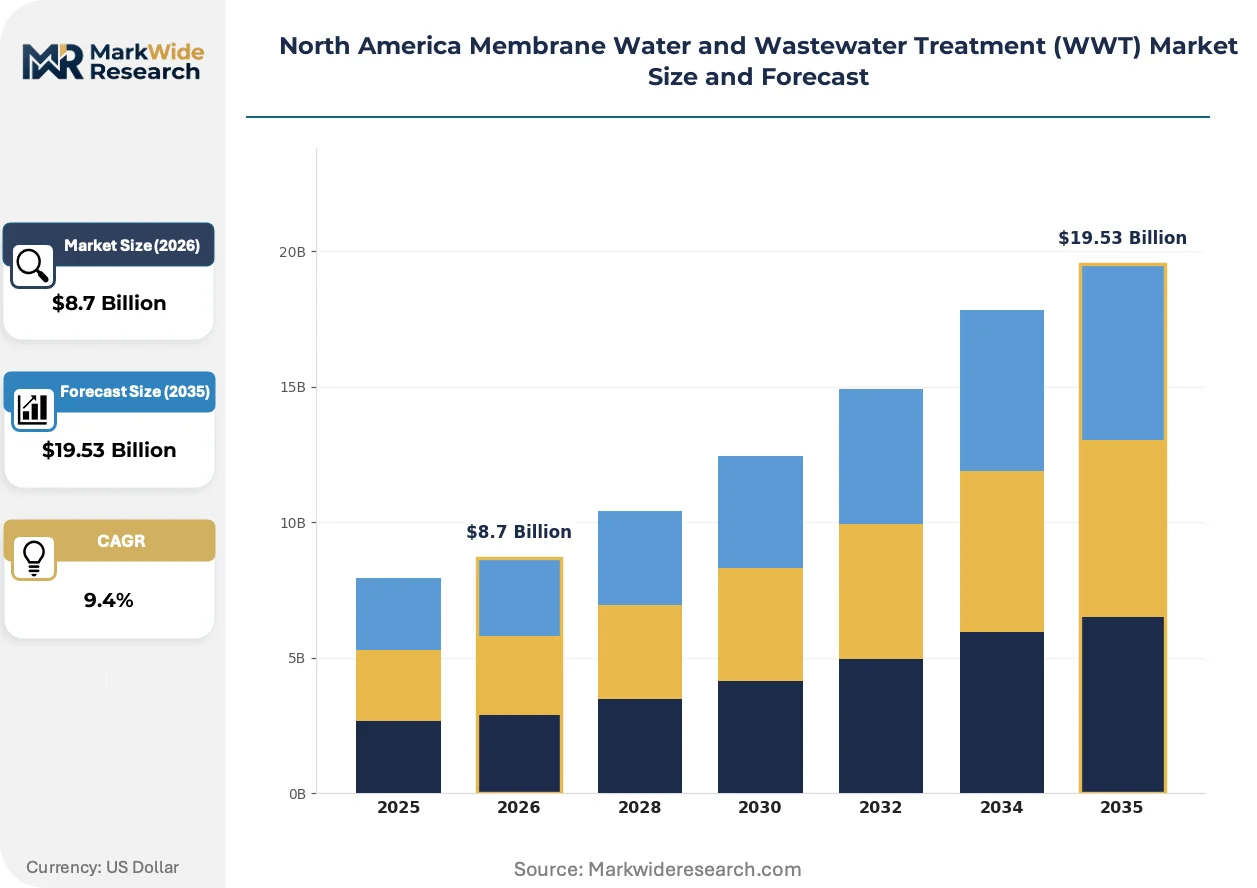
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microfiltration, Ultrafiltration, Nanofiltration, Reverse Osmosis Application: Municipal, Industrial, Agricultural, Desalination Technology: Crossflow Filtration, Dead-end Filtration, Membrane Bioreactors, Integrated Systems End User: Utilities, Manufacturing, Food & Beverage, Pharmaceuticals |
| Companies Covered | Kurita Water Industries Ltd, Ecolab, Suez, Aquatech International LLC, Evoqua Water Technologies LLC, DuPont Water Solutions, Veolia Water Technologies, Koch Separation Solutions, Pall Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Membrane Water and Wastewater Treatment (WWT) Market Evolving Landscape
Active materials research and regulatory chemistry targeting are compressing development cycles for membrane systems purpose-built to exclude specific contaminant classes.
Ceramic alumina membranes with engineered surface chemistries are overtaking polymeric alternatives in high-temperature industrial process streams and aggressive chemical cleaning regimes. Food and dairy processors operating clean-in-place protocols at elevated temperatures are specifying these systems for protein concentration and whey fractionation. The shift is compressing addressable market scope for polyethersulfone suppliers in hygienic design applications.
EPA's evolving PFAS enforcement framework under the Safe Drinking Water Act is mandating detection technology upgrades and treatment feasibility demonstrations. Municipal utilities in Michigan and New Jersey are conducting pilot-scale evaluations of nanofiltration and reverse osmosis trains for per- and polyfluoroalkyl substance removal. Equipment specification priorities are rotating toward membranes with demonstrated rejection of short-chain PFAS compounds.
Performance contracting and design-build-operate arrangements are displacing traditional capital procurement in municipal membrane projects. Florida water utilities facing hurricane resilience requirements are bundling membrane plant construction with long-term operations contracts. The model concentrates vendor selection criteria on lifecycle cost demonstration rather than upfront capital expenditure minimization.
North America Membrane Water and Wastewater Treatment (WWT) Market Segmentation
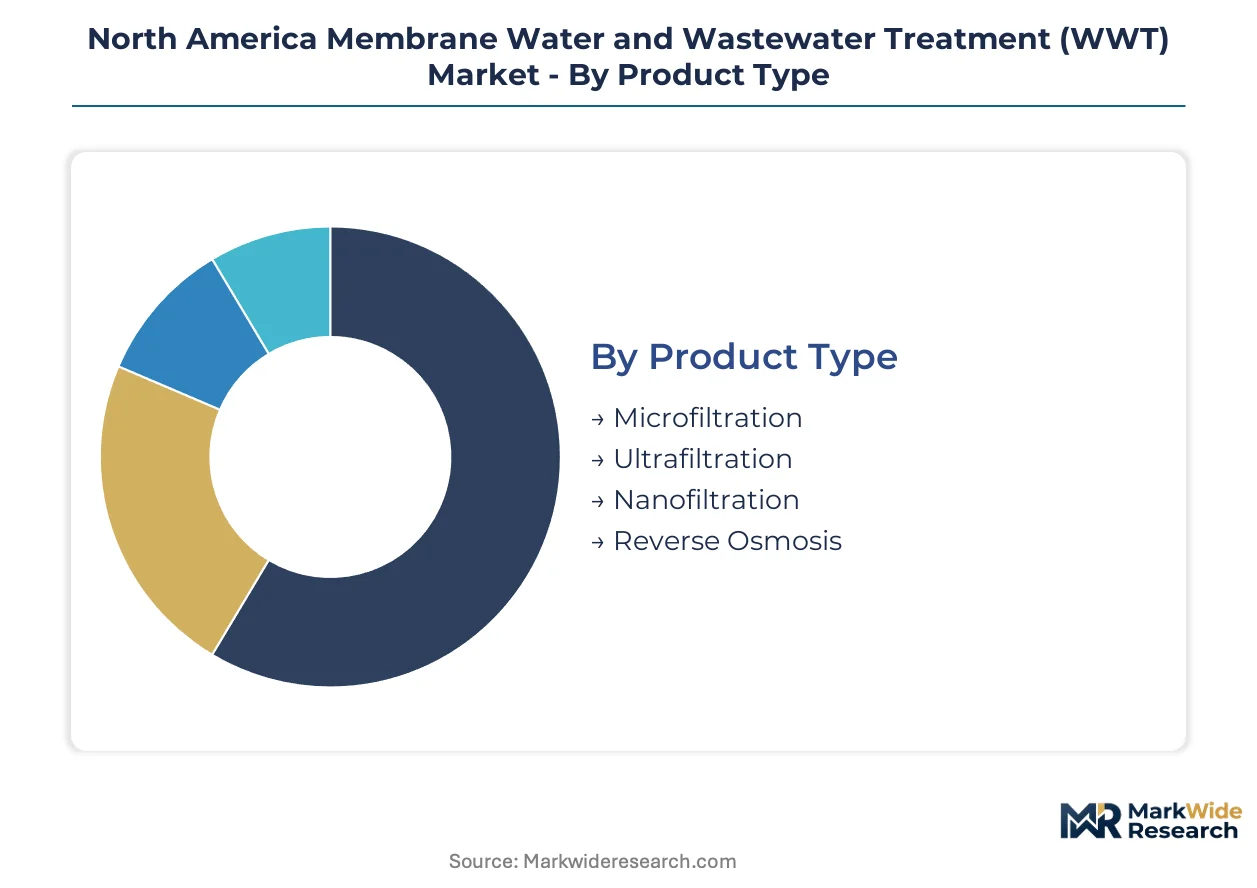
Membrane technology selection in North America follows water quality targets and regulatory pressure points rather than cost minimization alone. Procurement specifications now embed rejection performance for emerging contaminants, reshaping how segments compete.
Product Type:
Fluoropolymer synthesis capabilities concentrate among suppliers controlling high-pressure element production, creating tiered supply security.
- Reverse Osmosis:Polyamide thin-film composite membranes operate at 15-85 bar to exclude dissolved salts and sub-nanometer contaminants. California's Central Valley groundwater replenishment projects specify multi-stage RO trains for agricultural return flow treatment under SGMA compliance deadlines.
- Ultrafiltration:Hollow-fiber polyethersulfone modules with 0.01-0.1 micrometer pores target pathogen and macromolecule removal. Texas municipal utilities deploying direct potable reuse pilots prioritize UF pretreatment ahead of RO polishing for dual-barrier protection.
- Microfiltration:Ceramic alumina and polymeric membranes with 0.1-10 micrometer pores serve primary clarification in high-solids industrial streams.
- Nanofiltration:Tighter than ultrafiltration but looser than reverse osmosis, these membranes selectively reject divalent ions and organic micropollutants for softening and partial desalination.
Today's leader: Reverse Osmosis. Tomorrow's challenger: Ultrafiltration.
Application:
Procurement patterns diverge between municipal bond-financed infrastructure and industrial operational expenditure budgets.
- Municipal:Public utilities deploy membrane bioreactors and tertiary filtration to meet EPA Clean Water Act discharge limits. Michigan and New Jersey utilities pilot nanofiltration for PFAS removal ahead of federal maximum contaminant level enforcement.
- Industrial:Manufacturing facilities specify crossflow systems for process water recycling and zero-liquid discharge compliance. Food and dairy processors operating clean-in-place protocols at elevated temperatures drive ceramic membrane adoption over polymeric alternatives.
- Agricultural:California's Central Valley districts treat irrigation return flows for aquifer injection, creating concentrated demand for high-recovery RO systems.
- Desalination:Coastal Texas and Florida utilities evaluate seawater reverse osmosis for hurricane-resilient supply diversification.
Municipal channels anchor installed base volume. Industrial applications generate premium pricing for customized system integration.
Technology:
Footprint constraints and nutrient removal targets accelerate displacement of conventional activated sludge by compact membrane systems.
- Membrane Bioreactors:Immersed or sidestream membranes combine biological treatment with solids separation, eliminating secondary clarifiers. Urban utilities in land-constrained California and Texas metropolitan districts specify MBRs for capacity expansion without footprint expansion.
- Crossflow Filtration:Tangential flow patterns minimize fouling in high-solids streams. Dairy and food processors specify these systems for protein concentration and whey fractionation where hygienic design standards apply.
- Dead-end Filtration:Direct flow-through operation suits low-solids applications with periodic backwash cycles.
- Integrated Systems:Multi-barrier trains combining membrane types with advanced oxidation address complex industrial wastewaters and potable reuse specifications.
Membrane Bioreactors are expanding most quickly. Crossflow Filtration defends niche margin in hygienic applications.
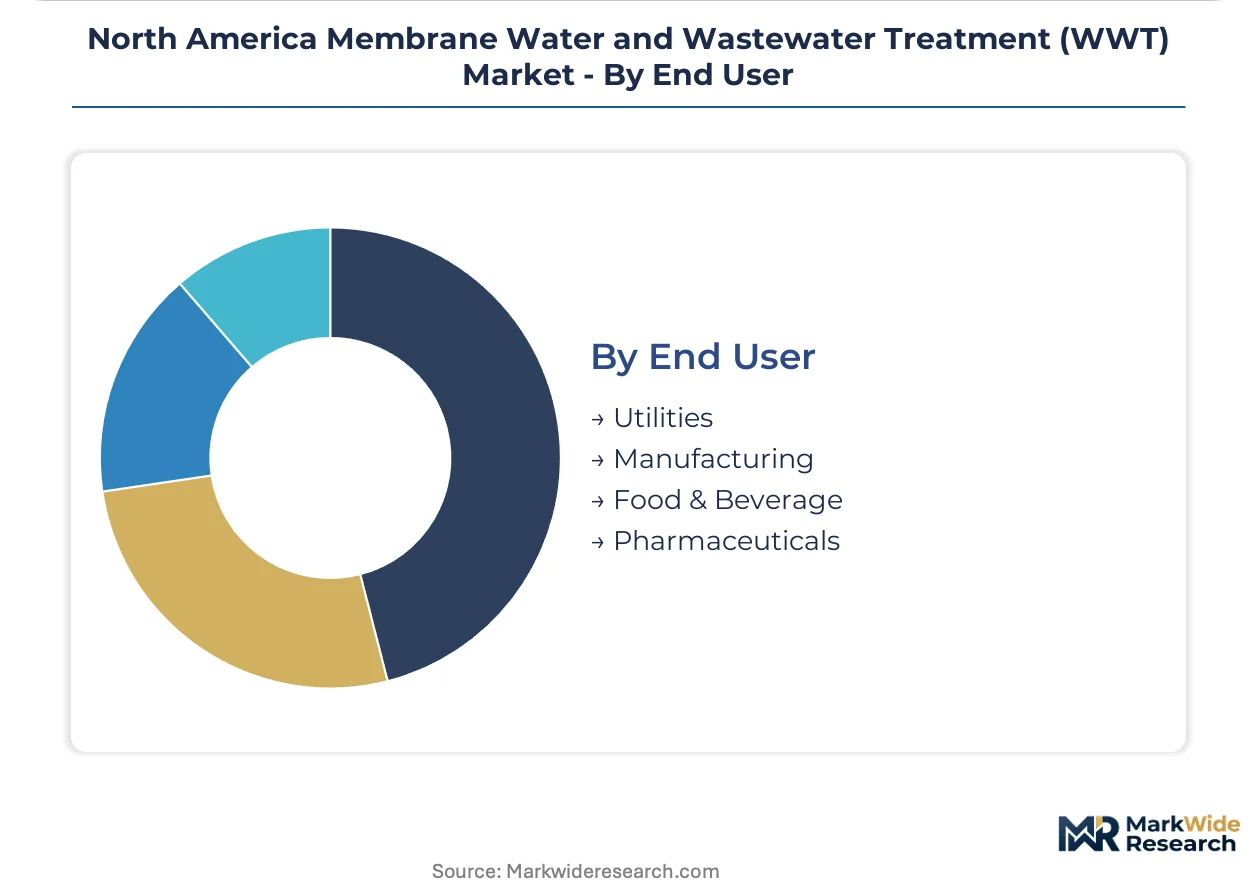
End User:
Validation requirements and extractables documentation create pricing stratification between regulated and unregulated sectors.
- Utilities:Municipal and regional water authorities procure through design-build-operate arrangements emphasizing lifecycle cost. Florida utilities bundle hurricane resilience requirements with long-term operations contracts.
- Pharmaceuticals:Biologics manufacturers demand validated ultrafiltration systems with full extractables documentation and FDA compliance packages, commanding substantial pricing premiums over standard industrial specifications.
- Manufacturing:Electronics and chemical processors specify high-purity water systems with demonstrated TOC rejection and consistent flux performance.
- Food & Beverage:Clean-in-place protocol compatibility and hygienic design standards drive ceramic membrane specification for protein processing and beverage clarification.
Pharmaceuticals extract maximum value per installed capacity. Utilities dominate unit volume deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands the dominant share of membrane system deployment, while Canada pursues differentiated strategies around mining effluent and indigenous water access. Mexico's industrial corridor expansion is generating parallel demand for compact treatment systems.
United States
California's Central Valley agricultural districts and Texas municipal utilities drive concentrated procurement of reverse osmosis trains and membrane bioreactors. EPA enforcement of emerging PFAS maximum contaminant levels under the Safe Drinking Water Act compresses retrofit timelines for conventional plants. Michigan and New Jersey utilities pilot nanofiltration systems for per- and polyfluoroalkyl substance removal ahead of federal deadlines.
Canada
Mining operations in Ontario and British Columbia specify ceramic ultrafiltration for process water recycling and acid mine drainage treatment. Health Canada and PMRA coordinate drinking water quality guidelines affecting membrane selection across provinces. Alberta's oil sands producers deploy crossflow systems for produced water management under provincial environmental compliance mandates.
Mexico
Nuevo León and Mexico City metropolitan water authorities evaluate membrane bioreactors for capacity expansion without footprint growth. The National Water Commission (CONAGUA) enforces discharge standards accelerating upgrades from conventional activated sludge. Baja California industrial parks near the US border adopt reverse osmosis for high-purity process water supply.
North America Membrane Water and Wastewater Treatment (WWT) Market Competitive Landscape
United States producers anchor one tier; European and Japanese specialists hold positions in chemical supply and module fabrication. The vendor base concentrates around integrated membrane manufacturers with captive polymer synthesis, creating a tiered structure where hollow-fiber spinning capabilities determine supply security. Two strategic archetypes dominate: diversified water technology conglomerates with dense service networks, and focused membrane material specialists leveraging fluoropolymer or ceramic expertise. Competitive moves center on strategic partnerships for regional market access and portfolio diversification into ceramic and advanced oxidation-integrated systems.
Within the diversified service tier, Evoqua Water Technologies and Veolia Water Technologies exemplify operators bundling equipment supply with long-term operations contracts. DuPont Water Solutions occupies a position among material-centric specialists. Suez represents European-headquartered players with North American operational scale. Kurita Water Industries Ltd anchors Japanese-origin water treatment expertise in the regional market.
| Leading Market Players |
|---|
| Kurita Water Industries Ltd |
| Ecolab |
| Suez |
| Aquatech International LLC |
| Evoqua Water Technologies LLC |
| DuPont Water Solutions |
| Veolia Water Technologies |
| Koch Separation Solutions |
| Pall Corporation |
| Others |
Value Network & Pricing Analysis
Captive fluoropolymer synthesis among high-pressure reverse osmosis element manufacturers anchors both supply security and pricing power in the North American membrane treatment market. DuPont Water Solutions and a limited supplier base control this upstream integration, enabling premium positioning for seawater desalination membranes while constraining price competition in critical applications.
Pricing Analysis
Capacity additions in Texas and California municipal markets are reshaping price floors for membrane bioreactor systems as utilities bundle long-term operations contracts with initial procurement. Project-based pricing with lifecycle cost demonstration dominates municipal channels, while pharmaceutical extractables documentation commands substantial premiums over standard industrial specifications. Cost compression in ultrafiltration pretreatment intensifies as hollow-fiber polyethersulfone module production scales. Municipal utilities exhibit highest price sensitivity due to bond financing constraints; pharmaceutical biologics manufacturers show least sensitivity given validation requirements.
Supply Chain Analysis
Dual-sourcing qualification requirements from California and Texas water utilities mandate multi-supplier validation for critical membrane trains, forcing integrators to maintain relationships with both fluoropolymer specialists and ceramic membrane producers. Polyamide thin-film composite production concentrates in the United States, Japan, and Germany; ceramic alumina substrate fabrication centers on Germany and Japan. Raw material dependencies span fluoropolymer resins, polyethersulfone pellets, and engineered ceramic powders. Single-source vulnerability in fluoropolymer synthesis creates supply chain risk for high-pressure desalination projects. Distribution runs through authorized system integrators with EPA operator certification capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America membrane water and wastewater treatment market functions as a stable compounder, with EPA enforcement of emerging contaminant standards providing durable retrofit demand across municipal infrastructure.
For Market Incumbents: Extend service network density in Texas metropolitan water districts ahead of direct potable reuse procurement waves. Deepen backward integration into hollow-fiber spinning capabilities to defend margin position against ceramic membrane convergence in food processing applications. Prioritize PFAS rejection certification investments as Michigan and New Jersey utilities accelerate pilot evaluations. For New Entrants and Emerging Players: EPA's evolving PFAS maximum contaminant levels under the Safe Drinking Water Act opens a window for nanofiltration specialists with demonstrated short-chain compound rejection. Target California Central Valley agricultural districts for high-recovery reverse osmosis systems under SGMA compliance deadlines. Pursue design-build-operate partnerships with Florida utilities bundling hurricane resilience requirements as the primary go-to-market angle. For Investors and Strategic Acquirers: Roll-up economics work for regional service integrators because fragmented municipal procurement favors dense aftermarket presence over manufacturing scale. The five-to-ten year viability window rests on membrane integrity testing certification requirements compressing operator qualification timelines. Target mid-cap system integrators with captive EPA operator training capabilities. Watch for ceramic membrane adoption inflection in dairy and food processing clean-in-place applications as the signal for polyethersulfone displacement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluoropolymer Synthesis | Captive resin production secures supply for high-pressure seawater desalination element manufacturing. |
| Design-Build-Operate Partnership Expansion | Florida utilities bundle hurricane resilience requirements with long-term operations contracts. |
| Ceramic Membrane Surface Chemistry Development | Engineered alumina systems penetrate food processing clean-in-place protocols above polyethersulfone limits. |
| PFAS Rejection Validation Investment | EPA enforcement compresses procurement cycles for membranes with demonstrated short-chain compound exclusion. |
| Membrane Bioreactor Footprint Optimization | California and Texas urban utilities specify compact systems for capacity expansion without land acquisition. |
Research Methodology
Multiple input streams — municipal utility planning officers, membrane system integrators, fluoropolymer procurement leads, and EPA regulatory affairs specialists — were reconciled against secondary validation from EPA enforcement guidance documents, state-level direct potable reuse legislation databases, and SEC 10-K filings from diversified water technology conglomerates. Bottom-up triangulation across equipment shipment data and top-down reconciliation against municipal bond financing disclosures established volume baselines.
Data-stream reconciliation across the projection horizon applied segmentation dimensions spanning product type, application channel, technology configuration, and end-user validation requirements. CAGRs were derived from installed base expansion modeling and replacement cycle analysis. Industry-specific forecast inputs incorporated California SGMA compliance deadlines and EPA PFAS maximum contaminant level implementation timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EPA enforcement scenarios or fluoropolymer supply disruptions. Deviation in Texas municipal direct potable reuse feasibility study mandates would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
Global Electrodeionization Market
Water & Sludge Treatment
Europe Water Treatment Chemicals Market
Water & Sludge Treatment
Anionic Flocculants Market
Water & Sludge Treatment
Fluid Waste Disposal Systems Market
Water & Sludge Treatment
Slurry Heaters Market
Water & Sludge Treatment
Wastewater Treatment Chemicals Market
Water & Sludge Treatment
North America Water Treatment Chemicals Market
Water & Sludge Treatment
Slurry Homogenizer Tank Market
Water & Sludge Treatment
Middle-East and Africa Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
Global Wet Waste Management Market
Water & Sludge Treatment
Drinking Water Adsorbents Market
Water & Sludge Treatment
Global Turbidity Meters Market
Water & Sludge Treatment
Internal Boiler Treatment Chemicals Market
Water & Sludge Treatment
Germany Water Treatment Chemicals Market
Water & Sludge Treatment
Asia-Pacific Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
Slurry Valves Market