
 Oil and Gas Water Treatment Chemicals Market | 2026-2036
Oil and Gas Water Treatment Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Oil and Gas Water Treatment Chemicals Market Outlook
Polyacrylamide is decoupling from traditional alum-based flocculation in high-salinity produced water streams, cutting chemical dosing rates by half in Permian and Bakken operations. Ecolab leverages its downstream service integration to lock in multi-year chemical supply contracts with major shale operators. Kurita Water Industries Ltd anchors its position through membrane-compatible antiscalant formulations that extend reverse osmosis run times in offshore platforms. Solenis LLC differentiates via digital dosing controls that tie chemical consumption directly to real-time water quality metrics.
Oil and gas water treatment chemicals comprise engineered formulations—flocculants, coagulants, biocides, and neutralizing agents—designed to remove suspended solids, control microbial fouling, and adjust pH in hydrocarbon extraction and processing effluents, typically dosed at 5–500 ppm depending on contaminant load and discharge specification. These chemicals enable produced water reinjection, cooling system integrity, and regulatory-compliant effluent release across upstream and midstream operations. Biocides command the strongest margin pool among product types due to microbial resistance dynamics and offshore logistics complexity that resist commoditization. Produced water treatment dominates application volume as unconventional wells generate four to ten barrels of water per barrel of oil, yet cooling water treatment offers more stable contract durations tied to refinery and gas processing infrastructure. Water management companies represent the fastest-expanding end-user channel as operators outsource treatment liability to specialized service firms.
EPA effluent limitation guidelines and China's MEE discharge standards for oilfield wastewater are tightening permissible oil-in-water concentrations, forcing reformulation of legacy demulsifier and defoamer chemistries. REACH registration requirements in Europe and state-level produced water recycling mandates in Texas and New Mexico are fragmenting product approval pathways across jurisdictions. Stakeholders must monitor regulatory divergence between jurisdictions that permit surface discharge versus those mandating zero-liquid-discharge architectures, as this split determines whether biocide-heavy or evaporation-focused chemical portfolios capture incremental capital deployment.
Market Dynamics
The Permian Basin's produced water volumes now exceed regional treatment capacity, forcing operators to upgrade from commodity alum-based chemistries to performance-engineered polyacrylamide formulations that halve dosing rates in high-salinity streams.
Growth Catalysts
- EPA Effluent Limitation Guidelines:Tightening oil-in-water discharge standards compel shale operators to reformulate legacy demulsifier chemistries, accelerating demand for advanced biocide and flocculant portfolios.
- Unconventional Extraction Intensity:Bakken and Permian wells generate four to ten barrels of water per barrel of oil, expanding the addressable base for produced water treatment chemicals across upstream operations.
- Water Management Outsourcing:Specialized service firms now assume treatment liability from operators, creating concentrated procurement channels that favor multi-year chemical supply contracts.
Market Restraints
- Acrylamide Monomer Volatility:Feedstock price swings for polyacrylamide precursors compress margin stability for formulated flocculant suppliers serving high-volume shale plays.
- REACH Registration Burden:European chemical approval pathways fragment product portfolios, forcing reformulation investments that delay market entry for biocide-heavy portfolios.
- Thermal Evaporation Substitution:Zero-liquid-discharge mandates in water-scarce jurisdictions shift capital toward mechanical vapor recompression, displacing chemical-intensive treatment trains in select basins.
Strategic Opportunities
- Membrane-Compatible Antiscalants:Offshore platform operators seek formulations that extend reverse osmosis run times, opening premium pricing for chemistry optimized to high-pressure seawater injection systems.
- Digital Dosing Integration:Real-time water quality metrics tied to automated chemical injection create service-layer differentiation beyond commodity supply.
- Texas Produced Water Recycling Mandates:State-level directives for beneficial reuse of oilfield wastewater expand addressable volume for treatment chemicals in the Permian and Eagle Ford.
Industry Challenges
- Microbial Resistance Management:Biocide efficacy degradation in recycled produced water streams demands continuous formulation rotation, complicating inventory planning for water management companies.
- Cross-Jurisdictional Approval Timelines:Divergent discharge standards between EPA frameworks and China's MEE requirements force parallel product registration tracks, extending time-to-revenue for global suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oil and Gas Water Treatment Chemicals Market |
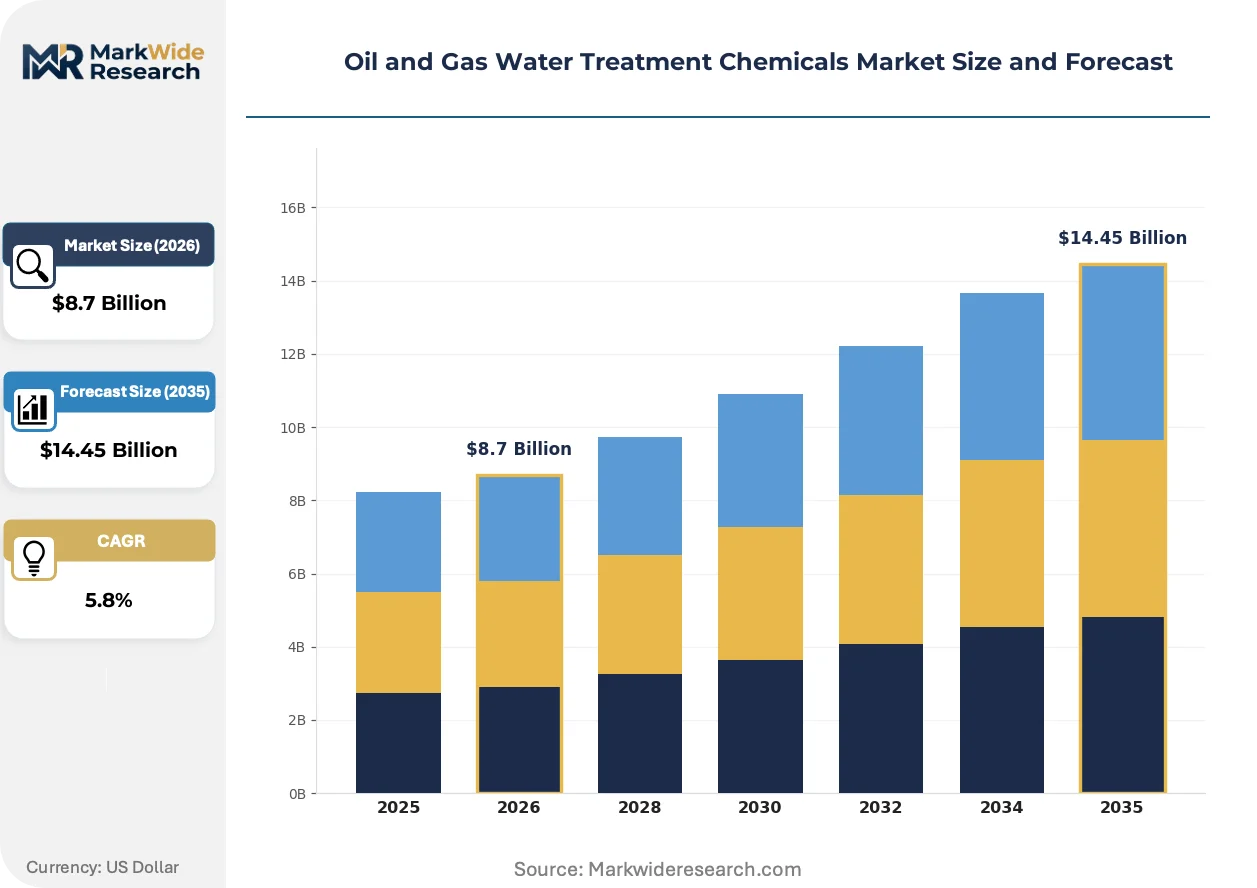
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flocculants, Coagulants, Biocides, Neutralizing Agents Application: Produced Water Treatment, Water Injection, Cooling Water Treatment, Wastewater Treatment End User: Oil Producers, Gas Producers, Water Management Companies, Treatment Plants Delivery Mode: Bulk Delivery, Packaged Delivery, On-site Mixing, Remote Monitoring |
| Companies Covered | Avista Technologies Inc, Ecolab Inc, Kurita Water Industries Ltd, Solenis LLC, BASF SE, Chemtex Speciality Limited, Veolia Water Technologies, Kemira Oyj, DuPont de Nemours Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oil and Gas Water Treatment Chemicals Market Strategic Shifts
Advanced formulation science is converging with digital infrastructure to transform how chemicals are dosed, monitored, and optimized across distributed oilfield operations.
Polyacrylamide-based flocculation is converging with machine learning-driven turbidity sensors to enable closed-loop dosing control in Permian produced water facilities. Midstream water management companies deploy these integrated systems to minimize chemical overfeed while maintaining discharge compliance. The structural compression of commodity alum suppliers accelerates as performance-guaranteed contracts displace spot purchasing.
REACH registration requirements in Europe are fragmenting biocide approval pathways, forcing reformulation of quaternary ammonium compounds ahead of 2026 renewal deadlines. Specialty chemical suppliers redirect R&D spend toward bio-based alternatives that preempt regulatory exclusion. Offshore North Sea operators face the steepest compliance costs, driving consolidation among smaller formulators lacking registration scale.
Water management companies now unbundle treatment liability from E&P balance sheets, converting chemical procurement from capital expenditure to operating expenditure line items. This shift compresses supplier sales cycles while extending contract durations for integrated service providers. The Permian Basin exhibits the most pronounced migration, with independents outsourcing produced water handling to specialized firms.
Oil and Gas Water Treatment Chemicals Market Segmentation
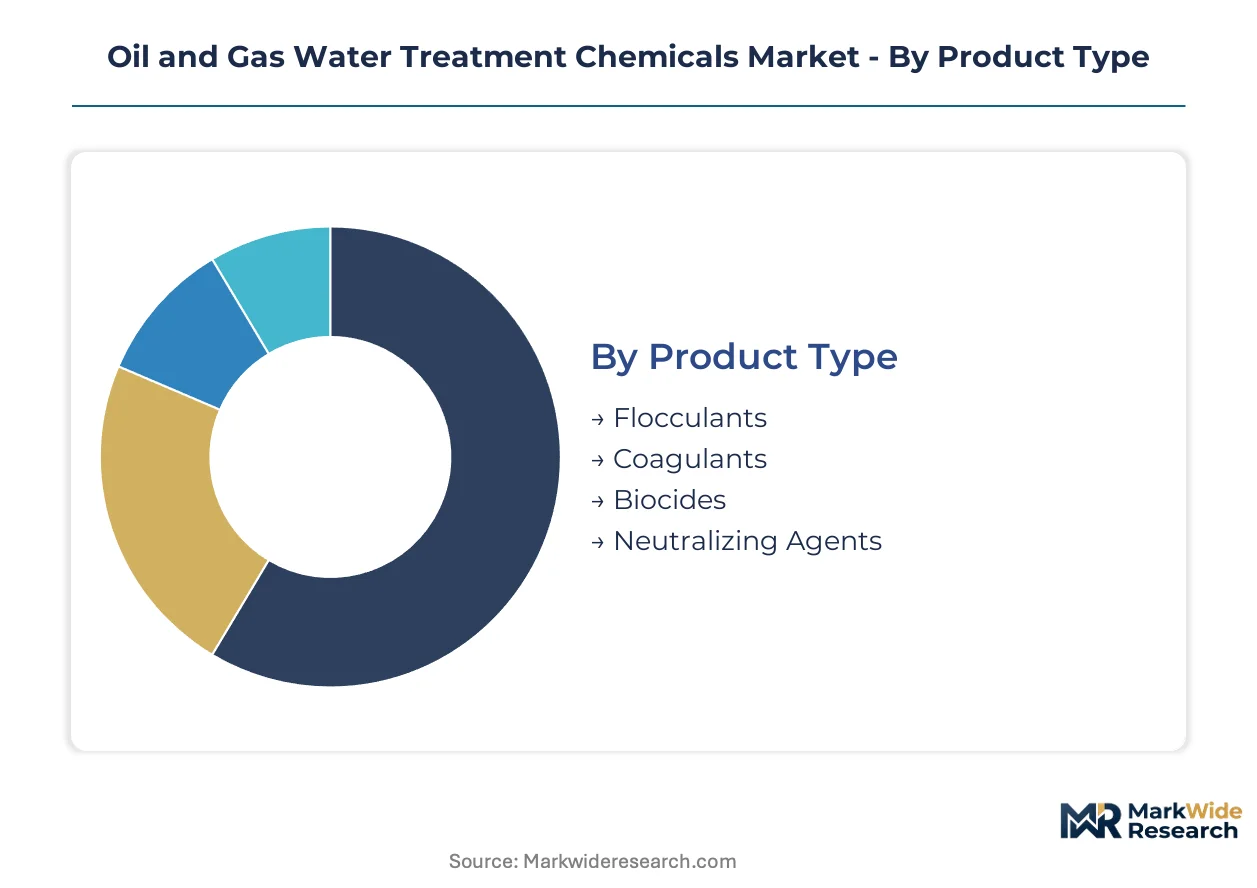
Segmentation in oil and gas water treatment chemicals reveals how procurement priorities diverge across operational contexts. Product chemistry, application severity, and delivery logistics each reshape supplier selection criteria and contract structures.
Product Type:
Buyers in this category differentiate by treatment intensity required and microbial risk exposure rather than commodity pricing alone.
- Flocculants:Polyacrylamide-based formulations dominate high-salinity produced water streams in Permian and Bakken operations, cutting dosing rates by half versus legacy alum chemistries. Demand concentrates where water-to-oil ratios exceed four barrels, forcing operators to prioritize polymer efficiency over unit cost.
- Biocides:Quaternary ammonium and glutaraldehyde blends command premium margins due to microbial resistance dynamics and offshore logistics complexity that resist commoditization. Offshore North Sea platforms drive formulation innovation as REACH registration deadlines approach.
- Coagulants:Alum and ferric chloride blends serve lower-salinity cooling systems and secondary clarification where cost sensitivity dominates.
- Neutralizing Agents:Caustic soda and sulfuric acid solutions adjust pH in refinery wastewater and gas sweetening effluents.
Volume sits with flocculants; growth tilts toward biocides.
Application:
Application segmentation tracks water chemistry severity and regulatory exposure across the hydrocarbon value chain.
- Produced Water Treatment:Unconventional wells generate four to ten barrels of water per barrel of oil, creating the largest addressable volume for flocculant and biocide consumption. Permian Basin operators face capacity constraints that accelerate outsourcing to water management companies.
- Cooling Water Treatment:Refinery and gas processing infrastructure demands stable, long-duration contracts tied to thermal efficiency guarantees rather than spot chemical purchasing.
- Water Injection:Seawater and produced water injection for reservoir pressure maintenance requires membrane-compatible antiscalants that extend reverse osmosis run times on offshore platforms.
- Wastewater Treatment:EPA effluent limitation guidelines and China's MEE discharge standards tighten oil-in-water permissible concentrations, forcing reformulation of legacy demulsifier chemistries.
Produced water treatment holds the volume base; cooling water treatment offers the most stable contract durations.
End User:
End-user segmentation reflects liability transfer trends and procurement centralization patterns.
- Water Management Companies:Specialized service firms now assume treatment liability from E&P operators, converting chemical procurement from capital expenditure to operating expenditure. This channel expands most quickly in the Permian Basin as independents outsource produced water handling.
- Oil Producers:Integrated majors and shale independents retain direct procurement for strategic basins where water chemistry varies significantly well-to-well.
- Gas Producers:Dry gas and liquids-rich operations prioritize cooling water and dehydration chemical packages tied to processing plant uptime.
- Treatment Plants:Municipal and industrial third-party facilities serving oilfield wastewater represent a fragmented, price-sensitive channel.
Water management companies are expanding most quickly; oil producers retain the largest absolute spend.
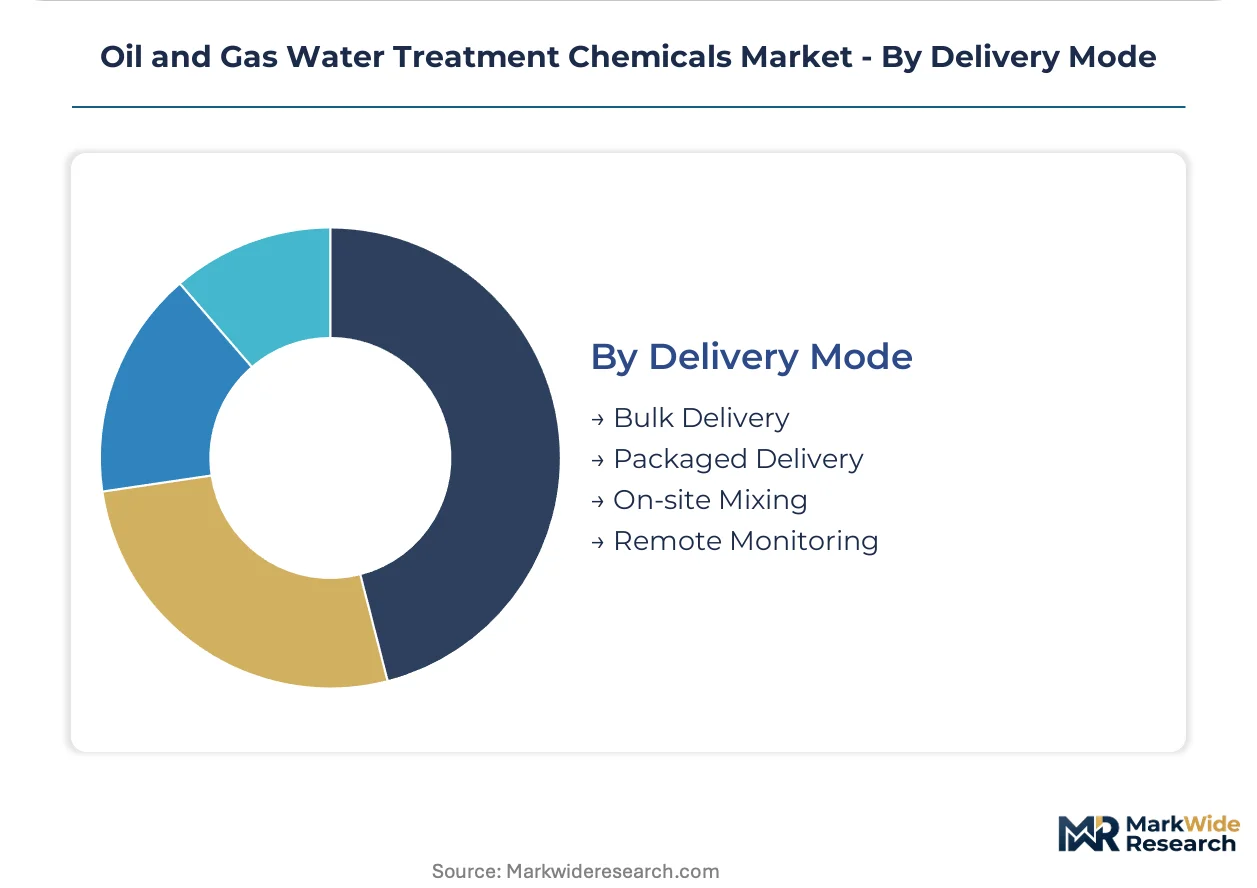
Delivery Mode:
Delivery segmentation separates volume-scale operations from precision-dosing requirements.
- On-site Mixing:Dry polymer activation and emulsion blending at the wellpad or central facility reduces transportation costs and enables real-time viscosity adjustment for varying produced water salinity.
- Remote Monitoring:Digital dosing controls tie chemical consumption to real-time turbidity and flow metrics, creating service-layer differentiation beyond commodity supply.
- Bulk Delivery:Tanker shipments of liquid emulsions serve high-volume shale plays with centralized storage infrastructure.
- Packaged Delivery:Drums and totes address remote locations and low-volume applications where capital investment in bulk handling is uneconomical.
Bulk delivery dominates absolute volume; remote monitoring carries the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates where unconventional extraction generates the highest water-to-oil ratios and regulatory discharge limits tighten fastest. The Permian Basin, North Sea offshore platforms, and Chinese shale developments drive formulation innovation and procurement centralization.
United States
EPA effluent limitation guidelines compel Permian and Bakken operators to upgrade from commodity alum to polyacrylamide formulations. Texas and New Mexico produced water recycling mandates expand addressable volume for treatment chemicals. Midland-Odessa water management companies now assume treatment liability from shale independents, converting procurement to multi-year operating contracts.
China
MEE discharge standards for oilfield wastewater tighten permissible oil-in-water concentrations across Sichuan and Tarim shale basins. State-owned operators accelerate membrane-compatible antiscalant deployment for high-pressure seawater injection systems. Tianjin and Qingdao chemical clusters supply formulated biocides to offshore Bohai Bay platforms facing dual carbon compliance timelines.
Saudi Arabia
Offshore Manifa and Safaniya fields require extended reverse osmosis run times, driving premium antiscalant consumption. The national petroleum regulator enforces zero-liquid-discharge architectures for new developments, displacing chemical-intensive treatment in favor of mechanical vapor recompression. Dhahran-based service firms centralize procurement for Aramco's produced water reinjection programs.
Norway
North Sea platforms face REACH registration deadlines for quaternary ammonium biocides, forcing reformulation toward bio-based alternatives. Statoil-operated fields demand digital dosing integration tied to real-time turbidity metrics. Stavanger and Bergen clusters host specialty chemical suppliers optimizing membrane performance for high-salinity produced water streams.
Brazil
Pre-salt carbonate reservoirs generate corrosive produced water chemistry, accelerating consumption of neutralizing agents and corrosion inhibitors. ANP regulatory frameworks mandate treatment system redundancy for deepwater FPSO installations. Rio de Janeiro and Macaé service bases supply formulated chemistries to Búzios and Mero field developments.
Oil and Gas Water Treatment Chemicals Market Competitive Environment
Multi-year chemical supply contracting dominates the current landscape as water management companies consolidate procurement authority. The vendor base separates into three tiers: integrated service providers with downstream treatment assets, specialty formulators with membrane-compatibility expertise, and regional commodity suppliers. Strategic archetypes include performance-guaranteed integrators, registration-scale biocide specialists, and digital dosing platform developers. M&A activity and technology licensing agreements reshape positioning as REACH deadlines and EPA guidelines fragment approval pathways.
Among integrated service providers, Ecolab Inc and Veolia Water Technologies exemplify the performance-guaranteed model, anchoring chemical supply within bundled water management contracts. Kurita Water Industries Ltd represents the membrane-specialist archetype, while Solenis LLC occupies a position on the digital dosing vector. BASF SE and Kemira Oyj sit within the registration-scale tier, leveraging global compliance infrastructure to navigate divergent EPA and MEE approval timelines. DuPont de Nemours Inc and Avista Technologies Inc anchor positions in membrane chemistry and reverse osmosis optimization respectively.
| Leading Market Players |
|---|
| Avista Technologies Inc |
| Ecolab Inc |
| Kurita Water Industries Ltd |
| Solenis LLC |
| BASF SE |
| Chemtex Speciality Limited |
| Veolia Water Technologies |
| Kemira Oyj |
| DuPont de Nemours Inc |
| Others |
Value Chain & Pricing Dynamics
Multi-year chemical supply contracting by Permian Basin water management companies is compressing spot market liquidity and forcing suppliers toward performance-guaranteed pricing models that bundle formulation expertise with real-time dosing infrastructure.
Pricing Analysis
Volume concentrates in commodity alum and ferric chloride coagulants where price differentiation rests on freight economics and bulk delivery scale; margins accrue to biocide and polyacrylamide specialists serving high-salinity produced water streams. Three-tier pricing structure separates membrane-compatible antiscalants for offshore platforms from standard flocculants for onshore shale plays and economy-grade neutralizing agents for refinery cooling systems. Cost compression in commodity tiers is intensifying because water management companies centralize procurement through dedicated supply contracts. Independent shale operators exhibit the highest price sensitivity; integrated majors and offshore platform operators prioritize performance guarantees over unit cost.
Supply Chain Analysis
Empty drum returns and spent emulsion recovery from Permian wellpads create reverse-logistics burdens that specialized service firms internalize to secure chemical supply exclusivity. Manufacturing concentration centers on Texas and Louisiana petrochemical corridors for polyacrylamide precursors, with formulated biocides sourcing active ingredients from Chinese and Indian chemical clusters. Feedstock exposure to acrylamide monomer volatility and REACH-registered quaternary ammonium compound shortages generates margin instability for smaller formulators. Distribution runs through Midland-Odessa and Houston service hubs that coordinate bulk emulsion delivery to centralized storage facilities across the Permian and Eagle Ford.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polyacrylamide-based flocculation systems are displacing legacy alum chemistries in high-salinity produced water treatment, creating asymmetric returns for suppliers with polymer synthesis capabilities and digital dosing integration.
For Market Incumbents: Deploy digital dosing platform integration to lock in multi-year operating contracts with water management companies. Backward integration into acrylamide monomer production mitigates feedstock volatility that threatens margin stability in high-volume shale plays. Ecolab and Veolia's bundled service models demonstrate how downstream treatment asset control secures chemical procurement channel dominance against commodity suppliers.
For New Entrants and Emerging Players: Capture membrane-compatible antiscalant niches in offshore North Sea and Bohai Bay platforms where REACH and MEE registration barriers limit incumbent flexibility. Texas produced water recycling mandates open white-space for bio-based biocide alternatives that preempt regulatory exclusion of quaternary ammonium compounds. Partner with regional water management companies to embed formulations within outsourced treatment liability structures.
For Investors and Strategic Acquirers: The window for entry favors specialty formulators with registration-scale compliance infrastructure across EPA and MEE frameworks. Long-term viability hinges on consolidation plays that combine digital dosing capabilities with polymer synthesis assets. Monitor REACH biocide renewal deadlines and Texas beneficial reuse mandate implementation as inflection indicators for portfolio reallocation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylamide Production | Captive supply of polyacrylamide precursors insulates margin stability from feedstock volatility in Permian operations. |
| Digital Dosing Platform Deployment | Real-time turbidity-driven injection systems tie chemical consumption to water quality metrics, creating service-layer differentiation. |
| REACH-Compliant Biocide Reformulation | Bio-based alternatives to quaternary ammonium compounds preempt regulatory exclusion ahead of European renewal deadlines. |
| Membrane-Compatible Antiscalant Development | Extended reverse osmosis run times on offshore platforms command premium pricing in North Sea and Saudi Arabian markets. |
| Water Management Company Partnership | Outsourced treatment liability conversion from capital to operating expenditure compresses sales cycles and extends contract durations. |
Study Parameters
Independent corroboration across water treatment plant managers, chemical procurement leads at shale operators, technical R&D directors at specialty formulators, and distribution channel partners underwrites the qualitative findings. Primary interviews with EPA compliance officers and MEE regulatory specialists in Beijing were cross-referenced against customs data for acrylamide monomer trade flows, SEC 10-K disclosures from integrated service providers, and American Chemistry Council sector reports. Bottom-up demand modeling from individual basin water-to-oil ratios was triangulated against top-down chemical consumption estimates derived from produced water reinjection volumes.
Rate-of-change decomposition across the analysis window separates volume growth from pricing dynamics and mix shifts toward premium formulations. Segmentation dimensions modeled include product chemistry tier, application severity, end-user procurement structure, and regional regulatory framework cluster. CAGRs were derived from basin-level production forecasts and water management outsourcing penetration curves, with sensitivity analysis around EPA effluent guideline implementation timing and Texas recycling mandate enforcement.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to microbial resistance dynamics that accelerate biocide formulation rotation and thermal evaporation substitution in zero-liquid-discharge jurisdictions. Forecasts reflect documented assumptions regarding shale well decline curves and regulatory divergence between surface discharge and closed-loop architectures. Practitioners should monitor REACH biocide renewal outcomes and Permian water management company consolidation rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
Liquid Waste Container Market
Water & Sludge Treatment
Process Chemicals for Water Treatment Market
Water & Sludge Treatment
Feedwater Treatment Chemicals Market
Water & Sludge Treatment
Polish Water Treatment Chemicals Market
Water & Sludge Treatment
Global Municipal Water Treatment Chemicals Market
Water & Sludge Treatment
Nanotechnology in Water Treatment Market
Water & Sludge Treatment
Germany Water Treatment Chemicals Market
Water & Sludge Treatment
Water Dispersible Granules Market
Water & Sludge Treatment
Asia-Pacific Membrane Water and Wastewater Treatment (WWT) Market
Water & Sludge Treatment
South America Membrane Water and Wastewater (WWT) Treatment Market
Water & Sludge Treatment
Global Turbidity Meters Market
Water & Sludge Treatment
Global Wood Activated Carbon Market
Water & Sludge Treatment
Swimming Pool Treatment Chemicals Market
Water & Sludge Treatment
Electrodeionization (EDI) Technology Market
Water & Sludge Treatment
US Water and Wastewater Treatment Chemicals Market
Water & Sludge Treatment
Sludge Heater Market