
 US Intravenous Immunoglobulin Market | 2026-2036
US Intravenous Immunoglobulin Market Size, Share, and Industry Trends Forecast 2026-2036
US Intravenous Immunoglobulin Market Intelligence
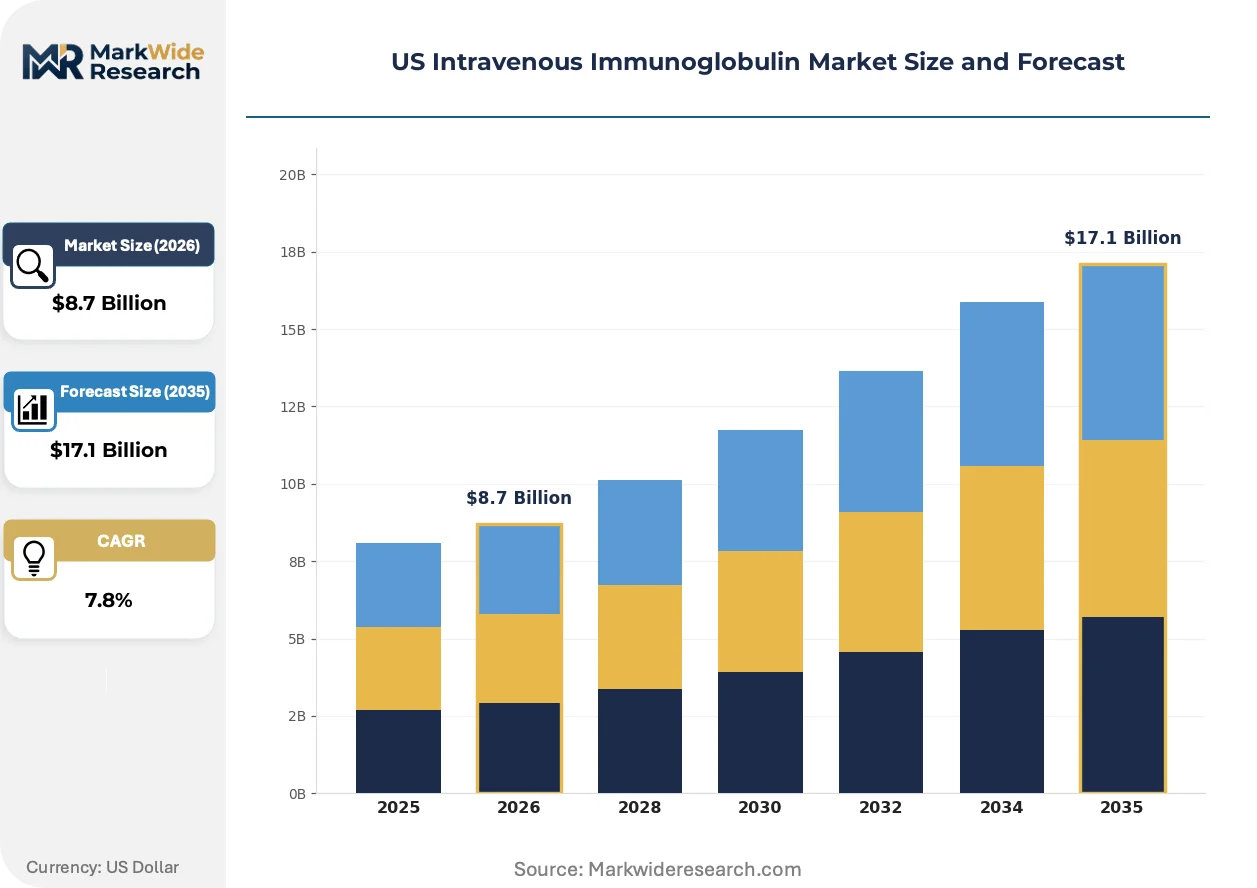
Homecare settings are gaining share as patient preference for outpatient administration is bifurcating demand away from traditional hospital infusion floors. CSL Behring leverages its vertically integrated plasma collection network to sustain domestic supply security. Takeda Pharmaceutical Company Limited anchors its position through specialized immunoglobulin R&D pipelines. Grifols, S.A. differentiates via scaled fractionation capacity and geographic concentration in southern US plasma centers.
Intravenous immunoglobulin comprises pooled human plasma antibodies, typically immunoglobulin G purified through cold ethanol fractionation and viral inactivation, administered to modulate immune response in antibody-deficient or autoimmune patients. IVIG product type retains the dominant revenue position due to established reimbursement codes and clinician familiarity, though specialized formulations for neurological indications capture expanding margin pools. Hospitals remain the volume anchor, while homecare settings represent the fastest-growing end user segment as subcutaneous administration protocols reduce facility dependency.
FDA plasma donor eligibility standards, CMS national coverage determinations, and OSHA bloodborne pathogen requirements collectively elevate compliance costs and limit new entrant access. Plasma collection center licensing through state health departments adds localized regulatory friction. Stakeholders must monitor FDA guidance on pathogen reduction technologies and CMS reimbursement adjustments for site-of-care differentials.
Market Dynamics
Plasma collection center density in Texas and Florida is reshaping supply security calculations for hospital formulary committees, while FDA pathogen reduction guidance accelerates capital deployment toward inactivation technologies.
Growth Catalysts
- Autoimmune neurology protocol expansion:Hospital systems in Texas and Florida are formalizing IVIG first-line protocols for CIDP and myasthenia gravis, expanding addressable patient pools beyond traditional immunodeficiency indications.
- CMS site-of-care reimbursement differentials:Medicare payment rate spreads between hospital outpatient departments and home infusion settings are accelerating patient migration toward lower-acuity administration venues.
- Subcutaneous immunoglobulin formulation advances:Concentrated SCIG products with extended dosing intervals are capturing patient preference for self-administration, reducing facility dependency and total cost of care.
Market Restraints
- Plasma donor pool constraints:FDA donor eligibility restrictions and post-COVID antibody titer requirements have tightened source plasma availability, elevating collection center operating costs.
- Fractionation capacity concentration:Domestic immunoglobulin purification infrastructure clusters in southern US manufacturing corridors, creating geographic supply vulnerability to regional weather or logistics disruptions.
- Recombinant monoclonal substitution threat:Targeted biologics for specific autoimmune conditions are capturing physician prescribing preference in neurology and rheumatology verticals.
Strategic Opportunities
- Underpenetrated homecare corridors:Rural Texas counties and northern Florida markets lack specialty infusion nursing density, creating whitespace for regional home health platform expansion.
- FDA pathogen reduction technology mandates:Anticipated guidance updates on nucleic acid testing and solvent-detergent treatment are creating first-mover advantage for fractionators with validated inactivation platforms.
- Neurology-specific indication expansion:Dosing protocol development for multiple sclerosis and autoimmune encephalitis represents emerging demand verticals with limited competitive saturation.
Industry Challenges
- Specialized plasma phlebotomist scarcity:Collection center expansion in Texas and Florida is outpacing certified donor technician training pipeline output, elevating labor costs and donor wait times.
- Legacy hospital EMR integration friction:Home infusion platforms face interoperability barriers with Epic and Cerner systems, delaying referral workflow automation and prior authorization processing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Intravenous Immunoglobulin Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.1 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: IVIG, SCIG, Specialized Formulations, Hyperimmune Globulin End User: Hospitals, Clinics, Homecare Settings, Infusion Centers Indication: Primary Immunodeficiency, Autoimmune Disorders, Infectious Diseases, Neurological Conditions Administration Route: Intravenous, Subcutaneous, Intramuscular, Intrathecal |
| Companies Covered | Octapharma AG, Takeda Pharmaceutical Company Limited, CSL Behring, Grifols, S.A., Kedrion Biopharma, Biotest AG, ADMA Biologics, Inc., Bio Products Laboratory Ltd., Pfizer, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Intravenous Immunoglobulin Market Strategic Shifts & Innovations
Pathogen reduction technologies and site-of-care migration are compressing traditional supply chain and clinical delivery models, while regulatory pressure on plasma sourcing standards accelerates quality system investments.
Next-generation nanofiltration and solvent-detergent viral inactivation systems are displacing older cold ethanol fractionation methods as the manufacturing standard for high-titer immunoglobulin products. Specialty neurology-focused fractionators are adopting these platforms fastest, driven by hospital formulary requirements for documented pathogen safety margins. The shift is compressing margin structures for legacy production assets while rewarding capital-intensive quality upgrades.
FDA draft guidance on nucleic acid testing for emerging pathogens is tightening plasma pool screening requirements ahead of formal rulemaking. Fractionators with validated PCR and next-generation sequencing protocols are securing preferred supplier status with major hospital systems. The neurology indication segment faces the steepest compliance cost escalation due to higher dosing volumes and extended therapy durations.
Patient-administered subcutaneous protocols are fragmenting demand away from hospital-based infusion centers toward home health nursing networks. Florida's specialty infusion cooperatives and Texas independent nursing agencies are capturing referral volume through direct physician contracting. The behavioral shift is most pronounced in CIDP maintenance therapy, where quarterly IVIG cycles convert to weekly SCIG self-administration.
US Intravenous Immunoglobulin Market Segmentation
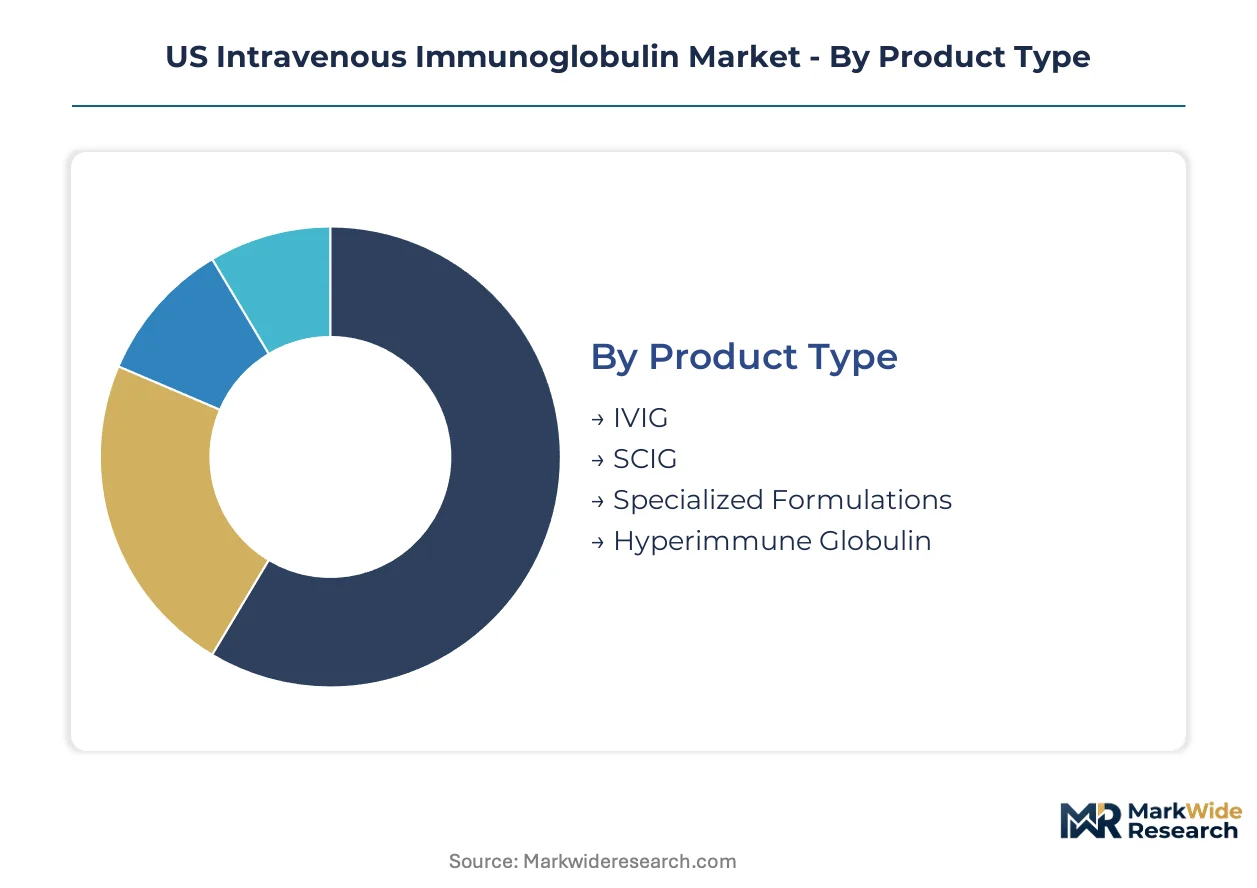
IVIG market segmentation reveals distinct channel economics where product form, care setting, and clinical indication intersect to determine reimbursement rates and margin structures. Each dimension carries implications for plasma sourcing requirements, regulatory compliance burden, and patient access pathways.
Product Type:
Channel mix varies sharply across product categories, with hospital-based infusion centers favoring established IVIG formulations while homecare networks drive concentrated SCIG adoption for maintenance therapy.
- IVIG:Pooled immunoglobulin G administered through intravenous infusion remains the standard of care for acute immunodeficiency crises and high-dose autoimmune protocols. Demand concentrates in Texas and Florida hospital systems where specialty neurology departments have formalized first-line CIDP treatment pathways, though fractionation capacity bottlenecks in southern manufacturing corridors create periodic supply allocation pressures.
- SCIG:Subcutaneous formulations enable patient self-administration through portable infusion pumps, eliminating facility dependency for chronic maintenance regimens. Home health agencies in rural Texas counties and northern Florida markets are capturing this volume through direct physician contracting, with CMS site-of-care reimbursement differentials accelerating the behavioral shift from quarterly hospital cycles to weekly home protocols.
- Specialized Formulations:Neurology-specific immunoglobulin products with enhanced IgG subclass profiles command formulary preference for multiple sclerosis and autoimmune encephalitis protocols.
- Hyperimmune Globulin:Pathogen-specific antibody concentrates derived from vaccinated donor pools serve targeted infectious disease indications with limited production scale.
IVIG dominates installed base. SCIG is where expansion concentrates.
End User:
Cost tier stratification separates high-acuity hospital administration from lower-cost ambulatory alternatives, with reimbursement spreads determining patient migration patterns across settings.
- Hospitals:Academic medical centers and community hospital systems anchor volume for acute immunodeficiency presentations, high-dose autoimmune loading regimens, and complex neurological diagnoses requiring inpatient monitoring. Texas Medical Center-affiliated institutions and Florida hospital networks with dedicated neuroimmunology units capture the most concentrated demand, supported by established plasma collection center density in both states.
- Homecare Settings:Specialty infusion nursing platforms and independent home health agencies are gaining share fastest as subcutaneous protocols reduce facility dependency. Epic and Cerner EMR integration friction delays referral workflow automation, creating temporary barriers to volume capture despite patient preference for outpatient administration.
- Clinics:Physician office-based infusion suites serve stable maintenance patients with predictable dosing requirements and established vascular access.
- Infusion Centers:Freestanding ambulatory facilities operated by hospital systems or independent platforms occupy the middle tier between acute hospital and home settings.
Hospitals retain the highest-margin acute cases. Homecare settings are climbing the fastest in volume terms.
Indication:
Application intensity varies by therapeutic area, with neurological conditions requiring extended therapy durations and higher cumulative dosing volumes than traditional immunodeficiency maintenance.
- Primary Immunodeficiency:Hereditary antibody deficiency syndromes represent the foundational indication with established lifetime therapy requirements and predictable dosing schedules. Pediatric and adult patients in Florida's dense specialty care corridors access these therapies through established referral networks, with maintenance regimens increasingly shifting toward home-based subcutaneous administration.
- Neurological Conditions:CIDP, myasthenia gravis, and emerging multiple sclerosis protocols are expanding addressable patient pools beyond traditional immunology boundaries. Texas hospital systems formalizing first-line IVIG protocols for these indications face the steepest compliance cost escalation under FDA draft guidance on nucleic acid testing, given higher per-patient plasma consumption.
- Autoimmune Disorders:Systemic lupus, dermatomyositis, and vasculitis applications compete with targeted biologics for physician prescribing preference in rheumatology and dermatology verticals.
- Infectious Diseases:Adjunctive immunoglobulin therapy for severe or refractory infections occupies a narrower niche with limited protocol standardization.
Primary immunodeficiency anchors steady baseline demand. Neurological conditions are gaining share fastest as protocol expansion outpaces other categories.
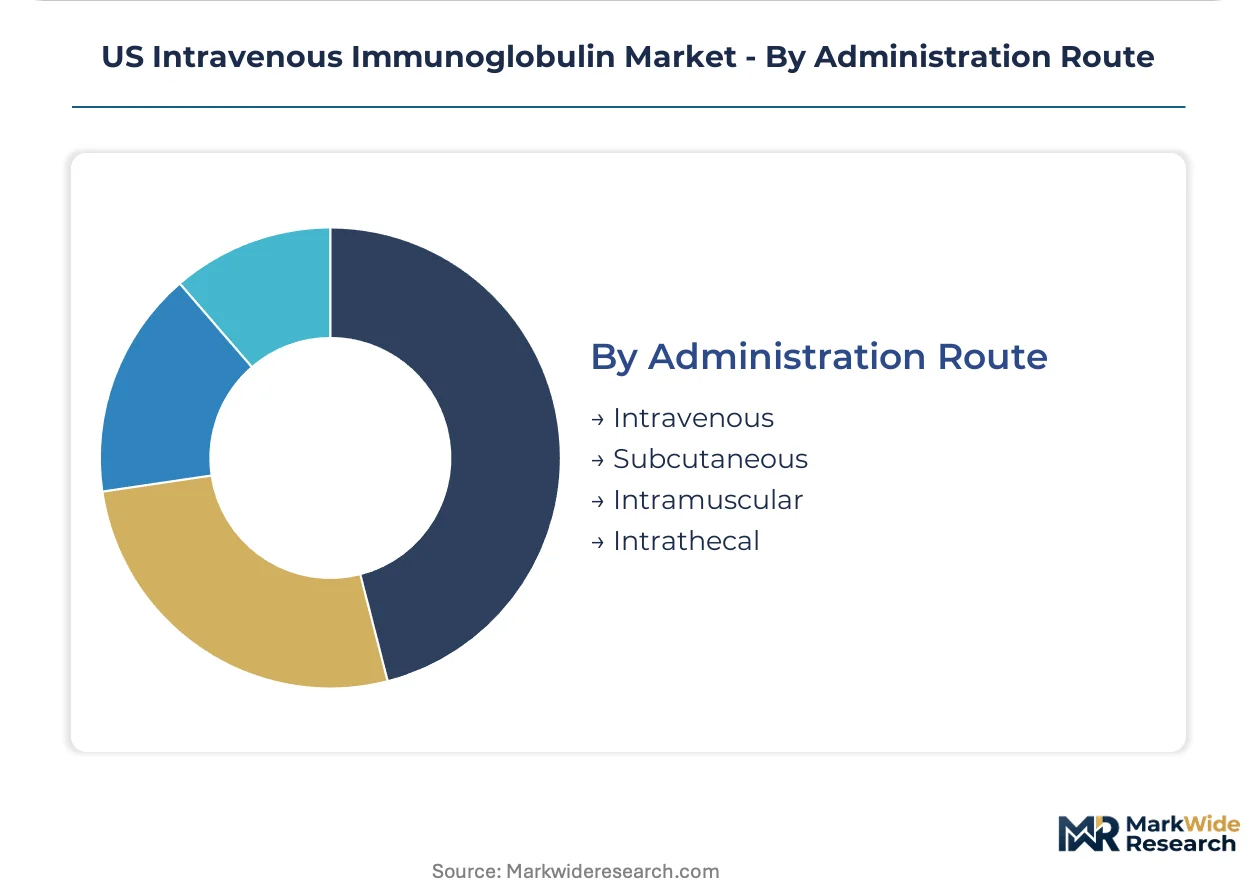
Administration Route:
Supply concentration for delivery devices and infusion pumps creates dependencies that shape route selection for chronic therapy patients.
- Intravenous:Central venous or peripheral catheter administration enables rapid high-volume antibody delivery for acute presentations and loading doses. Hospital outpatient departments in Texas and Florida maintain the infrastructure density for this route, though patient preference is bifurcating toward alternatives for maintenance phases.
- Subcutaneous:Abdominal or thigh tissue deposition through fine-gauge needles supports patient self-administration with concentrated 20% immunoglobulin formulations. FDA approval of extended-interval SCIG products with 10-14 day dosing gaps is displacing weekly protocols and reducing total injection burden.
- Intramuscular:Limited contemporary use for hyperimmune globulin delivery in specific infectious disease contexts with low volume requirements.
- Intrathecal:Experimental direct central nervous system delivery for neuroimmunological research protocols with restricted commercial availability.
Intravenous routes retain the highest acute care attachment. Subcutaneous administration is where patient preference and volume expansion are converging.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital formulary committees and specialty neurology departments concentrate purchasing power in southern and coastal states where plasma collection infrastructure and infusion center density intersect. State Medicaid programs and CMS regional contractors shape site-of-care migration patterns through reimbursement rate differentials.
Texas
The Texas Medical Center in Houston anchors acute immunoglobulin demand through dedicated neuroimmunology units formalizing CIDP first-line protocols. State health department licensing requirements for plasma collection centers create localized regulatory friction for new entrant expansion. Dallas-Fort Worth and San Antonio corridor networks are densifying specialty infusion nursing capacity to capture homecare migration volume.
Florida
Miami and Tampa metropolitan areas concentrate pediatric and adult immunodeficiency patient pools accessing therapies through established referral networks. Florida Agency for Health Care Administration Medicaid managed care contracts influence formulary positioning for maintenance therapy products. Northern Florida counties present whitespace for regional home health platform expansion due to limited specialty infusion nursing density.
California
Los Angeles and San Francisco Bay Area academic medical centers drive demand for high-titer immunoglobulin products with documented pathogen safety margins. California Department of Public Health oversight of plasma collection center operations adds compliance layer to FDA federal standards. Southern California independent nursing agencies are capturing SCIG referral volume through direct physician contracting arrangements.
New York
New York City metropolitan hospital systems maintain infrastructure density for intravenous loading regimens requiring inpatient monitoring capabilities. New York State Department of Health regulations on bloodborne pathogen handling elevate operating costs for hospital outpatient departments. Upstate and western New York regions lag in homecare nursing density, creating geographic access disparities for maintenance therapy patients.
Illinois
Chicago-area academic medical centers anchor demand for complex neurological indications requiring specialized immunoglobulin formulations. Illinois Department of Public Health plasma center inspection protocols align with OSHA bloodborne pathogen requirements. Downstate and rural Illinois markets face collection center scarcity, elevating supply security calculations for hospital formulary committees.
US Intravenous Immunoglobulin Market Key Industry Players
Player mix skews toward vertically integrated plasma fractionators with captive collection networks. Three manufacturers control the majority of domestic immunoglobulin purification capacity, creating tiered supply security relationships with hospital systems. Strategic archetypes separate plasma-sourced incumbents from recombinant monoclonal developers and regional specialty fractionators. Competitive moves concentrate on pathogen reduction technology validation and homecare channel partnerships.
Among Swiss and Australian-anchored biopharmaceuticals, CSL Behring and Octapharma AG exemplify the integrated fractionator archetype through upstream control over donor pool access. Takeda Pharmaceutical Company Limited occupies a position representing the diversified pharmaceutical model with specialized immunoglobulin R&D concentration. Grifols, S.A. anchors the southern US manufacturing corridor presence, exemplifying geographic concentration strategies in plasma collection center placement.
| Leading Market Players |
|---|
| Octapharma AG |
| Takeda Pharmaceutical Company Limited |
| CSL Behring |
| Grifols, S.A. |
| Kedrion Biopharma |
| Biotest AG |
| ADMA Biologics, Inc. |
| Bio Products Laboratory Ltd. |
| Pfizer, Inc. |
| Others |
Cost & Logistics Intelligence
Fractionation facility utilization rates above 85% in southern US manufacturing corridors create scale economies that compress per-liter production costs while elevating price floors for smaller regional competitors. Plasma collection center density in Texas and Florida concentrates bargaining power among vertically integrated manufacturers, translating upstream supply security into downstream pricing discipline across hospital formulary negotiations.
Pricing Analysis
Cost-plus contracts with plasma cost indexation dominate hospital system procurement, linking immunoglobulin pricing to donor compensation and collection center operating expenses. Price differentiation rests on pathogen reduction certification tier and IgG subclass purity profile, with neurology-focused formulations commanding premium positioning over standard immunodeficiency grades. Pricing pressure stems from CMS site-of-care reimbursement compression, which squeezes margin structures for hospital outpatient departments while preserving home infusion profitability. Academic medical centers exhibit lowest price sensitivity due to protocol standardization requirements, whereas independent infusion centers negotiate aggressively on volume commitments.
Supply Chain Analysis
Strategic plasma stockpiling prevails over just-in-time sourcing as fractionators buffer against FDA donor eligibility fluctuations and seasonal collection variation. Supply concentrates in the United States, with raw material dependencies on source plasma, viral inactivation reagents, and specialized filtration membranes. Single-source vulnerability runs through the southern US manufacturing corridor, where weather disruptions or logistics interruptions threaten nationwide product allocation. Distribution runs through hospital system-owned specialty pharmacies and independent home health nursing networks, with direct-to-physician contracting gaining share in Florida and Texas maintenance therapy markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA pathogen reduction technology mandates are disrupting competitive positioning by accelerating capital requirements for nucleic acid testing infrastructure and solvent-detergent validation platforms.
For Market Incumbents: Secure plasma collection center expansion in northern Florida and rural Texas corridors before specialty infusion nursing density catches demand growth. Backward integration into donor management software and EMR interoperability layers defends against homecare platform disintermediation. Priority investment in extended-interval SCIG formulation R&D addresses patient preference migration while preserving margin structures against recombinant monoclonal substitution in neurology indications. For New Entrants and Emerging Players: FDA 510(k) fast-track pathways for pathogen reduction technology retrofits represent the most penetrable entry vector for regional fractionators lacking legacy cold ethanol infrastructure. Target whitespace in northern Florida home health networks, where specialty infusion nursing scarcity delays patient migration from hospital outpatient departments. Go-to-market positioning should emphasize direct physician contracting and Epic EMR integration partnerships to bypass hospital formulary gatekeeping. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among homecare platform operators with captive nursing networks and direct payer contracts, offering superior cash flow predictability versus hospital-dependent supply relationships. Long-term viability over the projection horizon favors acquisition targets with validated nucleic acid testing platforms and southern US plasma collection center licenses. Watch FDA draft guidance formalization on emerging pathogen screening as the inflection signal for compliance cost escalation and consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Pathogen Reduction Technology Validation | FDA nucleic acid testing mandates secure preferred supplier status with Texas Medical Center-affiliated hospital systems. |
| Homecare Nursing Network Expansion | Direct physician contracting in Florida Medicaid managed care corridors captures site-of-care migration volume. |
| Extended-Interval SCIG Formulation Development | 10-14 day dosing protocols reduce patient injection burden and defend against hospital outpatient competition. |
| EMR Interoperability Investment | Epic and Cerner integration layers automate referral workflows and accelerate prior authorization processing. |
| Plasma Collection Center Licensing | Texas and Florida state health department permits create localized regulatory moats against new entrant expansion. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital formulary directors, neuroimmunology department heads, plasma collection center operations managers, home health agency executives, and CMS regional contractor specialists. Secondary validation drew from FDA guidance documents, CMS national coverage determinations, state health department licensing records, and hospital procurement database extracts. Bottom-up patient volume modeling triangulated against top-down fractionation capacity utilization estimates across the analysis window.
Across the modeling period, analytical frameworks segmented demand by product formulation, administration route, clinical indication, and site-of-care setting, with neurology-specific protocols treated as a distinct growth vertical. CAGRs were derived from plasma collection center expansion trajectories, CMS reimbursement rate evolution, and patient migration patterns between hospital and homecare venues. Forecast inputs incorporated FDA regulatory timeline assumptions and subcutaneous formulation adoption curves.
Underlying assumptions cover plasma donor pool stability and pathogen reduction technology validation timelines, with deviation risk concentrated in FDA donor eligibility standard revisions and CMS site-of-care reimbursement restructuring. Forecasts reflect these baseline conditions without scenario-weighting for black-swan regulatory shifts. Revision becomes warranted when FDA formal rulemaking on nucleic acid testing crosses implementation thresholds or when plasma collection center labor cost inflation exceeds sustained double-digit annual rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Long-Acting Beta-Agonists Market
Pharmaceuticals
Global Pharmaceutical Traceability Market
Pharmaceuticals
Tunisia Pharmaceutical Market
Pharmaceuticals
Pharmaceutical Water Market
Pharmaceuticals
Steroid Injections Market
Pharmaceuticals
Prothrombin Complex Concentrate (PCC) Market
Pharmaceuticals
Iodine Deficiency Drug Market
Pharmaceuticals
Asia-Pacific Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
Asia-Pacific Contraceptive Drugs and Devices Market
Pharmaceuticals
Oral Anti-Diabetic Drugs Market
Pharmaceuticals
OX40 Receptor Agonist Market
Pharmaceuticals
Urinary Retention Drugs Market
Pharmaceuticals
Global Gastroparesis Drug Market
Pharmaceuticals
Global Dengue Vaccine Market
Pharmaceuticals
Global Psychotropic Drugs Market
Pharmaceuticals
Human Growth Hormone Treatment and Drugs Market